
 Asia-Pacific Semiconductor Etch Equipment Market | 2026-2036
Asia-Pacific Semiconductor Etch Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Etch Equipment Market Outlook
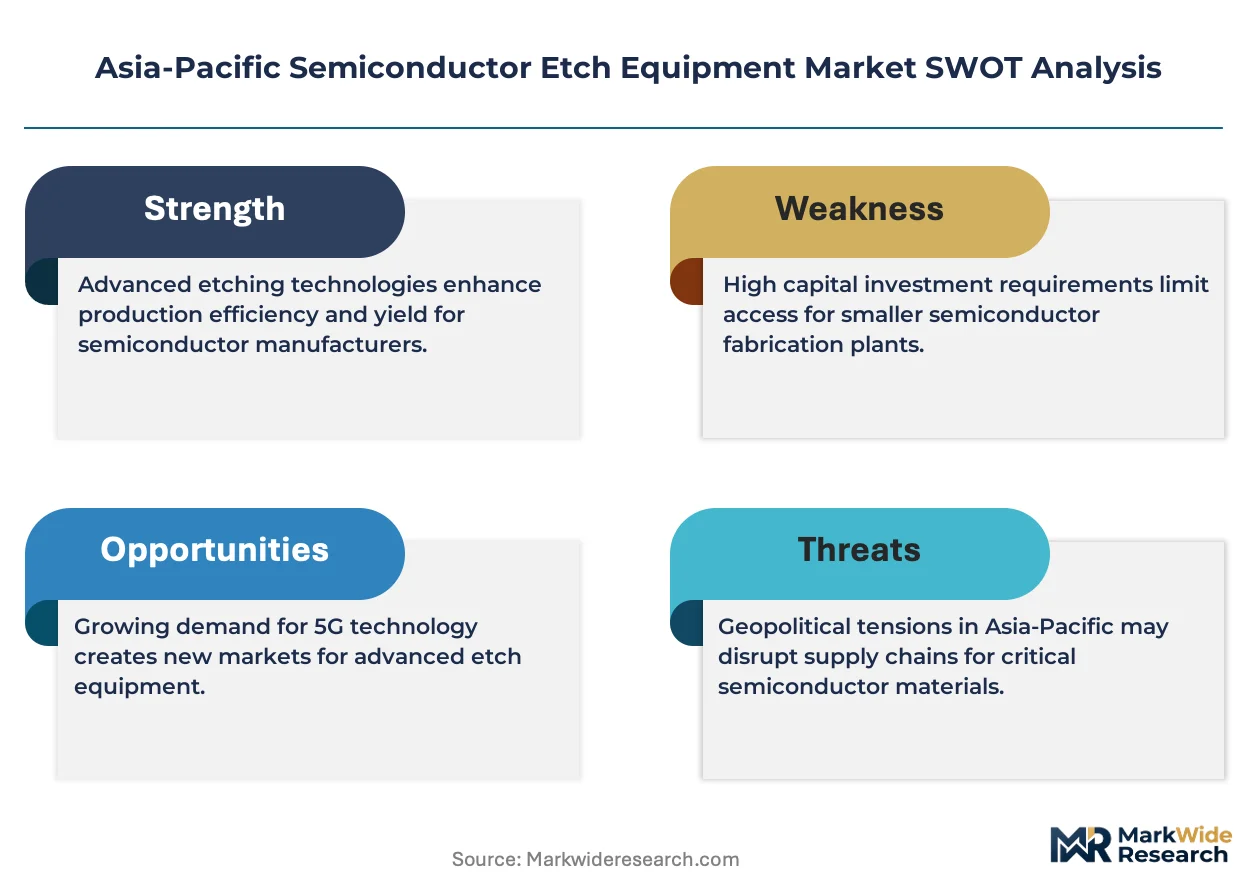
A capital-intensity divergence between plasma etch specialists and wet etch generalists is rotating competitive leverage toward equipment makers with captive source technology. Tokyo Electron Limited leverages its dry etching portfolio to anchor premium positioning in Japan's advanced logic sector. NAURA Technology Group Co., Ltd. competes on cost-optimized wet etch systems for China's domestic foundry buildouts. Applied Materials, Inc. sustains its regional presence through service density and chamber refurbishment networks.
Semiconductor etch equipment removes material layers from wafer surfaces using chemically reactive plasmas or liquid chemistries, with critical process parameters including selectivity ratios above 100:1 and uniformity control within ±3% across 300mm substrates. Plasma etch systems dominate margin pools in leading-edge logic where atomic-scale precision commands premium pricing, while wet etch systems retain volume leadership in mature node memory and power semiconductor fabrication. Dry etching technology leads capital allocation as foundries transition to gate-all-around transistor architectures requiring anisotropic profile control.
Japan's METI export licensing regime on fluorinated polyimide and photoresist compounds shapes equipment sourcing decisions for Korean memory manufacturers, while China's GB standards on semiconductor manufacturing emissions and MIIT localization mandates restrict import dependency ratios for domestic fabs. South Korea's K-Battery and K-Semiconductor Act subsidies are accelerating etch equipment procurement timelines for Pyeongtaek and Yongin cluster expansions. Stakeholders must monitor how Japan's material export controls and China's equipment import substitution targets create divergent compliance and supply chain architectures across the region's three dominant manufacturing hubs.
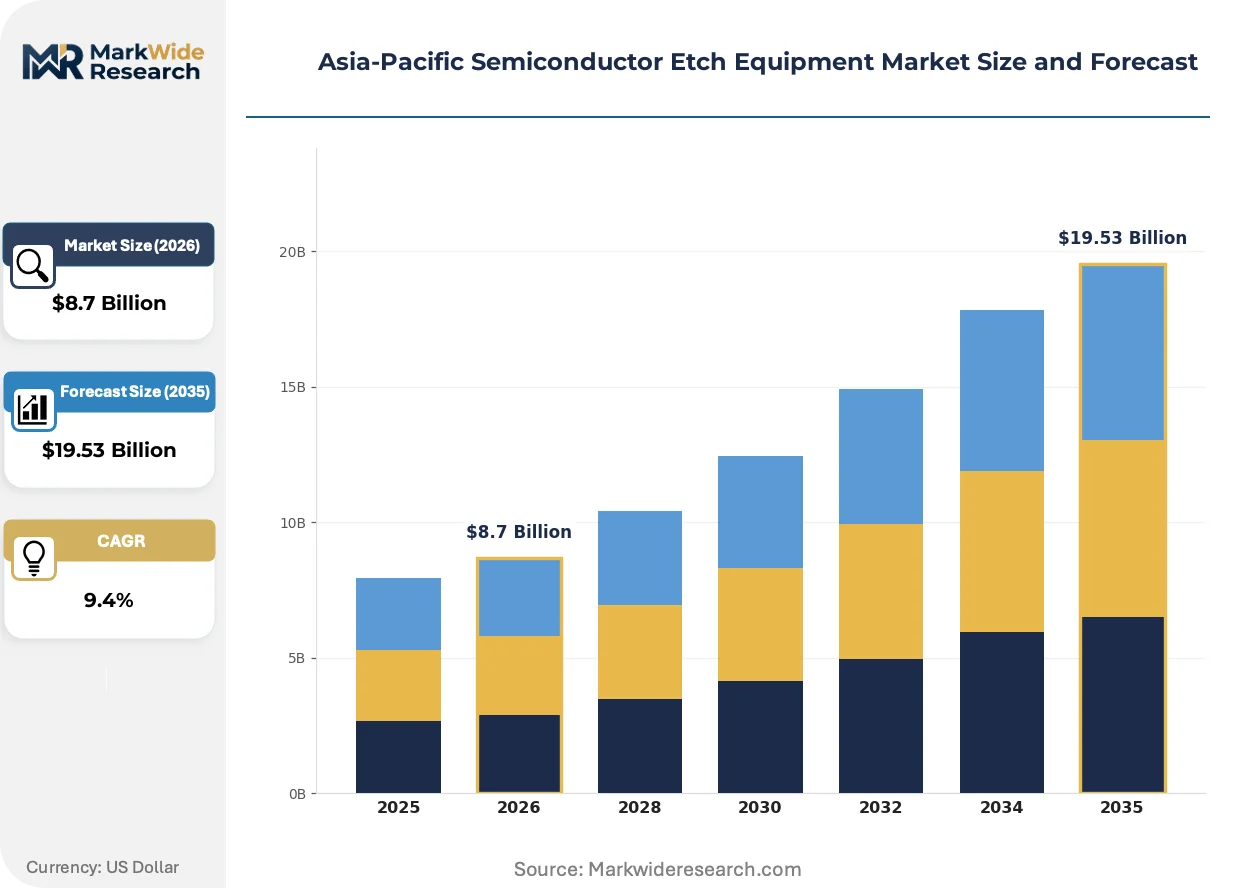
Market Dynamics
Gate-all-around transistor architectures are forcing foundries to retool etch chambers for atomic-scale anisotropic control, compressing equipment replacement cycles and concentrating procurement authority with advanced logic manufacturers in South Korea and Taiwan.
Growth Catalysts
- Dual carbon goals:China's GB standards on semiconductor manufacturing emissions are accelerating fab equipment upgrades in the Yangtze River Delta cluster.
- K-Semiconductor Act subsidies:South Korea's Pyeongtaek and Yongin expansions are compressing etch equipment procurement timelines for memory manufacturers.
- Fluorinated polyimide licensing:Japan's METI export controls are redirecting Korean memory makers toward captive source etch chemistry strategies.
Market Restraints
- Advanced material concentration:Photoresist and fluorinated compound supply concentrates among Japanese specialty chemical suppliers, exposing Korean fabs to licensing delays.
- Chamber refurbishment bottlenecks:Leading-edge plasma etch systems require proprietary spare parts with 12-18 month lead times from original equipment makers.
- Atomic-scale precision limits:Current plasma etch selectivity ratios plateau near 100:1 for 3nm gate-all-around structures, constraining yield ramps.
Strategic Opportunities
- Domestic foundry buildouts:China's MIIT localization mandates are creating procurement windows for wet etch system suppliers serving mature node expansion.
- Power semiconductor fabrication:Silicon carbide etch applications for electric vehicle inverters represent underpenetrated demand within China's automotive supply chain.
- Service unbundling:Chamber refurbishment and predictive maintenance contracts are emerging as standalone revenue streams separate from equipment sales.
Industry Challenges
- Process integration complexity:Gate-all-around architectures require synchronized etch-deposition-etch sequences that strain legacy equipment coordination protocols.
- Specialized technician scarcity:Atomic layer etch calibration and chamber matching expertise concentrates among engineers with 10+ years of plasma physics experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Etch Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Etch Systems, Wet Etch Systems, High-Density Plasma Etch, Others Technology: Dry Etching, Wet Etching, Reactive Ion Etching, Deep Silicon Etching End User: Foundries, Memory Manufacturers, Integrated Device Manufacturers, Other Application: Microelectronics, Telecommunications, Automotive Electronics, Medical Devices |
| Companies Covered | Hitachi High-Tech Corporation, ULVAC, Inc., Applied Materials, Inc., SPTS Technologies, Panasonic Corporation, Lam Research Corporation, NAURA Technology Group Co., Ltd., ACM Research, Inc., Tokyo Electron Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Etch Equipment Market Strategic Shifts
Etch equipment architecture is bifurcating between atomic-precision dry systems for leading-edge logic and cost-optimized wet platforms for mature node memory, with process control software emerging as the primary differentiation layer.
Atomic layer etching is supplanting conventional plasma etch for critical dimension control in 3nm gate-all-around production. Samsung and TSMC are qualifying ALE chambers for their most advanced logic lines. This precision requirement is compressing the supplier base to equipment makers with proprietary radical generation technology.
Japan's METI export licensing regime on fluorinated polyimide and photoresist compounds is reshaping equipment sourcing decisions for Korean memory manufacturers. Korean fabs are accelerating qualification of alternative etch chemistries and chamber materials to reduce import dependency. The regulatory friction most acutely affects DRAM manufacturers with high-volume fluorinated material throughput.
Equipment procurement is consolidating under direct fab-engineering relationships rather than through regional distributors. Memory manufacturers in South Korea are negotiating multi-year service contracts bundled with chamber refurbishment commitments. This channel compression is most visible in the Pyeongtaek cluster where Samsung has centralized etch equipment vendor management.
Asia-Pacific Semiconductor Etch Equipment Market Segmentation
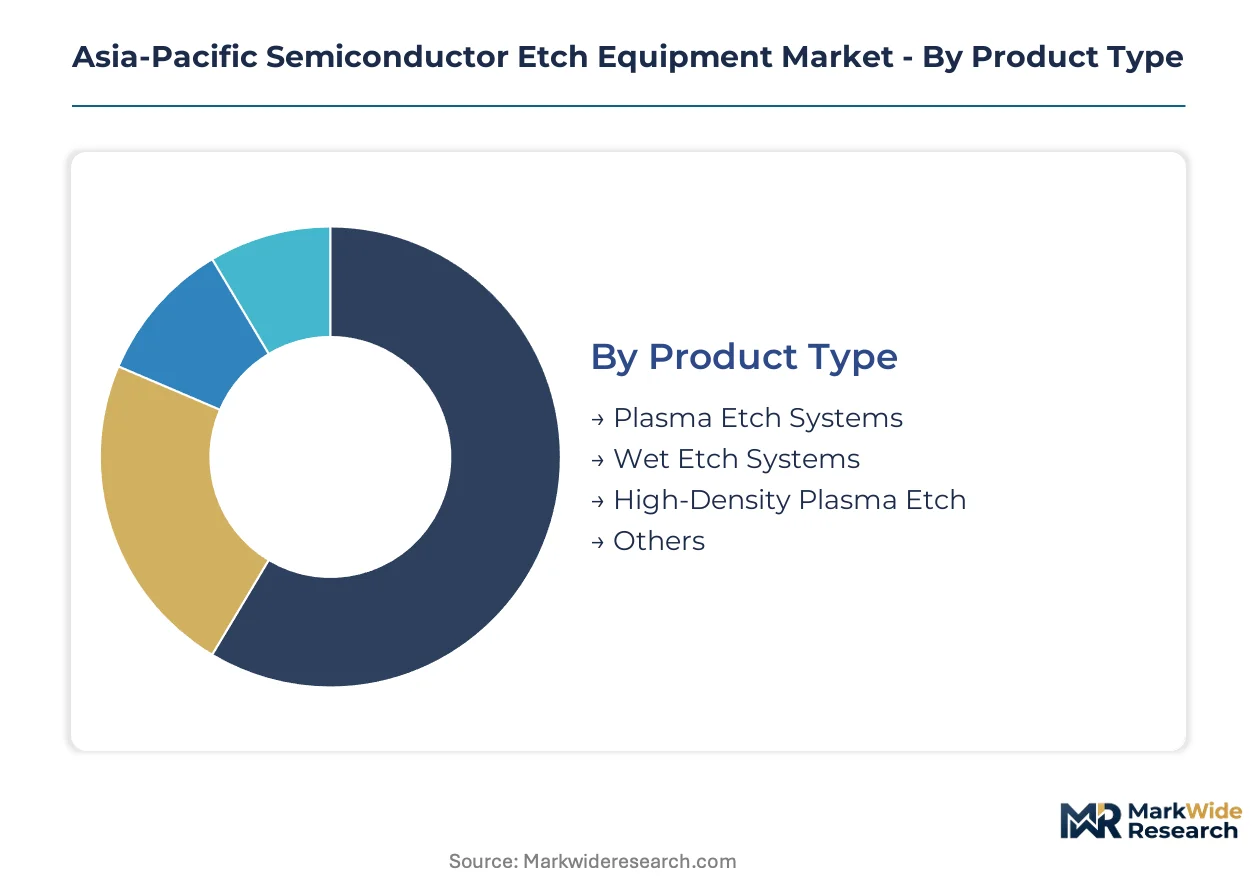
Etch equipment segmentation in Asia-Pacific reflects divergent technology requirements across South Korea's memory dominance, Taiwan's foundry concentration, and China's import substitution push. Regulatory frameworks from Japan's METI and China's MIIT create distinct procurement pathways that reshape competitive positioning by product category and end-user type.
Product Type:
Japan's METI export licensing on fluorinated compounds and China's GB emission standards are bifurcating equipment procurement between precision dry systems and cost-optimized wet platforms.
- Plasma Etch Systems:These systems deploy radio-frequency excited plasmas to achieve anisotropic etch profiles with selectivity ratios exceeding 100:1 for 3nm gate-all-around architectures. South Korean foundries in Pyeongtaek and Yongin dominate procurement as they transition to advanced logic nodes requiring atomic-scale precision, though chamber refurbishment bottlenecks with 12-18 month lead times constrain fleet expansion.
- Wet Etch Systems:Liquid chemistry platforms utilizing acid or solvent baths excel in batch processing for mature node memory and power semiconductors with lower selectivity requirements. China's Yangtze River Delta cluster absorbs the majority of regional volume as domestic foundries prioritize cost-optimized equipment under MIIT localization mandates that restrict import dependency ratios.
- High-Density Plasma Etch:Inductively coupled plasma configurations deliver higher ion density for deep trench etching in 3D NAND fabrication. Samsung's Pyeongtaek memory complex qualifies these chambers for vertical channel hole etching.
- Others:Emerging atmospheric pressure plasma and cryogenic etch variants address specialized applications in compound semiconductor processing. Taiwan's Hsinchu Science Park pilots these technologies for silicon carbide power device fabrication.
Established volume favors Wet Etch Systems; emerging adoption favors Plasma Etch Systems.
Technology:
Cost tier differentiation separates premium atomic-precision platforms from standard-volume production systems.
- Dry Etching:Plasma-based material removal without liquid chemistry enables sub-nanometer critical dimension control for gate-all-around transistors. TSMC's advanced logic lines in Tainan and Taichung drive qualification timelines for radical-generation chamber technologies.
- Wet Etching:Immersion-based processing with selective chemistries dominates mature node production where isotropic profiles suffice. Chinese domestic fabs under dual carbon goals prioritize these systems for lower emission intensity per wafer pass.
- Reactive Ion Etching:Combined physical sputtering and chemical reaction mechanisms balance anisotropy with throughput for analog and mixed-signal devices. South Korea's System LSI foundries deploy these for specialty chip production.
- Deep Silicon Etching:Bosch process alternation of etch and passivation cycles creates high-aspect-ratio trenches for MEMS and power devices. Japan's automotive sensor manufacturers anchor demand from Kyushu-based fabrication facilities.
Volume concentration sits with Wet Etching; technology leadership resides with Dry Etching.
End User:
Customer type determines procurement authority consolidation and service contract bundling intensity.
- Foundries:Pure-play contract manufacturers including TSMC and Samsung Foundry command premium pricing for leading-edge plasma etch through direct engineering relationships. Centralized vendor management in Taiwan's Tainan cluster compresses distribution layers and locks in multi-year refurbishment commitments.
- Memory Manufacturers:DRAM and NAND producers face acute pressure from Japan's fluorinated material export controls, accelerating captive source chemistry strategies. Samsung and SK Hynix in South Korea renegotiate supply terms to reduce licensing exposure.
- Integrated Device Manufacturers:Vertically integrated players like Sony and Toshiba retain in-house etch expertise for image sensor and power discrete production. Japan's IDMs sustain older equipment fleets through proprietary maintenance capabilities.
- Other:Research institutions and pilot lines at Tsinghua University and KAIST qualify next-generation atomic layer etch chemistries before commercial fab adoption.
Procurement scale concentrates with Foundries; margin pressure concentrates with Memory Manufacturers.
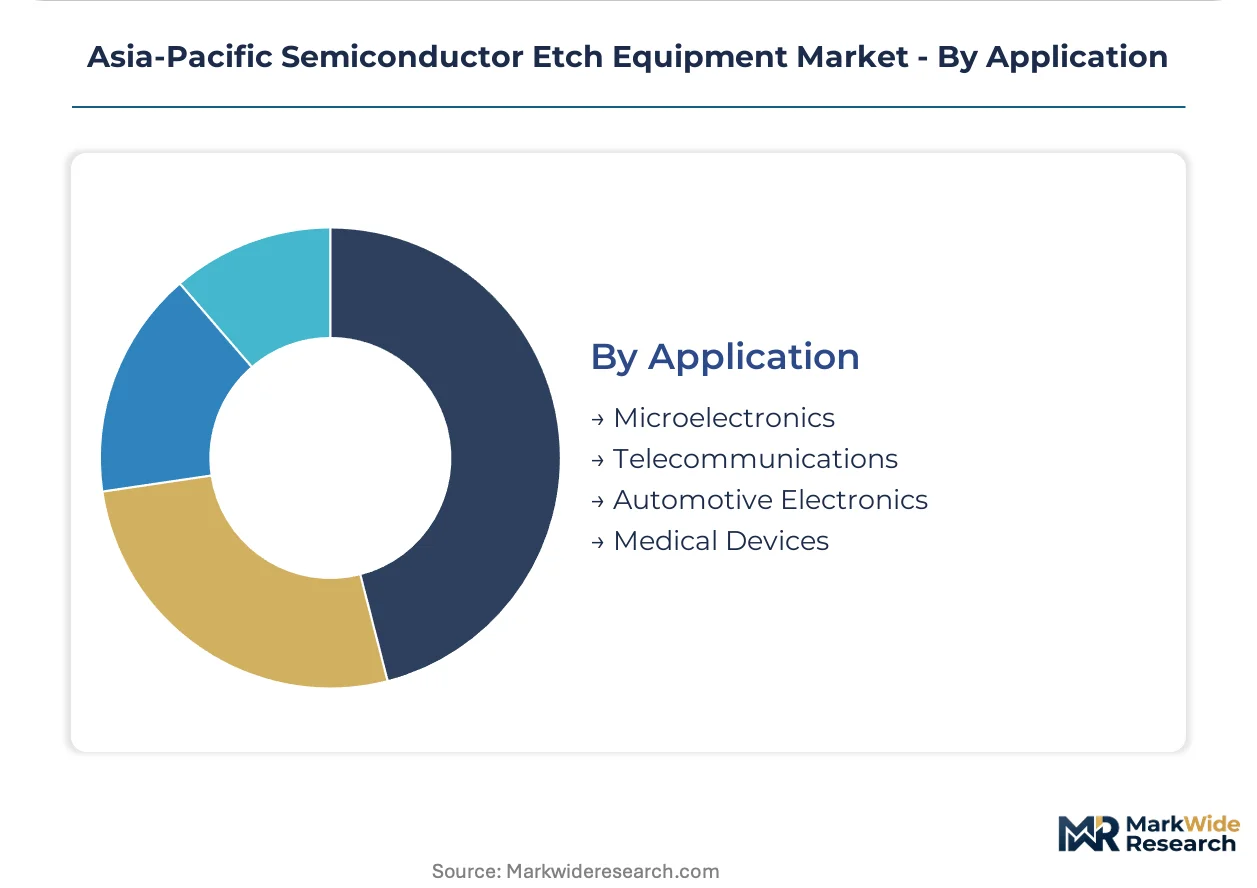
Application:
End-use sector maturity creates divergent equipment lifecycle and replacement cadence patterns.
- Microelectronics:Logic and memory semiconductor fabrication consumes the majority of high-selectivity plasma etch capacity. Taiwan and South Korea collectively anchor this segment's equipment demand.
- Telecommunications:5G baseband and RF front-end modules require compound semiconductor etch for gallium arsenide and gallium nitride devices. China's Huawei supply chain investments drive domestic equipment qualification.
- Automotive Electronics:Silicon carbide power module fabrication for electric vehicle inverters represents the steepest expansion trajectory within China's BYD and NIO supplier networks. Wet etch systems dominate current volume as the sector scales from 6-inch to 8-inch wafer processing.
- Medical Devices:Biosensor and implantable electronics demand ultra-clean etch chemistries with trace metal contamination below parts-per-billion thresholds. Japan's precision manufacturing base sustains niche equipment requirements.
Current fleet deployment favors Microelectronics; capacity expansion favors Automotive Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Japanese plasma etch specialists while Chinese wet etch fabricants compete on procurement cost. This asymmetry shapes equipment sourcing decisions across South Korea's memory expansion and Taiwan's foundry buildouts.
China
Domestic foundry construction in the Yangtze River Delta cluster drives wet etch system procurement under MIIT localization mandates. GB emission standards on semiconductor manufacturing accelerate fab equipment upgrades. Shanghai and Wuxi anchor capacity expansion for mature node production serving automotive and consumer electronics supply chains.
South Korea
Memory manufacturers in Pyeongtaek and Yongin compress etch equipment procurement timelines for 3D NAND and DRAM capacity ramps. K-Semiconductor Act subsidies lock in multi-year capital expenditure commitments. Samsung's centralized vendor management in the Seoul Capital Area consolidates negotiation authority for plasma etch chambers.
Japan
Advanced logic foundries in the Kyushu and Tohoku regions sustain premium positioning for dry etch systems with atomic-scale precision. METI export licensing on fluorinated polyimide and photoresist compounds redirects regional supply chain architectures. Tokyo Electron anchors technology leadership from its Kanto base.
Taiwan
TSMC's Tainan and Taichung facilities drive qualification timelines for gate-all-around transistor etch chambers. Direct fab-engineering relationships compress distribution layers and bundle multi-year refurbishment contracts. The Hsinchu Science Park pilots emerging atmospheric pressure plasma variants for compound semiconductor processing.
Asia-Pacific Semiconductor Etch Equipment Market Competitive Environment
Concentration sits with diversified equipment conglomerates possessing captive source technology and service density networks. The vendor base stratifies across three tiers: plasma etch specialists commanding premium pricing, wet etch generalists competing on localization compliance, and refurbishment service providers unbundling maintenance from equipment sales. Competitive moves center on strategic partnerships for radical generation technology and backward integration into specialty gas supply chains.
Within the plasma etch specialist tier, Tokyo Electron Limited and Lam Research Corporation exemplify premium positioning through proprietary chamber architectures. Among Asia-Pacific-based fabricants, NAURA Technology Group Co., Ltd. occupies a cost-optimized position serving domestic foundry buildouts under import substitution policies. Applied Materials, Inc. anchors the service-density archetype through chamber refurbishment networks that extend equipment lifecycles.
| Leading Market Players |
|---|
| Hitachi High-Tech Corporation |
| ULVAC, Inc. |
| Applied Materials, Inc. |
| SPTS Technologies |
| Panasonic Corporation |
| Lam Research Corporation |
| NAURA Technology Group Co., Ltd. |
| ACM Research, Inc. |
| Tokyo Electron Limited |
| Others |
Value Chain & Pricing Dynamics
Japan's METI export licensing regime on fluorinated polyimide and photoresist compounds gates both chamber material qualification and premium pricing tiers simultaneously. Korean memory manufacturers face elongated supplier audits that compress margin pools for non-captive etch chemistry strategies while rewarding Japanese plasma etch specialists with configured-to-order premiums.
Pricing Analysis
Configured-to-order plasma etch systems command spreads of 40-60 percent above standard wet etch platforms due to radical generation technology customization and chamber matching protocols. Price differentiation rests on atomic-scale precision certification tiers and bundled refurbishment commitments. Pricing pressure stems from Chinese domestic foundry procurement under MIIT localization mandates. Memory manufacturers in South Korea exhibit highest price sensitivity as fluorinated material licensing costs compound equipment TCO, while Taiwan foundries prioritize performance over unit economics.
Supply Chain Analysis
Port congestion across the Busan-Yokohama trade lane elevates inbound logistics costs for chamber components and specialty gas delivery systems. Component fabrication concentrates in Japan, South Korea, and the United States, with high-purity ceramic chamber parts and RF power supplies drawing from Kyushu-based suppliers. Single-source vulnerability persists for inductively coupled plasma coil assemblies. Distribution runs through direct fab-engineering relationships rather than regional distributor networks, compressing channel layers in the Pyeongtaek and Tainan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific semiconductor etch equipment sits in early-cycle expansion as gate-all-around transistor adoption accelerates chamber replacement cadences beyond historical depreciation schedules. Foundry capital commitments in Taiwan and South Korea anchor demand visibility.
For Market Incumbents: Secure captive supply agreements for fluorinated etch chemistries before Japanese METI licensing tightens further. Deepen backward integration into specialty gas purification to defend margin position against Chinese wet etch generalists. Lock multi-year refurbishment contracts with Samsung's centralized vendor management to forestall service unbundling by third-party maintenance providers.
For New Entrants and Emerging Players: MIIT localization certification fast-tracks unlock procurement windows for China's Yangtze River Delta domestic foundry buildouts. Silicon carbide power semiconductor etch for electric vehicle inverters represents the most penetrable white-space segment. Lead with cost-optimized wet platforms targeting mature node automotive electronics qualification.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across atomic layer etch chamber technologies as radical generation R&D cycles lengthen. Long-term viability favors equipment makers with proprietary process control software and service density networks. Target acquisition archetypes include refurbishment specialists with captive technician pools. Watch Samsung and TSMC ALE qualification timelines as inflection signals for supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Gas Supply | Reduces Japanese METI licensing exposure for Korean memory manufacturers. |
| Atomic Layer Etch Chamber Qualification | TSMC and Samsung adoption gates premium pricing for radical generation technology. |
| Service Contract Unbundling | Creates standalone revenue streams separate from equipment sales in mature node segments. |
| Silicon Carbide Etch Platform Development | Addresses BYD and NIO supplier network demand for power module fabrication. |
| MIIT Localization Compliance Investment | Unlocks procurement access for China's domestic foundry expansion under import substitution mandates. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with equipment engineering directors, fab procurement managers, and chamber refurbishment specialists, combined with secondary validation against customs trade records, SEC equipment supplier filings, and foundry capital expenditure disclosures. Bottom-up and top-down triangulation cross-referenced unit shipment estimates with aggregate wafer capacity expansion data across the Yangtze River Delta, Pyeongtaek, and Tainan clusters.
Across the analysis window, the forecasting framework modeled equipment demand by product type, technology tier, end-user category, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression analysis and foundry node transition timelines. Industry-specific inputs included gate-all-around transistor architecture adoption curves and fluorinated material licensing throughput assumptions.
Decision-makers should treat outputs as directional under base assumptions of continued K-Semiconductor Act subsidy execution and stable Japanese METI licensing administration; material deviation would warrant model refresh. Forecasts reflect assumptions about chamber refurbishment lead time stability and Chinese domestic foundry utilization rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
Semiconductor Production Equipment Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market