

High-Temperature Adhesives for SiC/GaN Power Module Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Adhesives for SiC/GaN Power Module Packaging Market Insights
Modular power module packaging is pivoting from traditional wire-bonded layouts toward embedded die and double-sided cooling configurations, forcing adhesive suppliers to validate materials for thinner bondlines and higher thermal cycling stress. Henkel leverages its automotive electronics portfolio to anchor qualification programs with European tier-1 suppliers. Heraeus Electronics specializes in sintering and adhesive solutions for silver and copper interfaces in SiC modules. Indium Corporation competes through its thermal materials expertise applied to GaN-on-Si power devices.
High-temperature adhesives for SiC/GaN power module packaging are formulated resins—typically epoxies, silicones, or polyimides with ceramic fillers—engineered to maintain shear strength above 150°C while conducting heat away from gallium nitride and silicon carbide dies; these materials bond semiconductor dies to direct-bonded copper substrates or baseplates in packages that must survive thousands of thermal cycles between minus 40°C and 175°C. Epoxy formulations currently dominate commercial volume due to established processing infrastructure, though silicone segments are gaining share in automotive powertrain applications where flexibility under thermal shock matters most. Electrically insulating technology categories command margin premiums because they eliminate the need for separate passivation layers in high-voltage SiC modules.
The US EPA and NHTSA coordinate fuel-economy and emissions rules that push automakers toward SiC-based inverters, directly expanding the addressable adhesive market. The EU Green Deal and REACH framework restrict certain halogenated flame retardants, compelling reformulation of legacy adhesives toward compliant chemistries. Japan's METI sets domestic content targets for power semiconductor supply chains, influencing adhesive procurement patterns among Japanese module assemblers. Stakeholders must track qualification timelines at individual OEMs, as adhesive approval cycles often lag power device development by two to three generations and determine competitive lock-in.
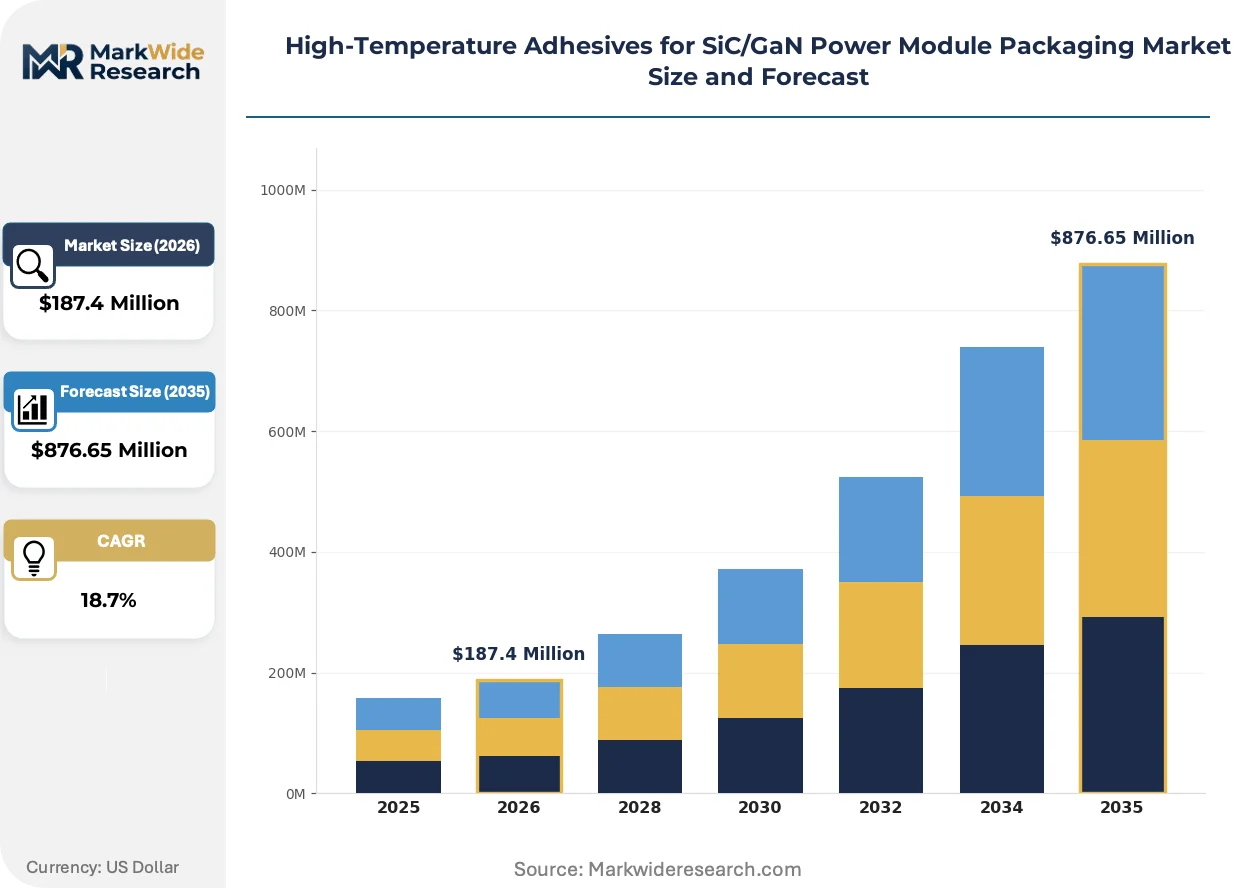
Market Dynamics
Die-attach materials face mounting qualification pressure as automotive OEMs migrate from wire-bonded layouts toward embedded die configurations with sub-100-micron bondlines and double-sided cooling architectures.
Growth Catalysts
- EU Green Deal efficiency mandates:Tightening CO2 targets for heavy-duty transport force rapid SiC inverter deployment across European truck and bus platforms, pulling die-attach procurement volumes upward.
- US IRA clean vehicle credits:Domestic content requirements for electric powertrain assembly incentivize localized adhesive manufacturing and qualification programs with Detroit-area module assemblers.
- Japan METI supply chain localization:Domestic content targets for power semiconductors redirect procurement toward Japanese adhesive formulators with established automotive tier-1 relationships.
Market Restraints
- Silver flake cost volatility:Conductive filler loading requirements expose formulations to precious metal price swings that compress formulation margins unpredictably.
- Epoxy resin supply concentration:Bisphenol-A and specialty hardener production clusters in Northeast Asia create geographic chokepoints for high-purity electronic-grade feedstocks.
- REACH substance restrictions:ECHA scrutiny of halogenated flame retardants forces costly reformulation cycles for legacy adhesive platforms before requalification.
Strategic Opportunities
- Copper sintering hybridization:Convergence of pressure-assisted sintering with printable adhesive formats opens white space in high-current traction inverter modules where pure sintering remains capital-intensive.
- India PLI scheme for semiconductors:Production-linked incentives for compound semiconductor fabs create first-mover advantage for adhesive suppliers establishing local technical service infrastructure.
- Aviation electrification:Emerging demand from regional electric aircraft programs for adhesives rated above 200°C with aviation-specific outgassing certification represents uncaptured volume.
Industry Challenges
- Automotive qualification timelines:AEC-Q100 and AQG-324 validation cycles spanning 24-36 months delay revenue recognition and tie up R&D resources across multiple OEM programs simultaneously.
- Formulation-to-module matching complexity:Each SiC die metallization scheme requires bespoke adhesive interface engineering, fragmenting SKU portfolios and stretching technical service teams.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Adhesives for SiC/GaN Power Module Packaging Market Trends and Innovations
Formulation chemistry and application equipment are converging to enable thinner bondlines and higher thermal cycling survival as power density targets escalate across automotive and renewable energy inverter platforms.
Transient liquid phase sintering adhesives containing micron-scale copper and tin alloys are electrifying die-attach performance by forming intermetallic joints with thermal conductivity exceeding 200 W/m-K. Tier-1 automotive suppliers in Germany and Japan are piloting these materials for 800V traction inverters where conventional silver-filled epoxies hit thermal limits. This metallurgical bonding approach is electrifying competitive positioning by enabling module designs previously reserved for pressure-sintering equipment.
REACH authorization procedures for boron-based substances are tightening scrutiny of boron nitride filler chemistries widely used in thermally conductive adhesives. ECHA's 2024-2025 substance evaluation roadmap signals potential restriction pathways that would force rapid ceramic filler substitution. High-voltage SiC module producers in the Netherlands and France are accelerating alternative filler qualification to preempt supply disruption.
Power semiconductor foundries are consolidating adhesive specification authority previously held by module assemblers, centralizing material selection at die design stage. Wolfspeed and Infineon now issue approved material lists that downstream packaging houses must adopt, compressing supplier diversity. This procurement concentration is most visible in Germany and the United States where automotive OEMs delegate packaging decisions to captive foundry operations.
High-Temperature Adhesives for SiC/GaN Power Module Packaging Market Segmentation
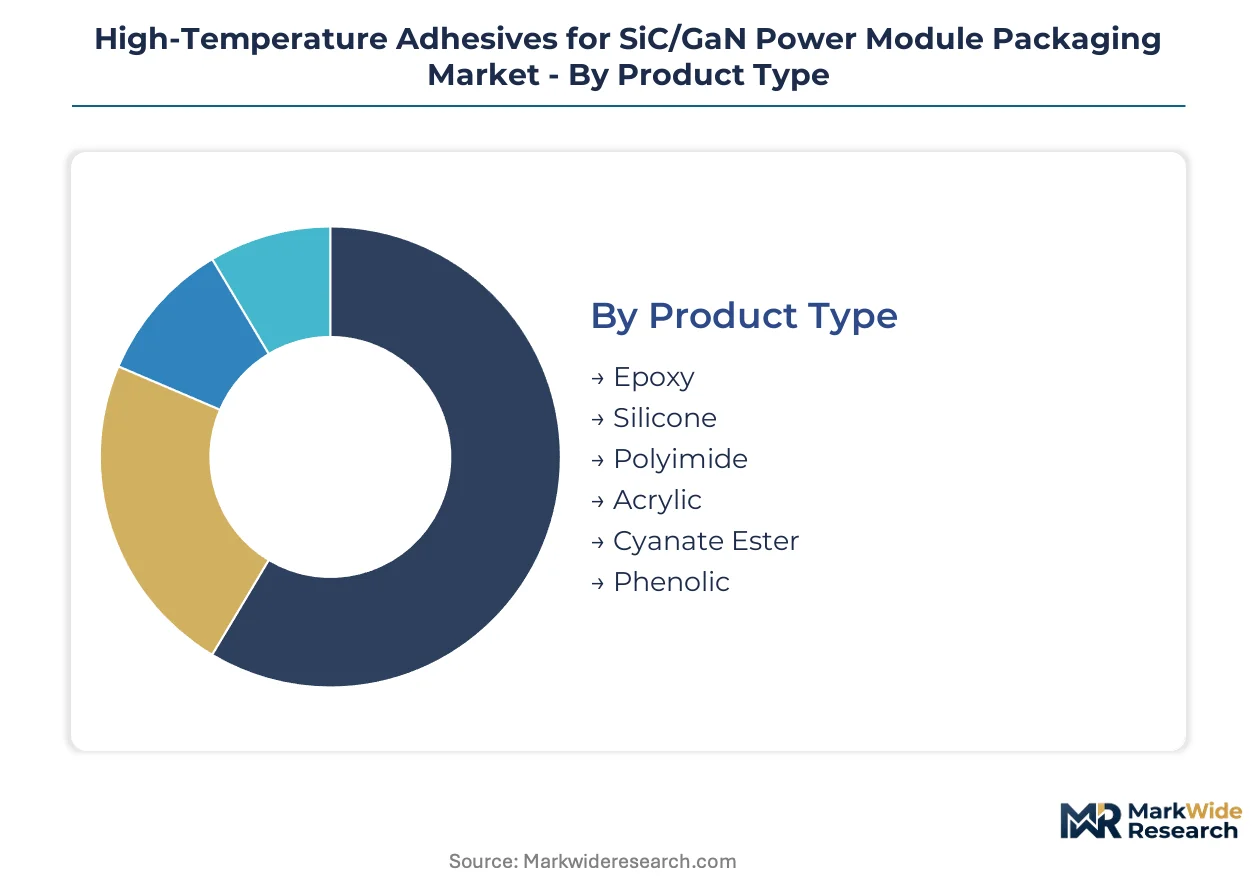
Segmentation in high-temperature adhesives reveals how formulation chemistry, thermal performance specifications, and end-use certification requirements fragment procurement patterns across SiC and GaN packaging value chains. Material selection at each tier determines qualification timelines, pricing power, and supplier lock-in duration.
Product Type:
Epoxy resin production concentrates in Northeast Asian chemical clusters, creating supply chokepoints that module assemblers must navigate through dual-sourcing strategies and strategic inventory positions.
- Epoxy:Ceramic-filled bisphenol-A and novolac formulations dominate commercial volume through established stencil printing and dispensing infrastructure. Automotive powertrain manufacturers in Germany and the United States anchor procurement volumes for die-attach applications rated to 175°C continuous operation.
- Silicone:Flexible polydimethylsiloxane-based systems with aluminum oxide or boron nitride fillers accommodate thermal expansion mismatch between SiC dies and copper substrates. Demand clusters in Japanese automotive programs where thermal shock resistance from minus 40°C to 200°C proves critical for reliability validation.
- Polyimide:High-temperature aromatic heterocycle polymers for extreme environments above 250°C.
- Acrylic:UV-curable and thermal cure systems for lower-temperature consumer and industrial applications.
- Cyanate Ester:High-performance thermosetting resins with low outgassing for aerospace-grade modules.
- Phenolic:Cost-effective novolac resins for industrial drives with moderate thermal requirements.
Today's leader: Epoxy. Tomorrow's challenger: Silicone.
Technology:
Thermal performance tiers stratify pricing power, with electrically insulating formulations commanding margin premiums by eliminating secondary passivation steps in high-voltage SiC modules.
- Thermal Conductive:Silver, copper, or aluminum-filled adhesives engineered for heat dissipation above 2 W/m-K through bondlines under 100 microns. Wolfspeed and Infineon specify these materials in approved vendor lists for 800V traction inverter platforms.
- Electrically Insulating:Ceramic-filled systems with dielectric strength above 15 kV/mm that isolate high-voltage SiC dies from grounded substrates without separate passivation layers. European module assemblers in the Netherlands and France prioritize these formulations to simplify stack geometry.
- UV Curing:Rapid processing adhesives for consumer electronics and prototyping applications.
- Two-Component:Mix-in-use systems for industrial drives requiring extended pot life.
- Solvent-Free:Environmental compliance formulations for REACH-regulated European assembly operations.
- High Modulus:Rigid adhesives for aerospace electronics with minimal creep under mechanical load.
Electrically insulating technology captures margin premiums; thermal conductive formulations anchor volume scale.
Application:
Power density trajectories diverge sharply across end-use segments, with automotive qualification cycles stretching 24-36 months while consumer electronics demand 6-12 month turnaround.
- Power Electronics:Broad category spanning server power supplies, telecom rectifiers, and data center infrastructure. Baseplate attachment and heat spreader bonding drive formulation requirements for thermal cycling survival above 10,000 cycles.
- Automotive Powertrain:Traction inverters, onboard chargers, and DC-DC converters for battery electric vehicles. US IRA domestic content requirements and EU Green Deal CO2 mandates are accelerating SiC module deployment across 400V and 800V architectures.
- Renewable Energy Systems:Solar inverters, wind turbine converters, and energy storage power conditioning systems.
- Aerospace Electronics:Satellite power systems and electric aircraft propulsion with outgassing certification per ASTM E595.
- Industrial Drives:Motor drives and automation equipment with moderate thermal cycling requirements.
- Consumer Electronics:Fast chargers and adapter applications with cost-sensitive, high-volume procurement.
Automotive powertrain commands longest qualification cycles; renewable energy systems offer steepest expansion trajectory as utility-scale solar and storage deployments accelerate.
End User:
Procurement authority is consolidating upstream, with semiconductor foundries displacing module assemblers as specification gatekeepers through approved material list centralization.
- Semiconductor Manufacturers:Wolfspeed, Infineon, STMicroelectronics, and Rohm now dictate adhesive selection at die design stage, compressing supplier diversity and extending qualification-driven lock-in periods.
- Electronic Assemblers:Packaging houses in Malaysia, Vietnam, and Mexico execute foundry-directed material choices with limited formulation discretion.
- Renewable Technology Firms:Solar inverter and energy storage system integrators with module-level adhesive procurement authority.
- Tier-1 Suppliers:Automotive module integrators such as BorgWarner and Vitesco executing OEM-directed specifications.
- Aerospace Contractors:Boeing, Airbus, and satellite manufacturers with aviation-specific certification requirements.
- Research Laboratories:National labs and university programs piloting next-generation sintering and transient liquid phase adhesive formats.
Semiconductor manufacturers concentrate specification authority; tier-1 suppliers retain fragmented procurement influence in legacy wire-bonded architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The high-temperature adhesives industry for SiC/GaN power module packaging traces its commercial roots to post-war German chemical engineering and Japanese electronics miniaturization, with both nations establishing early dominance in electronic-grade polymer formulation that persists in today's qualification-driven procurement landscape.
Germany
Automotive OEM qualification programs in Stuttgart and Munich drive die-attach material volumes for 800V traction inverters. The EU Green Deal mandates heavy-duty transport electrification by 2030, accelerating SiC module deployment across truck and bus platforms. Bavaria's power semiconductor cluster around Infineon anchors adhesive specification authority with European tier-1 suppliers.
United States
Detroit-area module assemblers scale procurement for electric powertrain die-attach rated above 200°C. The US IRA domestic content requirements incentivize localized adhesive manufacturing and technical service infrastructure. Wolfspeed's North Carolina operations centralize material selection at the foundry level, compressing supplier diversity.
Japan
Automotive powertrain manufacturers in Nagoya and Tokyo prioritize silicone formulations for thermal shock resistance across minus 40°C to 200°C cycling. METI domestic content targets redirect procurement toward Japanese adhesive formulators with established tier-1 relationships. Kyushu's power semiconductor packaging houses execute foundry-directed material choices.
Netherlands
High-voltage SiC module producers in Eindhoven accelerate alternative ceramic filler qualification to preempt REACH disruption. ECHA scrutiny of boron-based substances tightens supply security for boron nitride filler chemistries. ASMI and NXP operations centralize packaging decisions with captive foundry specifications.
South Korea
Hyundai and Kia electrification programs pull die-attach volumes for 400V and 800V inverter architectures. The country's national industrial policy supports compound semiconductor fab expansion with production-linked incentives. Seoul Capital Area packaging houses qualify materials against AEC-Q100 and AQG-324 automotive standards.
High-Temperature Adhesives for SiC/GaN Power Module Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification-driven automotive segments, where 24-36 month AEC-Q100 validation cycles create defensive moats against faster-moving industrial entrants. The vendor base stratifies into three tiers: diversified chemical conglomerates with automotive electronics portfolios, specialized sintering and thermal material formulators, and regional adhesive suppliers serving cost-sensitive consumer segments. Dominant competitive moves include strategic partnerships with semiconductor foundries for approved material list placement and backward integration into ceramic filler supply to mitigate REACH-related disruption.
Among diversified chemical conglomerates, Henkel and DuPont exemplify the premium-tier archetype through established automotive qualification relationships. Heraeus Electronics occupies a specialized position within the sintering-adhesive convergence space, representing the metallurgical bonding approach that enables high-current traction inverter designs. These three entities anchor the competitive structure by demonstrating how qualification depth and formulation breadth determine lock-in duration with consolidated foundry customers.
| Leading Market Players |
|---|
| Henkel |
| Heraeus Electronics |
| Indium Corporation |
| MacDermid Alpha Electronics Solutions |
| NAMICS Corporation |
| Shin-Etsu Chemical |
| DuPont |
| Dow |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Formulation chemists specializing in high-purity epoxy hardener synthesis concentrate in Germany's Ruhr industrial basin and Japan's Kansai corridor, with labor-cost differentials between these qualified talent pools and emerging Asian chemical hubs widening spreads between automotive-grade premium formulations and industrial-standard adhesives.
Pricing Analysis
Three-tier pricing structure across automotive-qualified, industrial-performance, and economy-grade adhesive levels governs procurement negotiations, with AEC-Q100 certification tier and silver filler loading percentage serving as primary price differentiation drivers. Cost compression in economy-grade epoxy segments is intensifying because Southeast Asian module assemblers are consolidating purchase volumes. Tier-1 automotive powertrain manufacturers exhibit lowest price sensitivity due to qualification lock-in, while consumer electronics fast-charger assemblers demonstrate highest sensitivity to per-gram adhesive costs.
Supply Chain Analysis
Workforce availability for ceramic filler processing and precision dispensing equipment operation concentrates in Japan, Germany, and South Korea, constraining rapid capacity expansion despite demand acceleration. Raw material dependencies center on silver flake from precious metal refiners, high-purity bisphenol-A from Northeast Asian petrochemical complexes, and boron nitride from limited specialty ceramic producers. Single-source vulnerability for electronic-grade hardeners creates supply chain risk given REACH authorization timelines for alternative chemistries. Distribution runs through semiconductor foundry-approved material lists that bypass traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal CO2 mandates for heavy-duty transport and US IRA domestic content requirements are structurally expanding adhesive procurement volumes faster than underlying semiconductor unit growth.
For Market Incumbents: Deploy backward integration into boron nitride and aluminum oxide filler supply to preempt REACH-driven ceramic substitution disruption. Anchor capacity addition in South Korea's Seoul Capital Area to capture Hyundai-Kia electrification procurement. Pressure from transient liquid phase sintering alternatives threatens silver-filled epoxy margins in 800V traction inverter applications. For New Entrants and Emerging Players: Begin with aviation electrification programs requiring ASTM E595 outgassing certification, where incumbent qualification backlogs create immediate white space. India's PLI scheme for compound semiconductor fabs offers the most penetrable geography given absent local technical service infrastructure. Target foundry technical partnership as the specific go-to-market angle rather than module assembler direct sales. For Investors and Strategic Acquirers: Specialty chemical conglomerates with automotive electronics portfolios are the most active acquirer in this space, seeking formulation breadth to complement existing die-attach material lines. Long-term viability hinges on sintering-adhesive hybridization capability development over the coming decade. Acquisition target archetype: regional adhesive formulators with captive automotive tier-1 relationships but limited foundry-approved material list placement. Watch Infineon and Wolfspeed approved vendor list expansion velocity as the inflection indicator signaling procurement consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Filler Supply | Henkel and DuPont are securing boron nitride sources to mitigate ECHA restriction risk. |
| Foundry Technical Partnership Formation | Heraeus Electronics anchors approved material list placement through Wolfspeed collaboration. |
| Aviation-Specific Certification Investment | Shin-Etsu Chemical targets ASTM E595 qualification for regional electric aircraft programs. |
| India Local Technical Service Buildout | NAMICS Corporation establishes compound semiconductor fab proximity to capture PLI scheme volumes. |
| Transient Liquid Phase Sintering Scale-Up | Indium Corporation pilots copper-tin alloy formats for 800V traction inverter thermal performance. |
Research Methodology
Multiple input streams — primary interviews with power module packaging engineers and adhesive formulation chemists, secondary validation through SEMI industry association reports and EPA fuel-economy rulemaking dockets, and customs data on silver-filled epoxy trade flows — were reconciled through bottom-up procurement volume modeling and top-down semiconductor unit demand triangulation.
Historical die-attach material consumption patterns were cross-referenced against panel input from automotive tier-1 procurement directors to establish baseline assumptions across the projection horizon. Segmentation dimensions modeled include resin chemistry type, thermal conductivity tier, application voltage architecture, and foundry versus module assembler procurement authority. CAGRs were derived from differential growth rates across 400V and 800V inverter deployment trajectories, with silicon carbide die attach area per module serving as a key industry-specific forecast input.
Several conditions sit outside the modeled scope, including potential ECHA restrictions on boron-based substances beyond current evaluation roadmaps and unforeseen substitutions to pure copper sintering in high-current applications. Forecasts reflect stated policy assumptions regarding IRA domestic content phase-in schedules and EU heavy-duty CO2 target enforcement. Material deviation in precious metal price volatility or automotive OEM platform cancellation decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.