
 Fan Out Packaging Market | 2026-2036
Fan Out Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fan Out Packaging Market Foresight
Multi-source sourcing of advanced packaging capacity is realigning competitive dynamics across the semiconductor supply chain. Taiwan Semiconductor Manufacturing Company leverages captive wafer-level fan-out production to secure priority allocation for leading-edge customers. ASE Technology Holding anchors outsourced assembly and test services with broad geographic manufacturing footprints. Amkor Technology competes through specialized fan-out portfolios serving automotive and communications end markets.
Fan out packaging redistributes input/output connections across an expanded die area using a redistribution layer, enabling higher pin density and thinner form factors than traditional wire bonding. The process typically employs epoxy mold compounds and silicon or glass carriers to create reconstituted wafers for subsequent bumping and singulation. Wafer-level fan-out dominates value capture due to its suitability for mobile processors and baseband modems where miniaturization commands premium pricing. Non-hermetic packaging grows fastest as cost-sensitive consumer applications tolerate reduced environmental protection. Automotive applications concentrate margin pools because AEC-Q100 qualification requirements filter out commoditized suppliers.
REACH compliance in Europe governs chemical substances in molding compounds and adhesives, while RoHS restricts lead content in redistribution layer metallization. The EPA oversees hazardous waste from etching and plating operations in U.S.-based packaging facilities. Japan's METI promotes domestic advanced packaging through supply chain resilience initiatives. Stakeholders must monitor evolving substance restrictions and regional subsidy programs when siting new fan-out capacity.
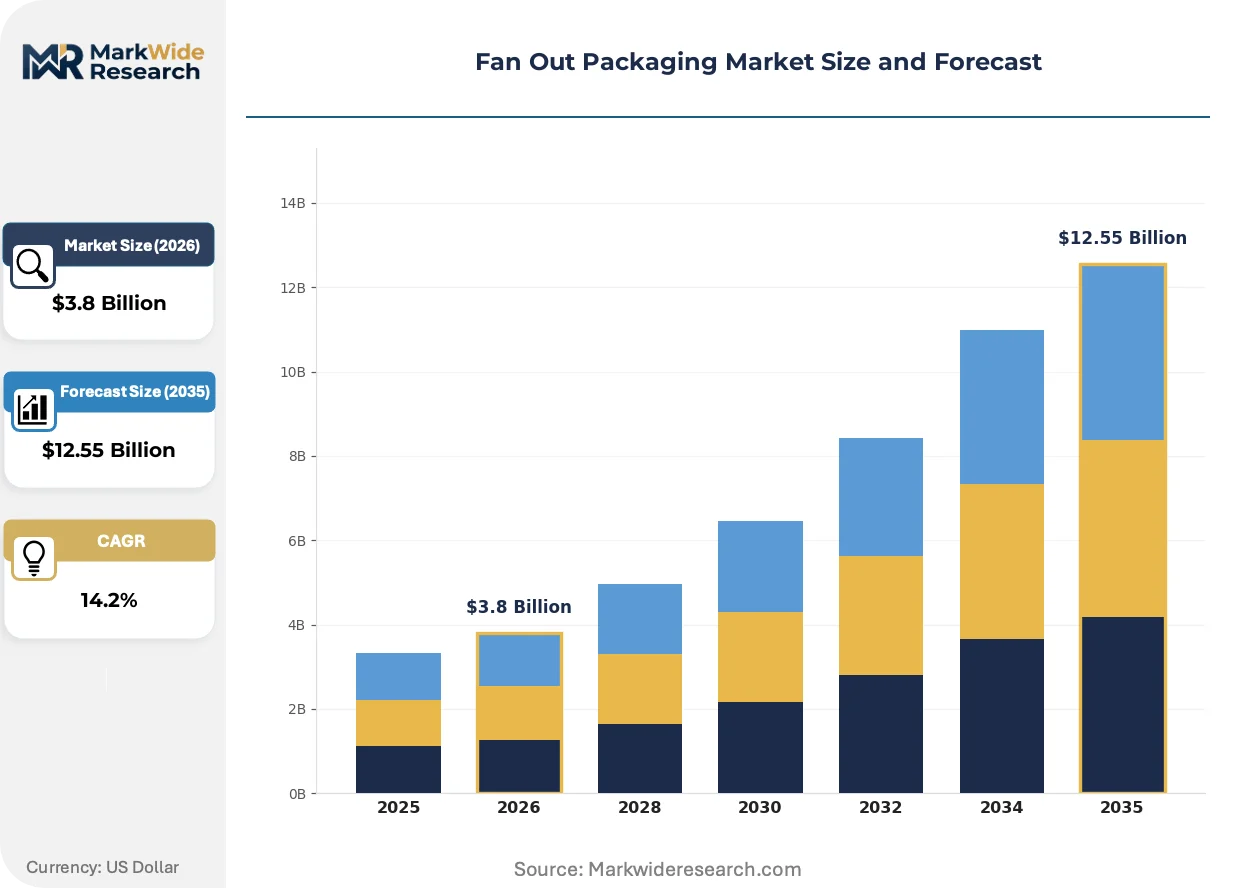
Market Dynamics
Wafer-level fan-out packaging is rewriting cost structures across semiconductor assembly as smartphone OEMs compress module thickness below 0.4mm while integrating multiple die functions. Taiwan's foundry concentration creates supply-side leverage that shapes pricing and capacity allocation globally.
Growth Catalysts
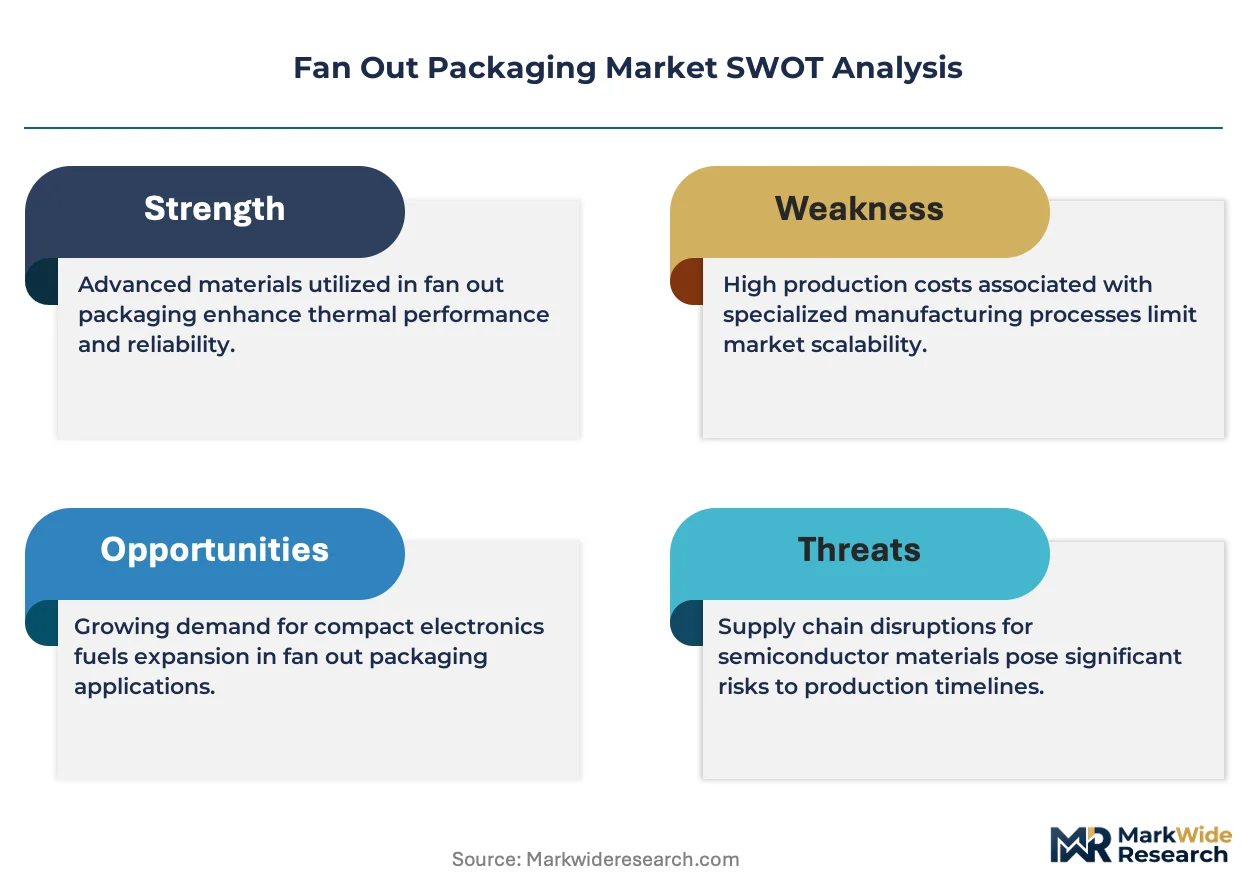
- EU RoHS Directive:Lead-free interconnect mandates accelerate migration from wire bonding to redistribution layer architectures in consumer electronics assembly.
- Epoxy Mold Compounds:Advanced thermal-mechanical properties enable thinner reconstituted wafers with improved warpage control for high-density mobile processors.
- Taiwan Foundry Cluster:Geographic concentration of advanced packaging capacity and substrate suppliers reduces logistics friction for fabless semiconductor customers.
Market Restraints
- Silicon Carrier Costs:Temporary bonding and debonding materials for reconstituted wafer processing account for disproportionate yield-loss exposure.
- Taiwan Supply Concentration:Single-region dependency for wafer-level fan-out capacity creates geopolitical risk and earthquake exposure for automotive qualification programs.
- Die Shift Limitations:Thermal expansion mismatches during mold compound curing restrict maximum die size and placement accuracy in high-density configurations.
Strategic Opportunities
- India PLI Scheme:Semiconductor assembly incentives attract fan-out packaging investments targeting domestic smartphone and automotive module demand.
- Automotive Radar Modules:AEC-Q100 qualification pathways open margin pools in advanced driver-assistance systems requiring hermetic fan-out variants.
- Glass Carrier Convergence:Transparent substrate integration with optical interconnects enables photonic fan-out packaging for data center transceivers.
Industry Challenges
- Redistribution Layer Lithography Talent:Shortage of process engineers skilled in fine-line RDL patterning on reconstituted wafers constrains capacity expansion timelines.
- Non-Hermetic Reliability Certification:Accelerated stress-test protocols for consumer-grade fan-out packages lag automotive qualification requirements by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fan Out Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hermetic, Non-Hermetic, Redistribution Layer, Wafer-Level Fan-Out Application: Consumer Electronics, Automotive, Telecommunication, Medical Devices Material: Silicon, Epoxy, Polyimide, Adhesives End User: OEMs, Contract Manufacturers, Semiconductor Manufacturers, Research Institutions |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, ASE Technology Holding, Amkor Technology, Samsung Electronics, JCET Group, Powertech Technology, SK Hynix, Samsung Electro-Mechanics, Nepes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fan Out Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape process flows and equipment specifications across fan-out packaging lines. Equipment vendors and chemical suppliers must coordinate roadmaps around evolving substance bans.
Panel-level fan-out processing is rewriting capital efficiency assumptions for high-volume consumer packaging. Display-grade substrate handling equipment from PCB manufacturing is migrating into semiconductor assembly lines. Equipment suppliers in South Korea and Taiwan are retrofitting panel coaters and exposure systems for 600mm square reconstituted panels, compressing cost-per-die by 30-40% against round-wafer alternatives at equivalent technology nodes.
REACH substance restrictions on bisphenol-A epoxies are forcing reformulation of mold compounds across European packaging facilities. ECHA's candidate list expansion drives substitution toward hydrogenated epoxy resins with modified anhydride curing agents. Japanese material suppliers are accelerating bio-based epoxy development to preempt regulatory action, while Taiwan compounders stockpile legacy formulations for non-EU export markets.
Smartphone OEMs now mandate die-to-die interconnect roadmaps extending fan-out into 3D architectures. Apple and Samsung procurement teams specify hybrid bonding compatibility for next-generation baseband modems, displacing solder bump interconnects below 10μm pitch. This specification cascade forces OSATs to reserve cleanroom capacity for plasma activation and room-temperature bonding, compressing legacy wire-bonding investment cycles in Malaysia and Vietnam packaging corridors.
Fan Out Packaging Market Segmentation
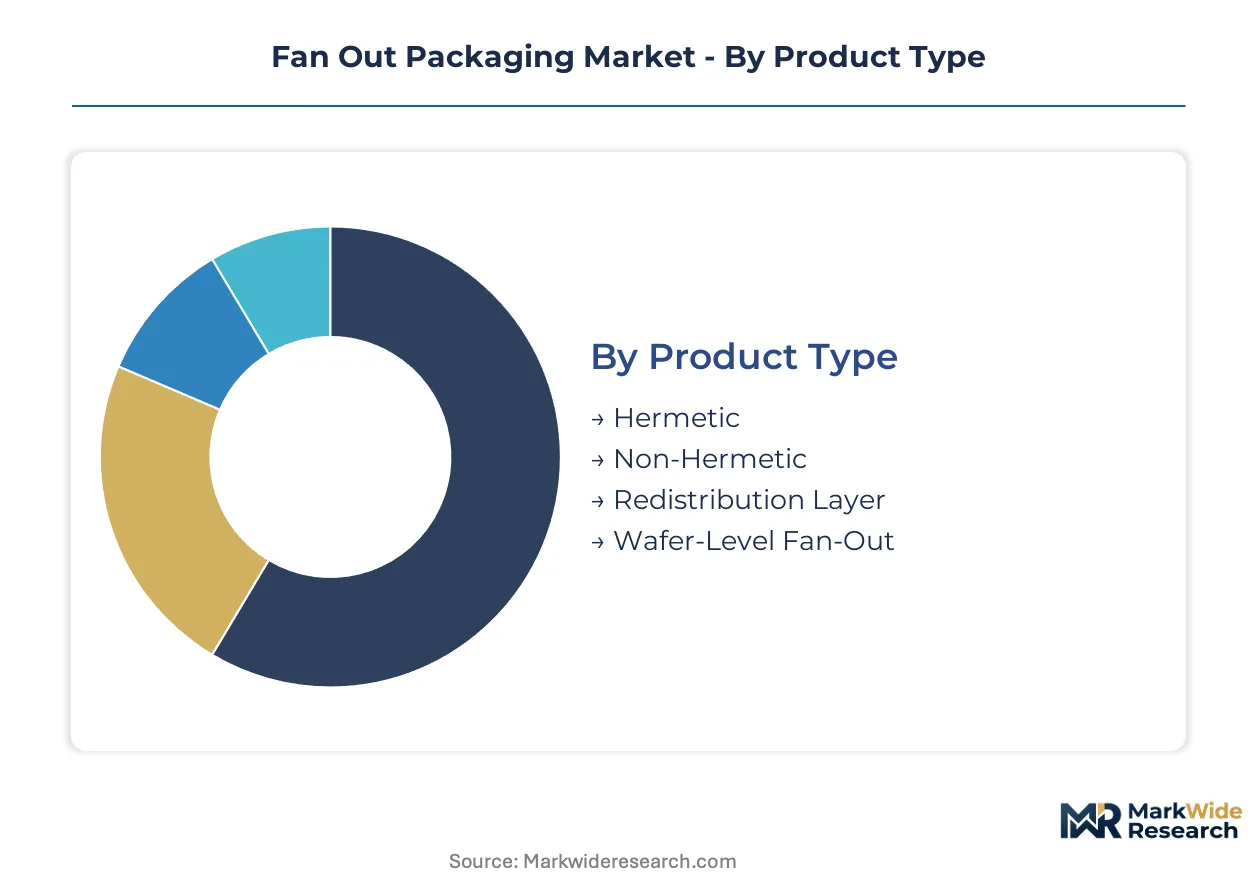
Fan out packaging segments diverge sharply in capital requirements and qualification barriers. Wafer-level configurations demand billion-dollar cleanroom investments while panel-level alternatives repurpose display equipment. Understanding these structural divides illuminates where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Capital intensity escalates dramatically from non-hermetic consumer variants to hermetic automotive-qualified packages requiring vacuum sealing and extended reliability testing.
- Hermetic:Vacuum-sealed ceramic or metal enclosures protect sensitive die from moisture and contaminants. Automotive radar modules and aerospace components in Germany and Japan drive qualification investments.
- Non-Hermetic:Epoxy mold compound encapsulation dominates smartphone and tablet processors where cost sensitivity outweighs environmental protection. Taiwan's OSATs process the highest volumes.
- Redistribution Layer:Fine-line copper traces on dielectric films reroute I/O pads across expanded die areas. Lithography equipment for sub-2μm line widths commands premium depreciation schedules.
- Wafer-Level Fan-Out:Reconstituted wafer processing integrates multiple die with through-mold vias for 3D stacking. Taiwan Semiconductor Manufacturing Company anchors captive capacity for leading-edge mobile processors.
Most installed capacity flows through Wafer-Level Fan-Out. Expansion is steepest in Non-Hermetic as cost-sensitive consumer applications absorb panel-level process migration.
Application:
Application segments separate by reliability certification intensity and volume scale, with automotive imposing AEC-Q100 barriers that filter out commoditized suppliers.
- Consumer Electronics:Smartphones, tablets, and wearables compress module thickness below 0.4mm while integrating baseband, RF, and power management die. Apple and Samsung procurement teams specify hybrid bonding roadmaps.
- Automotive:Advanced driver-assistance systems and electric vehicle power electronics demand hermetic variants with 15-year operational lifespans. Germany's KBA and Japan's METI shape qualification protocols.
- Telecommunication:Base station amplifiers and optical transceivers balance thermal performance with signal integrity. 5G massive MIMO deployments in South Korea accelerate demand.
- Medical Devices:Implantable pacemakers and diagnostic imaging equipment require biocompatible encapsulants and extended sterilization compatibility. FDA 510(k) pathways govern U.S. market entry.
Consumer Electronics absorbs the largest die volume. Automotive commands the steepest pricing premiums due to qualification filtration.
Material:
Material selection determines thermal-mechanical performance windows and regulatory compliance exposure across REACH-restricted chemistry portfolios.
- Silicon:Temporary carriers and permanent interposers provide matched thermal expansion for high-reliability configurations. Japan's Shin-Etsu and Germany's Siltronic anchor wafer supply.
- Epoxy:Mold compounds with silica filler control warpage in reconstituted wafers. ECHA's bisphenol-A restrictions force hydrogenated resin reformulation for European facilities.
- Polyimide:High-temperature dielectric films enable redistribution layers with low moisture absorption. Aerospace and defense applications in the U.S. specify military-grade formulations.
- Adhesives:Die attach and temporary bonding materials must survive thermal cycling without outgassing. Japanese suppliers accelerate bio-based development to preempt regulatory expansion.
Epoxy compounds represent the largest material volume. Polyimide is climbing fastest as fine-line redistribution layers proliferate.
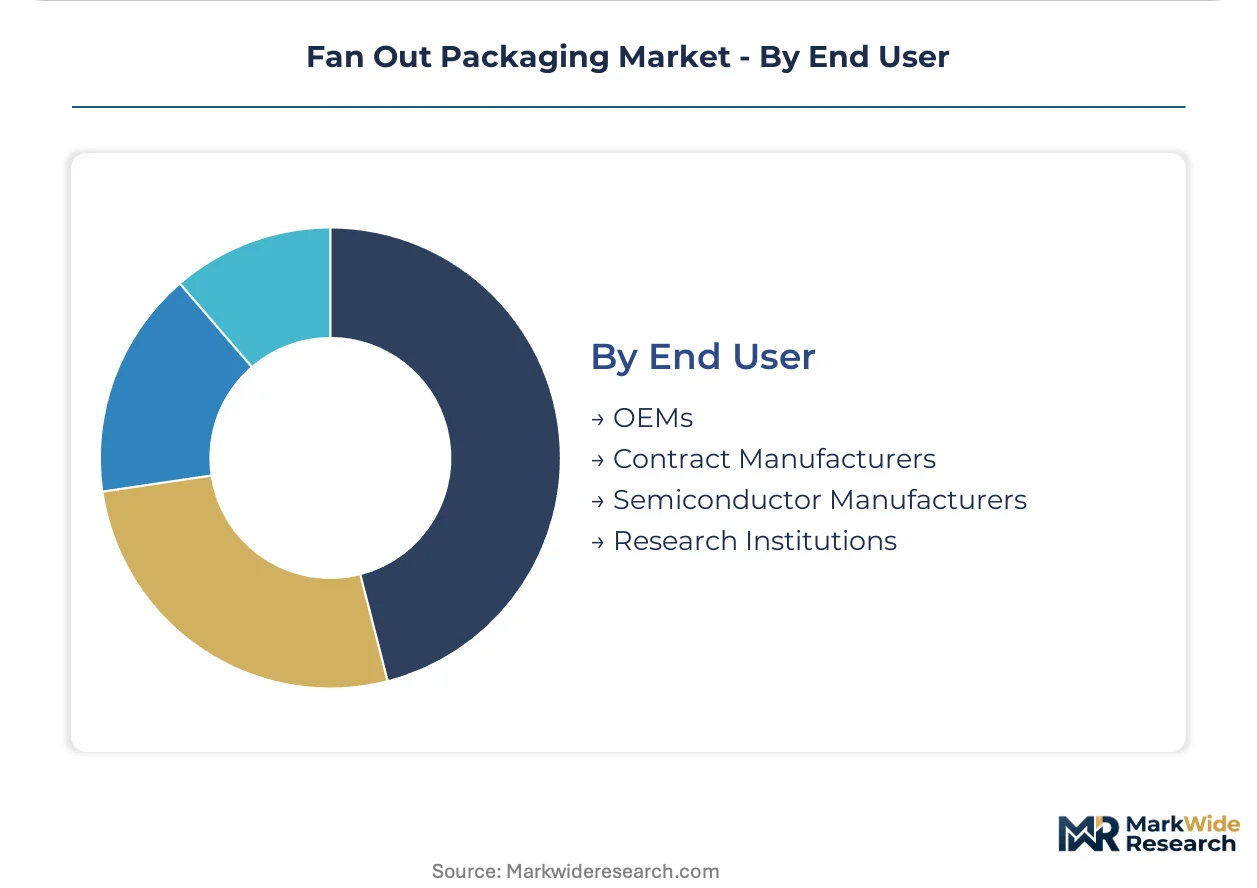
End User:
End user categories diverge by in-house packaging capability, with IDMs and foundries capturing value upstream while OSATs compete on scale and specialization.
- OEMs:Apple, Samsung, and automotive tier-1s specify fan-out requirements while outsourcing execution to captive or merchant suppliers. Vertical integration into packaging remains rare.
- Contract Manufacturers:Foxconn and Pegatron assemble modules incorporating fan-out packages from upstream suppliers. Their procurement leverage shapes pricing in high-volume consumer corridors.
- Semiconductor Manufacturers:IDMs like Intel and foundries like TSMC control wafer-level fan-out for proprietary products. Capacity reservation agreements lock in priority allocation.
- Research Institutions:IMEC in Belgium and CEA-Leti in France pilot panel-level and 3D integration concepts. Government funding from the EU Chips Act supports pre-competitive development.
Semiconductor Manufacturers deploy the most captive capacity. Research Institutions are expanding fastest as public funding for advanced packaging R&D accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing fan-out packaging investments as REACH compliance costs in Europe push capacity toward Asian jurisdictions with streamlined chemical substance oversight. Manufacturers weigh RoHS alignment against logistics proximity to fabless semiconductor customers.
Taiwan
Smartphone processor demand and baseband modem integration drive wafer-level fan-out volumes at TSMC and ASE facilities. The island's EPA oversees industrial waste from plating and etching operations in Hsinchu and Taichung science parks. Tainan anchors the highest concentration of advanced packaging cleanrooms globally, with substrate suppliers clustered within 50-kilometer radii of major OSATs.
South Korea
5G massive MIMO deployments and memory-logic integration requirements accelerate panel-level fan-out adoption. METI-equivalent Korean regulators enforce hazardous substance reporting for mold compound imports under K-REACH frameworks. Seoul Capital Area manufacturers retrofit display-grade coaters for 600mm square reconstituted panels, compressing die costs against round-wafer alternatives.
United States
Automotive radar modules and aerospace hermetic packages sustain niche demand for AEC-Q100 and MIL-STD-883 qualified production. The EPA monitors hazardous waste streams from California and Arizona packaging facilities under RCRA permitting. Greater Phoenix hosts captive packaging operations for defense and satellite communication die, insulated from consumer pricing pressure.
China
Domestic smartphone OEM procurement mandates and EV power electronics expansion drive non-hermetic fan-out capacity buildout. MIIT administers GB standards for electronic component environmental protection, with RoHS-equivalent restrictions on lead content. Yangtze River Delta clusters in Jiangsu and Shanghai provinces concentrate imported lithography equipment for redistribution layer processing.
Japan
Automotive tier-1 supplier qualification programs and medical device encapsulant requirements sustain premium hermetic packaging demand. METI promotes domestic advanced packaging through supply chain resilience subsidies and pre-competitive R&D consortia. Kyushu-based material suppliers accelerate bio-based epoxy development to preempt ECHA regulatory expansion into Asian export markets.
Fan Out Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue panel-level cost compression and automotive qualification pathways. The vendor base stratifies across captive foundry operations, merchant OSATs with geographic diversification, and specialized automotive-focused assemblers. Three archetypes dominate: integrated device manufacturers with in-house packaging, pure-play packaging houses with multi-site footprints, and substrate-integrated specialists controlling material input costs. Capacity reservation agreements and strategic equipment partnerships constitute the primary competitive levers.
Within the captive-foundry tier, Taiwan Semiconductor Manufacturing Company exemplifies vertical control over leading-edge wafer-level fan-out. Among merchant OSATs, ASE Technology Holding and Amkor Technology occupy positions spanning consumer and automotive qualification portfolios. These three entities represent the structural poles around which pricing and capacity allocation dynamics organize.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| ASE Technology Holding |
| Amkor Technology |
| Samsung Electronics |
| JCET Group |
| Powertech Technology |
| SK Hynix |
| Samsung Electro-Mechanics |
| Nepes |
| Others |
Supply & Pricing Matrix
Silica-filled epoxy mold compound pricing indices cascade through fan-out packaging supply chains, compressing margins on non-hermetic consumer tiers while hermetic automotive variants absorb cost pass-through via AEC-Q100 qualification premiums. Taiwan's substrate supplier concentration amplifies pricing power upstream, forcing OSATs in Malaysia and Vietnam to absorb logistics premiums or surrender volume share.
Pricing Analysis
Input-cost pass-through from hydrogenated epoxy resin reformulation under REACH restrictions stratifies pricing across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive modules from consumer-grade non-hermetic packages and commodity wire-bond alternatives. Cost compression in standard-tier fan-out is intensifying because panel-level equipment migration from display manufacturing compresses die costs by 30-40% against round-wafer processing. Consumer electronics OEMs exhibit highest price sensitivity, while automotive tier-1 suppliers tolerate premiums for 15-year operational lifespan guarantees.
Supply Chain Analysis
Freight cost differentials between air-shipped temporary bonding materials and sea-freight mold compounds concentrate margin pressure on reconstituted wafer logistics. Supply concentrates in Taiwan, South Korea, and China, with Taiwan anchoring wafer-level capacity and South Korea retrofitting panel-level display equipment. Raw material dependencies draw from Japanese epoxy resin suppliers, German silicon wafer producers, and Taiwanese substrate manufacturers. Single-source vulnerability for sub-2μm lithography equipment from Dutch and Japanese vendors creates qualification bottlenecks. Distribution runs through fabless semiconductor procurement teams in Hsinchu and San Jose, with capacity reservation agreements locking priority allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fan-out packaging has matured into a late-cycle quality story as smartphone OEMs mandate hybrid bonding roadmaps and automotive radar modules filter suppliers through AEC-Q100 protocols. Premium specifications now command sustainable margin pools that commoditized wire-bond alternatives cannot replicate.
For Market Incumbents: Deploy capacity reservation agreements as the primary lever to lock fabless semiconductor priority allocation before panel-level cost compression erodes wafer-level premiums. Defensive consolidation moves should concentrate on securing temporary bonding material supply from Japanese vendors and qualifying secondary redistribution layer lithography sources to mitigate single-equipment vulnerability. The threat of glass carrier convergence in photonic packaging demands pre-emptive cleanroom investment in optical interconnect compatibility. For New Entrants and Emerging Players: The 40-50% price-point gap between hermetic automotive and non-hermetic consumer tiers opens white-space targeting at mid-tier industrial applications requiring extended temperature cycling without vacuum sealing. India's PLI scheme subsidies offer the most penetrable geography for greenfield panel-level capacity serving domestic smartphone module demand. Go-to-market execution should anchor on automotive qualification pathway partnerships with German KBA-recognized test facilities. For Investors and Strategic Acquirers: Asymmetric upside sits with panel-level equipment retrofit specialists controlling display-grade coater and exposure system supply. Long-term viability over a 5-10 year window favors acquisition targets with captive substrate integration and established REACH-compliant chemistry portfolios. The inflection signal to monitor is hybrid bonding specification adoption rates in Apple and Samsung procurement roadmaps, which would accelerate displacement of solder bump architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Panel-Level Capacity Expansion | Retrofitting 600mm square display equipment compresses die costs against round-wafer alternatives. |
| Hydrogenated Epoxy Reformulation | REACH-compliant resin substitution protects European facility access against ECHA substance restrictions. |
| Hybrid Bonding Cleanroom Reservation | Plasma activation capacity secures qualification for sub-10μm pitch baseband modem roadmaps. |
| AEC-Q100 Qualification Pathway | Automotive radar module certification filters out commoditized suppliers in ADAS margin pools. |
| Glass Carrier Optical Integration | Transparent substrate convergence enables photonic fan-out for data center transceiver applications. |
Research Methodology
Coverage spans Taiwan, South Korea, China, the United States, and Japan, with primary inputs from each region's packaging ecosystem. Primary interviews with OSAT operations executives, fabless semiconductor procurement directors, epoxy compound R&D leads, and lithography equipment application engineers combined with secondary validation from SEC filings, Taiwan EPA industrial waste permits, ECHA substance restriction updates, and SEMI equipment shipment databases. Bottom-up die volume estimates and top-down foundry capacity announcements underwent triangulation to reconcile supply-side and demand-side perspectives.
Rate-of-change decomposition across the analysis window isolated volume drivers from price-mix effects in wafer-level versus panel-level process migration. Segmentation dimensions modeled include package type, application sector, material chemistry, and end-user category, with technology node and redistribution layer line width as industry-specific forecast inputs. CAGRs were derived from logistic adoption curves for hybrid bonding penetration and panel-level equipment installation timelines.
The model assumes a particular technology adoption path; alternative pathways for glass carrier optical interconnects would alter the outlook if photonic integration accelerates beyond baseband modem applications. Forecasts reflect assumptions regarding REACH substance restriction enforcement timelines and Taiwan seismic risk exposure. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market