
 Chip Carrier Socket Market | 2026-2036
Chip Carrier Socket Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Carrier Socket Market Insights
Server and datacenter OEMs are gaining procurement share as consumer electronics brands scale back socket volumes, while the chip carrier socket demand base is bifurcating between high-reliability industrial buyers and cost-optimized consumer tiers. TE Connectivity leverages vertical integration into precision stamping and plating operations to secure automotive qualification pipelines. Amphenol competes through geographic dominance in Asian manufacturing clusters, while Molex differentiates via R&D intensity in high-speed signal integrity socket architectures.
A chip carrier socket is a mechanical interconnect device designed to house integrated circuits without permanent soldering, typically fabricated from high-temperature thermoplastics with beryllium copper or phosphor bronze contact springs and engineered for insertion forces below 100 grams per pin. Its primary purpose is to enable field replacement, test access, and burn-in cycling for semiconductor packages across production and service environments. Ball grid array sockets command premium positioning due to pitch density requirements in server processors, while surface mount technology leads volume production across consumer electronics. Through hole configurations retain structural share in automotive and aerospace modules where vibration resistance and rework accessibility carry priority over miniaturization.
ISO 9001 quality management and IEC 60191 mechanical standardization govern socket dimensional interchangeability and contact reliability testing protocols, with RoHS and REACH compliance in Europe restricting hazardous substance content in plating chemistries and substrate resins. In the United States, NHTSA functional safety expectations and EPA chemical reporting obligations shape automotive socket qualification pathways. Stakeholders must monitor evolving packaging form factors from leading processor architects and align contact metallurgy investments with impending halogen-free material mandates.
Market Dynamics
Ball grid array socket architectures are compressing contact pitch specifications below 0.8mm as server processor packaging drives mechanical interconnect precision to physical limits.
Growth Catalysts
- EU Green Deal material mandates:REACH substance restrictions are accelerating tin-lead to pure tin plating conversions across European automotive supply chains.
- Taiwan's semiconductor packaging corridor:OSAT concentration in Hsinchu and Tainan is driving socket specification standardization for advanced packaging nodes.
- Electric powertrain controllers:German and Japanese automotive module assembly lines are expanding ball grid array socket procurement for high-voltage control systems.
Market Restraints
- Beryllium copper contact spring costs:Volatility in specialty copper alloy pricing compresses margin structures for high-reliability socket tiers.
- Taiwan supply concentration:Single-source dependency on precision stamping clusters creates geopolitical exposure for global socket procurement.
- Phosphor bronze fatigue limits:Insertion cycle degradation below 500 operations restricts field-replacement applications in industrial automation.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic packaging incentives are attracting socket manufacturers to Gujarat and Karnataka corridors.
- Halogen-free substrate resins:IEC 60191 alignment with flame-retardant chemistry bans opens premium positioning for compliant socket families.
- High-speed signal integrity convergence:PCIe 5.0 and DDR5 memory channel requirements are fusing mechanical and electrical socket design disciplines.
Industry Challenges
- ISO 9001 certification timelines:Automotive qualification pathways require 18-24 month validation cycles that delay new socket product launches.
- Legacy through-hole rework accessibility:Surface mount technology migration is straining service infrastructure for vibration-critical aerospace modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Carrier Socket Market |
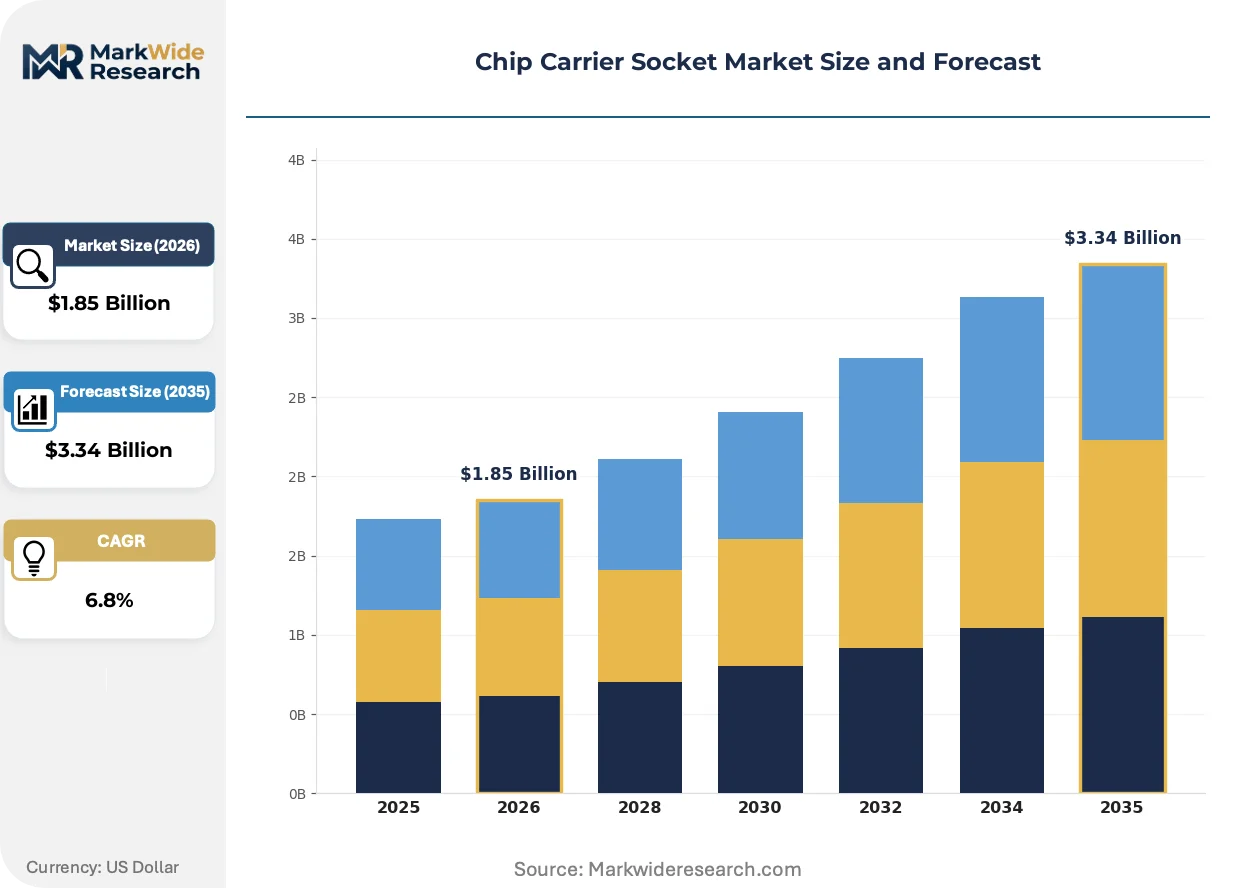
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual In-line Package, Pin Grid Array, Quad Flat Package, Ball Grid Array Technology: Surface Mount, Through Hole, Hybrid, Leadless End User: Consumer Electronics, Automotive, Telecommunications, Aerospace Installation: Manual, Automated, Semi-Automated, Inspection |
| Companies Covered | TE Connectivity, Samtec, 3M, Amphenol, Molex, Kycon Inc, Adam Tech, TruConnect, HARTING Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Carrier Socket Market Trends and Innovations
Contact metallurgy and substrate material science are converging to address thermal cycling reliability while regulatory chemistry restrictions force plating system replacements.
Land grid array sockets with beryllium copper contact springs are miniaturizing pitch density to 1.0mm and below for server processor applications. Datacenter OEMs in the United States are specifying these configurations for thermal management of 500W+ chips. The technology is miniaturizing mechanical interconnect footprints while maintaining insertion force below 100 grams per pin.
REACH substance restrictions in Europe are prohibiting hexavalent chromium and cadmium in plating chemistries for automotive socket applications. ECHA enforcement is forcing suppliers to validate pure tin and nickel-palladium-gold alternatives through accelerated corrosion testing. German Tier-1 module suppliers are absorbing qualification costs to maintain CE marking compliance.
Buyer concentration among server and datacenter OEMs is displacing fragmented consumer electronics procurement with consolidated volume contracts. Direct sourcing relationships are replacing distributor intermediaries for high-reliability socket tiers. Taiwan-based OSATs are consolidating specification authority through captive socket design partnerships.
Chip Carrier Socket Market Segmentation
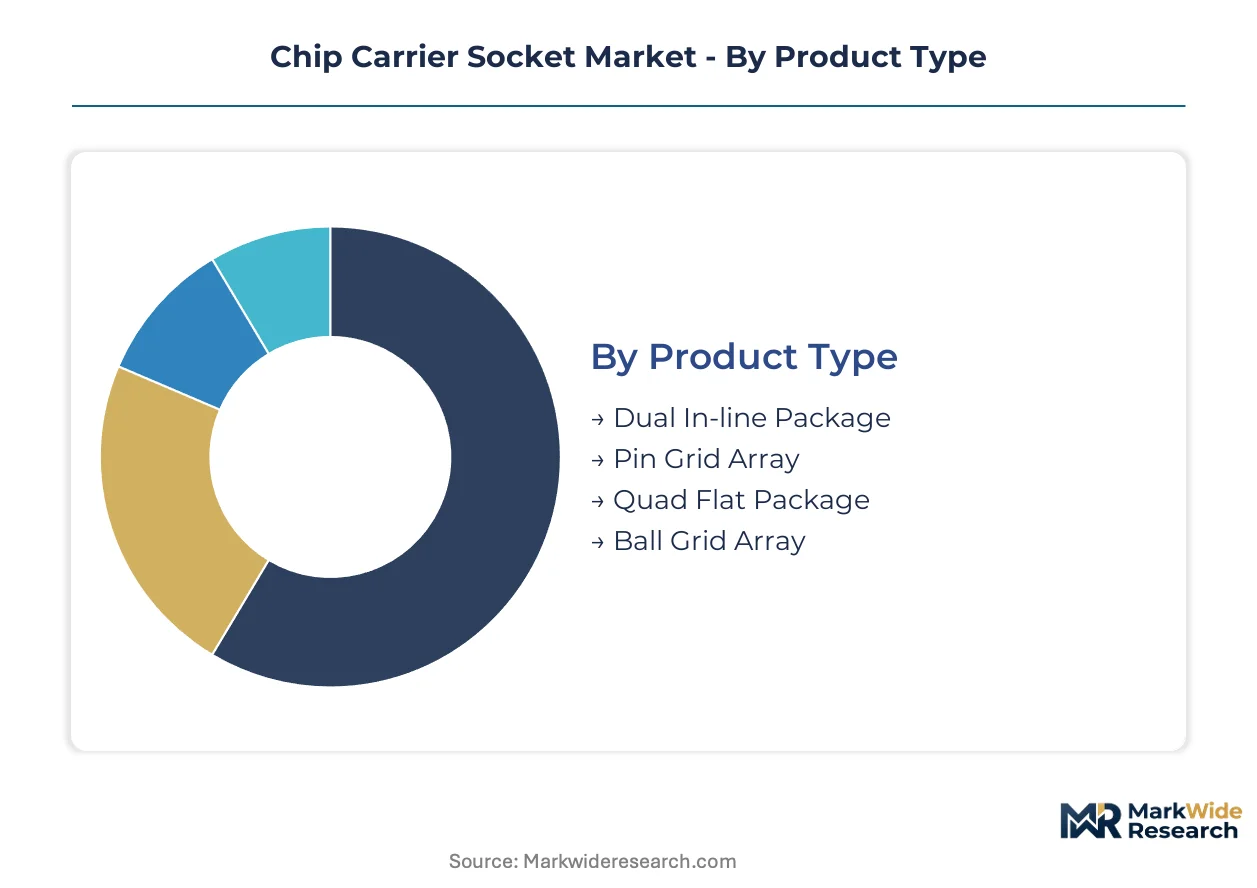
Chip carrier socket procurement patterns diverge sharply across product architectures and installation methods. Regulatory compliance tiers in automotive and aerospace verticals create premium qualification pathways that reshape segment profitability structures.
Product Type:
REACH substance restrictions and EU Green Deal material mandates differentiate plating system requirements across socket form factors, with high-density arrays facing stricter metallurgical validation.
- Ball Grid Array:High-density interconnect architecture with pitch specifications compressing below 0.8mm for server processor applications. Datacenter OEMs in the United States specify these configurations for thermal management of 500W+ chips, with beryllium copper contact springs maintaining insertion forces below 100 grams per pin despite miniaturization pressures.
- Dual In-line Package:Legacy through-hole configuration retaining structural share in industrial automation modules where rework accessibility and vibration resistance carry priority over density. German automotive module assembly lines continue procurement for electric powertrain controller applications where field replacement cycles exceed 500 operations.
- Pin Grid Array:Perimeter contact arrangement with moderate density suited for mid-range computing hardware.
- Quad Flat Package:Gull-wing lead configuration dominant in consumer electronics volume production.
Established volume favors Dual In-line Package; emerging adoption favors Ball Grid Array.
Technology:
Cost tier stratification separates high-reliability industrial specifications from consumer-optimized production economics.
- Surface Mount:Dominant volume production technology across consumer electronics, utilizing automated pick-and-place assembly with reflow soldering compatibility. Taiwan-based OSATs drive specification standardization for this segment through captive socket design partnerships with packaging houses in Hsinchu and Tainan corridors.
- Through Hole:Structural retention in aerospace modules where vibration resistance and manual rework accessibility override miniaturization imperatives. NHTSA functional safety expectations in the United States prolong automotive qualification timelines for these configurations.
- Hybrid:Mixed mounting approach bridging density and mechanical reliability requirements.
- Leadless:Miniaturized footprint technology gaining traction in space-constrained telecommunications hardware.
Surface Mount commands production scale; Through Hole retains service infrastructure value.
End User:
Application criticality determines contact metallurgy investments and certification depth across buyer verticals.
- Automotive:High-reliability tier requiring ISO 9001 quality management and 18-24 month validation cycles for ball grid array sockets in electric powertrain controllers. German and Japanese module assembly lines absorb qualification costs to maintain CE marking compliance under ECHA enforcement of REACH substance restrictions.
- Aerospace:Vibration-critical applications where phosphor bronze fatigue limits below 500 insertion cycles restrict field-replacement automation. Legacy through-hole rework accessibility faces strain from surface mount technology migration.
- Consumer Electronics:Cost-optimized procurement with consolidated volume contracts displacing fragmented distributor relationships.
- Telecommunications:Signal integrity requirements fusing mechanical and electrical design disciplines for PCIe 5.0 and DDR5 memory channels.
Automotive anchors qualification-intensive revenue; telecommunications shows steepest expansion trajectory.
Installation:
Supply concentration in Taiwan's precision stamping clusters shapes equipment sourcing patterns for assembly line automation.
- Automated:High-throughput assembly line integration for surface mount technology across consumer electronics and server manufacturing. India's PLI scheme for semiconductors is attracting socket manufacturers to Gujarat and Karnataka corridors for automated production infrastructure.
- Manual:Retained for aerospace module assembly where low-volume, high-mix production economics favor operator-controlled insertion force management.
- Semi-Automated:Intermediate configuration for mid-scale automotive module production.
- Inspection:Quality validation stage integrated with IEC 60191 mechanical standardization protocols for contact reliability testing.
Automated installation scales with OSAT concentration; manual methods persist in aerospace certification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Socket procurement patterns cluster around precision stamping infrastructure and semiconductor packaging corridors. Taiwan's OSAT concentration and Germany's automotive module assembly lines anchor supply-side activity. Regulatory enforcement in Europe and industrial policy in Asia are reshaping plating chemistry investments and qualification timelines.
United States
Datacenter OEMs in California and Texas are specifying land grid array sockets for thermal management of high-wattage server processors. NHTSA functional safety expectations prolong automotive qualification cycles for through-hole configurations. The Pacific Northwest hosts precision stamping operations serving aerospace module suppliers.
Germany
Tier-1 automotive module suppliers absorb qualification costs for ball grid array sockets in electric powertrain controllers. ECHA enforcement of REACH substance restrictions mandates pure tin plating alternatives to hexavalent chromium systems. Bavarian assembly lines maintain procurement of dual in-line package configurations for field-replacement cycles.
Japan
Automotive module assembly lines expand ball grid array socket procurement for high-voltage control systems. METI industrial standards govern contact reliability testing protocols for burn-in cycling applications. The Nagoya industrial corridor concentrates precision stamping capacity for high-reliability contact springs.
Taiwan
OSATs in Hsinchu and Tainan drive socket specification standardization for advanced packaging nodes. The country's national semiconductor regulator aligns domestic standards with IEC 60191 mechanical protocols. Captive socket design partnerships with packaging houses consolidate procurement authority.
India
Domestic packaging incentives under the PLI scheme attract socket manufacturers to Gujarat and Karnataka corridors. CDSCO-equivalent industrial standards are emerging for automotive qualification pathways. Automated production infrastructure is scaling in the Delhi-Mumbai industrial belt.
Chip Carrier Socket Market Competitive Landscape
Concentration sits with diversified interconnect specialists and precision stamping operators. The vendor base spans three tiers: global diversified electrical component houses, regional precision metalwork specialists, and captive socket design units within OSATs. Consolidation pressures favor backward integration into plating operations and captive supply of beryllium copper alloys. Geographic expansion into India's PLI corridors and technology licensing for high-speed signal integrity architectures represent dominant competitive vectors.
Among diversified electrical component houses, TE Connectivity, Amphenol, and Molex exemplify archetype positioning through scale and qualification depth. TE Connectivity occupies a position emphasizing captive production of precision stamping and plating operations. Amphenol represents geographic anchoring in Asian manufacturing clusters. Molex exemplifies R&D intensity in high-speed signal integrity socket architectures. These three entities sit within the premium tier where ISO 9001 certification and 18-24 month automotive validation cycles create barrier structures.
| Leading Market Players |
|---|
| TE Connectivity |
| Samtec |
| 3M |
| Amphenol |
| Molex |
| Kycon Inc |
| Adam Tech |
| TruConnect |
| HARTING Technology Group |
| Others |
Pricing and Supply Chain Analysis
ISO 9001 certification gates both supplier qualification and price differentiation simultaneously, creating tiered access where automotive validation cycles absorb 18-24 month cost burdens that flow through to premium socket pricing. German Tier-1 module suppliers absorb these qualification costs to maintain CE marking compliance, while cost-optimized consumer tiers bypass certification depth entirely.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European automotive supply chains. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified automotive sockets from industrial-grade configurations and consumer-optimized surface mount variants. Cost compression in beryllium copper contact tiers is intensifying because of specialty alloy price volatility. Consumer electronics procurement shows highest price sensitivity; datacenter OEMs demonstrate lowest sensitivity due to thermal management specifications for 500W+ chips.
Supply Chain Analysis
Taiwan Strait shipping lanes underwrite precision stamping cluster access for global socket procurement. Manufacturing gravity centers on Taiwan, Germany, and Japan, with raw material feeds drawing from Chilean copper concentrate, Indonesian nickel, and domestic phosphor bronze alloy production. Single-source dependency on Hsinchu and Tainan precision stamping creates geopolitical exposure for contact spring supply. Distribution runs through direct sourcing relationships with OSATs for high-reliability tiers, replacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified precision stamping capacity represents the binding constraint, with 18-24 month automotive certification timelines creating defendable moats for incumbents while excluding rapid entrants.
For Market Incumbents: Secure captive supply of beryllium copper alloys through backward integration into plating operations, insulating margin structures from specialty metal volatility. Deepen ISO 9001 certification pipelines to prolong validation timelines that deter emerging Asian competitors from automotive qualification pathways. For New Entrants and Emerging Players: Post-sales technical support for legacy through-hole configurations in aerospace modules offers under-served service layers where incumbents have deprioritized manual rework accessibility. India's PLI scheme corridors present the most penetrable geography, with Gujarat and Karnataka automated production infrastructure scaling under domestic packaging incentives. Lead with halogen-free substrate resin compliance as a regulatory-first go-to-market angle. For Investors and Strategic Acquirers: EU Green Deal material mandates reshape the acquisition landscape by forcing plating chemistry replacements that favor vertically integrated precision metalwork specialists over pure-play distributors. Five-to-ten year viability favors targets with in-house nickel-palladium-gold validation capabilities and existing ECHA enforcement relationships. Monitor ECHA substance restriction expansion timelines as the critical inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Operations | Captive nickel-palladium-gold capacity secures REACH compliance margins against ECHA enforcement waves. |
| Halogen-Free Substrate Certification | IEC 60191 alignment opens premium positioning as flame-retardant chemistry bans propagate through Europe. |
| India PLI Corridor Manufacturing Scale-Up | Gujarat and Karnataka infrastructure captures domestic packaging incentives under CDSCO-equivalent standards. |
| High-Speed Signal Integrity R&D Partnership | PCIe 5.0 socket architectures fuse mechanical and electrical design disciplines for datacenter OEM specifications. |
| OSAT Captive Design Partnership | Taiwan packaging house alliances consolidate procurement authority for advanced node socket standardization. |
Research Methodology
Cross-validation between primary interviews with socket procurement managers, OSAT packaging engineers, and automotive Tier-1 supplier quality directors anchors the qualitative findings against secondary validation from SEC 10-K filings, customs trade data, and IEC 60191 mechanical standard documentation. Bottom-up demand modeling from individual packaging node specifications triangulates with top-down semiconductor capital equipment expenditure tracking.
Sensitivity analysis across beryllium copper price scenarios and Taiwan supply disruption probabilities tests forecast robustness over the projection horizon. Segmentation dimensions include socket form factor, mounting technology, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and electric powertrain controller socket penetration curves.
Material uncertainties — REACH substance list expansion, Taiwan strait logistics disruption, and phosphor bronze fatigue limit breakthroughs — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and OSAT geographic diversification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Asia Pacific LED Packaging Market