
 System-On-Package Market | 2026-2036
System-On-Package Market Size, Share, and Industry Trends Forecast 2026-2036
System-On-Package Market Analytics
EU RoHS substance restrictions and REACH chemical compliance is expanding the cost-of-entry calculus for System-On-Package suppliers serving European automotive and medical device clients. ASE Technology Holding leverages captive substrate capacity to sustain margin control across flip-chip and wire-bonding lines. TSMC anchors advanced-node 3D packaging leadership through CoWoS and SoIC platforms. Amkor Technology competes on geographic diversification, operating high-volume facilities in Portugal, Vietnam, and South Korea to navigate tariff and logistics complexity.
System-On-Package denotes a multi-die integration architecture where heterogeneous chips—processors, memory, RF components, and sensors—are assembled within a single encapsulated unit using interposers, redistribution layers, or through-silicon vias to achieve functional density exceeding traditional system-on-chip limits. TSV technology commands premium positioning as the enabler of true 3D stacking with sub-100-micron pitch interconnects, while wire bonding retains volume dominance in cost-sensitive consumer electronics and legacy automotive modules. Embedded System products lead in unit shipments for IoT and wearable applications, whereas Mixed Signal System configurations capture widening margin pools as medical device OEMs demand analog-digital fusion for portable diagnostics.
FDA device classification rules and EU MDR technical documentation requirements shape product validation cycles for medical-grade System-On-Package suppliers, extending qualification timelines but creating defensible certification moats. Japan's METI semiconductor revitalization subsidies and South Korea's K-Semiconductor Belt tax incentives are redirecting capital toward domestic advanced packaging ecosystems. Stakeholders must monitor how export control frameworks on deposition and lithography equipment propagate into packaging tool availability and regional capacity buildout decisions.
Market Dynamics
TSV pitch scaling below 50-micron is compressing thermal management margins while automotive electrification mandates force heterogeneous integration roadmaps. Foundry concentration in Taiwan and South Korea locks substrate access for mid-tier assemblers.
Growth Catalysts
- EU F-Gas Regulation phase-down:High-GWP fluorinated gases face supply constraints, accelerating dry etch and plasma dicing adoption for hermetic System-On-Package sealing in automotive sensor modules.
- Japan METI semiconductor subsidies:Domestic advanced packaging capacity expansion redirects capital toward TSV-enabled 3D stacking for medical imaging equipment.
- Heterogeneous integration:Chiplets displace monolithic SoC designs in AI accelerators, pulling demand for interposer-based System-On-Package architectures with sub-100-micron interconnect pitch.
Market Restraints
- Substrate supply concentration:Ajinomoto Build-up Film (ABF) substrate capacity concentrates among three Japanese suppliers, creating allocation risk for flip-chip ball grid array packages.
- EU MDR technical documentation:Extended validation timelines for Class IIb medical devices stretch qualification cycles to 18-24 months, freezing design iterations.
- Wire bonding cost floor:Gold and copper wire price volatility compresses margins in legacy automotive modules where TSV migration remains uneconomical.
Strategic Opportunities
- Vietnam packaging corridor:Amkor and ASE facility investments near Ho Chi Minh City create tariff-advantaged export capacity for North American automotive OEMs.
- Photonics-electronics convergence:Silicon photonics co-packaging with CMOS logic opens bandwidth density for datacenter optical interconnects using TSV-enabled 3D stacking.
- South Korea K-Semiconductor Belt tax credits:Domestic R&D expenditure deductions redirect foundry capital toward fan-out panel-level packaging scale-up.
Industry Challenges
- Thermal-mechanical modeling talent:Finite element analysis expertise for multi-physics chip-package interaction simulation remains scarce across packaging houses.
- EU REACH substance authorization:SVHC candidate list expansion forces material requalification for underfill and molding compounds, disrupting qualified product lists.
- Legacy automotive ECU integration:10-15 year vehicle platform lifecycles lock wire-bonded System-On-Package designs, constraining TSV upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System-On-Package Market |
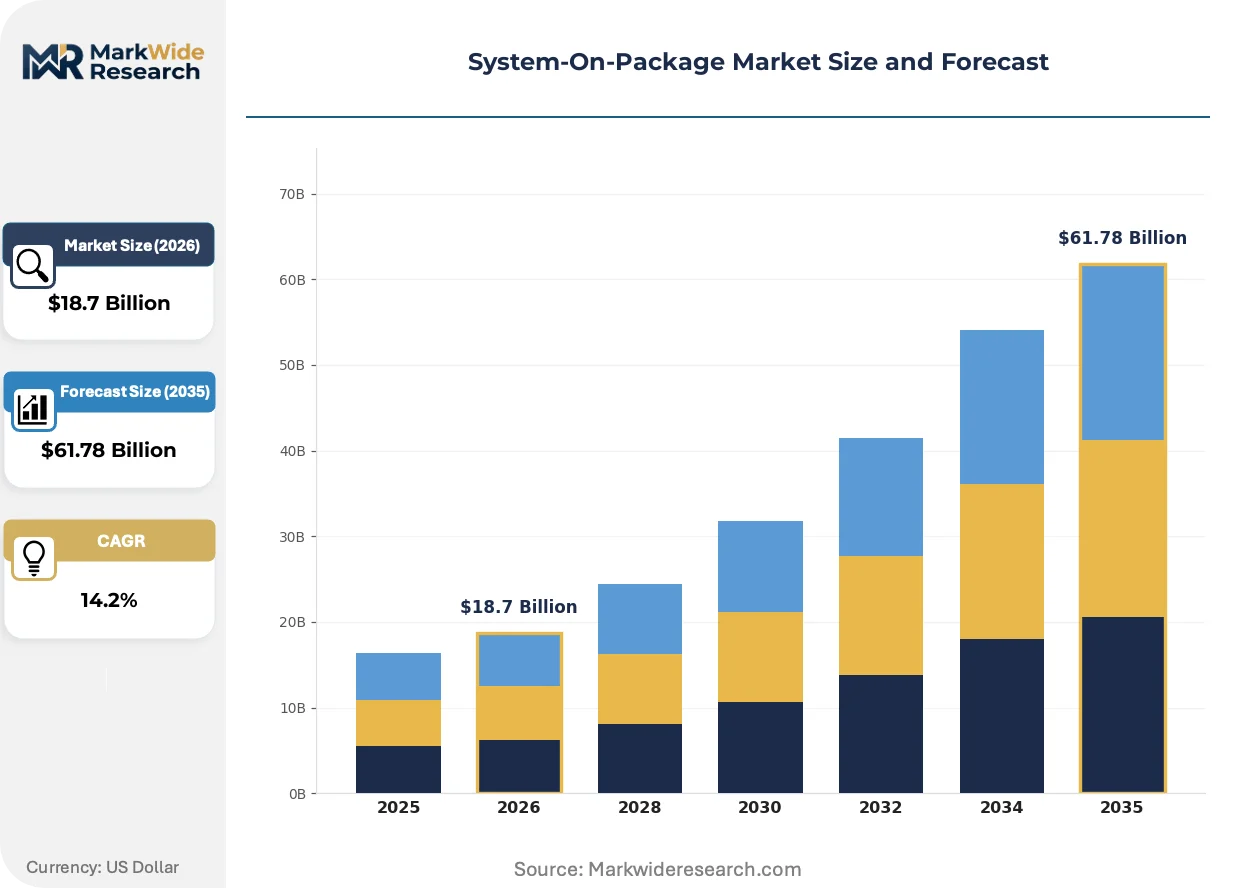
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded System, Digital System, Analog System, Mixed Signal System Technology: 3D Packaging, Flip Chip, Wire Bonding, TSV Technology End User: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications Application: Wearable Devices, Smart Home, IoT Devices, Medical Devices |
| Companies Covered | JCET, UTAC, Amkor Technology, Infineon, Hana Micron, ASE Technology Holding, Siliconware Precision Industries, TSMC, NXP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System-On-Package Market Evolving Landscape
Chiplet disaggregation is redefining value capture boundaries between foundries, memory suppliers, and packaging houses. Standardization gaps between proprietary interfaces create both friction and differentiation space.
Hybrid bonding is consolidating copper-to-copper direct attach as the successor to microbump stacking for sub-10-micron pitch 3D integration. Memory suppliers at 1-alpha and 1-beta nodes deploy hybrid bonding for high-bandwidth memory stacks, compressing the interposer real estate required for AI accelerator packages. This consolidation is collapsing the traditional boundary between front-end wafer processing and back-end assembly, forcing foundries to absorb packaging capabilities or cede margin to dedicated OSATs.
EU AI Act risk classification tiers impose documentation burdens on edge AI System-On-Package deployments in automotive and medical contexts. High-risk system providers must maintain technical files spanning training data provenance, model architecture, and hardware-software interface specifications. Automotive Tier-1 suppliers in Germany and France are pre-emptively segregating AI-enabled advanced driver-assistance System-On-Package designs into EU-conforming and non-EU product lines to isolate compliance scope.
Medical device OEMs now unbundle packaging qualification from semiconductor procurement, inserting dedicated packaging engineering teams between chip vendors and finished device manufacturers. This disintermediation compresses the traditional foundry-OSAT-OEM chain, with Boston Scientific and Medtronic maintaining captive packaging validation labs in Minnesota and California. The shift is most visible in portable diagnostic System-On-Package sourcing, where FDA 510(k) submission timelines now dominate vendor selection criteria over unit cost.
System-On-Package Market Segmentation
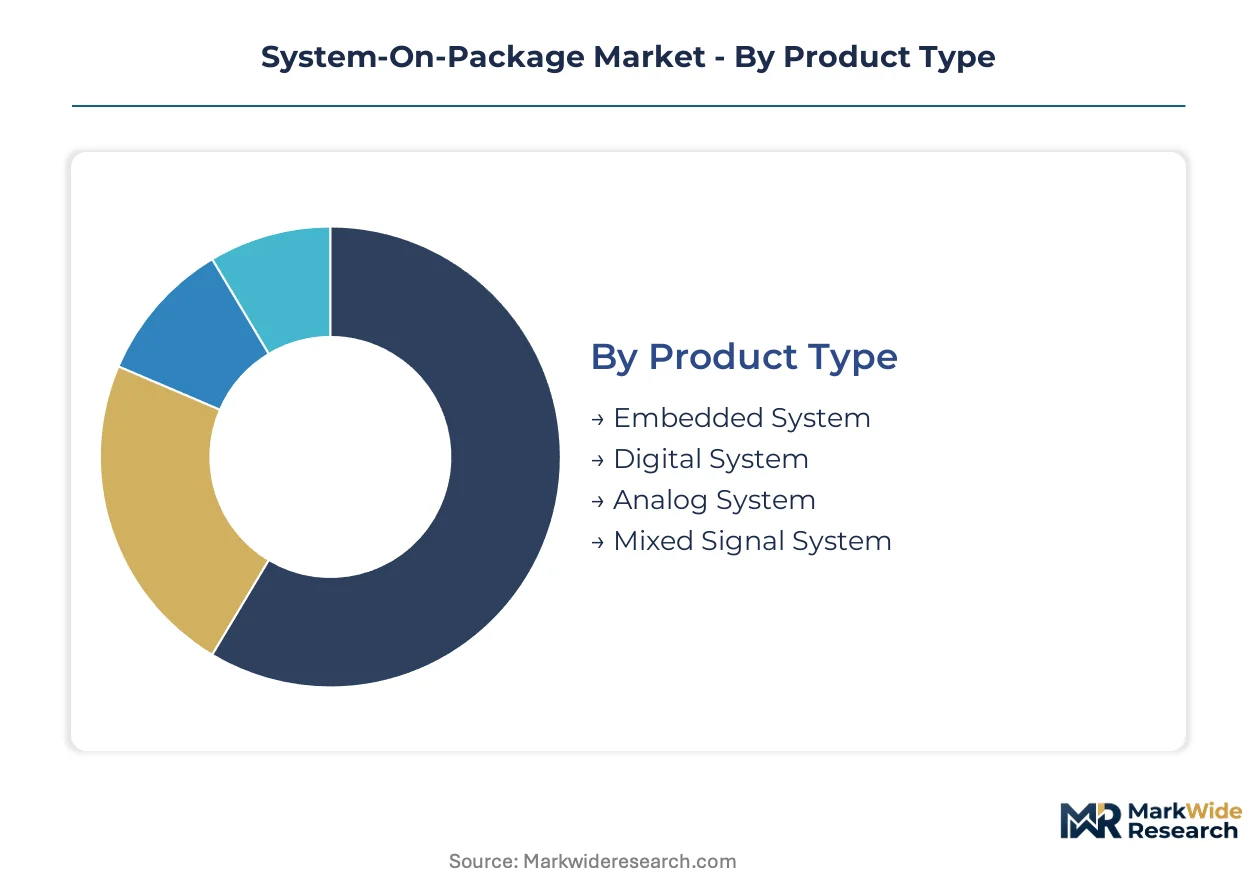
System-On-Package architectures fragment across integration density, interconnect pitch, and thermal envelope specifications. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier competitive positioning.
Product Type:
Integration complexity and analog-digital fusion requirements define the product type axis, with heterogeneous chip assembly driving cost and performance differentiation.
- Embedded System:Microcontroller-plus-memory configurations dominate IoT endpoint and wearable unit shipments. Demand concentrates in Taiwan and South Korea where fan-out panel-level packaging scales reduce unit costs for fitness trackers and smart home sensors.
- Mixed Signal System:Analog-digital fusion architectures integrate RF transceivers with CMOS logic for portable diagnostic equipment. Medical device OEMs in Germany and Minnesota drive qualification cycles, prioritizing FDA 510(k) pathway compatibility over unit economics.
- Digital System:Logic-intensive stacks for AI inference accelerators leverage interposer-based integration. Datacenter deployments in Virginia and Frankfurt pull high-bandwidth memory proximity packaging.
- Analog System:Sensor front-end and power management integration serves automotive battery monitoring modules. Legacy wire-bonded configurations retain cost advantages in Detroit and Stuttgart Tier-1 supply chains.
Mature deployment sits with Embedded System products in consumer volume applications. Newer deployment is concentrated in Mixed Signal System configurations for medical and automotive edge AI.
Technology:
Interconnect pitch and stacking architecture determine thermal performance, form factor, and capital intensity thresholds across packaging houses.
- TSV Technology:Through-silicon vias enable true 3D stacking with sub-100-micron pitch interconnects. AI accelerator demand in Taiwan and South Korea foundries absorbs premium capacity despite thermal management complexity at sub-50-micron scaling.
- Wire Bonding:Gold and copper wire interconnects retain dominance in cost-sensitive consumer electronics and legacy automotive modules. Price volatility in precious metals compresses margins for Detroit-based ECU suppliers locked into 10-15 year vehicle platform lifecycles.
- 3D Packaging:Die-to-die stacking without interposers targets high-bandwidth memory integration. Memory suppliers at advanced nodes deploy hybrid bonding for AI training clusters in Oregon and Hsinchu.
- Flip Chip:Solder bump interconnects with organic substrates balance performance and cost for mobile application processors. ABF substrate allocation risk from Japanese suppliers constrains capacity expansion for Ho Chi Minh City packaging corridors.
Volume concentration remains with Wire Bonding in automotive and consumer legacy lines. Steepest expansion trajectory belongs to TSV Technology as heterogeneous integration roadmaps displace monolithic SoC designs.
End User:
Regulatory intensity and product lifecycle duration segment end user demand into distinct procurement patterns and qualification timelines.
- Automotive Electronics:Electrification mandates across EU, Japan, and California force sensor fusion and power module integration. NHTSA functional safety requirements and EU battery regulations extend validation cycles for advanced driver-assistance packages.
- Consumer Electronics:Smartphone and tablet form factor constraints drive fan-out wafer-level packaging adoption. Seasonal volume spikes strain substrate supply chains serving Vietnam and South Korea assembly facilities.
- Telecommunications:5G baseband and mmWave RF front-end integration demands low-loss substrate materials. FCC spectrum allocation timelines synchronize design cycles for North American infrastructure OEMs.
- Industrial Automation:Extended temperature range and vibration tolerance specifications favor ceramic substrate configurations. German and Japanese factory automation suppliers prioritize 20-year field reliability over cost minimization.
Margin stability characterizes Industrial Automation procurement with long-term supply agreements. Fastest share gains are emerging in Automotive Electronics as electrification mandates tighten across major economies.
Application:
Form factor constraints and power envelope limitations differentiate application requirements for wearable, residential, infrastructure, and clinical deployment contexts.
- Medical Devices:Portable diagnostic equipment demands biocompatible encapsulation and FDA Class IIb documentation compliance. Boston Scientific and Medtronic captive validation labs in Minnesota and California compress traditional foundry-OSAT-OEM chains.
- IoT Devices:Sensor-to-cloud connectivity modules integrate microcontrollers with wireless transceivers in minimal footprint configurations. Smart city deployments in Singapore and Barcelona pull low-power wide-area network package demand.
- Wearable Devices:Skin-contact and sweat-exposure requirements drive hermetic sealing and flexible substrate development. Fitness tracker OEMs in Shenzhen and Cupertino prioritize sub-millimeter thickness over cost optimization.
- Smart Home:Voice assistant and security camera modules balance processing density with thermal dissipation in plastic enclosures. Amazon and Google hardware teams in Seattle and Mountain View specify fan-out packages for voice processing ASICs.
Qualification burden is heaviest in Medical Devices with EU MDR technical documentation and FDA submission timelines. Wearable Devices are gaining deployment velocity as health monitoring functions expand beyond fitness into clinical-grade sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's K-Semiconductor Belt tax credits and Taiwan's Science Park incentives concentrate advanced packaging investment in East Asian manufacturing corridors. Foundry clustering in Hsinchu and Yongin locks substrate access for mid-tier assemblers serving automotive and AI accelerator demand.
Taiwan
CoWoS and SoIC platform demand from AI training clusters absorbs premium TSV capacity at foundry-integrated facilities. NSTC semiconductor research subsidies under Taiwan's Chip Implementation Center redirect academic-industry collaboration toward 3D stacking thermal management. Hsinchu Science Park anchors the densest packaging ecosystem, with ASE Technology Holding and TSMC operating adjacent facilities.
South Korea
High-bandwidth memory stacking for AI accelerators pulls hybrid bonding adoption at 1-alpha and 1-beta DRAM nodes. K-Semiconductor Belt tax credits allow R&D expenditure deductions for fan-out panel-level packaging scale-up. Yongin and Pyeongtaek host Samsung and SK Hynix packaging divisions serving Oregon and Hsinchu fabless customers.
United States
CHIPS Act packaging facility grants target substrate-constrained flip-chip and TSV lines for defense and automotive qualification. NHTSA functional safety requirements extend validation cycles for advanced driver-assistance System-On-Package modules. Arizona and Texas host emerging advanced packaging facilities seeking to reduce Taiwan supply chain exposure.
Japan
METI semiconductor revitalization subsidies redirect capital toward domestic TSV-enabled 3D stacking for medical imaging equipment. Ajinomoto Build-up Film substrate suppliers concentrate capacity among three domestic chemical conglomerates. Kyoto-Osaka industrial corridors host precision equipment manufacturers supplying die bonders and plasma dicing tools.
Vietnam
Amkor and ASE facility investments near Ho Chi Minh City create tariff-advantaged export capacity for North American automotive OEMs. EU-Vietnam Free Trade Agreement rules of origin compliance enables duty-free medical device module shipments to Rotterdam and Hamburg. Northern Bac Ninh and Bac Giang provinces attract wire-bonding line expansion for consumer electronics assembly.
System-On-Package Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across System-On-Package assembly tiers. The vendor base stratifies between foundry-integrated captives controlling advanced-node interposers and independent OSATs competing on geographic diversification and substrate access. Three archetypes dominate: IDM-affiliated packaging divisions, dedicated OSATs with captive substrate partnerships, and foundry-integrated advanced packaging units. Competitive moves center on ABF substrate allocation security and Vietnam corridor capacity expansion.
Among dedicated OSATs, Amkor Technology exemplifies geographic diversification strategy with facility networks spanning Portugal, Vietnam, and South Korea. ASE Technology Holding anchors the captive substrate capacity archetype, leveraging in-house ABF laminate supply to sustain margin control. TSMC occupies the foundry-integrated position, absorbing packaging capabilities that traditionally ceded to OSATs. JCET and UTAC represent scale-driven Chinese and Singapore-based competitors respectively, while Hana Micron exemplifies South Korean memory-supplier-affiliated packaging specialization.
| Leading Market Players |
|---|
| JCET |
| UTAC |
| Amkor Technology |
| Infineon |
| Hana Micron |
| ASE Technology Holding |
| Siliconware Precision Industries |
| TSMC |
| NXP |
| Others |
Value Network & Pricing Analysis
Captive substrate production anchors both supply security and margin control for System-On-Package suppliers navigating ABF laminate allocation constraints. ASE Technology Holding's in-house laminate capacity insulates flip-chip pricing from Japanese chemical conglomerate supply bottlenecks, while mid-tier assemblers absorb spot-market volatility.
Pricing Analysis
Short-lead-time premiums command pricing power for TSV-enabled 3D stacking capacity serving AI accelerator demand in Taiwan and South Korea. Three-tier pricing structure across premium, standard, and economy levels separates hybrid-bonded HBM stacks from wire-bonded automotive modules and fan-out panel-level consumer packages. Cost compression in wire-bonded legacy automotive lines is intensifying because gold and copper wire price volatility squeezes Detroit-based ECU suppliers locked into decade-long platform commitments. Automotive Tier-1 procurement teams exhibit highest price sensitivity, whereas medical device OEMs in Minnesota and Germany prioritize FDA 510(k) pathway compatibility over unit economics.
Supply Chain Analysis
Photoresist and ABF substrate supply rests on Japanese specialty chemical producers concentrated in Kyoto-Osaka industrial corridors. Raw material dependencies span Ajinomoto Build-up Film laminates, high-purity copper wire, and ceramic substrate materials sourced from Japan, South Korea, and Vietnam. Single-source vulnerability concentrates in three domestic Japanese suppliers controlling ABF capacity allocation for flip-chip ball grid array packages. Distribution runs through foundry-integrated captives in Hsinchu and Yongin, independent OSAT corridors in Vietnam and Portugal, and captive medical device validation labs in Minnesota and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The System-On-Package market is a vertical-integration race. Foundry-integrated players absorb packaging capabilities to capture margin pools traditionally ceded to OSATs, while substrate access becomes the decisive upstream lever.
For Market Incumbents: Deploy captive substrate partnerships to lock ABF laminate allocation before Japanese chemical conglomerates ration capacity. Consolidate thermal-mechanical modeling talent through targeted acquisition of finite element analysis specialists in Germany and Japan, defending against foundry-integrated competitors poaching packaging engineering teams. Reinforce Vietnam corridor scale to maintain tariff-advantaged export positioning for North American automotive OEMs. For New Entrants and Emerging Players: Fabless AI accelerator designers in Oregon and Hsinchu represent the most penetrable channel partner type for specialized TSV assembly services. Target photonics-electronics convergence applications where silicon photonics co-packaging demand outstrips incumbent capacity in datacenter optical interconnects. Pursue EU MDR technical documentation expertise as a differentiated qualification service for medical device OEMs seeking to compress 18-24 month validation cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in foundry-integrated acquisition of OSAT specialists with TSV-enabled 3D stacking capabilities. Long-term viability over the projection horizon favors packaging houses with hybrid bonding expertise and medical-grade certification moats. Watch Japan METI subsidy disbursement velocity as an inflection indicator for domestic advanced packaging capacity redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Scale-Up | Enables sub-10-micron pitch 3D integration for HBM stacks at 1-alpha DRAM nodes. |
| Vietnam Packaging Corridor Expansion | Creates tariff-advantaged export capacity under EU-Vietnam Free Trade Agreement rules. |
| Medical Device Validation Lab Captivity | Compresses FDA 510(k) submission timelines for portable diagnostic System-On-Package sourcing. |
| ABF Substrate Backward Integration | Insulates margin control from Japanese chemical conglomerate allocation decisions. |
| Photonics-Electronics Convergence Partnership | Opens bandwidth density for TSV-enabled datacenter optical interconnect deployments. |
Research Methodology
Document review covered SEC 10-K filings, Japan METI subsidy disbursement records, and EU MDR technical documentation guidelines, complemented by interviews with packaging engineering directors at medical device OEMs, thermal-mechanical modeling specialists, and ABF substrate procurement leads. Primary fieldwork engaged foundry-integrated packaging strategists, independent OSAT operations executives, and automotive Tier-1 supplier quality assurance managers. Secondary validation drew from Taiwan NSTC research program disclosures, South Korea K-Semiconductor Belt tax credit utilization data, and Vietnam Ministry of Industry and Trade investment licensing records. Bottom-up capacity buildout tracking triangulated against top-down demand segmentation across AI accelerator, automotive electrification, and medical imaging end-use categories.
Segmented outputs across product type, interconnect technology, end-user vertical, and application context informed the analytical framework throughout the forecast period. Modeled dimensions included TSV pitch scaling trajectories, wire-bonding to flip-chip migration rates, and heterogeneous integration adoption curves in AI training versus inference deployments. CAGRs derived from capacity expansion announcements, equipment import data, and foundry capex allocation patterns. Industry-specific inputs incorporated EU F-Gas Regulation phase-down timelines and FDA device classification rule revisions affecting qualification cycle duration.
Caveats apply where export control framework propagation into packaging tool availability, ABF substrate supply disruption, or EU AI Act risk classification tier enforcement could materially shift the outlook. Forecasts reflect assumptions regarding Taiwan Science Park incentive continuity and South Korea R&D tax credit renewal. A small set of named triggers—Japanese chemical conglomerate capacity allocation decisions, Vietnam infrastructure development velocity, and NHTSA functional safety requirement evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
ESD Stackable Boxes Market