
 Saudi Arabia Cloud Kitchen Market | 2026-2036
Saudi Arabia Cloud Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cloud Kitchen Market Insights
SFDA food safety certification is redrawing competitive boundaries for cloud kitchen operators in Saudi Arabia. Kitopi leverages centralized procurement and multi-brand kitchen infrastructure to sustain economies across its Riyadh facilities. Jahez International anchors last-mile delivery density through proprietary rider networks. Talabat competes via platform-integrated virtual brand incubation and data-driven menu optimization.
A cloud kitchen constitutes a delivery-optimized food production facility without consumer-facing dining space, typically operating square footage between 200 and 800 square meters with modular cooking lines designed for order aggregation from multiple virtual brands. Its commercial purpose centers on minimizing real estate overhead while maximizing throughput for digital-native food service. The Delivery service type dominates transaction volume due to platform dependency and urban consumer habits, while Kitchen Automation technology captures expanding capital allocation as operators seek throughput consistency and labor cost containment. Healthy Options within the Food Category segment represents the fastest-growing margin pool, reflecting dietary shifts among Saudi professionals and families.
SFDA mandates HACCP-aligned kitchen audits and allergen labeling protocols that shape facility design and staff training requirements. The Saudi Communications and Information Technology Commission enforces data localization standards for customer transaction records, affecting platform architecture decisions. SAMR-influenced digital commerce guidelines on promotional transparency further constrain pricing and discounting mechanics. Stakeholders must monitor evolving municipal zoning interpretations for industrial-area kitchen permits, as Riyadh and Jeddah authorities recalibrate land-use classifications to accommodate food-tech facility clustering.
Market Dynamics
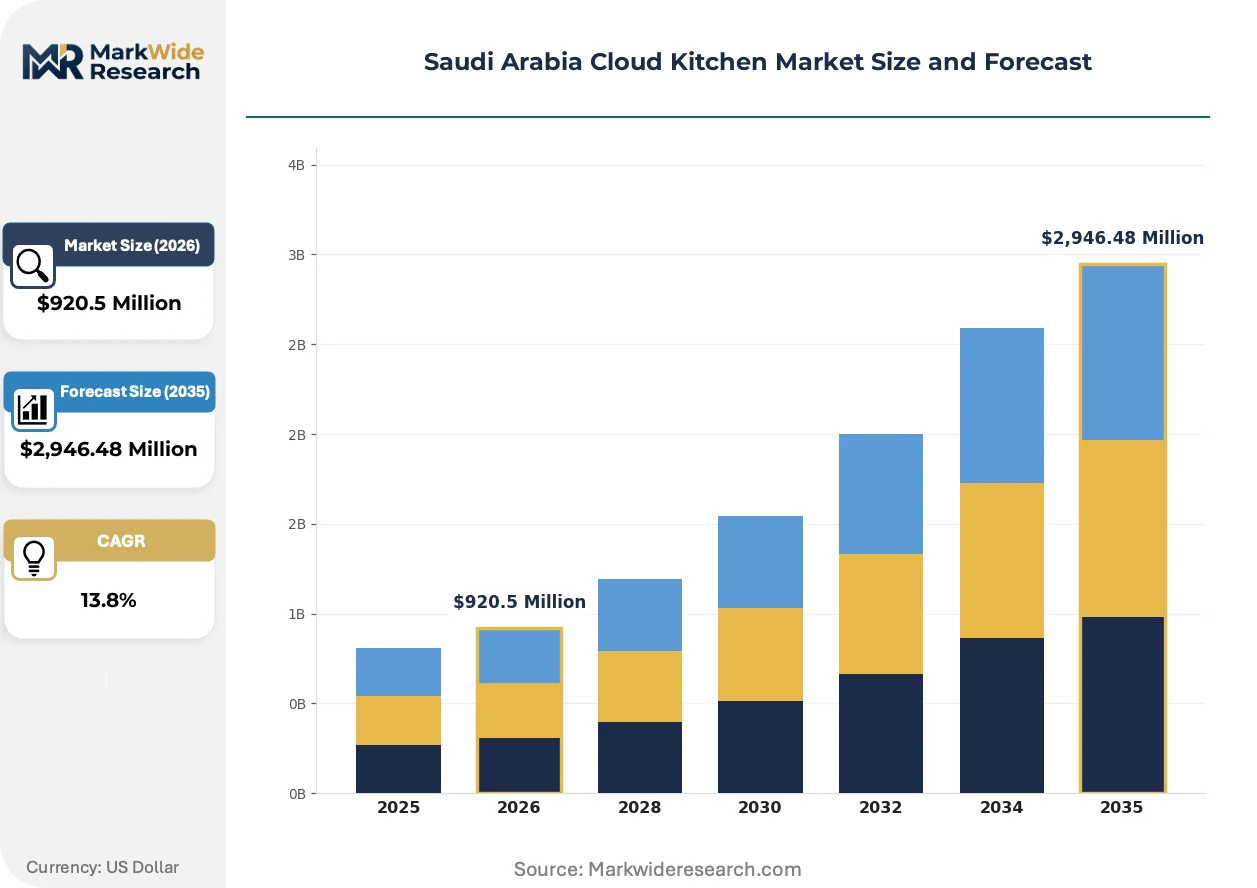
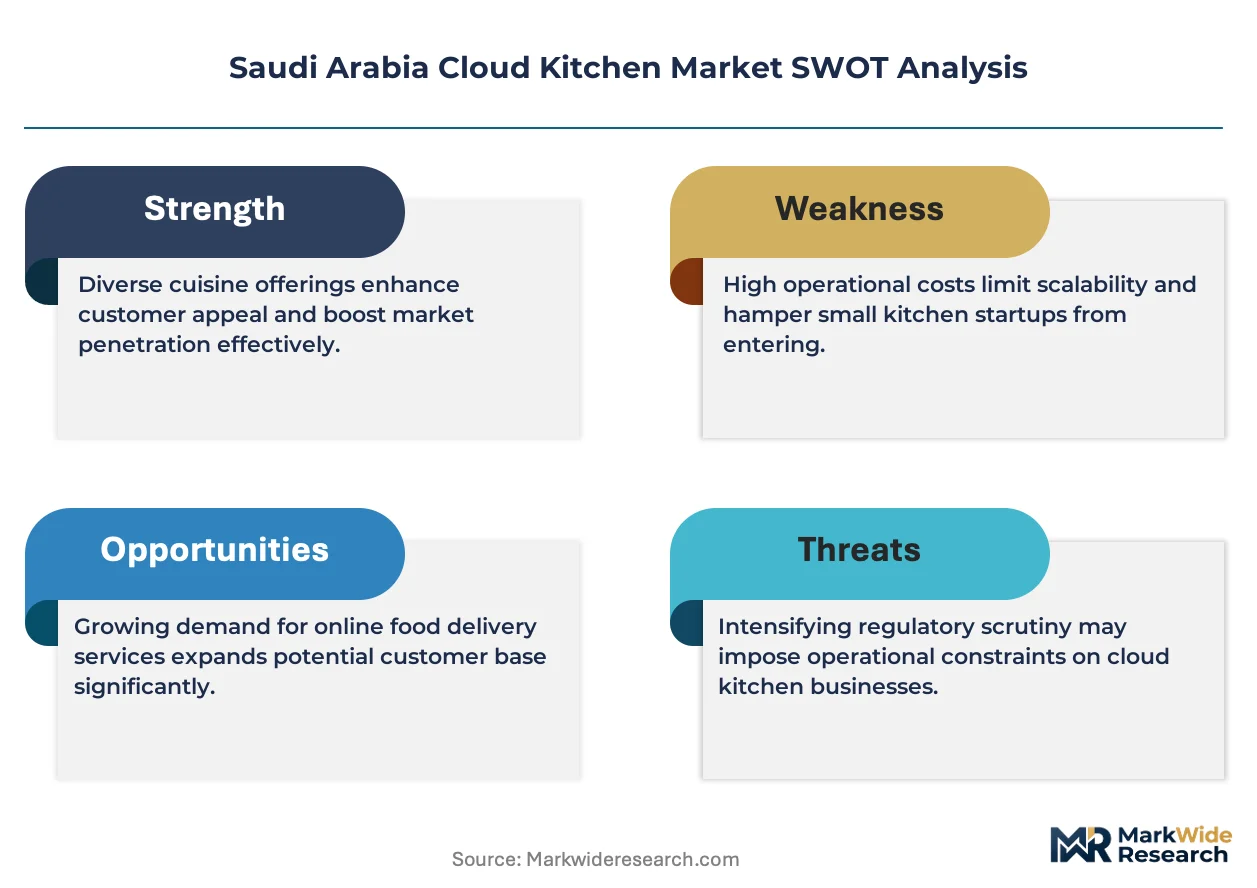
SFDA food safety certification and SAMR-aligned digital commerce standards are compressing operational margins while filtering out undercapitalized operators across Riyadh and Jeddah facilities.
Growth Catalysts
- Platform-integrated delivery infrastructure:Proprietary rider networks and last-mile density investments by delivery platforms are expanding addressable customer bases for virtual brand operators in urban Saudi clusters.
- HACCP-aligned facility mandates:SFDA kitchen audit requirements are accelerating professionalization of food production standards, creating competitive separation for certified operators.
- Smartphone-native consumption patterns:High-frequency digital ordering behaviors among Saudi professionals and families are normalizing delivery-only meal solutions without dine-in alternatives.
Market Restraints
- Industrial real estate scarcity:Municipal zoning recalibrations in Riyadh and Jeddah are constraining permitted locations for food-tech facility clustering, elevating site acquisition costs.
- Data localization compliance burden:Saudi Communications and Information Technology Commission standards for customer transaction records are forcing platform architecture rebuilds and elevating IT infrastructure spend.
- Allergen labeling protocol complexity:SFDA-mandated ingredient disclosure requirements are extending menu development timelines and complicating multi-brand kitchen operations.
Strategic Opportunities
- Eastern Province expansion:Dammam and Khobar present underpenetrated demand pools with comparable urban density and disposable income profiles to established Riyadh-Jeddah corridors.
- Kitchen automation convergence:Integration of robotic cooking lines with order aggregation software is opening throughput scalability for operators seeking labor cost containment.
- Healthy Options segment incubation:Dietary shifts among Saudi professionals are creating white space for specialized virtual brands targeting protein-forward and low-sodium meal solutions.
Industry Challenges
- HACCP certification timeline compression:SFDA audit backlogs and staff training requirements are delaying facility licensing, extending cash runway needs for new entrants.
- Multi-brand operational complexity:Modular cooking line configuration for virtual brand aggregation is demanding specialized kitchen design expertise scarce in the Saudi market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cloud Kitchen Market |
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,946.48 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Delivery, Takeout, Dine-in, Meal Kits Food Category: Fast Food, Healthy Options, Desserts, Beverages Technology: Online Ordering, Mobile Apps, POS Systems, Kitchen Automation Customer Segment: Millennials, Families, Professionals, Students |
| Companies Covered | Rebel Foods, IKCON, Kitopi, Kook, Matbakhi Catering Services Holdings Ltd., Kaykroo, Kitchen Park, Jahez International, Talabat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cloud Kitchen Market Trends and Innovations
Cloud kitchen operators are reconfiguring production architecture around automation density and regulatory compliance, abandoning traditional restaurant capital models for asset-light, technology-heavy facility designs.
Robotic cooking stations equipped with programmable recipe execution and automated portion control are displacing traditional line-cook staffing models in Riyadh facilities. Operators with capital reserves are deploying these systems to achieve throughput consistency during peak order windows. The technology is compressing labor cost structures while elevating capital intensity requirements for competitive positioning.
SFDA's phased implementation of allergen labeling protocols and HACCP audit digitization is mandating real-time kitchen monitoring systems and blockchain-traceable ingredient documentation. Food safety compliance is now a technology procurement decision rather than a procedural checkbox. Virtual brand operators are responding by integrating compliance software into core platform architecture rather than treating it as peripheral.
Saudi families are consolidating meal ordering around platform-native subscription models and predictive reordering algorithms, abandoning spontaneous single-transaction behavior. This pattern is concentrating demand volume with operators capable of data-driven menu optimization and loyalty program integration. The shift is most visible among dual-income households in Riyadh's northern districts and Jeddah's coastal compounds.
Saudi Arabia Cloud Kitchen Market Segmentation
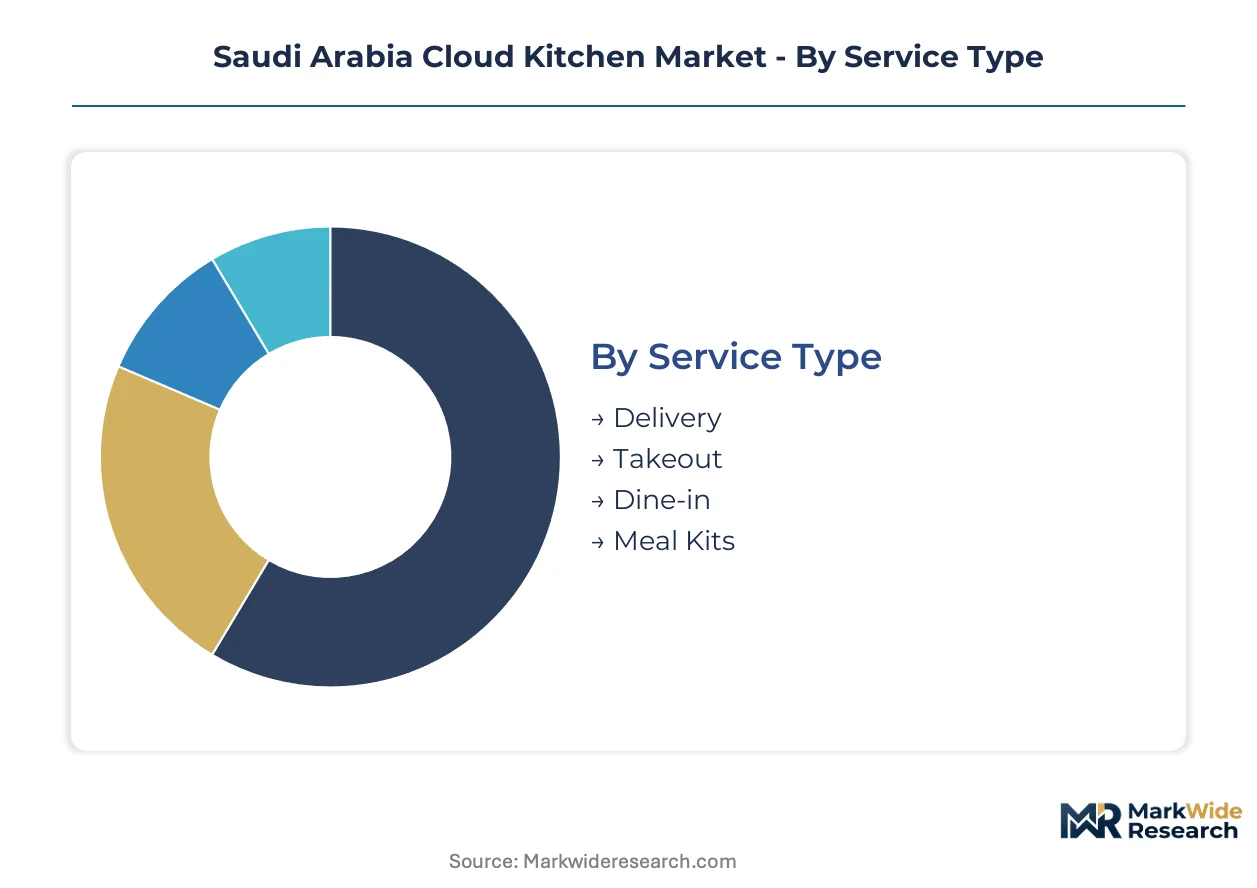
Cloud kitchen economics in Saudi Arabia fragment across four operational dimensions, each governing capital allocation and margin capture differently. Service type determines real estate footprint and labor models. Food category shapes procurement complexity and shelf-life management. Technology tier separates scalable operators from facility-dependent competitors. Customer segment dictates platform partnership strategy and promotional cadence.
Service Type:
Delivery commands platform commission structures and rider network dependencies, while other service types alter kitchen design and customer acquisition economics.
- Delivery:Pure-play digital order fulfillment through aggregator platforms and proprietary apps dominates transaction volume in Riyadh and Jeddah. SFDA packaging requirements and last-mile temperature controls compress margins but lock in habitual urban consumers.
- Takeout:Customer-directed pickup without dine-in infrastructure reduces platform dependency. This segment concentrates in compounds and business districts where parking accessibility and order-ready notifications drive repeat usage.
- Dine-in:Limited seating configurations attached to production facilities serve as brand showcases and catering pickup points rather than revenue centers. Municipal zoning in Riyadh restricts these hybrid formats to designated mixed-use corridors.
- Meal Kits:Pre-portioned ingredient assemblies with recipe instructions target subscription-oriented households in Jeddah's coastal compounds. Cold-chain logistics and portion precision requirements elevate operational complexity.
Delivery dominates installed base. Meal Kits is where expansion concentrates.
Food Category:
Margin profiles diverge sharply across preparation complexity, ingredient cost volatility, and platform algorithm favorability.
- Fast Food:Standardized protein-carb combinations with sub-ten-minute production cycles maximize throughput during peak windows. Riyadh's northern districts generate the highest order frequency for burger and fried chicken virtual brands.
- Healthy Options:Protein-forward bowls, low-sodium preparations, and macro-calculated meals attract dual-income professionals in Jeddah's corporate clusters. Calorie transparency and ingredient provenance requirements extend menu development timelines.
- Desserts:Temperature-sensitive fulfillment with narrow delivery windows demands specialized packaging and rapid handoff protocols. This segment shows seasonal concentration around Ramadan and Eid ordering surges.
- Beverages:Coffee, fresh juices, and functional drinks require equipment-dense production lines with high capital intensity. Spill-proof packaging standards from delivery platforms constrain product formulation.
Fast Food captures volume leadership. Healthy Options is climbing the fastest.
Technology:
Capital deployment into technology tiers separates asset-light entrants from infrastructure-heavy operators seeking defensible positioning.
- Online Ordering:Web-based interfaces with integrated payment gateways remain the entry-level stack for single-brand operators. Customer data retention limitations under Saudi Communications and Information Technology Commission rules elevate compliance spend.
- Mobile Apps:Native iOS and Android applications with push notification capabilities and loyalty program integration concentrate investment among multi-brand aggregators. Development and maintenance costs filter out undercapitalized players.
- POS Systems:Order aggregation hardware connecting kitchen display systems with delivery platform APIs reduces ticket errors and preparation delays. This tier shows widest adoption across mid-scale Riyadh facilities.
- Kitchen Automation:Robotic cooking stations with programmable recipe execution and automated portion control displace line-cook staffing models. Capital intensity requirements restrict deployment to well-funded operators with multi-location footprints.
POS Systems anchors current infrastructure. Kitchen Automation is gaining share fastest.
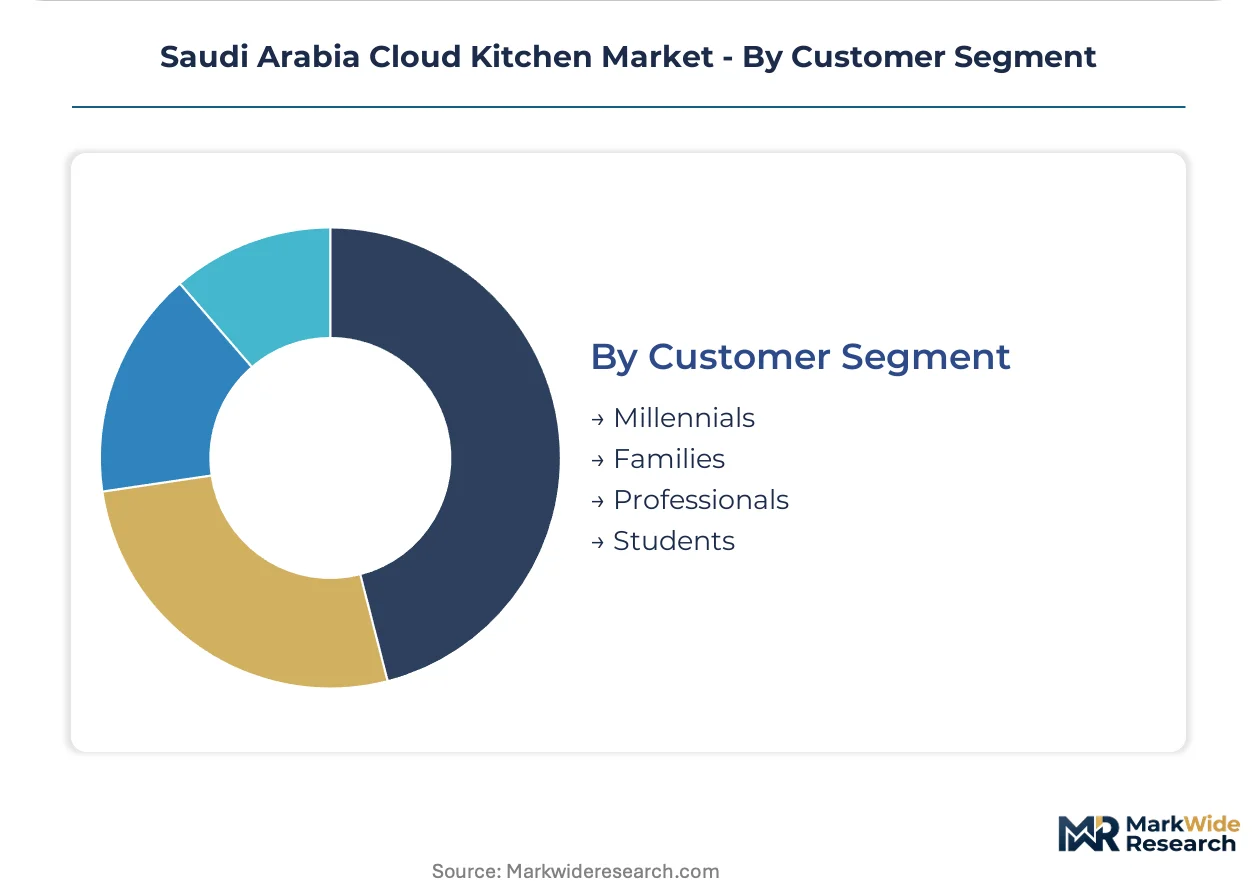
Customer Segment:
Ordering frequency, basket size, and price sensitivity vary substantially across demographic cohorts, shaping virtual brand positioning and promotional mechanics.
- Millennials:Digital-native consumers aged 25-40 with platform subscription memberships and predictive reordering habits. This cohort concentrates in Riyadh's technology and finance employment corridors.
- Families:Multi-person household orders with higher average basket values and dietary accommodation requirements. Jeddah's compound residents show strongest concentration for bundled meal solutions.
- Professionals:Time-constrained office workers prioritizing convenience and nutritional transparency over price minimization. Corporate catering contracts and recurring lunch orders define this segment.
- Students:Price-sensitive consumers with irregular ordering patterns and high promotional responsiveness. University-adjacent kitchen locations in Riyadh and Jeddah target this cohort with value-tier virtual brands.
Millennials dominate platform-native volume. Professionals is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA licensing incentives and municipal zoning reforms are redrawing facility deployment patterns across Saudi Arabia's urban corridors. Cloud kitchen operators concentrate production capacity where regulatory clarity intersects with delivery platform density.
Riyadh
Corporate catering contracts and dual-income household density drive order volume in the capital's northern districts. SFDA HACCP audit digitization mandates accelerate facility professionalization among established operators. The King Abdullah Financial District anchors premium virtual brand incubation targeting time-constrained professionals.
Eastern Province
Industrial workforce clusters and compound residential patterns generate underpenetrated demand pools in Dammam and Khobar. Municipal authorities are recalibrating land-use classifications to accommodate food-tech facility clustering near logistics corridors. Aramco-adjacent employment zones show particular concentration for meal-kit subscription services.
Western Region
Jeddah's coastal compounds and pilgrimage-adjacent hospitality infrastructure support seasonal demand surges and year-round family ordering. SAMR-influenced digital commerce guidelines constrain promotional mechanics for platform-integrated operators. The King Abdulaziz International Airport logistics zone anchors cold-chain dependent virtual brands.
NEOM Northwest
Greenfield urban development and regulatory sandbox provisions attract technology-heavy kitchen automation deployments. The Saudi Communications and Information Technology Commission's data localization standards shape platform architecture decisions for entrants. NEOM's planned food-tech clusters represent experimental ground for robotic cooking line integration.
Saudi Arabia Cloud Kitchen Market Competitive Landscape
Player mix skews toward platform-integrated aggregators and specialized kitchen infrastructure operators. Market structure shows moderate consolidation around delivery platforms with captive cloud kitchen investments and independent multi-brand facility managers. Two strategic archetypes dominate: technology-heavy automation deployers seeking labor cost containment, and asset-light virtual brand incubators leveraging platform data for menu optimization. Competitive moves center on proprietary rider network expansion and municipal permit pre-positioning in high-density districts.
Among Middle East-based infrastructure specialists, Kitopi and Jahez International exemplify contrasting approaches to market development. Kitopi occupies a position as a multi-brand kitchen operator with centralized procurement capabilities across Riyadh facilities. Jahez International anchors last-mile delivery density through proprietary logistics investments. Talabat represents the platform-integrated archetype, leveraging order data for virtual brand incubation. Rebel Foods and IKCON sit within the international expansion tier, bringing cross-market virtual brand portfolios to Saudi facilities.
| Leading Market Players |
|---|
| Rebel Foods |
| IKCON |
| Kitopi |
| Kook |
| Matbakhi Catering Services Holdings Ltd. |
| Kaykroo |
| Kitchen Park |
| Jahez International |
| Talabat |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with multi-brand kitchen operators lock in both cold-chain ingredient access and predictable unit economics across Riyadh and Jeddah facilities. These contracts tie pricing visibility to SFDA certification timelines and municipal permit allocations.
Pricing Analysis
Cost-plus contracts with commodity food indexation anchor procurement pricing for cloud kitchen operators sourcing through centralized aggregators. Price differentiation rests on HACCP certification tier and last-mile delivery radius, with certified operators commanding premium positioning. Cost compression in the meal-kit tier intensifies because cold-chain logistics requirements elevate spoilage risk. Students represent the most price-sensitive buyer archetype, while dual-income professionals in Riyadh's northern districts show least sensitivity.
Supply Chain Analysis
Inbound logistics costs from Red Sea port congestion and container availability constraints on Asia-Saudi trade lanes elevate lead times for kitchen automation equipment. Supply concentrates in China for robotic cooking stations, the UAE for refrigerated transport assets, and India for packaging materials. Raw material dependencies span stainless steel cooking surfaces, IoT sensors, and temperature-controlled packaging. Single-source vulnerability sits with specialized kitchen display system providers. Distribution runs through platform-integrated dark stores and proprietary rider hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a regulatory consolidation phase and entering cyclical expansion as SFDA digitization clears licensing backlogs and permits new facility deployment.
For Market Incumbents: Secure municipal permit pre-positioning in Riyadh's northern districts and Jeddah's coastal corridors before zoning recalibrations tighten site availability. Invest in HACCP-aligned kitchen automation to defend margins against labor cost inflation. Kitopi-style centralized procurement capabilities represent the critical lever for sustaining economies across multi-brand facilities. For New Entrants and Emerging Players: Lead with healthy-options virtual brands targeting protein-forward meal solutions in Dammam and Khobar, where demand density lags supply. The Eastern Province presents the most penetrable geography given comparable disposable income profiles and underdeveloped platform competition. A subscription-first go-to-market angle with predictive reordering algorithms captures habitual household ordering patterns. For Investors and Strategic Acquirers: Multi-brand kitchen infrastructure operators with captive rider networks or platform data integration capabilities offer the strongest acquisition profile. Long-term viability hinges on automation deployment scale and regulatory compliance technology integration. Watch for SFDA audit digitization completion as the inflection signal for facility licensing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Automation Deployment | Robotic cooking lines from Chinese suppliers compress labor costs during Riyadh peak windows. |
| HACCP Certification Investment | SFDA-aligned audit digitization creates competitive separation for compliant operators. |
| Eastern Province Expansion | Dammam and Khobar zoning reforms enable first-mover facility clustering near logistics corridors. |
| Platform Data Integration | Proprietary order analytics from Talabat and Jahez optimize virtual brand menu development. |
| Healthy Options Brand Incubation | Protein-forward meal solutions capture dietary shifts among Saudi corporate professionals. |
Research Methodology
A spread of perspectives from cloud kitchen operators, delivery platform executives, SFDA compliance officers, and municipal planning authorities converged on the working assumptions. Primary interviews with facility managers and virtual brand operators combined with secondary validation from Saudi Customs trade data, SFDA regulatory filings, delivery platform commission disclosures, and real estate zoning records. Bottom-up facility capacity estimates and top-down platform transaction analysis provided triangulation.
Segmentation dimensions modeled span service type, food category, technology tier, and customer segment across the projection horizon. CAGRs were derived from facility deployment trajectories, platform rider network expansion, and smartphone order frequency trends. Analytical inputs incorporated SFDA licensing velocity, municipal permit approval timelines, and kitchen automation capital deployment patterns.
The analysis sits within stated boundaries; outcomes outside sustained SFDA digitization progress, stable Red Sea logistics corridors, or continued platform commission structures would require recalibration. Forecasts reflect assumptions around regulatory enforcement consistency and urban delivery density maintenance. Recalibration cycles align with material shifts in SFDA audit protocols, municipal zoning interpretations, or platform market consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Delivery Takeaway Food Market
Food Service
Qatar Food Service Market
Food Service
Kamado Grill Market
Food Service
Indonesia Foodservice Market
Food Service
Europe Online Grocery Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Self-Heating Hot Pot Market
Food Service
Chinese Takeout Market
Food Service
Flat Top Grills Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Philippines Foodservice Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
South Africa Fast Food Market
Food Service
A La Carte Market