
 Self-Heating Hot Pot Market | 2026-2036
Self-Heating Hot Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Heating Hot Pot Market Insights
Young professionals living alone is rotating toward the dominant buyer archetype as family-size traditional hot pot occasions fragment into individual consumption moments. Haidilao International Holding Ltd. leverages its restaurant brand equity to anchor premium self-heating product lines. Zihaiguo specializes in authentic Sichuan flavor profiles that dominate regional taste preferences. Baijia Food competes through aggressive channel control across China's lower-tier urban wholesale networks.
A self-heating hot pot is a portable meal system combining pre-packaged ingredients with an exothermic chemical heating pouch, typically using calcium oxide and water to generate sustained temperatures for food preparation without external power sources. The primary commercial purpose centers on delivering hot, freshly-cooked meal experiences in settings lacking kitchen infrastructure or time for conventional preparation. Stainless steel vessels lead material selection for durability and heat retention, while aluminum formats capture cost-sensitive segments through lighter weight and faster production cycles. Online retail channels now pull the fastest volume growth, though supermarkets still occupy the largest margin pool through impulse placement and bundled promotions.
China's SAMR enforces GB standards for food contact materials and exothermic reaction safety, directly shaping product design requirements and factory certification barriers for new entrants. Japan's PMDA and METI frameworks govern imported self-heating food devices, creating compliance complexity for brands seeking cross-border expansion. South Korea's MFDS maintains parallel safety protocols for chemical heating elements in consumer packaged goods. Stakeholders must monitor how divergent national standards for exothermic packaging will fragment or harmonize as export ambitions intensify beyond domestic strongholds.
Market Dynamics
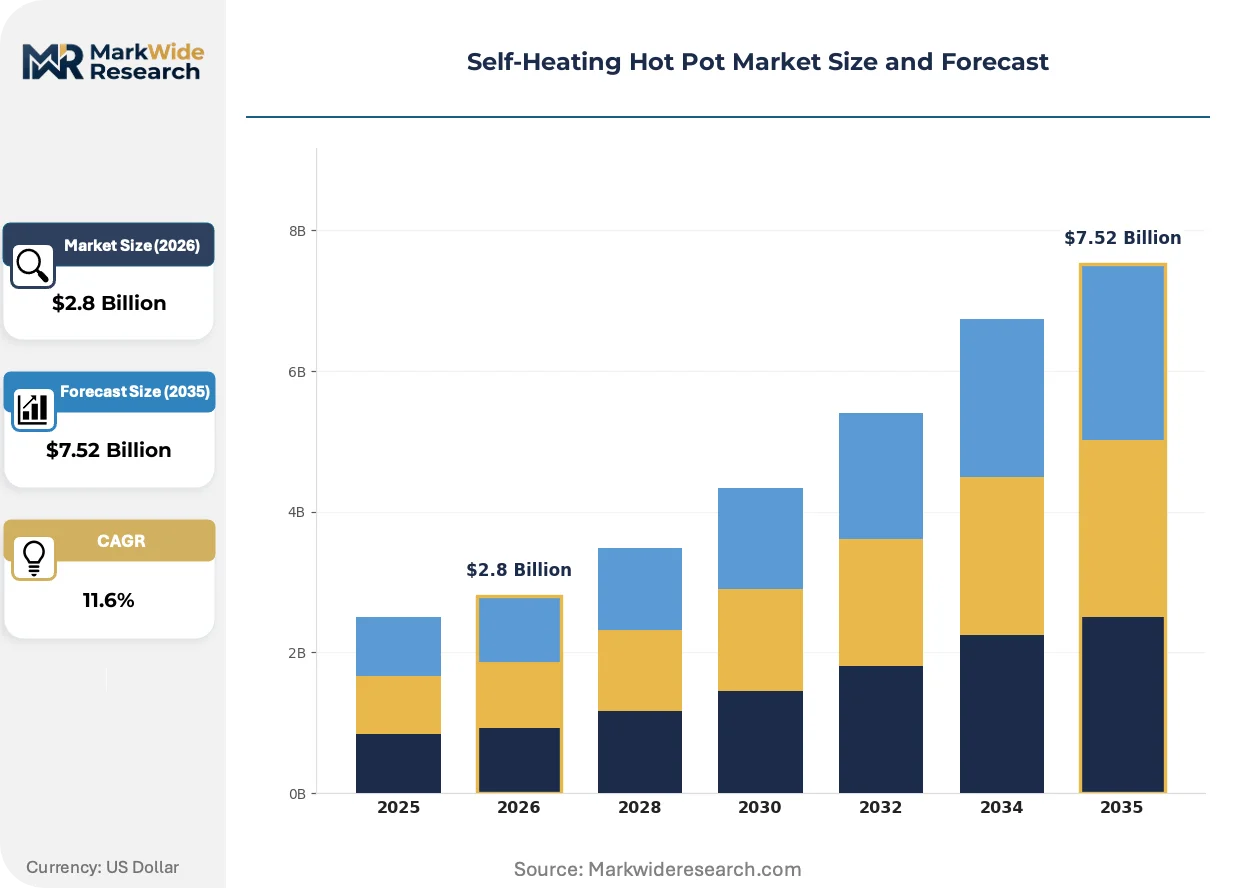
Urban apartment-dwelling lifestyles across China's tier-one cities are compressing kitchen infrastructure requirements, redirecting meal occasions toward portable, self-contained heating systems that bypass traditional cooking apparatus entirely.
Growth Catalysts
- Single-person household formation:Solo professionals in Shanghai, Beijing, and Shenzhen generate recurring demand for individual-portion formats that replicate restaurant hot pot experiences without social coordination.
- GB 4806 food contact material standards:SAMR's evolving safety protocols for exothermic reaction packaging legitimize product categories previously constrained by consumer safety skepticism.
- Calcium oxide pouch chemistry:Refinements in controlled exothermic reaction rates extend safe heating duration, enabling protein-heavy ingredient sets that require sustained thermal profiles.
Market Restraints
- Aluminum input cost volatility:Lightweight vessel formats remain exposed to London Metal Exchange price swings that compress margin structures for cost-positioned product lines.
- Regional taste concentration:Sichuan and Chongqing flavor dominance limits geographic portability of standardized SKUs, forcing costly regional formulation adaptation.
- Substitution by delivery aggregators:Meituan and Ele.me same-day hot pot delivery erodes the core convenience proposition for occasional-use occasions.
Strategic Opportunities
- Japan PMDA import pathway:METI framework navigation for exothermic food devices opens premium positioning in convenience-store channels underserved by domestic competitors.
- Outdoor recreation vertical:Camping and hiking applications in Zhejiang and Sichuan province trail systems extend usage occasions beyond urban apartment contexts.
- South Korea MFDS alignment:Harmonized chemical heating element standards with Chinese GB protocols reduce dual-certification burden for cross-border product launches.
Industry Challenges
- Exothermic reaction safety certification timelines:SAMR testing protocols for new pouch geometries extend product development cycles by 8-14 months.
- Food technologist scarcity:Formulation expertise spanning both shelf-stable ingredient science and thermal reaction engineering concentrates in Chengdu and Guangzhou.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Heating Hot Pot Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Charcoal, Induction, Ceramic Material: Stainless Steel, Cast Iron, Aluminum, Porcelain End User: Household, Restaurants, Food Trucks, Campsites Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Haidilao International Holding Ltd., Zihaiguo, Baijia Food, Sichuan Baibaibei Food Co., Ltd., Master Kong Holdings Limited, Uni-President Enterprises Corp., Nissin Foods Holdings Co., Ltd., Samyang Corporation, Ottogi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Heating Hot Pot Market Trends and Innovations
Product architecture is splitting between premium stainless steel formats emphasizing heat retention and disposable aluminum vessels optimized for cost and regulatory compliance, with each path demanding distinct manufacturing competencies.
Controlled-release calcium oxide formulations are bifurcating the competitive landscape between laboratory-grade chemical suppliers and commodity chemical processors. Tier-one brands with captive pouch production secure consistent thermal performance curves, while outsourced manufacturers face batch variability that triggers consumer complaints. This capability gap is compressing mid-tier brand viability and concentrating share among vertically integrated producers.
China's SAMR is tightening GB 4806.9-2023 migration limits for heavy metals in food contact materials, directly constraining vessel coating chemistry and supplier qualification requirements. Factory audit protocols now mandate third-party testing for every production lot, elevating compliance costs disproportionately for sub-scale manufacturers. Premium product lines absorb these costs through pricing power; economy-tier competitors face margin compression or exit.
Urban convenience stores in Chengdu and Hangzhou are displacing traditional wholesale distribution as the primary volume channel for impulse purchases. 7-Eleven and FamilyMart localized assortments now command dedicated refrigerated sections and promotional calendar slots previously reserved for beverage categories. This channel rotation demands SKU rationalization and packaging formats optimized for vertical shelf placement rather than palletized logistics.
Self-Heating Hot Pot Market Segmentation
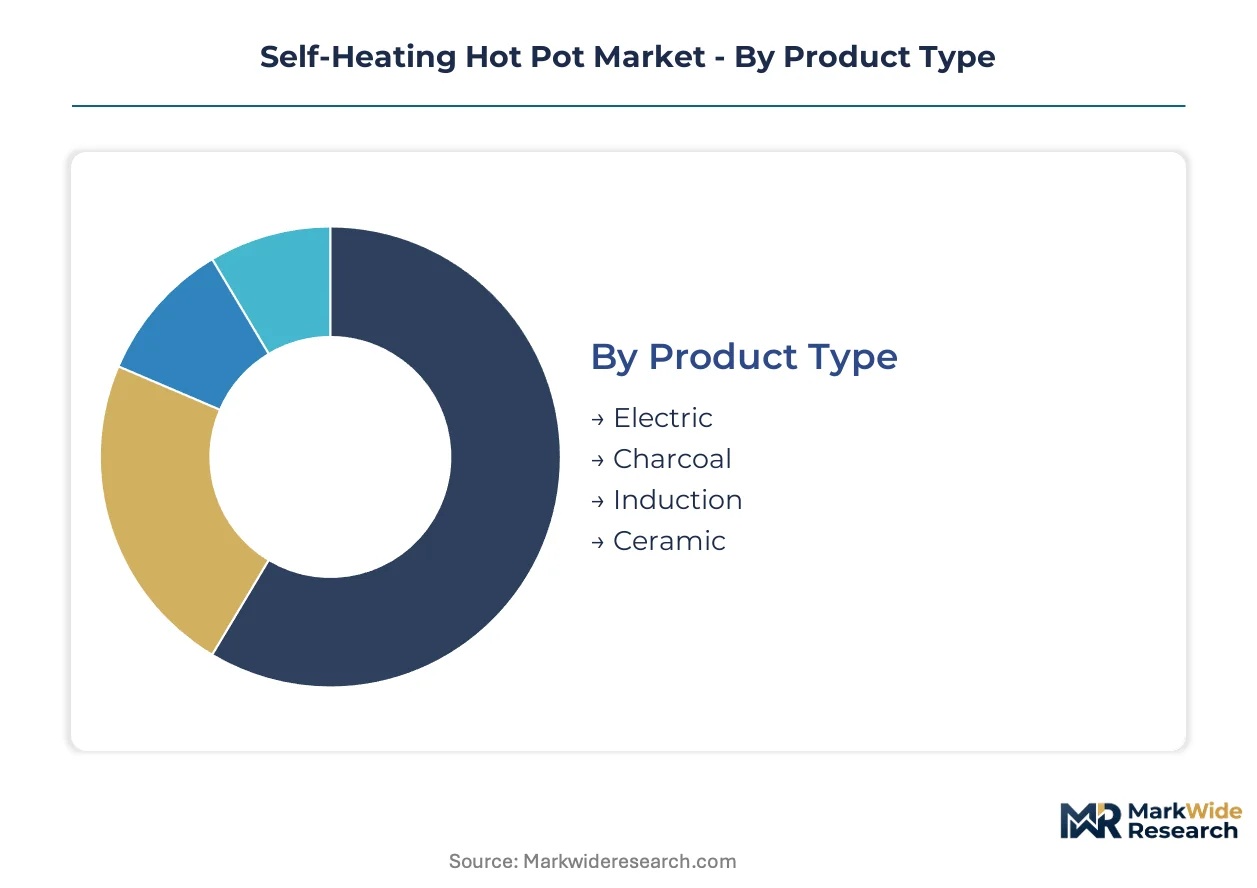
Segmentation in self-heating hot pot markets reveals how substitution pressures from delivery platforms and outdoor recreation equipment reshape demand concentration across product architectures. Understanding these fault lines exposes where chemical heating pouch technology retains defensible positioning versus where electrified alternatives erode market share.
Product Type:
Substitution pressure from battery-powered portable cooking devices and conventional electric appliances fragments demand across heating modality segments, with chemical exothermic formats facing the steepest competitive threat from rechargeable alternatives in urban household contexts.
- Electric:Battery-powered or USB-rechargeable heating bases deliver precise temperature control through resistive elements, capturing demand from tech-forward consumers in Shanghai and Shenzhen who prioritize adjustable thermal profiles over single-use chemical reactions. Meituan same-day appliance delivery compresses adoption cycles for this segment.
- Charcoal:Traditional carbon-based combustion systems generate intense sustained heat for authentic flavor profiles, dominating outdoor recreation applications in Zhejiang province trail systems where open-flame regulations permit usage. Campsite operators in Moganshan and Anji source this format for guest experience differentiation.
- Induction:Electromagnetic field heating enables rapid temperature modulation through compatible metal vessels, appealing to restaurant operators seeking portable buffet solutions without open-flame liability.
- Ceramic:Retained-heat ceramic vessels with pre-heated cores offer passive thermal maintenance, occupying niche positioning in specialty tea-house adjacent dining concepts in Chengdu.
Electric formats anchor the volume base while charcoal configurations gain share at the steepest rate in outdoor verticals.
Material:
Cost tier stratification across vessel materials determines margin architecture, with premium heat-retention alloys commanding pricing power against commodity lightweight alternatives exposed to input volatility.
- Stainless Steel:Austenitic 304-grade alloys deliver superior thermal mass and corrosion resistance, supporting sustained calcium oxide reaction temperatures required for protein-heavy Sichuan ingredient sets. Haidilao premium product lines specify this material for brand-equity reinforcement in tier-one urban convenience channels.
- Aluminum:Drawn 3003-series aluminum sheet enables single-use disposable formats at mass-market price points, though London Metal Exchange price swings compress margins for economy-tier competitors. GB 4806.9-2023 heavy metal migration limits constrain coating chemistry options.
- Cast Iron:Enameled cast iron vessels provide exceptional heat retention for extended dining occasions, capturing premium positioning in gift-oriented retail channels.
- Porcelain:Glazed ceramic construction offers aesthetic differentiation and neutral flavor profiles, serving specialty regional cuisine adaptations in Hangzhou and Suzhou.
Aluminum dominates unit volume through disposable format penetration while stainless steel captures value share expansion in premium convenience store placements.
End User:
Customer-type concentration determines packaging format requirements, with solitary consumption occasions driving single-serve pouch miniaturization against institutional bulk formats.
- Household:Solo professionals in Beijing and Guangzhou apartment complexes generate recurring demand for individual-portion SKUs with sub-15-minute heating cycles, displacing traditional family-size hot pot gatherings. 7-Eleven refrigerated sections dedicate vertical shelf space to these configurations.
- Restaurants:Full-service operators deploy self-heating formats for outdoor catering and emergency backup kitchen capacity, requiring NSF-certified vessel materials and batch-traceable heating pouch documentation.
- Food Trucks:Mobile operators leverage chemical heating to bypass generator dependency for auxiliary menu items, particularly in Shenzhen's regulated street-vendor zones.
- Campsites:Provincial park operators in Sichuan and Yunnan source institutional-format products for guest rental programs, extending usage beyond urban convenience contexts.
Household consumption anchors the volume base while campsite applications climb the fastest as outdoor recreation infrastructure expands.
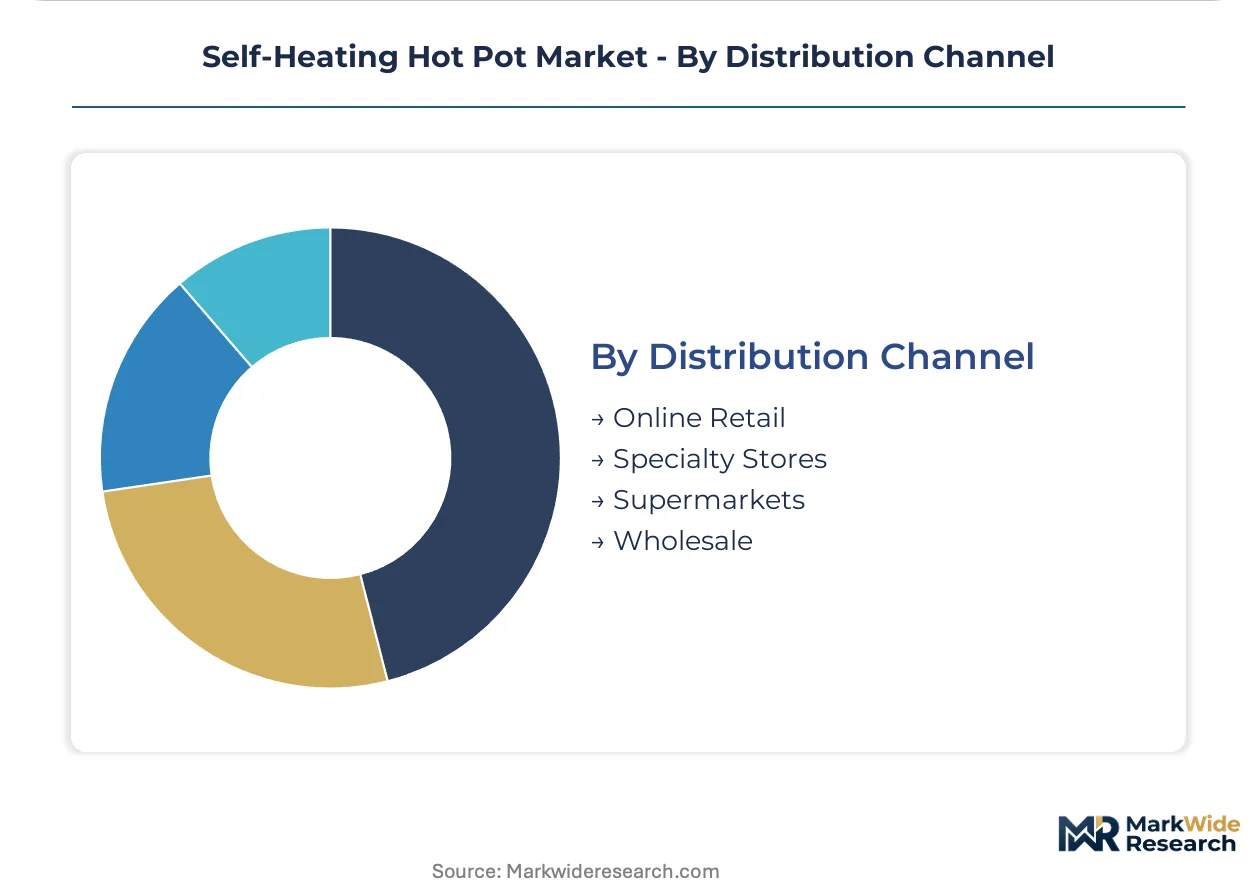
Distribution Channel:
Channel migration from palletized wholesale toward impulse-oriented retail reshapes packaging specifications, with vertical shelf placement requirements displacing traditional logistics-optimized formats.
- Online Retail:Tmall and JD.com flagship stores pull the steepest volume growth for subscription-oriented bulk purchases, though last-mile delivery constraints limit calcium oxide pouch shipment volumes per order. Live-stream commerce in Chengdu drives trial conversion for novel flavor launches.
- Supermarkets:Hema Fresh and Yonghui Superstores command the largest margin pool through bundled promotional calendars and refrigerated end-cap placement, capturing impulse substitution from fresh ingredient hot pot sections.
- Specialty Stores:Outdoor recreation retailers in Hangzhou and Chengdu curate camping-format assortments with seasonal promotional alignment to holiday travel periods.
- Wholesale:Traditional lower-tier urban distribution networks retain volume concentration for economy-tier aluminum formats, though channel share erodes toward convenience retail.
Supermarkets anchor the volume base while online retail gains share at the steepest rate through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solo urban professionals in Shanghai, Beijing, and Shenzhen concentrate demand for single-serve self-heating hot pot formats. Apartment-dwelling lifestyles across China's tier-one cities compress kitchen infrastructure requirements. Convenience culture intersects most intensely in these metropolitan clusters.
China
Shanghai and Beijing solo professionals generate recurring demand for individual-portion formats with sub-15-minute heating cycles. SAMR enforces GB 4806 food contact material standards and evolving safety protocols for exothermic reaction packaging. Chengdu and Chongqing industrial clusters concentrate formulation expertise spanning shelf-stable ingredient science and thermal reaction engineering.
Japan
Convenience-store channel penetration in Tokyo and Osaka drives premium positioning for imported exothermic food devices. METI and PMDA frameworks govern chemical heating element safety certification for consumer packaged goods. Nagoya-based packaging specialists navigate dual compliance requirements for cross-border product launches.
South Korea
Seoul Capital Area young professionals adopt portable meal systems for office and apartment consumption occasions. MFDS maintains parallel safety protocols for chemical heating elements that align with Chinese GB standards. Busan-Ulsan manufacturing corridors supply pouch components to regional brand networks.
United States
Outdoor recreation enthusiasts in California and Colorado trail systems extend usage contexts beyond urban convenience scenarios. FDA food contact substance notifications apply to imported vessel materials and heating pouch chemistry. Pacific Northwest camping retailers curate seasonal assortments for holiday travel periods.
Vietnam
Ho Chi Minh City and Hanoi young professionals replicate Chinese convenience consumption patterns in emerging urban middle-class segments. National food safety authorities develop parallel protocols for exothermic packaging categories. Mekong Delta manufacturing zones supply aluminum vessel components to regional assembly networks.
Self-Heating Hot Pot Market Competitive Landscape
Player mix skews toward restaurant-brand derivatives and specialty flavor houses rather than diversified food conglomerates. Tiered structure separates premium stainless steel formats from economy-tier aluminum disposables. Strategic archetypes include restaurant-brand licensors, regional flavor specialists, and contract manufacturers with captive pouch production. Capacity expansion and channel control dominate competitive moves as brands defend shelf placement in convenience retail rotations.
Within the restaurant-brand licensor tier, Haidilao International Holding Ltd. anchors premium positioning through established dining equity. Zihaiguo exemplifies the regional flavor specialist archetype with Sichuan province concentration. Baijia Food occupies the channel-control position across lower-tier urban wholesale networks. These three entities represent distinct strategic vectors rather than direct substitutability.
| Leading Market Players |
|---|
| Haidilao International Holding Ltd. |
| Zihaiguo |
| Baijia Food |
| Sichuan Baibaibei Food Co., Ltd. |
| Master Kong Holdings Limited |
| Uni-President Enterprises Corp. |
| Nissin Foods Holdings Co., Ltd. |
| Samyang Corporation |
| Ottogi Corporation |
| Others |
Pricing and Supply Chain Analysis
Calcium oxide pouch chemistry displacing traditional induction heating in urban apartment contexts simultaneously concentrates supply geography around Sichuan and Guangzhou chemical clusters while compressing margin structures for brands lacking captive pouch production. This substitution dynamic forces pricing power toward vertically integrated manufacturers and exposes outsourced competitors to batch variability penalties.
Pricing Analysis
London Metal Exchange-indexed aluminum contracts dominate vessel procurement, with pricing stratifying across premium stainless steel, standard hybrid formats, and economy-tier disposable aluminum tiers. Price differentiation rests on GB 4806.9-2023 certification tier and brand equity anchored by restaurant-licensed marks. Cost compression in aluminum-dependent economy lines is intensifying because of base metal volatility. Household solo professionals in tier-one cities show lowest price sensitivity, while lower-tier wholesale buyers exhibit acute elasticity.
Supply Chain Analysis
Inventory cycles for calcium oxide pouches extend 8-14 months due to SAMR safety certification queues, constraining working capital for new entrants. Manufacturing concentrates in China, South Korea, and Japan, with raw material dependencies spanning metallurgical-grade calcium oxide, food-contact aluminum sheet, and laminated barrier films. Single-source vulnerability runs through Sichuan-based chemical suppliers for controlled-release formulations. Distribution runs through convenience store refrigerated sections displacing traditional palletized wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
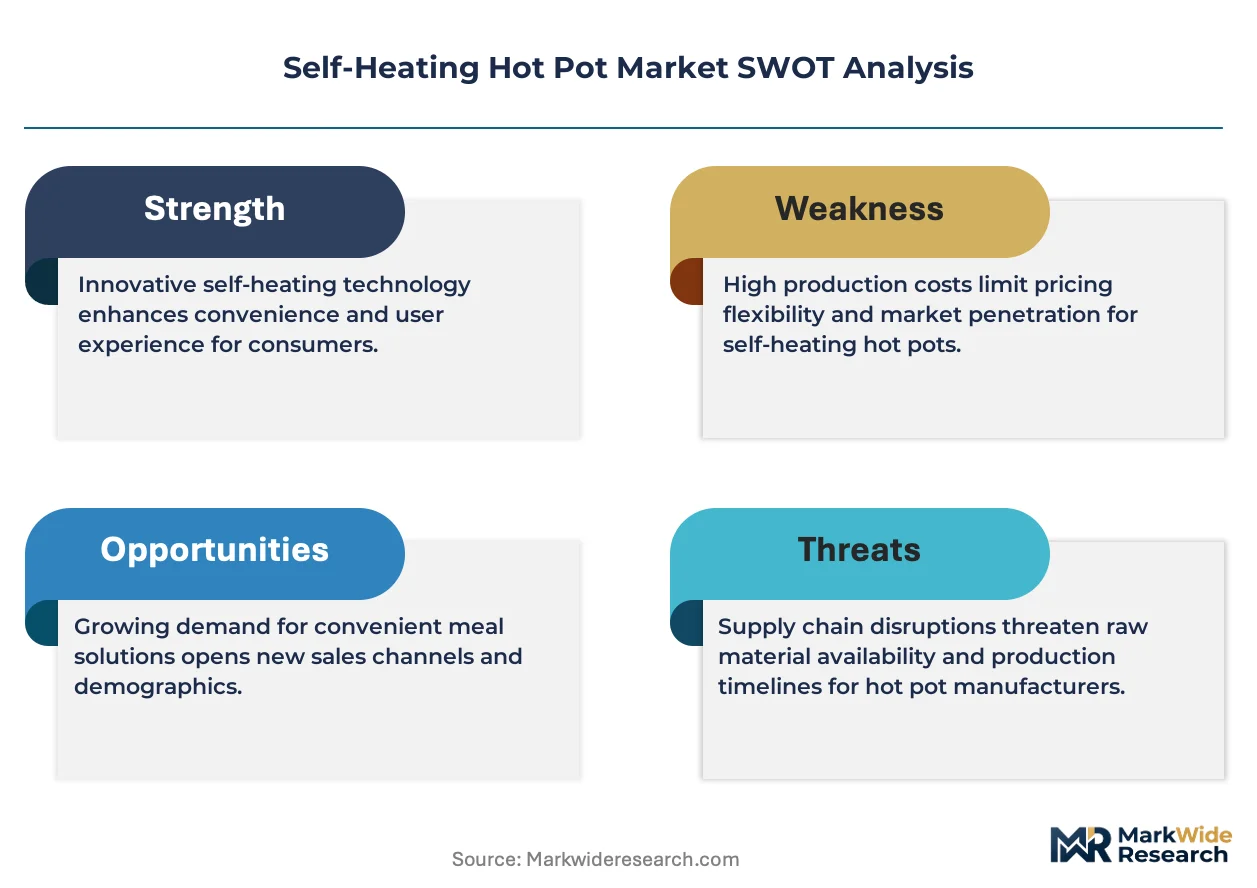
This market functions as a regulatory-moat arena where SAMR exothermic certification timelines create switching costs that entrench incumbents with established testing relationships and documented safety dossiers.
For Market Incumbents: Compound brand equity through restaurant-licensed product extensions that leverage existing GB 4806.9-2023 certification infrastructure. Prioritize captive pouch production capacity in Chengdu chemical corridors to neutralize batch variability complaints eroding mid-tier competitors. Defend against electric portable cooking substitution by emphasizing sub-15-minute heating speed in convenience retail placements.
For New Entrants and Emerging Players: White-space in Japan PMDA import pathways offers premium positioning where METI framework complexity deters Chinese mass-market brands. Target outdoor recreation verticals in Zhejiang and Sichuan provincial parks where charcoal format incumbents under-serve chemical heating demand. Deploy direct-to-campsite distribution partnerships bypassing convenience store slotting fee barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with in-house calcium oxide formulation and SAMR pre-certified vessel geometries. Long-term viability hinges on regulatory entrenchment deepening across tightening GB standards iterations. Monitor cross-border harmonization between Chinese SAMR and South Korea MFDS protocols as inflection signal for regional consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pouch Production Buildout | In-house calcium oxide formulation secures consistent thermal curves against outsourced batch variability. |
| Japan PMDA Import Pathway Navigation | METI compliance expertise opens premium convenience-store channels underserved by domestic competitors. |
| Outdoor Recreation Vertical Expansion | Campsite rental programs in Sichuan and Yunnan extend usage beyond urban apartment contexts. |
| GB 4806.9-2023 Pre-Certification Investment | Third-party testing documentation accelerates SAMR approval timelines for new product geometries. |
| Cross-Border MFDS Alignment | Harmonized South Korean chemical heating standards reduce dual-certification burden for regional launches. |
Research Methodology
Operator-level perspectives from product development directors at self-heating food manufacturers, SAMR compliance officers, convenience store category buyers, and calcium oxide chemical suppliers anchored the qualitative base. Primary fieldwork combined with secondary validation against customs trade records, GB standards documentation, SAMR certification registries, and convenience retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Sensitivity analysis tested demand elasticity to aluminum price shocks and regulatory approval timeline extensions across the projection horizon. Segmentation dimensions spanned heating modality, vessel material tier, end-user consumption occasion, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to channel-specific adoption rates, with inputs including single-person household formation trajectories and outdoor recreation infrastructure investment pipelines.
Underlying assumptions cover sustained urban apartment-dwelling lifestyle compression and stable GB 4806 enforcement intensity, with deviation risk concentrated in delivery platform substitution acceleration and cross-border regulatory harmonization failures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
US Food Service Market
Food Service
Chile Food Delivery Market
Food Service
Contract Catering Market
Food Service
Japan Foodservice Market
Food Service
Halal Food and Beverages Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Restaurant Griddle Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Brazil Foodservice Market
Food Service
Global Waffle Maker Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Gourmet Street Food Market
Food Service
Australia Foodservice Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Food Service Dairy Products Market