
 India Quick Service Restaurant Market | 2026-2036
India Quick Service Restaurant Market Size, Share, and Industry Trends Forecast 2026-2036
India Quick Service Restaurant Market Insights
Cloud kitchen expansion across Mumbai and Bengaluru is realigning how QSR chains deploy capital without prime real estate. Hardcastle Restaurants dominates the burger segment through McDonald's franchise operations across western and southern India. Jubilant FoodWorks anchors pizza delivery through Domino's extensive last-mile network. Devyani International leverages its Yum! Brands portfolio to compete in fried chicken and pizza across tier-2 cities.
India Quick Service Restaurants are commercial foodservice outlets characterized by standardized menus, limited preparation time under ten minutes, and price points typically between INR 150 and INR 500 per transaction, designed for high-volume, low-margin turnover. Their primary purpose is delivering consistent, affordable meals to time-constrained consumers through repeatable operational workflows. Burgers and pizzas occupy the largest share of product type revenue, driven by global brand recognition and localized flavor adaptations. Delivery and takeaway service types are expanding fastest, propelled by aggregator platform integration and dedicated dark kitchen infrastructure. The master franchise model concentrates margin pools with area developers who control multi-city expansion rights.
FSSAI mandates on ingredient traceability and hygiene ratings directly shape store licensing and consumer trust. BIS packaging standards and state-level municipal corporation food licenses create layered compliance requirements for national operators. RBI digital payment guidelines and NPCI UPI infrastructure enable cashless transaction scaling across outlets. Stakeholders must monitor how state-level plastic ban enforcement and evolving FSSAI labeling rules affect packaging costs and menu engineering decisions.
Market Dynamics
Cloud kitchen infrastructure is rewriting capital deployment patterns across Indian QSR chains, allowing operators to bypass prime real estate premiums while maintaining last-mile density through aggregator platform integration.
Growth Catalysts
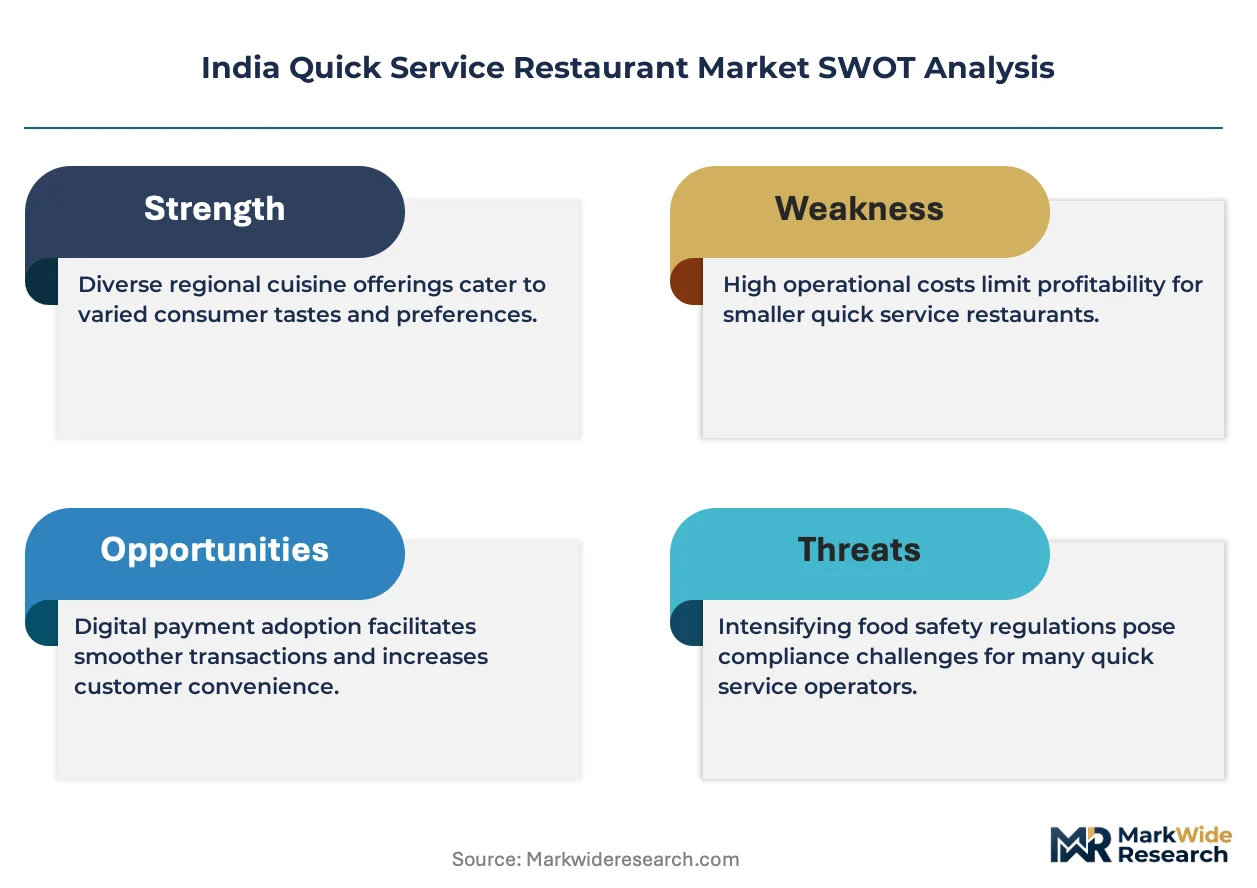
- UPI Payment Rails:NPCI's real-time settlement infrastructure enables frictionless cashless transactions at scale, reducing checkout friction and expanding addressable consumer base beyond cash-dependent segments.
- Aggregator Platform Integration:Swiggy and Zomato's logistics networks provide dedicated dark kitchen access and demand aggregation, compressing customer acquisition costs for emerging chains.
- FSSAI Hygiene Rating Mandates:Standardized food safety certification creates consumer trust signals that accelerate brand penetration in tier-2 and tier-3 city clusters.
Market Restraints
- Input Cost Volatility:Wheat flour and edible oil price fluctuations squeeze margin structures, forcing menu engineering trade-offs between portion sizes and price points.
- Supply Concentration Risk:Cold chain infrastructure bottlenecks in eastern and northeastern states limit perishable ingredient sourcing reliability for national expansion.
- Regulatory Friction:State-level plastic ban enforcement variations create packaging compliance complexity, requiring multi-SKU inventory strategies across municipal jurisdictions.
Strategic Opportunities
- Tier-2 City Penetration:Underpenetrated markets in Indore, Lucknow, and Kochi offer first-mover advantages for chains with localized menu adaptation capabilities.
- PLI Scheme Alignment:Food processing infrastructure incentives reduce capital intensity for automated kitchen equipment deployment at scale.
- AI-Driven Demand Forecasting:Machine learning convergence with POS data enables dynamic inventory management, cutting waste ratios in high-SKU operations.
Industry Challenges
- Skilled Kitchen Labor Scarcity:Standardized recipe execution at volume requires trained personnel, yet culinary vocational pipeline output lags chain expansion timelines.
- Multi-License Compliance Burden:Municipal corporation food licenses, FSSAI state registrations, and BIS packaging certifications create overlapping approval timelines that delay store openings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Quick Service Restaurant Market |
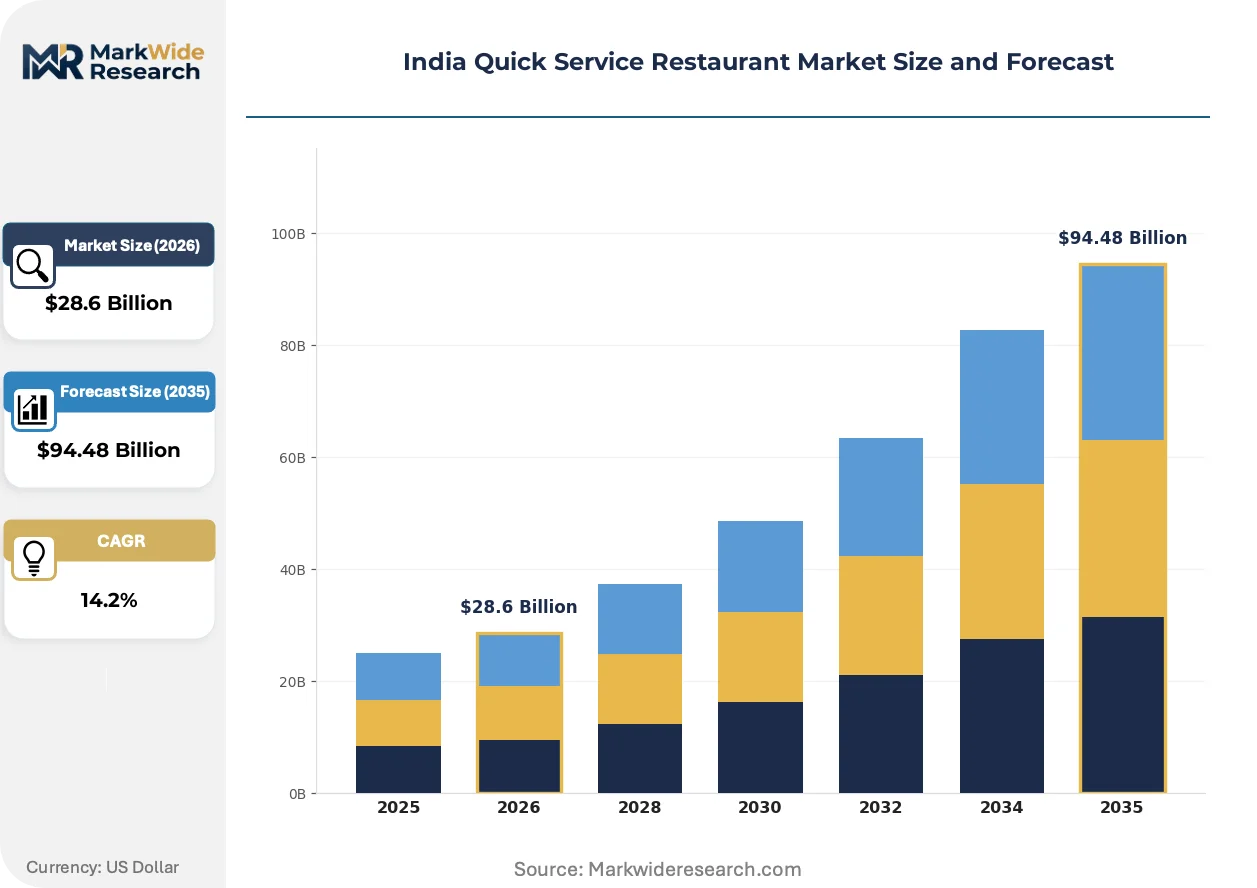
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Pizzas, Sandwiches, Salads Service Type: Dine-in, Takeaway, Delivery, Drive-thru Customer Type: Students, Working Professionals, Families, Tourists Franchise Model: Single Unit, Multi-unit, Master Franchise, Area Development |
| Companies Covered | Restaurant Brands Asia, Hardcastle Restaurants, Jubilant FoodWorks, Haldiram's, Everstone Group, Westlife Foodworld, Connaught Plaza Restaurants, Burger King India, Devyani International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Quick Service Restaurant Market Trends and Innovations
Digital-native operational models are displacing legacy dine-in-centric architectures, with technology investment priorities shifting toward predictive analytics and automated fulfillment systems that compress order-to-delivery windows.
Kitchen automation hardware is rewriting throughput economics for high-volume operators. Robotic frying stations and automated beverage dispensers reduce per-unit labor minutes. Metro chains in Mumbai and Bengaluru are piloting these systems during peak hours. The technology is rewriting staff deployment models from fixed-shift to dynamic task allocation based on real-time demand signals.
FSSAI's mandatory ingredient traceability requirements reshape procurement documentation standards. Suppliers must maintain batch-level digital records accessible to enforcement inspectors. Pizza and burger chains with centralized commissary models face accelerated compliance costs compared to dispersed kitchen networks.
Subscription-based meal programs disrupt traditional transaction economics for habitual consumers. Swiggy One and Zomato Gold memberships bundle delivery fee waivers with restaurant discounts, shifting loyalty from individual brands to platform ecosystems. This behavior concentrates order flow toward platform-preferred partners in Delhi NCR and Bengaluru clusters.
India Quick Service Restaurant Market Segmentation
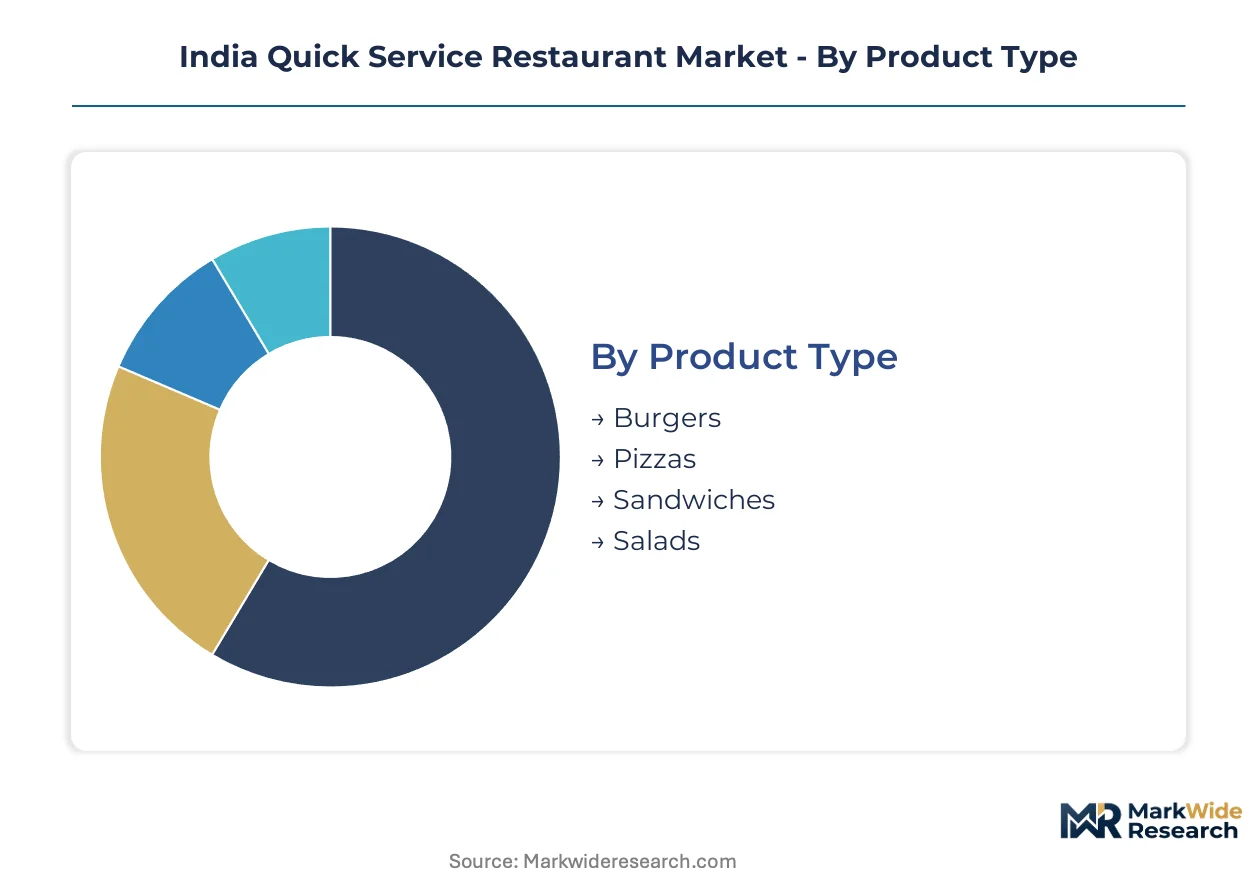
Segmentation in the Indian QSR market reveals how consumption patterns fragment across urban density tiers, digital payment maturity, and franchise capital availability. Understanding these divides helps operators allocate kitchen automation investments and localize menu engineering for distinct occasion-based demand clusters.
Product Type:
Standalone menu categories dominate transaction volumes in high-street and mall locations, while embedded combo formats drive aggregator platform economics through higher basket values.
- Burgers:Standardized patty specifications with localized spice profiles anchor western and southern India operations. Maharashtra and Karnataka metro clusters generate concentrated demand through McDonald's franchise density and cloud kitchen burger specialists.
- Pizzas:Thin-crust variants with tandoori chicken and paneer toppings command premium pricing in Delhi NCR delivery corridors. Domino's last-mile infrastructure and oven-standardized throughput create defensible economics against emerging regional players.
- Sandwiches:Subway's cold-chain dependent model faces margin pressure from FSSAI hygiene rating mandates on fresh vegetable sourcing.
- Salads:Health-positioned offerings remain niche outside Bengaluru and Mumbai wellness-conscious consumer pockets.
Burgers lead volumes today; pizzas are gaining share fastest through aggregator bundling and dark kitchen penetration.
Service Type:
Cost tier stratification separates capital-light delivery-only models from real estate-heavy dine-in formats requiring municipal corporation licensing and FSSAI state registration compliance.
- Dine-in:Full-format stores with seating capacity above forty covers require fire safety NOCs and higher rental deposits in prime mall locations. Hardcastle Restaurants and Devyani International concentrate this format in Tier-1 catchments where foot traffic justifies fixed-cost absorption.
- Delivery:Dark kitchen infrastructure bypasses front-of-house costs while maintaining last-mile density through Swiggy and Zomato integration. Mumbai and Bengaluru host the highest cloud kitchen concentration, with operators leveraging NPCI UPI rails for cashless settlement at scale.
- Takeaway:Counter-service models with limited seating optimize throughput during lunch rushes in commercial district clusters.
- Drive-thru:Highway-adjacent formats remain underdeveloped outside Delhi NCR expressway corridors due to land acquisition costs and traffic pattern limitations.
Delivery climbs fastest; dine-in retains margin premium in premium mall locations.
Customer Type:
Volume concentration varies sharply by daypart and geography, with working professionals driving weekday lunch economics while families dominate weekend transaction baskets.
- Working Professionals:Time-constrained weekday demand concentrates in Mumbai's Bandra-Kurla Complex and Bengaluru's Electronic City corridors. Aggregator platform subscriptions compress delivery fees for habitual office orders, shifting loyalty toward platform ecosystems rather than individual brands.
- Students:Price-sensitive demand clusters near university towns in Pune, Hyderabad, and Chandigarh. Value-menu engineering and UPI wallet integrations capture this segment's limited disposable income.
- Families:Weekend occasion-driven visits prioritize dine-in ambience and child-friendly menu options in suburban mall locations.
- Tourists:Transit-hub demand at airports and railway stations favors recognizable global brands with standardized quality signals.
Working professionals generate highest transaction frequency; students show steepest expansion trajectory as Tier-2 university towns digitize.
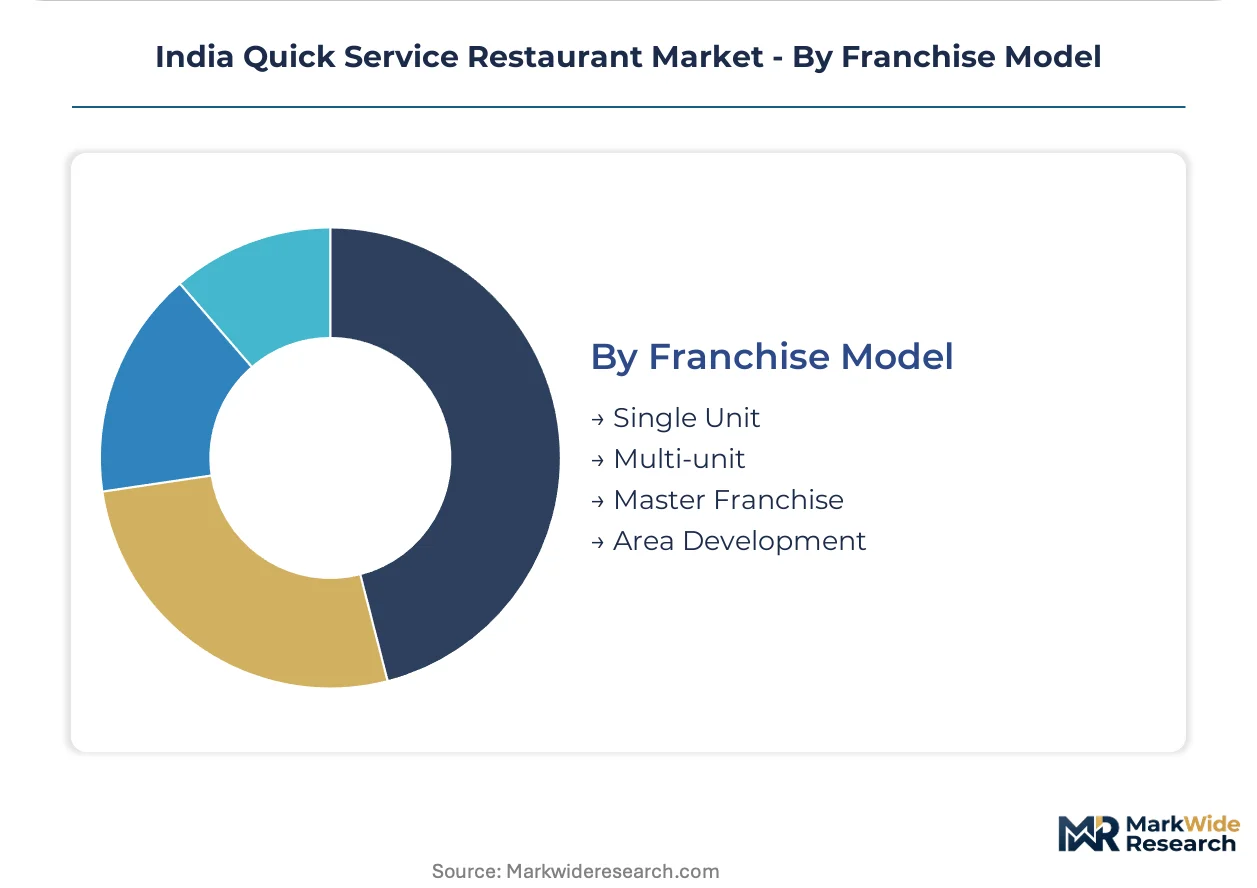
Franchise Model:
Maturity gradients separate established master franchise operators with multi-city expansion rights from emerging single-unit entrants navigating BIS packaging compliance and FSSAI licensing complexity.
- Master Franchise:Area developers control exclusive territorial rights across western and southern India, concentrating margin pools with Jubilant FoodWorks and Hardcastle Restaurants. These operators bear centralized supply chain investment and negotiate directly with Yum! Brands and McDonald's Corporation.
- Multi-unit:Regional operators with 5-15 store portfolios leverage localized real estate relationships in Indore, Lucknow, and Kochi underpenetrated markets.
- Single Unit:First-time entrepreneurs face overlapping approval timelines from municipal corporations and state FSSAI registrations that delay store openings.
- Area Development:Emerging format in Tier-2 expansion where operators commit to store-count milestones in exchange for territorial exclusivity.
Master franchise dominates revenue concentration; multi-unit models are expanding most quickly as capital seeks Tier-2 penetration exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate QSR expansion in states where FSSAI compliance costs and municipal licensing timelines diverge significantly, pushing capital toward Maharashtra and Karnataka where digital infrastructure reduces operational friction.
Maharashtra
Mumbai's cloud kitchen density and UPI penetration anchor western India QSR volume, with Swiggy and Zomato dark kitchens clustering in Bandra-Kurla and Andheri corridors. FSSAI state registration protocols here standardize faster than eastern counterparts, compressing store-opening timelines. Hardcastle Restaurants concentrates McDonald's franchise operations across Pune and Nashik satellite markets.
Karnataka
Bengaluru's Electronic City and Whitefield tech corridors generate concentrated weekday lunch demand from IT professionals, driving delivery-format dominance. BIS packaging standards enforcement in the state creates compliance clarity that attracts multi-unit regional operators. White-label cloud kitchen infrastructure in Koramangala reduces capital barriers for emerging chains.
Delhi NCR
The National Capital Region's highway-adjacent real estate enables limited drive-thru piloting along Delhi-Jaipur and Delhi-Agra expressways, though land acquisition costs constrain scaling. FSSAI hygiene rating mandates face strictest municipal enforcement in New Delhi municipal limits, elevating compliance costs for dine-in formats. Connaught Plaza Restaurants anchors northern India McDonald's operations from this cluster.
Telangana
Hyderabad's HITEC City corridor replicates Bengaluru's tech-worker demand profile, with aggregator platform penetration expanding fastest among southern tier-2 markets. State-level plastic ban enforcement variations create packaging SKU complexity for national operators. Devyani International leverages Yum! Brands portfolio expansion into Secunderabad and Warangal catchments.
Tamil Nadu
Chennai's organized retail mall density supports dine-in format viability, with Phoenix MarketCity and Express Avenue hosting concentrated QSR foot traffic. RBI digital payment guidelines accelerate UPI wallet integration among price-sensitive student segments near Anna University and IIT Madras. Cold chain infrastructure gaps in Coimbatore and Madurai constrain perishable ingredient reliability for pizza and burger chains.
India Quick Service Restaurant Market Competitive Landscape
Western India franchise operators anchor one tier; southern India specialists hold territorial exclusivity through master franchise structures. The market presents a consolidated structure where three area developers control multi-city expansion rights for global brands. Two strategic archetypes dominate: vertically integrated commissary operators and aggregator-platform-dependent dark kitchen networks. Competitive moves concentrate on tier-2 city preemption and cloud kitchen capacity scaling.
Among master franchise holders, Hardcastle Restaurants, Jubilant FoodWorks, and Devyani International occupy positions that exemplify the area-developer archetype, each controlling exclusive territorial rights across distinct regional clusters. Hardcastle Restaurants represents western and southern India McDonald's operations, while Jubilant FoodWorks anchors pizza delivery infrastructure nationwide. Devyani International sits within the multi-brand portfolio tier, leveraging Yum! Brands licensing to compete across fried chicken and pizza categories.
| Leading Market Players |
|---|
| Restaurant Brands Asia |
| Hardcastle Restaurants |
| Jubilant FoodWorks |
| Haldiram's |
| Everstone Group |
| Westlife Foodworld |
| Connaught Plaza Restaurants |
| Burger King India |
| Devyani International |
| Others |
Pricing and Supply Chain Analysis
Aggregator-dependent delivery operators concentrate order flow and compress margins through platform fee structures, forcing a transactional pricing model tethered to Swiggy and Zomato commission tiers rather than brand-controlled premium positioning.
Pricing Analysis
Distributor-aggregator margins absorb 18-25% of gross transaction value, squeezing operator economics across delivery formats. Three-tier pricing structure across premium dine-in, standard delivery, and economy cloud kitchen tiers separates Hardcastle Restaurants' mall locations from dark kitchen specialists. Pricing pressure stems from wheat flour and edible oil input volatility, forcing portion-size reductions at the economy tier. Students near Pune and Chandigarh university clusters exhibit highest price sensitivity, while working professionals in Mumbai's Bandra-Kurla Complex prioritize speed over per-transaction cost.
Supply Chain Analysis
Reverse logistics for perishable returns and temperature-compromised ingredients flows through centralized commissary networks back to supplier credit programs. Supply concentrates in Maharashtra and Karnataka for processed cheese and frozen patty inputs, with cold chain infrastructure gaps in Tamil Nadu and Telangana creating sourcing reliability differentials. Wheat flour from Punjab and Haryana, edible oils from Indonesia and Malaysia, and packaging materials from Gujarat feed national operations. Single-source vulnerability in frozen poultry supply from integrated processors creates concentration risk. Distribution runs through Jubilant FoodWorks' commissary hubs to last-mile dark kitchens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where FSSAI hygiene rating mandates and ingredient traceability requirements push demand toward certified operators with centralized supply chain control.
For Market Incumbents: Hedge against aggregator platform disintermediation by building direct-ordering infrastructure through proprietary apps with UPI integration. Defend margin position by deepening backward integration into commissary operations and securing long-term supply agreements with frozen protein processors. FSSAI compliance cost escalation threatens single-unit franchisees; capture their exit through selective multi-unit acquisitions in Indore and Lucknow corridors. For New Entrants and Emerging Players: Capture white-space in Tier-2 cloud kitchen deployment where real estate costs remain 40% below Mumbai levels and aggregator penetration is accelerating fastest. Target Kochi and Warangal catchments where master franchise coverage remains thin and municipal licensing timelines compress store-opening windows. Lead with health-positioned menu differentiation to exploit Bengaluru and Mumbai wellness-conscious demand pockets. For Investors and Strategic Acquirers: Private equity firms with foodservice platform experience are the most active acquirer in this space, consolidating multi-unit regional operators into scalable area-development platforms. Five-to-ten year viability hinges on cloud kitchen infrastructure ownership and direct consumer data access. Monitor FSSAI enforcement intensity in eastern states as inflection indicator for compliance-cost-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Buildout | Swiggy and Zomato dark kitchen partnerships reduce capital intensity for emerging chains entering Tier-2 markets. |
| Commissary Network Expansion | Centralized procurement from Punjab and Haryana grain belts cuts input cost volatility for pizza and burger operators. |
| Direct-to-Consumer App Launch | Proprietary ordering platforms with NPCI UPI integration bypass aggregator commission tiers and capture customer data. |
| FSSAI Hygiene Rating Investment | Five-star certification signals quality in tier-2 and tier-3 city clusters where brand recognition remains limited. |
| Subscription Meal Program Development | Swiggy One and Zomato Gold partnerships lock in habitual demand from working professionals in Bengaluru and Delhi NCR. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with master franchise operations directors, FSSAI compliance officers, aggregator platform partnership managers, and cold chain logistics providers with secondary validation from FSSAI hygiene rating databases, RBI digital payment statistics, NPCI UPI transaction reports, and municipal corporation licensing records. Bottom-up store-count modeling and top-down consumption expenditure triangulation anchored market sizing.
Segment-weighting approaches distributed value across product type, service format, customer archetype, and franchise model dimensions throughout the projection horizon. CAGRs derived from trend-line extrapolation of historical expansion patterns adjusted for cloud kitchen infrastructure deployment rates and aggregator platform penetration curves. Forecast inputs incorporated PLI scheme incentive uptake for food processing equipment and state-level plastic ban enforcement variation.
Input cost volatility, regulatory enforcement intensity shifts, and aggregator platform pricing power moves are the dominant revision risks to modeled outputs. Practitioners should monitor wheat flour and edible oil futures, FSSAI inspection frequency changes, and Swiggy-Zomato commission tier adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Brazil Foodservice Market
Food Service
Food Service Dairy Products Market
Food Service
Beverage Coaster Market
Food Service
One-Off Chopsticks Market
Food Service
Benelux Foodservice Market
Food Service
New Zealand Foodservice Market
Food Service
Europe Pizza Oven Market
Food Service
Undercounter Ice Makers Market
Food Service
South America Free from Food Market
Food Service
Ship Catering Service Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Global Online Food Delivery Services Market
Food Service
Instant Grocery Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Pizza Foodservice Market