
 Egypt Food Service Market | 2026-2036
Egypt Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Service Market Insights
Buyer fragmentation across Egypt's young professional demographic is repositioning where food service operators deploy capital. Americana Restaurants International PLC leverages its multi-brand portfolio to capture frequency across income tiers, while Mo'men Group anchors its position in the quick-service segment through localized menu engineering. Alamar Foods Company competes on supply chain density, sustaining kitchen-level consistency across dispersed locations.
Egypt food service encompasses commercial preparation and delivery of ready-to-consume meals through institutional and retail channels, requiring HACCP-compliant cold storage, standardized portion control, and real-time inventory tracking to manage perishability across high-temperature climates. Full-service restaurants and fast food chains command the largest revenue pools, though catering services targeting corporate clients and wedding events represent the fastest-expanding margin segment. Budget and mid-range price tiers dominate transaction volume, while premium positioning concentrates in Cairo's satellite compounds and coastal resort zones.
Egypt's National Food Safety Authority and the Egyptian Organization for Standardization and Quality enforce escalating hygiene protocols and ingredient traceability mandates that elevate compliance costs for smaller operators. The Ministry of Trade and Industry's industrial licensing framework shapes where central kitchens and commissary facilities may locate, directly constraining expansion geography. Stakeholders must weigh regulatory escalation against the capital requirements of backward integration into in-house bakery and protein processing operations.
Market Dynamics
Digital ordering platforms are compressing order-to-delivery cycles across Egypt's food service sector, forcing operators to reconfigure kitchen workflows and last-mile logistics around app-based demand spikes rather than traditional foot-traffic patterns.
Growth Catalysts
- NFSA Modernization:Egypt's National Food Safety Authority mandates are accelerating cold-chain infrastructure investment, elevating compliance standards that favor scaled operators with centralized quality systems.
- University Digital Adoption:Quick-service penetration among Egyptian university students is deepening as mobile payment integration reduces friction for recurring small-ticket transactions.
- Administrative Capital Development:Greater Cairo's new administrative capital district is concentrating commercial real estate deployment, creating captive demand pools for food service operators with early site access.
Market Restraints
- Protein Input Volatility:Poultry and red meat price swings in Egyptian wholesale markets compress margin predictability for operators without forward-contracting capabilities.
- Refrigeration Energy Costs:Grid instability and diesel generator dependency in Egypt's high-temperature climate inflate cold-storage operating expenditures beyond regional benchmarks.
- Import Dependency:Specialized food processing equipment and certain ingredient categories remain concentrated in European and Asian supplier bases, exposing operators to currency fluctuation risk.
Strategic Opportunities
- Catering Corporate Contracts:Egypt's wedding and corporate event catering segment remains fragmented, creating consolidation potential for operators with HACCP-certified central kitchens.
- Coastal Resort Zones:Premium positioning in Red Sea and North Coast developments offers margin expansion for brands with experience in tourist-facing service models.
- Commissary Licensing Arbitrage:Ministry of Trade and Industry industrial licensing constraints create site scarcity value for operators securing approved central kitchen locations ahead of competitors.
Industry Challenges
- Cold-Chain Technician Scarcity:Egypt's food service sector faces acute shortages of HACCP-certified refrigeration technicians and temperature-controlled logistics coordinators.
- Legacy POS Integration:Fragmented point-of-sale systems across franchised networks complicate real-time inventory synchronization with aggregator platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Service Market |
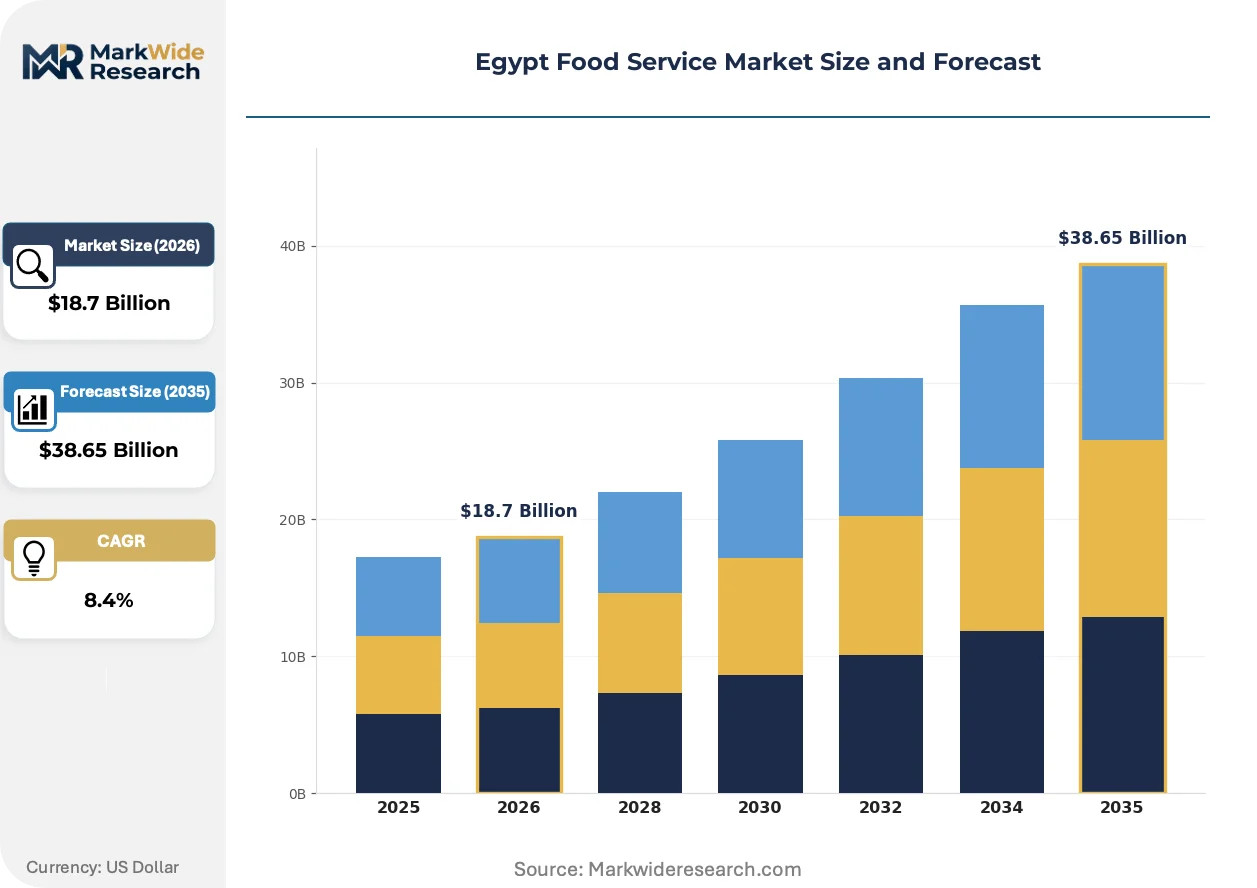
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-service Restaurants, Fast Food Chains, Cafés, Catering Services Customer Type: Families, Business Professionals, Tourists, Students Product Category: Beverages, Appetizers, Main Courses, Desserts Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Alamar Foods Company, Americana Restaurants International PLC, Mansour Group, Mo'men Group, The Olayan Group, Fawaz Abdulaziz AlHokair Company, Hassan Abou Shakra Restaurants, SAAL Invest, TBS Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Service Market Trends and Innovations
Cloud-based kitchen management systems are penetrating Egypt's food service infrastructure, enabling multi-location operators to centralize procurement and production planning across dispersed sites.
Artificial intelligence-driven demand forecasting is automating inventory replenishment cycles for Egyptian quick-service chains. Operators with ten-plus locations are deploying machine learning models trained on aggregator platform data to reduce protein waste and optimize prep schedules. This compression of forecasting error rates is reallocating working capital from safety stock toward expansion capex.
Egypt's National Food Safety Authority traceability mandates are forcing ingredient documentation upgrades across the supply chain. Smaller operators face compliance cost escalation as paper-based lot-tracking systems become non-viable. Full-service restaurants with complex multi-supplier sourcing are experiencing the steepest adaptation friction.
Aggregator platform loyalty programs are displacing operator-owned customer relationships in Greater Cairo. Young professional households now initiate food discovery through app algorithms rather than brand search, compressing lifetime value capture for chains without platform co-marketing budgets. This channel dependency is most pronounced in Cairo's new administrative capital district where digital-native residents dominate.
Egypt Food Service Market Segmentation
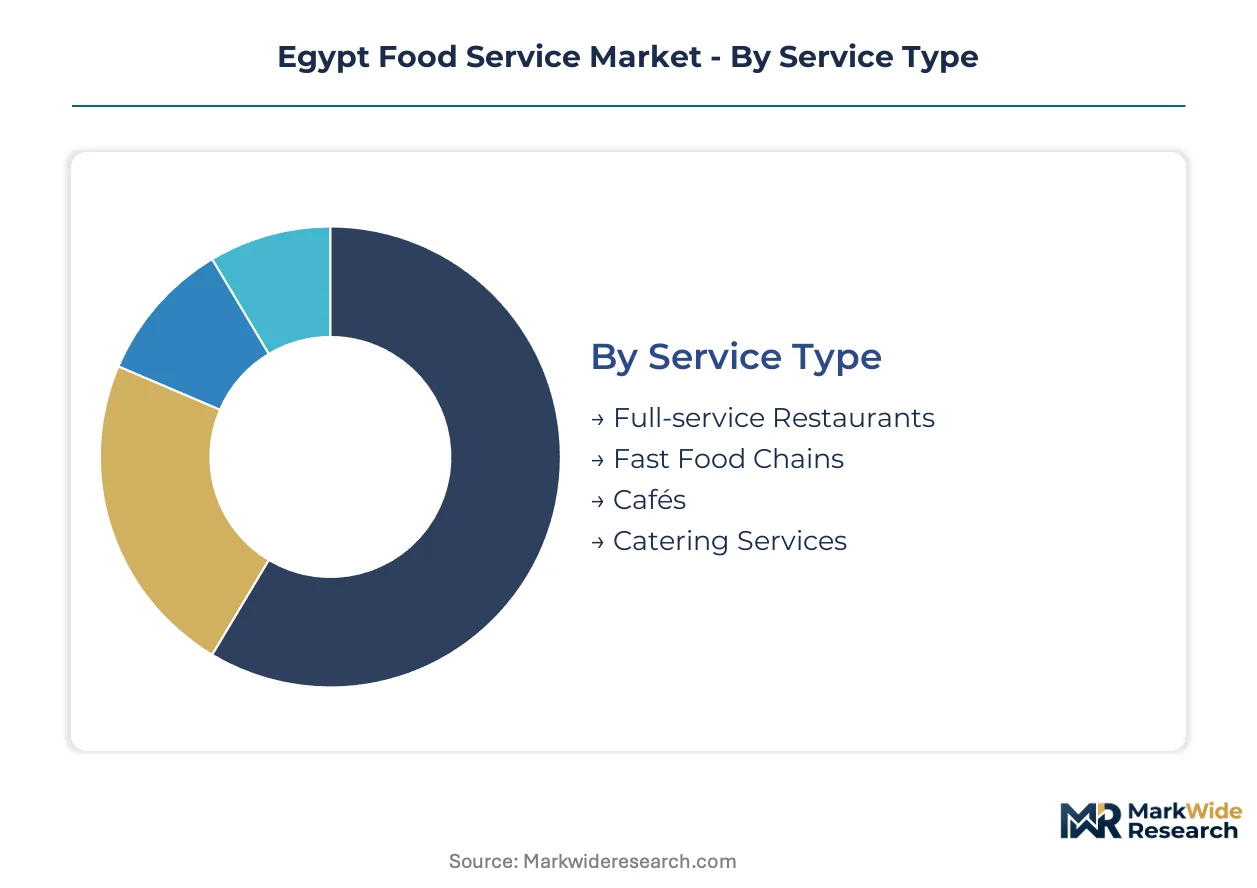
Segmentation in Egypt's food service market reveals how regulatory compliance burdens, price sensitivity gradients, and customer occasion types reshape capital allocation across service formats. Operators must match certification requirements to segment complexity while navigating NFSA traceability mandates that vary by operational scale.
Service Type:
NFSA HACCP certification intensity escalates with kitchen complexity and multi-site coordination, creating tiered compliance thresholds across operational models.
- Full-service Restaurants:Table-service operations with on-premise cooking require full cold-chain documentation and ingredient lot-tracking under NFSA mandates. Demand concentrates in Cairo's satellite compounds where affluent households seek dine-in experiences, though refrigeration energy costs compress margins for independent operators without generator backup.
- Fast Food Chains:Standardized menu platforms with centralized supply chains leverage economies of scale to absorb NFSA compliance investments. University districts and the new administrative capital district anchor expansion, where digital-native consumers drive frequency through aggregator platform ordering.
- Cafés:Beverage-forward formats with limited food preparation face lighter HACCP documentation but must still maintain temperature logs for dairy supply chains.
- Catering Services:Event-based production with variable batch sizing encounters acute traceability challenges under NFSA lot-tracking rules, particularly for wedding-scale protein procurement.
Fast Food Chains sits at the top of the volume ranking, with Catering Services climbing the fastest.
Customer Type:
Transaction frequency patterns and payment method preferences segment Egypt's food service demand by life-stage and income stability.
- Families:Multi-person dining occasions favor full-service restaurants with child-accommodating formats in suburban Cairo developments. Weekend concentration creates demand spikes that strain kitchen capacity planning.
- Business Professionals:Time-compressed lunch occasions in central business districts drive quick-service penetration, with corporate catering contracts offering volume predictability for operators with central kitchen infrastructure.
- Tourists:Coastal resort zones and Nile cruise operations require multilingual service capabilities and international payment acceptance, with Red Sea developments commanding premium positioning.
- Students:Egyptian university populations exhibit the steepest digital adoption curve, with mobile wallet integration enabling small-ticket frequency that aggregator platforms capture through loyalty algorithms.
Students generate the highest transaction velocity, while Business Professionals deliver the strongest per-visit spend expansion.
Product Category:
Perishability windows and ingredient import dependency create divergent margin profiles across menu construction.
- Beverages:Fountain and packaged drinks with extended shelf stability require minimal cold-chain investment, though sugar taxation proposals threaten margin structures. Local bottling partnerships reduce currency exposure versus imported concentrate models.
- Appetizers:Fried and cold-start items with shorter holding periods demand precise production timing to minimize waste under Egypt's high-temperature climate conditions.
- Main Courses:Protein-centric plates face acute input volatility from Egyptian poultry and red meat wholesale markets, pushing scaled operators toward forward contracting with domestic suppliers.
- Desserts:Dairy-dependent preparations with strict temperature requirements encounter NFSA scrutiny on custard and cream handling protocols, favoring operators with commissary-level pastry production.
Main Courses anchors revenue contribution, with Beverages expanding most quickly through aggregator platform combo pricing.
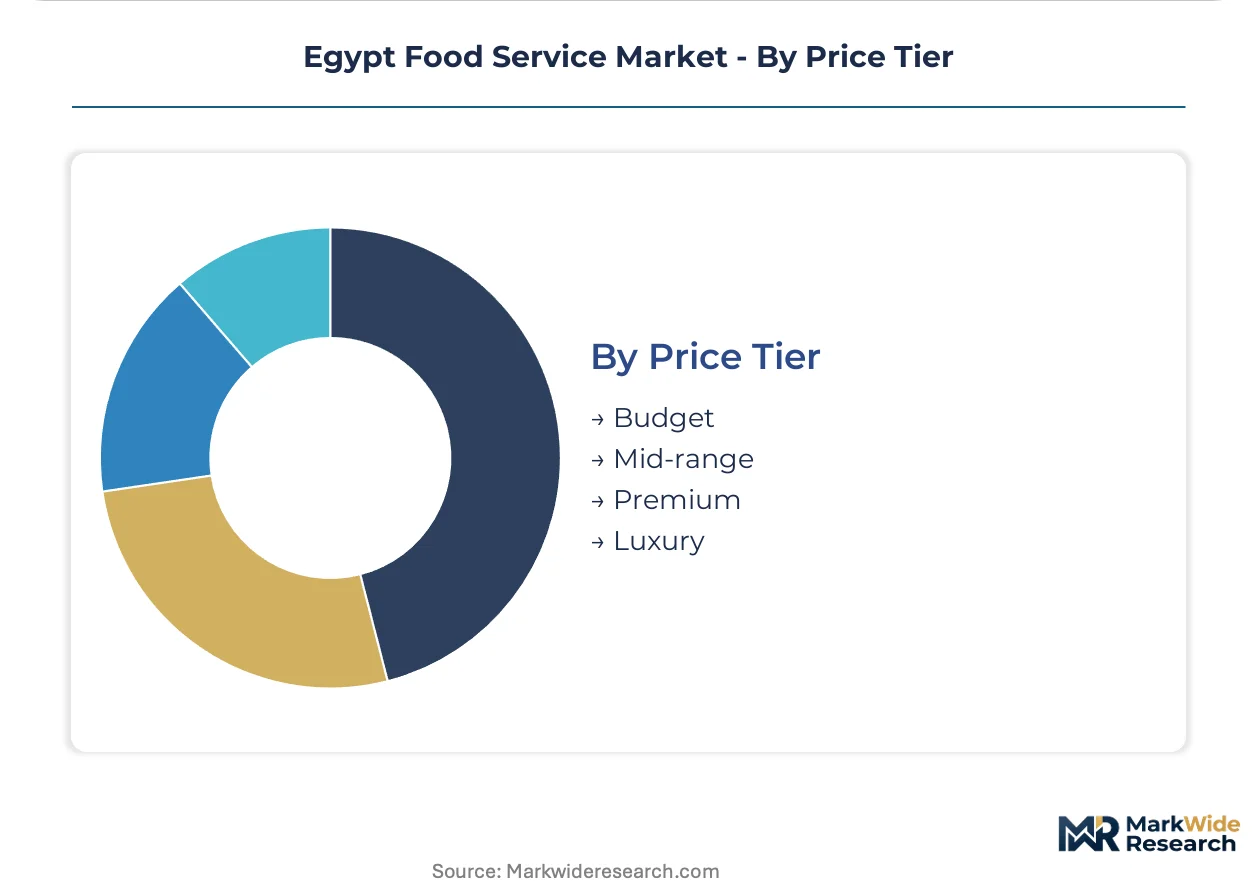
Price Tier:
Capital deployment returns vary sharply across Egypt's stratified consumer base, with location access determining feasible positioning.
- Budget:Street-food adjacent formats and limited-menu kiosks dominate transaction count in dense urban cores, though NFSA registration requirements now capture previously informal operators.
- Mid-range:Full-service and quick-service hybrids in Greater Cairo's middle-income districts balance accessibility with experience, representing the largest addressable revenue pool.
- Premium:Chef-driven concepts and international brand licensing concentrate in Cairo's new administrative capital district and coastal compounds, where expatriate and affluent Egyptian households cluster.
- Luxury:Fine-dining with imported ingredient dependence and specialized equipment faces acute currency risk, limiting viable site selection to dollarized revenue environments like Red Sea resorts.
Mid-range commands absolute transaction volume, with Premium gaining share fastest through new administrative capital development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unlike Saudi Arabia's concentrated Riyadh-Jeddah corridor, Egypt's food service expansion disperses across multiple governorates with divergent regulatory enforcement intensity and infrastructure maturity.
Greater Cairo
Metropolitan Cairo generates the highest transaction density through mixed-use developments in the new administrative capital district. The National Food Safety Authority operates its primary inspection hub here, accelerating HACCP certification timelines for operators with central kitchen infrastructure. Zamalek and New Cairo satellite compounds concentrate premium full-service dining.
Alexandria and the North Coast
Summer tourism surges reshape Alexandria's food service calendar, with coastal resort zones commanding threefold pricing premiums during peak months. The Ministry of Trade and Industry maintains lighter industrial licensing scrutiny in secondary cities, enabling faster commissary deployment. Borg El Arab industrial city anchors protein processing clusters serving Alexandria's quick-service chains.
Upper Egypt Governorates
Asyut and Sohag exhibit nascent quick-service penetration among public university populations with accelerating mobile wallet adoption. The National Food Safety Authority extends regional office coverage slowly, creating compliance timing arbitrage for early-scaling operators. Local poultry supply chains reduce protein input volatility versus Cairo-dependent logistics.
Suez Canal Zone
Port Said and Ismailia leverage transshipment logistics for imported ingredient access, though currency fluctuation risk concentrates among operators with European equipment dependencies. The Suez Canal Economic Zone Authority offers industrial licensing fast-tracks for central kitchen investments exceeding specified capital thresholds.
Egypt Food Service Market Competitive Landscape
Cairo-based operators anchor the volume tier; Gulf-backed specialists hold premium positioning through franchise licensing. Market structure tilts toward consolidated quick-service chains with multi-brand portfolios, while independent full-service restaurants fragment across income districts. Three archetypes dominate: diversified portfolio conglomerates, single-format scale specialists, and family-owned regional networks. Competitive moves concentrate on site access racing in the administrative capital and backward integration into commissary production.
Within the diversified portfolio tier, Americana Restaurants International PLC and Alamar Foods Company occupy positions spanning quick-service and casual dining formats. Mo'men Group exemplifies the single-format scale archetype with concentrated quick-service penetration. These three anchors represent distinct capital deployment strategies: Americana leverages cross-brand customer frequency, Alamar competes on supply chain density, and Mo'men deepens localized menu engineering.
| Leading Market Players |
|---|
| Alamar Foods Company |
| Americana Restaurants International PLC |
| Mansour Group |
| Mo'men Group |
| The Olayan Group |
| Fawaz Abdulaziz AlHokair Company |
| Hassan Abou Shakra Restaurants |
| SAAL Invest |
| TBS Co. |
| Others |
Pricing and Supply Chain Analysis
Poultry and red meat input volatility cascades through Egypt's food service tiers, compressing margins for operators without forward-contracting capabilities while elevating price floors for budget formats dependent on spot-market procurement. NFSA traceability mandates layer compliance costs onto smaller players, widening spreads between HACCP-certified chains and informal street-food adjacent competitors.
Pricing Analysis
Capacity additions in Greater Cairo's new administrative capital district are reshaping price floors as early-site operators capture captive demand pools before competitive density intensifies. Three-tier pricing structure across premium, mid-range, and budget levels dominates, with price differentiation driven by cold-chain certification grade and generator backup availability. Pricing pressure stems from protein input volatility and refrigeration energy costs, with students exhibiting highest price sensitivity and coastal resort tourists showing lowest.
Supply Chain Analysis
Workforce availability constraints in Egypt's cold-chain technician training pipeline bottleneck HACCP-compliant operations expansion. Supply concentrates in domestic poultry clusters around Borg El Arab and imported equipment corridors through Port Said and Ismailia. Raw material dependencies span Egyptian poultry, European processing equipment, and Asian packaging inputs. Single-source vulnerability concentrates in specialized refrigeration compressor imports. Distribution runs through aggregator platforms for last-mile delivery and central kitchen networks for B2B catering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
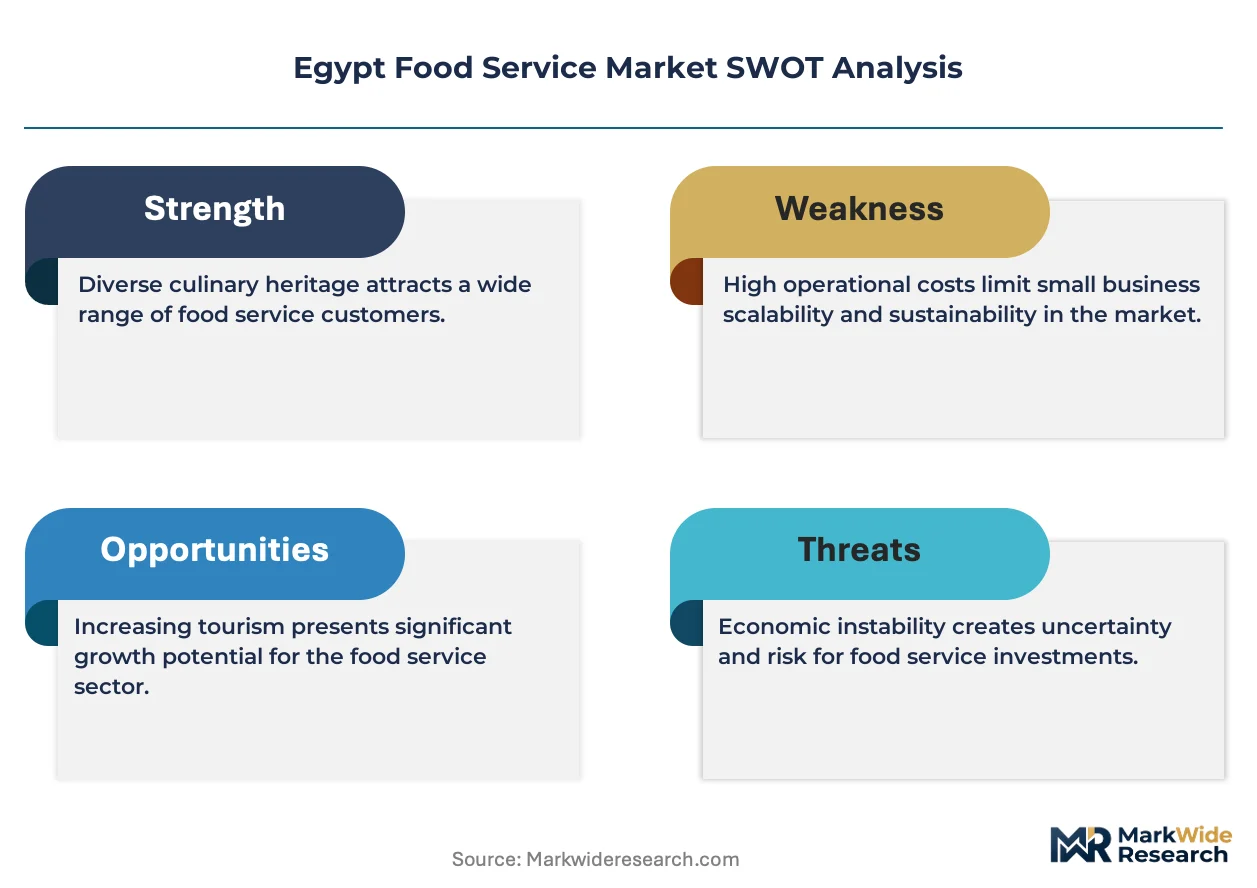
Egypt's food service market functions as a geographic-arbitrage play where NFSA compliance timing in Upper Egypt governorates lags Greater Cairo by 18-24 months, enabling cost-efficient scaling before regulatory parity.
For Market Incumbents: Deploy commissary licensing arbitrage to secure Ministry of Trade and Industry-approved central kitchen sites ahead of competitors in the administrative capital district. Anchor defensive positioning through backward integration into in-house protein processing, countering import dependency exposure and aggregator platform disintermediation threats. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in Upper Egypt's university districts offer white-space entry with lighter NFSA enforcement intensity. Target Asyut and Sohag public university corridors with mobile-first quick-service formats, leveraging local poultry supply chains and aggregator platform loyalty algorithm partnerships for customer acquisition. For Investors and Strategic Acquirers: Consolidation pressure builds where HACCP-certified central kitchen infrastructure remains scarce relative to administrative capital commercial development velocity. Long-term viability favors operators with captive supply chain control and platform-independent customer data assets. Monitor NFSA regional office expansion announcements as inflection signals for compliance cost parity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Licensing Arbitrage | Ministry of Trade and Industry site scarcity creates durable competitive moats for early movers. |
| Backward Integration into Protein Processing | In-house poultry processing insulates margins from Egyptian wholesale market volatility. |
| Aggregator Platform Co-Marketing Investment | Algorithm-driven discovery in Cairo's administrative capital district displaces brand-owned customer relationships. |
| Cold-Chain Technician Training Pipeline | HACCP-certified workforce scarcity constrains multi-site expansion for unscaled operators. |
| Coastal Resort Zone Premium Positioning | Red Sea and North Coast developments command tourist-facing pricing premiums during seasonal peaks. |
Research Methodology
Coverage spans Greater Cairo, Alexandria and North Coast, Upper Egypt governorates, and Suez Canal Zone, with primary inputs from each. The analysis combines structured interviews with central kitchen operations directors, NFSA compliance officers, aggregator platform account managers, and quick-service franchise development leads with secondary validation from customs records, Ministry of Trade and Industry licensing databases, and National Food Safety Authority inspection filings. Bottom-up location-level transaction modeling and top-down sector revenue triangulation anchor the quantitative framework.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include service type, customer archetype, product category, price tier, and regional regulatory enforcement intensity. CAGRs derive from time-series regression of location-level transaction data, aggregator platform order flow, and commercial real estate deployment pipelines. Industry-specific forecast inputs incorporate protein wholesale price indices and NFSA inspector deployment schedules.
Caveats apply where currency fluctuation, NFSA enforcement acceleration, or grid instability could materially shift the outlook. Forecasts reflect assumptions about aggregator platform market concentration and cold-chain infrastructure investment continuity. Practitioners should monitor NFSA regional office staffing announcements and central bank foreign exchange auction patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Service Gloves Market
Food Service
Tabletop Pizza Oven Market
Food Service
Belgium HRI Market
Food Service
Europe Airline Catering Services Market
Food Service
Food Service Pasta Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Russia Foodservice Market
Food Service
Food Trays Market
Food Service
Spain Food Service Market
Food Service
Mexico Foodservice Market
Food Service
Global Sushi Restaurants Market
Food Service
Charbroiler Market
Food Service
India Quick Service Restaurant Market
Food Service
United Kingdom Foodservice Market
Food Service
West Africa Food Services Market
Food Service
Contract Blending Services Market