
 United Arab Emirates Full Service Restaurants Market | 2026-2036
United Arab Emirates Full Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Full Service Restaurants Market Insights
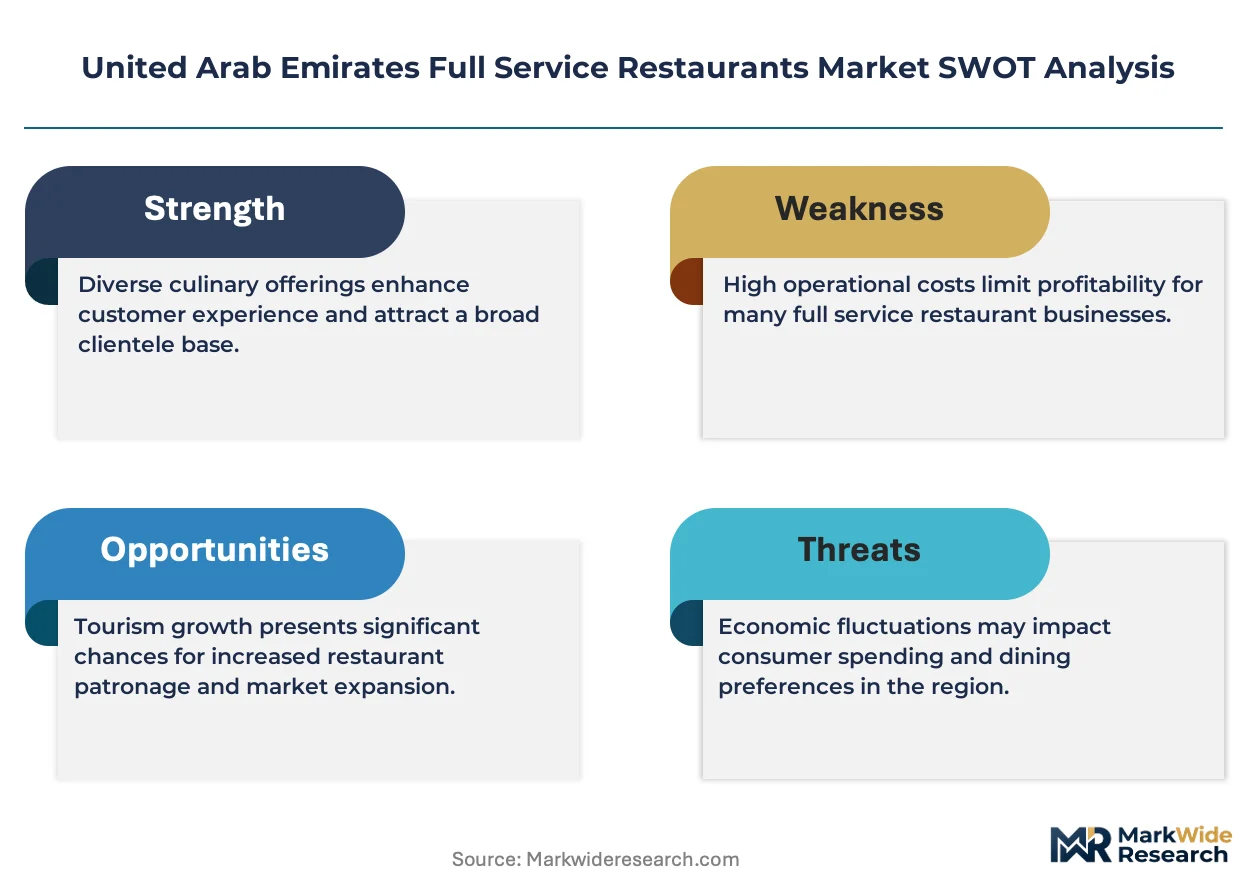
A capital-intensity divergence between flagship property investments and lean cloud-kitchen models is bifurcating competitive dynamics across the UAE full-service restaurant landscape. Americana Restaurants International PLC leverages its multi-brand portfolio and captive supply chain infrastructure to sustain pricing power across Gulf markets. M.H. Alshaya Co. WLL anchors its position through franchise control of global casual-dining banners with deep mall penetration. Alamar Foods Company differentiates via specialized pizza and quick-casual formats that compete for share-of-stomach against traditional table-service venues.
Full service restaurants in the United Arab Emirates are licensed foodservice establishments where patrons order at table, receive full waiter service, and consume meals on premises, typically operating with kitchen brigades, beverage programs, and front-of-house staff ratios exceeding ten employees per outlet. These venues function as experiential consumption platforms, combining culinary execution with ambiance design to capture extended dwell time and higher per-cover spending than limited-service alternatives. The cuisine type dimension shows Arabic and Italian concepts dominating revenue pools among tourists and resident expatriates, while Asian formats represent the fastest-growing category driven by South Asian demographic density and emerging Southeast Asian culinary interest. Price tier segmentation reveals mid-range and premium bands capturing the bulk of transaction volume, though luxury positioning commands disproportionate margin concentration in Dubai's hotel-anchored dining circuit.
MOHAP enforces HACCP-aligned food safety protocols and allergen labeling mandates that shape kitchen design and staff training investments across all emirates, while municipal tourism authorities in Dubai and Abu Dhabi regulate outdoor seating, entertainment licensing, and alcohol service permissions that directly affect revenue model viability. The country's central bank and SEBI-equivalent frameworks indirectly influence hospitality financing costs and foreign ownership structures for restaurant operators. Stakeholders must monitor evolving VAT enforcement patterns, labor quota adjustments under Emiratization policy, and sustainability disclosure requirements that will determine which full-service concepts retain operational licenses and consumer trust in the next planning cycle.
Market Dynamics
MOHAP food safety certification mandates and digital ordering platform mandates are compressing operational margins while forcing capital redeployment toward compliance infrastructure and guest-facing technology stacks.
Growth Catalysts
- Tourism corridor density:Dubai's hospitality corridor generates concentrated demand from business travelers and high-net-worth visitors, creating predictable revenue basins for premium table-service concepts.
- MOHAP HACCP alignment:Standardized food safety protocols reduce cross-emirate operational friction and enable multi-location brand expansion with unified training matrices.
- Cloud kitchen integration:Hybrid models combining flagship dining rooms with delivery-optimized ghost kitchens expand addressable market without proportional real estate burden.
Market Restraints
- Labor quota rigidity:Emiratization policy constraints limit front-of-house staffing flexibility, compressing service ratios during peak dining periods.
- Alcohol licensing fragmentation:Municipal tourism authority permitting variations across Dubai and Abu Dhabi create revenue model uncertainty for beverage-dependent concepts.
- Input cost volatility:Imported protein and specialty ingredient exposure to currency fluctuation and shipping rate spikes erodes menu margin predictability.
Strategic Opportunities
- Sharjah and Northern Emirates penetration:Underserved suburban corridors offer first-mover positioning ahead of infrastructure maturation.
- Sustainability disclosure alignment:Early compliance with emerging environmental reporting requirements builds license-to-operate advantage and corporate dining contract eligibility.
- AI-driven demand forecasting:Convergence of reservation platforms and inventory management systems enables dynamic pricing and waste reduction.
Industry Challenges
- Certification timeline compression:MOHAP audit backlogs and documentation requirements delay new outlet openings and concept refreshes.
- Legacy POS integration friction:Digital ordering platform mandates force costly retrofitting of established kitchen display and payment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Full Service Restaurants Market |
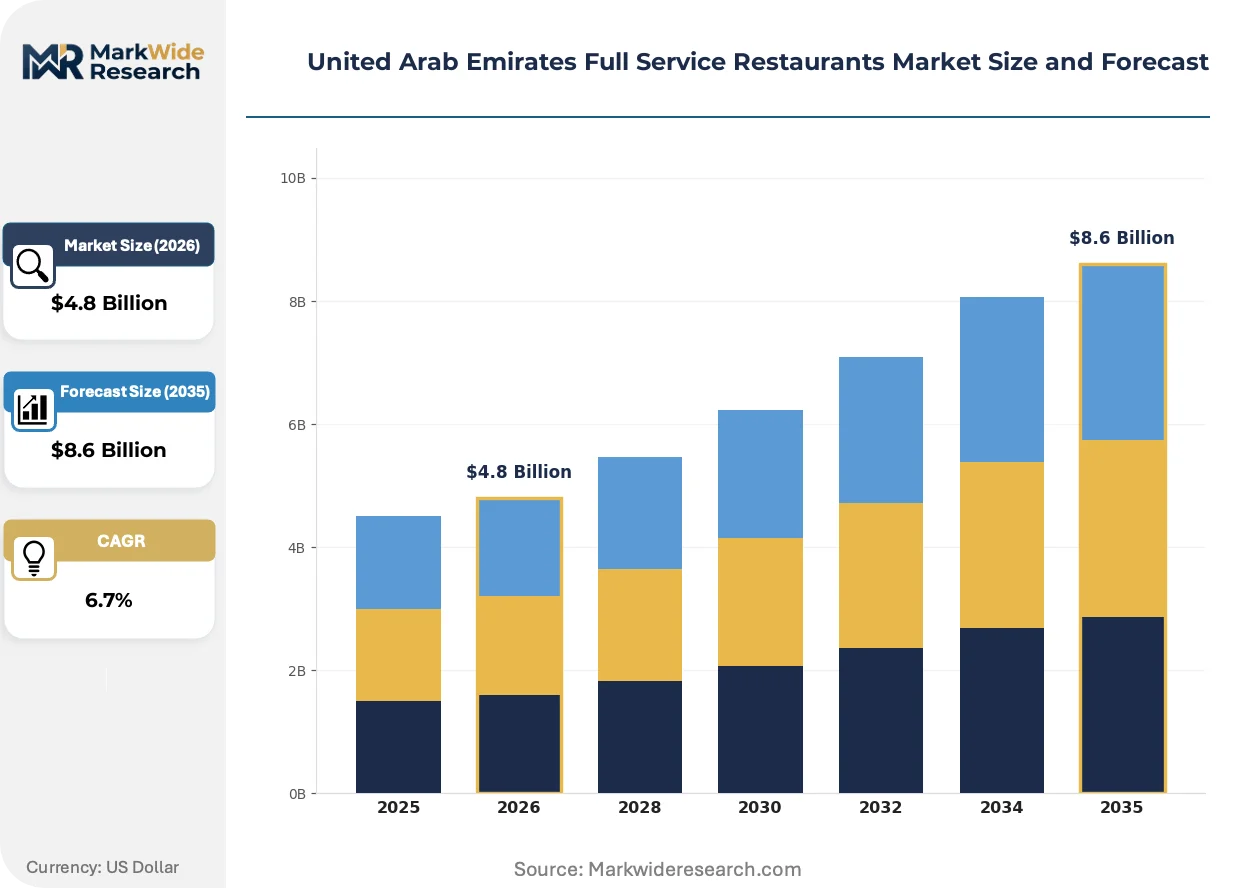
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-In, Takeaway, Catering, Delivery Price Tier: Budget, Mid-range, Premium, Luxury Cuisine Type: Arabic, Asian, Italian, American Customer Type: Families, Tourists, Business Travelers, Couples |
| Companies Covered | Americana Restaurants International PLC, M.H. Alshaya Co. WLL, Apparel Group, Al Khaja Group of Companies, Alamar Foods Company, Majid Al Futtaim Lifestyle, Brinker International Inc., The Olayan Group, LuLu Group International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Full Service Restaurants Market Trends and Innovations
Guest-facing technology deployment and regulatory compliance automation are restructuring capital allocation patterns across UAE full-service operations, with operators diverting spend from ambiance toward data infrastructure.
Kitchen automation hardware is miniaturizing. Compact robotic prep stations and automated beverage dispensers now fit retrofit configurations without structural renovation. Mid-range casual-dining chains in Dubai Mall and Yas Mall corridors are piloting these systems to compress labor hours per cover. The technology is miniaturizing equipment footprints, enabling automation in legacy kitchen layouts previously deemed incompatible with robotics.
MOHAP allergen labeling mandates are tightening disclosure requirements across all emirates. Operators must now display ingredient traceability data on digital menus and printed collateral. Premium hotel-anchored venues in Downtown Dubai face the steepest compliance burden, with kitchen brigades retraining on cross-contamination protocols and documentation workflows.
Business traveler procurement patterns are fragmenting across channel types. Corporate dining allowances now split between expensed table-service meals and reimbursable delivery orders, pressuring full-service venues to maintain dual-format presence. This bifurcation concentrates in Abu Dhabi's central business district, where weekday lunch covers increasingly originate from platform orders rather than walk-in traffic.
United Arab Emirates Full Service Restaurants Market Segmentation
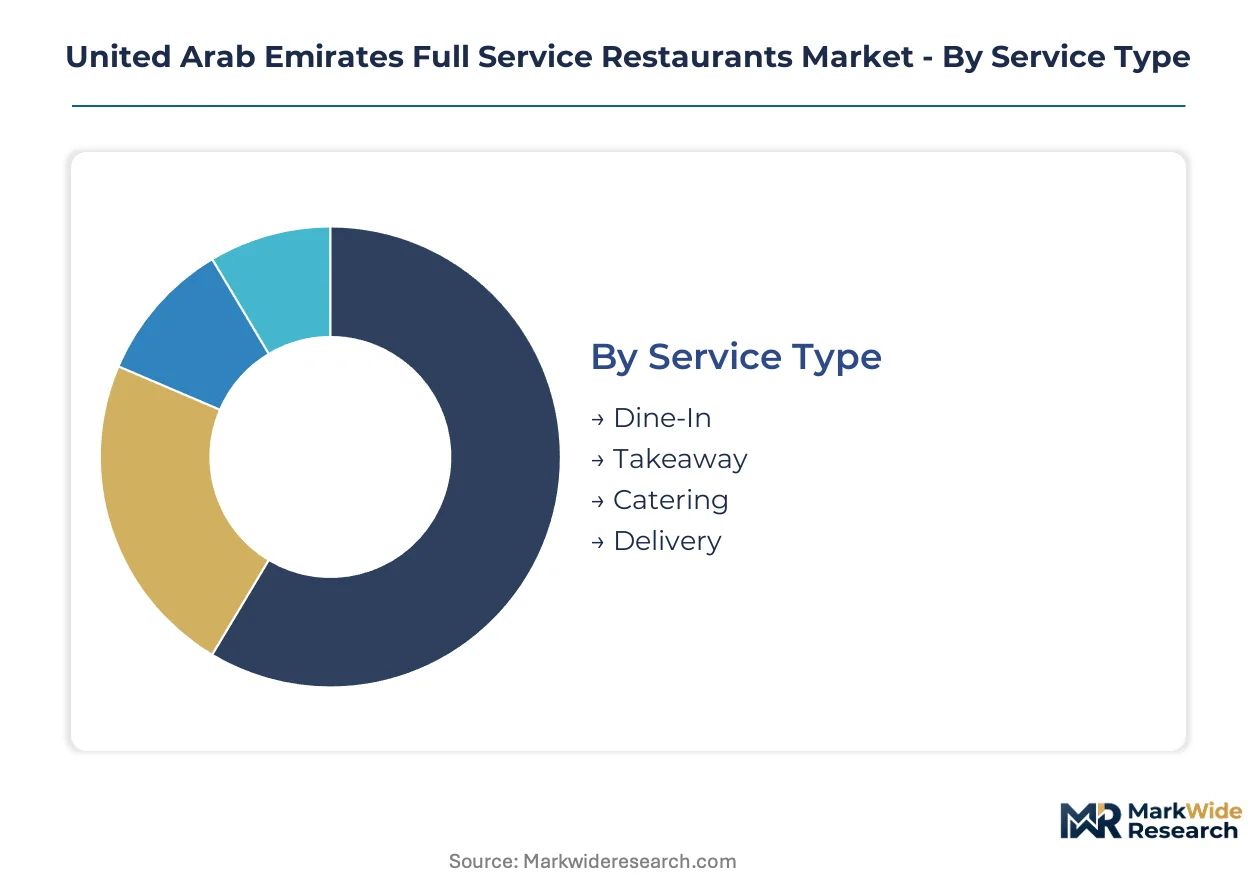
Full-service restaurant operators in the United Arab Emirates configure their operational models around distinct service modalities, price positioning, and cuisine specializations. Segmentation discipline determines real estate selection, labor deployment, and technology investment priorities across Dubai and Abu Dhabi corridors.
Service Type:
Cloud-kitchen proliferation and platform economics are intensifying substitution pressure against traditional dine-in formats, forcing table-service venues to defend their experiential value proposition.
- Dine-In:Full waiter service with extended dwell time remains the revenue anchor for premium concepts in Downtown Dubai and Saadiyat Island. Tourist expenditure and celebratory occasions sustain cover counts despite delivery platform encroachment.
- Takeaway:Counter-collection formats with minimal front-of-house staffing enable mid-range brands to capture price-sensitive weekday lunch demand from office clusters in Abu Dhabi's central business district.
- Catering:Corporate event and private function contracts deliver volume predictability for established operators with centralized commissary infrastructure. Wedding and hospitality sector procurement drives seasonal revenue spikes.
- Delivery:Platform-originated orders now constitute a parallel revenue stream requiring dedicated kitchen lines and packaging protocols. Ghost kitchen integration allows full-service brands to expand addressable market without flagship real estate burden.
Dine-In anchors the volume base while Delivery gains share at the steepest rate.
Price Tier:
Cost tier stratification determines capital intensity requirements and margin structure, with mid-range operators facing the tightest squeeze between input inflation and price-sensitive demand.
- Budget:Value-positioned concepts in suburban Sharjah and Ajman corridors compete primarily with limited-service alternatives. Labor cost minimization and menu simplification sustain unit economics.
- Mid-range:Casual-dining formats dominate transaction volume across Dubai Mall and Yas Mall food courts. Franchise-operated global banners leverage brand recognition to maintain traffic amid competitive density.
- Premium:Chef-driven independent restaurants and hotel-anchored venues command per-cover spending multiples through beverage program attachment and tasting menu structures. Business traveler expense accounts sustain weekday demand.
- Luxury:Ultra-high-end dining rooms in Burj Al Arab and Emirates Palace properties function as brand amplifiers with limited seat counts. Culinary tourism and special occasion spending justify substantial kitchen brigade investments.
Mid-range captures transaction volume leadership while Premium climbs the fastest in absolute revenue contribution.
Cuisine Type:
Application-based demand concentration varies sharply by visitor origin and resident demographic composition, with Asian formats benefiting from South Asian population density and emerging Southeast Asian culinary interest.
- Arabic:Traditional Emirati and Levantine concepts anchor tourist expectation sets and local family dining rituals. Heritage ingredient sourcing and live cooking theater differentiate authentic operators from commoditized mall formats.
- Asian:South Asian, East Asian, and Southeast Asian sub-specializations represent the steepest expansion trajectory. Indian, Chinese, and emerging Vietnamese concepts concentrate in Karama and Deira districts with strong diaspora patronage.
- Italian:Pasta and pizza formats maintain consistent demand across expatriate European and Latin American demographics. Wine program integration and regional ingredient storytelling sustain premium positioning.
- American:Steakhouse and burger concepts compete for share-of-stomach against quick-casual alternatives. Mall-based locations emphasize portion size and beverage pairing to justify table-service price premiums.
Arabic anchors the volume base while Asian gains share at the steepest rate.
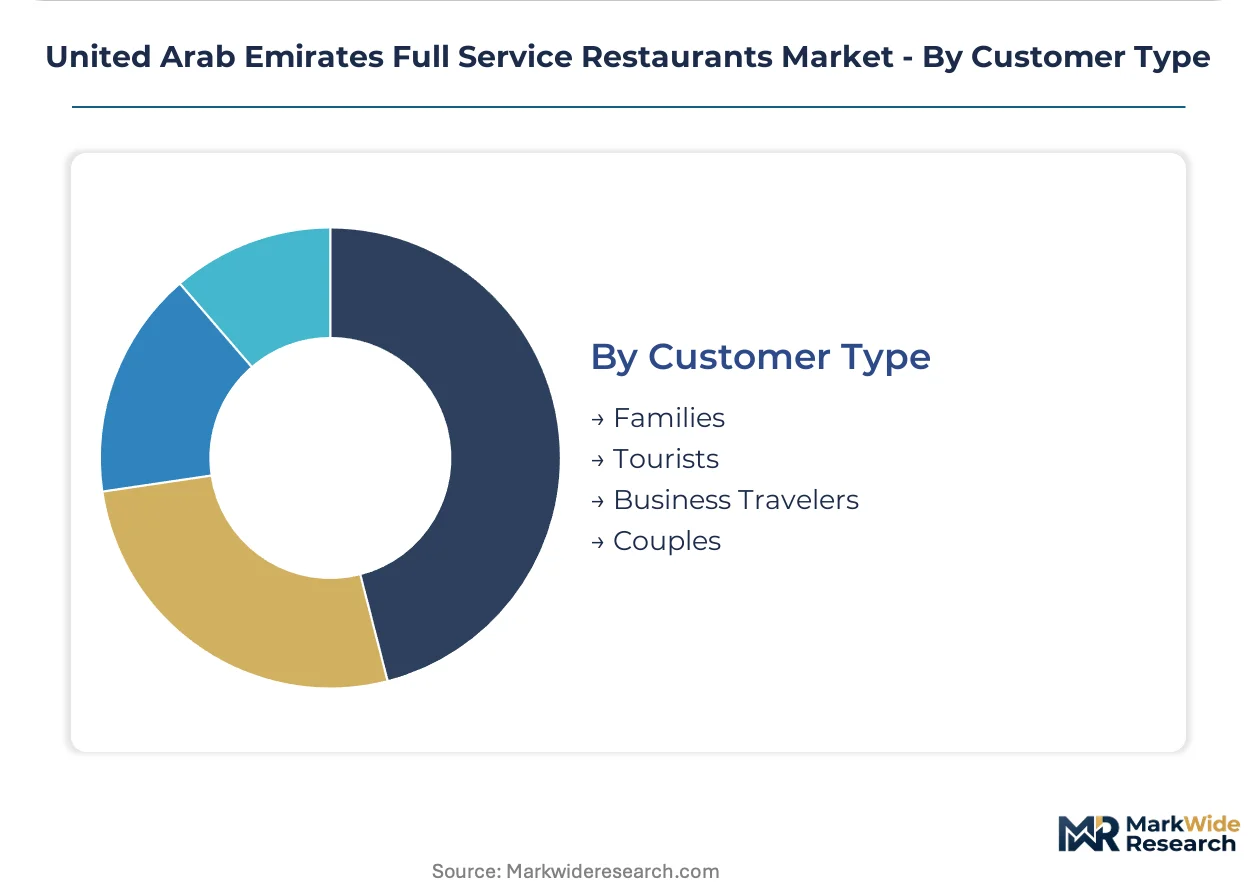
Customer Type:
Volume concentration by customer archetype determines daypart staffing patterns and marketing channel allocation, with business traveler procurement fragmentation creating operational complexity.
- Families:Weekend and holiday dining drives large-party table turnover in mall-adjacent and beachfront locations. Children's menu engineering and entertainment licensing sustain extended visit durations.
- Tourists:International visitor expenditure concentrates in Dubai's hospitality corridor with cuisine exploration and Instagram-optimized ambiance as primary selection criteria. Hotel concierge relationships drive referral traffic.
- Business Travelers:Corporate dining allowances now split between expensed table-service meals and reimbursable delivery orders. Weekday lunch covers in Abu Dhabi's central business district increasingly originate from platform orders.
- Couples:Date-night and special occasion positioning emphasizes intimacy design and beverage program sophistication. Prix fixe structures and wine pairings elevate per-cover economics.
Families anchor the volume base while Business Travelers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dubai's hospitality corridor while Abu Dhabi commands premium corporate dining rates, creating a two-speed revenue environment across the emirates.
Dubai
Tourism expenditure and business traveler procurement sustain premium table-service demand across Downtown Dubai and Dubai Marina. MOHAP food safety certification requirements enforce standardized kitchen protocols for all new outlet openings. The Dubai Mall and Yas Mall corridors host the densest concentration of mid-range franchise concepts competing for tourist and resident traffic.
Abu Dhabi
Corporate dining allowances and government hospitality procurement anchor weekday lunch demand in the central business district. Municipal tourism authority alcohol licensing regulations shape revenue model viability for hotel-anchored venues. Saadiyat Island and Al Maryah Island clusters concentrate luxury chef-driven restaurants serving diplomatic and energy-sector clientele.
Sharjah
Family dining rituals and value-positioned consumption drive traffic in suburban mall locations away from premium tourism corridors. MOHAP allergen labeling mandates apply uniformly across all emirates, raising compliance costs for independent operators. The Sharjah Corniche and Al Majaz waterfront districts host emerging casual-dining clusters serving resident expatriate communities.
Northern Emirates
Underserved suburban corridors in Ajman, Ras Al Khaimah, and Fujairah offer first-mover positioning ahead of infrastructure maturation. Emiratization labor quota constraints limit staffing flexibility equally across all emirates, compressing service ratios. Ras Al Khaimah's hospitality development zone attracts mid-range brand expansion seeking lower real estate costs than Dubai or Abu Dhabi.
United Arab Emirates Full Service Restaurants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UAE full-service restaurant landscape. The market exhibits tiered consolidation with multi-brand portfolio operators commanding mall penetration advantages while specialized single-concept venues compete on culinary differentiation. Three strategic archetypes dominate: captive supply chain integrators, franchise portfolio aggregators, and format-specific specialists. Competitive dynamics center on cloud-kitchen hybridization and sustainability disclosure alignment as primary expansion vectors.
Among portfolio-heavy operators, Americana Restaurants International PLC and M.H. Alshaya Co. WLL occupy positions representing scale-driven franchise control and mall-anchored distribution density. Alamar Foods Company exemplifies the format-specialist archetype, competing for share-of-stomach against traditional table-service venues through focused pizza and quick-casual positioning. These three entities represent distinct competitive vectors—supply chain integration, brand portfolio breadth, and category specialization—that structure rivalry across Dubai and Abu Dhabi corridors.
| Leading Market Players |
|---|
| Americana Restaurants International PLC |
| M.H. Alshaya Co. WLL |
| Apparel Group |
| Al Khaja Group of Companies |
| Alamar Foods Company |
| Majid Al Futtaim Lifestyle |
| Brinker International Inc. |
| The Olayan Group |
| LuLu Group International |
| Others |
Pricing and Supply Chain Analysis
MOHAP food safety certification requirements gate both supplier qualification and menu price positioning across UAE full-service restaurants, forcing operators to absorb compliance costs into premium tiers while budget concepts face margin compression from identical regulatory burdens. This dual-gating mechanism concentrates pricing power with hotel-anchored venues that can pass certification investments through beverage program markups and tasting menu structures.
Pricing Analysis
Configured-to-order pricing versus standard menu pricing creates a spread of three to five multiples across Dubai's hospitality corridor. Premium hotel-anchored venues command chef-driven customization premiums through beverage pairings and ingredient provenance storytelling, while mid-range mall concepts compete on standardized portion efficiency. Price differentiation rests on MOHAP certification tier and brand heritage, with luxury positioning least sensitive to cost compression. Input volatility in imported proteins is intensifying margin pressure at the budget tier, where price-sensitive Sharjah families limit pass-through elasticity.
Supply Chain Analysis
Jebel Ali port congestion and Red Sea container routing disruptions have elevated inbound logistics costs for Australian lamb, European dairy, and Japanese seafood arriving through Dubai's re-export hub. Protein sourcing concentrates in Australia, New Zealand, and Brazil, while specialty ingredients draw from Italy, Japan, and India. Single-source vulnerability runs through UAE's near-total dependence on imported foodstuffs, with currency fluctuation amplifying landed cost unpredictability. Distribution runs through centralized commissary networks serving multi-outlet portfolios, though ghost kitchen integration is fragmenting last-mile delivery economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE full-service restaurants are entering a cyclical recovery phase as tourism expenditure rebounds through Dubai's hospitality corridor and business traveler procurement normalizes across Abu Dhabi's central business district.
For Market Incumbents: Shield flagship positioning by deepening captive supply chain control over heritage ingredient sourcing and accelerating MOHAP compliance automation to compress audit timelines. Defend against cloud-kitchen substitution by amplifying experiential theater elements—live cooking stations and sommelier interaction—that resist platform commoditization. For New Entrants and Emerging Players: Anchor in Sharjah and Northern Emirates suburban corridors where real estate costs run at forty percent discounts to Dubai Mall equivalents and Emiratization quotas apply with identical rigor but less competitive density. Target mid-range Asian cuisine formats in Karama and Deira districts, where South Asian demographic density supports volume basins without premium positioning requirements. Pursue ghost kitchen partnerships as primary go-to-market channel to test demand before flagship capital deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-kitchen hybrid formats, creating acquisition windows for operators with proven unit economics and scalable technology stacks. Long-term viability favors portfolio-heavy entities with centralized commissary infrastructure and multi-brand mall penetration. Monitor MOHAP audit backlog clearance rates as inflection indicator for new outlet opening velocity and concept refresh cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Hybridization | Expands addressable market without proportional flagship real estate burden across Dubai corridors. |
| MOHAP Compliance Automation | Compresses certification timelines and reduces kitchen brigade retraining costs for allergen protocols. |
| Heritage Ingredient Sourcing | Differentiates authentic Arabic concepts from commoditized mall formats through provenance storytelling. |
| AI-Driven Demand Forecasting | Converges reservation platforms with inventory systems to enable dynamic pricing and waste reduction. |
| Sustainability Disclosure Alignment | Builds license-to-operate advantage and corporate dining contract eligibility ahead of mandates. |
Research Methodology
The analysis maps dine-in, takeaway, catering, and delivery service modalities, each validated through executive interviews with multi-brand portfolio operators, franchise development directors, hotel F&B procurement managers, and cloud kitchen facility operators. Secondary validation draws from Dubai Department of Economic Development licensing records, Abu Dhabi Department of Culture and Tourism hospitality sector reports, MOHAP food safety compliance databases, and customs import data for protein and specialty ingredient categories. Bottom-up outlet counting triangulates against top-down tourism expenditure modeling.
Consistency checks validate volume and value outputs against external benchmarks including emirate-level hospitality sector revenue disclosures and platform aggregator transaction estimates. The analytical framework segments by service type, price tier, cuisine specialization, and customer archetype across the projection horizon. CAGRs derive from regression analysis of historical outlet expansion rates, tourist arrival patterns, and business traveler procurement indices, with labor quota constraints and alcohol licensing fragmentation incorporated as supply-side dampeners.
Underlying assumptions cover tourism corridor demand stability, MOHAP regulatory continuity, and currency peg maintenance, with deviation risk concentrated in Emiratization policy tightening and Red Sea shipping route disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Clear Ice Maker Market
Food Service
Sandwich Toasters Market
Food Service
Global Combi Ovens Market
Food Service
Charbroiler Market
Food Service
Bar Refrigeration Market
Food Service
Global Online Food Ordering Market
Food Service
South Korea Foodservice Market
Food Service
Food and Grocery Retail Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Halal Food and Beverages Market
Food Service
United States Food Truck Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Germany Foodservice Market
Food Service
Europe Food Away from Home Market
Food Service
Rotisseries Market
Food Service
Food Service Gloves Market