
 Hot Pot Market | 2026-2036
Hot Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Pot Market Insights
China's dual carbon goals are shifting procurement priorities across the hot pot supply chain, compelling broth manufacturers to reformulate production processes and source lower-emission ingredients. Haidilao International Holdings Limited leverages its captive logistics network to sustain quality consistency across hundreds of locations. Sichuan Xiaolongkan Holding Group Co., Ltd. anchors its position through chili-oil specialization and regional brand loyalty. Chongqing Dezhuang Industrial (Group) Co., Ltd. competes on fermented bean paste heritage and manufacturing scale.
Hot pot denotes a communal cooking method where diners simmer raw ingredients in a shared, seasoned broth at the table, typically maintained at 85–100°C via induction or gas-heated vessels; the broth base—often comprising animal fats, fermented pastes, dried chilies, and Sichuan peppercorns—determines flavor chemistry and repeat purchase rates. Broth and sauce categories dominate value capture due to formulation complexity and brand differentiation, while accessories and dipping segments attract premium pricing through artisan positioning. Distribution through restaurants commands the highest margin pools, whereas supermarkets and online retail channels expand trial among families and students seeking at-home replication.
China's SAMR enforces food additive and labeling standards that directly shape broth formulation decisions, while the country's GB standards mandate hygiene protocols for communal dining equipment. The EU's F-Gas Regulation and REACH framework constrain imported seasoning blends and equipment materials entering European markets. Stakeholders must monitor regulatory divergence between China's evolving national standards and import-market requirements to preserve cross-border growth pathways.
Market Dynamics
China's dual carbon goals are compressing margins across the hot pot supply chain, forcing broth manufacturers to abandon coal-fired reduction methods and adopt electric induction systems while reformulating base stocks to lower emission profiles.
Growth Catalysts
- Clean Energy Mandates:China's dual carbon goals compel suppliers to retrofit production lines with renewable-powered equipment, opening procurement contracts for low-emission ingredient sourcing.
- Younger Demographics:Quick-service restaurant chains across Southeast Asia are expanding hot pot menus to capture diners aged 18-34 seeking communal dining experiences.
- GB Standards Enforcement:SAMR-mandated hygiene protocols for communal dining equipment are accelerating replacement cycles for induction vessels and temperature-control systems.
Market Restraints
- Animal Fat Volatility:Beef tallow and pork bone input costs fluctuate with livestock disease outbreaks and feed grain prices, compressing broth manufacturer margins.
- Sichuan Peppercorn Concentration:Premium Hanyuan peppercorn supply concentrates in narrow growing regions of Sichuan province, creating weather-dependent shortage risks.
- EU Import Friction:REACH framework constraints on fermented paste additives and F-Gas Regulation limits on equipment refrigerants block entry for Chinese seasoning blends.
Strategic Opportunities
- Vietnam Expansion:Underpenetrated central Vietnamese cities present whitespace for mid-priced hot pot concepts targeting factory workers and university students.
- Induction-Convection Convergence:Hybrid heating systems combining precision induction with circulating convection are enabling tableside broth consistency previously unattainable with gas.
- Community Group Buying:WeChat-based collective purchasing channels are unlocking at-home trial among price-sensitive families previously excluded from restaurant distribution.
Industry Challenges
- Broth Chemist Scarcity:Formulation expertise combining traditional fermentation science with modern food safety compliance remains concentrated among aging specialists in Chongqing and Chengdu.
- Cross-Border Certification Lag:Chinese manufacturers face 14-18 month timelines to secure EFSA novel food approvals for probiotic-enriched broth bases targeting European diaspora markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Pot Market |
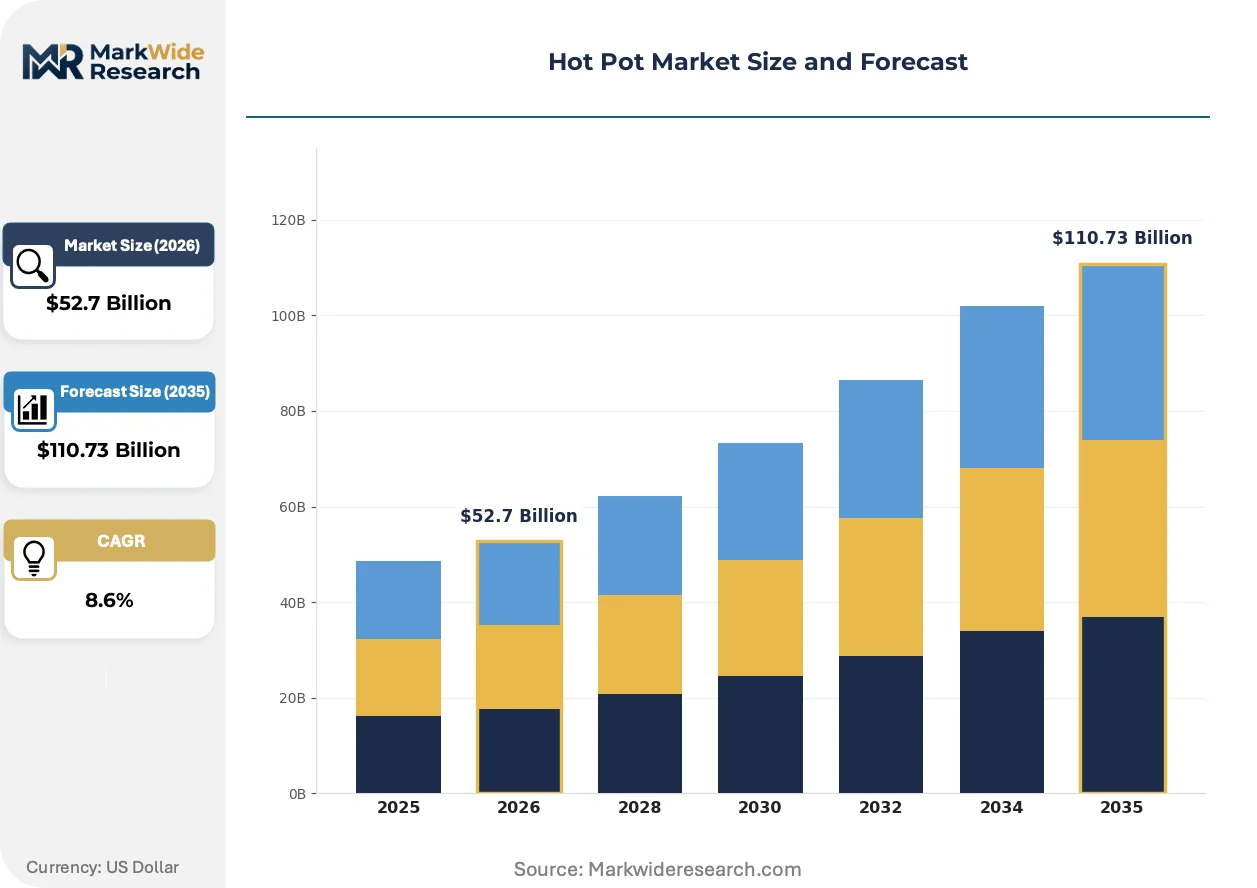
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broth, Sauce, Dipping, Accessories Ingredient Type: Meat, Seafood, Vegetables, Noodles Distribution Channel: Supermarkets, Online Retail, Restaurants, Food Festivals End User: Families, Food Enthusiasts, Tourists, Students |
| Companies Covered | Chongqing Dezhuang Industrial (Group) Co., Ltd., Sichuan Zhishan Brand Management Co., Ltd., Haidilao International Holdings Limited, Chengdu Dalongyi Catering Management Co., Ltd., Beijing Donglaishun Group Co., Ltd., Sichuan Xiaolongkan Holding Group Co., Ltd., Xiabuxiabu Catering Management Co., Ltd., Sichuan Three Frogs Food and Beverage Management Co., Ltd., Inner Mongolia Little Tail Sheep Catering Chain Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Pot Market Trends and Innovations
Active reformulation of broth chemistry and heating infrastructure is compressing traditional preparation timelines while expanding addressable occasions beyond conventional restaurant settings.
Precision fermentation technology is converging with traditional bean paste aging protocols to produce standardized umami compounds without the 180-day outdoor fermentation cycles. Premium restaurant groups in Shanghai and Shenzhen are piloting these bio-reactor outputs to reduce kitchen footprint and odor complaints. The technology is converging with automated broth dispensing systems to enable consistent flavor profiles across franchise locations.
China's GB 2760 food additive standard revisions are restricting synthetic flavor enhancer concentrations in commercial broth bases, compelling manufacturers to intensify natural extraction methods. SAMR enforcement actions against mislabeled "bone broth" products are accelerating third-party testing adoption. Broth concentrate exporters targeting European retail channels are most affected, with reformulation costs absorbed or passed through to supermarket buyers.
Subscription-based at-home hot pot kits are displacing single-purchase supermarket formats among urban Chinese families with children. Meituan and Ele.me delivery platforms are bundling timed ingredient drops with reusable induction equipment to capture weekly meal-planning budgets. Tier-one city apartment dwellers represent the densest adoption geography, with penetration thinning rapidly beyond Beijing, Shanghai, and Guangzhou subway catchments.
Hot Pot Market Segmentation
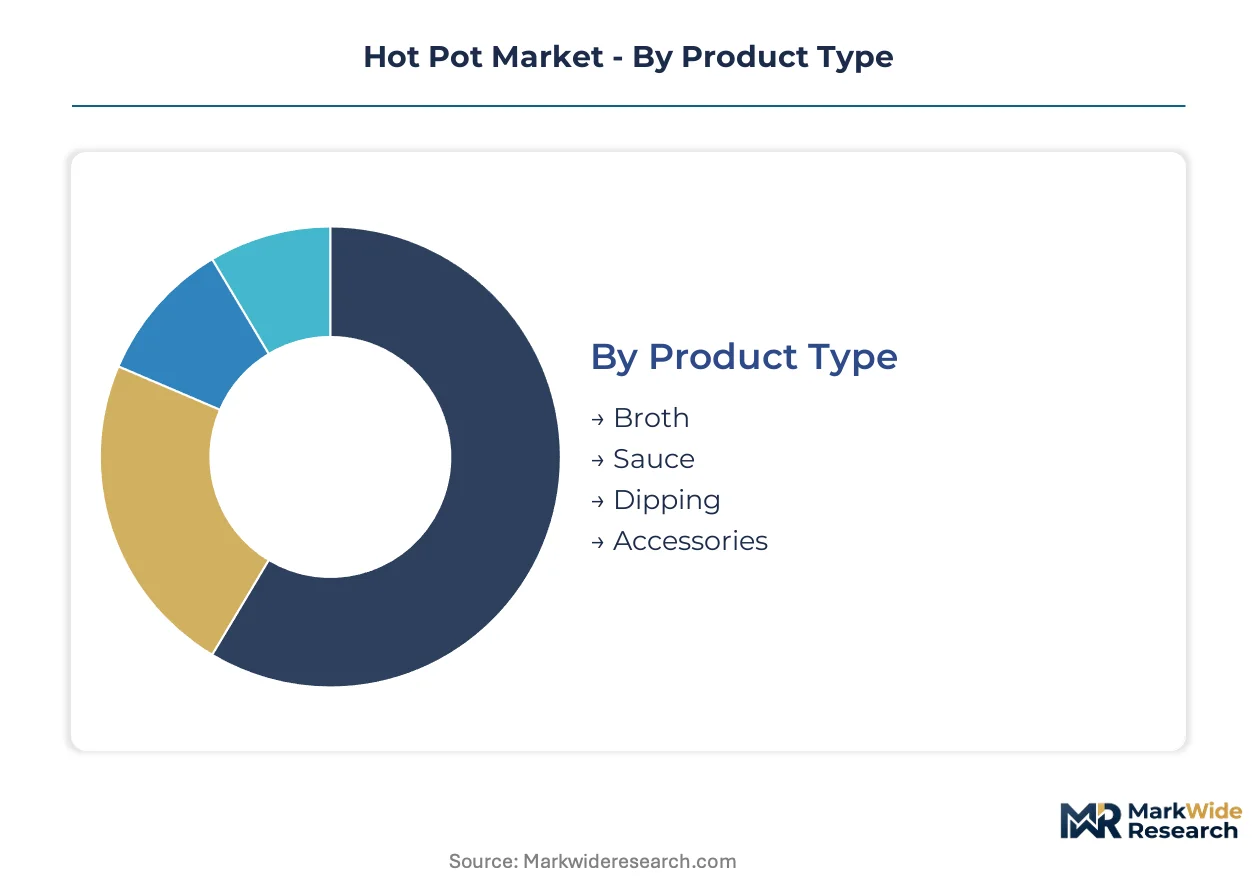
Hot pot market segmentation tracks how formulation complexity, procurement behavior, and occasion-based usage fragment revenue pools across distinct product and channel configurations. Understanding these splits reveals where margin concentration diverges from volume concentration.
Product Type:
Product differentiation centers on formulation chemistry and preparation labor intensity, with complexity tiers separating commodity-adjacent inputs from proprietary flavor systems.
- Broth:Base stocks combining animal fats, fermented pastes, dried chilies, and Sichuan peppercorns require 180-day outdoor fermentation cycles or precision fermentation substitutes. Premium dining concepts in China's tier-one cities capture the densest demand, driven by repeat purchase sensitivity to flavor consistency.
- Sauce:Chili-oil specialization and regional bean paste heritage create defendable brand positions through proprietary aging protocols. Sichuan Xiaolongkan Holding Group anchors loyalty via heritage formulations that resist private-label substitution.
- Dipping:Artisan positioning commands premium pricing through small-batch production and limited regional ingredient sourcing.
- Accessories:Reusable induction equipment and temperature-control systems accelerate replacement cycles under SAMR-mandated hygiene protocols.
Mature deployment sits with Broth. Newer deployment is concentrated in Accessories.
Ingredient Type:
Input cost volatility and supply geography shape procurement risk profiles across protein and carbohydrate categories.
- Meat:Beef tallow and pork bone costs fluctuate with livestock disease outbreaks and feed grain prices, compressing manufacturer margins. Quick-service chains across Southeast Asia source frozen sliced proteins through captive logistics networks to sustain quality consistency.
- Seafood:Cold-chain requirements and import documentation complexity favor coastal procurement clusters with established customs clearance relationships.
- Vegetables:Weather-dependent shortage risks concentrate in narrow growing regions, particularly premium Hanyuan peppercorn supply.
- Noodles:Wheat and starch-based products standardize most easily for at-home kit formats targeting urban families.
Volume leadership rests with Meat. Margin expansion concentrates in Seafood.
Distribution Channel:
Channel economics separate experience-driven occasions from convenience-driven replication, with margin pools inversely related to customer acquisition friction.
- Restaurants:Communal dining at 85–100°C via induction or gas-heated vessels commands the highest margin pools through service labor capture and beverage attachment.
- Supermarkets:Single-purchase formats face displacement from subscription-based kits among urban Chinese families with children.
- Online Retail:Meituan and Ele.me bundle timed ingredient drops with reusable equipment to capture weekly meal-planning budgets in tier-one city apartment catchments.
- Food Festivals:Temporary activation sites build trial among tourists and students with lower conversion to repeat purchase.
Margin concentration favors Restaurants. Volume expansion is climbing fastest in Online Retail.
End User:
User segmentation maps occasion frequency against price sensitivity, with household composition determining kit format preference.
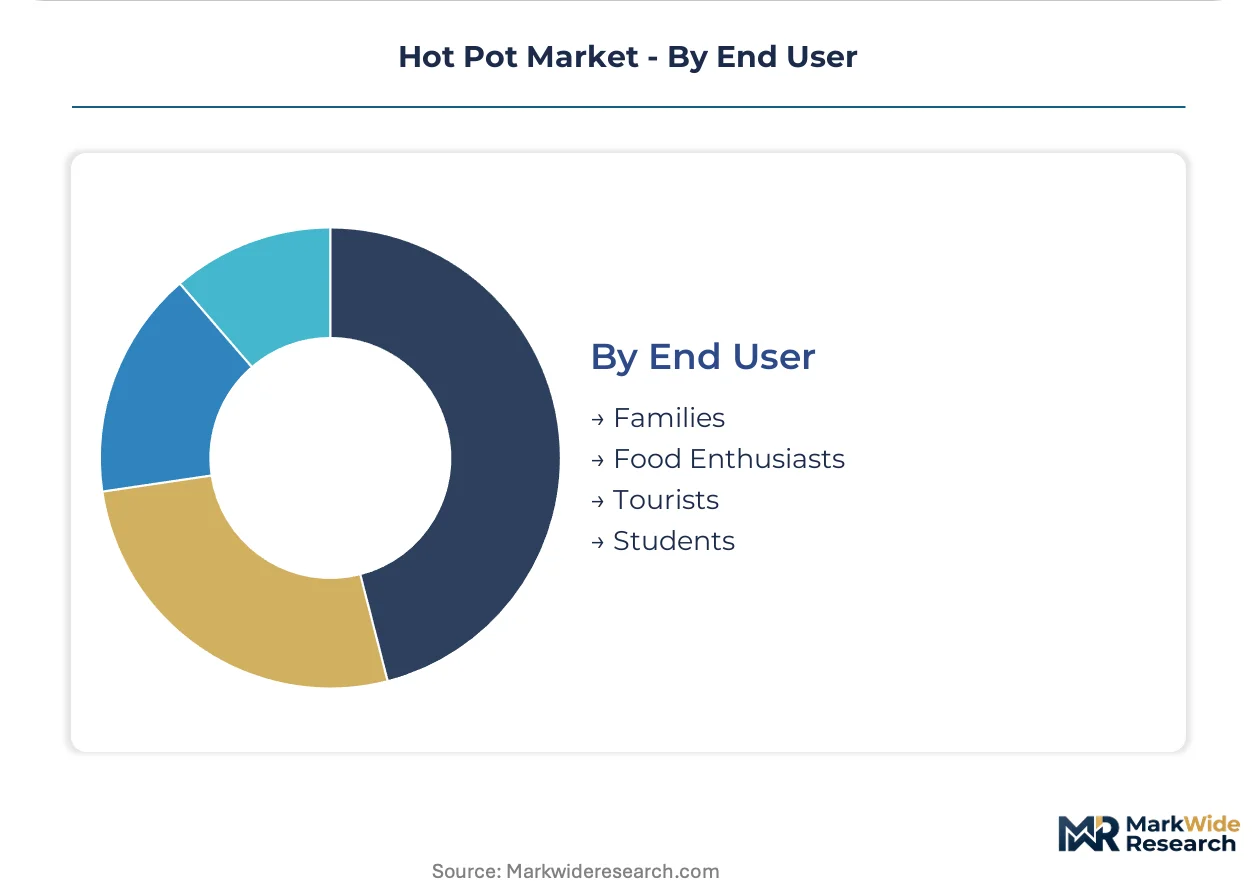
- Families:Subscription-based at-home kits displace supermarket formats among urban Chinese households with children, with penetration thinning rapidly beyond Beijing, Shanghai, and Guangzhou subway catchments.
- Food Enthusiasts:Premium broth chemistry and artisan dipping sauces attract repeat experimentation with regional style variation.
- Tourists:Destination dining in Chongqing and Chengdu generates one-time trial with limited at-home replication.
- Students:WeChat-based community group buying unlocks price-sensitive trial previously excluded from restaurant distribution.
Established demand centers on Families. Steepest expansion trajectory sits with Students.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chongqing anchors global hot pot production gravity, with the Sichuan-Chongqing corridor housing the densest concentration of heritage broth manufacturers and fermentation facilities. Demand radiates outward through tier-one Chinese cities and into Southeast Asian expansion corridors.
China
Beijing, Shanghai, and Guangzhou subway catchments concentrate subscription kit adoption among urban families. SAMR enforces GB 2760 additive limits that compel natural extraction method investments. Chengdu's precision fermentation pilots are compressing traditional 180-day aging cycles into bioreactor outputs.
Vietnam
Central Vietnamese cities present whitespace for mid-priced concepts targeting factory workers and university students. The country's food safety authority mandates hygiene certifications for imported seasoning blends. Ho Chi Minh City's quick-service chains are expanding hot pot menus to capture 18-34 demographic trial.
Thailand
Bangkok's restaurant density supports premium dining concept proliferation among experience-seeking tourists. Thai FDA regulations govern fermented paste import documentation and cold-chain compliance. Chiang Mai's food festivals generate seasonal demand spikes for communal dining equipment.
South Korea
Seoul Capital Area apartment dwellers drive at-home kit penetration through Meituan-equivalent delivery platforms. MFDS standards restrict synthetic flavor enhancer concentrations in commercial broth bases. Busan-Ulsan coastal clusters specialize in seafood-forward hot pot variations for export-oriented production.
United States
California and New York Metro areas concentrate diaspora demand for authentic Sichuan and Chongqing-style concepts. FDA labeling requirements and state-level health codes shape equipment import specifications. Los Angeles's San Gabriel Valley hosts the densest cluster of regional chain expansions targeting Chinese-American households.
Hot Pot Market Competitive Landscape
Premium-margin players sit above commodity-margin players across broth formulation complexity and captive logistics infrastructure. The market structures around three tiers: heritage fermentation houses with decades of bean paste aging protocols, quick-service chains scaling through standardized induction systems, and subscription kit assemblers bundling timed ingredient drops. Consolidation pressure concentrates among mid-scale regional operators lacking backward integration into ingredient sourcing. Dominant competitive moves include vertical integration into peppercorn procurement and strategic partnerships with precision fermentation technology providers.
Within the heritage fermentation tier, Chongqing Dezhuang Industrial (Group) Co., Ltd. and Sichuan Xiaolongkan Holding Group Co., Ltd. exemplify regional brand loyalty anchored through chili-oil specialization and fermented paste heritage. Haidilao International Holdings Limited occupies a position representing premium-service quick-service scale, with its captive logistics network sustaining quality consistency across hundreds of locations. These three entities collectively illustrate the competitive spectrum from artisan positioning to operational scale.
| Leading Market Players |
|---|
| Chongqing Dezhuang Industrial (Group) Co., Ltd. |
| Sichuan Zhishan Brand Management Co., Ltd. |
| Haidilao International Holdings Limited |
| Chengdu Dalongyi Catering Management Co., Ltd. |
| Beijing Donglaishun Group Co., Ltd. |
| Sichuan Xiaolongkan Holding Group Co., Ltd. |
| Xiabuxiabu Catering Management Co., Ltd. |
| Sichuan Three Frogs Food and Beverage Management Co., Ltd. |
| Inner Mongolia Little Tail Sheep Catering Chain Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals are compelling broth manufacturers to abandon coal-fired reduction methods, forcing capital reallocation toward electric induction systems and reformulated base stocks that compress margins while elevating compliant product premiums. This procurement pivot concentrates pricing power among suppliers with captive renewable energy contracts and precision fermentation capabilities.
Pricing Analysis
Flavor consistency at the table anchors value-based pricing, with repeat purchase sensitivity to broth chemistry justifying 40-60% premiums for heritage fermentation houses over commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels separates artisan-positioned dipping sauces from private-label supermarket formats. Cost compression in mid-tier broth concentrates is intensifying because SAMR-mandated natural extraction methods displace synthetic enhancers. Students and price-sensitive families exhibit highest price sensitivity, while premium dining concepts in Shanghai and Shenzhen show least elasticity to formulation-driven increases.
Supply Chain Analysis
Dual-sourcing requirements for Sichuan peppercorn now dominate procurement protocols, with Haidilao and Xiaolongkan mandating qualification across Hanyuan county and emerging Yunnan cultivation zones to mitigate weather-dependent shortage risks. Supply concentrates in China, Vietnam, and Thailand for fermented paste inputs, with beef tallow and pork bone sourcing anchored in Brazilian and Australian livestock markets. Logistics chokepoints at Chongqing-Chengdu highway corridors create seasonal bottlenecks during peak fermentation harvests. Distribution runs through captive logistics networks for restaurant chains, while online retail channels aggregate fragmented supermarket and community group buying demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side fermentation capacity constraints in the Sichuan-Chongqing corridor prop pricing premiums, with 180-day outdoor aging cycles limiting throughput expansion regardless of capital deployment.
For Market Incumbents: To counter precision fermentation technology disruption from Shanghai and Shenzhen biotech pilots, accelerate backward integration into Hanyuan peppercorn cultivation through long-term grower contracts and invest in automated broth dispensing systems to standardize franchise outputs. Certification investment in EU EFSA novel food pathways preserves European diaspora market access against REACH-compliant entrants. For New Entrants and Emerging Players: Begin with central Vietnamese cities where factory worker and university student demand remains underpenetrated by established Sichuan brands, using WeChat-based community group buying to unlock price-sensitive trial before physical restaurant buildout. Subscription-based at-home kits targeting tier-one city apartment dwellers offer the most penetrable format given Meituan and Ele.me infrastructure maturity. For Investors and Strategic Acquirers: The window for entry favors heritage fermentation houses with decades of bean paste aging protocols and established regional brand loyalty. Long-term viability hinges on 5-10 year transition timelines toward precision fermentation compatibility. The signal to watch is SAMR enforcement intensity against mislabeled "bone broth" products, which will accelerate third-party testing adoption and consolidate formulation expertise among capitalized players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peppercorn Cultivation | Long-term grower contracts in Hanyuan and Yunnan regions mitigate weather-dependent shortage risks for premium Sichuan peppercorn supply. |
| Precision Fermentation Technology Adoption | Bioreactor-based umami production reduces 180-day outdoor fermentation cycles and kitchen footprint in dense urban locations. |
| EFSA Novel Food Certification Investment | 14-18 month approval timelines for probiotic-enriched broth bases unlock European diaspora market access against REACH constraints. |
| Automated Broth Dispensing Systems | Standardized flavor profiles across franchise locations reduce reliance on aging broth chemists concentrated in Chongqing and Chengdu. |
| WeChat Community Group Buying Activation | Collective purchasing channels capture price-sensitive families and students previously excluded from restaurant distribution economics. |
Research Methodology
Trade databases, SAMR regulatory filings, and customs export records formed the secondary backbone, supplemented by primary interviews with broth formulation chemists, quick-service chain procurement directors, and precision fermentation technology providers. Bottom-up and top-down triangulation validated volume estimates across product and channel segments. Stakeholder input captured substitution dynamics between traditional outdoor fermentation and bioreactor-based production methods.
Bottom-up modeling tracked ingredient-level throughput from Sichuan-Chongqing fermentation facilities through downstream channel configurations, while top-down analysis cross-referenced consumer expenditure patterns in tier-one Chinese cities and Southeast Asian expansion corridors. Segmentation dimensions included broth chemistry complexity, distribution channel economics, and end-user occasion frequency. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and technology adoption curves in precision fermentation.
Underlying measurement precision varies by segment; subscription kit penetration in Beijing, Shanghai, and Guangzhou subway catchments carries tighter precision than central Vietnamese whitespace estimates. Forecasts reflect assumptions regarding SAMR enforcement continuity and dual carbon goal implementation timelines. Deviation in Hanyuan peppercorn harvest yields or EU EFSA approval acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Guacamole Market
Specialty Foods
Brahmi Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Cultures Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Grain-Free Pet Food Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Global Truffle Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Military Forces Ready to Eat Meals Market