
 Global Seismic Survey Market | 2026-2036
Global Seismic Survey Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seismic Survey Market Outlook
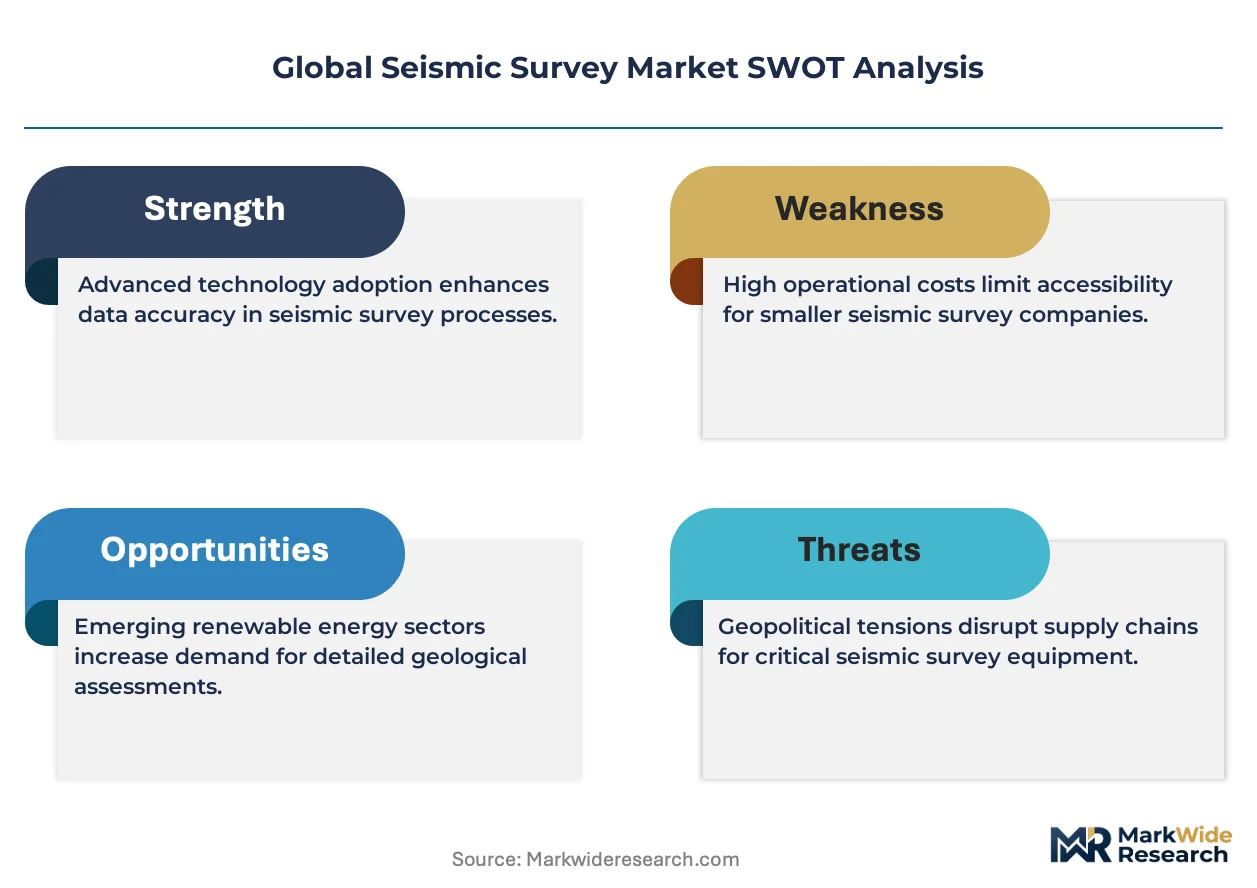
Fiber-optic sensing cable is expanding its share in marine seismic arrays, displacing legacy electrical streamer systems that suffer from higher noise floors and maintenance burdens. Schlumberger leverages its integrated technology portfolio to bundle seabed nodal systems with processing software, capturing full workflow value. CGG anchors its position through proprietary high-resolution imaging algorithms that differentiate its data processing output. PGS ASA competes on vessel scale, operating one of the largest specialized seismic fleets deployed across the Atlantic margin.
Seismic survey denotes the geophysical method of mapping subsurface structures by inducing controlled energy waves and recording reflected or refracted signals via hydrophone or geophone arrays, typically resolving formations to depths exceeding six kilometers beneath the seabed or land surface. The technique enables hydrocarbon prospect identification, geothermal reservoir characterization, and carbon storage site assessment. Three-dimensional seismic acquisition dominates contract value across the product type dimension, while 4D time-lapse surveys represent the fastest-growing category as producers prioritize reservoir optimization over greenfield discovery. Data acquisition services command the largest share of service type revenue, though processing and interpretation margins expand as artificial intelligence-driven velocity modeling reduces turnaround times.
The US Bureau of Ocean Energy Management shapes Atlantic and Gulf of Mexico lease schedules, directly determining multi-client seismic investment cycles. Norway's Petroleum Safety Authority and Brazil's National Petroleum Agency enforce seabed monitoring standards that mandate 4D surveys for certain field developments, tightening compliance scope. The EU Marine Strategy Framework Directive adds environmental assessment layers to North Sea permitting. Stakeholders must weigh exposure to offshore licensing volatility against the structural pull of energy transition applications including carbon capture site characterization.
Market Dynamics
Deepwater exploration economics now hinge on seismic data density rather than acreage coverage, forcing contractors to deploy ocean-bottom node arrays that multiply receiver counts tenfold over conventional towed streamers.
Growth Catalysts
- Pre-salt licensing rounds:Brazil's National Petroleum Agency maintains aggressive concession schedules in the Santos and Campos basins, sustaining multi-year survey commitments from international operators.
- EU Green Deal carbon storage mandates:The EU Marine Strategy Framework Directive requires subsurface characterization for offshore CO2 injection sites, opening new demand for high-resolution 3D seismic in the North Sea.
- Fiber-optic sensing maturation:Distributed acoustic sensing cables now achieve signal fidelity matching electrical streamers while eliminating crossline noise and deck maintenance.
Market Restraints
- Specialized vessel scarcity:Only twelve purpose-built seismic vessels worldwide can deploy ocean-bottom node systems, creating queue bottlenecks for 4D reservoir monitoring contracts.
- Capital intensity of nodal hardware:A single seabed node array for deepwater Brazil requires capital deployment exceeding the annual equipment budgets of most independent seismic contractors.
- Permitting timeline extension:The US Bureau of Ocean Energy Management has lengthened environmental review periods for Atlantic seismic programs, compressing viable acquisition windows.
Strategic Opportunities
- Geothermal reservoir imaging:Iceland's national energy agency and Kenya's geothermal development company now commission onshore 3D seismic for resource delineation, replicating oilfield workflows.
- CCS site certification demand:Norway's Petroleum Safety Authority mandates baseline seismic surveys for carbon storage license applications, creating recurring data acquisition cycles.
- AI velocity model convergence:Machine learning algorithms trained on legacy seismic libraries now reduce processing turnaround from months to weeks, enabling subscription-based interpretation services.
Industry Challenges
- Geophysicist talent pipeline:University programs in applied geophysics have contracted since 2014, leaving contractors to compete for a shrinking pool of specialists capable of nodal array design.
- Legacy data integration:Operators seeking 4D time-lapse comparison must reconcile 1990s towed-streamer surveys with modern ocean-bottom node geometry, introducing uncertainty quantification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seismic Survey Market |
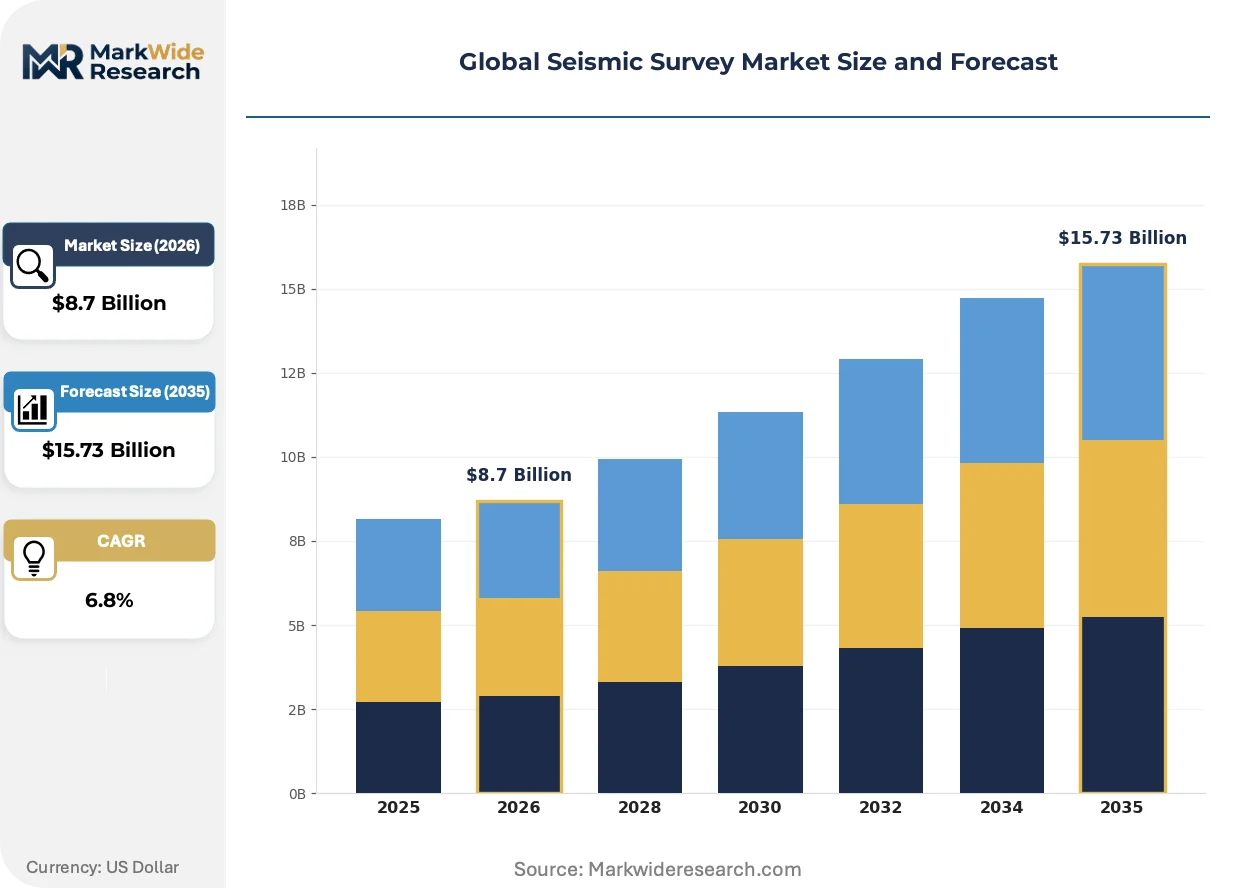
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Seismic, 3D Seismic, 4D Seismic, Microseismic Technology: Vibration, Refraction, Reflection, Acoustic End User: Oil & Gas, Mining, Construction, Environmental Service Type: Consulting, Data Acquisition, Processing, Interpretation |
| Companies Covered | Schlumberger, CGG, PGS ASA, TGS, Fugro, BGP Inc., Halliburton Company, SAExploration Holdings, Shearwater GeoServices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seismic Survey Market Strategic Shifts
Seismic acquisition is fragmenting into two distinct technology tracks: ultra-dense nodal arrays for reservoir optimization versus lightweight, rapidly deployable systems for exploration reconnaissance.
Distributed acoustic sensing using standard telecom fiber is rewriting marine survey economics by converting existing subsea cables into permanent seismic arrays. Offshore wind developers in the North Sea now install sensing-enabled export cables during construction, capturing passive seismic data continuously rather than commissioning discrete vessel surveys. This permanence is compressing the addressable market for conventional time-lapse vessel contracts in mature basins.
Norway's Petroleum Safety Authority recently tightened 4D monitoring requirements for subsea field developments, mandating repeat surveys at maximum five-year intervals for fields with active water injection. This regulatory compression is accelerating contract velocity for nodal operators with North Sea presence. Operators are responding by pre-positioning equipment inventories in Bergen and Stavanger to shorten mobilization timelines.
Buyers of seismic data are unbundling processing from acquisition, contracting directly with specialized interpretation shops rather than accepting bundled packages from vessel operators. This disintermediation is most pronounced among US Gulf of Mexico independents, who now license raw shot records and apply proprietary velocity models in-house. The shift is fragmenting vendor relationships and compressing margins for integrated service providers.
Global Seismic Survey Market Segmentation
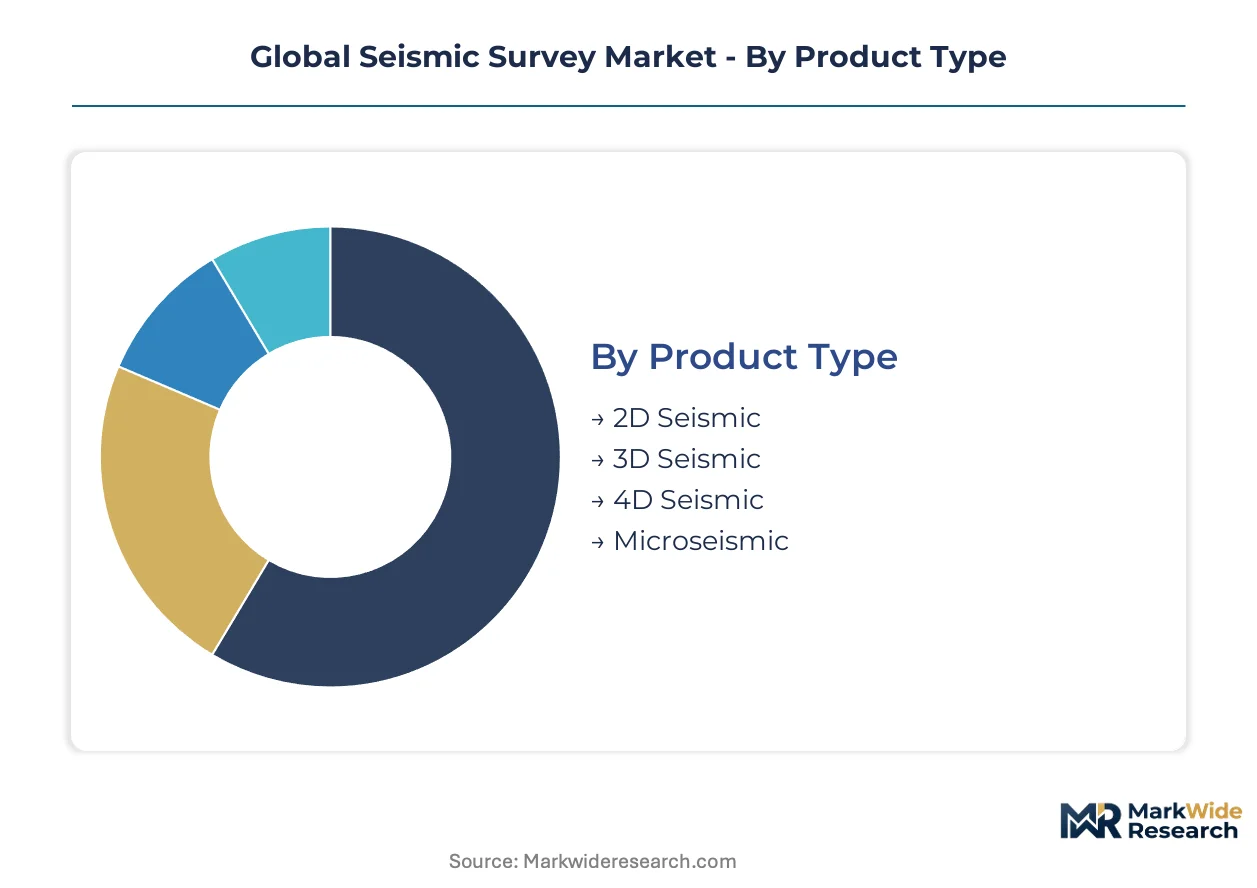
Technology choices in seismic surveying determine data resolution, acquisition speed, and total survey economics. Operators match segment specifications to reservoir complexity, regulatory requirements, and capital deployment timelines across exploration and production workflows.
Product Type:
Upgrade cycles from legacy 2D surveys to dense 3D and 4D acquisition reshape capital allocation patterns among exploration departments and production engineers.
- 2D Seismic:Linear receiver arrays capture cross-sectional subsurface profiles for initial basin reconnaissance. Frontier exploration in underexplored basins across West Africa and Southeast Asia sustains contract flow where full 3D grids remain economically unjustified.
- 3D Seismic:Dense source-receiver grids generate volumetric earth models resolving fault geometries and trap definitions. Gulf of Mexico lease rounds and Brazil's pre-salt licensing sustain the largest contract volumes for high-density marine acquisition.
- 4D Seismic:Time-lapse repeat surveys track fluid movement and pressure depletion across producing reservoirs. Norway's Petroleum Safety Authority mandates five-year repeat intervals for water-injection fields, tightening compliance scope for North Sea operators.
- Microseismic:Passive monitoring arrays detect induced seismicity from hydraulic fracturing or geothermal stimulation. Permian Basin operators deploy surface and downhole networks to optimize completion designs and mitigate regulatory scrutiny.
3D seismic sits at the top of the volume ranking, with 4D seismic climbing the fastest.
Technology:
Cost tier differentiation separates established reflection methods from emerging distributed acoustic sensing platforms that eliminate vessel dependency.
- Vibration:Controlled-source energy input via vibroseis trucks or marine air-gun arrays generates coherent wavefields. Onshore heavy oil projects in Canada's oil sands and Venezuela's Orinoco Belt rely on vibrator fleets for shallow high-resolution imaging.
- Refraction:First-arrival analysis of critically refracted waves maps basement topography and velocity layering. Geothermal developers in Iceland and Kenya commission refraction profiles for deep heat source delineation prior to drilling commitments.
- Reflection:Primary wavefield analysis dominates commercial hydrocarbon exploration with mature processing workflows. Ocean-bottom node deployments in deepwater Brazil and the Gulf of Mexico multiply receiver density tenfold over conventional towed streamers.
- Acoustic:Passive and active sonar methods support shallow hazard surveys and pipeline route engineering. North Sea offshore wind developers integrate acoustic sensing into export cable installations for continuous seabed monitoring.
Reflection technology commands the dominant share, with acoustic methods gaining share fastest in offshore wind and carbon storage applications.
End User:
Customer type concentration in oil and gas creates exposure to licensing cycle volatility, while environmental and construction segments diversify revenue streams.
- Oil & Gas:Exploration and production companies commission the majority of marine and land seismic contracts. Supermajors in the Gulf of Mexico and Brazil's Santos Basin drive demand for ultra-deepwater nodal surveys exceeding six kilometer target depths.
- Mining:Hard rock and alluvial deposit operators apply seismic for ore body delineation and geotechnical hazard assessment. South African platinum producers and Australian iron ore miners deploy 3D seismic ahead of mechanized extraction planning.
- Construction:Civil engineering firms characterize foundation conditions and tunneling hazards through shallow seismic surveys. Major infrastructure projects in the Alps and Himalayas require detailed fault mapping prior to bore excavation.
- Environmental:Regulators and developers assess carbon storage sites, groundwater resources, and contaminated land through non-invasive geophysical methods. EU Green Deal carbon storage mandates in the North Sea generate recurring baseline and monitoring survey requirements.
Oil and gas dominates the customer base, with environmental end use expanding most quickly on carbon capture site certification demand.
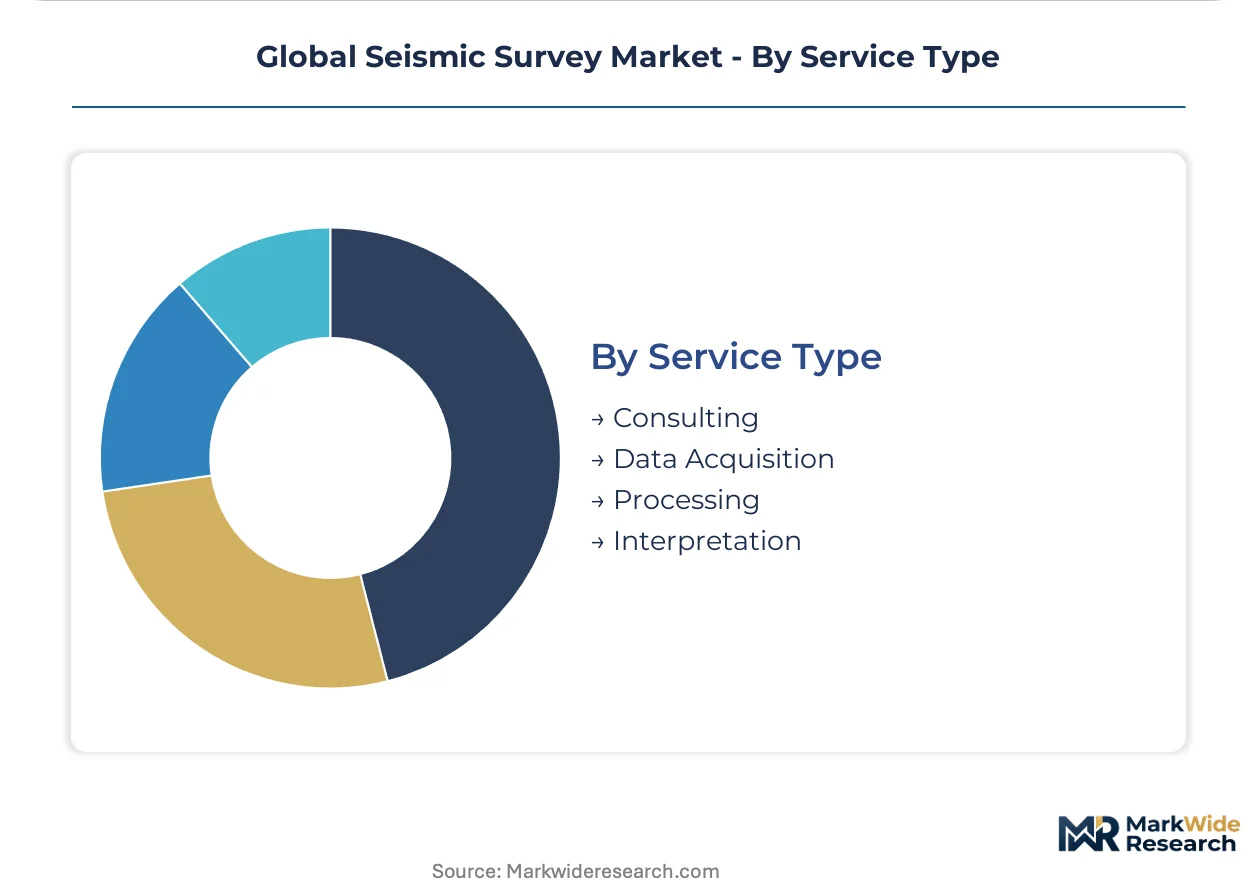
Service Type:
Margin structure varies sharply across the value chain, with processing and interpretation capturing premium pricing against commoditized acquisition services.
- Consulting:Front-end advisory services cover survey design, regulatory permitting, and risk assessment. Specialists in Houston and Stavanger advise on ocean-bottom node array geometry optimization for complex salt canopy environments.
- Data Acquisition:Field execution of source and receiver operations generates the largest revenue pool but thinnest margins. Only twelve purpose-built vessels worldwide can deploy deepwater nodal systems, creating queue bottlenecks for 4D reservoir monitoring.
- Processing:Computational workflows transform raw shot records into migrated seismic images suitable for interpretation. Machine learning velocity models now compress turnaround from months to weeks, enabling subscription-based service offerings.
- Interpretation:Geoscientist-led analysis delivers prospect risking, reservoir characterization, and drilling recommendations. US Gulf of Mexico independents increasingly unbundle this function, licensing raw data and applying proprietary models in-house.
Data acquisition represents the largest revenue category, with processing services delivering the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf of Mexico anchors global seismic survey demand through deepwater licensing rounds and reservoir monitoring mandates. Operators concentrate capital in Brazil's Santos Basin and Norway's North Sea shelf where regulatory frameworks enforce repeat survey intervals. Service providers position vessel fleets and nodal equipment inventories around these three dominant basins.
United States
The Gulf of Mexico sustains the largest contract volumes for ultra-deepwater ocean-bottom node surveys, with independent operators and supermajors commissioning 3D and 4D acquisition ahead of lease commitments. The US Bureau of Ocean Energy Management shapes Atlantic and Gulf permitting timelines, directly determining multi-client seismic investment cycles. Houston hosts the primary advisory cluster for survey design and array geometry optimization.
Brazil
The Santos and Campos basins drive pre-salt exploration seismic demand as the National Petroleum Agency maintains aggressive concession schedules. Petrobras and international operators commit to multi-year survey programs exceeding six-kilometer target depths. Rio de Janeiro anchors the regional service hub where contractors pre-position nodal hardware to shorten mobilization timelines.
Norway
The North Sea continental shelf enforces the strictest 4D monitoring compliance through Petroleum Safety Authority mandates requiring repeat surveys at maximum five-year intervals for water-injection fields. Equinor and partner operators sustain contract velocity for nodal providers with Bergen and Stavanger serving as equipment staging centers. EU Marine Strategy Framework Directive layers add environmental assessment requirements to permitting.
United Kingdom
The UK North Sea sector prioritizes carbon storage site characterization under EU Green Deal mandates, generating baseline seismic demand for depleted reservoir certification. The Oil and Gas Authority coordinates licensing rounds that tie exploration commitments to seismic work programs. Aberdeen maintains its position as the primary processing and interpretation cluster for North Atlantic surveys.
China
The South China Sea and Bohai Bay sustain state-backed seismic programs for offshore oil and gas development, with CNOOC driving vessel charter demand. National energy security priorities protect domestic survey capacity from international market volatility. Tianjin and Shenzhen host the primary equipment fabrication and vessel maintenance infrastructure.
Global Seismic Survey Market Competitive Environment
Global majors compete with regional champions across technology integration and vessel scale dimensions. The vendor base organizes around three tiers: integrated energy service conglomerates with bundled software-hardware offerings, specialized seismic contractors with proprietary imaging algorithms, and state-affiliated survey operators with protected domestic markets. Consolidation pressure intensifies as processing margins compress and buyers unbundle acquisition from interpretation services. Strategic moves center on fleet modernization for ocean-bottom node deployment and AI-driven velocity modeling capabilities.
Within the integrated service tier, Schlumberger and Halliburton occupy positions spanning seabed systems through processing software. CGG exemplifies the specialized imaging archetype with proprietary high-resolution algorithms. PGS ASA anchors the vessel-scale segment through Atlantic-margin fleet deployment. BGP Inc. represents state-affiliated capacity with protected access to Chinese offshore programs. Shearwater GeoServices and TGS occupy mid-tier positions between bundled offerings and pure-play processing.
| Leading Market Players |
|---|
| Schlumberger |
| CGG |
| PGS ASA |
| TGS |
| Fugro |
| BGP Inc. |
| Halliburton Company |
| SAExploration Holdings |
| Shearwater GeoServices |
| Others |
Value Chain & Pricing Dynamics
Performance divergence between ocean-bottom node arrays and conventional towed streamers manifests in both day-rate spreads and equipment sourcing geography, with premium-tier contractors commanding vessel premiums while commodity acquisition services face margin compression from buyer unbundling.
Pricing Analysis
Input-cost pass-through from specialized vessel scarcity and nodal hardware capital intensity shapes contract economics across the seismic services value chain. Project-based long-term contracting dominates ultra-deepwater surveys in Brazil and the Gulf of Mexico, while spot charter arrangements prevail for reconnaissance 2D programs. Price differentiation rests on receiver density specifications and proprietary imaging algorithm integration, with processing and interpretation capturing premium multiples over commoditized acquisition. Pricing pressure intensifies as US Gulf of Mexico independents license raw shot records for in-house velocity modeling, bypassing bundled service margins. Exploration departments at supermajors exhibit lowest price sensitivity given reservoir optimization imperatives, whereas mid-tier operators in frontier basins prioritize acreage coverage over data density.
Supply Chain Analysis
Regional equipment staging centers in Houston, Rio de Janeiro, Bergen, and Stavanger form a hub-and-spoke distribution pattern that positions nodal arrays and vessel fleets adjacent to high-activity basins. Manufacturing concentration for ocean-bottom nodes and fiber-optic sensing cables centers on Norway, the United Kingdom, and the United States, with specialized vessel construction concentrated in Singapore and South Korea. Raw material dependencies include high-strength steel for pressure-rated housings, rare-earth magnetics for sensor calibration, and telecommunications-grade fiber for distributed acoustic sensing arrays. Supply chain risk concentrates in single-source vulnerability for deepwater node deployment vessels, with only twelve purpose-built units globally. Distribution runs through contractor-owned regional bases rather than third-party logistics networks, reflecting the capital intensity and technical specialization of seismic equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in seismic services hinges on artificial intelligence-driven processing automation compressing turnaround times and enabling subscription-based interpretation offerings.
For Market Incumbents: Anchor market position through backward integration into seabed node manufacturing and proprietary algorithm development, defending against processing margin erosion from buyer unbundling. Pre-position equipment inventories in Bergen and Stavanger to capture Norway's five-year 4D monitoring mandate velocity. Prioritize fleet modernization for ocean-bottom node deployment capability, as specialized vessel scarcity creates queue bottlenecks that favor scale players.
For New Entrants and Emerging Players: Begin with carbon capture site characterization in the UK North Sea and geothermal reservoir imaging in Kenya and Iceland, where regulatory mandates generate recurring baseline survey demand without requiring deepwater vessel scale. Target environmental end-use segments where EU Green Deal compliance creates data acquisition cycles independent of oil and gas licensing volatility. Pursue direct licensing relationships with depleted reservoir operators seeking CCS certification, bypassing established seismic contractor intermediation.
For Investors and Strategic Acquirers: Consolidation pressure builds where processing margins compress and vessel-scale advantages intensify, favoring acquisition of specialized interpretation shops with machine learning velocity modeling capabilities. Long-term viability rests on exposure to energy transition applications—carbon storage, geothermal, offshore wind seabed monitoring—rather than pure hydrocarbon exploration cyclicality. Watch for regulatory compression in 4D monitoring mandates as the inflection signal, with Norway's Petroleum Safety Authority enforcement pattern likely to replicate across mature North Sea jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization for Nodal Deployment | Captures queue premiums from twelve-vessel scarcity in deepwater Brazil and Gulf of Mexico. |
| AI Velocity Model Development | Compresses processing turnaround from months to weeks, enabling subscription revenue streams. |
| Carbon Storage Site Certification Services | Secures recurring baseline and monitoring contracts under EU Green Deal North Sea mandates. |
| Equipment Staging Hub Expansion | Shortens mobilization timelines for Norway's five-year 4D compliance intervals. |
| Geothermal Imaging Capability Buildout | Replicates oilfield workflows for Iceland's national energy agency and Kenya's development company. |
Study Parameters
Direct dialogue with seismic vessel operators, petroleum geoscientists at supermajors and independents, regulatory affairs specialists at Norway's Petroleum Safety Authority and Brazil's National Petroleum Agency, and procurement leads at offshore wind developers grounded qualitative findings. Secondary validation drew from US Bureau of Ocean Energy Management lease schedules, EU Marine Strategy Framework Directive implementation guidance, SEC filings of publicly traded seismic contractors, and multi-client seismic library disclosure documents. Bottom-up and top-down triangulation reconciled vessel-day availability, nodal array deployment counts, and regional licensing round timing against aggregate market value estimates.
Analytical lens alternated between bottom-up equipment deployment tracking and top-down exploration budget allocation analysis across the projection horizon. Segmentation dimensions modeled encompassed product type, technology method, end-use industry, and service type, with vessel class and water-depth tier added as seismic-specific stratifiers. CAGRs derived from regression against historical licensing round correlation, vessel supply elasticity, and technology substitution curves for fiber-optic sensing penetration. Industry-specific forecast inputs included Petrobras pre-salt commitment schedules and Equinor reservoir monitoring contract velocity.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on Atlantic seismic permitting, breakthroughs in passive seismic monitoring that eliminate active source requirements, and vessel casualty events that tighten supply beyond queue bottlenecks already identified. Forecasts reflect documented assumptions on licensing round timing, technology adoption curves, and buyer unbundging progression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Perforating Gun Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
North America Proppants Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Digital Oilfield Solutions Market