
 Asia-Pacific Oilfield Chemicals Market | 2026-2036
Asia-Pacific Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oilfield Chemicals Market Outlook
Independent producers are reorganizing procurement patterns across the Asia-Pacific oilfield chemicals value chain, shifting from spot purchasing toward long-term service contracts with integrated chemical suppliers. BASF SE leverages its Ludwigshafen-based R&D network to sustain formulation leadership in high-temperature drilling fluids. Baker Hughes Company anchors its regional position through captive manufacturing in Thailand and direct technical service teams deployed at Indonesian operator sites. Huntsman International LLC differentiates via specialized amine chemistry for sour gas corrosion inhibition.
Asia-Pacific oilfield chemicals encompass surfactant-laden drilling fluids, polymer-thickened cement slurries, and sulfur-scavenging production chemicals engineered to maintain wellbore integrity under extreme downhole conditions of 150°C-plus and 10,000 psi. These formulations prevent formation damage, control corrosion rates, and optimize hydrocarbon flow from exploration through abandonment. Drilling fluids command the largest product volume share due to relentless offshore exploration in the South China Sea and Bay of Bengal, though production chemicals represent the fastest-expanding margin pool as mature fields require escalating scale inhibitor and demulsifier dosages. Enhanced oil recovery applications are gaining structural importance as Chinese and Malaysian operators deploy chemical flooding in depleted carbonate reservoirs.
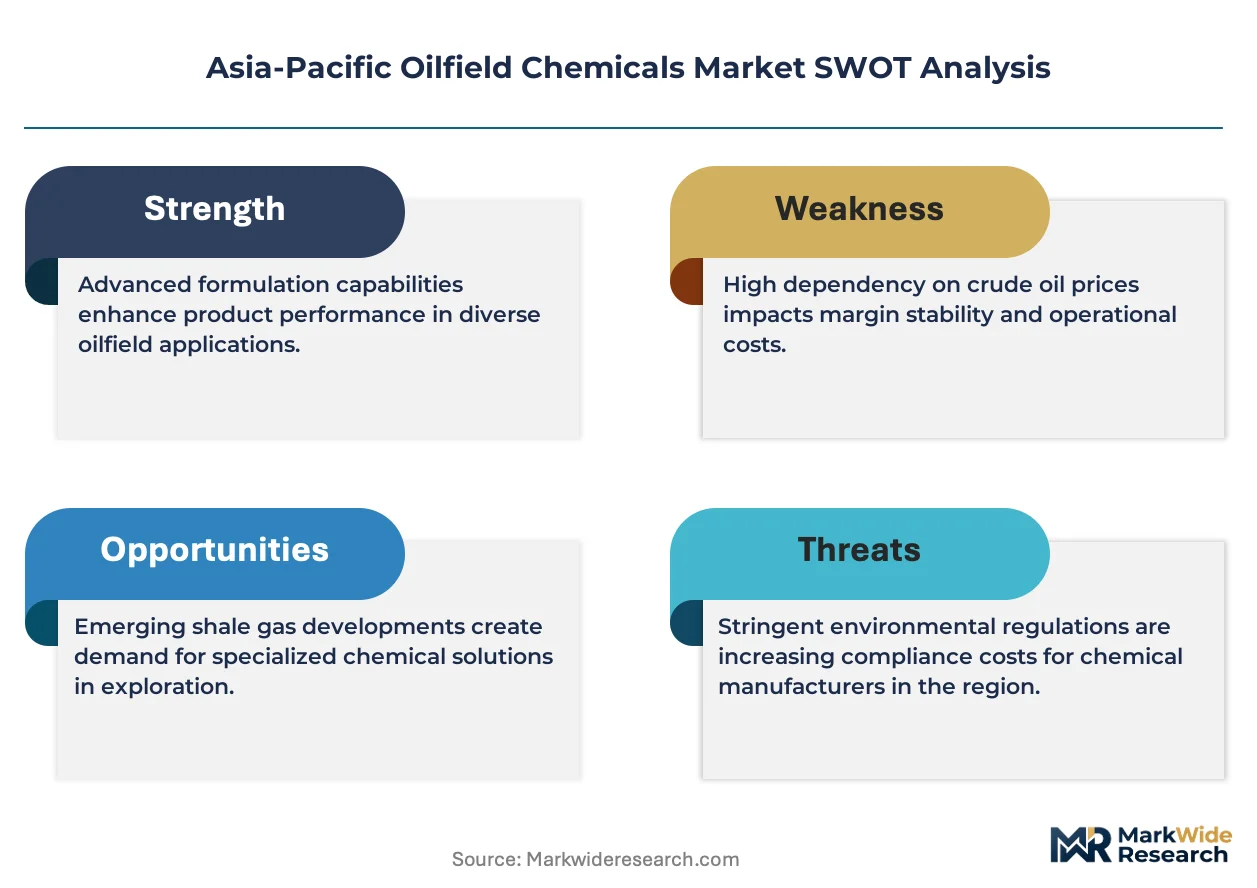
China's MEE enforces wastewater discharge standards that mandate biodegradable drilling fluid base oils, while Australia's NOPSEMA imposes strict chemical hazard assessments for offshore permit holders. India's BIS certification framework for oilfield additives creates compliance barriers for uncertified imports. Stakeholders must monitor regulatory divergence between ASEAN harmonization talks and country-specific environmental permitting to anticipate formulation reformulation costs and sourcing restructuring requirements.
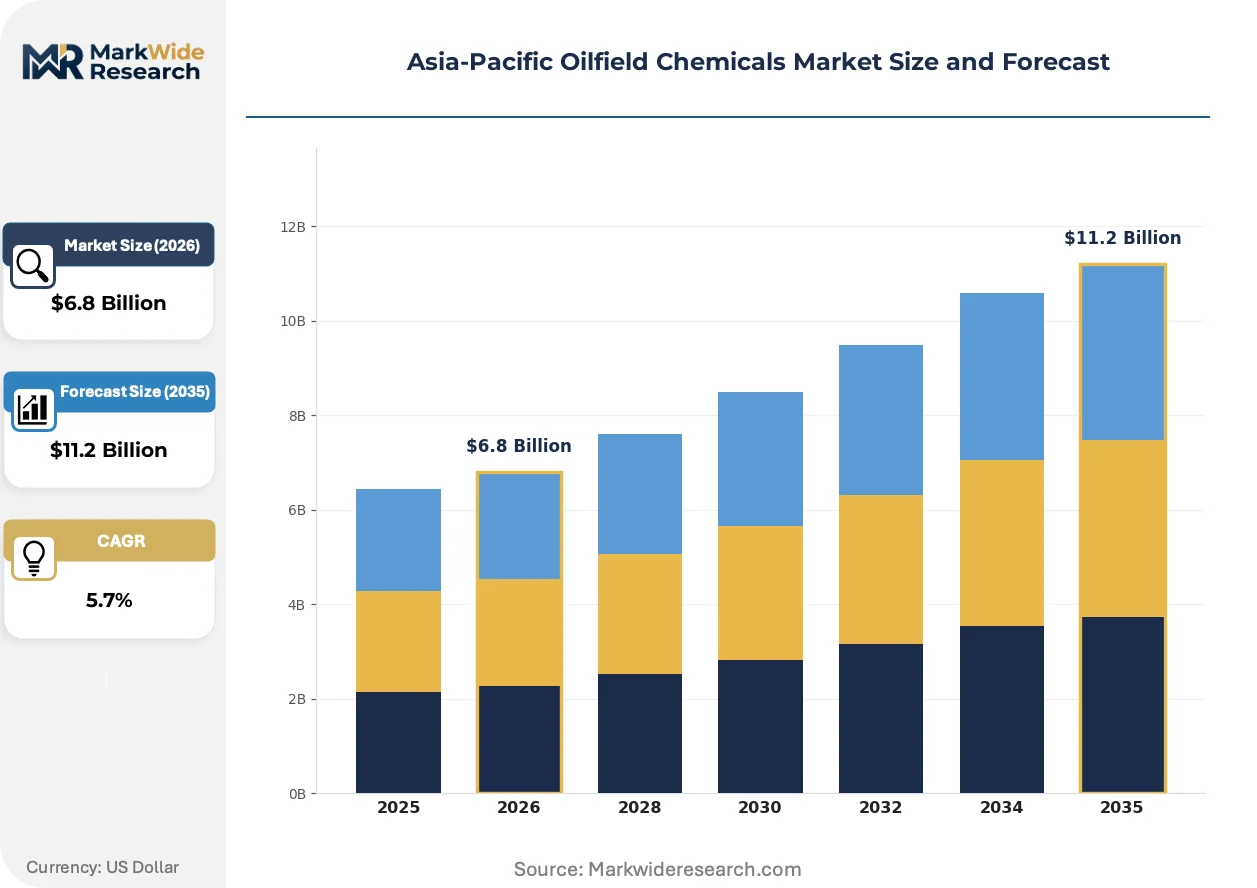
Market Dynamics
Maturing offshore basins across Southeast Asia and Australia are forcing operators to escalate production chemical dosages, restructuring procurement from commodity spot purchases toward integrated service contracts with formulation specialists.
Growth Catalysts
- MEE wastewater mandates:China's Ministry of Ecology and Environment enforces biodegradable base oil standards for drilling fluids, compelling formulation upgrades that expand addressable market for compliant suppliers.
- HPHT extraction intensity:Australia's offshore high-pressure high-temperature fields drive specialized corrosion inhibitor consumption at multiples of conventional well requirements.
- Enhanced oil recovery deployment:Chemical flooding in depleted carbonate reservoirs across China and Malaysia creates structural demand for polymer and surfactant flooding systems.
Market Restraints
- Alpha olefin supply concentration:Feedstock for synthetic drilling fluids concentrates among Middle Eastern and North American petrochemical complexes, exposing Asia-Pacific blenders to freight and currency volatility.
- BIS certification timelines:India's Bureau of Indian Standards approval protocols for drilling fluid additives extend supplier qualification cycles by 12-18 months, freezing out uncertified imports.
- Biodegradability-performance tradeoff:Vegetable oil esters meeting MEE discharge standards exhibit inferior thermal stability above 140°C, limiting application in deepwater HPHT environments.
Strategic Opportunities
- Indonesian mature field revival:Pertamina's accelerating chemical EOR pilots in Duri and Minas fields create first-mover advantage for integrated chemical-flooding service providers.
- Digital chemical monitoring:Real-time downhole sensor networks combined with predictive dosage algorithms enable outcome-based chemical management contracts displacing traditional volume-based supply.
- Vietnam offshore licensing:Block B and Ca Voi Xanh development approvals mandate full-field chemical service packages, opening integrated procurement channels unavailable in fragmented spot markets.
Industry Challenges
- HPHT formulation expertise scarcity:Competent chemists capable of stabilizing emulsions above 150°C and 10,000 psi remain concentrated among a handful of specialist laboratories in Singapore and Perth.
- Legacy well chemical compatibility:Decades-old production infrastructure in Malaysia's Peninsular basins requires extensive pretreatment before accepting modern high-activity scale inhibitors, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oilfield Chemicals Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Fluids, Production Chemicals, Corrosion Inhibitors, Cementing Additives Application: Exploration, Well Completion, Enhanced Oil Recovery, Workover End User: Oil & Gas Companies, Independent Producers, Service Providers, Mining Corporations Distribution Channel: Direct Sales, Online Sales, Distributors, Resellers |
| Companies Covered | BASF SE, AkzoNobel N.V., Baker Hughes Company, ChampionX, SLB, Halliburton, Huntsman International LLC, Solvay, Schlumberger, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oilfield Chemicals Market Strategic Shifts
Formulation chemistry and procurement architecture are undergoing parallel transformation as environmental compliance tightens and operator cost pressures intensify across Asia-Pacific offshore developments.
Internal olefin-based synthetic drilling fluids are supplanting diesel and mineral oil base stocks in environmentally sensitive offshore blocks. Shell's Prelude FLNG and Woodside's Scarborough development specify these formulations for discharge compliance. The shift compresses market space for conventional base oil suppliers while elevating specialty chemical margins.
NOPSEMA's chemical hazard assessment requirements for offshore permit holders in Australia now mandate full environmental fate documentation prior to deployment. Operators must submit toxicity and biodegradation data for every production chemical. This regulatory friction most affects demulsifier and corrosion inhibitor categories, where suppliers are consolidating product lines to reduce registration burden.
Integrated service contracting now dominates procurement for major offshore developments, with operators bundling chemical supply, technical service, and performance guarantees into single-source agreements. Spot purchasing persists only in onshore conventional fields. This structural shift is most visible in Australia's Northwest Shelf and Thailand's Gulf of Thailand blocks, where Chevron and PTTEP have consolidated supplier panels.
Asia-Pacific Oilfield Chemicals Market Segmentation
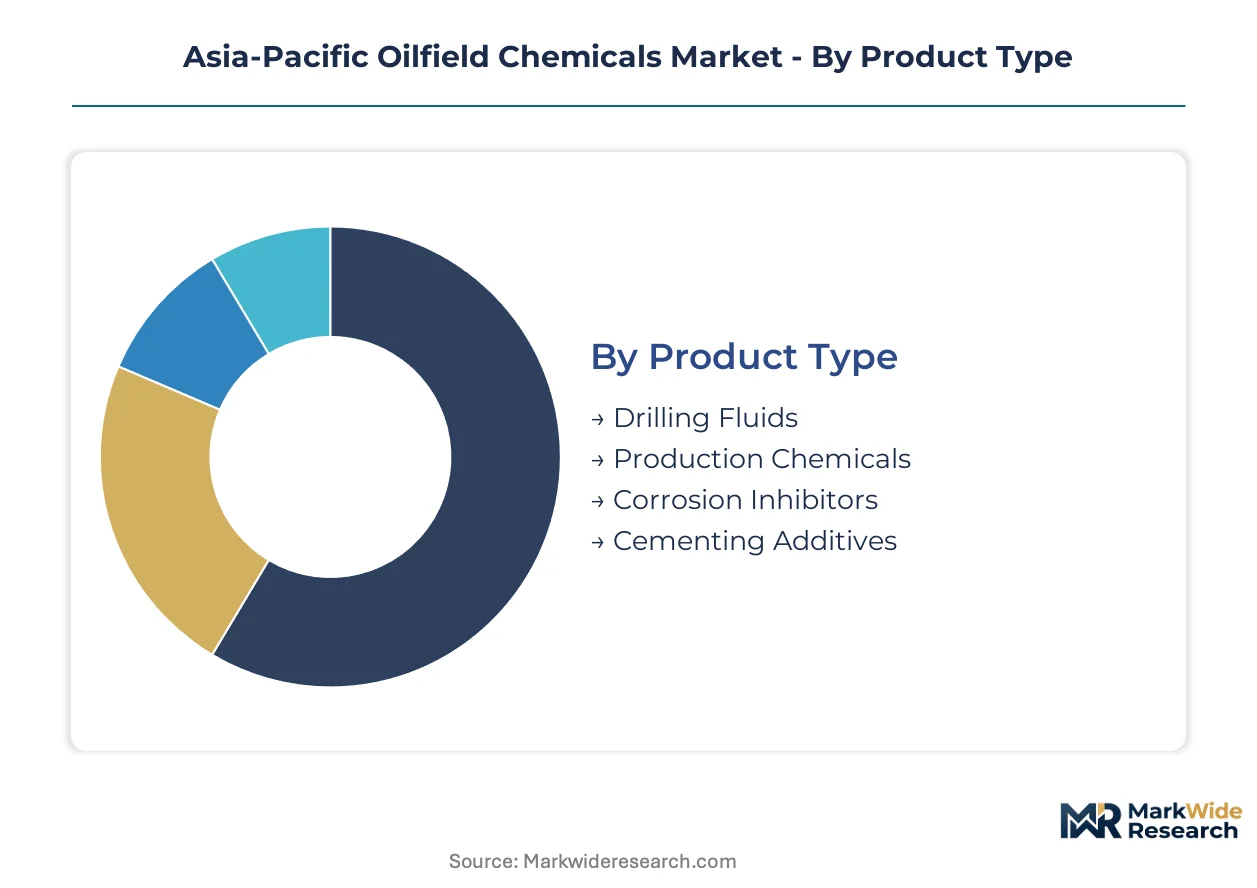
Segmentation in Asia-Pacific oilfield chemicals reveals where formulation value concentrates and where procurement power shifts. Understanding these divides exposes which suppliers capture margin and which face displacement from integrated service models.
Product Type:
Drilling fluids face the most acute substitution pressure as internal olefin synthetics displace legacy diesel and mineral oil bases under MEE wastewater mandates.
- Drilling Fluids:Complex suspensions of weighting agents, viscosifiers, and fluid-loss additives engineered to 150°C-plus thermal stability. Demand concentrates in Australia's Northwest Shelf and Indonesia's deepwater blocks where HPHT conditions mandate synthetic base stocks. MEE biodegradable requirements are accelerating formulation turnover among Chinese blenders.
- Production Chemicals:Scale inhibitors, demulsifiers, and sulfur scavengers deployed to sustain output from maturing reservoirs. Australia's Bass Strait and Malaysia's Peninsular basins drive consumption as operators escalate dosages to combat declining reservoir pressure. These formulations command the steepest margin expansion as field maturity deepens.
- Corrosion Inhibitors:Amine-based and film-forming compounds protecting carbon steel infrastructure in sour gas environments.
- Cementing Additives:Polymer-thickened slurries ensuring zonal isolation across varying downhole chemistries.
Drilling fluids retain volume leadership; production chemicals hold the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive exploration from recurring production expenditure, with procurement patterns diverging sharply between one-off project phases and ongoing field operations.
- Exploration:High-specification drilling fluid systems deployed in frontier basins with unproven formation characteristics. The South China Sea and Bay of Bengal absorb the bulk of exploration chemical volumes as CNOOC and ONGC advance wildcat programs. Regulatory pre-approval requirements for offshore discharge extend procurement cycles.
- Enhanced Oil Recovery:Polymer and surfactant flooding systems injected into depleted carbonate reservoirs. China's Daqing and Malaysia's Dulang fields are expanding chemical EOR pilots, creating structural demand for alkali-surfactant-polymer formulations. These applications require multi-year chemical supply commitments distinct from spot purchasing.
- Well Completion:Cement slurries and completion fluids establishing wellbore integrity before production.
- Workover:Remedial chemical interventions to restore production from damaged or plugged wells.
Exploration dominates absolute chemical tonnage; enhanced oil recovery is climbing the fastest as mature field priorities restructure operator budgets.
End User:
Customer type determines contract structure, with national oil companies favoring integrated service agreements while independents retain spot purchasing flexibility.
- Oil & Gas Companies:Integrated majors and national oil companies operating proprietary production assets. Pertamina, PTTEP, and Woodside are consolidating supplier panels into single-source chemical service contracts spanning supply, technical service, and performance guarantees. These buyers capture volume pricing leverage unavailable to smaller operators.
- Service Providers:Schlumberger, Halliburton, and regional drilling contractors procuring chemicals as part of integrated well services. This segment is expanding most quickly as operators outsource chemical management to field service specialists with captive formulation capabilities and real-time monitoring infrastructure.
- Independent Producers:Smaller operators without integrated supply chain functions, reliant on distributor networks.
- Mining Corporations:Diversified resource companies with ancillary hydrocarbon operations requiring drilling and completion chemicals.
Oil and gas companies retain procurement volume leadership; service providers are gaining share fastest through integrated contracting capture.
Distribution Channel:
Supply concentration among formulation specialists with captive manufacturing is compressing intermediary roles across Asia-Pacific offshore developments.
- Direct Sales:Manufacturer-to-operator supply relationships bypassing intermediaries, dominant in Australia's Northwest Shelf and Thailand's Gulf of Thailand blocks. BASF and Baker Hughes deploy technical service teams at operator sites to support direct supply relationships. These arrangements enable outcome-based chemical management contracts displacing volume-based purchasing.
- Distributors:Regional stockists serving fragmented onshore conventional fields in India and China's inland basins. This channel faces margin compression as certified suppliers consolidate procurement panels and operators reduce supplier counts.
- Online Sales:Digital procurement platforms for standardized commodity additives with established specifications.
- Resellers:Independent traders bridging uncertified imports into markets with delayed BIS or equivalent qualification timelines.
Direct sales retain value leadership; distributor channel share is eroding fastest under integrated service contracting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Karratha Gas Plant and Dampier-to-Bunbury Natural Gas Pipeline anchor Western Australia's role as the regional hub for high-pressure high-temperature chemical demand. These infrastructure assets service the Northwest Shelf and Browse Basin developments where specialized corrosion inhibitors command premium pricing.
Australia
Woodside's Scarborough and Pluto Train 2 projects drive consumption of synthetic drilling fluids and production chemicals. NOPSEMA mandates comprehensive environmental fate documentation before offshore deployment. Perth hosts the dominant technical service cluster serving Bass Strait mature fields with escalating scale inhibitor dosages.
China
CNOOC advances wildcat programs in the South China Sea while Sinopec expands chemical EOR pilots in Daqing carbonate reservoirs. MEE wastewater standards enforce biodegradable base oil formulations for drilling fluids. Tianjin and Qingdao blenders are reformulating product lines to meet discharge compliance requirements.
India
ONGC's Bay of Bengal deepwater exploration and Reliance's KG-D6 development sustain drilling fluid volumes. BIS certification protocols for additives extend supplier qualification cycles by 12-18 months. Mumbai and Chennai serve as procurement coordination points for offshore block developments.
Indonesia
Pertamina's chemical EOR pilots in Duri and Minas fields create integrated service contract opportunities. SKK Migas licensing terms for Block B and East Natuna mandate full-field chemical service packages. Jakarta and Balikpapan concentrate technical service teams supporting mature field revitalization programs.
Thailand
PTTEP's Gulf of Thailand blocks drive production chemical demand as reservoir pressure declines. Board of Investment incentives for petrochemical manufacturing support local blending capacity expansion. Rayong's industrial corridor hosts captive manufacturing facilities supplying integrated service contracts.
Asia-Pacific Oilfield Chemicals Market Competitive Environment
Listed leaders compete with private specialists across formulation complexity and service integration dimensions. The vendor base concentrates among integrated majors with captive R&D networks and regional manufacturing footprints. Three archetypes dominate: global diversified chemical conglomerates with oilfield divisions, specialized oilfield service companies with in-house formulation capabilities, and regional blenders serving spot markets. Competitive moves center on backward integration into feedstock supply and outcome-based contracting displacing volume-based supply arrangements.
Within the integrated service tier, Baker Hughes Company and SLB exemplify the captive manufacturing model with technical service deployment at operator sites. BASF SE anchors the diversified chemical conglomerate position through Ludwigshafen-based R&D networks sustaining formulation leadership. Huntsman International LLC occupies the specialized chemistry niche with amine-based product lines for sour gas applications. These three represent distinct competitive vectors: service integration, scale-driven formulation breadth, and targeted molecular specialization.
| Leading Market Players |
|---|
| BASF SE |
| AkzoNobel N.V. |
| Baker Hughes Company |
| ChampionX |
| SLB |
| Halliburton |
| Huntsman International LLC |
| Solvay |
| Schlumberger |
| Others |
Value Chain & Pricing Dynamics
India's BIS certification protocols for drilling fluid additives simultaneously gate supplier entry and stratify pricing tiers across the Asia-Pacific oilfield chemicals market. Operators seeking qualified suppliers face extended qualification cycles that compress spot-market participation while elevating contract premiums for certified formulations.
Pricing Analysis
Volume-discount tiering structures separate integrated service contracts from spot purchases across Australian and Thai offshore blocks. Three-tier pricing stratifies across premium HPHT-certified formulations, standard biodegradable base stocks meeting MEE discharge standards, and economy-grade mineral oil systems for onshore conventional fields. Cost compression in the economy tier intensifies as Indian and Chinese blenders expand capacity. National oil companies exhibit lowest price sensitivity due to performance guarantees and technical service bundling, while independent producers in fragmented onshore basins drive commodity-tier negotiation.
Supply Chain Analysis
Inventory lead times for synthetic base stocks extend 8-12 weeks as Asia-Pacific blenders draw from Middle Eastern and North American alpha olefin complexes. Formulation production rests on feedstock concentration in Saudi Arabia, Qatar, and the US Gulf Coast, with Singapore and Thailand hosting regional blending and technical service hubs. Single-source vulnerability concentrates in alpha olefin supply channels exposed to freight rate volatility and currency fluctuation. Distribution runs through direct manufacturer-to-operator relationships in Australian and Indonesian offshore developments, compressing distributor margins in fragmented onshore markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Internal olefin synthetic base stocks threaten legacy mineral oil and diesel formulations as MEE wastewater mandates harden, forcing incumbents to defend substitution risk through certification-locked supply relationships.
For Market Incumbents: Secure BIS pre-certification for drilling fluid additive portfolios to freeze out uncertified import competition in Indian offshore procurement. Anchor backward integration into alpha olefin feedstock through long-term offtake agreements with Middle Eastern petrochemical complexes, reducing exposure to freight volatility that compresses blending margins.
For New Entrants and Emerging Players: India's BIS certification fast-track for drilling fluid additives offers 12-18 month entry acceleration versus standard qualification timelines. Target Vietnam's Block B and Ca Voi Xanh developments where SKK Migas licensing mandates full-field chemical service packages unavailable to spot-market suppliers. Lead with digital chemical monitoring capabilities to displace volume-based supply contracts with outcome-based performance guarantees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across HPHT formulation specialists as R&D expenditure concentrates in Singapore and Perth technical service clusters. Five-to-ten year viability favors acquisition of regional blenders with captive manufacturing in Thailand's Rayong corridor and established NOPSEMA environmental fate documentation. Monitor Pertamina's Duri and Minas chemical EOR pilot scale-up as inflection signal for integrated service contract expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha Olefin Supply | Captive feedstock from Qatar's Ras Laffan complex secures margin against freight volatility. |
| BIS Certification Pre-Investment | Early qualification locks out uncertified competitors from ONGC's Bay of Bengal procurement. |
| Digital Chemical Monitoring Platform | Predictive dosage algorithms enable outcome-based contracts displacing volume supply at Woodside. |
| HPHT Formulation R&D Expansion | Singapore laboratory capacity addresses emulsion stability scarcity above 150°C and 10,000 psi. |
| Integrated Service Contract Consolidation | Single-source agreements spanning supply and technical service capture PTTEP Gulf of Thailand panel positions. |
Study Parameters
A standing panel of procurement directors at national oil companies, technical service managers at integrated chemical suppliers, plant managers at Singapore and Thai blending facilities, and regulatory affairs specialists tracking MEE and NOPSEMA compliance provided ongoing calibration. Primary interviews combined with secondary validation from customs trade data, ASEAN petrochemical association reports, BIS certification registries, and SEC filings from listed chemical conglomerates. Bottom-up volume estimates from field-level chemical consumption triangulated against top-down market sizing from regional production forecasts.
Consistency checks validated volume and value outputs against external benchmarks including regional offshore drilling activity indices and mature field production decline curves. The analytical framework segmented across product type, application, end user, and distribution channel dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical chemical intensity per well and projected exploration and production expenditure patterns. Industry-specific inputs incorporated HPHT well count trajectories in Australian basins and chemical EOR pilot expansion timelines in Chinese and Indonesian carbonate reservoirs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of MEE biodegradable standards or BIS certification timelines would require recalibration. Forecasts reflect assumptions regarding offshore licensing approval schedules and mature field decline rates. Supply chain disruption from alpha olebin feedstock concentration or tariff friction on synthetic base stock imports represents specific revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Coiled Tubing Services Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Underreamers Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Casing Centralizer Market