
 North America Proppants Market | 2026-2036
North America Proppants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Proppants Market Analytics
Proppant logistics and last-mile delivery services are expanding as a distinct revenue layer, with operators now contracting guaranteed supply programs rather than purchasing bulk material alone. Covia Holdings LLC leverages its integrated mine-to-wellhead network across Wisconsin and Texas to control delivery timing and reduce trucking costs for Appalachian and Permian customers. US Silica Holdings Inc. anchors its position through owned rail infrastructure and transload facilities that bypass third-party bottlenecks during peak drilling seasons. Badger Mining Corp. competes on Northern White sand purity grades that meet API specifications for deep-well applications in Oklahoma and North Dakota.
North America proppants are granular materials injected into hydraulically fractured rock formations to hold fissures open after fluid pressure dissipates, typically sized between 12/20 and 40/70 mesh with sphericity and roundness values exceeding 0.6 per API RP 19C. Their primary purpose is to maintain fracture conductivity so hydrocarbons can flow to the wellbore under thousands of psi of overburden stress. Sand dominates volume across all applications due to its low cost and adequate performance in shallow-to-mid-depth wells, while ceramic proppants command the premium tier where closure stress exceeds 8,000 psi and conductivity degradation threatens EUR estimates. Resin-coated proppants are gaining share among E&P companies seeking to reduce proppant flowback and minimize formation fines migration in multi-stage horizontal completions.
The EPA regulates proppant handling under the Clean Water Act and Safe Drinking Water Act, particularly concerning silica dust exposure limits and stormwater discharge from mining operations. OSHA enforces permissible exposure limits for respirable crystalline silica at mining and transload facilities, while the Bureau of Land Management imposes bonding requirements for proppant extraction on federal lands that shape supplier site selection. State-level regulators in Texas and North Dakota administer additional setback rules and aquifer protection standards that filter which proppant grades qualify for specific basin deployments. Stakeholders must monitor how evolving particulate matter standards and railcar availability constraints interact to reshape procurement priorities across the major shale plays.
Market Dynamics
Closure stress thresholds in deep horizontal wells are forcing operators toward engineered proppant systems that preserve fracture conductivity under extreme downhole conditions, reshaping supplier R&D priorities and procurement specifications across the Permian, Bakken, and Eagle Ford.
Growth Catalysts
- EPA Effluent Limitations Guidelines:Revised standards for oil and gas extraction wastewater are mandating cleaner completion fluids, accelerating resin-coated proppant adoption to minimize formation damage and reduce post-fracture recovery requirements.
- Permian Basin drilling intensity:Multi-mile laterals in Texas and New Mexico are consuming record proppant volumes per well, with single-stage sand loads now exceeding 3,000 pounds per lateral foot in Wolfcamp and Bone Spring targets.
- Ceramic proppant conductivity advantages:High-strength bauxite-based materials maintain 80% permeability at 12,000 psi closure stress, enabling operators to book higher estimated ultimate recovery in deep Delaware Basin horizontals.
Market Restraints
- Northern White sand supply concentration:API-specified frac sand deposits cluster in Wisconsin, Minnesota, and Illinois, creating 1,200-mile rail hauls to Permian demand centers that amplify delivered cost volatility during peak drilling seasons.
- Silica respirable crystalline exposure:OSHA's 50 micrograms per cubic meter permissible exposure limit forces mining and transload operators to deploy dust suppression capital, raising fixed costs for dry sand handling infrastructure.
- Lightweight ceramic substitution limits:Sintered bauxite proppants cost 8-12x more than regional sand alternatives, capping addressable market share to ultra-high-stress formations above 10,000 psi where conductivity degradation threatens production economics.
Strategic Opportunities
- Last-mile logistics integration:Guaranteed supply programs that bundle mine-origin sand with dedicated trucking and wellsite storage are capturing premium pricing from operators seeking to eliminate demurrage risk during completion windows.
- Resin-coated proppant flowback control:Curable and pre-cured resin systems that bond under bottom-hole temperature conditions are expanding into Oklahoma SCOOP/STACK plays where proppant return reduction protects artificial lift equipment.
- Canadian oil sands thermal applications:Steam-assisted gravity drainage operators in Alberta are piloting high-conductivity ceramic proppants to enhance injector-producer communication in McMurray Formation bitumen recovery.
Industry Challenges
- API RP 19C testing capacity:Third-party sphericity, roundness, and crush resistance certification bottlenecks are extending new product qualification timelines, delaying commercial deployment of alternative proppant sources outside traditional Wisconsin supply basins.
- Railcar fleet availability:Class I railroad sand car allocations tighten during Q2-Q3 completion surges, forcing operators to pre-position inventory at elevated carrying costs or accept spot market trucking premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Proppants Market |
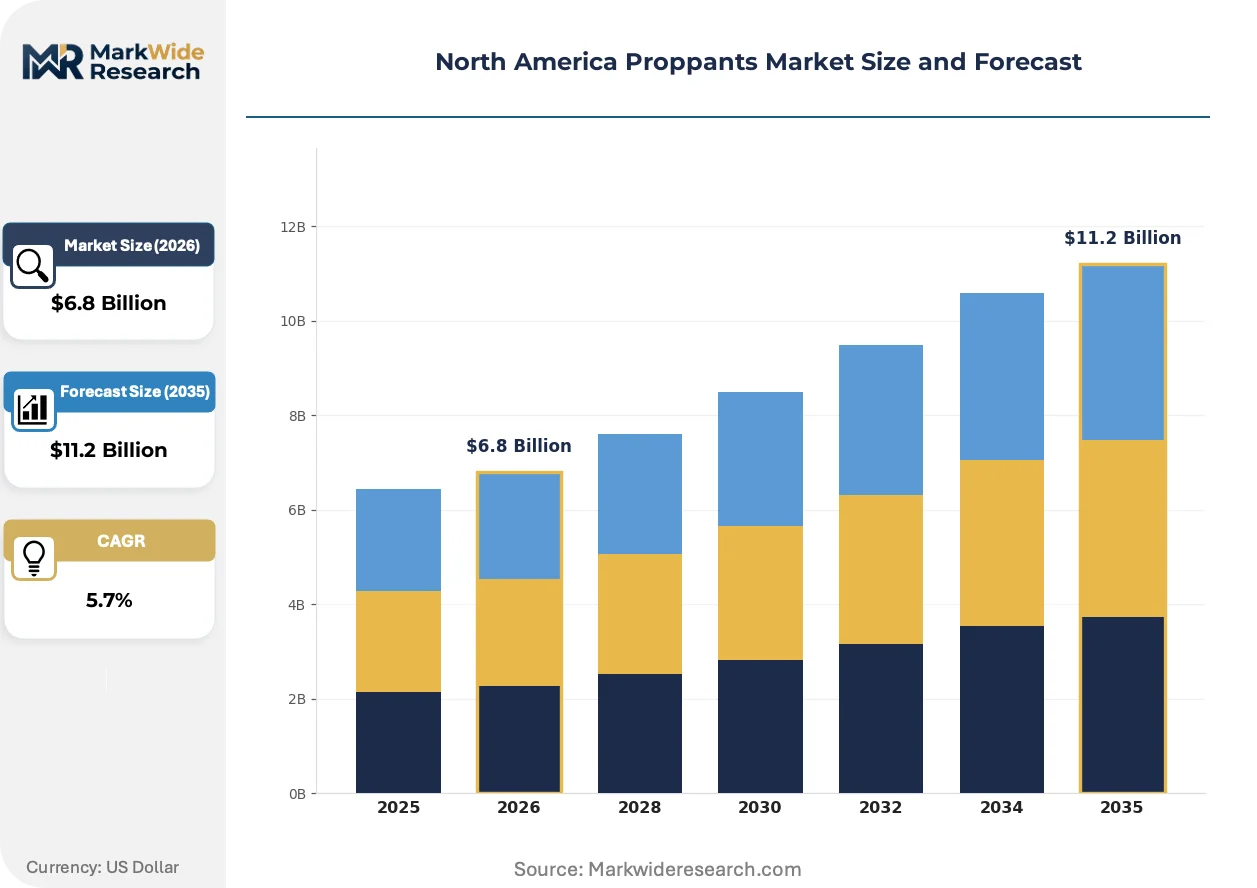
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sand, Resin-coated Proppants, Ceramic Proppants, Others Application: Oil & Gas, Mining, Water Treatment, Construction End User: E&P Companies, Service Providers, Government, Industrial Users Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Badger Mining Corp., Compagnie de Saint-Gobain SA, Covia Holdings LLC, Hi-Crush Inc., Atlas Sand Company, LLC, US Silica Holdings Inc., Imerys S.A., Superior Silica Sands LLC, CARBO Ceramics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Proppants Market Evolving Landscape
In-basin sand mining is collapsing traditional supply chain architectures, with Permian and Appalachian producers now sourcing material within 50 miles of well pads rather than accepting Midwest rail economics.
Regional sand processing is decentralizing fracture supply chains by eliminating 1,000-plus-mile rail hauls from Wisconsin to Texas. E&P operators in the Permian Delaware and Midland sub-basins are contracting mine-mouth facilities that crush and wash local sand deposits to API specifications. This geographic compression is collapsing delivered cost structures and eroding Northern White sand premium pricing in shallow-to-mid-depth applications.
The EPA's revised effluent limitations guidelines for oil and gas extraction are mandating cleaner completion fluid chemistries that reduce formation damage. Operators must now manage produced water discharge under stricter biological oxygen demand and total dissolved solids thresholds. Resin-coated proppants are capturing share in multi-stage horizontals where reduced fluid recovery requirements align with compliance cost minimization strategies.
Guaranteed supply contracting is displacing spot market bulk purchasing as the dominant procurement model among large independents and majors. Long-term offtake agreements that embed logistics, storage, and wellsite delivery are transferring inventory risk from E&P balance sheets to supplier networks. This structural shift is most pronounced in Texas, where Permian drilling cadence volatility punishes operators holding unsandstocked completion crews.
North America Proppants Market Segmentation
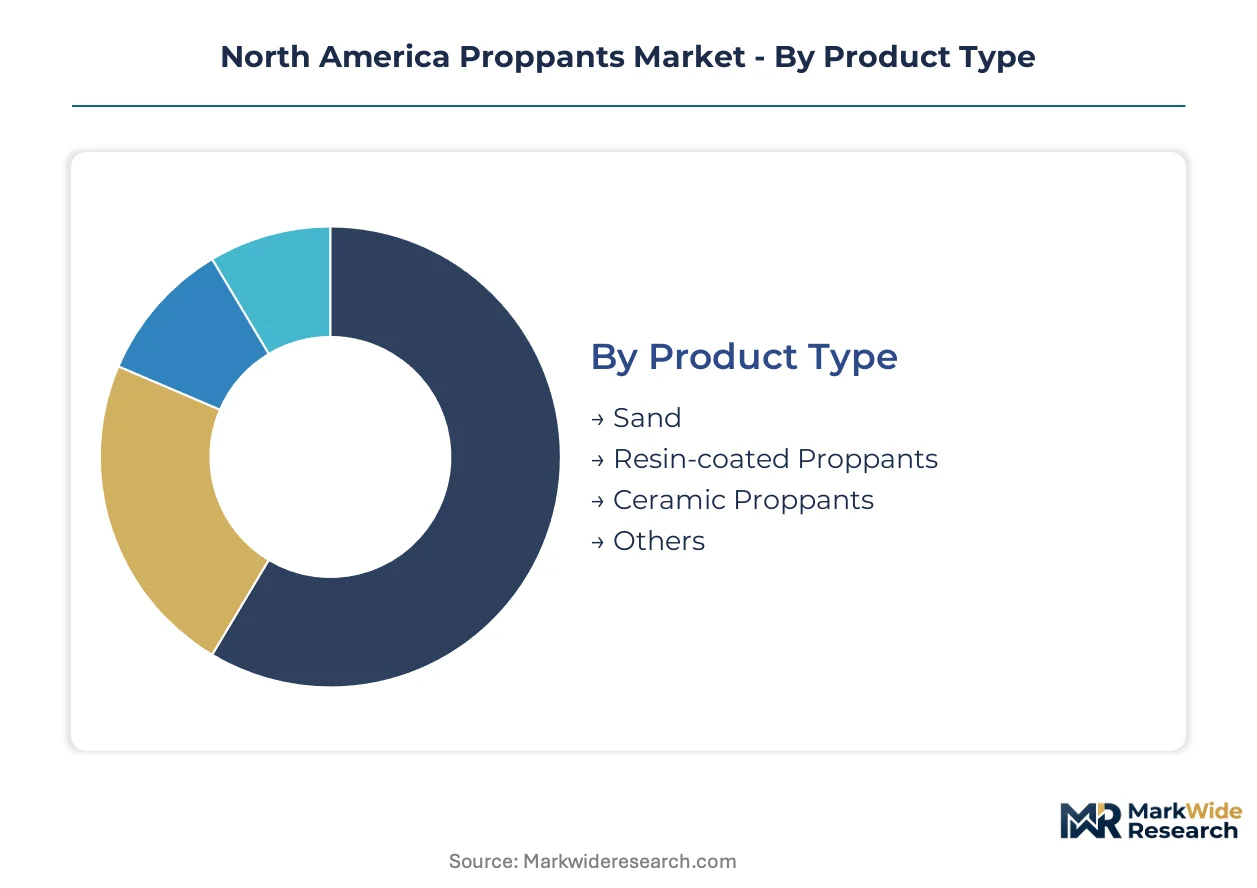
Proppant procurement specifications diverge sharply between high-volume horizontal shale completions and specialized deep-well applications. Understanding these segment boundaries clarifies why suppliers maintain parallel product portfolios rather than converging on single-material solutions.
Product Type:
Volume dominates the low-cost tier while premium materials capture extreme-stress niches.
- Sand:Naturally occurring silica quartz processed to API RP 19C sphericity and roundness specifications above 0.6. Northern White deposits in Wisconsin and regional Permian mines supply 85% of total proppant volume for Eagle Ford and Bakken shallow-to-mid-depth laterals where closure stress stays below 8,000 psi.
- Resin-coated Proppants:Pre-cured or curable polymer films applied to sand substrates that bond under bottom-hole temperature to prevent flowback and fines migration. Delaware Basin operators in Texas are expanding resin-coated loads in multi-stage horizontals to protect artificial lift equipment from returned proppant damage.
- Ceramic Proppants:Sintered bauxite-based engineered materials maintain fracture conductivity above 80% at 12,000 psi closure stress. Premium pricing limits deployment to ultra-deep Wolfcamp and Bone Spring targets where conductivity degradation directly threatens EUR estimates.
- Others:Lightweight synthetic alternatives and coated walnut hull derivatives serving niche coalbed methane and water fracturing applications in Oklahoma and Appalachian basins.
Today's leader: Sand. Tomorrow's challenger: Resin-coated Proppants.
Application:
Upstream hydrocarbon extraction consumes the dominant share of engineered proppant tonnage.
- Oil & Gas:Hydraulic fracturing of unconventional shale reservoirs in Permian, Bakken, and Eagle Ford formations. EPA effluent limitations guidelines are accelerating resin-coated adoption to minimize formation damage and reduce produced water recovery requirements.
- Mining:In-situ leaching and solution mining applications where proppant-packed fractures enhance mineral access. Limited penetration outside southwestern copper and uranium extraction zones.
- Water Treatment:Filtration media and well rehabilitation applications using graded sand proppants as permeable barriers.
- Construction:Lightweight aggregate and concrete additive applications absorbing lower-specification sand grades rejected by oilfield quality standards.
Oil & Gas anchors current demand. Water Treatment offers the steepest expansion trajectory outside hydrocarbon extraction.
End User:
Procurement authority concentrates with operators controlling drilling schedules and completion designs.
- E&P Companies:Integrated majors and large independents in Texas and North Dakota specifying proppant grades, mesh sizes, and logistics terms in master service agreements. Guaranteed supply programs now transfer inventory risk from operator balance sheets to supplier networks.
- Service Providers:Hydraulic fracturing contractors executing proppant placement per operator specifications. Halliburton and Liberty Oilfield Services maintain strategic sand reserves to ensure crew utilization during demand surges.
- Government:State mineral agencies and federal land managers imposing bonding and aquifer protection requirements that filter qualifying proppant sources for federal lease development.
- Industrial Users:Foundries, glass manufacturers, and construction material producers competing for sand supply outside peak oilfield demand windows.
E&P Companies dictate material specifications. Service Providers are capturing expanded procurement influence through integrated logistics offerings.
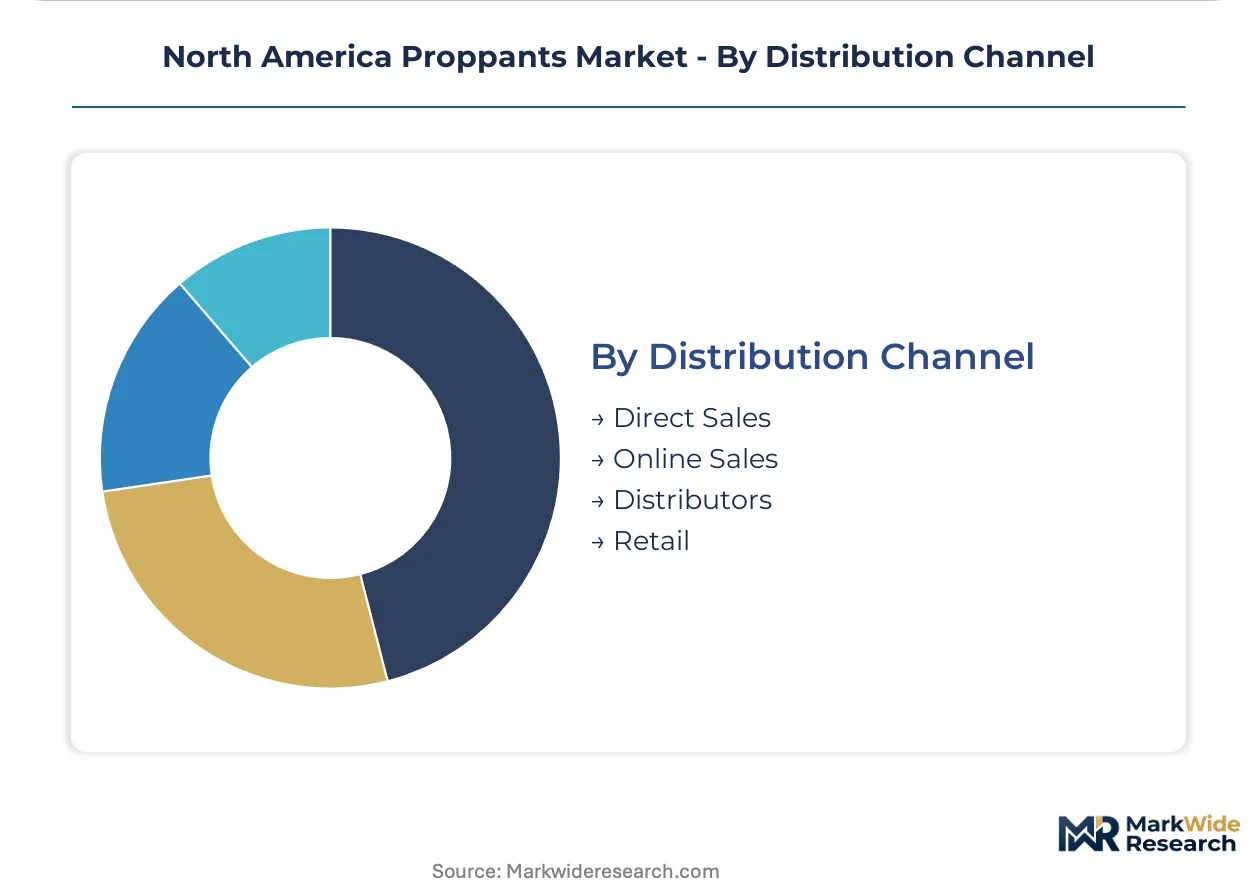
Distribution Channel:
Physical proximity to well pads now outweighs price minimization in channel selection.
- Direct Sales:Mine-to-wellhead contracts with dedicated rail and trucking fleets eliminating third-party transload bottlenecks. Covia Holdings and US Silica anchor positions through owned infrastructure across Wisconsin and Texas.
- Distributors:Regional sand suppliers buffering inventory for small independents lacking volume to justify direct mine contracts. Concentrated in Oklahoma SCOOP/STACK and Appalachian Marcellus plays.
- Online Sales:Digital procurement platforms for spot market sand purchases during unplanned completion accelerations. Limited adoption due to railcar allocation constraints and quality verification requirements.
- Retail:Bagged proppant sales for workover operations and water well rehabilitation. Negligible share of total market volume.
Direct Sales commands the premium tier. Distributors defend relevance through regional inventory positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada consumes roughly one-fifth the proppant tonnage of the United States, yet Alberta's thermal oil sands operations are driving specialized demand for high-conductivity ceramics that diverges sharply from Texas shale patterns.
United States
Texas dominates continental consumption through Permian Basin Wolfcamp and Bone Spring drilling, where single-stage sand loads exceed 3,000 pounds per lateral foot. EPA effluent limitations guidelines are accelerating resin-coated proppant adoption to minimize formation damage and reduce produced water recovery requirements. Midland-Odessa anchors the largest in-basin sand mining cluster, with regional processing facilities collapsing traditional 1,200-mile rail hauls from Wisconsin.
Canada
Alberta's steam-assisted gravity drainage operators pilot high-conductivity ceramic proppants to enhance injector-producer communication in McMurray Formation bitumen recovery. Environment and Climate Change Canada administers additional aquifer protection standards that filter qualifying proppant sources for oil sands thermal applications. The Fort McMurray region concentrates pilot deployment activity where conductivity under cyclic steam injection conditions drives material selection.
Mexico
Burgos Basin shale exploration in Nuevo León and Tamaulipas is generating initial proppant demand as Pemex and international operators test Eagle Ford analog formations. The country's national hydrocarbons regulator CNH imposes bonding requirements for hydraulic fracturing operations that shape supplier qualification protocols. Monterrey anchors emerging logistics infrastructure development for potential cross-border supply integration with Texas Permian networks.
North America Proppants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mine-to-wellhead operators commanding premium pricing against regional toll processors. The vendor base concentrates around three strategic tiers: Northern White sand purists defending API specification leadership, in-basin regional miners competing on delivered cost, and ceramic specialists capturing ultra-high-stress niches. Dominant competitive moves include backward integration into captive rail and transload infrastructure, plus guaranteed supply contracting that transfers inventory risk from E&P balance sheets to supplier networks.
Among Wisconsin-based mining specialists, Badger Mining Corp. and Superior Silica Sands LLC represent the Northern White sand purity tier that anchors premium positioning for deep-well applications. Covia Holdings LLC exemplifies the integrated logistics archetype through its mine-to-wellhead network spanning Wisconsin and Texas. US Silica Holdings Inc. occupies a parallel position through owned rail infrastructure that bypasses third-party bottlenecks during peak drilling seasons.
| Leading Market Players |
|---|
| Badger Mining Corp. |
| Compagnie de Saint-Gobain SA |
| Covia Holdings LLC |
| Hi-Crush Inc. |
| Atlas Sand Company, LLC |
| US Silica Holdings Inc. |
| Imerys S.A. |
| Superior Silica Sands LLC |
| CARBO Ceramics Inc. |
| Others |
Value Network & Pricing Analysis
EPA-mandated resin-coated proppant specifications for cleaner completion fluids are forcing suppliers to absorb polymer coating cost premiums while defending sand-grade price positions, compressing margins across mid-tier product lines and accelerating tier consolidation.
Pricing Analysis
Capacity additions in Texas and Wisconsin are reshaping price floors for Northern White sand as regional Permian mines undercut traditional rail-delivered economics. Three-tier pricing structure across premium ceramic, standard resin-coated, and economy sand levels stratifies by closure stress rating and logistics bundling. Pricing pressure stems from in-basin sand oversupply in Midland-Odessa, where mine-mouth processing collapses delivered cost structures. Small independents exhibit highest price sensitivity, while majors prioritize guaranteed supply program premiums over unit cost minimization.
Supply Chain Analysis
Mine-to-wellhead direct contracts handle hyperscale E&P demand, bypassing third-party transload bottlenecks through captive rail and trucking fleets. Geographic supply concentrates in Wisconsin, Texas, and Minnesota, with Canadian oil sands emerging as a secondary ceramic proppant destination. Raw material dependencies center on API-specified silica quartz deposits, sintered bauxite feedstock, and curable resin polymer systems. Single-source vulnerability runs through Class I railroad sand car allocations during Q2-Q3 completion surges. Distribution runs through integrated logistics networks rather than spot market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America proppants market functions as a stable compounder anchored by irreplaceable demand from Permian Basin drilling intensity, where proppant intensity per lateral foot continues advancing without substitution risk.
For Market Incumbents: Hedge against in-basin sand price erosion by securing captive rail infrastructure and transload assets that spot-market competitors cannot replicate. Invest in resin-coating capacity additions to capture EPA-driven specification shifts before toll-coating margins compress. Defend Northern White sand premium positioning through API RP 19C certification leadership that regional miners cannot immediately match.
For New Entrants and Emerging Players: Digital procurement platforms for spot-market sand purchases offer a route around established logistics networks for small independents lacking volume for direct mine contracts. Target Oklahoma SCOOP/STACK and Appalachian Marcellus plays where distributor networks retain relevance and in-basin mine saturation remains lower. Pursue guaranteed supply program partnerships that bundle last-mile delivery with inventory risk transfer.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated mine-to-wellhead operators owning Wisconsin-to-Texas logistics corridors that cannot be replicated through organic expansion. Five-to-ten year viability hinges on Permian drilling cadence durability and resin-coated proppant share expansion. Watch railcar fleet utilization rates as the inflection signal for pricing power shifts between suppliers and railroads.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rail Infrastructure | Covia Holdings and US Silica bypass third-party bottlenecks through owned sand car fleets and transload facilities. |
| Resin-Coating Capacity Expansion | EPA effluent limitations guidelines accelerate demand for curable polymer systems that minimize formation damage. |
| In-Basin Mine Development | Permian regional sand processing collapses 1,200-mile Wisconsin rail hauls and erodes Northern White premium pricing. |
| Guaranteed Supply Program Structuring | Long-term offtake agreements transfer inventory risk from E&P balance sheets to supplier networks during drilling volatility. |
| Ceramic Proppant R&D Investment | Sintered bauxite conductivity advantages at 12,000 psi closure stress defend premium tier against lightweight substitution. |
Research Methodology
Bottom-up hydraulic fracturing operator modeling reconciled against top-down proppant supplier production tracking forms the analytical core of this study. Primary interviews with completion engineers, procurement managers at E&P companies, sand plant operations directors, and railroad logistics coordinators combined with secondary validation from EIA drilling statistics, EPA regulatory filings, SEC 10-K disclosures from listed suppliers, and API RP 19C certification databases. Triangulation across demand-side consumption patterns and supply-side capacity utilization ensures dimensional consistency.
Historical trendline analysis of proppant intensity per lateral foot, closure stress deployment patterns, and logistics cost structures informs the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, application stress environment, end-user procurement authority, and distribution channel proximity to well pads. CAGRs derive from bottom-up well count forecasts multiplied by proppant load assumptions, cross-checked against supplier revenue recognition patterns and railcar loading data.
The model assumes a particular technology adoption path for resin-coated proppant penetration; alternative pathways for lightweight ceramic substitution or regulatory relaxation of effluent standards would alter the outlook. Forecasts reflect base-case assumptions regarding Permian drilling economics, Wisconsin sand deposit depletion rates, and Class I railroad pricing discipline. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Desalter Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Well Completion Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
North America Wireline Services Market