
 Central Asia Oil and Gas Market | 2026-2036
Central Asia Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Central Asia Oil and Gas Market Outlook
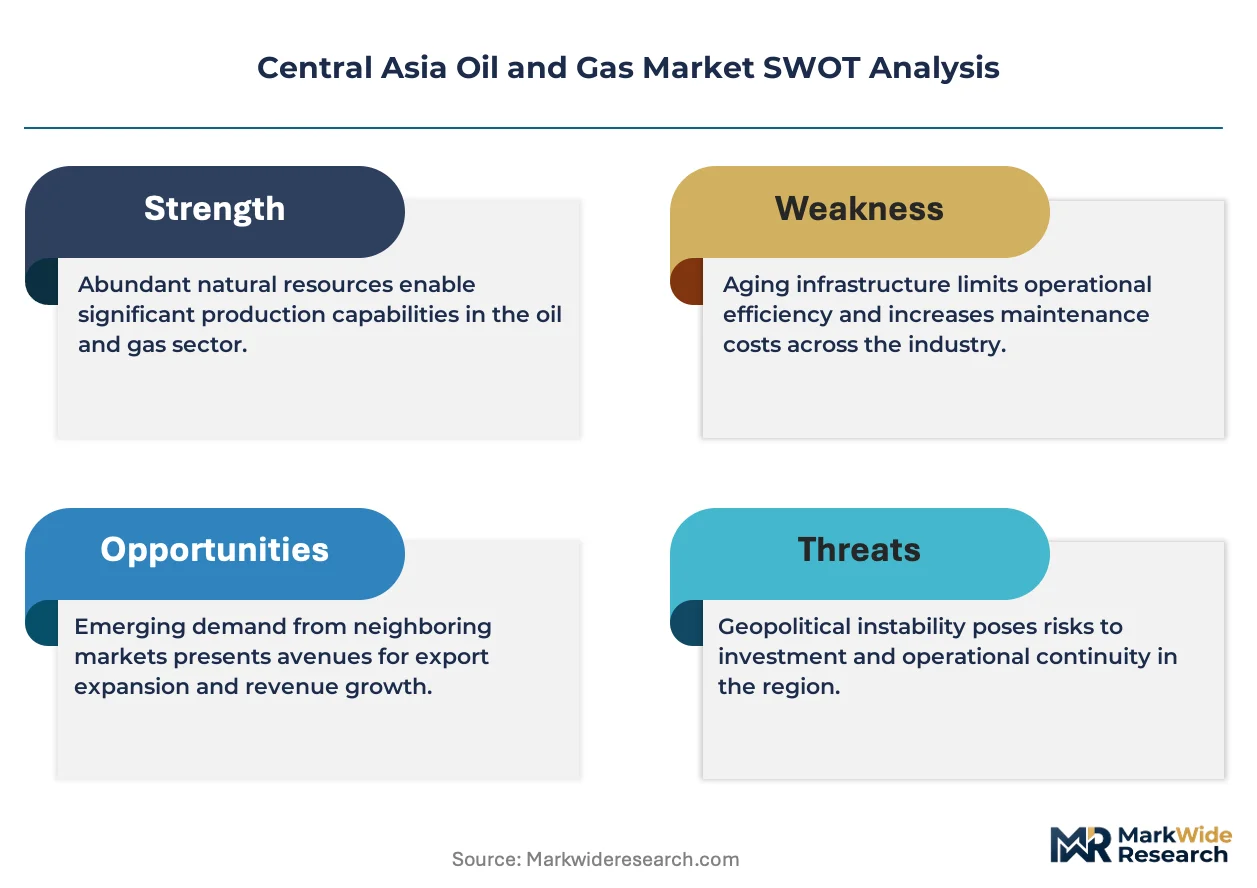
Higher API gravity sweet crude specifications are redrawing procurement priorities across Central Asian refineries. PJSC Lukoil Oil Company leverages its Caspian Pipeline Consortium stake to sustain volume commitments into Black Sea terminals. National Company JSC (KazMunayGas) anchors state-level production targets through direct equity in Kashagan and Tengiz megaprojects. Chevron Corporation competes on operational intensity, having occupied the Tengizchevroil leadership position for decades.
Central Asia oil and gas encompasses hydrocarbon extraction, processing, and transport infrastructure spanning onshore fields with reservoir depths from 1,500 to 5,500 meters and sulfur content ranging below 0.5% to above 4% by weight, serving power generation and petrochemical feedstock needs across Eurasian markets. Crude oil and natural gas together carry the bulk of regional export revenue, with gas liquids emerging as the fastest-growing product type due to NGL fractionation investments at Karachaganak and Tengiz. Pipeline delivery mode dominates cross-border movements, though rail capacity expansion into China offers structural diversification for volumes blocked from traditional westward routes.
Kazakhstan's Ministry of Energy administers subsoil use contracts under local content requirements that mandate procurement from domestic suppliers, while Turkmenistan's national gas regulator enforces offtake quotas prioritizing domestic chemical industry feedstock. China's National Development and Reform Commission coordinates import quota allocations that determine the effective ceiling for Central Asian gas deliveries through the Central Asia-China pipeline system. Stakeholders must weigh the durability of Russian transit alternatives against direct China-bound infrastructure commitments when committing capital to greenfield developments.
Market Dynamics
Refinery feedstock flexibility investments are compressing sweet-heavy crude price spreads across Central Asian processing corridors. Kazakhstan's subsoil code revisions and Turkmenistan's gas processing mandates are synchronizing upstream capital cycles with midstream export commitments.
Growth Catalysts
- Enhanced Oil Recovery:CO2 flooding and polymer injection techniques are extending plateau production at mature fields in the Tengiz corridor. Field operators deploy these methods to sustain reservoir pressure without drilling additional wells.
- Kazakhstan's Local Content Mandates:Subsoil use contracts require procurement from domestic suppliers, channeling fabrication and engineering spend toward Kazakh manufacturing clusters. This redirects supply chain margins toward domestic entities.
- Central Asia-China Pipeline Capacity:China's National Development and Reform Commission import quotas determine effective ceiling for Turkmen and Kazakh gas deliveries. Infrastructure expansion at the Uzbekistan-Kazakhstan border is removing compression bottlenecks.
Market Restraints
- High-Sulfur Crude Processing Costs:Kashagan's four percent sulfur content requires specialized metallurgy and sulfur recovery units. Refineries lacking coking capacity face yield penalties when processing these grades.
- Transit Route Concentration:Eighty percent of Kazakh crude moves through the Caspian Pipeline Consortium to Novorossiysk. Russian port capacity constraints and tariff negotiations create volume uncertainty for producers.
- Arid Region Water Scarcity:Thermal enhanced recovery and refinery cooling demand freshwater volumes that compete with agricultural irrigation. Desalination capex adds fifteen to twenty percent to field development economics.
Strategic Opportunities
- Uzbekistan's GTL and Chemicals Pivot:The country's national gas company prioritizes domestic chemical industry feedstock over raw gas exports. Methanol-to-olefins and urea-ammonia complexes absorb gas volumes previously committed to pipeline sales.
- Digital Twin Deployment:Real-time reservoir simulation integrated with predictive maintenance platforms is reducing unplanned downtime at Karachaganak. Operators model well performance to optimize artificial lift schedules.
- Rail Export Diversification:Kazakhstan Temir Zholy is expanding tank car fleets serving Chinese refineries at Dushanzi and Lanzhou. This offers structural hedge against Caspian transit disruptions.
Industry Challenges
- Specialized Welding and Metallurgy Skills:Sour service pipeline construction demands certified technicians for chromium-molybdenum steel joining. Training pipelines lag project ramp schedules by eighteen to twenty-four months.
- Legacy SCADA Integration:Soviet-era automation systems at Turkmenbashi and Atyrau refineries require protocol translation layers for modern distributed control systems. Cybersecurity hardening adds commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Asia Oil and Gas Market |
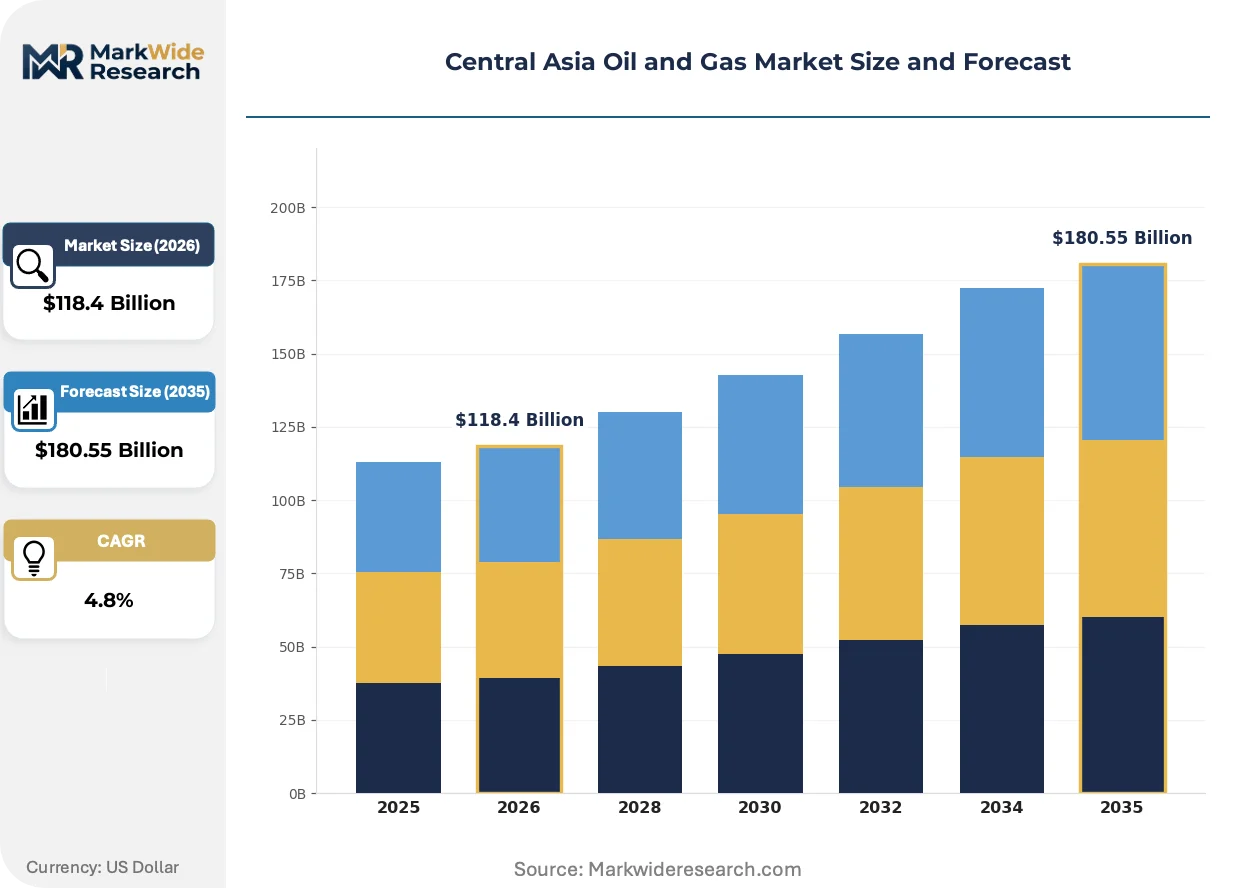
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $180.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Oil Products, Gas Liquids Delivery Mode: Pipelines, Tankers, Rail, Road End User: Utilities, Refineries, Industrial Users, Commercial Users Application: Power Generation, Heat Production, Transportation, Petrochemicals |
| Companies Covered | PJSC Lukoil Oil Company, JSC Turkmengaz, National Company JSC (KazMunayGas), National Company QazaqGaz JSC, Karachaganak Petroleum Operating BV, Chevron Corporation, Sinopec Oilfield Service Corporation, Intergas Central Asia JSC, Gazprom International Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Asia Oil and Gas Market Strategic Shifts
Modular processing equipment and remote monitoring architectures are redrawing field development economics across Central Asia's high-cost extraction environment. Technology adoption patterns cluster around sulfur management and export route optimization.
Modular gas processing units are miniaturizing. These skid-mounted NGL fractionation systems separate condensate and LPG at wellhead locations, eliminating gathering line construction. Tengiz operators deploy twelve-unit trains that reduce field installation time from eighteen months to four months. The technology is compressing capital intensity for marginal field development.
Kazakhstan's updated subsoil use code imposes stricter environmental liability provisions and abandonment fund requirements. Operators must escrow fifteen percent of field development costs for future site remediation. Greenfield projects in the Caspian offshore and Pre-Caspian basin absorb the heaviest compliance burden, with project timelines extending six to nine months for permit acquisition.
Chinese refiners are consolidating procurement authority at the provincial level, bypassing traditional trading house intermediaries. Sinopec and PetroChina now contract directly with Kazakh producers for fifteen-year term supply agreements. This disintermediation concentrates price negotiation leverage with three national oil companies and compresses trader margins on eastbound volumes.
Central Asia Oil and Gas Market Segmentation
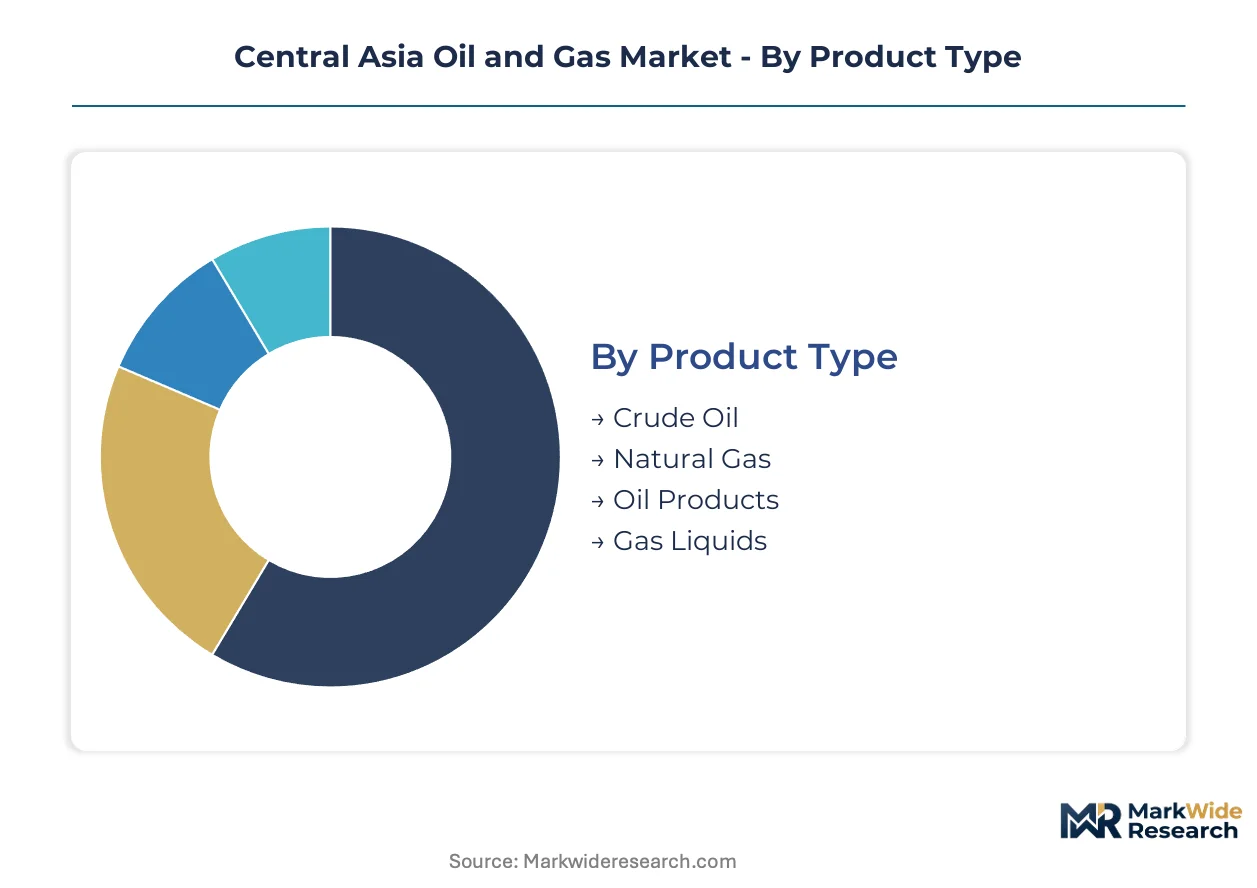
Segmentation in Central Asia's oil and gas market reveals how infrastructure constraints and export route dependencies shape commercial priorities. Product specifications, transport modalities, and end-use applications each carry distinct margin profiles and capital intensity requirements that determine investment allocation across the region's hydrocarbon corridors.
Product Type:
Substitution pressure runs strongest against conventional crude oil as gas liquids and refined products capture higher value per barrel in constrained export markets.
- Crude Oil:Sulfur content ranging from below 0.5% to above 4% by weight defines processing economics across Kazakhstan's Tengiz and Kashagan fields. Kazakhstan's Ministry of Energy subsoil use contracts channel the majority of upstream capital toward heavy sour grade development for Black Sea terminal export.
- Natural Gas:Reservoir depths from 1,500 to 5,500 meters in Turkmenistan's Amu Darya basin require specialized drilling packages. China's National Development and Reform Commission import quotas determine effective ceiling for Turkmen and Kazakh deliveries through the Central Asia-China pipeline system.
- Oil Products:Refined fuels including gasoline, diesel, and fuel oil move through regional distribution networks serving domestic transport and heating demand. Turkmenbashi and Atyrau refineries process primarily for captive supply of domestic industrial clusters.
- Gas Liquids:NGL fractionation investments at Karachaganak and Tengiz separate condensate and LPG for petrochemical feedstock. Modular skid-mounted units reduce field installation time from eighteen months to four months at marginal wellhead locations.
Crude oil anchors the volume base while gas liquids gains share at the steepest rate.
Delivery Mode:
Cost tier differentiation separates pipeline-dependent volumes from rail and road alternatives that absorb tariff and infrastructure risk premiums.
- Pipelines:The Caspian Pipeline Consortium moves eighty percent of Kazakh crude to Novorossiysk terminals. Compression bottlenecks at the Uzbekistan-Kazakhstan border constrain Central Asia-China gas pipeline throughput.
- Tankers:Caspian Sea marine terminals at Aktau and Turkmenbashi handle crude and refined product movements to Azerbaijan and Iran. Port capacity constraints create queuing delays during peak export windows.
- Rail:Kazakhstan Temir Zholy tank car fleets serve Chinese refineries at Dushanzi and Lanzhou. This modality offers structural hedge against Russian transit disruptions for volumes blocked from westward routes.
- Road:Tanker truck networks distribute refined products to remote industrial sites and commercial fueling stations. Road transport carries the highest per-ton-kilometer cost but reaches destinations beyond pipeline and rail nodes.
Pipelines dominate total throughput while rail climbs the fastest as producers diversify export dependence away from single-corridor concentration.
End User:
Application-driven demand splits between power sector offtake with long-term contract security and spot-exposed industrial consumption.
- Utilities:Power generation companies contract for natural gas under take-or-pay arrangements. Uzbekistan's national gas company prioritizes domestic chemical industry feedstock over raw gas exports to pipeline systems.
- Refineries:Processing facilities at Atyrau, Pavlodar, and Turkmenbashi demand specific API gravity and sulfur specifications. Feedstock flexibility investments compress sweet-heavy crude price spreads across Central Asian processing corridors.
- Industrial Users:Methanol-to-olefins and urea-ammonia complexes absorb gas volumes previously committed to export sales. Desalination capex adds fifteen to twenty percent to field development economics for thermal recovery operations.
- Commercial Users:Retail fuel stations and distributed heating systems purchase refined products through wholesale distribution networks. Local content mandates require procurement from domestic suppliers, redirecting supply chain margins toward Kazakh manufacturing clusters.
Refineries anchor the volume base while industrial users gain share at the steepest rate as downstream chemical capacity expands.
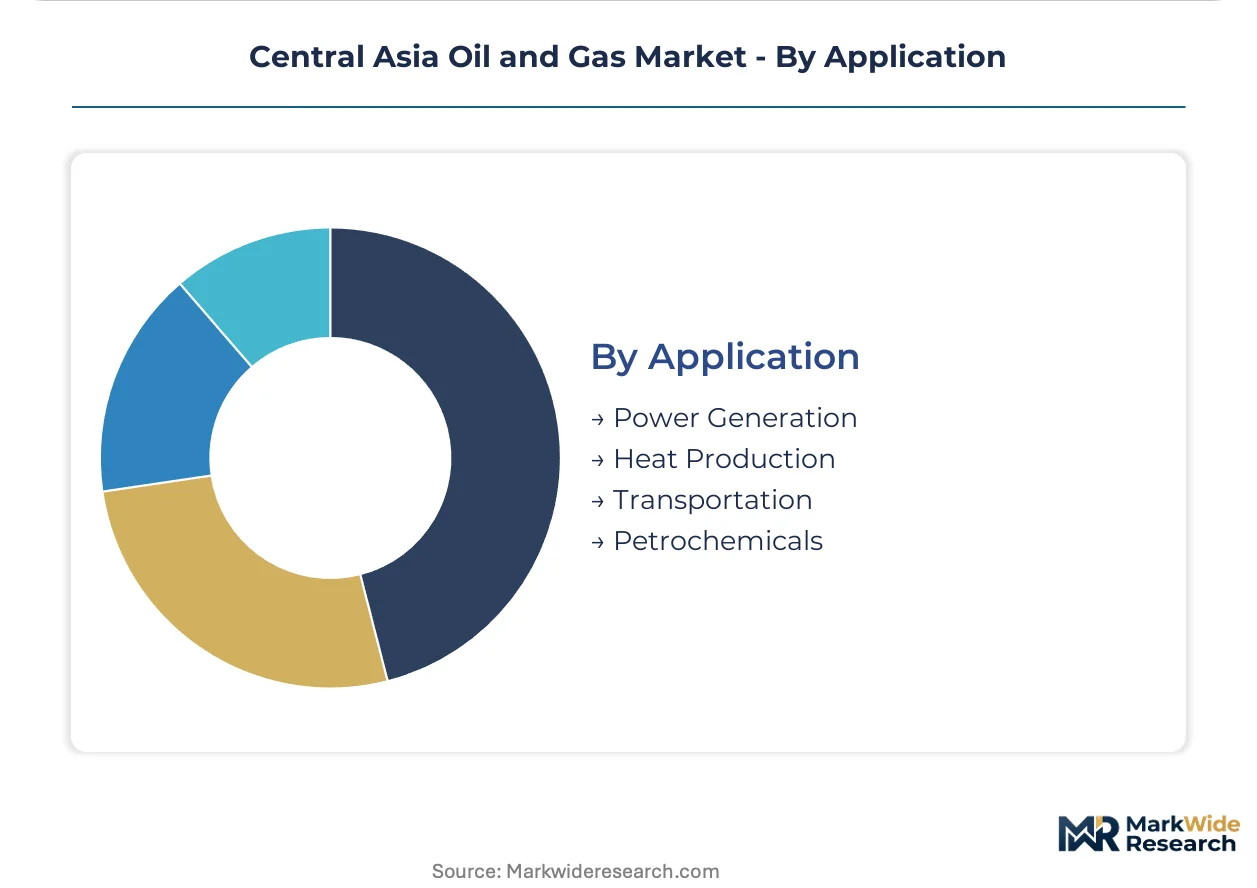
Application:
Customer type concentration varies by energy intensity, with petrochemical feedstock commanding premium pricing over combustion applications.
- Power Generation:Combined-cycle gas turbines and thermal coal plants compete for baseload electricity supply. CO2 flooding and polymer injection techniques extend plateau production at mature fields serving generation fuel demand.
- Heat Production:District heating systems in Kazakh and Uzbek cities consume natural gas and residual fuel oil. Arid region water scarcity forces tradeoffs between thermal enhanced recovery and agricultural irrigation.
- Transportation:Diesel and gasoline demand concentrates in Kazakhstan's urban corridors and long-haul trucking routes. Rail export diversification into China offers alternative supply security for transport fuel refineries.
- Petrochemicals:Ethylene, propylene, and aromatics production from NGL feedstock expands at Karachaganak and Tengiz fractionation complexes. Real-time reservoir simulation integrated with predictive maintenance platforms reduces unplanned downtime for feedstock supply reliability.
Power generation anchors the volume base while petrochemicals gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream capital clusters along Kazakhstan's Tengiz and Kashagan corridor, with field redevelopment absorbing the majority of investment. Turkmenistan's gas processing modernization and Uzbekistan's chemicals pivot reshape sub-regional export flows. Infrastructure constraints at compression stations and marine terminals create divergent cost structures across the five republics.
Kazakhstan
Tengiz and Kashagan megaprojects drive upstream capital allocation, with the Ministry of Energy administering subsoil use contracts under strict local content mandates. The updated subsoil use code imposes fifteen percent abandonment fund escrow requirements, extending greenfield permit timelines by six to nine months. The Atyrau-Pavlodar refinery corridor processes heavy sour grades for domestic supply and Black Sea export.
Turkmenistan
Amu Darya basin gas fields at 1,500 to 5,500 meter depths require specialized drilling packages for sustained plateau production. The national gas regulator enforces offtake quotas prioritizing domestic chemical industry feedstock over raw pipeline exports. Turkmenbashi refinery modernization and gas processing complexes at Bagtyyarlyk absorb capital previously directed toward volume expansion.
Uzbekistan
Methanol-to-olefins and urea-ammonia complexes redirect gas volumes from pipeline sales to captive chemical feedstock. The national gas company prioritizes domestic industrial clusters over export commitments through the Central Asia-China pipeline system. The Bukhara-Khiva corridor hosts GTL pilot projects testing synthetic fuel economics at scale.
China (Import Corridor)
The National Development and Reform Commission coordinates import quota allocations determining the effective ceiling for Central Asian gas deliveries. Compression bottleneck removal at the Uzbekistan-Kazakhstan border expands throughput capacity for Turkmen and Kazakh supply. Dushanzi and Lanzhou refineries source directly through fifteen-year term agreements, bypassing traditional trading intermediaries.
Azerbaijan (Transit Hub)
Caspian Sea marine terminals at Aktau connect Kazakh crude to Baku-Tbilisi-Ceyhan pipeline alternatives, diversifying export routes away from Russian port dependence. Port capacity constraints at Aktau create queuing delays during peak export windows. The Trans-Caspian corridor development remains contingent on upstream volume commitments from Kashagan offshore expansion.
Central Asia Oil and Gas Market Competitive Environment
Concentration sits with national oil companies holding direct equity in megaprojects and supermajors operating through production-sharing contracts. The competitive structure splits between state-backed upstream operators and international partners contributing technical intensity for complex reservoir development. Two archetypes dominate: integrated national champions controlling midstream export infrastructure, and technology-heavy international operators deploying enhanced recovery methods. Capacity expansion at Karachaganak and Tengiz, alongside strategic partnerships for digital twin deployment, represent the primary competitive moves reshaping positioning.
Among state-backed operators, National Company JSC (KazMunayGas) and JSC Turkmengaz anchor upstream production targets through direct equity stakes and regulatory control over export quotas. Chevron Corporation occupies a distinct position at the technology-intensive end, having sustained operational leadership at Tengizchevroil through decades of reservoir management. These three exemplify the bifurcation between state capital allocation and international technical partnership models.
| Leading Market Players |
|---|
| PJSC Lukoil Oil Company |
| JSC Turkmengaz |
| National Company JSC (KazMunayGas) |
| National Company QazaqGaz JSC |
| Karachaganak Petroleum Operating BV |
| Chevron Corporation |
| Sinopec Oilfield Service Corporation |
| Intergas Central Asia JSC |
| Gazprom International Limited |
| Others |
Value Chain & Pricing Dynamics
Kazakhstan's updated subsoil use code gates both supplier qualification and price differentiation simultaneously, mandating fifteen percent abandonment fund escrow requirements that compress margins for non-compliant operators while rewarding early adopters with preferential contract terms.
Pricing Analysis
Kazakhstan's Ministry of Energy subsoil use contract terms dictate the pricing tier structure across upstream development corridors. Three-tier pricing structure across premium, standard, and economy levels separates Tengiz sweet crude from Kashagan heavy sour grades and marginal field condensate. Cost compression in heavy sour processing is intensifying because specialized metallurgy requirements and sulfur recovery unit capex penalize refiners lacking coking capacity. National oil companies demonstrate the least price sensitivity due to state-backed offtake guarantees, while independent traders face acute margin pressure from direct Sinopec and PetroChina procurement consolidation.
Supply Chain Analysis
Caspian Pipeline Consortium throughput constraints at Russian Black Sea terminals underwrite supply vulnerability for eighty percent of Kazakh crude movements. Geographic supply concentration centers on Kazakhstan, Turkmenistan, and Uzbekistan as the primary hydrocarbon extraction nodes. Raw material dependencies draw from chromium-molybdenum steel for sour service pipelines, specialized drilling packages for Amu Darya basin depths, and modular NGL fractionation skids. Single-source vulnerability runs through the Novorossiysk port corridor where tariff negotiations and capacity limits create volume uncertainty. Distribution runs through pipeline trunk systems with rail diversification emerging as structural hedge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welding technicians for chromium-molybdenum steel joining represent the critical capability gap, with training pipelines lagging project ramp schedules by eighteen to twenty-four months and constraining field development velocity across the region.
For Market Incumbents: Compound operational intensity advantages at Tengizchevroil and Karachaganak through digital twin deployment and predictive maintenance platforms. Defend against Chinese direct procurement consolidation by deepening captive supply relationships with Kazakhstan Temir Zholy rail capacity. Prioritize backward integration into modular gas processing unit fabrication to capture local content mandate margins. For New Entrants and Emerging Players: Anchor in Uzbekistan's GTL and chemicals pivot where methanol-to-olefins complexes absorb gas volumes previously committed to pipeline exports. Target the Bukhara-Khiva corridor for synthetic fuel pilot project partnerships with the national gas company. Pursue fifteen-year term supply agreements with provincial-level Chinese refinery procurement authorities as the primary go-to-market pathway. For Investors and Strategic Acquirers: Kazakhstan's abandonment fund escrow requirement reshapes the acquisition landscape by extending greenfield permit timelines and elevating working capital intensity. Long-term viability favors operators with demonstrated reservoir management capabilities and existing production-sharing contract relationships. Monitor compression bottleneck removal progress at the Uzbekistan-Kazakhstan border as the inflection signal for Central Asia-China pipeline throughput expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Deployment | CO2 flooding at Tengiz extends plateau production without incremental drilling capex. |
| Modular Processing Unit Expansion | Skid-mounted NGL fractionation reduces Karachaganak field installation time by fourteen months. |
| Rail Export Diversification | Kazakhstan Temir Zholy tank car fleets hedge against Caspian Pipeline Consortium disruptions. |
| Digital Twin Integration | Real-time reservoir simulation cuts unplanned downtime at sour service operations. |
| Local Content Compliance | Domestic supplier mandates redirect fabrication margins toward Kazakh manufacturing clusters. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with field operations managers at Tengiz and Kashagan, procurement leads at Atyrau and Pavlodar refineries, pipeline logistics coordinators at the Caspian Pipeline Consortium, and reservoir engineers at Karachaganak Petroleum Operating. Secondary validation drew from Kazakhstan Ministry of Energy subsoil use contract disclosures, Turkmenistan national gas regulator offtake quota publications, China National Development and Reform Commission import quota allocations, and Central Asia-China pipeline throughput data. Bottom-up field-level production estimates and top-down regional demand projections were triangulated to anchor volume assumptions.
Across the analysis window, the forecast framework models segmentation by product type spanning crude oil, natural gas, oil products, and gas liquids; by delivery mode across pipeline, tanker, rail, and road; by end user covering utilities, refineries, industrial users, and commercial users; and by application including power generation, heat production, transportation, and petrochemicals. CAGRs were derived from production growth trajectories at named megaprojects, export capacity expansion timelines, and downstream chemical capacity commissioning schedules. Industry-specific inputs incorporated reservoir decline curves from mature fields and modular processing unit deployment rates at marginal wellhead locations.
Material uncertainties — upstream capital commitment delays, transit route tariff renegotiations, and Chinese import quota adjustments — sit outside the modeled envelope. Forecasts reflect assumptions documented in field operator guidance and regulatory disclosure filings. Practitioners should keep alternative scenarios live as subsoil use code enforcement patterns and Central Asia-China pipeline compression expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Well Cementing Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Oilwell Completion Tools Market