
 India Oil and Gas Midstream Market | 2026-2036
India Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
India Oil and Gas Midstream Market Foresight
Aftermarket service revenue across LNG regasification terminals is reconfiguring margin pools away from pure commodity throughput. GAIL (India) Ltd leverages its pipeline monopoly to sustain long-term take-or-pay contracts across the Hazira-Vijaipur-Jagdishpur network. Adani Total Gas Ltd anchors its position through exclusive city gas distribution licenses in multiple geographical areas. Indian Oil Corporation Ltd competes by integrating its refineries with captive pipeline and storage infrastructure.
India oil and gas midstream encompasses the transportation, storage, and processing of hydrocarbons between upstream production and downstream refining, operating through pipelines rated for pressures between 60-100 bar, cryogenic LNG storage at minus 162 degrees Celsius, and fractionation units separating natural gas liquids. The primary commercial purpose is to bridge temporal and spatial mismatches between production basins and consumption centers while preserving product integrity. Pipelines command the largest service type share due to their cost advantage over rail and road for bulk crude and natural gas movement. Storage facilities are gaining structural importance as strategic petroleum reserve mandates and LNG import dependency deepen tankage requirements. Refined products within the product type dimension carry thinner margins but higher throughput velocity compared to crude oil logistics.
The Petroleum and Natural Gas Regulatory Board sets pipeline tariffs and open access norms, while the Central Electricity Authority coordinates gas-based power plant connectivity to midstream networks. BIS standards govern pipeline metallurgy and pressure vessel construction, shaping procurement specifications for domestic fabricators. Compliance with these frameworks determines market access for new terminal developers and pipeline operators. Stakeholders must monitor regulatory shifts around third-party access obligations and LNG terminal licensing timelines to calibrate capital deployment across the midstream value chain.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's open access regulations are dismantling pipeline monopolies and forcing incumbents to surrender capacity to third-party shippers, fundamentally altering how transportation economics are captured across the midstream value chain.
Growth Catalysts
- City Gas Distribution Mandates:The government's push to expand piped natural gas to households and commercial establishments under the CGD bidding rounds is pulling LNG through import terminals at Hazira, Dahej, and Kochi.
- Fertilizer Sector Expansion:Urea manufacturers are converting from naphtha to natural gas feedstock, creating dedicated offtake agreements with LNG regasification facilities.
- Strategic Petroleum Reserve Buildout:Underground rock cavern storage at Vishakhapatnam, Mangalore, and Padur is expanding crude tankage capacity under Indian Strategic Petroleum Reserves Ltd mandates.
Market Restraints
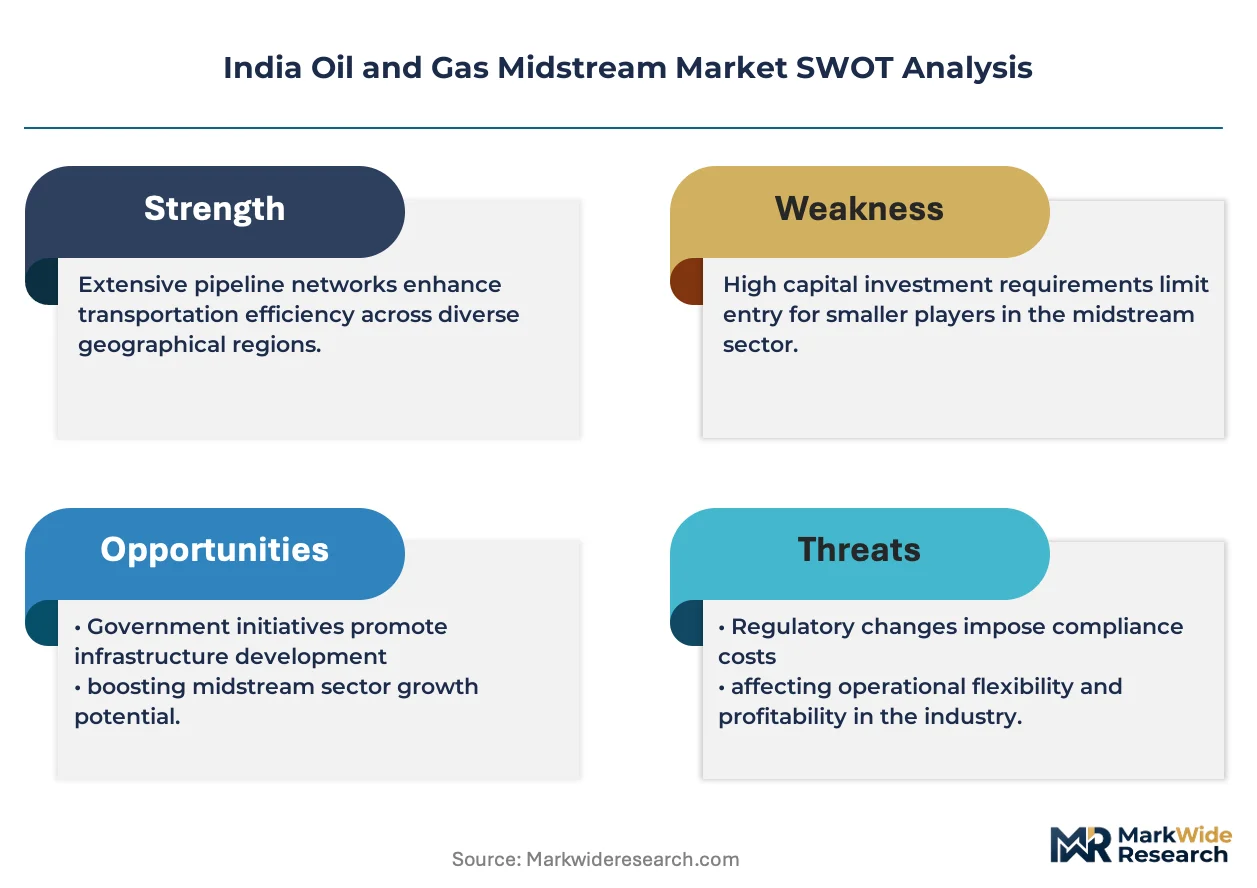
- Pipeline Tariff Disputes:The Petroleum and Natural Gas Regulatory Board's tariff-setting methodology creates revenue uncertainty for greenfield pipeline developers awaiting regulatory approval.
- Import Dependency Concentration:Over 45 percent of natural gas consumption relies on LNG cargoes from Qatar, exposing terminal operators to shipping rate volatility and geopolitical supply interruptions.
- Domestic Pipeline Fabrication Constraints:BIS-certified steel mills face capacity bottlenecks for high-grade API 5L line pipe, extending procurement timelines for cross-country projects.
Strategic Opportunities
- North-East Connectivity Gap:The Indradhanush Gas Grid project targets seven north-eastern states currently isolated from the national pipeline network, offering first-mover terminal and trunk line positioning.
- Small-Scale LNG Distribution:Cryogenic road tankers and satellite regasification units can serve industrial clusters beyond pipeline reach, particularly in Rajasthan and Odisha.
- Hydrogen Blending Infrastructure:Existing high-pressure natural gas pipelines can accommodate hydrogen admixtures up to 10 percent by volume, positioning midstream operators for energy transition services.
Industry Challenges
- Right-of-Way Acquisition Delays:Land aggregation for pipeline corridors across agricultural holdings triggers protracted negotiations with state revenue departments and district collectors.
- Welding Inspector Certification Backlogs:ASME-certified welding inspectors and radiographic testing technicians remain scarce, slowing commissioning schedules for pressure-rated infrastructure.
- Legacy SCADA Integration:Brownfield pipeline networks require cybersecurity retrofits to meet Central Electricity Authority guidelines for critical energy infrastructure protection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Oil and Gas Midstream Market |
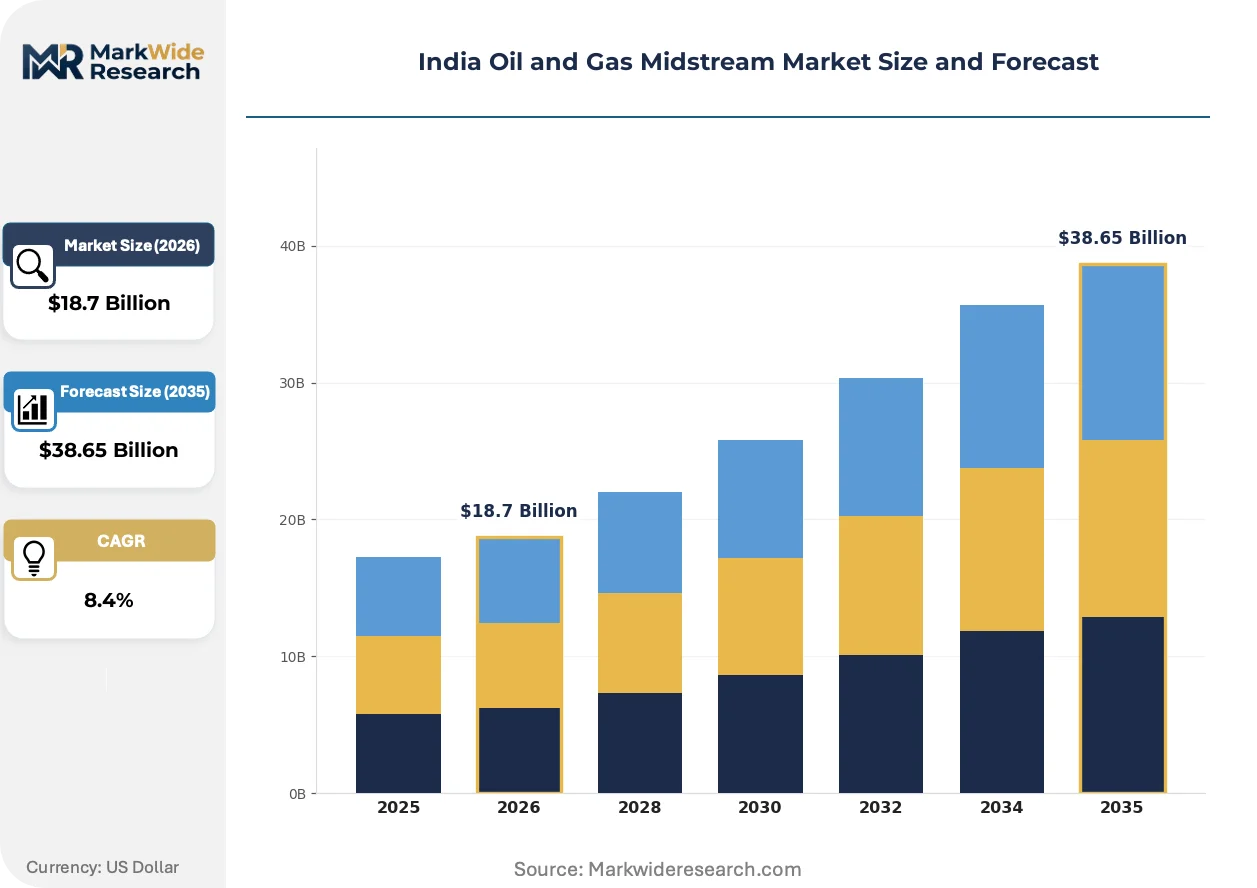
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pipelines, Storage Facilities, Transportation, Processing End User: Utilities, Industrial, Commercial, Government Product Type: Natural Gas, Crude Oil, Refined Products, Liquefied Gas Installation: Onshore, Offshore, Terminal, Depot |
| Companies Covered | Bharat Petroleum Corp Ltd, Aegis Logistics Ltd, GAIL (India) Ltd, Adani Enterprises Ltd, Adani Total Gas Ltd, Petronet LNG Ltd, Hindustan Petroleum Corp Ltd, Mahanagar Gas Ltd, Indian Oil Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Oil and Gas Midstream Market Shifts & Advancements
Digital instrumentation and predictive analytics are penetrating hydrocarbon logistics, compressing inspection cycles and enabling condition-based maintenance across aging pipeline networks and cryogenic storage assets.
Pipeline integrity management systems incorporating fiber-optic leak detection and drone-based right-of-way surveillance are digitizing risk assessment protocols. GAIL and Indian Oil Corporation are deploying these platforms across the HVJ and Salaya-Mathura networks. The technology is digitizing how operators prioritize cathodic protection upgrades and excavation damage prevention.
The Petroleum and Natural Gas Regulatory Board's third-party access regulations now mandate common carrier obligations for all transmission pipelines above a defined diameter threshold. This policy is fragmenting long-term ship-or-pay contracts into shorter-term, interruptible service agreements. Gujarat-based industrial consumers are responding by aggregating demand through gas pooling mechanisms to secure pipeline capacity.
Industrial buyers are unbundling terminal services from commodity procurement, contracting regasification capacity separately from LNG cargo purchases. This decoupling is displacing integrated supply contracts at Dahej and Hazira terminals. Fertilizer manufacturers in Maharashtra and steel producers in Odisha are driving this shift toward tolling-based commercial structures.
India Oil and Gas Midstream Market Segmentation
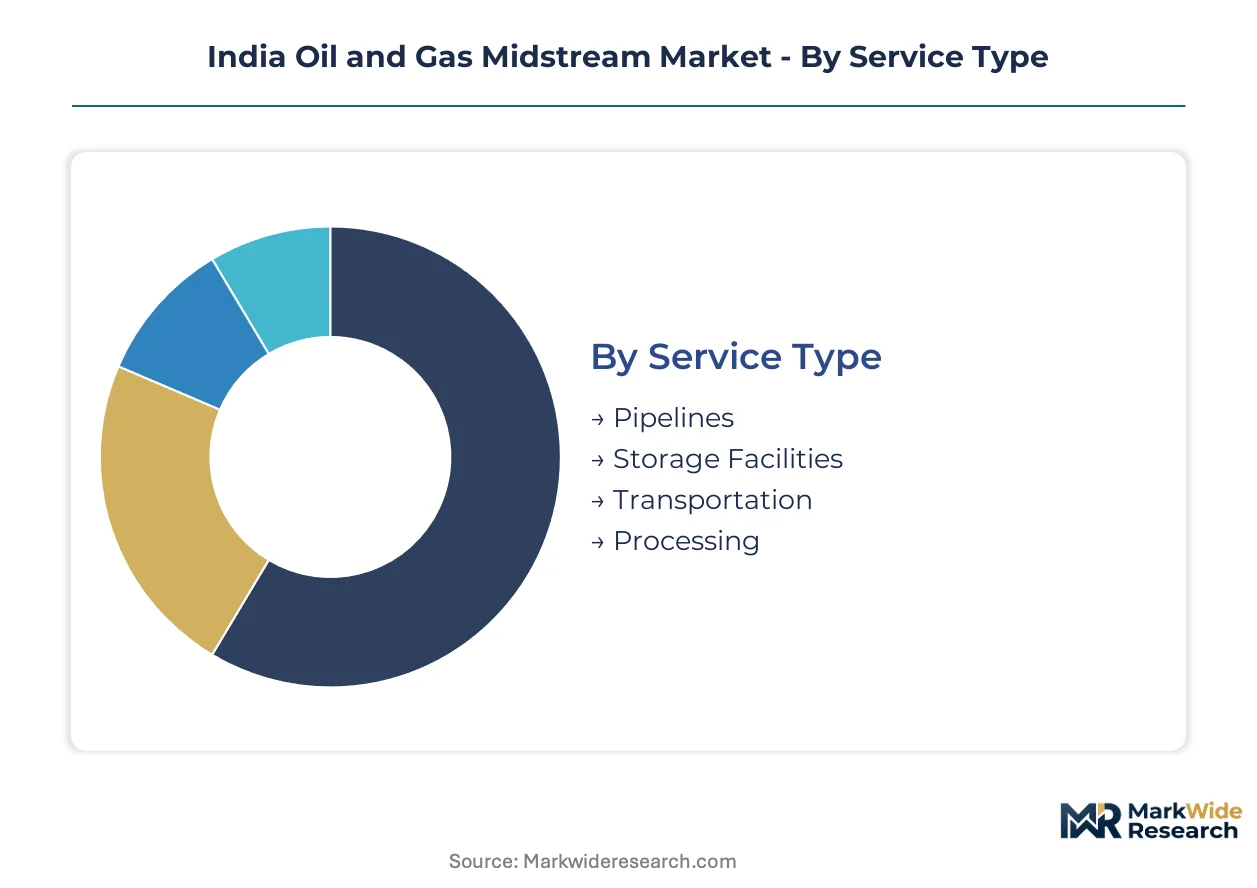
Segmentation in India's oil and gas midstream reveals how capital intensity and regulatory exposure vary across infrastructure types. Service configurations determine maintenance contract structures and equipment replacement cycles. Product characteristics dictate storage specifications and pipeline metallurgy requirements.
Service Type:
Aftermarket service intensity runs highest where pressure-rated equipment operates continuously and failure carries safety or supply consequences.
- Pipelines:High-pressure steel networks rated for 60-100 bar transport crude and natural gas across thousands of kilometers. Demand concentrates along Gujarat's industrial corridor where Hazira-Vijaipur-Jagdishpur trunk lines feed fertilizer complexes and city gas distribution zones. The Petroleum and Natural Gas Regulatory Board's open access mandates are fragmenting long-term contracts into shorter-term, interruptible service agreements.
- Storage Facilities:Cryogenic LNG tanks at minus 162 degrees Celsius and underground rock caverns preserve product integrity across temporal demand mismatches. Strategic Petroleum Reserve buildout at Vishakhapatnam, Mangalore, and Padur is expanding crude tankage capacity under Indian Strategic Petroleum Reserves Ltd mandates. BIS standards govern pressure vessel construction and cathodic protection specifications.
- Transportation:Rail and road logistics bridge pipeline gaps for remote industrial clusters and emergency supply scenarios. Rajasthan and Odisha industrial zones rely on cryogenic road tankers where pipeline networks remain undeveloped.
- Processing:Fractionation units separate natural gas liquids into component streams for petrochemical feedstock. Dahej and Hazira terminal complexes host integrated processing infrastructure serving Maharashtra's chemical manufacturing belt.
By volume, Pipelines leads. By growth pace, Storage Facilities is ahead.
End User:
Customer procurement sophistication ranges from standardized utility tenders to complex multi-year industrial offtake negotiations.
- Industrial:Fertilizer manufacturers and steel producers drive dedicated pipeline connections and LNG terminal capacity bookings. Urea producers converting from naphtha to natural gas feedstock are signing firm take-or-pay contracts with regasification terminals.
- Utilities:Gas-based power plants and city gas distribution entities require interruptible supply flexibility. The Central Electricity Authority coordinates grid connectivity for gas-fired generation assets.
- Commercial:Hotels, hospitals, and educational institutions consume piped natural gas through localized distribution networks. CGD bidding rounds are expanding household and commercial connections in Maharashtra's urban centers.
- Government:Defense establishments and strategic reserve operators mandate supply security protocols exceeding commercial standards. Indian Strategic Petroleum Reserves Ltd manages crude stockpiling for emergency release scenarios.
Industrial users command the largest volume share. Commercial connections are expanding most quickly as CGD networks proliferate.
Product Type:
Physical state and vapor pressure determine containment specifications and transportation economics across the midstream chain.
- Natural Gas:Methane-rich streams require compression and dehydration before pipeline injection or cryogenic liquefaction for marine transport. LNG import terminals at Dahej, Hazira, and Kochi handle over 45 percent of national consumption, exposing operators to shipping rate volatility.
- Crude Oil:Unrefined hydrocarbon mixtures with varying sulfur content and API gravity flow through heated pipelines or tanker vessels. Strategic reserve caverns store imported crude for supply disruption contingencies.
- Refined Products:Gasoline, diesel, and kerosene move through product pipelines with dedicated batch sequencing to prevent contamination. Thinner margins but higher throughput velocity characterize this logistics segment compared to crude handling.
- Liquefied Gas:LPG and petrochemical feedstocks require pressurized or refrigerated storage depending on composition. Terminal infrastructure at major ports handles import and coastal distribution.
Natural Gas dominates current throughput. Refined Products infrastructure is gaining share fastest as consumption centers multiply.
Installation:
Site characteristics determine construction methodologies, regulatory permitting pathways, and operational risk profiles.
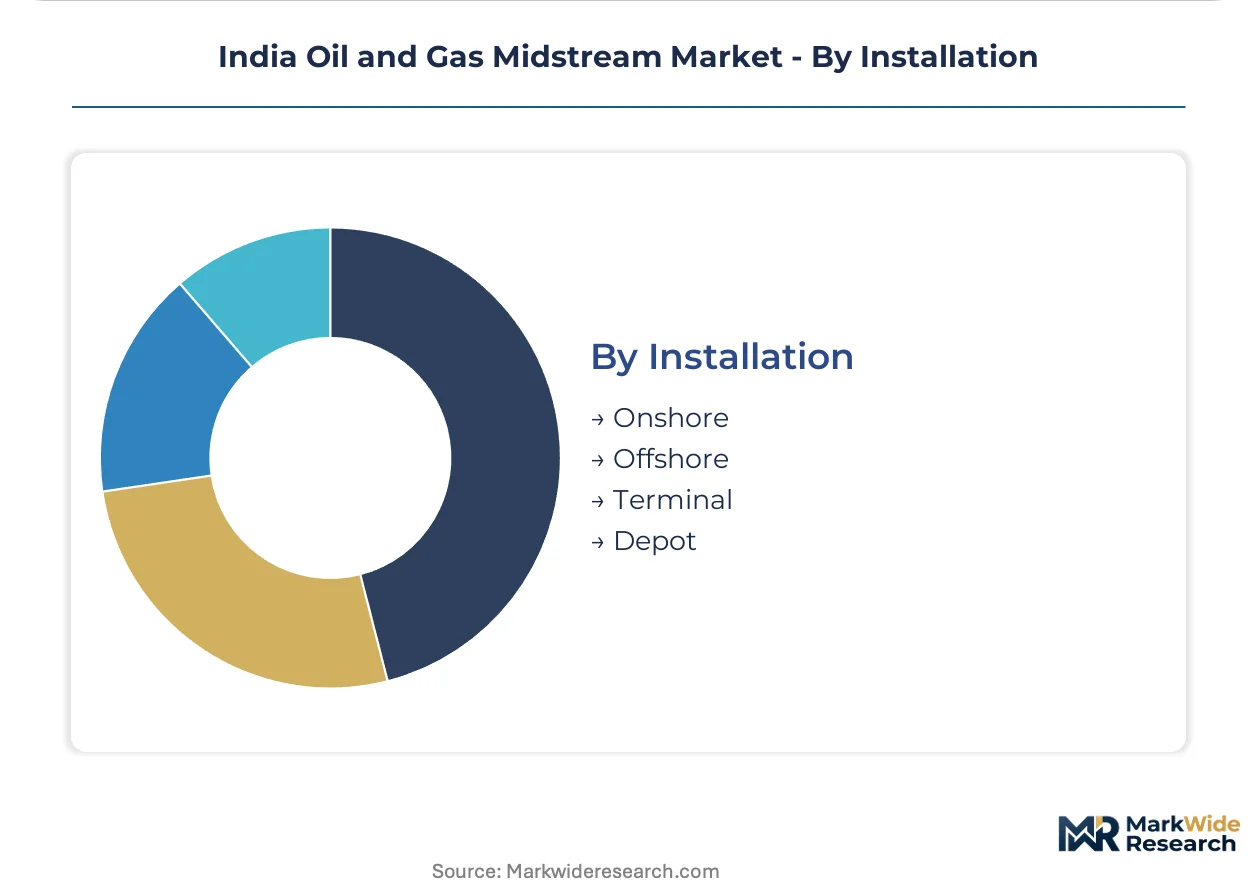
- Onshore:Cross-country pipelines and above-ground storage terminals traverse agricultural holdings and industrial zones. Right-of-way acquisition across state revenue jurisdictions triggers protracted negotiations with district collectors.
- Offshore:Subsea pipelines and platform-connected infrastructure link coastal terminals to deepwater port facilities. Corrosion protection and marine growth management dominate maintenance protocols.
- Terminal:Integrated receipt, storage, and dispatch facilities at Dahej, Hazira, and Kochi aggregate LNG cargoes for national distribution. Regasification capacity is increasingly unbundled from commodity procurement under tolling-based commercial structures.
- Depot:Refined product distribution points and satellite LNG storage units serve localized demand clusters beyond main pipeline networks. Small-scale cryogenic installations are penetrating Rajasthan and Odisha industrial corridors.
Onshore installations carry the greatest asset base. Terminal infrastructure is climbing the fastest as LNG import dependency deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline throughput concentrates in western and central India where industrial corridors align with trunk line geography. The Hazira-Vijaipur-Jagdishpur network and Gujarat's LNG terminal cluster process the majority of national hydrocarbon flows. State-level regulatory variations and right-of-way acquisition timelines create divergent investment climates across sub-regional markets.
Gujarat
Hazira and Dahej LNG terminals anchor import capacity serving fertilizer manufacturers and city gas distribution networks. The state's Industrial Policy incentivizes petrochemical complexes along the Gulf of Khambhat corridor. Mundra and Kandla port zones host integrated storage and pipeline infrastructure feeding northern hinterlands.
Maharashtra
Mumbai and Thane metropolitan zones drive city gas distribution penetration through piped natural gas mandates. The Maharashtra Natural Gas Distribution network extends into Pune and Nashik industrial belts. Ratnagiri coastal terminals handle refined product imports for western India consumption centers.
Andhra Pradesh
Kakinada deepwater port and surrounding Krishna-Godavari basin infrastructure process domestic natural gas production. The Visakhapatnam Strategic Petroleum Reserve caverns provide emergency crude storage under Indian Strategic Petroleum Reserves Ltd mandates. Vijayawada-Guntur industrial corridors attract pipeline spur investments.
Tamil Nadu
Ennore LNG terminal and Manali refinery complex anchor midstream capacity serving southern peninsula markets. Chennai metropolitan gas distribution networks expand through CGD bidding round allocations. Tuticorin port handles coastal refined product movements to Kerala and Karnataka.
Assam and the North-East
The Indradhanush Gas Grid project targets seven north-eastern states currently isolated from national pipeline networks. Guwahati and Numaligarh refinery zones provide localized processing capacity. Barauni-Guwahati pipeline extensions face protracted right-of-way negotiations across agricultural holdings.
India Oil and Gas Midstream Market Competitive Landscape
Integrated energy conglomerates and specialized gas infrastructure operators split the market between pipeline dominance and terminal specialization. The competitive structure reflects regulatory moats around city gas distribution licenses and long-term take-or-pay pipeline contracts. Three archetypes prevail: state-owned integrated oil companies leveraging refinery-pipeline integration, pure-play gas transporters with trunk line monopolies, and city gas distribution specialists with exclusive geographical licenses. Capacity expansion and regulatory capture through CGD bidding rounds constitute the dominant competitive moves.
Among state-owned integrated operators, Indian Oil Corporation Ltd and Bharat Petroleum Corp Ltd exemplify the refinery-anchored archetype with captive pipeline and storage infrastructure. GAIL (India) Ltd occupies the national gas transporter position with trunk line dominance across the Hazira-Vijaipur-Jagdishpur network. Adani Total Gas Ltd represents the specialized city gas distribution model with exclusive licenses in multiple geographical areas.
| Leading Market Players |
|---|
| Bharat Petroleum Corp Ltd |
| Aegis Logistics Ltd |
| GAIL (India) Ltd |
| Adani Enterprises Ltd |
| Adani Total Gas Ltd |
| Petronet LNG Ltd |
| Hindustan Petroleum Corp Ltd |
| Mahanagar Gas Ltd |
| Indian Oil Corporation Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity at Dahej and Hazira LNG terminals is compressing regasification tariffs and forcing terminal operators to unbundle capacity contracts from commodity procurement, reshaping how midstream service providers capture value across the value chain.
Pricing Analysis
Aftermarket service revenue from compressor overhauls and cryogenic maintenance contracts drives lifetime value for terminal operators more than pure throughput fees. Three-tier pricing structure across firm, interruptible, and spot capacity bookings differentiates industrial offtakers from utility buyers. Cost compression in interruptible tiers is intensifying because fertilizer manufacturers are aggregating demand through gas pooling mechanisms. City gas distribution entities show highest price sensitivity due to regulatory tariff ceilings, while steel producers accept premium firm capacity for supply security.
Supply Chain Analysis
Upstream LNG feedstock draws from Qatar, the United States, and Australia, with long-term supply contracts anchoring cargo schedules to Indian terminal slots. High-grade API 5L line pipe, cryogenic storage membranes, and subsea umbilicals constitute critical imported inputs. Single-source vulnerability concentrates in ASME-certified welding inspector labor pools, slowing project commissioning. Distribution runs through pipeline trunk networks feeding regional industrial clusters, with cryogenic road tankers bridging gaps in Rajasthan and Odisha.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as third-party access regulations dismantle pipeline monopolies and create entry points for specialized operators in underserved industrial corridors and city gas distribution zones.
For Market Incumbents: Pre-empt regulatory displacement by securing exclusive city gas distribution licenses in upcoming CGD bidding rounds before competitors aggregate demand. Deepen backward integration into cryogenic equipment maintenance capabilities to capture aftermarket revenue streams that pure commodity handlers cannot match. Anchor long-term viability through strategic petroleum reserve management contracts with Indian Strategic Petroleum Reserves Ltd.
For New Entrants and Emerging Players: Establish a beachhead in small-scale LNG distribution for industrial clusters beyond pipeline reach in Rajasthan and Odisha. Target tolling-based regasification contracts with fertilizer manufacturers converting from naphtha to natural gas feedstock. Deploy modular satellite regasification units as a go-to-market angle to bypass trunk line infrastructure gaps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across LNG terminal infrastructure as regasification capacity expands faster than throughput growth. Acquisition targets should display pipeline right-of-way secured across agricultural corridors or exclusive CGD geographical area licenses with household connection mandates. Monitor Petroleum and Natural Gas Regulatory Board tariff determinations for greenfield projects as the inflection signal for developer profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands regasification throughput at Dahej and Hazira to serve fertilizer sector conversion from naphtha. |
| Backward Integration | Captures cryogenic maintenance and compressor overhaul revenue streams from LNG terminal operations. |
| Long-term Supply Agreement | Secures dedicated LNG cargo schedules with Qatar and US suppliers for terminal utilization guarantees. |
| Joint Venture | Combines pipeline infrastructure with city gas distribution licenses across Maharashtra industrial belts. |
| Green Certification Program | Positions hydrogen blending infrastructure for 10% admixture in existing high-pressure natural gas networks. |
Research Methodology
Desk research of Petroleum and Natural Gas Regulatory Board tariff orders, BIS construction standards, and Central Electricity Authority grid connectivity guidelines preceded structured interviews with pipeline project developers, LNG terminal operators, fertilizer procurement managers, and city gas distribution license holders. Secondary validation drew from Indian Strategic Petroleum Reserves Ltd capacity disclosures, GAIL annual reports, and CGD bidding round documentation. Bottom-up capacity utilization models and top-down national gas demand projections were triangulated to anchor volume estimates.
Assumptions around regulatory adherence to open access timelines and LNG import dependency ratios were held fixed while domestic production trajectories from Krishna-Godavari basin fields were varied across scenarios. Segmentation modeling spanned service type, end user archetype, product physical state, and installation geography. CAGRs were derived from regression analysis against industrial production indices and fertilizer sector capacity expansion plans.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates or global LNG spot pricing would shift the trajectory for import terminal economics. Forecasts reflect assumptions around right-of-way acquisition timelines and welding inspector certification throughput. Quarterly review of Petroleum and Natural Gas Regulatory Board licensing decisions and CGD bidding round outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Whipstocks Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Global Floating LNG Terminal Market