
 US Oil and Gas Analytics Market | 2026-2036
US Oil and Gas Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
US Oil and Gas Analytics Market Analysis
Market Context
US shale producers is realigning capital deployment toward digital twins and edge computing infrastructure. Schlumberger leverages its integrated drilling platform to anchor software subscriptions across the Permian and Bakken. Baker Hughes competes through specialized turbomachinery diagnostics that extend asset life cycles. ConocoPhillips dominates the independent operator segment with proprietary subsurface analytics that reduce exploration risk.
Technical Definition and Structural Segments
US Oil and Gas Analytics encompasses the collection, processing, and interpretation of subsurface, operational, and market data to optimize hydrocarbon extraction, processing, and logistics decisions. The discipline integrates seismic imaging resolution below ten meters, real-time sensor streams from downhole tools, and stochastic reservoir simulation to maximize recovery factors and minimize non-productive time. Big Data infrastructure occupies the largest service spend as operators aggregate decades of well logs, completion designs, and production histories into queryable lakes. Artificial Intelligence applications in production optimization represent the fastest-expanding technology segment, with machine learning models now predicting equipment failures seventy-two hours in advance across major basins. Cloud Computing deployment lags in offshore environments where satellite bandwidth constraints persist, though managed services contracts are displacing on-premise installations among mid-cap producers seeking operational expenditure flexibility.
Regulatory Frame and Outlook
EPA methane emissions standards under the Inflation Reduction Act impose granular monitoring and reporting obligations that drive demand for continuous emissions analytics and leak detection algorithms. FERC pipeline safety directives require real-time pressure and flow surveillance, reinforcing software procurement across interstate transmission networks. OSHA process safety management rules intersect with state-level Texas Railroad Commission field regulations to create overlapping compliance datasets that operators must reconcile through unified analytics platforms. Stakeholders should monitor how EPA enforcement intensity and state primacy disputes over Class VI carbon sequestration permitting reshape the addressable market for emissions verification tools.
Market Dynamics
Upstream operators in the Permian Basin are accelerating predictive maintenance adoption as EPA methane monitoring rules and AI-driven reservoir modeling reshape procurement priorities. Supermajors and independents now deploy real-time drilling analytics at scale, forcing vendors to integrate emissions verification directly into production optimization platforms.
Growth Catalysts
- EPA Methane Emissions Standards:The Inflation Reduction Act imposes granular monitoring obligations that drive continuous emissions analytics demand. Leak detection algorithms now anchor software procurement cycles.
- Edge Computing Infrastructure:Real-time sensor streams from downhole tools require localized processing power. Operators aggregate decades of well logs into queryable lakes for stochastic reservoir simulation.
- Permian Basin Concentration:Texas supermajors deploy digital twins at scale, creating reference architectures that mid-cap producers replicate. This geographic density accelerates technology diffusion.
Market Restraints
- Satellite Bandwidth Constraints:Cloud computing deployment lags in offshore environments where connectivity limitations persist. Managed services contracts displace on-premise installations only among land-based operators.
- Legacy System Integration Costs:Decades of proprietary subsurface data formats resist standardization. Operators face expensive middleware development to unify compliance datasets.
- Specialized Talent Scarcity:Machine learning engineers with petroleum domain expertise command premium compensation. Universities produce insufficient graduates trained in both geoscience and data science.
Strategic Opportunities
- Class VI Carbon Sequestration Permitting:State primacy disputes over EPA enforcement create demand for emissions verification tools. Analytics vendors can anchor platforms around sequestration site monitoring.
- Bakken Shale Expansion:North Dakota operators lag Permian digital maturity. Predictive maintenance adoption rates remain below basin potential, opening white space for first-mover platforms.
- FERC Pipeline Safety Directives:Real-time pressure and flow surveillance mandates reinforce software procurement across interstate transmission networks. Midstream operators seek unified compliance platforms.
Industry Challenges
- OSHA Process Safety Management Overlap:Texas Railroad Commission field regulations create redundant compliance datasets. Operators must reconcile overlapping rules through unified analytics platforms.
- Seismic Imaging Resolution Limits:Subsurface uncertainty below ten meters persists despite computational advances. Machine learning models require extensive calibration against ground-truthed production histories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Oil and Gas Analytics Market |
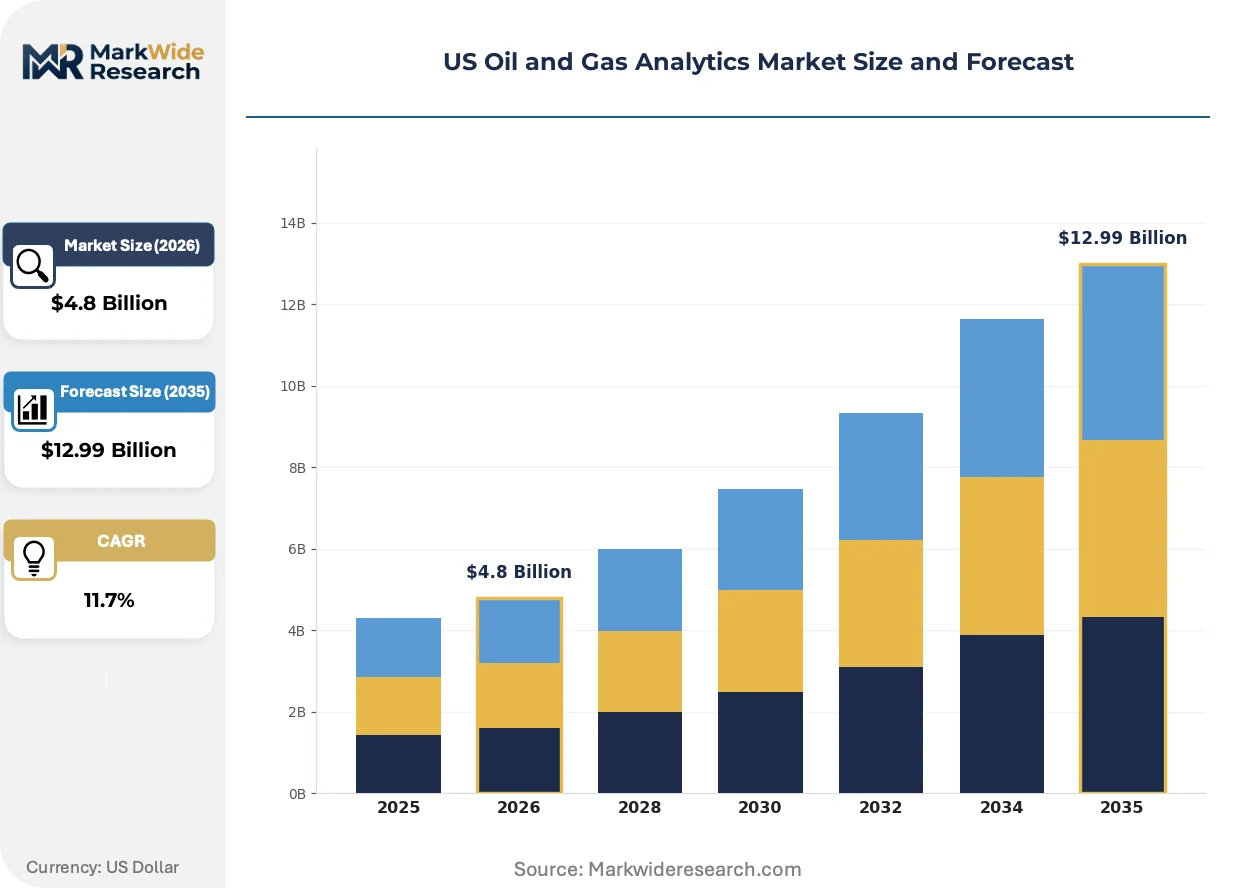
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Exploration, Production, Refining, Distribution Technology: Big Data, Artificial Intelligence, Cloud Computing, Machine Learning Service Type: Consulting, Software, Managed Services, Maintenance End User: Oil Operators, Gas Producers, Regulators, Energy Traders |
| Companies Covered | ConocoPhillips, Baker Hughes, Halliburton, BP, Weatherford, ExxonMobil, Schlumberger, Shell, Chevron, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Oil and Gas Analytics Market Emerging Trajectories
Artificial intelligence applications now predict equipment failures seventy-two hours in advance across major basins, compressing maintenance windows and reducing non-productive time. This capability is forcing vendors to rearchitect platforms around prescriptive rather than descriptive analytics.
Machine learning models trained on turbomachinery vibration signatures are automating diagnostic workflows that previously required specialist interpretation. Mid-cap producers in the Eagle Ford Shale adopt these tools fastest, eliminating reliance on external engineering consultants. The technology is automating root-cause analysis for pump failures, collapsing response times from days to hours.
EPA enforcement intensity under the Inflation Reduction Act mandates continuous emissions monitoring rather than periodic surveys. Operators must deploy optical gas imaging integrated with production databases for automated reporting. The Permian Basin faces the steepest compliance curve, driving fastest adoption of methane analytics modules.
Subscription pricing for drilling optimization software displaces perpetual licenses as operators seek operational expenditure flexibility. Independent producers in the Anadarko Basin now demand usage-based contracts tied to wells drilled rather than enterprise seats. This procurement model shift favors vendors with cloud-native architectures over legacy on-premise platforms.
US Oil and Gas Analytics Market Segmentation
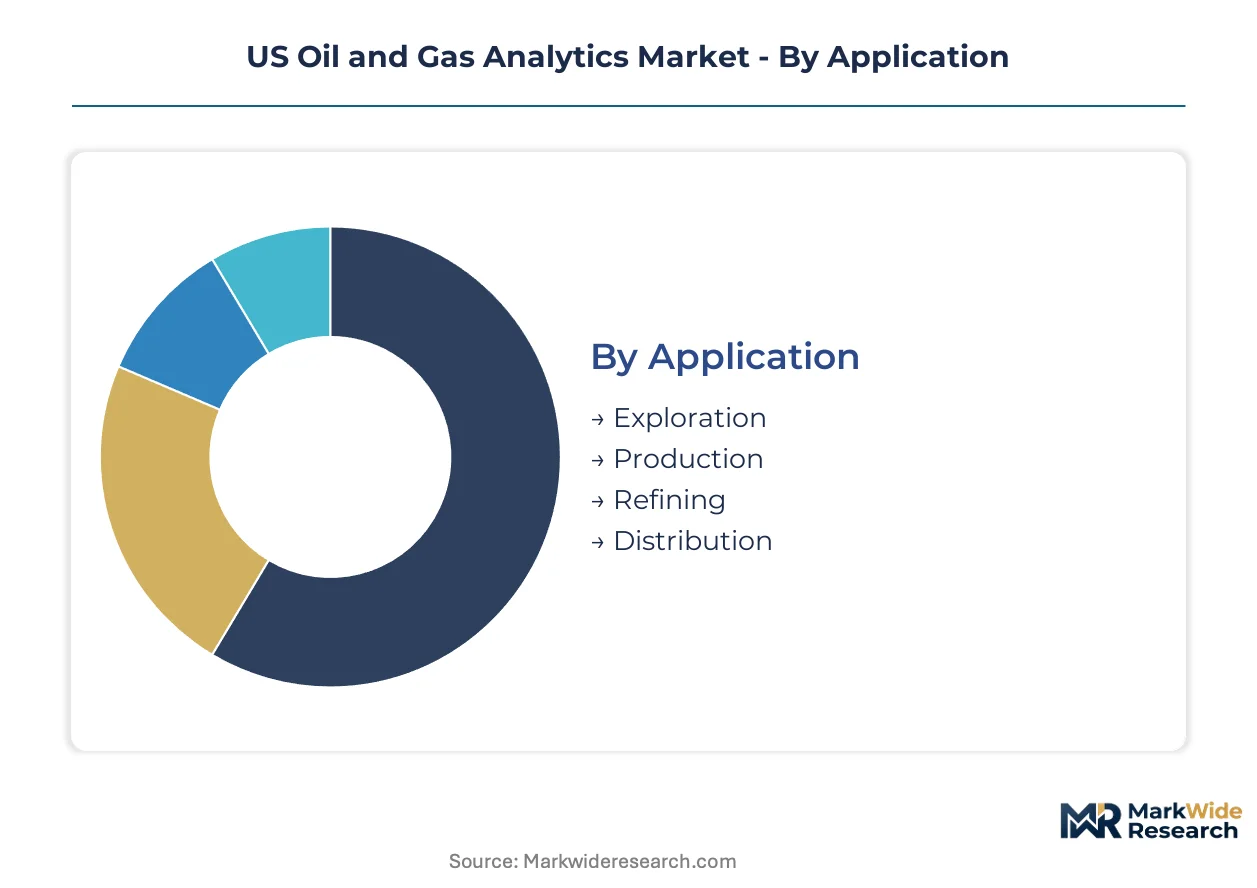
Analytics procurement patterns diverge sharply across upstream, midstream, and downstream operations. Each application layer demands distinct data architectures, compliance integrations, and vendor relationships that reshape competitive positioning.
Application:
Volume deployment concentrates in production optimization, while premium pricing attaches to exploration risk reduction.
- Exploration:Seismic imaging resolution below ten meters combines with stochastic reservoir simulation to reduce dry-hole risk. Permian Basin supermajors anchor demand here, driven by subsurface uncertainty and capital intensity of unconventional targets.
- Production:Real-time sensor streams from downhole tools enable predictive maintenance and artificial lift optimization. Texas independents deploy these capabilities at scale, pressured by EPA methane monitoring obligations and compressor uptime targets.
- Refining:Process analytics for yield optimization and energy efficiency.
- Distribution:FERC-mandated pressure and flow surveillance across interstate pipeline networks.
Mature deployment sits with Production. Newer deployment is concentrated in Exploration.
Technology:
Cost tiering separates legacy infrastructure investments from cloud-native architectures.
- Big Data:Aggregated well logs, completion designs, and production histories form queryable lakes. Permian operators lead spend here, consolidating decades of proprietary subsurface data for pattern recognition.
- Artificial Intelligence:Machine learning models predict equipment failures seventy-two hours in advance. Eagle Ford mid-caps adopt fastest, eliminating external engineering consultant reliance through automated diagnostics.
- Cloud Computing:Managed services contracts displace on-premise installations among land-based producers seeking operational expenditure flexibility.
- Machine Learning:Turbomachinery vibration signature analysis automates root-cause workflows.
Established infrastructure dominates Big Data. Fastest capability expansion attaches to Artificial Intelligence.
Service Type:
Customer type shapes procurement—supermajors favor in-house platforms while independents outsource.
- Consulting:Reservoir engineering and digital transformation advisory. Bakken operators lag Permian maturity here, creating white space for basin-specific expertise.
- Software:Subscription pricing for drilling optimization now displaces perpetual licenses. Anadarko independents demand usage-based contracts tied to wells drilled rather than enterprise seats.
- Managed Services:Cloud-native platform operation and data governance.
- Maintenance:Predictive analytics for asset life cycle extension.
Revenue concentration rests with Software. Emerging procurement momentum sits with Managed Services.
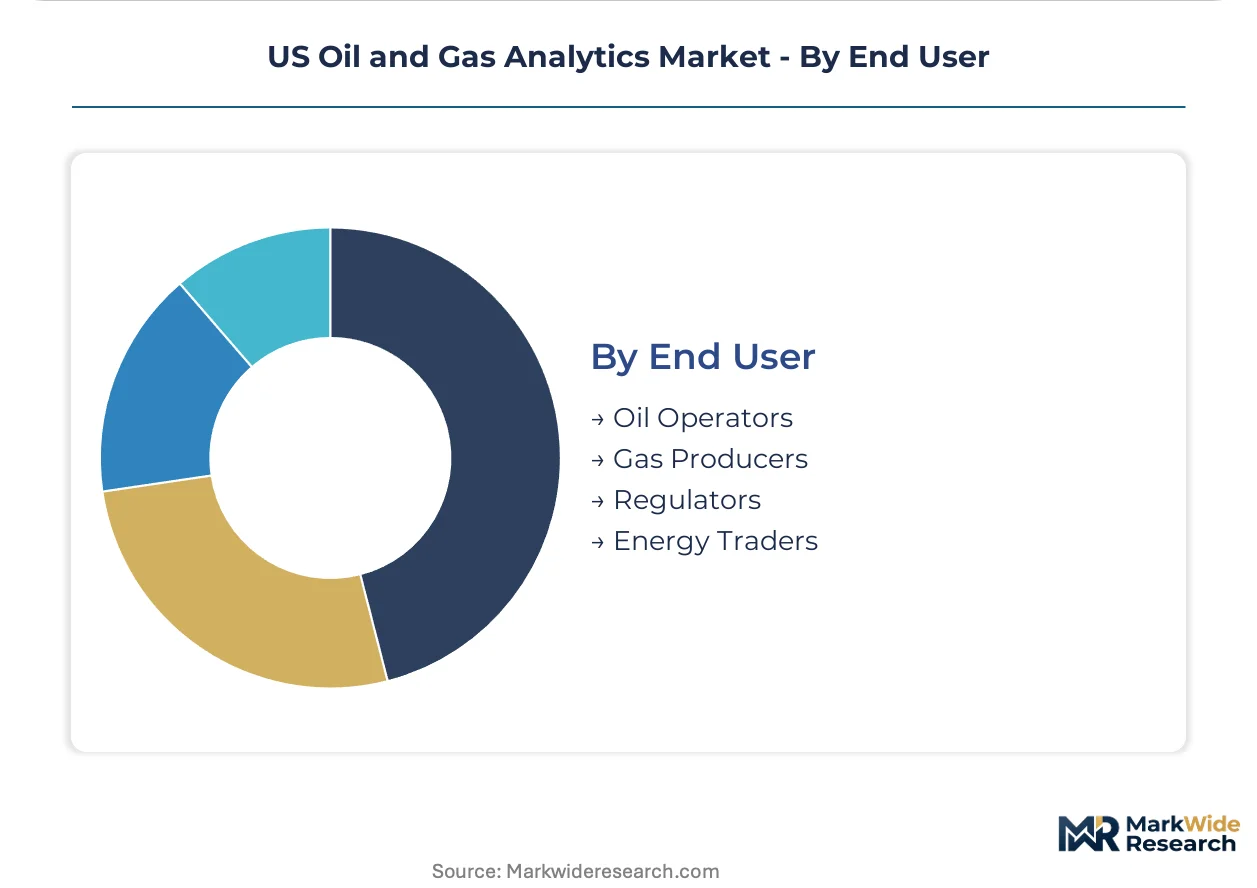
End User:
Margin structure varies by buyer sophistication and compliance burden intensity.
- Oil Operators:Upstream producers deploying digital twins and edge computing infrastructure. Texas concentration creates reference architectures that mid-caps replicate.
- Gas Producers:Methane emissions verification and leak detection algorithm deployment. Inflation Reduction Act enforcement drives fastest adoption here.
- Regulators:EPA and state-level data reconciliation platforms for emissions verification.
- Energy Traders:Real-time production forecasting for commodity positioning.
Technology maturity centers on Oil Operators. Regulatory pressure is expanding Gas Producer deployment fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin geology anchors US upstream analytics deployment. Texas shale operators concentrate capital in digital infrastructure. EPA methane enforcement drives software procurement cycles.
Texas
Supermajors deploy digital twins across the Permian Basin at unmatched scale. EPA methane monitoring rules under the Inflation Reduction Act force continuous emissions verification adoption. Midland-Odessa operators anchor real-time drilling analytics reference architectures that independents replicate.
North Dakota
Bakken Shale producers lag Permian digital maturity, creating white space for predictive maintenance platforms. State environmental regulations align with federal EPA standards for emissions reporting. Williston Basin drilling activity concentrates demand for reservoir simulation and completion optimization tools.
New Mexico
Permian Delaware sub-basin activity drives edge computing infrastructure investment. State-level air quality regulations complement EPA enforcement intensity for leak detection. Carlsbad and Hobbs field offices anchor supermajor operational headquarters for cross-border basin analytics.
Oklahoma
Anadarko Basin independents demand usage-based software contracts tied to wells drilled. Oklahoma Corporation Commission field regulations shape data reporting requirements. Oklahoma City headquarters clusters anchor mid-cap producer digital transformation initiatives.
Louisiana
Gulf Coast offshore operations face satellite bandwidth constraints slowing cloud adoption. Bureau of Safety and Environmental Enforcement regulations mandate real-time platform monitoring. Lake Charles and Houma industrial corridors anchor on-premise analytics infrastructure for deepwater producers.
US Oil and Gas Analytics Market Vendor Landscape
Global majors compete with regional champions across software subscription models and service delivery architectures. The vendor base organizes around integrated platform providers, specialized diagnostics specialists, and proprietary analytics developers. Three archetypes dominate: supermajor captive technology units, independent oilfield service platforms, and pure-play software vendors. Competitive moves center on subscription pricing displacement of perpetual licenses and emissions verification module integration into production optimization suites.
Within the integrated service tier, Schlumberger and Baker Hughes exemplify platform-centric strategies. Schlumberger anchors software subscriptions through drilling optimization suites deployed across Permian and Bakken basins. Baker Hughes occupies a position in turbomachinery diagnostics that extend asset life cycles. ConocoPhillips represents the independent operator archetype with proprietary subsurface analytics capabilities.
| Leading Market Players |
|---|
| ConocoPhillips |
| Baker Hughes |
| Halliburton |
| BP |
| Weatherford |
| ExxonMobil |
| Schlumberger |
| Shell |
| Chevron |
| Others |
Supply Flow & Price Mechanics
EPA methane monitoring mandates under the Inflation Reduction Act force operators to bundle emissions verification modules into production optimization suites, pressuring vendors to absorb sensor hardware costs into subscription pricing while maintaining cloud-native delivery architectures.
Pricing Analysis
Software warranty and tiered service bundling now separate premium subscriptions with predictive maintenance modules from stripped-down compliance-only tiers. Three-tier pricing structure across premium, standard, and economy levels reflects data lake query volume, edge computing node count, and after-sales engineering support intensity. Cost compression in the standard tier is intensifying because mid-cap Permian producers demand usage-based contracts tied to wells drilled rather than enterprise seats. Independents in the Anadarko Basin exhibit highest price sensitivity; supermajors prioritize integration depth over per-seat economics.
Supply Chain Analysis
Direct-to-operator channels handle hyperscale supermajor demand while value-added resellers serve mid-cap independents with bundled implementation support. Cloud infrastructure concentrates in the United States, with edge computing hardware sourcing from Taiwan and semiconductor components from South Korea. GPU and specialized AI accelerator dependencies create single-source vulnerability for real-time reservoir simulation workloads. Distribution runs through Schlumberger and Baker Hughes field service networks for integrated platform deployments, with pure-play vendors relying on AWS and Azure marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineering talent scarcity props pricing for AI-enabled production optimization platforms, constraining vendor capacity expansion and preserving incumbent margin structures.
For Market Incumbents: To counter pure-play software vendors encroaching on the Eagle Ford Shale, anchor platform retention through backward integration into proprietary edge hardware and deepen API ecosystems that lock in operator data workflows. Prioritize EPA emissions verification certification investments that mid-cap competitors cannot replicate quickly. For New Entrants and Emerging Players: Independent oilfield service contractors represent the most accessible channel partner type for bypassing supermajor procurement gatekeepers. Target Bakken Shale operators lagging Permian digital maturity with basin-specific predictive maintenance modules. White space exists in Class VI carbon sequestration site monitoring where regulatory clarity remains unsettled. For Investors and Strategic Acquirers: The window for entry favors vertically integrated oilfield service platforms with captive petroleum engineering talent pipelines. Five-to-ten year viability hinges on emissions verification module attach rates across existing production optimization installs. Monitor EPA enforcement intensity variance between Texas and New Mexico as the signal for addressable market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions Verification Module Integration | EPA Inflation Reduction Act enforcement anchors software procurement cycles for continuous monitoring compliance. |
| Edge Computing Infrastructure Buildout | Permian Basin sensor density requirements favor localized processing over satellite-dependent cloud architectures. |
| Predictive Maintenance Platform Acquisition | Turbomachinery diagnostics capabilities extend asset life cycles and displace external engineering consultants. |
| Subscription Pricing Model Transition | Usage-based contracts tied to wells drilled align vendor revenue with operator capital deployment cycles. |
| Class VI Sequestration Monitoring Development | State primacy disputes over EPA permitting create first-mover advantage for verification tool anchoring. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with petroleum engineers, digital transformation officers at independents, EPA compliance leads, cloud platform architects, and reservoir simulation specialists provided operational validation. EIA production databases, FERC pipeline safety filings, Texas Railroad Commission field reports, and SEC 10-K software revenue disclosures supplied quantitative benchmarks. Bottom-up well-level analytics adoption estimates triangulated against top-down vendor revenue aggregation.
Reconciliation of sensor deployment counts, cloud infrastructure capex disclosures, and operator digital budget surveys informed the analytical framework across the analysis window. Segmentation dimensions modeled include upstream-midstream-downstream application layer, on-premise versus cloud-native deployment architecture, and supermajor versus independent buyer archetype. CAGRs derived from technology diffusion curves calibrated against historical ERP adoption patterns in the Permian Basin, with methane monitoring regulatory compliance timelines as a demand-pull input.
Caveats apply where EPA enforcement intensity variance or satellite bandwidth cost trajectories could materially shift the outlook for offshore cloud adoption. Forecasts reflect assumptions regarding operator capital discipline and vendor platform consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Wireline Services Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
India Natural Gas Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Smart Well Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market