
 South America Crop Protection Chemicals Market | 2026-2036
South America Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Crop Protection Chemicals Market Insights
The agrochemical distribution channel is fragmenting across South America as independent cooperatives and digital procurement platforms erode traditional dealer networks. Syngenta Group leverages its integrated seed-chemistry portfolio to sustain direct-to-farmer relationships in Brazil's Mato Grosso state. BASF SE anchors its position through specialized fungicide formulations targeting soybean rust, the region's most destructive crop disease. Bayer AG competes via its glyphosate-tolerant seed systems that lock in complementary herbicide demand across Argentine pampas operations.
Crop protection chemicals encompass synthetic and biological formulations designed to control weeds, insects, fungi, and other agricultural pests, with active ingredients typically concentrated between 100-500 grams per liter in commercial emulsifiable concentrates. These substances protect yield potential in commodity and specialty crop systems by preventing pre- and post-emergence pest damage. Herbicides dominate volume demand as zero-tillage farming expands across the continent's soybean-corn rotation belts. Liquid formulations capture the largest share of value given their ease of aerial application over vast Brazilian estates, while granular products retain niche positions in horticultural crops where precision placement reduces environmental runoff.
ANVISA governs pesticide registration and toxicological review in Brazil, while Argentina's SENASA enforces residue limits and import tolerances on cross-border grain shipments. Both regulators are tightening maximum residue limits to align with European export standards, forcing reformulation of older organophosphate chemistries. Stakeholders must monitor evolving bioequivalence requirements for generic active ingredients, as these rules determine whether lower-cost manufacturers can access Brazil's protected market segments.
Market Dynamics
Herbicide resistance in Brazilian soybean fields is forcing rapid chemistry rotation and stacking strategies, compressing product lifecycles while elevating precision application requirements across the Cerrado and Pampas grain belts.
Growth Catalysts
- Glyphosate-resistant weed proliferation:Amaranthus palmeri and Conyza bonariensis infestations across Mato Grosso and Buenos Aires provinces are compelling farmers to adopt dicamba and 2,4-D tolerant seed systems alongside residual herbicide programs.
- ANVISA re-registration mandates:Brazil's toxicological reassessment of active ingredients is phasing out older chemistries and opening registration slots for novel modes of action with improved environmental profiles.
- Zero-tillage expansion:Conservation agriculture adoption across Paraguay's eastern departments and southern Brazil is sustaining pre-emergent herbicide volumes as cover crop systems require intensive weed suppression.
Market Restraints
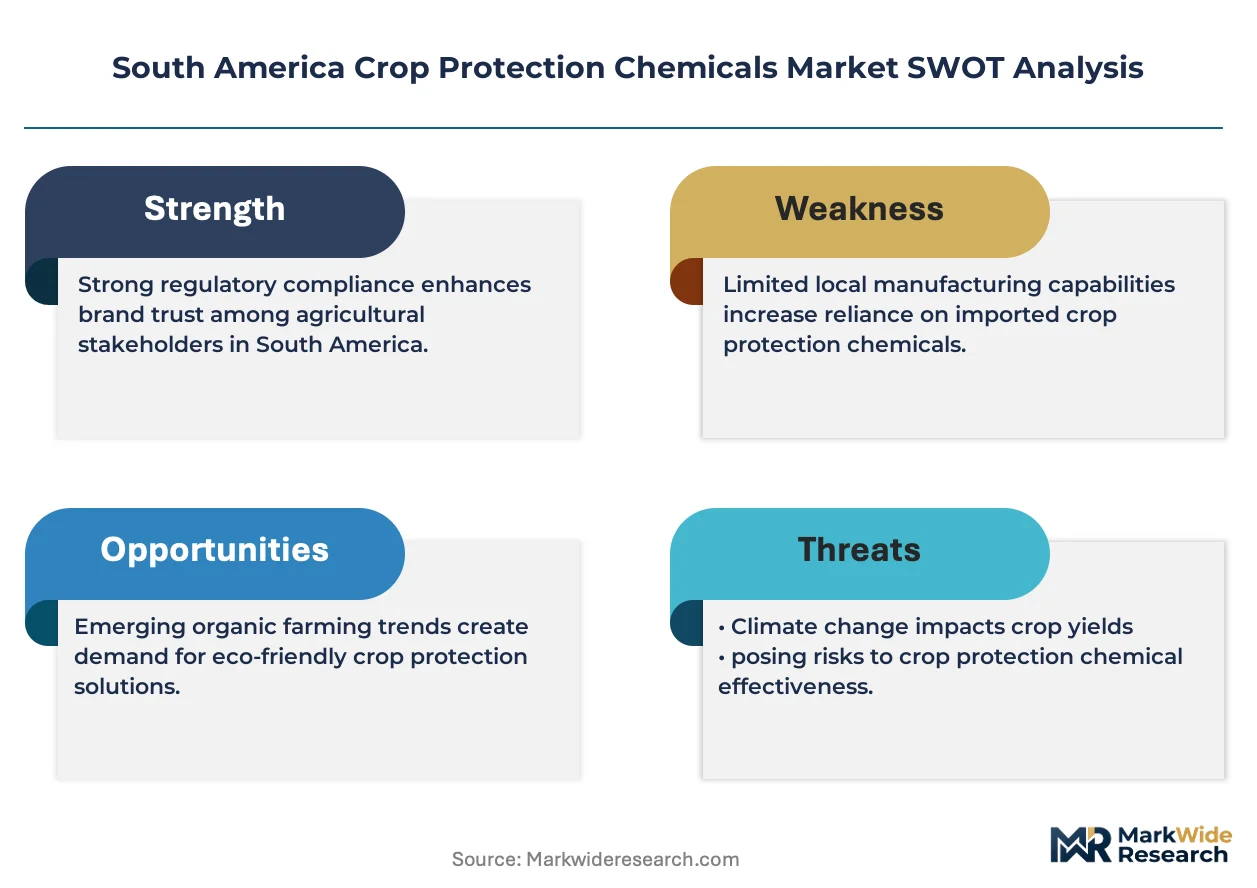
- Active ingredient import concentration:Chinese and Indian intermediate suppliers dominate technical-grade production, exposing Brazilian formulators to freight cost volatility and currency mismatch risks.
- Maximum residue limit misalignment:EU EFSA standards for glyphosate and chlorpyrifos residues on soybean exports are tightening faster than ANVISA domestic tolerances, creating compliance friction for export-oriented growers.
- Biological substitute encroachment:Bacillus thuringiensis and Trichoderma-based biofungicides are capturing niche segments in organic-certified fruit and vegetable operations, constraining synthetic fungicide expansion in high-value horticulture.
Strategic Opportunities
- Colombian Andean foothills penetration:Coffee and avocado expansion in Antioquia and Caldas is creating demand for specialized fungicide and insecticide portfolios previously concentrated in Brazil and Argentina.
- Drone-based variable-rate application:Aerial spraying platforms equipped with multispectral sensors are enabling prescription-based chemical deposition, reducing input waste and opening service-based revenue models.
- ANVISA fast-track for biologicals:Accelerated registration pathways for microbial and biochemical pesticides are lowering market entry barriers for domestic biopesticide developers targeting soybean rust and fall armyworm.
Industry Challenges
- Resistance management stewardship:Extension agronomist shortages in remote Argentine provinces are weakening farmer adherence to mandated herbicide rotation protocols, accelerating resistance evolution.
- Application equipment calibration:Nozzle wear and boom height inconsistency across aging Brazilian sprayer fleets are generating off-target drift incidents, triggering liability exposure and neighbor disputes.
- Generic bioequivalence documentation:ANVISA's evolving requirements for physical-chemical equivalence studies are extending registration timelines for post-patent manufacturers, compressing effective exclusivity windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Crop Protection Chemicals Market |
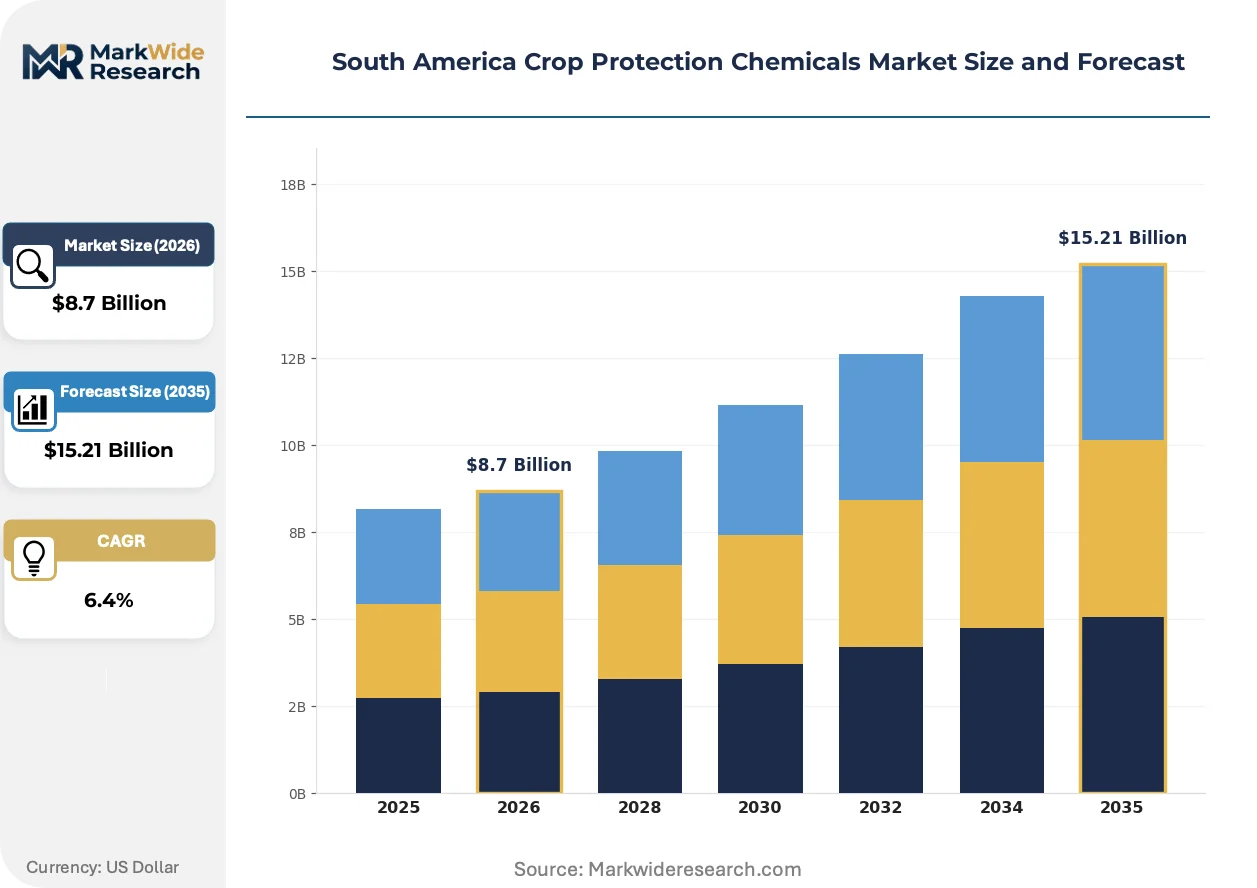
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural Crops, Horticultural Crops, Turf, Ornamentals Active Ingredient: Glyphosate, Atrazine, Chlorpyrifos, Cyhalothrin Formulation: Granules, Liquids, Powders, Emulsifiable Concentrates |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, UPL Ltd, ADAMA Agricultural Solutions Ltd, Nufarm Ltd, Ourofino Agrociencia, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Crop Protection Chemicals Market Trends and Innovations
Digital agriculture platforms are virtualizing traditional agronomic decision-making, embedding crop protection recommendations into automated farm management systems that override conventional dealer consultations.
RNA interference-based insecticides are virtualizing conventional neurotoxic chemistries by silencing essential genes in target pests without broad-spectrum ecological damage. Large-scale Brazilian soybean operations are piloting foliar RNAi sprays against Helicoverpa armigera. Bayer and Syngenta field trials indicate this technology is virtualizing pyrethroid and diamide demand in premium seed treatment and foliar segments.
ANVISA's 2022 resolution on pesticide packaging return and reverse logistics is mandating triple-rinse protocols and container collection infrastructure investments. Formulators must now finance rural collection point networks or face registration penalties. Mid-sized distributors in Paraná and Rio Grande do Sul are consolidating to share compliance costs, favoring integrated multinational supply chains over fragmented independents.
Farmer procurement is fragmenting across digital platforms that aggregate input pricing and enable direct manufacturer bidding. Argentina's Mercado Libre agrochemical marketplace and Brazil's Agrofy platform are disintermediating traditional cooperative purchasing departments. Mato Grosso grain producers are leveraging these channels to arbitrage price differentials between regional distributors, compressing dealer margins and forcing inventory risk transfers upstream.
South America Crop Protection Chemicals Market Segmentation
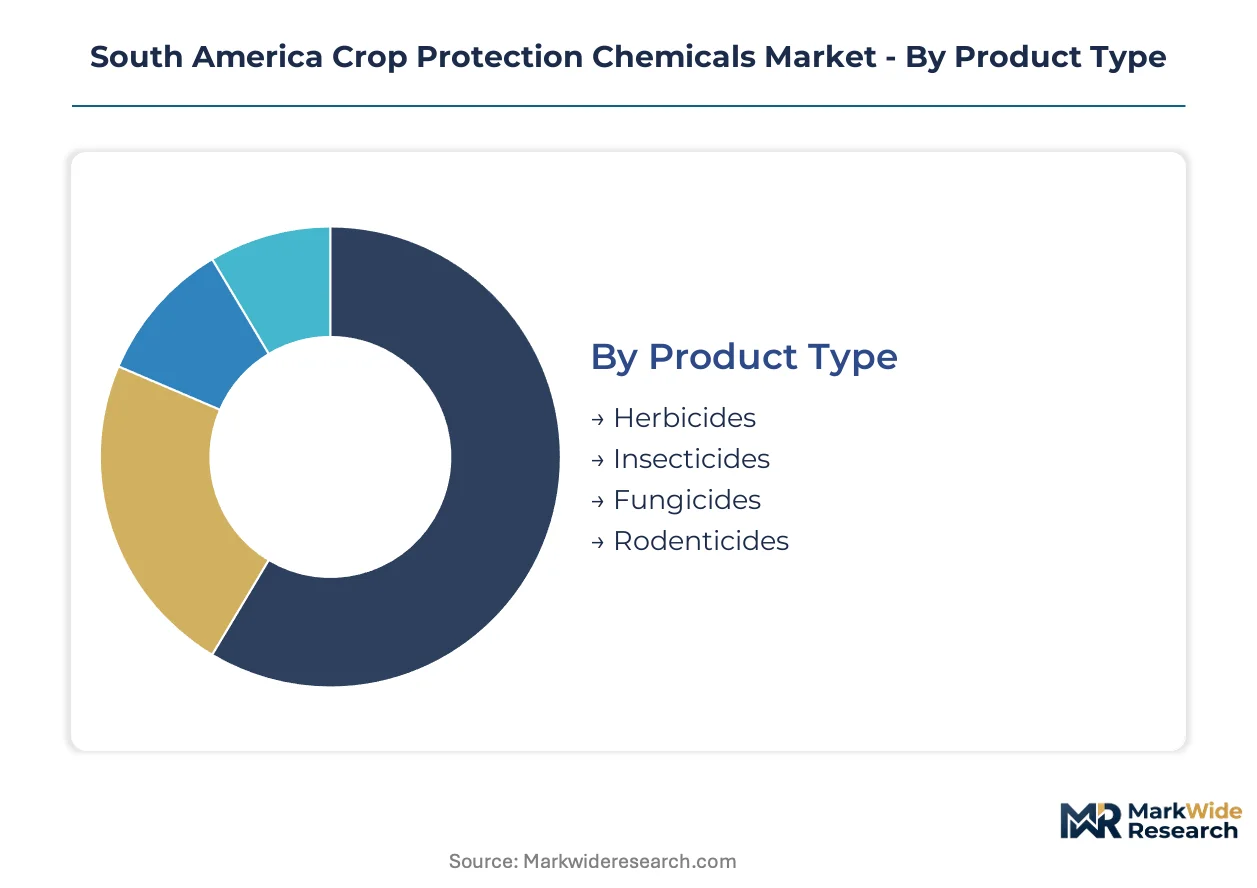
Segmentation in South America's crop protection chemicals market reveals how product chemistry, application context, and formulation technology align with distinct agronomic requirements across Brazil's Cerrado, Argentina's Pampas, and emerging Andean cultivation zones. Understanding these divisions exposes where manufacturer R&D investments concentrate and where distribution channels face pressure from resistance management protocols.
Product Type:
Cost tier differentiation across product categories reflects the intensity of weed, pest, and disease pressures in South American commodity cropping systems.
- Herbicides:These formulations dominate procurement budgets through glyphosate-based systems and residual chemistry stacks. Brazilian soybean operations in Mato Grosso and Goiás are expanding dicamba-tolerant seed adoption to combat Amaranthus palmeri resistance, elevating demand for auxin herbicide co-formulations.
- Insecticides:Neonicotinoid seed treatments and pyrethroid foliar sprays target fall armyworm and Helicoverpa armigera infestations. Argentine corn producers in Buenos Aires province are rotating to diamide chemistry as pyrethroid resistance thresholds rise.
- Fungicides:Triazole and strobilurin combinations protect soybean rust-prone regions.
- Rodenticides:Anticoagulant baits secure grain storage infrastructure.
Herbicides hold installed capacity. Insecticides are rotating up the share rankings.
Application:
Application context determines formulation specifications, residue limit compliance requirements, and the feasibility of aerial versus ground-based deployment methods.
- Agricultural Crops:Soybean, corn, and wheat operations across Brazil's MATOPIBA corridor and Argentina's core grain belt consume the majority of active ingredient volumes. Zero-tillage systems here require intensive pre-emergent herbicide programs and sequential fungicide applications for rust management.
- Horticultural Crops:Specialty fruit and vegetable production in São Paulo state and Peru's Ica Valley demands lower-residue chemistries with tighter spray intervals. Export-oriented avocado and grape growers face EU MRL compliance pressures that constrain organophosphate and carbamate selections.
- Turf:Golf course and sports field maintenance in Santiago and Montevideo uses selective herbicides and growth regulators.
- Ornamentals:Nursery operations and floriculture in Colombia's Sabana de Bogotá apply systemic fungicides and miticides.
Agricultural crops anchor volume demand. Horticultural crops are climbing the fastest as high-value export sectors expand.
Active Ingredient:
Maturity profiles of active ingredients reveal which chemistries face regulatory phase-out versus which novel modes of action are capturing replacement demand.
- Glyphosate:The isopropylamine salt formulation remains the backbone of South American no-till systems despite escalating resistance pressure. Brazilian ANVISA's ongoing toxicological reassessment is tightening application windows, while EU export tolerances constrain residue levels for international shipments.
- Atrazine:This triazine herbicide retains niche positions in corn and sorghum rotations where residual weed control extends into critical crop establishment periods. Regulatory scrutiny over groundwater contamination is restricting use zones in Paraguay's eastern departments.
- Chlorpyrifos:Organophosphate insecticide facing registration withdrawal across multiple South American jurisdictions.
- Cyhalothrin:Synthetic pyrethroid for foliar insect control in cotton and soybean.
Glyphosate maintains formulation dominance. Cyhalothrin is gaining share fastest as resistance management rotations intensify.
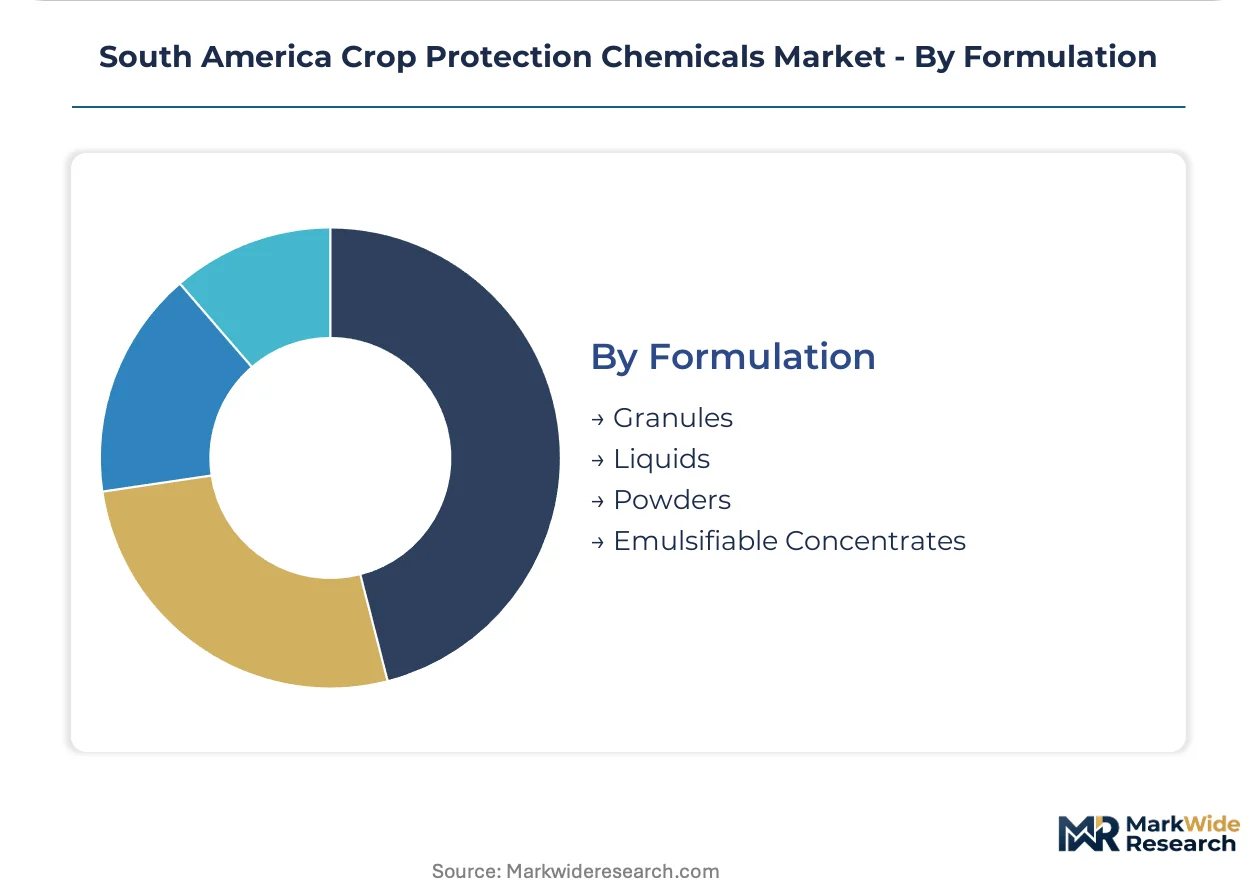
Formulation:
Supply concentration in formulation technology reflects manufacturing infrastructure location and the logistics economics of shipping concentrated technical grade versus finished product.
- Liquids:Soluble concentrates and suspension concentrates enable rapid tank-mixing and uniform aerial application over vast Brazilian estates. Mato Grosso spraying contractors prefer liquid formulations for their compatibility with drone-based variable-rate systems and reduced packaging waste under ANVISA's reverse logistics mandates.
- Emulsifiable Concentrates:Oil-in-water systems deliver lipophilic active ingredients with enhanced leaf penetration. These formulations dominate fungicide applications for soybean rust control in Argentina's humid pampas regions where rainfastness determines efficacy windows.
- Granules:Controlled-release matrices suit precision placement in horticultural beds.
- Powders:Wettable powder and water-dispersible granule formats serve smallholder markets.
Liquids command the largest installed base. Emulsifiable concentrates are rotating up the share rankings as fungicide demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing leverage over Argentine formulators through its concentrated soybean purchasing power and ANVISA regulatory gatekeeping, while Andean markets fragment across national residue standards.
Brazil
Mato Grosso and Goiás drive herbicide volumes through glyphosate-tolerant soybean systems and dicamba rotation stacks. ANVISA's 2022 toxicological reassessment of active ingredients is phasing out older organophosphate chemistries. The Cerrado mechanized belt concentrates aerial application contracting and digital procurement platform adoption.
Argentina
Buenos Aires province anchors fungicide demand for soybean rust management in humid pampas conditions. SENASA enforces EU-aligned residue limits on cross-border grain shipments, constraining chlorpyrifos tolerances. Rosario's agrochemical formulating cluster faces margin compression from Chinese technical-grade import volatility.
Colombia
Antioquia and Caldas departments generate specialized fungicide demand from coffee rust and avocado export operations. The national agricultural regulator tightens maximum residue limits for EU-bound specialty crop shipments. Bogotá's Sabana nursery district sustains miticide and systemic fungicide applications in floriculture.
Paraguay
Eastern departments sustain pre-emergent herbicide volumes through zero-tillage soybean-corn rotations. Groundwater protection statutes restrict atrazine use zones in sensitive aquifer regions. Ciudad del Este's border logistics corridor channels Brazilian-imported formulations to smallholder cooperatives.
Chile
Central Valley fruit exporters face EFSA MRL compliance pressures on grape and berry shipments. The national agricultural service mandates integrated pest management protocols in export-oriented orchards. Santiago's turf maintenance sector consumes selective herbicides for golf course and sports field management.
South America Crop Protection Chemicals Market Competitive Landscape
Integrated agrochemical-seed conglomerates and specialized generic formulators split the market between proprietary trait-chemistry bundles and price-competitive post-patent portfolios. Market concentration elevates multinational R&D scale against regional blending operations. Three archetypes dominate: trait-integrated innovators, post-patent generic specialists, and biological platform developers. Competitive positioning hardens through ANVISA registration asset accumulation and drone-application service integration.
Within the trait-integrated tier, Syngenta Group, BASF SE, and Bayer AG exemplify the dominant strategic archetype. These Switzerland-based and Germany-based conglomerates anchor market presence through stacked seed-chemistry systems. Brazilian formulator Ourofino Agrociencia occupies a position bridging multinational access and regional regulatory navigation.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| UPL Ltd |
| ADAMA Agricultural Solutions Ltd |
| Nufarm Ltd |
| Ourofino Agrociencia |
| Others |
Pricing and Supply Chain Analysis
The Santos-Paranaguá maritime corridor channels Chinese and Indian technical-grade imports into Brazilian formulation plants, where freight cost volatility feeds directly into glyphosate concentrate pricing and widens spreads between standard and customized herbicide blends. This logistics chokepoint concentrates supply-side power among multinational formulators with captive shipping contracts, compressing margins for regional distributors serving Mato Grosso soybean cooperatives.
Pricing Analysis
The customization-premium spread separates configured-to-order dicamba-tolerant seed treatment bundles from standard glyphosate-isopropylamine formulations. Three-tier pricing structure across premium, standard, and economy levels reflects brand recognition, volume scale, and after-sales agronomic support bundling. Pricing pressure stems from digital procurement platform transparency that exposes regional distributor markups to arbitrage-seeking grain producers. Smallholder cooperatives in Paraguay's eastern departments exhibit highest price sensitivity, while Brazilian Cerrado estate operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Supplier-financing facilities from Chinese intermediate producers extend 90-120 day payment terms to Brazilian formulators, masking currency mismatch risks in real-denominated sales. Technical-grade production concentrates in China and India, with formulation finishing anchored in Brazil and Argentina. Raw material dependencies span glyphosate acid, 2,4-D esters, and strobilurin fungicide intermediates. Single-source vulnerability from Indian chlorpyrifos precursor suppliers elevates disruption risk as ANVISA phases out registrations. Distribution runs through multinational direct-to-farmer platforms, cooperative purchasing departments, and independent agrochemical retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across South America's crop protection chemicals market as Mato Grosso grain cooperatives consolidate procurement through digital platforms, fragmenting traditional distributor influence and compressing effective manufacturer pricing leverage.
For Market Incumbents: Harden registration asset positions by accelerating ANVISA bioequivalence documentation for post-patent active ingredients before generic competitors extend timelines. Deepen backward integration into Chinese technical-grade supply through long-term offtake agreements with Zhejiang and Jiangsu intermediate producers, securing volume commitments against freight volatility. Lock in drone-application service contracts with Cerrado spraying contractors to preempt digital platform disintermediation of dealer networks.
For New Entrants and Emerging Players: Establish a beachhead in Colombia's Andean coffee and avocado fungicide segments where specialized rust and export-compliance chemistries face limited domestic formulation capacity. Target biological pesticide fast-track registrations under ANVISA's accelerated pathway for microbial alternatives to synthetic soybean rust treatments. Deploy agronomic advisory services as the primary go-to-market mechanism, embedding product recommendations into farm management software partnerships rather than competing on price through commodity channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized Brazilian distributors in Paraná and Rio Grande do Sul struggling to finance ANVISA-mandated reverse logistics infrastructure investments. Long-term viability hinges on regulatory navigation capabilities and integrated seed-chemistry bundling scale. Monitor ANVISA toxicological reassessment announcements as the critical inflection signal for active ingredient obsolescence windows and replacement chemistry valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Supply | Captive sourcing from Chinese intermediate producers insulates Brazilian formulators against freight volatility and currency mismatches. |
| Drone-Based Application Service Integration | Multispectral-equipped aerial platforms in Mato Grosso enable prescription-based chemical deposition and recurring revenue models. |
| Biological Pesticide Fast-Track Registration | ANVISA's accelerated pathway for microbial alternatives lowers entry barriers for domestic biopesticide developers targeting fall armyworm. |
| Digital Procurement Platform Partnership | Integration with Brazil's Agrofy and Argentina's Mercado Libre agrochemical marketplaces captures farmer price-arbitrage behavior. |
| Reverse Logistics Infrastructure Consolidation | Shared container collection networks among mid-sized Paraná distributors distribute ANVISA compliance costs and favor scale. |
Research Methodology
A standing panel of ANVISA registration affairs directors, Mato Grosso cooperative procurement managers, Argentine pampas extension agronomists, and Chinese technical-grade export traders provided ongoing calibration across primary interview cycles. Secondary validation drew from ANVISA toxicological reassessment filings, SENASA residue limit decrees, Brazilian customs import data, and SEC 10-K disclosures from listed agrochemical conglomerates. Bottom-up volume estimates from state-level pesticide consumption surveys were triangulated against top-down manufacturer shipment data.
Scenario-bracketing framed demand projections across baseline, accelerated resistance evolution, and biological substitution trajectories throughout the forecast period. Segmentation dimensions modeled encompassed product chemistry tier, crop application context, formulation technology, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized historical consumption baselines, with inputs from planted acreage expansion rates in MATOPIBA and Colombian Andean zones.
Stress conditions across glyphosate-resistant weed proliferation velocity, Chinese intermediate supply disruptions, and EU MRL tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions regarding ANVISA registration timeline stability and real-denominated farmer credit availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Global Insecticides Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Grain Fumigants Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Herbicides Market
Crop Protection
Global Termite Control Market
Crop Protection
Europe Herbicide Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Europe Fungicide Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Soil Fumigant Market
Crop Protection
Asia-Pacific Nematicides Market