
 Japan Crop Protection Chemicals Market | 2026-2036
Japan Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Crop Protection Chemicals Market Foresight
Granular-to-liquid unbundling is decoupling traditional bundled agrichemical packages into standalone formulation components. Sumitomo Chemical Co., Ltd. leverages its integrated R&D pipeline across synthetic pyrethroids to sustain domestic manufacturing scale. Mitsui Chemicals Agro, Inc. specializes in niche fruit and vegetable chemistries that anchor premium positioning in protected cultivation. Nihon Nohyaku Co., Ltd. competes through biological-originated active ingredient development that differentiates its portfolio from conventional synthetic rivals.
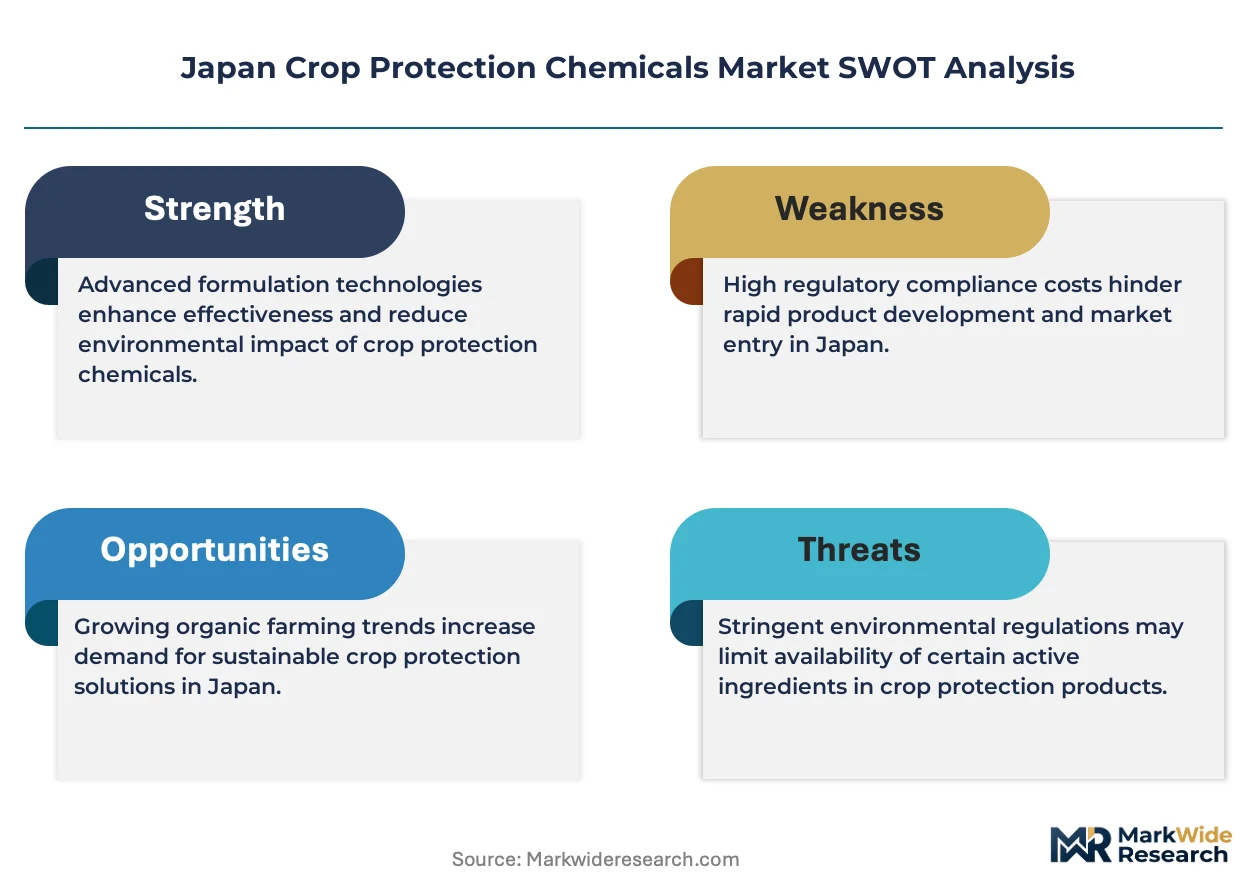
Japan crop protection chemicals encompass synthetic and biological substances formulated to prevent, destroy, or mitigate agricultural pests, with active ingredient concentrations typically ranging from 0.1% to 50% depending on target organism and crop specificity. These compounds function through contact, systemic, or fumigant action modes to safeguard yield quality and volume across staple and specialty crops. Herbicides command the largest share of product type demand, reflecting Japan's intensive weed management requirements in rice paddy systems where water-seeded cultivation demands selective chemistry. Liquid formulations are gaining formulation type preference as farmers adopt mechanized spraying equipment that requires pump-compatible, readily miscible products. Agricultural application dominates end-use consumption, though commercial turf and ornamental segments contribute margin-rich specialty volumes.
METI enforces chemical substance evaluation under the Chemical Substances Control Law, while the Ministry of Agriculture, Forestry and Fisheries (MAFF) regulates pesticide registration through efficacy and residue testing protocols that determine market access eligibility. The Food Sanitation Act, administered by the Ministry of Health, Labour and Welfare, establishes maximum residue limits that directly constrain active ingredient selection and application timing for domestic producers. PMDA oversight of novel active ingredient toxicology adds a pharmaceutical-grade scrutiny layer that elevates development costs and extends registration timelines. Stakeholders must monitor evolving biocide reclassification debates and cross-reference emerging residue standards against export destination requirements to preserve market optionality.
Market Dynamics
Japan's crop protection chemicals sector is undergoing structural recalibration as METI's chemical load reduction mandates force reformulation strategies across domestic manufacturers. This regulatory pressure is decoupling traditional bundled agrichemical packages into standalone components that enable precision dosing compliance.
Growth Catalysts
- Precision Application Technologies:Mechanized spraying equipment penetration in Kanto Plain rice operations is accelerating liquid formulation uptake. Farmers demand pump-compatible chemistries that reduce manual labor dependency.
- Biological Active Ingredient Development:MAFF residue testing protocols are creating market access pathways for bio-originated compounds. Nihon Nohyaku's R&D investments signal commercial viability of microbial and botanical alternatives.
- Protected Cultivation Expansion:Premium fruit and vegetable segments in greenhouse clusters around Tokyo are driving specialty chemistry demand. Protected cultivation requires targeted pest management without broad-spectrum runoff.
Market Restraints
- Active Ingredient Import Concentration:Japan relies on offshore synthesis for pyrethroid and neonicotinoid precursors. Geopolitical friction in East Asian supply corridors elevates input cost volatility.
- PMDA Toxicology Review Burden:Pharmaceutical-grade scrutiny of novel active ingredients extends registration timelines. Development cost escalation discourages mid-tier players from pipeline investment.
- Maximum Residue Limit Compression:Food Sanitation Act threshold tightening constrains application timing windows. Farmers face yield protection trade-offs against export market compliance.
Strategic Opportunities
- Hokkaido Grain Belt Expansion:Northern Japan's wheat and corn cultivation zones remain underpenetrated by specialized herbicide portfolios. Climate-adapted chemistry development captures acreage growth.
- Drone Application Infrastructure:UAV-based spraying is electrifying demand for ultra-low-volume formulations. Aviation law harmonization with MAFF aerial application rules creates channel innovation.
- Export-Oriented Residue Alignment:Codex Alimentarius and destination market MRL harmonization enables premium positioning. Formulators bundling multi-jurisdiction compliance documentation capture price premiums.
Industry Challenges
- Formulation Chemist Talent Scarcity:Japanese universities produce insufficient graduates with combined synthetic chemistry and agronomy expertise. Recruitment competition from pharmaceutical sectors elevates compensation costs.
- Legacy Paddy Infrastructure Integration:Water-seeded rice systems require selective chemistry compatibility with traditional irrigation timing. Mechanization retrofitting faces smallholder fragmentation barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Crop Protection Chemicals Market |
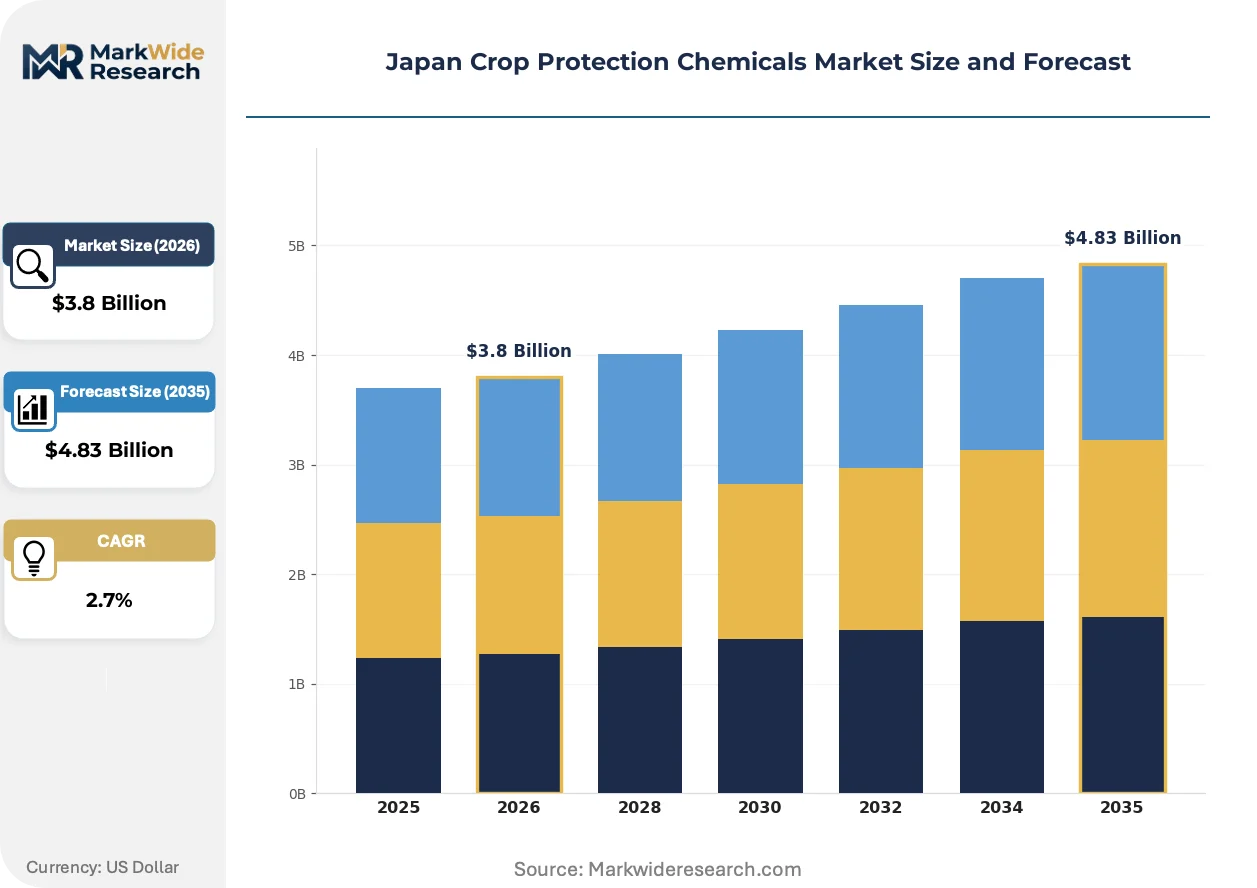
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural, Commercial, Residential, Forestry Formulation Type: Granules, Liquids, Solids, Emulsifiable Concentrates Distribution Channel: Retail, Direct Sales, E-commerce, Wholesale |
| Companies Covered | Sumitomo Chemical Co., Ltd., Syngenta CropProtection AG (Syngenta Group), Bayer AG, Mitsui Chemicals Agro, Inc., BASF SE, FMC Corporation, Nihon Nohyaku Co., Ltd., Kumiai Chemical Industry Co., Ltd., Nissan Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Crop Protection Chemicals Market Shifts & Advancements
Formulation technology is converging with digital agriculture platforms to reshape how crop protection chemistries are prescribed, applied, and monitored across Japanese farming operations.
Drone-mounted electrostatic spraying systems are electrifying precision agriculture adoption in Japan's rice paddies. These UAV platforms enable sub-hectare variable-rate application that reduces chemical load while maintaining efficacy. Large-scale agricultural cooperatives in Ibaraki and Chiba prefectures are deploying fleet-scale operations that compress labor requirements and enable nighttime application windows.
METI's Chemical Substances Control Law amendments are tightening biodegradability requirements for aquatic ecosystem discharge. The regulation forces reformulation of persistent organophosphate and carbamate chemistries toward hydrolysis-prone molecular structures. Rice paddy herbicide portfolios face the steepest redesign curves as water-shedding properties become compliance-critical.
Farmer purchasing patterns are consolidating through agricultural cooperative procurement platforms that displace independent distributor relationships. JA-Zenchu affiliated cooperatives aggregate demand across thousands of smallholders to negotiate formulation supply contracts. This channel shift concentrates price-setting power and compresses margins for non-integrated manufacturers serving the Kanto Plain cluster.
Japan Crop Protection Chemicals Market Segmentation
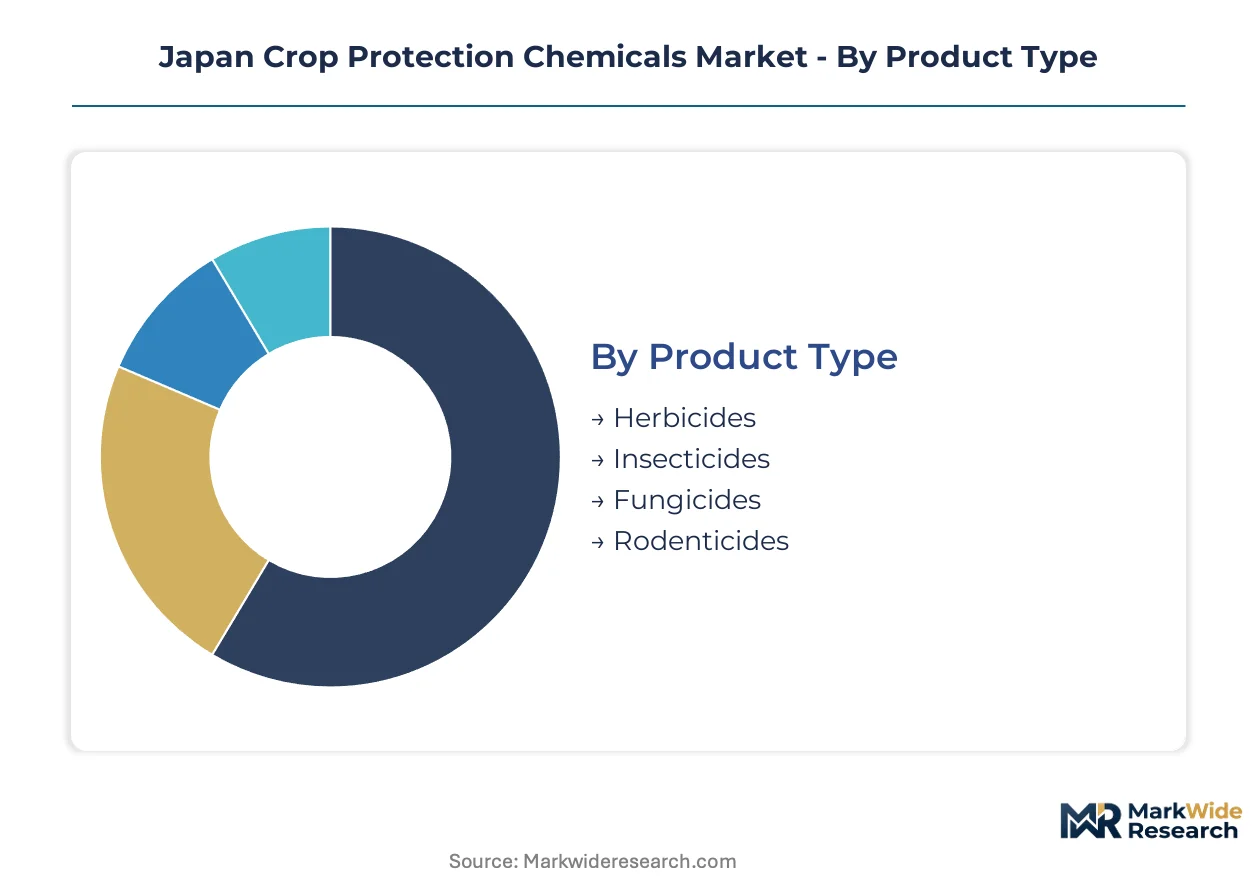
Segmentation in Japan's crop protection chemicals market reveals how regulatory pressure and farming system evolution are reshaping demand patterns across product categories and distribution pathways. Each dimension captures distinct structural forces from METI's chemical load mandates to JA-Zenchu procurement consolidation.
Product Type:
Standalone herbicide formulations dominate commercial volumes while insecticide-fungicide bundled systems embed into precision agriculture platforms across the Kanto Plain.
- Herbicides:Selective chemistries formulated for water-seeded rice systems command the largest application volumes. Kanto Plain rice cooperatives drive demand for aquatic-safe molecular structures that comply with METI biodegradability mandates.
- Insecticides:Synthetic pyrethroids and neonicotinoid precursors face reformulation pressure under Food Sanitation Act residue thresholds. Protected cultivation clusters around Tokyo require targeted chemistries without broad-spectrum runoff.
- Fungicides:Specialty portfolios for greenhouse fruit and vegetable production.
- Rodenticides:Niche volumes concentrated in grain storage and commercial turf segments.
Herbicides lead volumes today; insecticides are gaining share fastest through biological-originated alternatives.
Application:
Cost tier stratification separates high-frequency agricultural use from margin-rich specialty segments where compliance documentation commands price premiums.
- Agricultural:Rice paddy systems consume the majority of formulation volumes through mechanized spraying equipment. Ibaraki and Chiba prefecture cooperatives aggregate smallholder demand into bulk procurement contracts.
- Commercial:Turf and ornamental segments generate specialty chemistry demand with stringent residue documentation requirements. Golf course and landscape maintenance operators in Greater Tokyo pay premiums for multi-jurisdiction compliance bundling.
- Residential:Limited volumes through retail garden center channels.
- Forestry:Aerial application-dependent segment with aviation law harmonization constraints.
Agricultural applications anchor volume; commercial segments climb the fastest on margin expansion.
Formulation Type:
Volume concentration favors liquid miscible products while granule-to-liquid unbundling creates standalone component markets for precision dosing systems.
- Liquids:Pump-compatible formulations designed for mechanized spraying equipment penetration. Farmers across the Kanto Plain demand readily miscible chemistries that reduce manual labor dependency in rice operations.
- Granules:Traditional bundled packages facing decoupling pressure from METI chemical load reduction mandates. Legacy paddy infrastructure in fragmented smallholder systems sustates residual demand.
- Solids:Dust and powder formulations for specific crop protection applications.
- Emulsifiable Concentrates:Ultra-low-volume chemistries compatible with drone-mounted electrostatic spraying systems.
Liquids dominate current volumes; emulsifiable concentrates show steepest expansion trajectory through UAV adoption.
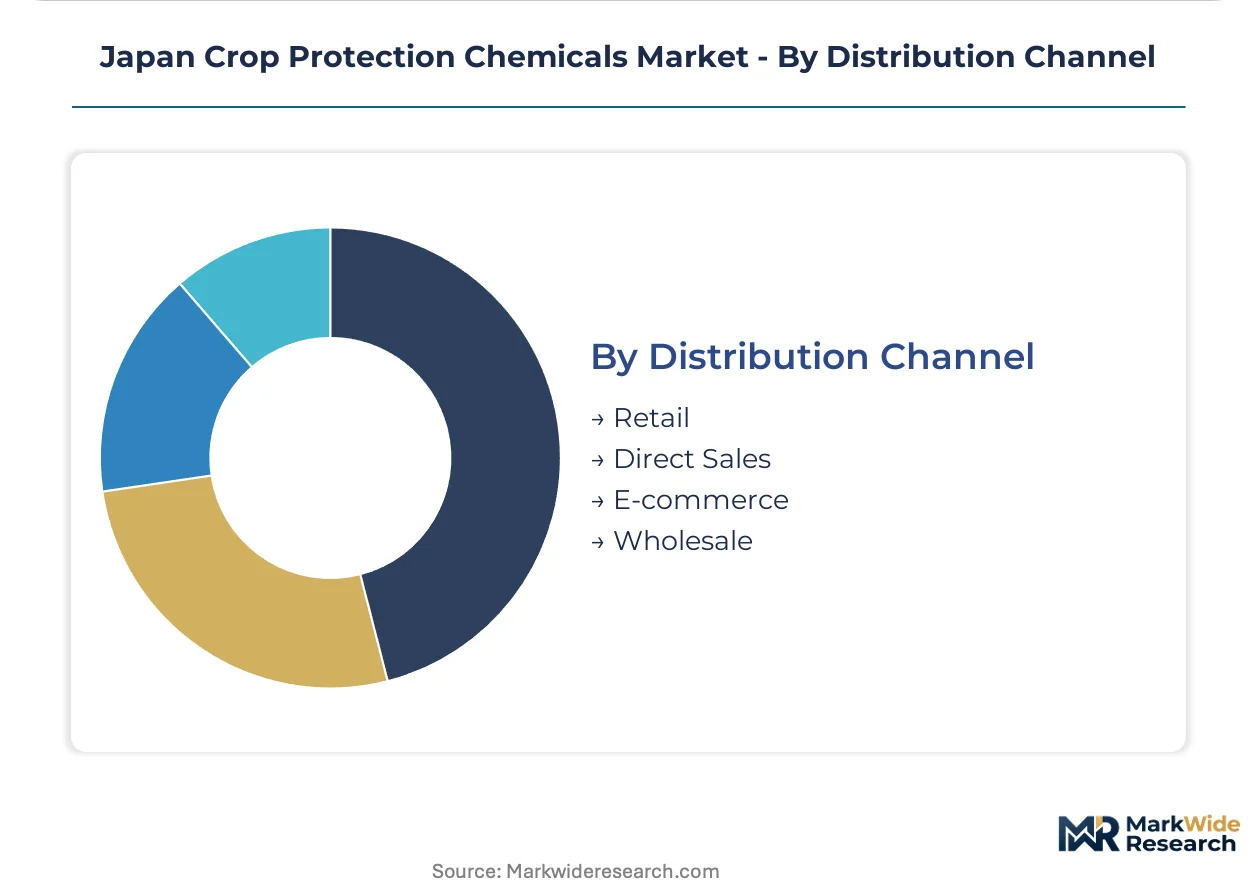
Distribution Channel:
Customer type consolidation is displacing independent distributor relationships as cooperative procurement platforms centralize price-setting power.
- Retail:Agricultural supply stores serving fragmented smallholders outside major cooperative networks. Chiba prefecture independents compete on technical advisory services.
- Direct Sales:Manufacturer relationships with large-scale agricultural cooperatives bypassing distributor margins. JA-Zenchu affiliated platforms aggregate thousands of Kanto Plain farmers into volume contracts.
- E-commerce:Emerging channel for standardized formulation components with documented compliance.
- Wholesale:Traditional distributor networks facing margin compression from cooperative consolidation.
Direct sales capture the largest volume share today; e-commerce is expanding most quickly among younger farm operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's crop protection chemicals industry traces its modern foundation to post-war agricultural modernization programs that established domestic synthesis capabilities for rice paddy herbicides. METI's subsequent chemical load reduction mandates have since redirected regional formulation priorities toward precision application systems.
Kanto Plain
Tokyo-adjacent prefectures of Ibaraki and Chiba concentrate Japan's highest mechanized spraying equipment density. JA-Zenchu affiliated cooperatives here aggregate thousands of smallholders into bulk procurement contracts for liquid formulations. The Kanto cluster drives national demand for pump-compatible chemistries that reduce manual labor dependency in rice operations.
Kansai Region
Osaka-centered protected cultivation zones generate specialty fungicide demand for greenhouse fruit and vegetable production. MAFF residue testing protocols in this region favor targeted chemistries without broad-spectrum runoff. Premium pricing for multi-jurisdiction compliance documentation commands margins from Greater Tokyo landscape maintenance operators sourcing through Kansai distribution channels.
Hokkaido
Northern Japan's wheat and corn cultivation zones remain underpenetrated by specialized herbicide portfolios. Climate-adapted chemistry development captures acreage growth as grain belt expansion accelerates. METI biodegradability mandates face implementation challenges in Hokkaido's shorter growing season windows.
Chubu Region
Nagoya-centered industrial corridors host integrated R&D pipelines across synthetic pyrethroid manufacturing. Domestic production scale sustains through captive supply of active ingredient precursors. PMDA toxicology review timelines extend registration cycles for novel compounds developed in Chubu research facilities.
Kyushu
Southern Japan's subtropical agriculture drives niche demand for botanical and microbial alternatives. Nihon Nohyaku's biological-originated active ingredient development anchors regional specialty positioning. Food Sanitation Act threshold tightening constrains application timing for export-oriented citrus operations in Fukuoka and Saga prefectures.
Japan Crop Protection Chemicals Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive R&D and manufacturing infrastructure. Domestic manufacturers maintain formulation leadership through METI compliance specialization, while multinational entrants compete on global active ingredient access. Three archetypes dominate: integrated conglomerates controlling full synthesis-to-formulation chains, biological specialists developing microbial alternatives, and regional cooperatives aggregating procurement power. Consolidation pressure intensifies through JA-Zenchu platform centralization and cooperative-direct manufacturer contracting.
Among integrated Japanese conglomerates, Sumitomo Chemical Co., Ltd. and Mitsui Chemicals Agro, Inc. occupy positions exemplifying synthetic chemistry scale and niche cultivation specialization respectively. Nihon Nohyaku Co., Ltd. represents the biological-originated alternative archetype, differentiating through active ingredient development outside conventional synthetic pathways. These three anchors illustrate how domestic players leverage regulatory compliance depth and regional cultivation knowledge against multinational competitors with superior global active ingredient sourcing.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd. |
| Syngenta CropProtection AG (Syngenta Group) |
| Bayer AG |
| Mitsui Chemicals Agro, Inc. |
| BASF SE |
| FMC Corporation |
| Nihon Nohyaku Co., Ltd. |
| Kumiai Chemical Industry Co., Ltd. |
| Nissan Chemical Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between METI-compliant precision formulations and legacy bundled chemistries manifests in both price premiums and supply chain reconfiguration. Premium portfolios command higher margins through PMDA toxicology documentation and multi-jurisdiction residue alignment, while commodity-grade alternatives face margin compression from cooperative procurement consolidation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Japan's crop protection chemicals sector. Premium tiers attach to biological-originated active ingredients with MAFF residue compliance documentation; standard tiers serve mechanized Kanto Plain cooperatives; economy tiers supply fragmented smallholders through retail channels. Cost compression in standard tiers intensifies because JA-Zenchu procurement platforms aggregate volume and squeeze manufacturer margins. Smallholder segments exhibit highest price sensitivity; export-oriented citrus operators in Kyushu show lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Empty container return logistics for liquid formulation totes remain underdeveloped across Japanese agricultural cooperatives, creating working capital inefficiencies for manufacturers. Active ingredient synthesis concentrates in China, India, and Germany for pyrethroid and neonicotinoid precursors. Formulation blending rests on domestic manufacturing scale in Chubu-region facilities. Single-source vulnerability in East Asian precursor corridors elevates input cost volatility. Distribution runs through JA-Zenchu cooperative platforms that displace independent wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's crop protection chemicals market compounds steadily as METI's chemical load mandates perpetuate reformulation cycles and precision application technology refresh.
For Market Incumbents: Anchor domestic manufacturing scale through captive R&D pipelines across synthetic pyrethroids to defend against biological-originated substitute technologies. Deepen backward integration into active ingredient precursors to offset East Asian supply corridor volatility. Secure direct contracting relationships with Ibaraki and Chiba prefecture cooperatives before procurement platform consolidation completes. For New Entrants and Emerging Players: Agricultural drone service providers represent the most penetrable channel partner type for ultra-low-volume formulation market entry. Target Hokkaido's underpenetrated grain belt with climate-adapted herbicide portfolios. Pursue white-label supply agreements with existing UAV spraying fleets rather than building independent distribution infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative procurement platforms concentrate price-setting power and compress non-integrated manufacturer margins. The market supports long-term compounder positioning through regulatory-mandated product refresh cycles. Acquire biological-originated active ingredient specialists with MAFF registration pathways. Monitor PMDA toxicology review timeline extensions as signal for pipeline investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive supply of pyrethroid inputs insulates margins from East Asian corridor volatility. |
| Biological Active Ingredient Pipeline Expansion | MAFF residue testing protocols create market access pathways for microbial alternatives. |
| Drone Application Formulation Development | Ultra-low-volume chemistries align with UAV fleet deployment across Kanto Plain cooperatives. |
| Multi-Jurisdiction Compliance Bundling | Codex Alimentarius alignment enables premium positioning for export-oriented citrus operators. |
| Cooperative Direct Sales Channel Investment | JA-Zenchu platform relationships displace wholesale distributor margins. |
Research Methodology
Bottom-up agricultural application modeling reconciled against top-down active ingredient supply tracking forms the analytical core of this study. Primary interviews with formulation R&D directors, JA-Zenchu cooperative procurement managers, MAFF regulatory affairs specialists, and precision agriculture equipment distributors combined with secondary validation from customs trade data, MAFF pesticide registration databases, METI chemical substance filings, and SEC 10-K disclosures from listed chemical conglomerates. Triangulation between farmer-level demand aggregation and manufacturer production disclosures ensures volume reconciliation.
Historical trendline analysis across rice paddy herbicide consumption, protected cultivation fungicide uptake, and grain belt expansion patterns established baseline growth trajectories. Segmentation dimensions modeled include product type, formulation technology, application method, and regional cultivation cluster. CAGRs derived from curve-fitting across the projection horizon incorporate METI regulatory phase-in schedules and mechanization penetration curves. Industry-specific inputs include drone spraying equipment deployment rates and biological active ingredient registration timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA toxicology review delays and East Asian supply corridor disruptions. Forecasts reflect documented assumptions regarding cooperative procurement consolidation velocity and METI biodegradability mandate enforcement intensity. Practitioners should monitor JA-Zenchu platform contract renewal cycles and precursor import tariff adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Acaricides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Pest Management Services Market
Crop Protection
Herbicides Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
Canada Nematicides Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Captan Fungicide Market
Crop Protection
US Herbicide Market
Crop Protection
Asia-Pacific Molluscicides Market