
 Europe Nematicide Market | 2026-2036
Europe Nematicide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nematicide Market Insights
Biological fermentation platforms is fragmenting the Europe nematicide technology stack as manufacturers race to scale non-synthetic active ingredient production. BASF SE leverages its microbial strain libraries to anchor biological nematicide development pipelines. Syngenta AG competes through integrated seed treatment-to-soil application platforms that extend its crop protection franchise. Bayer AG specializes in nematode-resistant trait stacks, differentiating its portfolio from conventional chemistries.
A nematicide is a pesticide compound specifically formulated to kill or suppress plant-parasitic nematodes, typically containing organophosphates, carbamates, or microbial metabolites such as avermectins and applied through soil drenching, fumigation, or seed coating to protect root systems. Biological nematicides now command premium positioning as REACH registration costs and EU MDR-equivalent residue thresholds push formulators toward Bacillus-based and Purpureocillium-derived actives. Systemic nematicides retain volume leadership in high-value greenhouse applications where contact alternatives fail to penetrate dense root mats. Granular formulations dominate field-scale deployment, though liquid concentrates gain share in precision irrigation systems across Dutch and Belgian glasshouse operations.
EMA residue monitoring frameworks and EU Green Deal pesticide reduction targets constrain synthetic nematicide authorization timelines, forcing manufacturers to revalidate actives under tightened toxicology standards. REACH compliance and F-Gas Regulation analogs for soil fumigants add registration cost burdens that favor larger formulators with dedicated regulatory affairs teams. Stakeholders must weigh biological pipeline maturity against the revenue at risk from scheduled synthetic active withdrawals across core European markets.
Market Dynamics
The EU Green Deal pesticide reduction targets are compressing synthetic nematicide authorization timelines across Mediterranean horticulture belts, forcing formulators to revalidate actives under tightened EFSA toxicology standards while biological alternatives scale through REACH registration pathways.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory pesticide reduction targets are accelerating grower adoption of biological nematicides in Spain and Italy's vegetable production regions.
- Integrated pest management protocols:Meloidogyne nematode pressure in greenhouse tomatoes and peppers is driving soil treatment-to-seed coating system purchases.
- Biological fermentation scale-up:Manufacturers are expanding Bacillus-based and Purpureocillium-derived active ingredient production capacity to meet residue threshold requirements.
Market Restraints
- REACH registration cost escalation:Synthetic active revalidation under tightened standards requires dedicated regulatory affairs teams that favor larger formulators.
- Biological pipeline maturity gaps:Microbial metabolite efficacy inconsistency in dense root mat penetration limits greenhouse application reliability.
- F-Gas Regulation analogs for soil fumigants:Restrictions on conventional chemistries are removing established products before biological alternatives achieve equivalent performance.
Strategic Opportunities
- Precision irrigation integration:Dutch and Belgian glasshouse operators are adopting liquid concentrate nematicides through drip systems, displacing granular field-scale deployment.
- Biological seed treatment expansion:EU Green Deal compliance incentives are opening premium positioning for microbial strain-based coatings in vegetable crop programs.
- EMA residue monitoring frameworks:Harmonized MDR-equivalent thresholds across member states are creating standardized market access for compliant biological formulations.
Industry Challenges
- Regulatory affairs talent scarcity:REACH toxicology documentation and EFSA residue submission expertise concentrates in specialized consultancies, constraining in-house capability building.
- Biological formulation stability:Bacillus spore viability maintenance through supply chain temperature excursions requires cold chain infrastructure investment that mid-tier formulators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nematicide Market |
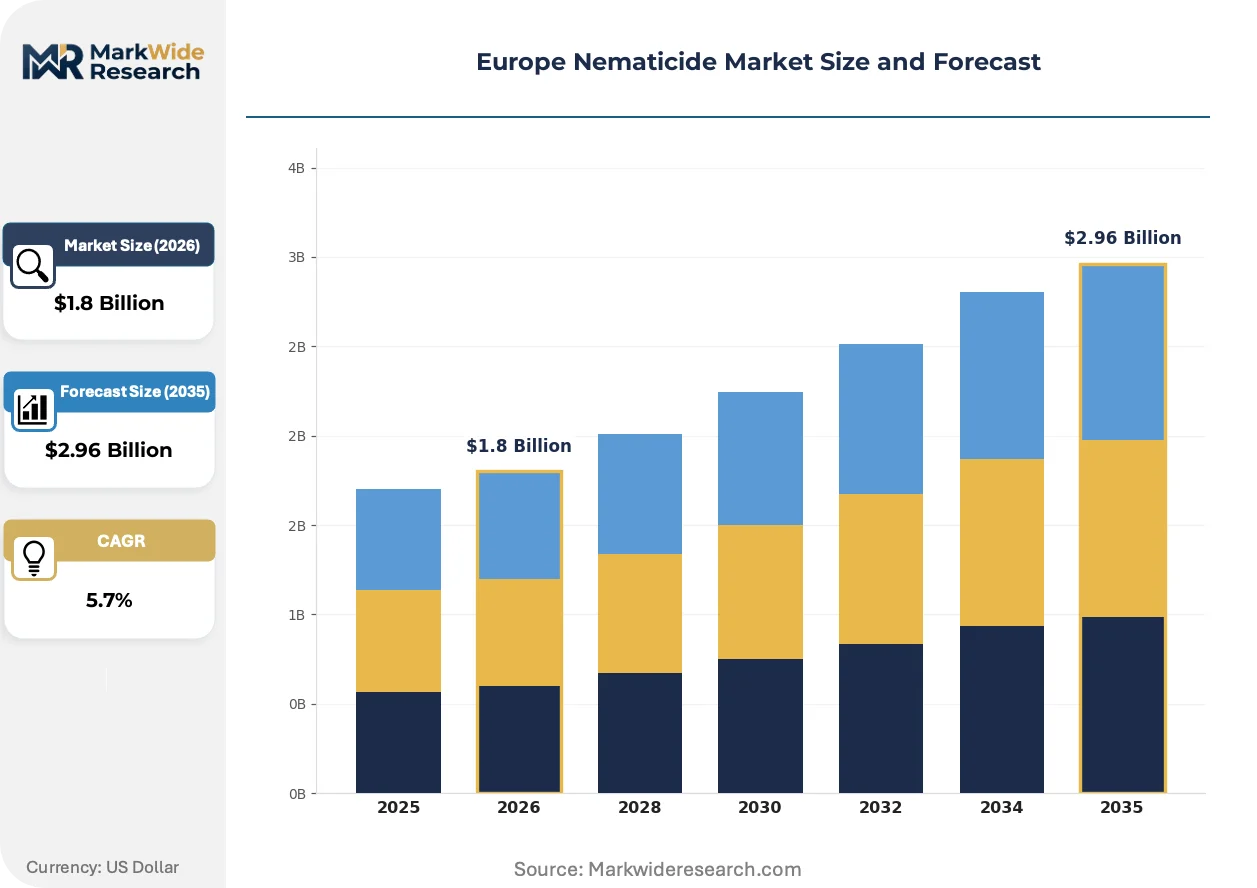
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Fumigants, Contact Nematicides, Systemic Nematicides, Biological Nematicides Application: Crops, Turf, Ornamentals, Greenhouses Form: Granular, Liquid, Solid, Powder Distribution Channel: Online, Retail Stores, Agricultural Cooperatives, Direct Sales |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, FMC Corporation, Corteva Agriscience, UPL Limited, ADAMA Agricultural Solutions, Sumitomo Chemical, Certis Biologicals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nematicide Market Trends and Innovations
Biological active ingredient platforms are displacing synthetic chemistries across European nematicide portfolios as regulatory pressure and grower sustainability commitments converge on microbial-derived solutions.
Microbial strain libraries from agricultural biotechnology collections are collapsing development timelines for new biological nematicides. Spanish and Italian vegetable cooperatives are integrating these actives into IPM programs at accelerating pace. The technology is collapsing the historical 8-10 year synthetic registration cycle into 3-5 year biological pathways, compressing competitive moats around established chemistries.
REACH authorization amendments for microbial pest control agents are streamlining biological nematicide market entry across EU member states. The regulatory shift is reducing equivalence data requirements for Bacillus firmus and Purpureocillium lilacinum strains with established safety profiles. Greenhouse operators in the Netherlands and Belgium are capturing first-mover advantages through early adoption of these streamlined registration products.
Outcome-based crop protection contracting is displacing traditional product-purchase models in high-value horticulture supply chains. Spanish tomato exporter cooperatives are negotiating root health guarantees rather than active ingredient volumes, transferring nematode control performance risk to formulators. The model is most visible in Almeria's integrated pest management clusters where processor consolidation has concentrated buyer leverage.
Europe Nematicide Market Segmentation
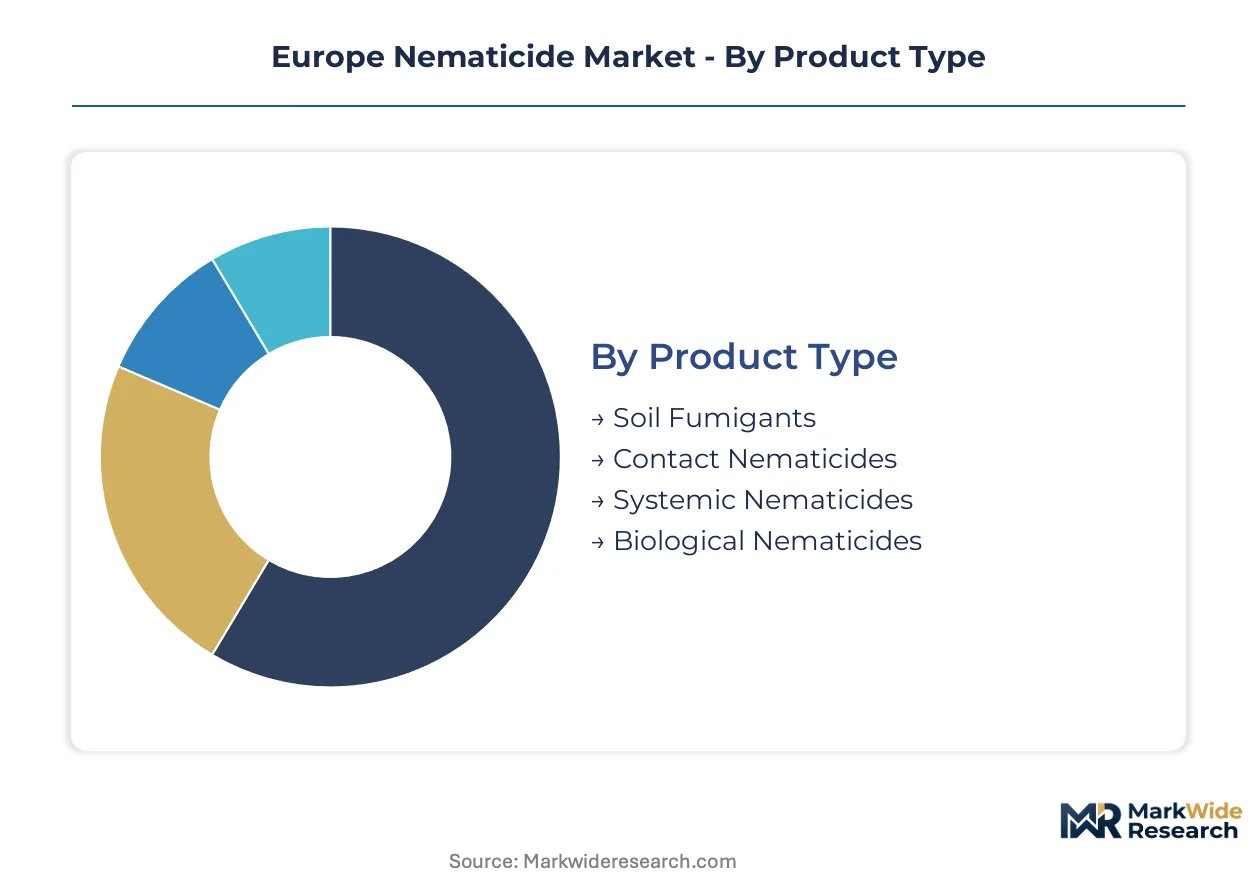
European nematicide procurement patterns diverge sharply across product categories, with biological alternatives commanding premium service relationships while legacy chemistries compete on volume logistics. Formulator support intensity varies by segment maturity, creating distinct margin architectures across the value chain.
Product Type:
After-sales service intensity peaks with biological nematicides, where viability monitoring and application timing advisory dominate customer retention economics.
- Biological Nematicides:Microbial formulations derived from Bacillus firmus and Purpureocillium lilacinum strains require cold chain stewardship and field efficacy troubleshooting. Dutch glasshouse operators in Westland and Aalsmeer purchase these with bundled technical support contracts due to temperature sensitivity and inconsistent root mat penetration.
- Systemic Nematicides:Organophosphate and carbamate chemistries translocate through plant vascular systems to protect root zones from endoparasitic nematodes. Spanish vegetable cooperatives in Almería and Murcia deploy these in high-value greenhouse tomatoes where contact alternatives fail to reach dense root systems, though EFSA reauthorization timelines compress product lifecycles.
- Contact Nematicides:Surface-acting compounds create lethal zones in rhizosphere soil without plant uptake. Italian open-field vegetable producers in Emilia-Romagna favor these for cost efficiency in lower-value crops.
- Soil Fumigants:Volatile pre-plant treatments sterilize soil profiles through fumigation. Belgian potato growers in Flanders apply these under increasingly strict F-Gas Regulation analogs restricting methyl bromide successors.
Systemic nematicides hold the largest share; momentum sits with biological alternatives.
Application:
Margin structures vary by cultivation intensity, with greenhouse applications supporting premium pricing through integrated pest management bundling.
- Greenhouses:Controlled-environment horticulture demands precision nematode management in substrate-based systems. Netherlands and Belgium operations invest in drip-integrated liquid applications with real-time monitoring, where Meloidogyne pressure in tomato and pepper crops justifies elevated input costs.
- Crops:Open-field vegetable and row crop production across Mediterranean Europe accounts for volume consumption. Spanish carrot and potato growers in Castilla-La Mancha balance biological program costs against EU Green Deal compliance incentives.
- Turf:Golf course and sports field maintenance in France and Germany drives seasonal demand for nematicides targeting Anguina and other turfgrass parasites.
- Ornamentals:Nursery stock and cut flower production in Italy and the Netherlands requires phytosanitary certification compliance for export markets.
Crop applications dominate volume; greenhouse segments generate steepest expansion trajectory.
Form:
Supply chain configuration determines form selection, with liquid concentrates gaining share through precision irrigation infrastructure investment.
- Liquid:Concentrates and emulsifiable formulations integrate with fertigation systems for targeted rhizosphere delivery. Belgian and Dutch operators retrofit drip infrastructure to accommodate these products, displacing broadcast granular methods.
- Granular:Slow-release pellets dominate field-scale deployment where mechanized application equipment prevails. French cereal and vegetable producers in Brittany and Normandy rely on established spreading protocols.
- Solid:Tablet and briquette formats serve specialized fumigation and spot-treatment applications.
- Powder:Wettable powders persist in manual application contexts and smallholder cooperatives with limited equipment access.
Granular formulations retain volume leadership; liquid concentrates are climbing the fastest.
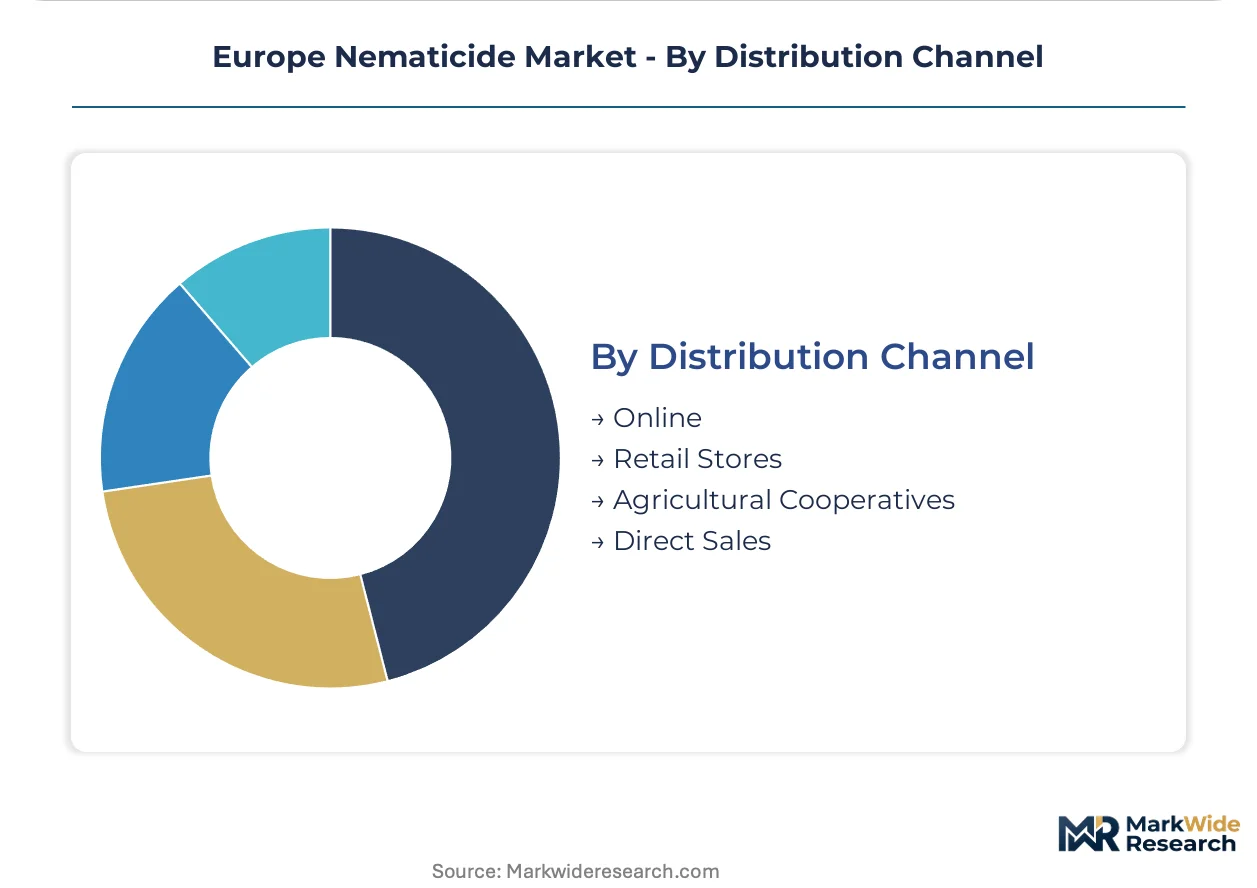
Distribution Channel:
Channel selection reflects farm scale and technical complexity, with cooperatives anchoring biological product adoption through collective purchasing power.
- Agricultural Cooperatives:Member-owned purchasing organizations aggregate demand and negotiate technical service packages. Italian vegetable cooperatives in Puglia and Sicily coordinate biological nematicide trials and shared cold chain logistics.
- Direct Sales:Formulator-to-grower relationships support high-value greenhouse accounts with customized IPM protocols. Spanish integrated pest management clusters in Almería source directly for outcome-based contracting.
- Retail Stores:Independent agrochemical distributors serve fragmented smallholder markets with standard product portfolios.
- Online:Digital procurement platforms emerge for replenishment purchasing of established products with documented application protocols.
Agricultural cooperatives command the largest channel share; direct sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vegetable cooperatives and greenhouse operators drive procurement across Mediterranean and Western European horticulture belts, with regulatory pressure from Brussels accelerating biological nematicide adoption in high-value production zones.
Spain
Almería and Murcia greenhouse clusters account for concentrated nematicide consumption in tomato and pepper production. The EU Green Deal pesticide reduction targets force cooperatives to revalidate synthetic actives under tightened EFSA standards while scaling Purpureocillium-based alternatives. Castilla-La Mancha carrot growers balance biological program costs against Farm to Fork compliance incentives.
Italy
Emilia-Romagna open-field vegetable producers favor contact nematicides for cost efficiency in lower-value crops. REACH registration cost escalation concentrates biological adoption in Puglia and Sicily cooperatives with shared cold chain logistics. Tomato exporter groups in southern regions negotiate outcome-based root health guarantees rather than active ingredient volumes.
Netherlands
Westland and Aalsmeer glasshouse operators purchase Bacillus-based formulations with bundled technical support contracts due to temperature sensitivity. Precision irrigation infrastructure retrofits accommodate liquid concentrate delivery through drip systems. Dutch operators capture first-mover advantages from streamlined REACH authorization amendments for microbial pest control agents.
Belgium
Flanders potato growers apply soil fumigants under increasingly strict F-Gas Regulation analogs restricting methyl bromide successors. Belgian glasshouse operations invest in drip-integrated liquid applications with real-time monitoring where Meloidogyne pressure justifies elevated input costs. The country's central distribution position serves cross-border horticulture supply chains into France and Germany.
France
Brittany and Normandy cereal and vegetable producers rely on established granular spreading protocols for field-scale deployment. Golf course and sports field maintenance in metropolitan regions drives seasonal demand for turfgrass nematicides. French cooperatives aggregate biological nematicide demand to negotiate technical service packages with formulators.
Europe Nematicide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure favoring integrated crop protection portfolios. Consolidation pressure intensifies as REACH compliance costs and biological fermentation scale-up requirements create tiered competitive positions. Three archetypes dominate: multinational agrochemical conglomerates with seed treatment integration, dedicated biological formulators with microbial strain libraries, and regional cooperatives with captive distribution networks. Dominant competitive moves include portfolio diversification into biological actives and strategic partnerships for fermentation capacity access.
Within the multinational tier, BASF SE, Syngenta AG, and Bayer AG exemplify divergent strategic positioning. BASF SE anchors its development pipeline through microbial strain library leverage. Syngenta AG occupies a position emphasizing integrated seed treatment-to-soil application platforms. Bayer AG represents the nematode-resistant trait stack specialization archetype, differentiating from conventional chemistry approaches. These three conglomerates sit within the premium service tier where bundled technical advisory and regulatory compliance support command margin premiums over commodity formulation competitors.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| FMC Corporation |
| Corteva Agriscience |
| UPL Limited |
| ADAMA Agricultural Solutions |
| Sumitomo Chemical |
| Certis Biologicals |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Bacillus-based fermentation facilities across Western Europe is compressing biological nematicide margins while concentrating pricing power among formulators with captive cold chain networks. Dutch and Belgian glasshouse operators leverage this surplus to negotiate bundled technical service contracts that embed viability guarantees into per-hectare pricing structures.
Pricing Analysis
Cost-plus contracts indexed to glucose feedstock and electricity tariffs dominate biological nematicide procurement between Spanish vegetable cooperatives and fermentation suppliers. Three-tier pricing structure across premium, standard, and economy levels separates cold chain-stewarded formulations from ambient-stable generics and commodity organophosphates. Pricing pressure stems from REACH registration cost escalation favoring larger formulators with dedicated regulatory affairs teams. Smallholder cooperatives in Italy's Puglia region exhibit highest price sensitivity, while Dutch IPM clusters purchasing outcome-based root health guarantees show lowest elasticity.
Supply Chain Analysis
Export-control regimes restricting dual-use fermentation technology limit microbial strain transfers from German and Dutch biotech collections to non-EU production sites. Active ingredient supply concentrates in Germany, the Netherlands, and Denmark, with formulation finishing distributed across Spain, Italy, and France. Raw material dependencies span glucose feedstocks, specialized bioreactor vessels, and temperature-controlled packaging. Single-source vulnerability runs through cold chain logistics providers serving biological nematicide distribution. Distribution runs through agricultural cooperatives aggregating demand for technical service bundles, supplemented by direct sales to integrated pest management clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward processor-consolidated horticulture cooperatives in Spain and Italy, where Almería tomato exporter groups now negotiate outcome-based root health guarantees rather than active ingredient volumes. This consolidation fragments supplier leverage across fragmented mid-tier formulators.
For Market Incumbents: Build regulatory affairs capability moats by embedding EFSA submission expertise in-house rather than outsourcing to specialized consultancies. Defensive moves center on backward integration into Bacillus strain library acquisition and captive fermentation capacity expansion in the Netherlands to secure cold chain stewardship. Threats emanate from streamlined REACH authorization amendments collapsing biological registration timelines for emerging competitors. Channel control through cooperative technical service contracts represents the critical lever for margin defense. For New Entrants and Emerging Players: Establish a beachhead in Italian open-field vegetable segments where contact nematicide substitution lags greenhouse adoption curves. White-space targets include Emilia-Romagna carrot producers and Castilla-La Mancha potato cooperatives seeking EU Green Deal compliance without premium biological pricing. The most penetrable segment is smallholder cooperatives with limited equipment access favoring wettable powder formulations. Go-to-market angle should emphasize shared cold chain logistics partnerships with established distributors to bypass infrastructure investment barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biological formulators with bundled technical support contracts in Dutch and Belgian glasshouse segments. Long-term viability favors acquisition targets with microbial strain libraries and REACH-authorized Purpureocillium lilacinum portfolios positioned for EFSA residue threshold tightening. The signal to watch is EMA harmonization of MDR-equivalent thresholds across member states, which would standardize market access and accelerate biological displacement of synthetic chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Bacillus production insulates margin from glucose feedstock volatility and cold chain subcontractor reliance. |
| Microbial Strain Library Acquisition | Purpureocillium and Bacillus firmus collections collapse development timelines under streamlined REACH microbial pest control agent pathways. |
| Outcome-Based Contracting Expansion | Root health guarantees transfer nematode control performance risk from Almería cooperatives to formulators, embedding recurring revenue. |
| Precision Irrigation Integration Partnerships | Drip system retrofit alliances in Westland glasshouses displace granular field-scale deployment with liquid concentrate adoption. |
| Regulatory Affairs Capability Buildout | In-house EFSA toxicology documentation reduces reliance on specialized consultancies constraining mid-tier competitor scaling. |
Research Methodology
Operator-level perspectives from greenhouse technical managers, cooperative procurement leads, biological formulator R&D directors, and EFSA regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation against EMA residue monitoring frameworks, EU Green Deal implementation reports, REACH authorization amendment documentation, and customs data tracking nematicide active ingredient trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European horticulture sector.
Scenario-bracketing framed projections across regulatory acceleration and biological pipeline maturity assumptions throughout the forecast period. Segmentation dimensions modeled include product type, application intensity, formulation stability requirements, and distribution channel control. CAGRs derived from historical authorization timeline compression and adoption curve analysis. Industry-specific forecast inputs incorporated EFSA reauthorization schedules for organophosphate actives and Farm to Fork Strategy compliance incentive trajectories.
Stress conditions across EFSA toxicology standard tightening velocity, biological fermentation yield variability, and cooperative buyer consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding REACH implementation consistency and EU member state harmonization progress. Material shifts in EU Green Deal pesticide reduction target enforcement intensity or microbial pest control agent authorization pathway amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
Pest Management Services Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Europe Insecticides Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Azoxystrobin Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Germany Crop Protection Chemicals Market