
 Oseltamivir Market | 2026-2036
Oseltamivir Market Size, Share, and Industry Trends Forecast 2026-2036
Oseltamivir Market Analysis
Pharmacopeial-grade oseltamivir phosphate is redrawing procurement benchmarks across public health systems. F. Hoffmann-La Roche Ltd anchors originator-quality supply chains through its established synthesis infrastructure. Hetero Healthcare Limited leverages backward integration into active pharmaceutical ingredient production to sustain cost-competitive positioning. NATCO Pharma Limited specializes in generic capsule formulations that dominate institutional tender markets across emerging economies.
Oseltamivir is a neuraminidase inhibitor administered orally for influenza treatment and prophylaxis, typically formulated as the phosphate salt with specified purity thresholds exceeding 98.5 percent to meet pharmacopeial monographs. The compound blocks viral release from host cells, reducing symptom duration when administered within 48 hours of onset. Capsules and tablets command the largest volume share due to shelf stability and dosing precision in hospital formularies, while oral suspension formats are gaining traction in pediatric and geriatric home care settings where swallowing difficulties limit solid-dose adherence. Distribution through hospital and clinic channels captures the highest-margin transactions tied to pandemic stockpiling protocols, whereas retail and online pharmacy penetration reflects growing outpatient prophylaxis demand.
The US FDA, WHO prequalification programme, and India's CDSCO collectively govern market access through bioequivalence requirements and good manufacturing practice audits that filter substandard suppliers from tender eligibility. REACH compliance in Europe and EMA centralized marketing authorizations add layered certification costs that favor manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor national pandemic preparedness budgets and seasonal influenza severity indices to align production cycles with procurement windows.
Market Dynamics
Hospital procurement of antiviral stockpiles is tightening around pharmacopeial-grade specifications as influenza surveillance networks expand their geographic coverage and detection sensitivity. This specification squeeze is compressing margins for non-compliant suppliers while rewarding manufacturers with dedicated synthesis infrastructure and regulatory affairs capacity.
Growth Catalysts
- Emergency Use Authorization Pathways:The US FDA's streamlined EUA frameworks accelerate stockpile procurement cycles, enabling rapid tender awards during surveillance alerts without full NDA review timelines.
- WHO Prequalification Standards:Institutional buyers in low- and middle-income countries now mandate PQ certification for tender eligibility, filtering substandard suppliers from pooled procurement mechanisms.
- India's API Manufacturing Scale:Domestic active pharmaceutical ingredient production under CDSCO oversight is reducing import dependency and shortening supply lead times for government immunization programs.
Market Restraints
- Shikimic Acid Supply Concentration:Star anise extraction and fermentation-derived precursors remain concentrated in Chinese manufacturing clusters, exposing formulation plants to raw material volatility.
- REACH Compliance Burden:ECHA registration requirements and EMA centralized marketing authorizations impose layered certification costs that disproportionately burden mid-scale generic manufacturers.
- Neuraminidase Inhibitor Substitution:Baloxavir marboxil's single-dose regimen and polymerase inhibition mechanism are capturing prophylaxis prescriptions from oseltamivir in outpatient settings.
Strategic Opportunities
- Pediatric Oral Suspension Formats:Geriatric and pediatric home care segments with swallowing difficulties present unmet demand for liquid formulations with extended stability profiles.
- India's PLI Scheme Incentives:Production-linked incentives for bulk drug manufacturing under DGFT notification are subsidizing capital expansion into neuraminidase inhibitor API synthesis.
- Online Pharmacy Channel Penetration:Direct-to-patient distribution models are bypassing traditional wholesale hierarchies for post-exposure prophylaxis prescriptions in urban outpatient markets.
Industry Challenges
- Bioequivalence Study Backlogs:CDSCO and US FDA inspection queues for generic capsule formulations are extending time-to-market for abbreviated new drug applications.
- Multi-Site GMP Audit Complexity:Synchronized good manufacturing practice inspections across API and finished dosage facilities require dedicated quality systems infrastructure that strains mid-tier organizational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oseltamivir Market |
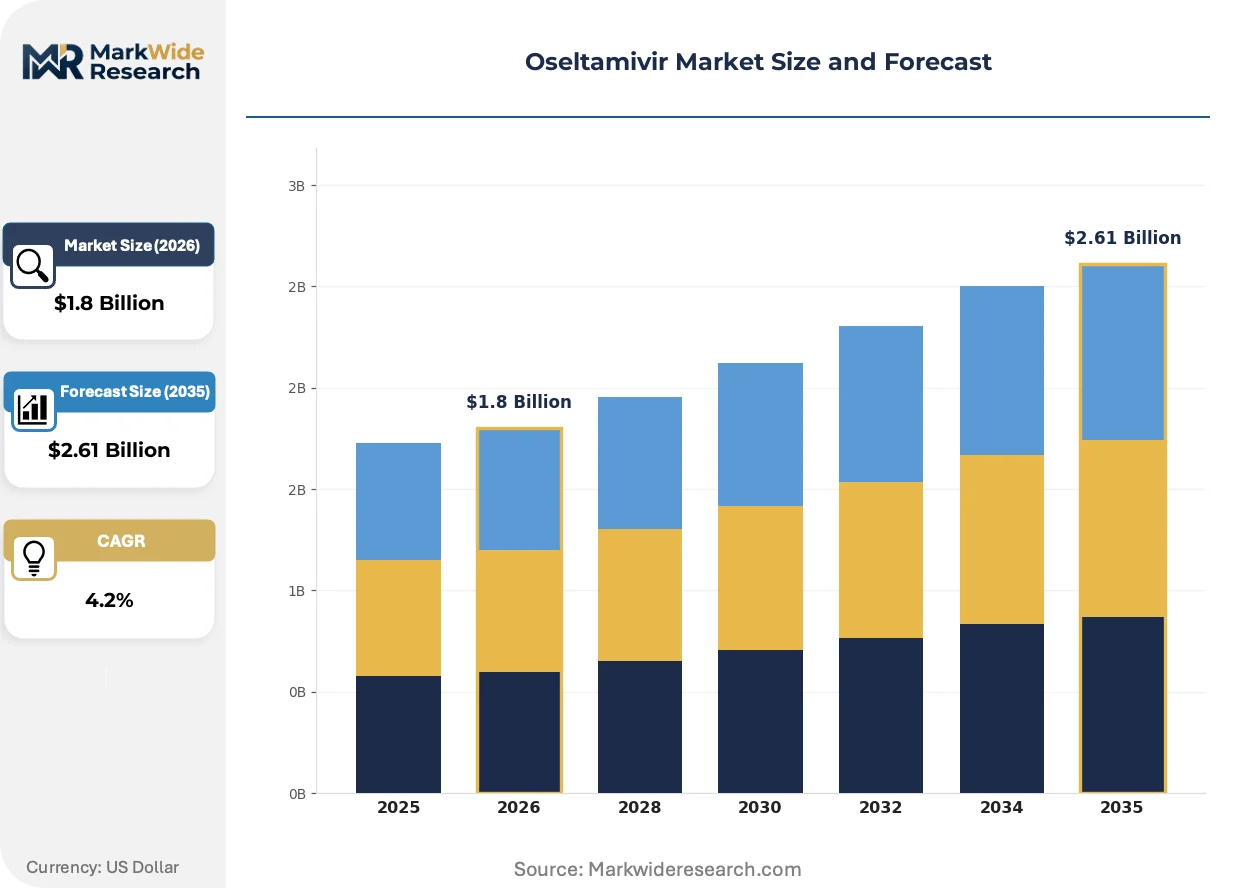
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oral Suspension, Injection, Tablets End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Direct Sales, Retail, Online Pharmacies, Wholesalers Formulation: Powder, Liquid, Coated, Extended Release |
| Companies Covered | NATCO Pharma Limited, Amneal Pharmaceuticals LLC, F. Hoffmann-La Roche Ltd, Hetero Healthcare Limited, Alembic Pharmaceuticals Limited, Cipla Inc, Macleods Pharmaceuticals Ltd, Lupin Limited, Zydus Cadila, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oseltamivir Market Emerging Trajectories
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times while tightening purity specifications beyond traditional pharmacopeial thresholds. These process innovations are redrawing competitive barriers between originator-quality and commodity-grade supply tiers.
Flow chemistry for oseltamivir phosphate synthesis is decomposing the traditional batch-reactor paradigm that has dominated neuraminidase inhibitor manufacturing for two decades. Contract development and manufacturing organizations in India and Switzerland are retrofitting multi-purpose plants with continuous processing skids to reduce solvent waste and improve yield consistency. This technology transition is decomposing the cost advantage previously held by high-volume batch producers with depreciated capital equipment.
REACH authorization requirements for pharmaceutical intermediates are tightening substance volume tracking and safety data sheet obligations across European supply chains. ECHA's 2024 updates to extended safety data sheet formats are forcing API exporters to re-document impurity profiles and occupational exposure limits. Formulation facilities in Germany and France are absorbing these compliance costs through dedicated regulatory affairs hires rather than passing through to tender prices.
Hospital formulary committees are consolidating antiviral procurement around single-source contracts with pandemic stockpile guarantees attached. Group purchasing organizations are displacing fragmented clinic-level purchasing for seasonal influenza preparedness. This concentration pattern is most visible in US integrated delivery networks and NHS England trust procurement frameworks, where multi-year agreements bundle treatment courses with real-time inventory monitoring systems.
Oseltamivir Market Segmentation
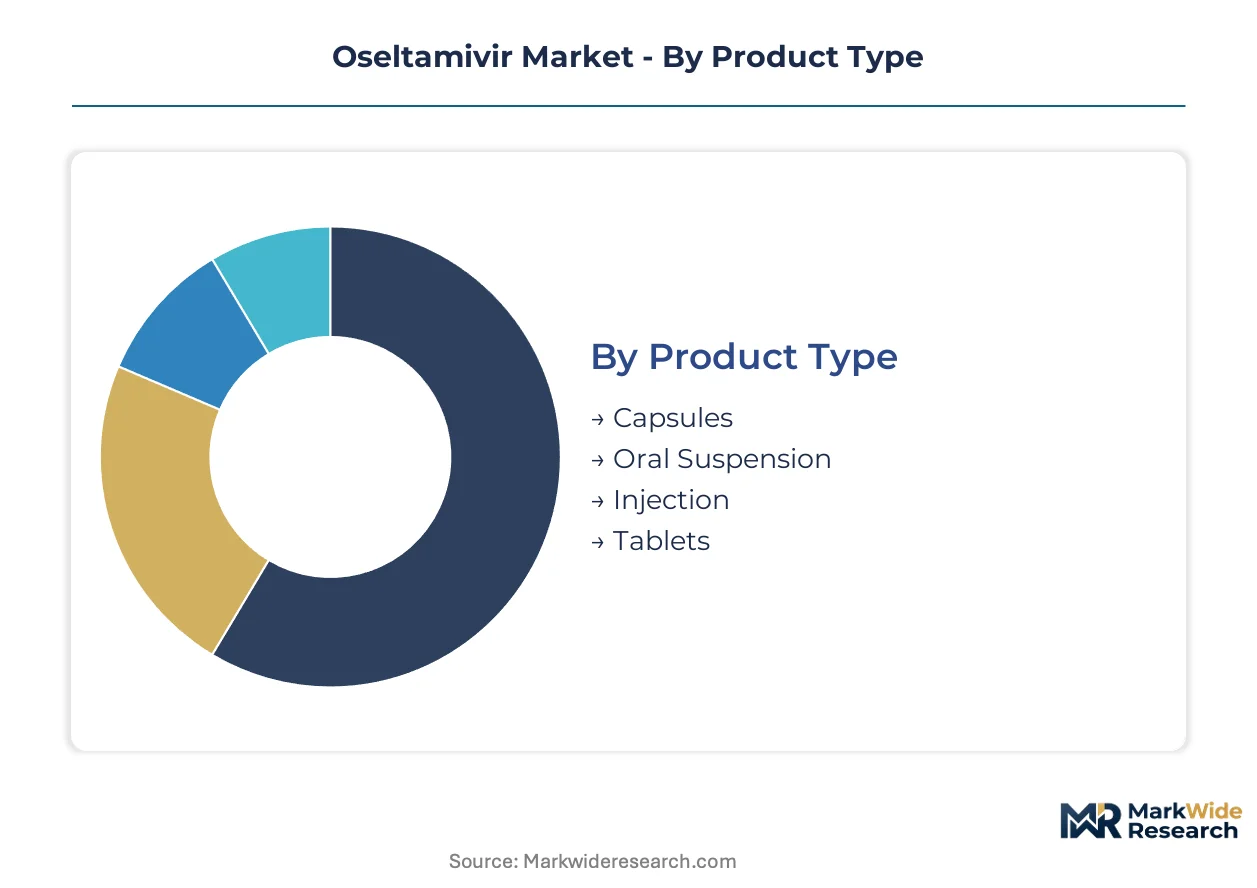
Neuraminidase inhibitor procurement patterns diverge sharply across dosage forms and care settings. Hospital formulary committees, retail pharmacy chains, and direct-to-patient platforms each impose distinct specification requirements that filter supplier eligibility differently.
Product Type:
Margin pools concentrate in solid-dose formats where pharmacopeial certification commands tender premiums, while liquid formulations capture pediatric and geriatric niches with limited competition.
- Capsules:Hard gelatin shells containing oseltamivir phosphate at 75mg standard strength dominate institutional stockpiling protocols. Hospital procurement in India and the United States concentrates demand here due to shelf stability exceeding 36 months and precise unit-dose accountability for pandemic inventory audits.
- Tablets:Compressed dosage forms with film coatings protect API from moisture degradation during tropical distribution. CDSCO-approved facilities in Hyderabad and Ahmedabad supply government immunization programs with cost-competitive tenders that undercut originator pricing by 40-60 percent.
- Oral Suspension:Reconstituted powder suspensions address swallowing difficulties in pediatric populations under 12 years.
- Injection:Intravenous formulations remain limited to critical care settings with severe influenza complications.
Capsules hold installed capacity. Oral Suspension is rotating up the share rankings.
End User:
Volume concentrates in acute care institutions where formulary lock-in creates multi-year contract visibility, while outpatient channels fragment across competing retail networks.
- Hospitals:Integrated delivery networks and NHS England trusts bundle antiviral procurement with real-time inventory monitoring systems. Pandemic preparedness budgets in the United States and United Kingdom mandate 90-day stockpile coverage, creating predictable offtake commitments for qualified suppliers.
- Home Care:Post-exposure prophylaxis prescriptions for household contacts drive demand outside institutional settings. Online pharmacy penetration in urban Indian and American markets enables direct-to-patient fulfillment that bypasses traditional wholesale markups.
- Clinics:Outpatient influenza diagnosis triggers same-day dispensing in urgent care chains.
- Pharmacies:Retail chains capture seasonal prophylaxis demand from travelers and healthcare workers.
Hospitals anchor procurement volume. Home Care is climbing the fastest as distribution models shift.
Distribution Channel:
Channel selection determines working capital intensity and regulatory documentation burden, with direct sales offering margin protection at the cost of dedicated account management infrastructure.
- Direct Sales:Manufacturer-to-institution contracts eliminate distributor margins and enable lot-traceability requirements for WHO prequalification compliance. Roche and Hetero Healthcare Limited deploy dedicated hospital account teams to secure multi-year antiviral stockpile agreements with procurement guarantees.
- Online Pharmacies:Digital platforms capture post-exposure prophylaxis demand from urban professionals seeking convenience. India's e-pharmacy regulations under CDSCO oversight require prescription verification protocols that filter unlicensed sellers from legitimate market participation.
- Retail:Brick-and-mortar pharmacy chains compete on seasonal availability during influenza surges.
- Wholesalers:Traditional distribution hierarchies retain rural and small-clinic coverage where direct sales economics fail.
Direct Sales holds installed capacity. Online Pharmacies is gaining share fastest through urban penetration.
Formulation:
Processing complexity and stability requirements create tiered manufacturing barriers, with immediate-release powders dominating volume and extended-release formats pursuing differentiation premiums.
- Powder:Bulk oseltamivir phosphate for reconstitution offers the lowest per-dose manufacturing cost and longest shelf life. API producers in Hyderabad and Visakhapatnam supply this base material to formulation facilities across emerging markets under CDSCO export certification.
- Liquid:Ready-to-use suspensions reduce preparation errors in pediatric administration. European REACH compliance for solvent residuals and preservative systems restricts supplier eligibility to manufacturers with dedicated regulatory affairs capacity.
- Coated:Enteric and moisture-barrier coatings protect API during tropical distribution.
- Extended Release:Modified-release matrices pursue once-daily dosing convenience that neuraminidase inhibitor pharmacokinetics rarely support.
Powder holds installed capacity. Liquid is rotating up the share rankings through pediatric demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis for neuraminidase inhibitors clusters in Indian pharmaceutical corridors and Chinese precursor manufacturing zones, with formulation capacity dispersing across European packaging facilities and North American distribution hubs. Regulatory divergence between FDA emergency use frameworks and EMA centralized authorizations fragments procurement standards across jurisdictions. Pandemic stockpiling mandates in the United States and United Kingdom create predictable demand anchors that contrast with India's government immunization program scaling.
United States
Hospital formulary consolidation and integrated delivery network procurement bundles concentrate antiviral purchasing power. FDA emergency use authorization pathways compress tender cycles during influenza surveillance alerts. The Southeast region, particularly Georgia and Florida distribution hubs, anchors seasonal stockpile deployment logistics for federal pandemic preparedness reserves.
India
Government immunization program expansion and domestic API manufacturing incentives drive procurement volume concentration. CDSCO oversight of bulk drug production and export certification shortens supply lead times for institutional buyers. Hyderabad and Visakhapatnam pharmaceutical clusters house backward-integrated synthesis facilities serving both domestic tenders and WHO prequalification markets.
China
Shikimic acid precursor extraction from star anise and fermentation-derived supply chains remain concentrated in manufacturing clusters. NMPA regulatory harmonization with ICH standards streamlines export documentation for API producers. Zhejiang and Jiangsu province chemical parks host intermediate synthesis operations feeding formulation plants across Asia-Pacific markets.
Germany
EMA centralized marketing authorization requirements and REACH compliance burdens filter supplier eligibility toward manufacturers with dedicated regulatory capacity. Hospital procurement through NHS England trust frameworks influences continental tender specifications for pandemic stockpile guarantees. Bavaria and North Rhine-Westphalia packaging facilities specialize in cold-chain distribution for liquid suspension formats.
Switzerland
Contract development and manufacturing organizations retrofit continuous processing platforms for neuraminidase inhibitor synthesis. Swissmedic marketing authorization procedures align with EMA standards while maintaining distinct inspection protocols. Basel-region pharmaceutical services clusters provide regulatory affairs consulting for API exporters seeking European market access.
Oseltamivir Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with originator-quality manufacturers maintaining synthesis infrastructure advantages while generic specialists capture institutional tender markets through backward integration. The vendor base separates into three tiers: originator-quality suppliers with dedicated regulatory affairs capacity, mid-scale generic manufacturers with CDSCO-approved facilities, and commodity-grade producers filtered from WHO prequalification eligibility. Dominant competitive moves include capacity expansion into pediatric liquid formulation lines and strategic partnerships with group purchasing organizations for multi-year stockpile contracts.
Among Indian pharmaceutical conglomerates, NATCO Pharma Limited and Hetero Healthcare Limited occupy positions within the generic API-to-formulation integrated tier, while F. Hoffmann-La Roche Ltd exemplifies the originator-quality archetype with established pharmacopeial-grade supply chains. These three entities represent distinct strategic postures: backward-integrated cost leadership, domestic market scale concentration, and regulatory-premium positioning respectively.
| Leading Market Players |
|---|
| NATCO Pharma Limited |
| Amneal Pharmaceuticals LLC |
| F. Hoffmann-La Roche Ltd |
| Hetero Healthcare Limited |
| Alembic Pharmaceuticals Limited |
| Cipla Inc |
| Macleods Pharmaceuticals Ltd |
| Lupin Limited |
| Zydus Cadila |
| Others |
Supply Flow & Price Mechanics
Ninety-day stockpile coverage mandates compress tender cycles to 45-60 day windows, concentrating pricing power with manufacturers holding dedicated synthesis infrastructure and WHO prequalification status while squeezing commodity-grade suppliers from institutional eligibility.
Pricing Analysis
WHO prequalification standards dictate the pricing tier structure across public procurement markets. Three-tier pricing structure across originator-grade, pharmacopeial-certified, and commodity-grade levels separates Roche's established supply chains from Hetero's backward-integrated operations and substandard producers filtered from tender pools. Cost compression in the commodity tier is intensifying because CDSCO and US FDA bioequivalence backlogs extend time-to-market for abbreviated new drug applications. Government immunization programs in India exhibit the highest price sensitivity, while US integrated delivery networks prioritize pandemic stockpile guarantees over per-dose cost minimization.
Supply Chain Analysis
Inventory volatility in shikimic acid precursors extends API lead times to 120-180 days during influenza surge periods, exposing formulation plants to raw material volatility. Active pharmaceutical ingredient synthesis clusters in India, China, and Switzerland feed downstream formulation facilities across North America and Europe. Fermentation-derived and star anise-extracted precursors draw from Zhejiang and Jiangsu province chemical parks, creating single-source vulnerability for neuraminidase inhibitor production. Distribution runs through hospital procurement bundles and direct manufacturer-to-institution contracts with lot-traceability requirements for WHO compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
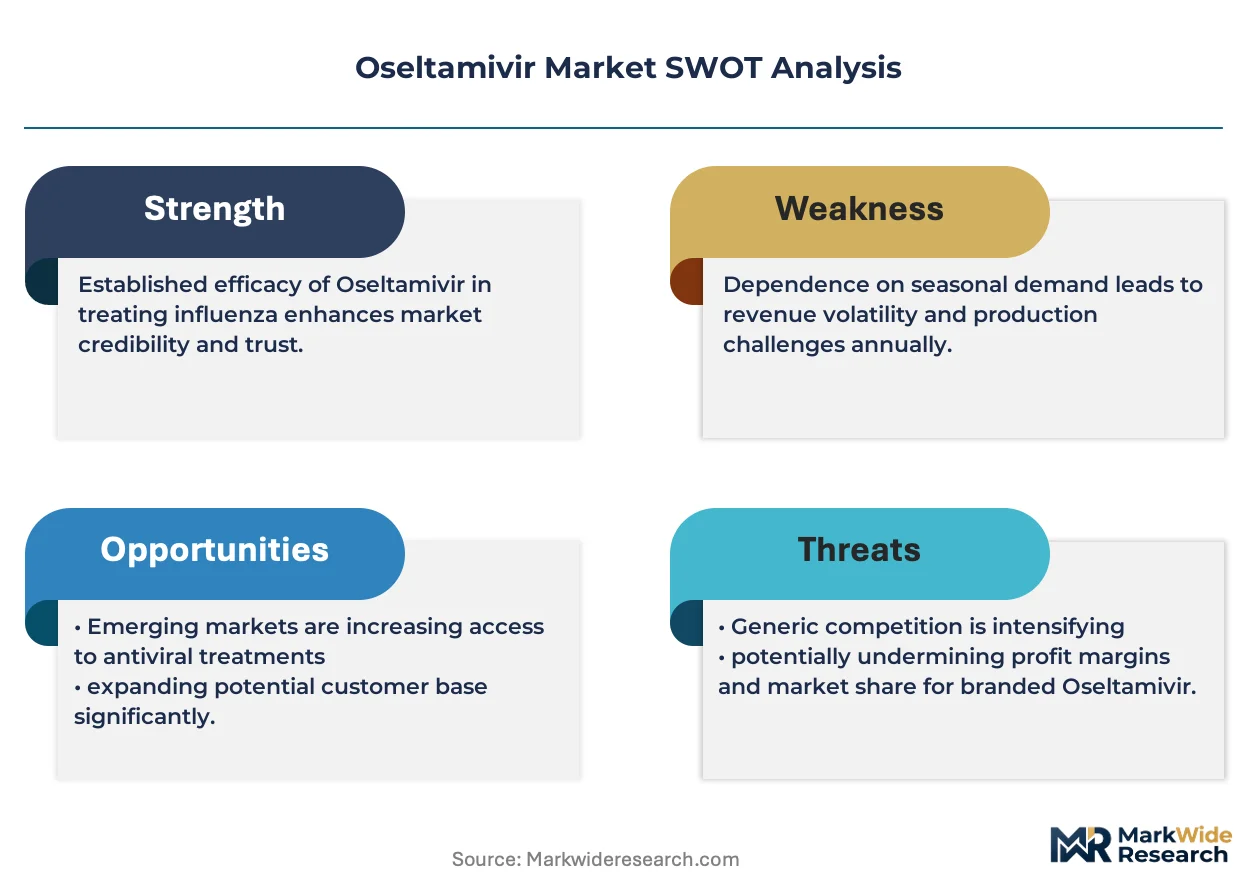
The oseltamivir market functions as a regulatory-moat arena where WHO prequalification and FDA emergency use authorization create switching costs that entrench qualified suppliers and filter marginal competitors from tender eligibility.
For Market Incumbents: Secure multi-year stockpile agreements with group purchasing organizations by attaching real-time inventory monitoring systems to tender awards. Deepen backward integration into shikimic acid precursor production through fermentation technology licensing or captive supply arrangements with Zhejiang chemical parks to neutralize raw material volatility exposure from Chinese manufacturing clusters. For New Entrants and Emerging Players: Anchor in pediatric oral suspension formats where geriatric and home care demand expansion outpaces qualified supplier capacity. Target India's production-linked incentive scheme for bulk drug manufacturing under DGFT notification to subsidize capital expansion into neuraminidase inhibitor API synthesis, then pursue CDSCO export certification for WHO prequalification eligibility. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-scale generic manufacturers with CDSCO-approved facilities but incomplete regulatory affairs infrastructure for EMA centralized marketing authorizations. Assess viability through a 5-10 year window anchored to national pandemic preparedness budget trajectories rather than seasonal influenza severity alone. Monitor baloxavir marboxil prescription capture rates in outpatient prophylaxis settings as the critical substitution threat signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | Flow chemistry platforms in Swiss CDMOs reduce solvent waste and compress batch cycle times below traditional pharmacopeial thresholds. |
| Pediatric Formulation Line Expansion | Liquid suspension capacity addresses swallowing difficulties in home care segments with limited qualified supplier competition. |
| WHO Prequalification Pursuit | PQ certification unlocks pooled procurement mechanisms for institutional buyers in low- and middle-income countries. |
| Shikimic Acid Supply Diversification | Fermentation-derived precursor production reduces dependency on Chinese star anise extraction concentration. |
| Direct-to-Patient Channel Development | Online pharmacy penetration bypasses wholesale markups for post-exposure prophylaxis in urban Indian and American markets. |
Methodological Framework
Operator-level perspectives from regulatory affairs directors, hospital formulary committee members, CDSCO inspection leads, and API synthesis plant managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA emergency use authorization filings, WHO prequalification inspection reports, CDSCO bulk drug export certifications, and EMA centralized marketing authorization databases. Bottom-up volume triangulation across dosage form segments and top-down value reconciliation against national pandemic preparedness budget disclosures ensured cross-verification.
Sensitivity analysis around influenza surveillance alert frequency and shikimic acid precursor pricing volatility informed the analytical framework across the projection horizon. Segmentation modeling incorporated dosage form, end-user setting, distribution channel, and regional regulatory cluster dimensions. CAGRs derived from trend extrapolation of hospital procurement volumes, government immunization program scaling trajectories, and substitution dynamics from polymerase inhibitors anchored the quantitative outputs.
Material uncertainties — pandemic declaration timing, raw material supply disruptions, and regulatory inspection queue extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about procurement cycle compression and tender eligibility standards. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market