
 Acitretin Market | 2026-2036
Acitretin Market Size, Share, and Industry Trends Forecast 2026-2036
Acitretin Market Analysis
India is tilting toward expanded acitretin manufacturing capacity as domestic pharmaceutical output scales for export markets. Teva Pharmaceuticals Industries Ltd sustains vertical integration across active pharmaceutical ingredient synthesis and finished dosage production. Sun Pharma Industries Limited anchors its position through dermatology-focused distribution networks spanning regulated and emerging markets. Chongqing Huapont Pharmaceutical Co., Ltd. specializes in cost-efficient oral retinoid supply for Asia-Pacific hospital procurement channels.
Acitretin is a second-generation oral retinoid, chemically classified as a synthetic derivative of etretinate with a molecular structure modified for reduced lipophilicity and shorter elimination half-life, prescribed primarily for severe psoriasis and other keratinization disorders requiring systemic therapy. Oral capsule formulations dominate prescription volumes due to established bioavailability profiles and standardized dosing regimens, while topical gel and cream variants serve adjunctive therapy roles with narrower eligibility criteria. Therapy area segmentation centers on psoriasis as the primary indication, with dermatitis and keratosis representing narrower but higher-margin prescriber segments where off-label utilization creates pricing flexibility.
FDA bioequivalence standards and EMA good manufacturing practice inspections constrain market entry for generic acitretin producers, elevating compliance costs but protecting incumbent supplier margins. India's CDSCO and China's NMPA maintain divergent bioequivalence study requirements that fragment regulatory submission strategies for multinational manufacturers. Stakeholders must monitor evolving pharmacovigilance mandates for teratogenic risk management programs as these protocols reshape prescribing patterns and patient access pathways.
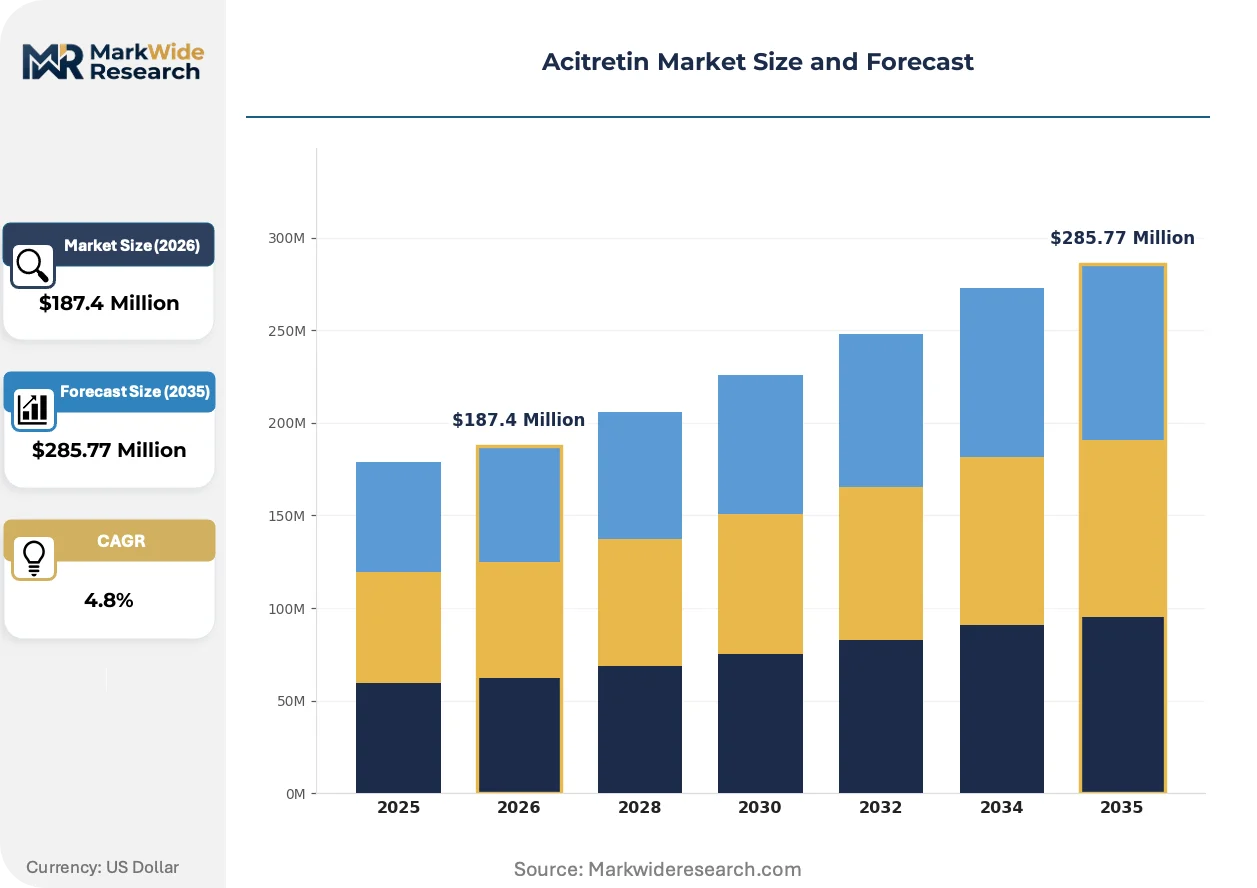
Market Dynamics
Oral retinoid manufacturing is consolidating around vertically integrated API-to-dosage producers as FDA and EMA bioequivalence standards tighten entry barriers for generic challengers.
Growth Catalysts
- EMA bioequivalence protocols:Stricter good manufacturing practice inspections elevate quality thresholds, filtering out subscale producers and protecting incumbent margins.
- Dermatology clinic expansion:India and China are scaling retinoid prescription protocols for moderate-to-severe psoriasis, expanding addressable patient pools.
- Teratogenic risk management programs:Mandatory pharmacovigilance frameworks are standardizing prescriber certification, reducing liability exposure for compliant manufacturers.
Market Restraints
- Isotretinoin substitution pressure:First-generation oral retinoids retain formulary preference in cost-sensitive hospital procurement channels, compressing acitretin volume.
- API supply concentration:Active pharmaceutical ingredient synthesis clusters in eastern China, creating geographic vulnerability to environmental compliance shutdowns.
- CDSCO-NMPA regulatory divergence:India's and China's divergent bioequivalence study requirements fragment submission strategies, duplicating compliance expenditure.
Strategic Opportunities
- Topical gel formulation development:Adjunctive therapy variants with narrower eligibility criteria command pricing flexibility in private dermatology practice channels.
- Keratosis off-label expansion:Higher-margin prescriber segments for actinic keratosis create volume opportunities beyond psoriasis labeling.
- Asia-Pacific hospital procurement integration:Direct contracting with centralized purchasing authorities in Vietnam and Indonesia bypasses fragmented wholesale distribution.
Industry Challenges
- Retinoid synthesis expertise scarcity:Skilled chemists capable of stereospecific manufacturing steps are concentrated among legacy producers, constraining capacity expansion.
- Legacy batch record system integration:Digital transformation of paper-based manufacturing execution systems requires capital outlay without immediate yield improvement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acitretin Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical, Oral, Capsule, Solution Therapy Area: Psoriasis, Acne, Keratosis, Dermatitis End User: Hospitals, Clinics, Pharmacies, Homecare Formulation Type: Liquid, Cream, Gel, Foam |
| Companies Covered | Amneal Pharmaceuticals, Inc., Merck KGaA, Teva Pharmaceuticals Industries Ltd, Prasco Laboratories, Chongqing Huapont Pharmaceutical Co., Ltd., Sun Pharma Industries Limited, GSK Plc, Alembic Pharmaceuticals Ltd, Glenmark Pharmaceuticals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acitretin Market Emerging Trajectories
Continuous manufacturing technologies are displacing batch synthesis across oral retinoid production, compressing cycle times while regulatory data integrity requirements reshape quality assurance investment priorities.
Continuous flow chemistry is collapsing traditional batch reactor economics in acitretin API synthesis. Mid-scale Indian and Chinese manufacturers are retrofitting pilot plants with modular flow reactors to reduce solvent waste and thermal degradation. The technology is collapsing capital intensity barriers that previously protected incumbent volume positions.
REACH authorization requirements for retinoid intermediates are tightening substance volume tracking obligations across European manufacturing networks. ECHA compliance deadlines are forcing reformulation of cleaning validation protocols to eliminate cross-contamination risk. German and French API facilities are absorbing the largest compliance cost increments, accelerating subcontracting to certified Asian suppliers.
Hospital formulary consolidation is compressing supplier rosters to single-source or dual-source arrangements for oral retinoid categories. Dermatology departments in US academic medical centers are demanding real-world evidence packages beyond registration trial data, shifting procurement evaluation criteria. The behavioral shift is most pronounced in Medicare Advantage-dominated markets where pharmacy benefit managers centralize specialty drug contracting.
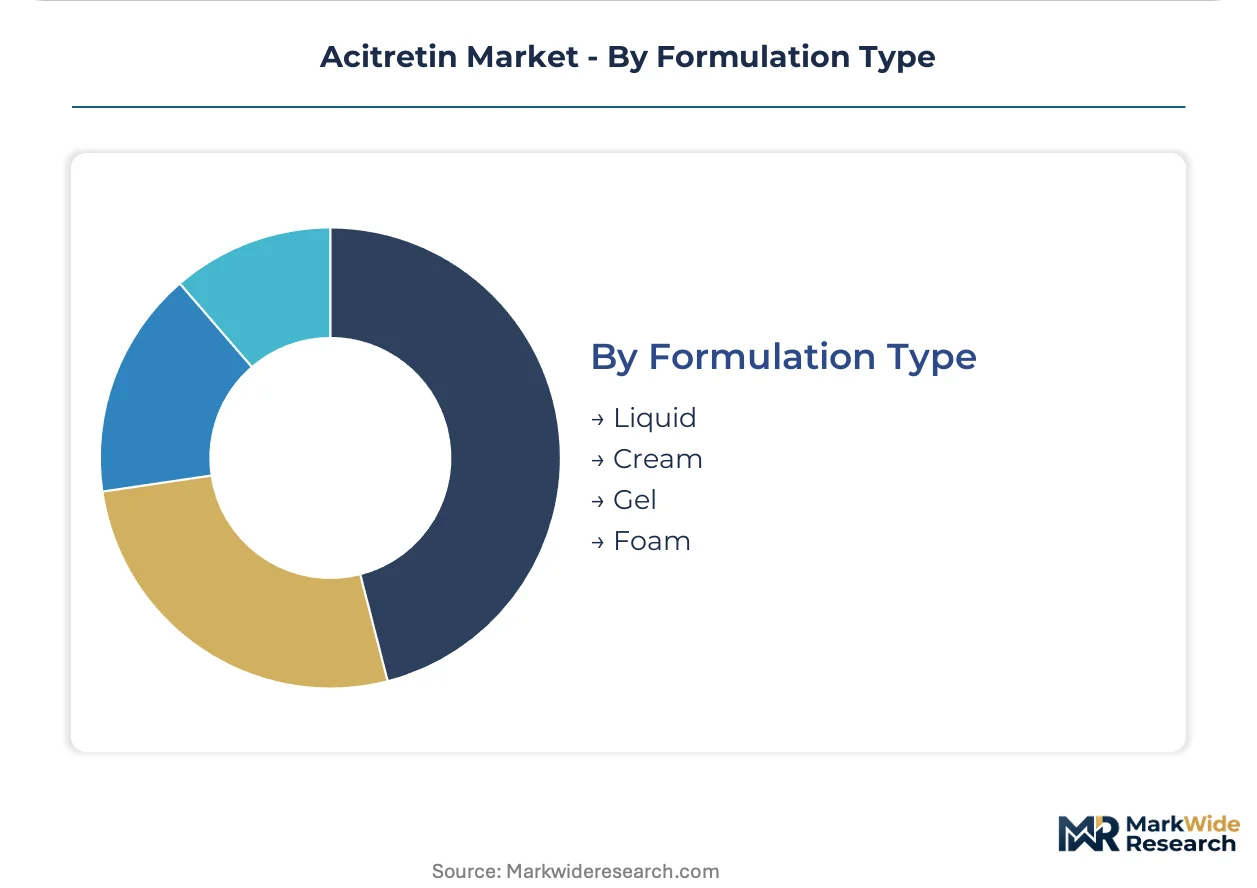
Acitretin Market Segmentation
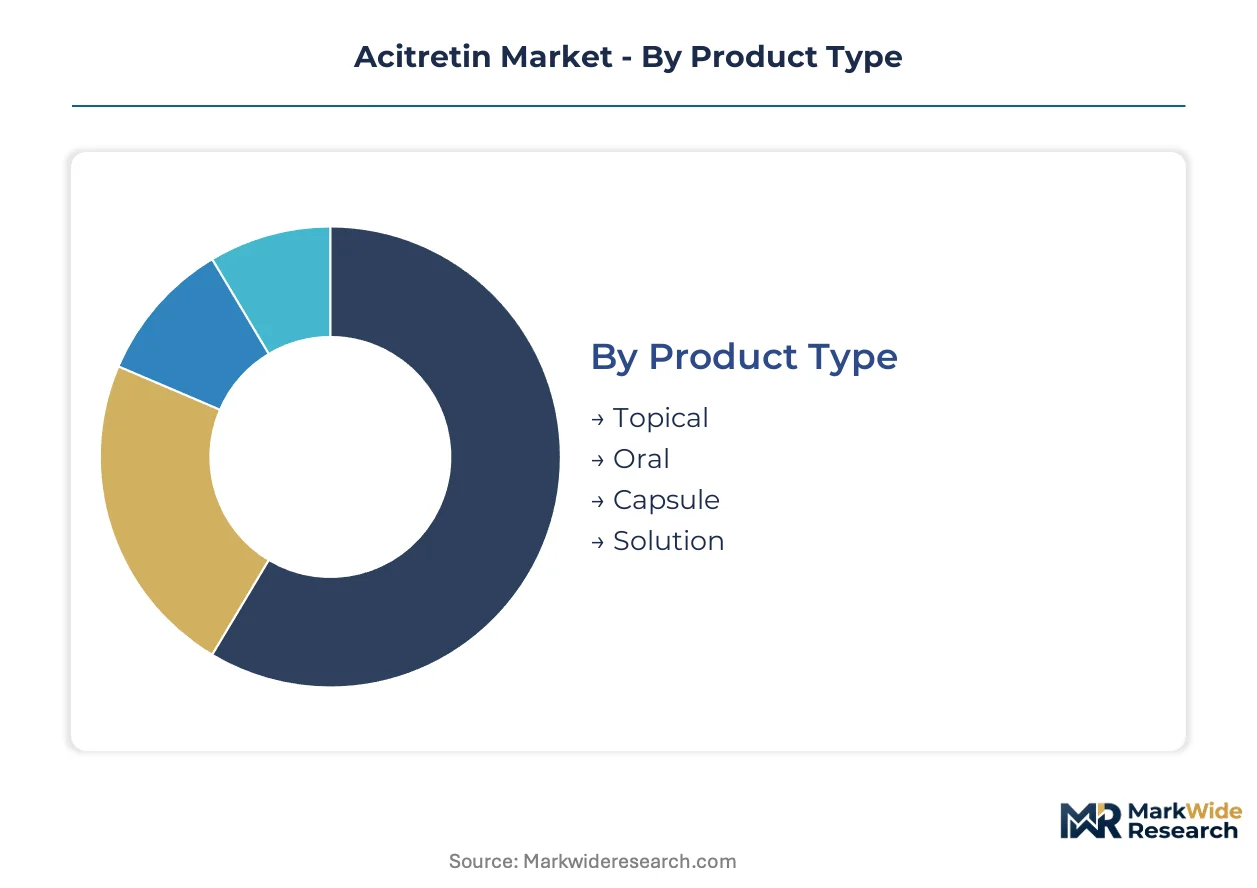
Acitretin market segmentation reflects divergent regulatory pathways and prescriber economics across delivery modes and care settings. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier prioritization.
Product Type:
Cost tier differentiation separates mass-market oral formats from premium topical alternatives with narrower eligibility criteria.
- Oral:Systemic delivery via capsule or solution formats dominates prescription volumes for moderate-to-severe psoriasis. Demand concentrates in Medicare Advantage networks where pharmacy benefit managers centralize specialty contracting.
- Capsule:Solid oral dosage forms with established bioavailability profiles anchor hospital formulary placement. FDA bioequivalence standards protect incumbent manufacturers from generic challengers.
- Topical:Localized delivery reduces systemic exposure for adjunctive therapy roles. Narrower prescriber pools in private dermatology practices command pricing flexibility.
- Solution:Liquid oral formats serve pediatric and geriatric populations with swallowing difficulties. Compounding pharmacies absorb fragmented demand.
Oral formats command the established base. The steepest expansion runs through topical variants.
Therapy Area:
Application focus determines prescriber certification requirements and pharmacovigilance investment intensity.
- Psoriasis:Chronic plaque psoriasis represents the primary labeled indication with standardized dosing protocols. Dermatology clinics in India and China are expanding retinoid prescription protocols for moderate-to-severe cases.
- Keratosis:Actinic keratosis and related keratinization disorders create higher-margin off-label utilization. EMA good manufacturing practice inspections constrain supply to compliant manufacturers.
- Dermatitis:Pustular and erythrodermic variants generate narrower but consistent volume. Hospital procurement channels favor single-source arrangements.
- Acne:Severe recalcitrant acne represents off-label positioning against isotretinoin formulary preference. Cost-sensitive channels compress volume realization.
Psoriasis anchors volume concentration. Keratosis applications are climbing the fastest.
End User:
Customer type shapes distribution architecture and real-world evidence requirements.
- Hospitals:Academic medical centers demand evidence packages beyond registration trial data for formulary inclusion. Centralized purchasing authorities in Vietnam and Indonesia are consolidating supplier rosters.
- Clinics:Dermatology-focused outpatient facilities drive topical formulation adoption. CDSCO and NMPA divergence fragments regulatory submission strategies for multinational suppliers.
- Pharmacies:Retail and specialty pharmacy channels manage teratogenic risk program enrollment. Pharmacovigilance mandates reshape patient access pathways.
- Homecare:Direct-to-patient delivery models expand for maintenance therapy populations. REACH authorization requirements tighten substance tracking obligations.
Hospitals retain the volume base. Clinic channels are gaining share fastest.
Formulation Type:
Supply concentration in API synthesis clusters determines formulation availability and geographic sourcing patterns.
- Gel:Semi-solid aqueous bases enable precise application for localized lesions. Continuous flow chemistry retrofits are collapsing capital intensity barriers for mid-scale manufacturers.
- Cream:Oil-in-water emulsions balance spreadability with cosmetic acceptability. Legacy batch record systems constrain digital transformation investment.
- Liquid:Oral solutions and suspensions serve populations with solid dosage limitations. Environmental compliance shutdowns in eastern China create supply vulnerability.
- Foam:Aerosolized delivery formats address scalp and hair-bearing areas. Narrower manufacturing expertise scarcity limits capacity expansion.
Cream formulations hold the established position. Gel variants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors API distribution networks serving oral retinoid manufacturers across the Asia-Pacific rim. Container throughput at Ningbo-Zhoushan underwrites bulk chemical export capacity for retinoid intermediate suppliers. These maritime assets determine regional sourcing economics for finished dosage producers.
United States
Medicare Advantage networks centralize specialty drug contracting for oral retinoid categories. FDA bioequivalence standards tighten entry barriers for generic challengers, protecting incumbent supplier margins. New Jersey and Pennsylvania host the densest clusters of dermatology-focused pharmaceutical distribution.
Germany
EMA good manufacturing practice inspections elevate quality thresholds for API-to-dosage producers. REACH authorization requirements tighten substance volume tracking obligations across manufacturing networks. The Rhine-Ruhr corridor concentrates batch record system modernization investments.
India
CDSCO bioequivalence study requirements diverge from Chinese protocols, fragmenting regulatory submission strategies. The PLI scheme subsidizes domestic pharmaceutical output scaling for export markets. Gujarat and Maharashtra anchor expanded acitretin manufacturing capacity.
China
NMPA maintains divergent bioequivalence standards from Indian regulators, duplicating compliance expenditure for multinational manufacturers. Yangtze River Delta clusters concentrate API synthesis for oral retinoid supply. Environmental compliance shutdowns in eastern provinces create geographic supply vulnerability.
United Kingdom
NHS England formulary consolidation compresses supplier rosters for oral retinoid categories. MHRA alignment with EMA post-Brexit maintains quality inspection continuity. The Golden Triangle biotech corridor shapes real-world evidence requirements for hospital procurement.
Acitretin Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in API synthesis and intermediate supply. The market structure tilts toward consolidated API-to-dosage production as regulatory compliance costs filter subscale participants. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, dermatology-focused specialty manufacturers, and cost-efficient regional suppliers. Incumbents defend position through backward integration into active pharmaceutical ingredient production and captive supply of critical intermediates.
Among Israel-based pharmaceutical conglomerates, Teva Pharmaceuticals Industries Ltd exemplifies vertical control spanning synthesis to finished dosage. Sun Pharma Industries Limited anchors the dermatology-focused specialty tier with distribution networks spanning regulated and emerging markets. Chongqing Huapont Pharmaceutical Co., Ltd. occupies the cost-efficient regional supplier position for Asia-Pacific hospital procurement channels.
| Leading Market Players |
|---|
| Amneal Pharmaceuticals, Inc. |
| Merck KGaA |
| Teva Pharmaceuticals Industries Ltd |
| Prasco Laboratories |
| Chongqing Huapont Pharmaceutical Co., Ltd. |
| Sun Pharma Industries Limited |
| GSK Plc |
| Alembic Pharmaceuticals Ltd |
| Glenmark Pharmaceuticals Ltd |
| Others |
Supply Flow & Price Mechanics
Overcapacity in eastern Chinese API synthesis clusters is forcing acitretin producers into aggressive volume-discount contracting while simultaneously driving backward integration investments among incumbent manufacturers seeking supply security. This utilization imbalance concentrates pricing power with hospital procurement authorities and pharmacy benefit managers who can consolidate purchasing across Medicare Advantage networks and Asia-Pacific centralized tenders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates acitretin procurement, with FDA-certified oral capsules commanding brand premiums over CDSCO-registered Indian generics and unbranded hospital tenders. Price differentiation hinges on bioequivalence certification tier and geographic delivery cost, with EMA-inspected European supply carrying 15-20% logistics premiums. Cost compression in the economy tier is intensifying because isotretinoin substitution pressure in cost-sensitive channels forces acitretin discounts. Hospital procurement managers exhibit the highest price sensitivity, while private dermatology clinics in India and China accept premium topical gel pricing for narrower eligibility formulations.
Supply Chain Analysis
Contract-manufacturing concentration for acitretin API rests with Yangtze River Delta facilities operated by Chongqing Huapont Pharmaceutical and Teva's in-house synthesis plants in Israel and India. Raw material dependencies draw from retinoid acid precursors sourced from Zhejiang province, specialized solvents from German chemical suppliers, and gelatin capsule shells from Indian excipient manufacturers. Single-source vulnerability in eastern Chinese environmental compliance zones poses structural supply risk, as MEE-mandated shutdowns can abruptly constrain intermediate availability. Distribution runs through hospital centralized purchasing authorities in Vietnam and Indonesia, bypassing fragmented wholesale channels for oral retinoid categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acitretin market expansion is fundamentally a service-attach opportunity, with teratogenic risk management programs and patient compliance monitoring services expanding faster than raw prescription volumes. This recurring-revenue layer reshapes supplier economics toward subscription-like pharmacovigilance relationships.
For Market Incumbents: Entrench formulary position through captive API supply and real-world evidence generation for Medicare Advantage pharmacy benefit managers. Isotretinoin substitution pressure in cost-sensitive hospital channels demands defensive pricing protocols and teratogenic risk program certification investments to differentiate acitretin value propositions. For New Entrants and Emerging Players: Mid-market dermatology clinics in Southeast Asia represent the most penetrable entry point, where centralized hospital procurement consolidation has not yet eliminated wholesale distribution fragmentation. Adjunctive topical gel formulations for actinic keratosis create higher-margin positioning against commoditized oral capsule competition, with direct-to-clinic sampling programs as the preferred go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated API-to-dosage producers with captive teratogenic risk management program enrollment infrastructure. Long-term viability across the projection horizon favors acquisition targets with backward integration into retinoid acid precursor synthesis and established EMA/FDA dual-inspection track records. The signal to watch is CDSCO-NMPA regulatory harmonization progress, which would collapse compliance duplication costs and revalue India-China manufacturing arbitrage positions.| Strategic Initiative | Industry Significance |
|---|---|
| Teratogenic Risk Program Certification | FDA-mandated iPLEDGE-style frameworks protect incumbent margins through prescriber lock-in. |
| Continuous Flow Chemistry Retrofit | Modular reactor installations at Indian and Chinese pilot plants reduce solvent waste and thermal degradation. |
| EMA Bioequivalence Pathway Investment | Good manufacturing practice inspection readiness filters subscale generic challengers from European markets. |
| Asia-Pacific Hospital Procurement Integration | Direct contracting with Vietnam and Indonesia centralized purchasing authorities bypasses fragmented wholesale. |
| Keratosis Off-Label Evidence Generation | Real-world data packages for actinic keratosis expand addressable prescriber pools beyond psoriasis labeling. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dermatology clinic directors, hospital formulary managers, regulatory affairs leads at generic manufacturers, and API synthesis chemists; and secondary validation against FDA Orange Book listings, EMA inspection databases, CDSCO approval records, ClinicalTrials.gov retinoid trial registries, and Asia-Pacific customs trade data. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to constrain estimate ranges.
Forecast inputs considered therapy area segmentation across psoriasis, keratosis, and dermatitis indications; formulation type differentiation between oral capsules and topical gels; and regional regulatory cluster divergence between FDA, EMA, CDSCO, and NMPA jurisdictions. CAGRs were derived from patient population epidemiology, prescriber protocol expansion rates in India and China, and bioequivalence study pipeline visibility. Industry-specific forecast inputs included REACH authorization timelines for retinoid intermediates and Medicare Advantage specialty drug contracting concentration trends.
Practitioners should monitor environmental compliance enforcement intensity in eastern Chinese provinces and EMA good manufacturing practice inspection backlog durations for early signals of supply constraint or regulatory delay. Forecasts reflect assumptions regarding continued dermatology clinic expansion in emerging markets and stable teratogenic risk program enrollment protocols. Quarterly review of API spot pricing in the Yangtze River Delta and hospital formulary consolidation announcements in US academic medical centers is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market