
 Asia-Pacific Insulin Pens Market | 2026-2036
Asia-Pacific Insulin Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insulin Pens Market Outlook
Homecare settings is repositioning as the dominant end-use channel across the Asia-Pacific Insulin Pens Market, shifting volume away from hospital-centric models. Novo Nordisk A/S anchors its presence through deep specialization in pre-filled disposable formats and direct-to-patient education programs. Sanofi competes aggressively on biosimilar insulin portfolios paired with reusable pen systems, while Eli Lilly and Company leverages connected device partnerships to extend its footprint in smart pen technologies across Japan and Australia.
Insulin pens are precision drug-delivery devices designed for subcutaneous insulin administration, typically featuring dose-calibration mechanisms accurate to one-unit increments and disposable or replaceable insulin cartridges. These devices serve the primary commercial purpose of enabling patient self-management of glycemic control outside clinical facilities. Smart pens and pre-filled pens represent the fastest-expanding product categories, capturing margin pools through digital connectivity and convenience-driven adherence programs. The homecare end-user segment now outpaces hospital pharmacy channels as diabetes center networks expand into tier-two cities and rural catchments across India and Southeast Asia.
Japan's PMDA and Australia's TGA enforce stringent device safety and biocompatibility standards that shape product registration timelines and manufacturing quality benchmarks for pen injectors entering these markets. India's CDSCO and BIS jointly regulate medical device classification and local production standards, creating compliance thresholds that favor established multinationals with in-country quality infrastructure. Stakeholders must monitor reimbursement list revisions and connected-device data privacy frameworks as digital health integration deepens across national healthcare systems.
Market Dynamics
Homecare channel migration is compressing hospital pharmacy volumes across Asia-Pacific, as diabetes management decentralizes toward patient-controlled environments and remote monitoring infrastructure spreads through tier-two cities.
Growth Catalysts
- Japan's PMDA connected-device pathway:Accelerated review timelines for Bluetooth-enabled insulin pens are shortening commercialization cycles for digital health integrators targeting elderly self-management populations.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are expanding local production capacity for disposable pen injectors, reducing import dependency for public procurement programs.
- Pre-filled pen convenience premium:Single-use formats are capturing patient preference in China's expanding reimbursement list, where dose accuracy and portability drive adherence in working-age diabetics.
Market Restraints
- Biocompatibility testing costs:Japan and Australia's stringent polymer and needle material standards impose extended validation timelines that inflate pre-market expenditure for new entrants.
- Insulin API supply concentration:Active pharmaceutical ingredient production clusters in limited geographies expose pen manufacturers to input price volatility and geopolitical supply interruptions.
- Reusable pen durability limitations:Mechanical dose-calibration degradation after repeated use creates reliability concerns that constrain device lifecycle extension strategies.
Strategic Opportunities
- Indonesia's underpenetrated rural diabetes networks:Dispersed patient populations in outer islands present whitespace for low-cost disposable pen distribution through mobile health clinics.
- Vietnam's emerging hospital-at-home programs:Government reimbursement pilots for remote glycemic monitoring are creating integrated pen-and-sensor procurement channels.
- Cloud-connected dose logging convergence:Integration of pen-injector hardware with smartphone adherence apps is enabling subscription-based digital therapeutics revenue models.
Industry Challenges
- Biomedical engineering talent scarcity:Shortages of specialists combining mechanical drug-delivery design with firmware development are constraining smart pen R&D pipelines.
- Multi-jurisdiction certification complexity:Divergent electrical safety and data privacy requirements across PMDA, TGA, and CDSCO frameworks fragment product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insulin Pens Market |
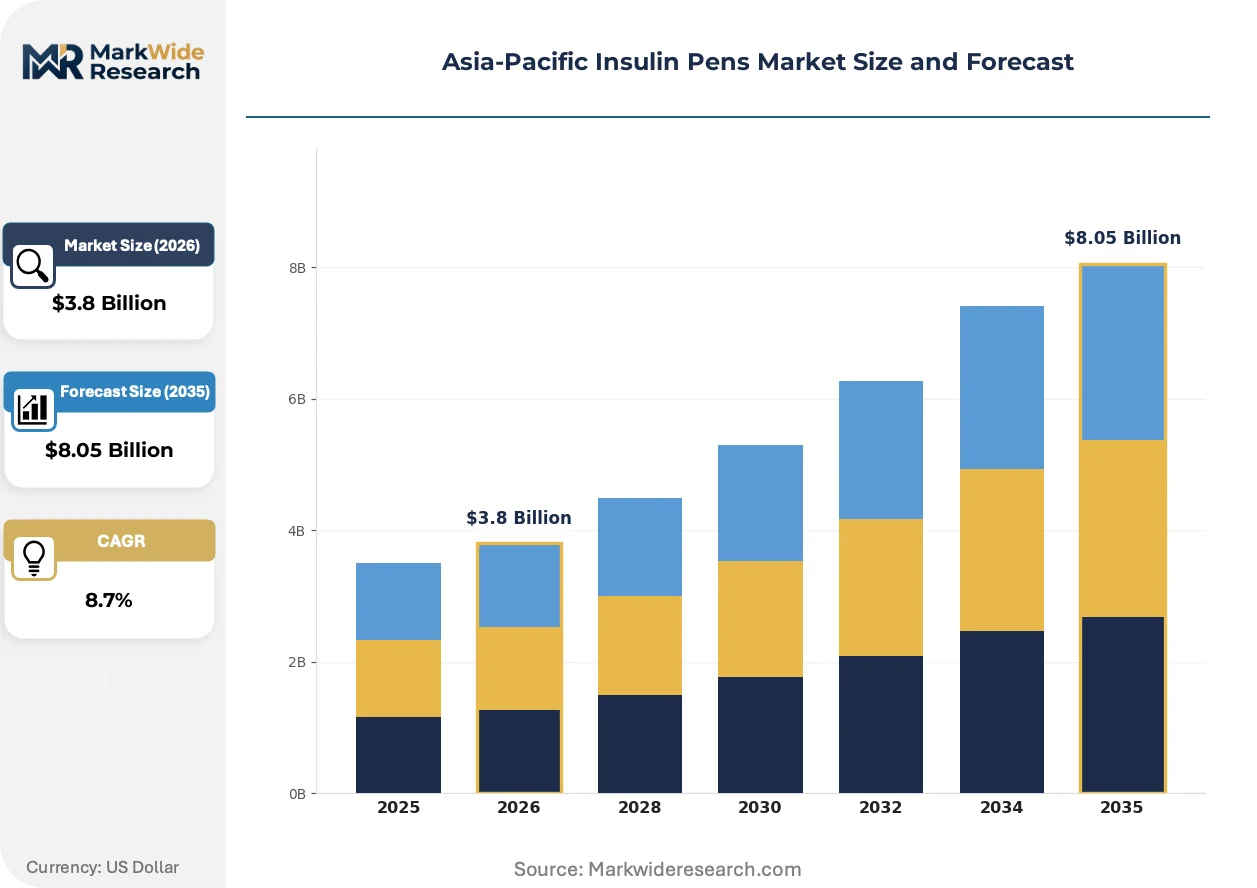
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Smart Pens, Pre-filled Pens End User: Hospitals, Clinics, Homecare, Diabetes Centers Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Specialty Stores Formulation: Rapid Acting, Long Acting, Mixed Insulin, Biosimilars |
| Companies Covered | Biocon, Medtronic PLC, Novo Nordisk A/S, Insulet Corp, Ypsomed Holding AG, Sanofi, Wockhardt, Becton Dickinson and Company, Eli Lilly and Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insulin Pens Market Strategic Shifts
Digital connectivity is penetrating insulin pen architectures at accelerating velocity, reshaping competitive advantage from mechanical precision toward software-enabled adherence ecosystems and real-time clinical data flows.
Smart pen technology incorporating Bluetooth dose capture and cloud synchronization is converging with mobile health platforms to create closed-loop diabetes management systems. Endocrinology practices in Australia and Japan are piloting these integrated workflows for patient cohorts requiring intensive insulin therapy. This convergence is compressing differentiation potential for standalone mechanical devices and elevating software partnerships to core strategic priority.
India's CDSCO and BIS are tightening medical device classification enforcement for imported pen injectors, mandating local quality infrastructure audits that extend registration timelines. Manufacturers are responding by establishing captive testing laboratories in Mumbai and Hyderabad to accelerate compliance documentation. Domestic producers with established BIS certification pathways are capturing public tender advantages over import-dependent competitors.
Patient self-procurement through retail pharmacy channels is displacing hospital-centric dispensing for stable Type 2 diabetes cases across China's provincial cities. Community pharmacy networks in Chengdu and Wuhan are expanding cold-chain storage capacity to support insulin pen inventory. This channel rotation is most visible in urban districts where government reimbursement direct-deposit programs reduce patient out-of-pocket friction.
Asia-Pacific Insulin Pens Market Segmentation
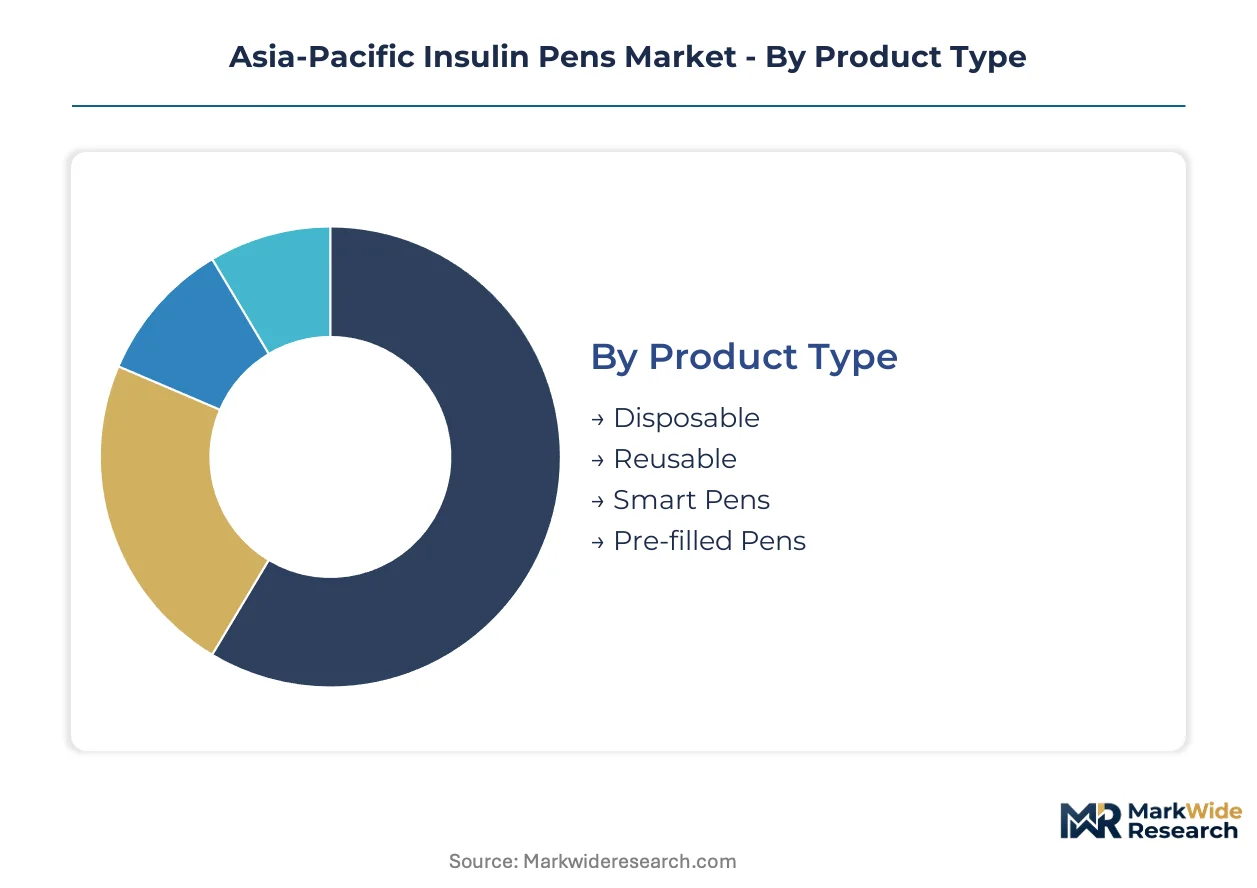
Insulin pen segmentation in Asia-Pacific reflects divergent patient capabilities, reimbursement structures, and supply chain maturity across national healthcare systems. Technology sophistication and channel accessibility determine commercial priority for manufacturers navigating heterogeneous regulatory environments.
Product Type:
Dose-delivery mechanisms segment across mechanical reliability, electronic connectivity, and single-use convenience axes that shape manufacturing investment and margin profiles.
- Disposable:Single-use pen injectors integrate fixed insulin cartridges with non-replaceable needle systems, eliminating patient handling complexity. Demand concentrates in India's tier-two cities and rural catchments where cold-chain infrastructure constraints favor simplified inventory management and reduced training burdens on healthcare workers.
- Smart Pens:Bluetooth-enabled devices capture dose timing and volume data for smartphone synchronization, enabling remote glycemic monitoring. Japan's PMDA accelerated review pathway is concentrating new product launches in elderly self-management populations requiring adherence tracking.
- Reusable:Durable mechanical housings accommodate replaceable insulin cartridges across multiple injection cycles. Cost-sensitive procurement in Indonesia's public hospital networks sustains volume despite calibration reliability concerns.
- Pre-filled Pens:Factory-sealed insulin cartridges reduce contamination risk and dosing errors in outpatient settings. China's expanding provincial reimbursement lists are capturing working-age diabetic preference through pharmacy direct-purchase channels.
Mature deployment sits with disposable formats across public procurement programs. Newer deployment is concentrated in smart pen systems gaining share fastest through Japan's digital health integration pilots.
End User:
Care setting segmentation tracks the decentralization of diabetes management from institutional facilities toward patient-controlled environments and remote monitoring infrastructure.
- Homecare:Self-administration by patients or caregivers outside clinical supervision requires intuitive device interfaces and reliable cold-chain storage. China's government reimbursement direct-deposit programs are reducing out-of-pocket friction and accelerating channel migration in Chengdu and Wuhan urban districts.
- Diabetes Centers:Specialized outpatient facilities combine pen dispensing with patient education and metabolic monitoring. India's expanding center networks into tier-two cities are repositioning this segment as the dominant volume channel.
- Hospitals:Inpatient glycemic management and initial patient training on injection technique. Compression from homecare migration is visible across Southeast Asia as stable Type 2 cases discharge to community settings.
- Clinics:Primary care and endocrinology practices providing ongoing prescription renewal and device troubleshooting. Australia's TGA quality infrastructure requirements favor established multinationals in tender participation.
Volume leadership belongs to diabetes centers capturing reimbursed patient flows. Steepest expansion trajectory is occurring in homecare as remote monitoring infrastructure penetrates provincial networks.
Distribution Channel:
Channel structure reflects cold-chain capability requirements, prescription authority, and patient payment mechanics across fragmented national pharmacy systems.
- Retail Pharmacy:Community-based dispensing with walk-in cold-chain storage and pharmacist counseling. Vietnam's emerging hospital-at-home reimbursement pilots are creating integrated procurement workflows.
- Hospital Pharmacy:Institutional dispensing tied to inpatient admission or specialist consultation. Volume compression is accelerating as diabetes management decentralizes.
- Online Pharmacy:Direct-to-patient delivery platforms with temperature-controlled logistics. Regulatory frameworks for connected-device data privacy are constraining expansion in Australia's TGA jurisdiction.
- Specialty Stores:Medical device retailers offering device demonstration and insurance coordination. Limited penetration outside Japan's metropolitan markets.
Established volume sits with hospital pharmacy channels. Retail pharmacy is capturing fastest growth as self-procurement normalizes across China's provincial cities.
Formulation:
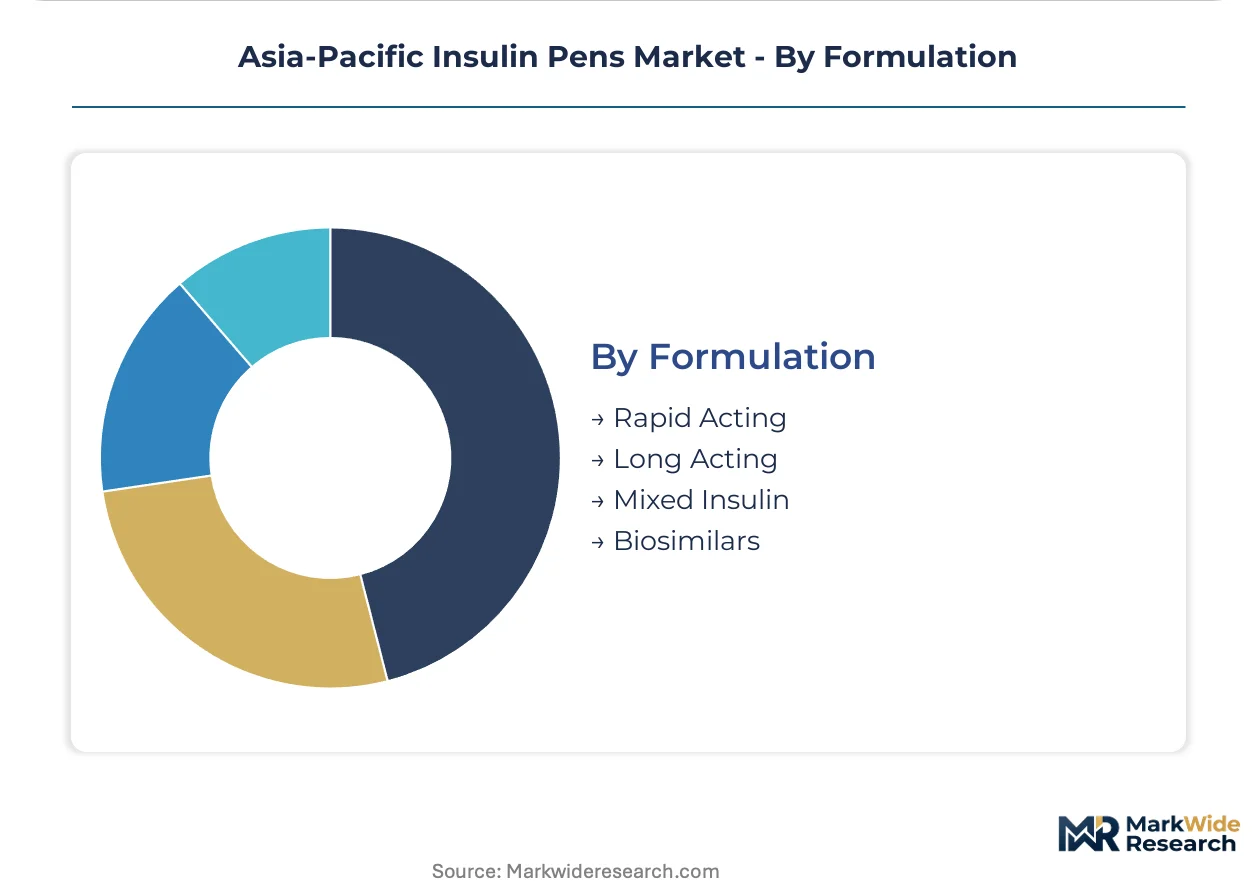
Insulin pharmacokinetics segment across onset speed, duration profile, and molecular origin, determining pen device compatibility and patient regimen complexity.
- Long Acting:Basal insulin analogs with 24-hour glucose-lowering coverage reducing injection frequency. Biosimilar competition from Sanofi's portfolio is intensifying in Australia's reimbursement-sensitive procurement.
- Rapid Acting:Prandial insulin with 15-minute onset matching meal-time carbohydrate intake. Japan's aging population with irregular meal patterns sustains premium positioning.
- Mixed Insulin:Fixed-ratio basal-bolus combinations simplifying twice-daily regimens for Type 2 patients with limited self-monitoring capacity. India's CDSCO quality audits favor domestic manufacturers with BIS certification.
- Biosimilars:Therapeutically equivalent insulin copies at reduced cost, requiring pen device compatibility verification. PLI scheme incentives are accelerating Indian domestic production capacity for disposable pen-biosimilar bundles.
Regimen standardization centers on long-acting basal analogs. Biosimilars are climbing the fastest as cost containment pressures intensify across Asia-Pacific public procurement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is concentrating manufacturing investment in special economic zones around Mumbai and Hyderabad. China's expanding provincial reimbursement networks are decentralizing demand toward tier-two urban centers. Japan's PMDA accelerated review pathways are shortening commercialization timelines for digital health integrators.
China
Provincial cities Chengdu and Wuhan are expanding retail pharmacy cold-chain capacity to support patient self-procurement. NMPA reimbursement list revisions are capturing working-age diabetics through direct-deposit programs. The Yangtze River Delta remains the dominant cluster for pen injector distribution logistics.
India
Tier-two city diabetes center networks are repositioning homecare as the dominant volume channel. CDSCO and BIS joint quality audits favor domestic manufacturers with Mumbai and Hyderabad testing infrastructure. The PLI scheme is accelerating captive production capacity for disposable pen-biosimilar bundles.
Japan
PMDA's connected-device pathway is concentrating smart pen launches in elderly self-management populations. Bluetooth-enabled dose capture systems are converging with mobile health platforms in Tokyo and Osaka endocrinology practices. METI standards shape biocompatibility validation timelines for polymer and needle materials.
Australia
TGA quality infrastructure requirements favor established multinationals in tender participation for pen injector procurement. Remote glycemic monitoring pilots are creating integrated pen-and-sensor channels through hospital-at-home programs. Sydney and Melbourne diabetes practices are piloting closed-loop management workflows.
Vietnam
Government reimbursement pilots for remote monitoring are emerging in Ho Chi Minh City and Hanoi. Mobile health clinic networks present whitespace for low-cost disposable pen distribution in outer provinces. Hospital-at-home program expansion is shifting procurement toward integrated digital therapeutics bundles.
Asia-Pacific Insulin Pens Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational pharmaceutical houses anchoring pre-filled and smart pen categories while regional fabricators capture disposable volume in price-sensitive procurement. The structure concentrates around three archetypes: integrated insulin-pen system developers, standalone device specialists, and biosimilar-bundle manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly around digital health integration and local production incentives.
Among the integrated system developers, Novo Nordisk A/S and Sanofi exemplify the branded pharmaceutical archetype combining proprietary insulin portfolios with pen delivery platforms. Eli Lilly and Company occupies a position within the connected-device tier, reflecting the industry pivot toward software-enabled adherence ecosystems. These three entities anchor the competitive matrix through differentiated specialization in pre-filled formats, biosimilar bundling, and smart pen technologies respectively.
| Leading Market Players |
|---|
| Biocon |
| Medtronic PLC |
| Novo Nordisk A/S |
| Insulet Corp |
| Ypsomed Holding AG |
| Sanofi |
| Wockhardt |
| Becton Dickinson and Company |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Polymer resin indices and stainless steel needle material benchmarks cascade through insulin pen manufacturing tiers, compressing margins for import-dependent assemblers while rewarding domestic producers with captive polymer compounding and BIS-certified testing infrastructure in India and China.
Pricing Analysis
Short lead-time premiums of three-to-four weeks command fifteen-to-twenty percent markups over standard procurement cycles in Japan's PMDA-regulated tenders, where hospital-at-home program deadlines create urgency-driven procurement. Three-tier pricing structure across premium smart pens, standard pre-filled formats, and economy disposable tiers separates connected-device ecosystems from basic mechanical delivery systems. Cost compression in India's public tender segment is intensifying because PLI scheme beneficiaries with Mumbai and Hyderabad manufacturing footprints undercut import-dependent competitors on landed cost. Government hospital procurement committees exhibit highest price sensitivity, while private diabetes center networks in Tokyo and Sydney absorb premiums for Bluetooth-enabled adherence tracking systems.
Supply Chain Analysis
Temperature-controlled freight costs from insulin API production clusters in China and South Korea to pen assembly facilities in India and Southeast Asia represent twelve-to-fifteen percent of total landed cost for disposable pen-biosimilar bundles. Active pharmaceutical ingredient supply concentrates in Tianjin and Shanghai pharmaceutical zones, while precision polymer molding for pen housings draws from Shenzhen and Dongguan industrial corridors. Single-source vulnerability in lyophilized insulin formulation creates exposure to cold-chain interruption during monsoon logistics disruptions across Bay of Bengal shipping routes. Distribution runs through hospital pharmacy procurement committees in tier-one cities, with retail pharmacy cold-chain expansion in Chengdu and Wuhan capturing self-procurement volume from discharged stable Type 2 patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific insulin pen manufacturing is consolidating around domestic production incentives and digital health integration capabilities, with CDSCO quality audit requirements and PMDA connected-device pathways forcing smaller import-dependent distributors toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into polymer compounding and needle fabrication in India's PLI scheme special economic zones, while capturing PMDA accelerated review pathway advantages for Bluetooth-enabled dose logging systems against emerging biosimilar-bundle competitors from domestic Indian manufacturers. For New Entrants and Emerging Players: Capture whitespace in Indonesia's outer island mobile health clinic networks and Vietnam's hospital-at-home reimbursement pilots, where low-cost disposable pen distribution partnerships with provincial pharmacy cooperatives offer the most penetrable entry vector without confronting established cold-chain infrastructure in tier-one cities. For Investors and Strategic Acquirers: The window for entry favors vertically integrated device specialists with captive BIS certification laboratories and biosimilar insulin partnerships, given long-term viability rests on regulatory compliance speed rather than pure manufacturing scale; watch for CDSCO registration timeline compression as inflection signal for domestic production preference hardening.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Acceleration | Captures public tender advantages through Mumbai and Hyderabad testing infrastructure proximity. |
| Smart Pen Software Partnership | Converges Bluetooth dose capture with Tokyo and Osaka mobile health platform integration. |
| PLI Scheme Manufacturing Scale-Up | Reduces import dependency for India's tier-two diabetes center network expansion. |
| Hospital-at-Home Procurement Integration | Aligns pen-and-sensor bundles with Vietnam's emerging reimbursement pilot structures. |
| Biosimilar-Device Bundle Development | Matches Sanofi's cost-positioning through domestic insulin API and pen co-production. |
Study Parameters
Regulatory filing databases, hospital procurement contract registries, and pharmaceutical trade flow records formed the secondary backbone, supplemented by primary interviews with biomedical engineers, diabetes center procurement managers, CDSCO regulatory affairs specialists, and GPO contracts administrators across the analysis window. Bottom-up and top-down triangulation validated segment-level volume estimates against insulin API production disclosures and pen injector import manifests.
Bottom-up modeling anchored in patient population epidemiology, reimbursement list expansion timelines, and device replacement cycle assumptions across the projection horizon, while top-down cross-checks applied regional healthcare expenditure growth patterns. Segmentation dimensions included product type sophistication tiers, end-user care setting migration patterns, distribution channel cold-chain capability grades, and insulin formulation biosimilar penetration rates. CAGRs derived from multivariate regression incorporating diabetes prevalence trajectories, government reimbursement expansion velocity, and digital health adoption curves in elderly self-management populations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA data privacy framework revisions, insulin API supply geopolitical disruption, and PLI scheme incentive continuity across Indian central government budget cycles. Forecasts reflect documented assumptions on reimbursement expansion pacing and connected-device regulatory pathway stability; stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Chemotherapy Market