
 Middle East and Africa Insulin Delivery Devices Market | 2026-2036
Middle East and Africa Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Insulin Delivery Devices Market Foresight
Hospital-based diabetes management is expanding across the Middle East and Africa, while home care settings are capturing incremental volume as patient education improves. Novo Nordisk A/S anchors the regional supply chain through its established insulin portfolio and localized distribution partnerships. Ypsomed competes with differentiated pen needle and pump reservoir offerings tailored to price-sensitive markets. Medtronic PLC dominates the automated insulin delivery segment with its closed-loop technology leadership and clinical validation in Gulf Cooperation Council hospital networks.
Insulin delivery devices are electromechanical or manual systems designed to administer controlled doses of insulin subcutaneously, typically featuring dose-calibration mechanisms, needle-safety engineering, and compatibility with U-100 or U-200 insulin concentrations. These devices serve the primary commercial purpose of enabling precise glycemic control for diabetes patients across clinical and non-clinical environments. Insulin pens command the largest product type share due to their portability and dosing accuracy, while automated insulin delivery systems represent the fastest-growing technology segment as algorithm-enabled pumps penetrate Saudi and South African tertiary care centers. Retail pharmacies remain the dominant distribution channel, though online sales are gaining structural share where regulatory frameworks permit direct-to-patient fulfillment.
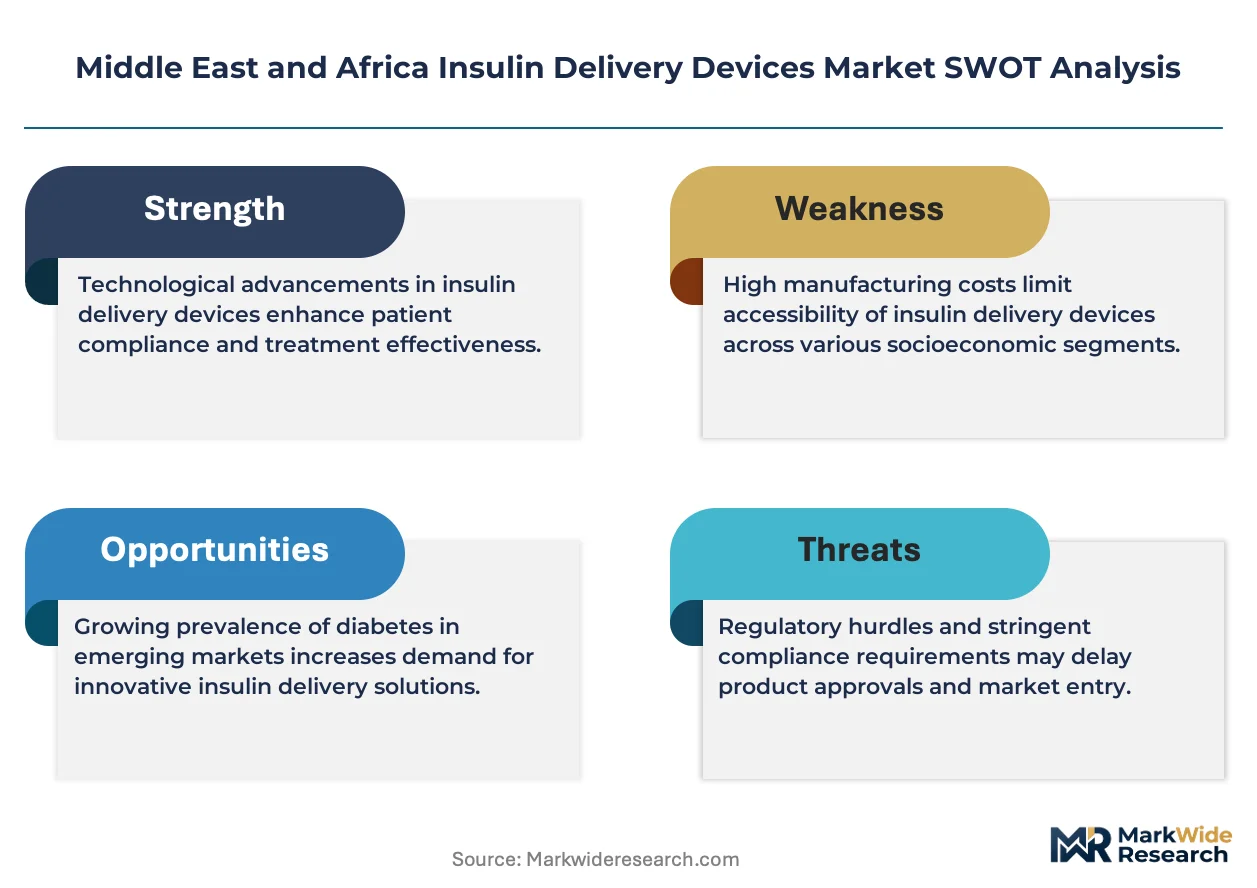
South Africa's Health Products Regulatory Authority, Saudi Arabia's SFDA, and the UAE's MOHAP collectively shape device registration timelines, reimbursement eligibility, and import licensing requirements across the region. These regulators enforce convergence with ISO 15197 and IEC 60601 standards, raising compliance costs for new entrants while protecting incumbent manufacturers with established quality management systems. Stakeholders must monitor evolving reimbursement lists in Saudi Arabia and the UAE, where national health insurance expansions will determine which smart pen and pump technologies achieve sustainable volume.
Market Dynamics
Saudi Arabia's SFDA and South Africa's Health Products Regulatory Authority are tightening ISO 15197 and IEC 60601 compliance timelines, forcing manufacturers to accelerate quality management system investments while hospital procurement shifts toward pre-certified automated delivery platforms.
Growth Catalysts
- Government screening mandates:Saudi Arabia's national diabetes detection programs are channeling public hospital procurement toward automated insulin delivery systems that reduce nursing workload in high-volume clinics.
- Smart pump algorithms:Closed-loop glucose-responsive dosing technology is penetrating tertiary care networks in the UAE and Kuwait, replacing manual basal-bolus protocols.
- Home care protocols:Type 1 diabetes self-management education initiatives across Gulf Cooperation Council states are expanding retail pharmacy demand for pen needle bundles and disposable insulin pens.
Market Restraints
- Import licensing friction:SFDA device registration timelines extending 18-24 months are blocking smaller manufacturers from entering Saudi Arabia's hospital supply chains.
- Reimbursement list rigidity:UAE's MOHAP and South Africa's national health insurance schemes limit pump coverage to specific patient risk categories, capping volume expansion.
- Sensor-pump interoperability gaps:Proprietary communication protocols between continuous glucose monitors and insulin pumps force single-vendor lock-in, raising total cost of ownership.
Strategic Opportunities
- Nigeria's underpenetrated diabetes clinics:Private hospital chains in Lagos and Abuja are importing pen-based systems directly, bypassing fragmented public procurement.
- Telemedicine-integrated dosing:Remote patient monitoring platforms paired with Bluetooth-enabled smart pens are enabling endocrinologists to adjust regimens without clinic visits.
- MOHAP fast-track certification:The UAE's accelerated approval pathway for devices with prior FDA or CE marking is attracting European manufacturers seeking Gulf market entry.
Industry Challenges
- Biomedical engineering talent scarcity:Saudi Arabia and South Africa face acute shortages of specialists trained in electromechanical pump maintenance and algorithm calibration.
- Legacy hospital IT integration:Automated insulin delivery systems require HL7 FHIR compatibility with existing electronic health record architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Insulin Delivery Devices Market |
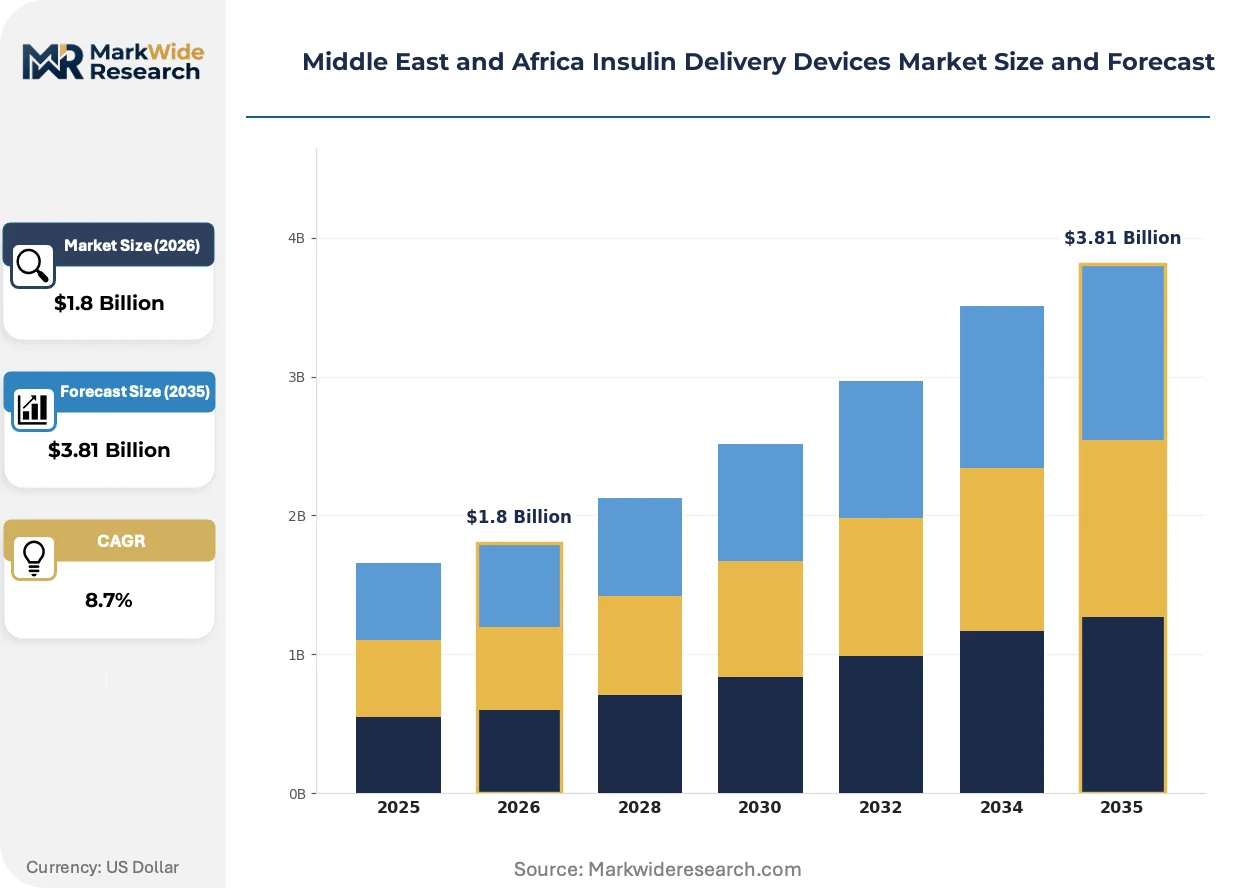
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Syringes, Jet Injectors Technology: Smart Insulin Pens, Continuous Glucose Monitors, Wearable Devices, Automated Insulin Delivery Systems End User: Home Care, Hospitals, Diabetes Clinics, Pharmacies Distribution Channel: Retail Pharmacies, Online Sales, Wholesale, Direct Sales |
| Companies Covered | Medtronic PLC, Ypsomed, Novo Nordisk A/S, F. Hoffmann-La Roche Ltd., Becton Dickinson & Company, Sanofi, Insulet Corporation, Tandem Diabetes Care, Eli Lilly and Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Insulin Delivery Devices Market Shifts & Advancements
Algorithm-enabled dosing systems and connected pen platforms are compressing the gap between clinical and home-based glycemic management, while regulatory convergence around international standards is reshaping competitive entry barriers across Middle East and African markets.
Closed-loop artificial pancreas systems is integrating predictive glucose algorithms with subcutaneous insulin delivery to automate basal rate adjustments. Saudi tertiary care centers and South African academic hospitals are piloting these platforms for Type 1 pediatric populations. The technology is integrating endocrinology workflow automation, reducing nursing intervention frequency and enabling higher patient-to-staff ratios in diabetes wards.
SFDA's 2023 medical device quality management system directive mandates ISO 13485 certification for all new insulin pump registrations, extending documentation requirements for software validation and post-market surveillance. European and Asian manufacturers with established quality systems are capturing accelerated approval slots, while regional distributors without captive manufacturing face exclusion. South Africa's Health Products Regulatory Authority is harmonizing with this framework, creating a two-country certification pathway for Gulf and sub-Saharan market access.
Patient-driven channel migration is fragmenting traditional hospital-centric supply chains. Type 1 diabetes patients in the UAE and Kuwait are purchasing smart pen systems through direct-to-consumer online platforms where MOHAP permits remote prescription verification. Retail pharmacy chains in Saudi Arabia are responding with subscription-based needle and cartridge replenishment services. This shift is most visible among digitally literate patient cohorts under 40, where convenience overrides traditional clinic-based dispensing preferences.
Middle East and Africa Insulin Delivery Devices Market Segmentation
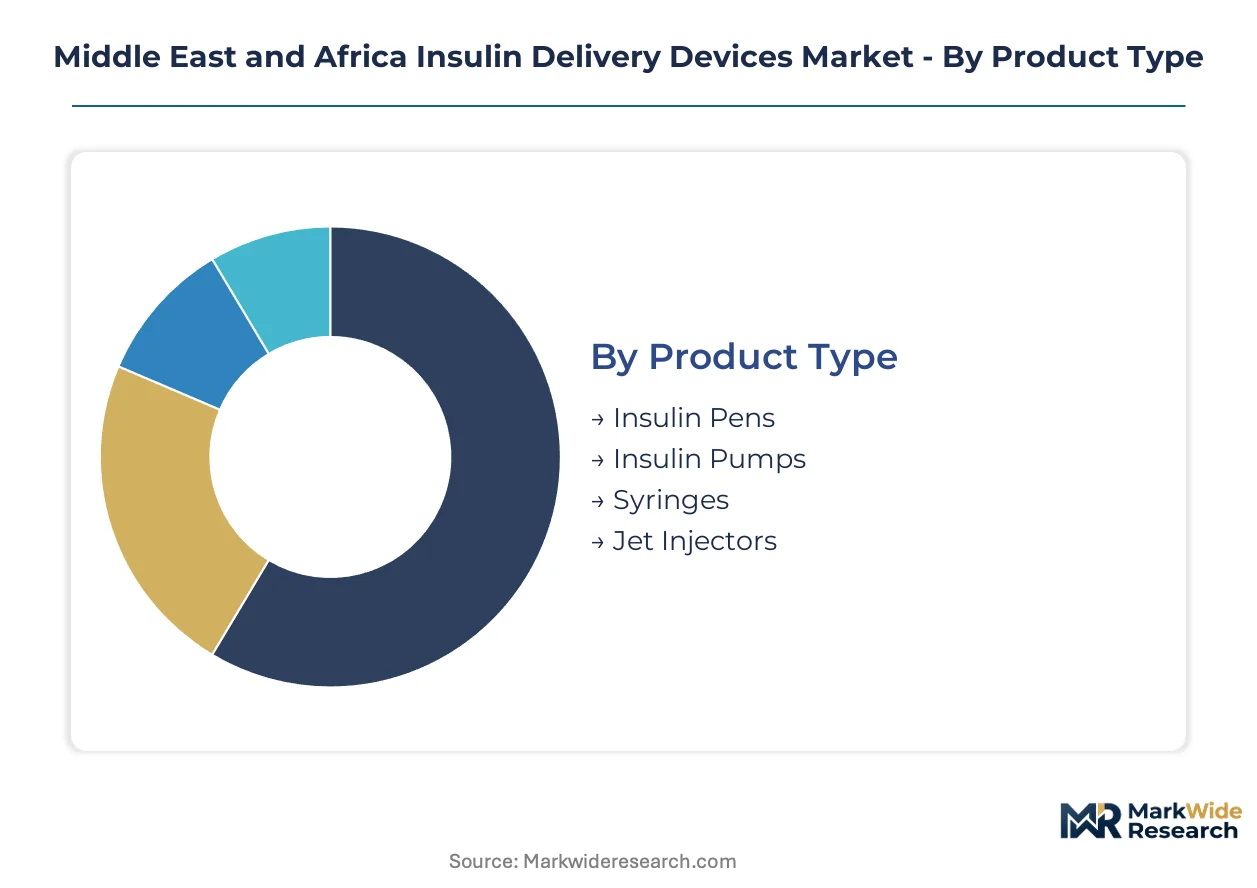
Device selection across Middle East and Africa insulin delivery markets hinges on reimbursement tier, clinical setting complexity, and patient digital literacy. Procurement patterns diverge sharply between Saudi hospital networks seeking closed-loop automation and Nigerian retail channels favoring disposable pen systems.
Product Type:
Hospital procurement officers weigh total cost of ownership against nursing workflow efficiency when selecting delivery mechanisms for diabetes wards.
- Insulin Pens:Portable, dose-calibrated devices with disposable or reusable cartridge systems. Saudi retail pharmacy chains and UAE hospital outpatient clinics prioritize pen-based systems for Type 2 diabetes populations where basal-bolus flexibility matters. SFDA certification requirements for pen needle safety engineering have consolidated supplier relationships around established manufacturers.
- Insulin Pumps:Electromechanical devices delivering continuous subcutaneous insulin infusion with programmable basal profiles. South African academic hospitals and Kuwaiti tertiary care centers are deploying pump therapy for pediatric Type 1 cohorts requiring precise glycemic control. Reimbursement authorization delays in South Africa's national health insurance framework constrain volume expansion despite clinical demand.
- Syringes:Manual U-100 calibrated injection systems with integrated needle safety mechanisms. Public hospital procurement in Egypt and Morocco continues bulk purchasing of syringe-and-vial combinations for cost containment in high-volume diabetes clinics.
- Jet Injectors:Needle-free systems using pressurized gas or spring mechanisms to propel insulin through skin. Limited adoption concentrated in UAE private endocrinology practices serving needle-phobic patient segments.
Insulin pens lead on scale across retail and outpatient channels; automated pump platforms lead on momentum in Gulf tertiary care networks.
Technology:
Algorithm sophistication and sensor interoperability now determine technology tier placement and pricing power in regional device markets.
- Smart Insulin Pens:Bluetooth-enabled devices with dose logging, timing reminders, and clinician dashboard integration. UAE and Kuwaiti patients under 40 are adopting smart pen systems through MOHAP-permitted direct-to-consumer channels. Telemedicine platform integration enables remote endocrinologist oversight without clinic visits.
- Continuous Glucose Monitors:Subcutaneous sensor systems transmitting real-time glucose data to receivers or smartphones. Saudi pediatric diabetes centers are pairing CGM data streams with pump algorithms to reduce hypoglycemic events. Sensor-pump proprietary protocol lock-in raises total ownership costs and limits patient choice.
- Wearable Devices:Patch pumps and skin-adherent delivery systems designed for discreet, tube-free insulin administration. South African private hospital chains are piloting wearable patch pumps for adolescent Type 1 patients prioritizing lifestyle flexibility.
- Automated Insulin Delivery Systems:Closed-loop platforms integrating CGM data with predictive algorithms for autonomous basal rate adjustment. Saudi Arabia's SFDA fast-track approval pathway and government screening program procurement are channeling hospital investment toward these systems. Clinical validation in Gulf Cooperation Council networks is displacing manual pump protocols in high-volume diabetes wards.
Smart insulin pens dominate patient-driven retail migration; automated insulin delivery systems are climbing the fastest in hospital procurement pipelines.
End User:
Care setting determines device complexity requirements, regulatory oversight intensity, and reimbursement pathway structure.
- Home Care:Self-managed diabetes environments where patients or caregivers administer insulin without clinical supervision. Gulf Cooperation Council Type 1 diabetes education initiatives are expanding home care device demand for pen needle bundles and disposable systems. Patient digital literacy gaps in rural Egypt and Nigeria constrain smart device penetration.
- Hospitals:Acute and chronic care facilities with nursing staff administering insulin or supervising patient self-dosing. Saudi public hospital infrastructure investments are prioritizing automated delivery platforms to reduce nursing workload in diabetes screening program clinics.
- Diabetes Clinics:Specialized outpatient facilities focused on endocrinology and metabolic disease management. South African academic hospital-affiliated clinics are piloting closed-loop systems for complex Type 1 pediatric cases requiring intensive monitoring.
- Pharmacies:Community and hospital-based dispensing points providing device supply and patient counseling. Saudi retail pharmacy chains are launching subscription-based needle and cartridge replenishment services for insulin pen users.
Hospitals command procurement volume for advanced systems; home care settings are gaining share fastest as self-management protocols expand.
Distribution Channel:
Channel selection reflects regulatory framework maturity, prescription verification infrastructure, and patient convenience preferences.
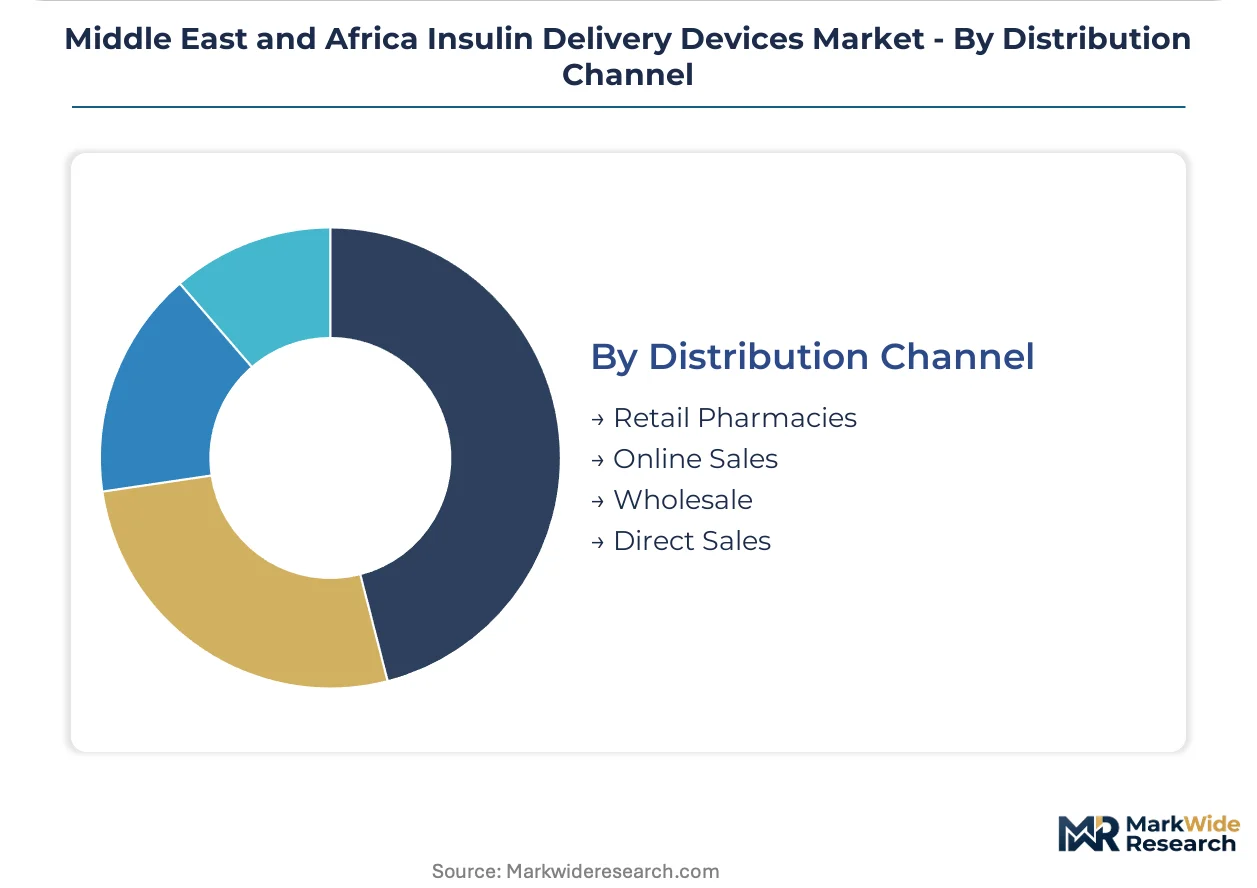
- Retail Pharmacies:Brick-and-mortar dispensing points with pharmacist oversight and in-person patient counseling. Dominant channel across Middle East and Africa due to established cold chain infrastructure for insulin storage and established relationships with hospital discharge workflows.
- Online Sales:Direct-to-patient fulfillment platforms with remote prescription verification and home delivery. MOHAP regulatory clarity in the UAE is enabling channel growth among digitally literate patient cohorts under 40.
- Wholesale:Bulk procurement intermediaries supplying hospital systems and pharmacy chains. Concentrated relationships with Saudi and South African national tender processes determine market access for new device entrants.
- Direct Sales:Manufacturer-to-institution contracting bypassing distribution intermediaries. Nigerian private hospital chains in Lagos and Abuja are importing pen-based systems directly to circumvent fragmented public procurement timelines.
Retail pharmacies maintain volume leadership; online sales are expanding most quickly where regulatory frameworks permit remote fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Gulf regulatory frameworks and sub-Saharan enforcement capacities are redirecting device certification investments toward Riyadh and Dubai, while South Africa's harmonization with IEC standards creates a secondary approval hub for broader African market access.
Saudi Arabia
Government diabetes screening programs and hospital infrastructure investments are channeling procurement toward automated insulin delivery technologies. SFDA's tightened ISO 15197 and IEC 60601 compliance timelines favor manufacturers with established quality management systems. Riyadh's tertiary care centers are piloting closed-loop artificial pancreas systems for pediatric Type 1 populations.
United Arab Emirates
MOHAP's accelerated approval pathway for devices with prior FDA or CE marking attracts European manufacturers seeking Gulf market entry. Dubai's private endocrinology practices serve needle-phobic patient segments with limited jet injector adoption. Telemedicine-integrated dosing platforms paired with Bluetooth-enabled smart pens enable remote regimen adjustments.
South Africa
Academic hospital-affiliated diabetes clinics pilot closed-loop systems for complex Type 1 pediatric cases requiring intensive monitoring. Health Products Regulatory Authority harmonization with SFDA frameworks creates a two-country certification pathway for broader African access. Cape Town and Johannesburg hospital networks face biomedical engineering talent scarcity in pump maintenance and algorithm calibration.
Nigeria
Private hospital chains in Lagos and Abuja import pen-based systems directly, bypassing fragmented public procurement timelines. Patient digital literacy gaps in rural regions constrain smart device penetration beyond major metropolitan clusters. Retail pharmacy cold chain infrastructure limitations favor disposable pen systems over pump reservoirs requiring specialized storage.
Kuwait
Closed-loop glucose-responsive dosing technology penetrates tertiary care networks, replacing manual basal-bolus protocols. Government-funded Type 1 diabetes self-management education initiatives expand home care demand for pen needle bundles. Kuwait City's hospital procurement officers weigh total cost of ownership against nursing workflow efficiency in device selection.
Middle East and Africa Insulin Delivery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automated delivery systems consolidating around validated quality systems while pen-based devices fragment across price tiers. European and North American manufacturers with captive ISO 13485 certification capture accelerated approval slots in Saudi Arabia and the UAE. Three archetypes dominate: algorithm-enabled pump specialists, disposable pen volume producers, and sensor-pump integration platforms. Geographic expansion through distributor partnerships and technology licensing for closed-loop algorithms represent the dominant competitive moves.
Among the established device manufacturers, Medtronic PLC, Novo Nordisk A/S, and Ypsomed occupy positions reflecting distinct strategic emphases. Medtronic exemplifies the automated insulin delivery archetype through its closed-loop technology presence in Gulf Cooperation Council hospital networks. Novo Nordisk anchors regional supply chains through localized distribution partnerships and established insulin portfolio relationships. Ypsomed sits within the pen needle and pump reservoir specialization tier, serving price-sensitive market segments across the region.
| Leading Market Players |
|---|
| Medtronic PLC |
| Ypsomed |
| Novo Nordisk A/S |
| F. Hoffmann-La Roche Ltd. |
| Becton Dickinson & Company |
| Sanofi |
| Insulet Corporation |
| Tandem Diabetes Care |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
ISO 13485 certification tiers bifurcate the Middle East and Africa insulin delivery landscape into accelerated-approval premium channels and extended-timeline commodity procurement, with SFDA and MOHAP compliance investments concentrating manufacturing partnerships among European and North American suppliers while price-sensitive sub-Saharan markets absorb residual inventory through direct-import channels.
Pricing Analysis
Distributor margin layers absorb 25-40% of landed device costs in Saudi Arabia and the UAE, compressing manufacturer netbacks while retail pharmacy markups on pen needle bundles sustain working capital for subscription replenishment services. Pricing stratifies across premium, standard, and economy tiers based on algorithm sophistication and sensor interoperability certification, with automated insulin delivery systems commanding three-to-five-fold premiums over disposable pen systems. Cost compression in the syringe-and-vial segment intensifies as Egyptian and Moroccan public hospitals consolidate bulk tenders, while Gulf Cooperation Council tertiary care networks show lowest price sensitivity for closed-loop platforms that reduce nursing FTE requirements.
Supply Chain Analysis
SFDA and MOHAP quality management system mandates gate supplier eligibility, concentrating electromechanical pump sourcing among Switzerland, Germany, and the United States while pen needle manufacturing draws from Ireland, Denmark, and China. Raw material dependencies include medical-grade polymers for cartridge systems, precision-machined steel for pen needles, and lithium-ion cells for pump power modules. Single-source vulnerability runs through proprietary CGM-to-pump communication protocols that lock patients into integrated ecosystems. Distribution runs through Saudi and South African national tender processes for hospital systems, with UAE retail pharmacy chains and Nigerian direct-import channels fragmenting downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa insulin delivery market represents a late-cycle quality story where SFDA and MOHAP regulatory convergence toward ISO 15197 and IEC 60601 standards is redirecting procurement volume toward pre-certified automated delivery platforms and algorithm-enabled dosing systems.
For Market Incumbents: Anticipate margin compression in the disposable pen segment as Chinese manufacturers achieve SFDA registration and undercut established European suppliers on tender pricing. Defensive consolidation moves should prioritize backward integration into pump reservoir manufacturing to capture recurring revenue streams, while certification investment in HL7 FHIR interoperability protects hospital IT integration moats against software-native challengers. For New Entrants and Emerging Players: Pharmacy chain partnerships in Saudi Arabia offer the most penetrable channel for smart pen systems with Bluetooth-enabled dose logging and subscription-based consumable replenishment. White-space targets include Nigerian private hospital direct-import procurement bypassing fragmented public tender timelines, and telemedicine-integrated dosing platforms serving UAE and Kuwaiti patients under 40 through MOHAP-permitted remote prescription verification channels. For Investors and Strategic Acquirers: Consolidation pressure builds where biomedical engineering talent scarcity in Riyadh and Johannesburg constrains pump maintenance and algorithm calibration capacity, favoring acquisition of regional service networks and training academies. Long-term viability in the 5-10 year window hinges on sensor-pump interoperability standardization breaking proprietary protocol lock-in. The signal to watch is SFDA publication of interoperability testing requirements, which would deflate integrated-ecosystem premiums and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Fast-Track Certification Investment | Accelerated approval slots capture Saudi hospital procurement ahead of IEC 60601 compliance deadlines. |
| Telemedicine Platform Integration | Bluetooth-enabled smart pen data streams enable remote endocrinologist oversight without clinic visits. |
| Pharmacy Chain Subscription Services | Saudi retail networks lock in recurring needle and cartridge replenishment revenue from Type 1 cohorts. |
| HL7 FHIR Interoperability Development | Hospital IT integration compatibility reduces deployment timelines in Gulf Cooperation Council networks. |
| Biomedical Engineering Training Academy | Riyadh and Johannesburg talent pipelines address acute pump maintenance and algorithm calibration scarcity. |
Research Methodology
Coverage spans Saudi Arabia, the UAE, South Africa, Nigeria, and Kuwait, with primary inputs from each market combining structured interviews with hospital procurement officers, biomedical engineers, retail pharmacy chain managers, and endocrinology department heads with secondary validation from SFDA device registration databases, MOHAP reimbursement lists, South African Health Products Regulatory Authority filings, and hospital tender documentation. Bottom-up triangulation across pen, pump, and automated delivery system unit economics converges with top-down expenditure modeling from national health insurance frameworks.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window, with segmentation dimensions spanning product type, technology tier, end-user setting, and distribution channel. CAGRs derive from patient population growth, screening program penetration, and reimbursement authorization velocity. Industry-specific forecast inputs include SFDA registration timeline distributions and MOHAP fast-track approval conversion rates for prior FDA or CE marked devices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sensor-pump interoperability standardization, Gulf sovereign health budget allocations, and sub-Saharan cold chain infrastructure investment. Forecasts reflect assumptions around regulatory harmonization pace and reimbursement list expansion velocity. A model refresh is warranted upon material change in SFDA quality management system directive enforcement intensity or MOHAP telemedicine prescribing framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market