
 Drug-Induced Immune Hemolytic Anemia Market | 2026-2036
Drug-Induced Immune Hemolytic Anemia Market Size, Share, and Industry Trends Forecast 2026-2036
Drug-Induced Immune Hemolytic Anemia Market Foresight
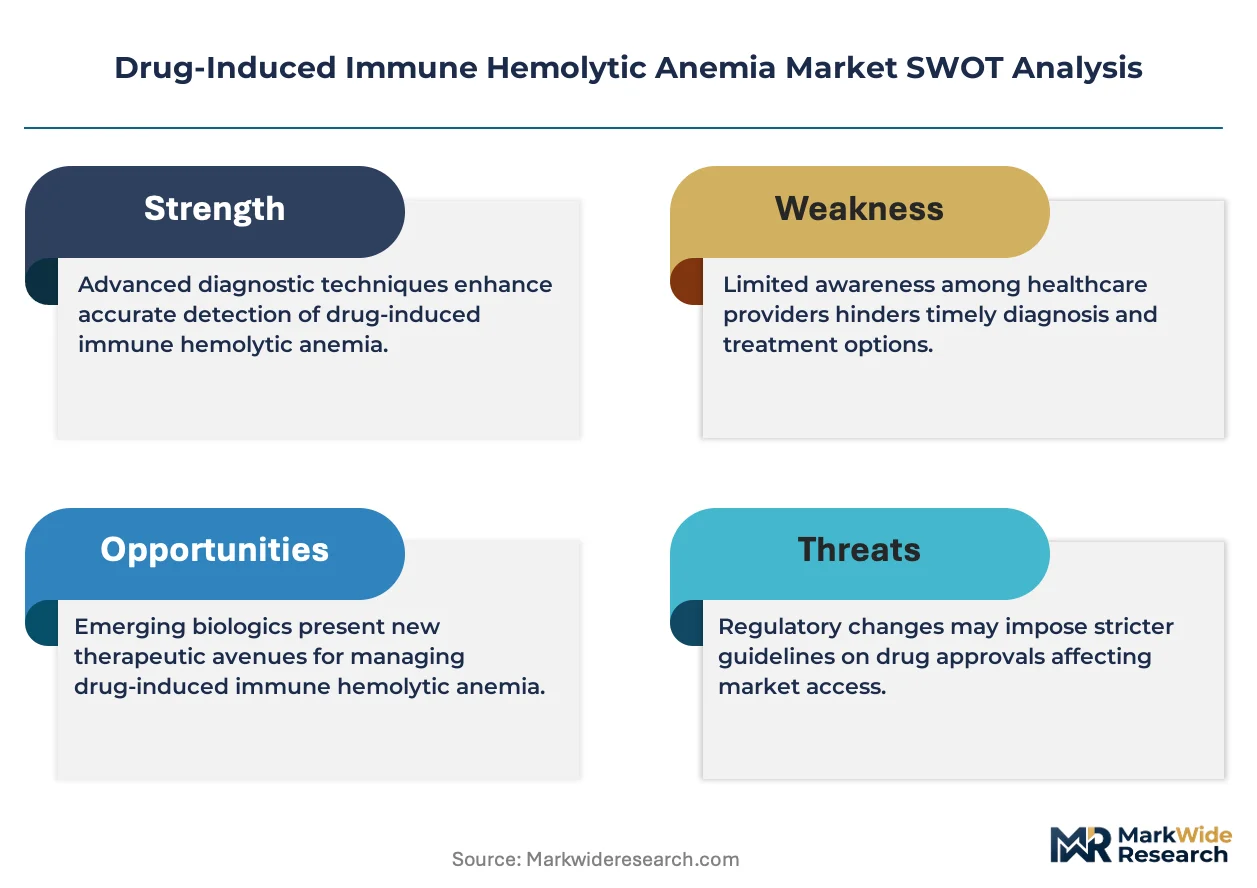
Hematologist workforce scarcity is bifurcating the Drug-Induced Immune Hemolytic Anemia market into high-volume academic centers and fragmented community settings. F. Hoffmann-La Roche Ltd. leverages its monoclonal antibody pipeline to dominate biologic-driven treatment pathways. CSL Behring anchors plasma-derived immunoglobulin supply chains across North American and European hospital networks. Grifols S.A. competes through vertical control of plasma collection and fractionation infrastructure.
Drug-induced immune hemolytic anemia represents an immune-mediated destruction of erythrocytes triggered by pharmaceutical compounds, primarily antibiotics, NSAIDs, and biologic agents, with diagnosis hinging on direct antiglobulin (Coombs) testing and elution studies to identify drug-dependent antibodies. Corticosteroids occupy the largest product type position due to their first-line status in acute hemolytic episodes, while monoclonal antibodies represent the fastest-expanding category as targeted B-cell depletion therapies gain protocol adoption. Intravenous therapy leads the treatment approach landscape in hospital settings, though oral corticosteroid tapers sustain outpatient revenue pools.
FDA pharmacovigilance requirements and EMA's Periodic Safety Update Reports shape biologic labeling and post-market surveillance obligations for manufacturers. The EU MDR and ISO 15189 standards govern diagnostic test validation in clinical laboratories processing Coombs assays. Stakeholders must monitor evolving biosimilar competition in monoclonal antibody segments and adaptive trial designs for rare adverse event detection.
Market Dynamics
Hospital consolidation into specialized hematology networks is concentrating patient volumes and treatment protocol standardization, while FDA pharmacovigilance mandates force manufacturers to restructure post-market surveillance infrastructure for biologic agents.
Growth Catalysts
- EMA Periodic Safety Update Reports:Biologic manufacturers must submit rigorous adverse-event documentation, expanding demand for specialized diagnostic testing infrastructure and pharmacovigilance services across European hospital networks.
- Academic medical center clustering:High-volume hematology centers in the United States, Germany, and Japan aggregate complex cases, creating concentrated demand for advanced monoclonal antibody therapies and combination protocols.
- Direct antiglobulin test automation:Clinical laboratories adopt high-throughput Coombs testing platforms, reducing diagnostic turnaround times and accelerating treatment initiation in acute hemolytic episodes.
Market Restraints
- Plasma fractionation concentration:Three North American and European suppliers control immunoglobulin raw material supply, exposing treatment protocols to collection center capacity constraints and viral screening bottlenecks.
- Specialized hematologist scarcity:Fellowship-trained immunohematology expertise concentrates in tertiary centers, fragmenting community care and delaying appropriate corticosteroid or biologic initiation.
- Biologic cold chain requirements:Monoclonal antibody therapies demand continuous temperature-controlled distribution, limiting rural hospital formulary access and emergency department stocking.
Strategic Opportunities
- Biosimilar monoclonal antibody pathways:Reference product exclusivity expirations create entry points for follow-on B-cell depletion therapies, compressing pricing and expanding protocol accessibility in cost-sensitive hospital systems.
- Telehematology consultation networks:Community hospitals connect to academic specialists through remote diagnostic review, extending expert Coombs test interpretation and treatment guidance to underserved regions.
- Japan's PMDA orphan drug incentives:Rare disease designation programs accelerate review timelines for novel biologic therapies targeting drug-induced hemolytic anemia with limited treatment alternatives.
Industry Challenges
- Adaptive trial design complexity:Rare adverse event detection requires novel statistical methodologies and extended follow-up periods, complicating biologic development timelines and regulatory submission preparation.
- Legacy Coombs assay interoperability:Automated platforms must interface with existing laboratory information systems, creating validation bottlenecks and delaying ISO 15189 certification completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug-Induced Immune Hemolytic Anemia Market |
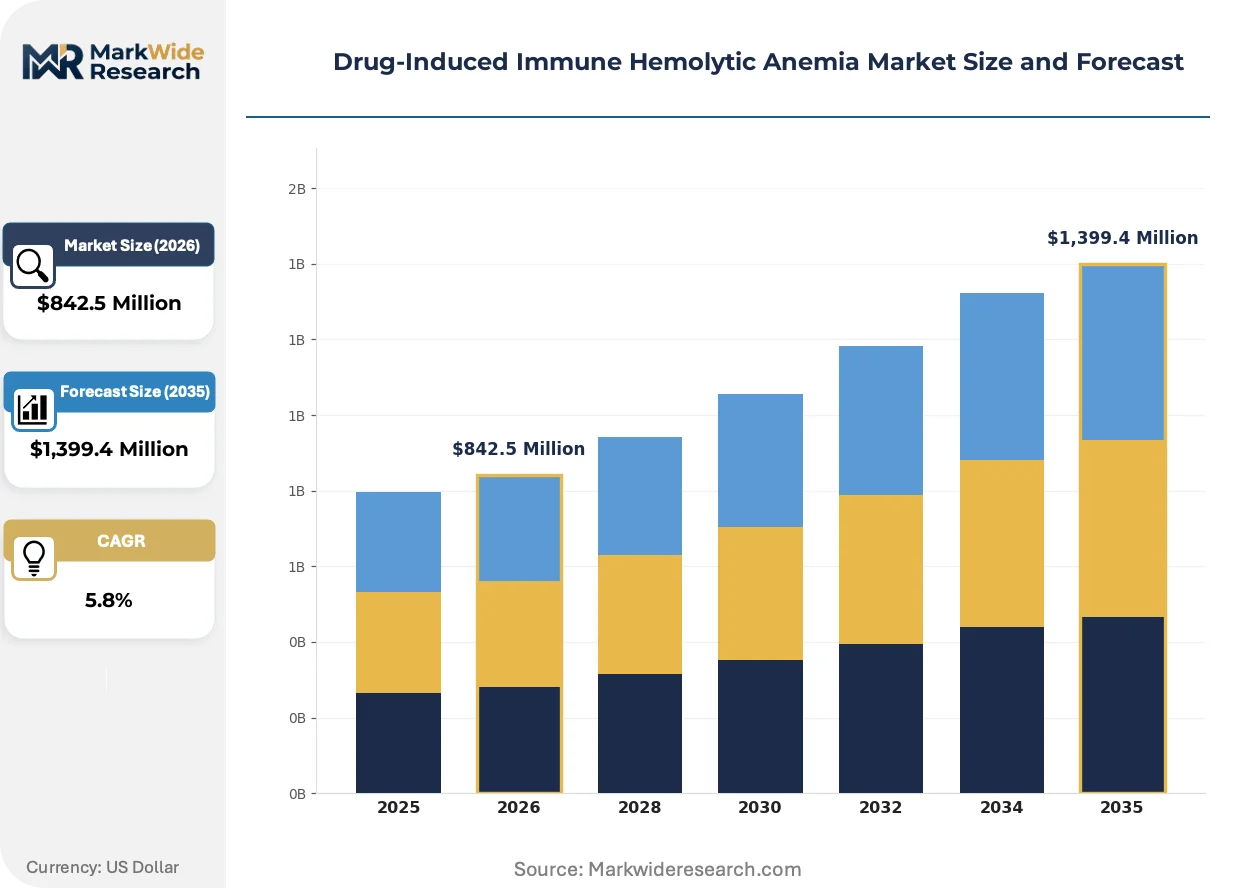
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,399.4 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono-Clonal Antibodies, Corticosteroids, Immunosuppressants, Erythropoietin End User: Hospitals, Clinical Laboratories, Blood Banks, Research Institutes Treatment Approach: Intravenous Therapy, Oral Therapy, Combination Therapy, Supportive Care Diagnosis Method: Blood Tests, Bone Marrow Biopsy, Coombs Test, Genetic Testing |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, Pfizer Inc., Sanofi, Johnson & Johnson, Amgen Inc., Teva Pharmaceutical Industries Ltd., CSL Behring, Grifols S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug-Induced Immune Hemolytic Anemia Market Shifts & Advancements
Diagnostic and therapeutic modalities are converging around precision immunohematology, with automation and targeted biologics displacing empirical corticosteroid protocols in frontline management.
Multiplexed microarray platforms for drug-dependent antibody detection are miniaturizing serological workups from multi-day elution studies to single-shift turnaround. Academic transfusion medicine departments in the United States and Germany deploy these systems to compress diagnostic timelines during acute hemolytic crises. The technology is miniaturizing laboratory footprints while enabling point-of-care screening feasibility in emergency departments.
EU MDR diagnostic device reclassification imposes strengthened clinical evidence requirements on Coombs test manufacturers, forcing retrospective validation studies and post-market clinical follow-up commitments. In vitro diagnostic firms must rebuild technical documentation to meet notified body expectations for Class C device conformity assessments. European hospital laboratories face supply interruptions as manufacturers rationalize product portfolios to concentrate on MDR-compliant platforms.
Academic medical centers now bundle biologic procurement with outcomes monitoring contracts, replacing traditional fee-for-service purchasing. Hospital pharmacy and therapeutics committees in the United States negotiate risk-sharing arrangements for monoclonal antibody therapies, tying reimbursement to hemolysis resolution metrics. This restructuring concentrates purchasing authority in integrated delivery networks and marginalizes independent community hematology practices.
Drug-Induced Immune Hemolytic Anemia Market Segmentation
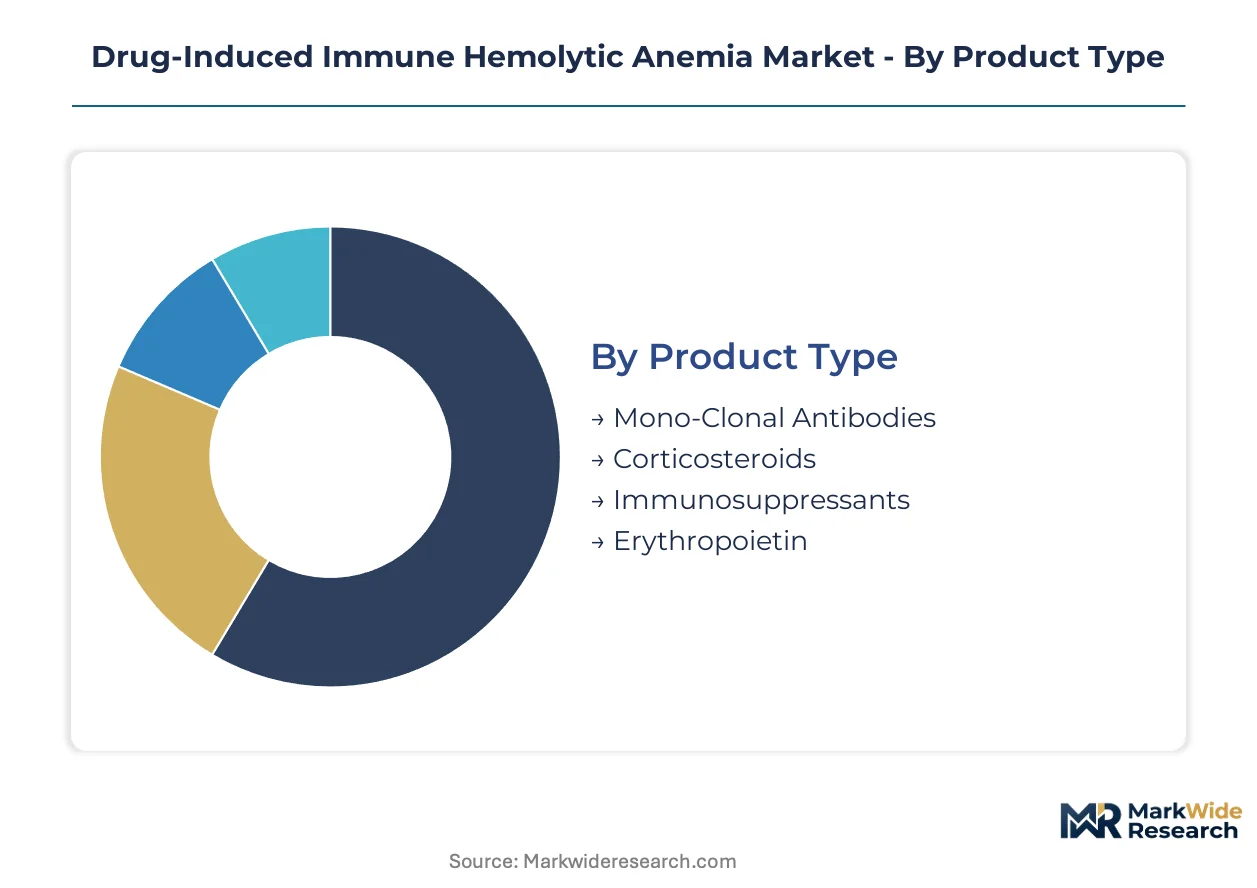
Segmentation in drug-induced immune hemolytic anemia reveals how diagnostic and therapeutic workflows split across institutional settings. Each category maps distinct procurement patterns, regulatory exposure, and substitution risks that shape commercial strategy.
Product Type:
Corticosteroids face intensifying substitution pressure as monoclonal antibodies displace empirical first-line protocols in academic medical centers.
- Corticosteroids:Synthetic glucocorticoids such as prednisone and methylprednisolone suppress immune-mediated erythrocyte destruction through broad anti-inflammatory action. Hospital formularies in the United States and Germany stock these agents for emergency hemolysis management, though prolonged exposure drives osteoporosis and hyperglycemia complications that limit chronic use.
- Mono-Clonal Antibodies:Engineered B-cell depletion therapies including rituximab target CD20 surface markers with precision immunohematology protocols. Tertiary centers in Japan and the United States prioritize these biologics for refractory cases, though cold chain infrastructure requirements restrict formulary access at rural facilities.
- Immunosuppressants:Azathioprine and cyclophosphamide modulate T-cell responses in corticosteroid-dependent patients.
- Erythropoietin:Recombinant erythropoiesis-stimulating agents address anemia sequelae without addressing underlying immune pathology.
Corticosteroids retain volume leadership; monoclonal antibodies hold the steepest expansion curve.
End User:
Cost tier stratification concentrates high-complexity case management in integrated hospital networks while fragmenting routine diagnostics.
- Hospitals:Tertiary and quaternary facilities manage acute hemolytic crises through dedicated transfusion medicine departments. Academic medical centers in the United States, Germany, and Japan aggregate complex cases requiring combination biologic protocols and specialized Coombs test interpretation.
- Clinical Laboratories:Hospital-affiliated and independent labs process direct antiglobulin testing with automated platform standardization. ISO 15189 accreditation demands and EU MDR device reclassification are compressing vendor options across European hospital networks.
- Blood Banks:Immunohematology reference laboratories perform antibody identification and compatibility testing for transfusion-dependent patients.
- Research Institutes:Academic transfusion medicine departments investigate drug-dependent antibody mechanisms and novel therapeutic targets.
Hospitals command the highest per-patient revenue; clinical laboratories show the fastest volume scaling with test automation.
Treatment Approach:
Application urgency drives modality selection, with inpatient intravenous protocols giving way to outpatient oral maintenance.
- Intravenous Therapy:Parenteral corticosteroid pulses and monoclonal antibody infusions dominate acute hemolysis management in emergency departments. United States hospital networks prioritize IVIG and rituximab protocols for rapid B-cell depletion in life-threatening presentations.
- Combination Therapy:Stacked corticosteroid-immunosuppressant-biologic regimens target refractory immune hemolysis with synergistic mechanism coverage. German hematology centers lead protocol standardization for multi-agent sequencing.
- Oral Therapy:Prednisone tapers and maintenance immunosuppressants sustain remission after acute control.
- Supportive Care:Transfusion support and folate supplementation address anemia without modifying immune pathology.
Intravenous therapy anchors acute revenue; combination therapy is climbing the fastest as protocol complexity increases.
Diagnosis Method:
Supply concentration in diagnostic platforms creates bottlenecks as laboratories await MDR-compliant instrument validation.
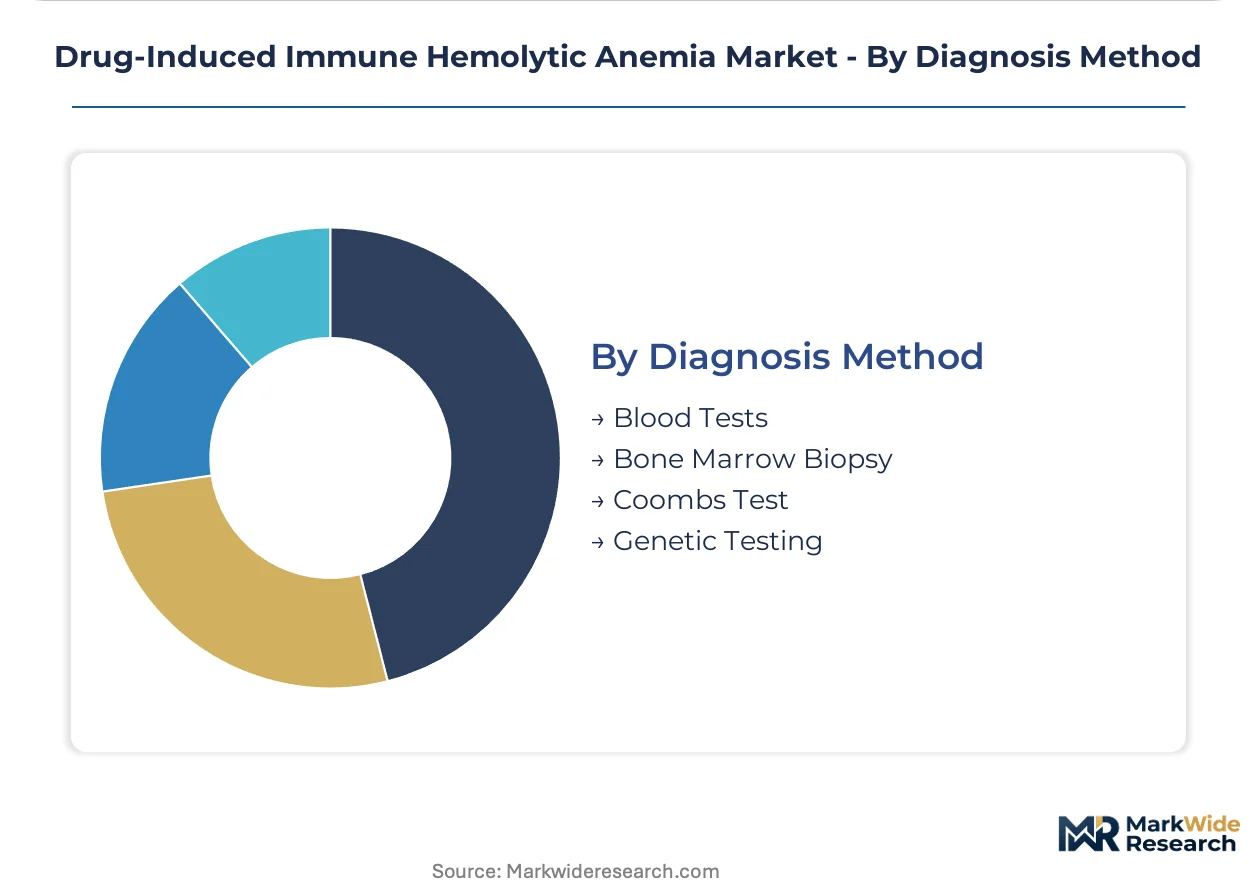
- Coombs Test:Direct antiglobulin testing detects erythrocyte-bound immunoglobulin and complement through agglutination assays. Automation vendors in the United States and Germany deploy high-throughput platforms that compress diagnostic turnaround from days to hours in acute presentations.
- Blood Tests:Complete blood count, reticulocyte indices, and lactate dehydrogenase panels establish hemolysis severity and bone marrow compensation. Japanese clinical laboratories integrate these parameters into standardized diagnostic algorithms for rapid triage.
- Bone Marrow Biopsy:Invasive sampling excludes underlying hematologic malignancy in atypical presentations.
- Genetic Testing:Pharmacogenomic screening identifies predisposition to drug-induced hemolysis in selected populations.
Coombs testing retains diagnostic volume leadership; blood tests show the steepest automation-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pharmacovigilance mandates in the United States anchor regulatory stringency across the Drug-Induced Immune Hemolytic Anemia market, with EMA and PMDA frameworks creating parallel compliance architectures in Europe and Japan. Academic medical center clustering concentrates specialized case volumes in three core geographies.
United States
Hospital consolidation into integrated delivery networks aggregates complex hemolysis cases at tertiary centers in Boston, Houston, and San Francisco. FDA adverse event reporting mandates for biologics force manufacturers to maintain post-market surveillance infrastructure. The Mayo Clinic and Johns Hopkins transfusion medicine departments standardize combination therapy protocols for refractory presentations.
Germany
EU MDR diagnostic device reclassification imposes clinical evidence requirements on Coombs test manufacturers, compressing vendor options for hospital laboratories. Heidelberg and Berlin academic hematology centers lead multi-agent sequencing protocols for corticosteroid-refractory patients. ISO 15189 accreditation demands accelerate platform standardization across the country's clinical laboratory networks.
Japan
PMDA orphan drug designation programs accelerate review timelines for novel biologic therapies targeting rare hemolytic presentations. Tokyo and Osaka metropolitan areas concentrate specialized immunohematology expertise at university hospitals. The country's national health insurance reimbursement framework shapes formulary access for monoclonal antibody therapies in acute care settings.
United Kingdom
NHS England specialized commissioning frameworks concentrate drug-induced hemolysis management at designated tertiary centers in London, Manchester, and Birmingham. MHRA pharmacovigilance requirements align with EMA Periodic Safety Update Report obligations for biologic manufacturers. Academic transfusion medicine departments at Oxford and Cambridge investigate drug-dependent antibody mechanisms.
Switzerland
Swissmedic regulatory frameworks govern biologic licensing and post-market surveillance for monoclonal antibody therapies distributed across European hospital networks. Basel and Zurich anchor pharmaceutical R&D clusters where manufacturers develop next-generation B-cell depletion therapies. The country's diagnostic device conformity assessment procedures create validation bottlenecks for automated Coombs platforms.
Drug-Induced Immune Hemolytic Anemia Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Drug-Induced Immune Hemolytic Anemia market, with biologic innovators and plasma fractionators occupying distinct competitive tiers. The vendor base splits between monoclonal antibody developers, plasma-derived immunoglobulin suppliers, and corticosteroid manufacturers. Three strategic archetypes dominate: integrated biopharmaceutical conglomerates with monoclonal antibody pipelines, vertically controlled plasma collection and fractionation specialists, and generic pharmaceutical manufacturers supplying corticosteroid volumes. M&A activity concentrates plasma collection assets, while strategic partnerships link diagnostic platform vendors to hospital laboratory networks.
Among integrated biopharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify technology leadership through monoclonal antibody development capabilities. CSL Behring represents the plasma fractionation archetype with captive control over immunoglobulin raw material supply chains. These three entities anchor distinct competitive positions without overlapping strategic territory, allowing parallel market expansion across biologic, plasma-derived, and small-molecule therapeutic categories.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| Johnson & Johnson |
| Amgen Inc. |
| Teva Pharmaceutical Industries Ltd. |
| CSL Behring |
| Grifols S.A. |
| Others |
Supply & Pricing Matrix
FDA pharmacovigilance mandates and EU MDR diagnostic reclassification simultaneously gate supplier qualification and stratify price tiers across the Drug-Induced Immune Hemolytic Anemia market. Manufacturers must absorb compliance infrastructure costs that concentrate pricing power among MDR-certified platform vendors and FDA-registered biologic producers.
Pricing Analysis
United States hospital networks pay 40-60% premiums over European counterparts for identical monoclonal antibody therapies due to reimbursement rate differentials and GPO contract structures. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and cold chain capability, with academic medical centers absorbing premium tiers for combination protocols. Cost compression in the corticosteroid segment is intensifying because of generic saturation and biosimilar monoclonal antibody entries. Community hospitals demonstrate highest price sensitivity due to formulary budget constraints, while integrated delivery networks leverage volume aggregation for least-sensitive procurement.
Supply Chain Analysis
United States and Germany anchor plasma collection and fractionation for immunoglobulin raw materials, while Switzerland and Japan concentrate monoclonal antibody bioproduction infrastructure. Plasma-derived therapies draw from donor collection center networks, cell culture media, and single-use bioreactor systems, with corticosteroid APIs sourcing from Indian and Chinese chemical synthesis hubs. Single-source vulnerability concentrates in the three North American-European plasma suppliers controlling immunoglobulin supply. Distribution runs through hospital pharmacy and therapeutics committees in integrated delivery networks, with cold chain logistics partners managing monoclonal antibody last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoclonal antibody biosimilar entry and automated Coombs platform deployment constitute simultaneous technological and regulatory inflections reshaping competitive dynamics across high-growth treatment and diagnostic segments.
For Market Incumbents: Secure plasma collection center capacity in United States Midwest and German donor networks to defend immunoglobulin supply positions against emerging fractionation entrants. Lock ISO 15189-accredited laboratory partnerships for automated Coombs platforms before MDR-compliant vendor consolidation completes, as diagnostic test interoperability becomes the priority lever for hospital formulary retention. For New Entrants and Emerging Players: Japan's PMDA orphan drug fast-track offers regulatory acceleration for novel B-cell depletion therapies targeting corticosteroid-refractory presentations. Target community hospital telehematology networks as the most penetrable access point, deploying remote diagnostic interpretation services that bridge hematologist scarcity gaps without requiring cold chain infrastructure investment. For Investors and Strategic Acquirers: EMA Periodic Safety Update Report mandates reshape the acquisition landscape by elevating pharmacovigilance infrastructure value in biologic target assessments. Five-to-ten-year viability hinges on backward integration into plasma collection or captive bioproduction capacity; monitor FDA adverse event reporting system data as the inflection signal for biologic safety profile deterioration that would trigger portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Behring and Grifols S.A. consolidate donor center assets across United States-Germany corridors. |
| Automated Coombs Platform Deployment | ISO 15189-accredited laboratories in Heidelberg and Boston compress diagnostic turnaround for acute hemolysis. |
| Biosimilar Monoclonal Antibody Filing | Follow-on rituximab entrants target cost-sensitive hospital systems with abbreviated FDA approval pathways. |
| Telehematology Network Integration | Remote consultation platforms connect Tokyo and Osaka specialists to underserved regional hospitals. |
| EU MDR Diagnostic Reclassification | Notified body conformity assessments force retrospective validation studies for legacy Coombs assay manufacturers. |
Research Methodology
Cross-validation between primary interviews with hematology department heads, transfusion medicine directors, hospital pharmacy procurement managers, and regulatory affairs specialists anchors the qualitative findings against secondary triangulation. FDA 483 inspection observations, EMA Periodic Safety Update Report submissions, ClinicalTrials.gov protocol registries, and hospital GPO contract databases provide external validation. Bottom-up patient volume modeling and top-down pharmaceutical revenue reconciliation converge on segment-level estimates.
Sensitivity analysis across treatment approach, product type, and end-user segmentation dimensions tests forecast robustness over the projection horizon. CAGRs derive from log-linear trend fitting adjusted for regulatory approval timelines and biosimilar entry assumptions. Modeled inputs include hospital consolidation rates, hematologist fellowship graduation counts, and plasma collection center capacity expansion schedules without year-specific anchoring.
Decision-makers should treat outputs as directional under stable regulatory enforcement and biologic safety profile assumptions; material deviation in FDA adverse event reporting stringency or EMA MDR implementation pace would warrant model refresh. Recalibration cycles align with material shifts in pharmacovigilance mandates, diagnostic platform validation completions, and plasma fractionation capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Atipamezole Market