
 Global SD WAN Market | 2026-2036
Global SD WAN Market Size, Share, and Industry Trends Forecast 2026-2036
Global SD WAN Market Outlook
Healthcare is repositioning its branch connectivity architecture toward cloud-delivered WAN models, displacing legacy MPLS dependencies in multi-site hospital systems. Cisco Systems leverages deep routing heritage to dominate enterprise installations with integrated security stacks. Fortinet sustains competitive density by anchoring its SD-WAN portfolio to native next-generation firewall capabilities. Versa Networks specializes in service provider channels, occupying the managed services tier with cloud-native orchestration.
Software-defined wide area networking decouples control plane intelligence from physical transport links, enabling policy-driven traffic steering across MPLS, broadband, and LTE paths using centralized controllers. Cloud-based deployment is capturing the fastest expansion as enterprises abandon premises-bound appliances for elastic consumption models; hybrid architectures retain durable share in regulated verticals requiring local breakout. Security-integrated technology segments command premium positioning, while pure routing functions face commoditization pressure from open-source alternatives.
FCC net neutrality rulings in the United States shape how providers engineer traffic prioritization, while GDPR and the EU NIS2 Directive mandate encrypted segmentation for cross-border enterprise data flows. ISO 27001 certification has become a de facto gate for vendor selection in European financial services procurement. Stakeholders must monitor how sovereign cloud mandates in Germany, France, and Japan fragment interoperability standards and force localization of policy orchestration layers.
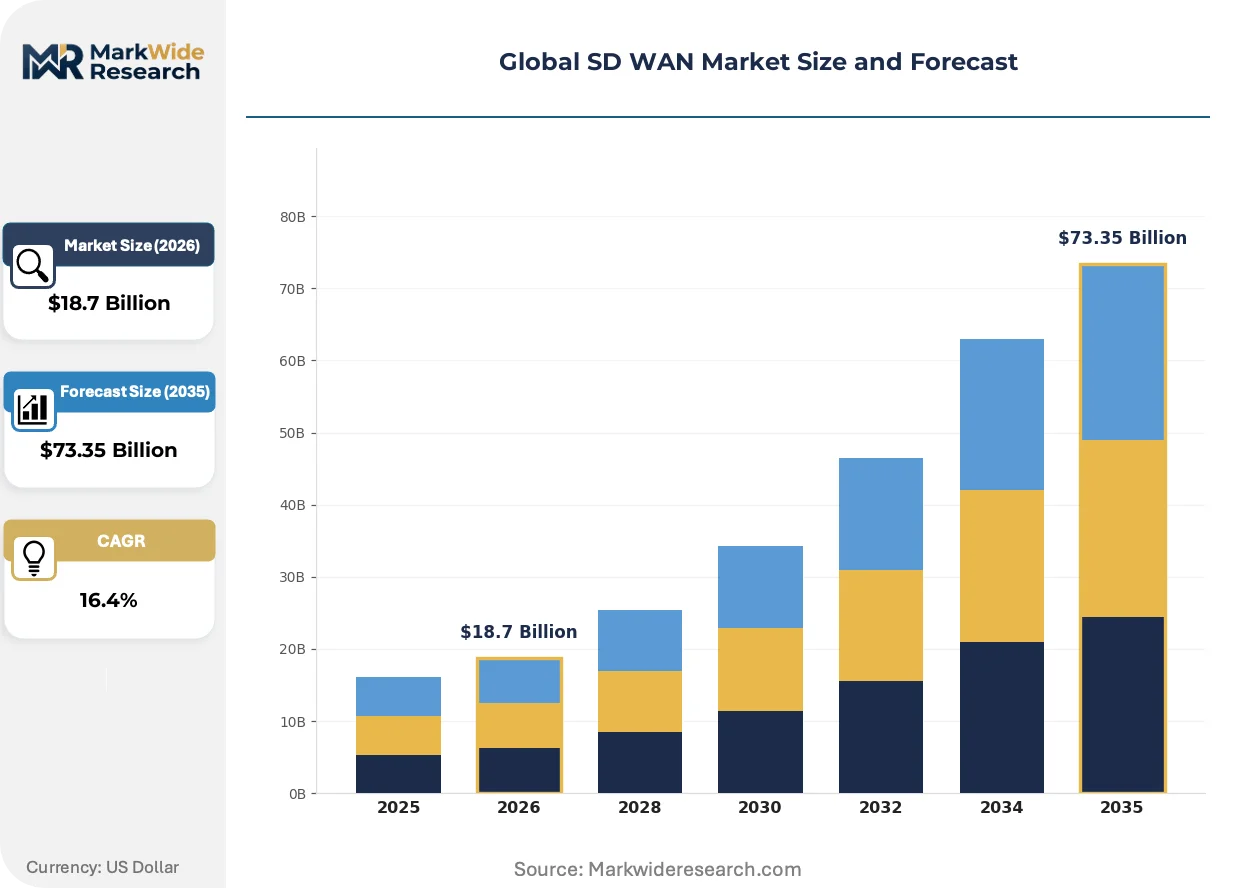
Market Dynamics
Cloud-delivered control planes are decoupling enterprise traffic management from physical transport infrastructure, compressing hardware refresh cycles and forcing incumbent vendors to rebundle security functions into subscription offerings.
Growth Catalysts
- EU NIS2 Directive:Mandated encryption and segmentation for cross-border data flows in critical infrastructure sectors accelerates procurement of security-integrated WAN architectures across European healthcare and energy operators.
- Healthcare cloud migration:Multi-site hospital systems in the United States are abandoning MPLS backbones for broadband-first connectivity to support telemedicine and electronic health record synchronization.
- Industrial automation clusters:Manufacturing concentration in Germany's Ruhr and Baden-Württemberg regions generates concentrated demand for managed SD-WAN services with deterministic latency guarantees.
Market Restraints
- Semiconductor supply concentration:Custom ASIC fabrication for high-throughput edge appliances depends on Taiwan-based foundry capacity, exposing lead time volatility.
- IPv6 transition friction:Enterprise networks with embedded IPv4-only legacy equipment face address space exhaustion blocking end-to-end policy orchestration.
- Skilled engineering scarcity:Shortage of certified network architects proficient in both legacy routing protocols and cloud-native controller APIs constrains deployment velocity.
Strategic Opportunities
- Japan's METI digital infrastructure push:Government incentives for SME cloud adoption create whitespace for managed service providers to displace premises-based CPE.
- Zero-trust architecture convergence:Integration of SD-WAN policy engines with identity-aware microsegmentation opens new procurement budgets from security-conscious financial services.
- Private 5G backhaul:Enterprises deploying campus-wide private cellular networks require software-defined aggregation layers not served by traditional WAN optimization appliances.
Industry Challenges
- Controller-to-edge synchronization latency:Real-time policy propagation across thousands of branch endpoints strains distributed database architectures and complicates failover design.
- Multi-cloud egress cost unpredictability:Traffic steering across AWS, Azure, and GCP regions without granular visibility into provider pricing tiers erodes total cost of ownership forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SD WAN Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Retail, Healthcare, Manufacturing, Education Service Type: Consulting, Integration, Support, Maintenance Technology: Virtualization, Routing, Security, Orchestration |
| Companies Covered | Cisco Systems, Fortinet, Hewlett Packard Enterprise, Nokia, Broadcom, VMware, Juniper Networks, Palo Alto Networks, Versa Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SD WAN Market Strategic Shifts
Artificial intelligence inference at the network edge is rewiring traffic patterns, forcing WAN architectures to accommodate unpredictable burst flows rather than predictable hub-and-spoke consolidation.
Single-vendor SASE stacks combining SD-WAN forwarding with cloud-native firewall and zero-trust network access are overtaking best-of-breed integration approaches in mid-market procurement. North American financial services and healthcare buyers prioritize consolidated billing and unified support over point-solution performance optimization. This consolidation is compressing standalone WAN optimization vendor margins and accelerating exits.
The EU AI Act's risk classification framework for automated decision-making systems is mandating audit trails for network traffic steering algorithms in high-risk deployments. German automotive manufacturers and French healthcare networks must now document how AI-driven path selection affects data residency compliance. Vendors are responding by localizing policy computation engines within sovereign cloud regions.
Enterprise sourcing departments are unbundling hardware procurement from managed service contracts, treating CPE as commodity infrastructure while competing on orchestration platform capabilities. This bifurcation is most pronounced in the United States, where Fortune 500 technology and retail buyers separate RFP processes for appliance supply from multi-year operational management agreements.
Global SD WAN Market Segmentation
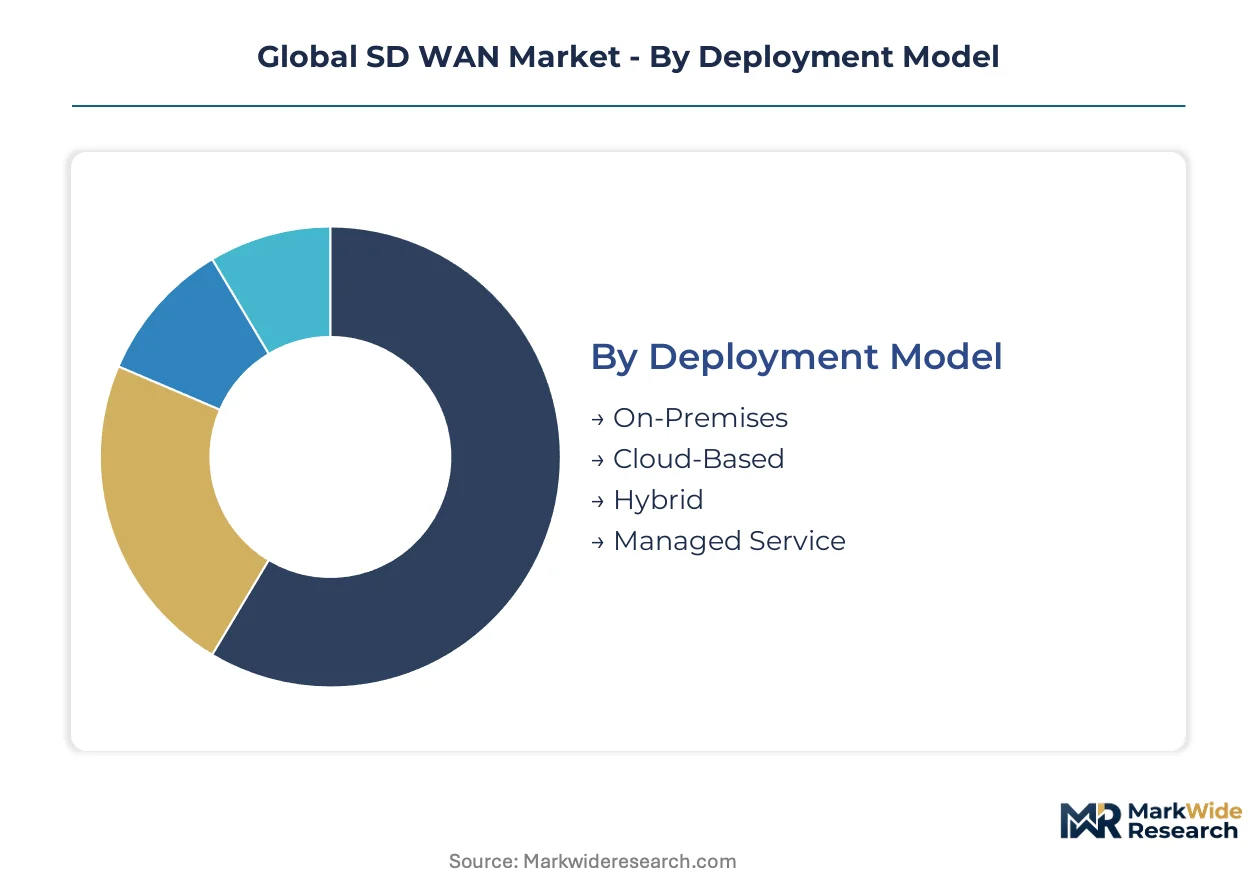
SD-WAN procurement patterns diverge sharply between enterprises seeking full-stack ownership and those outsourcing operational complexity to managed service providers. Segmentation reveals how deployment architecture, vertical requirements, and technology integration depth reshape vendor positioning and margin structures across the value chain.
Deployment Model:
Standalone appliance deployments retain durable share in regulated environments with strict data residency mandates, while embedded cloud-native control planes capture expansion in distributed enterprise footprints.
- On-Premises:Physical controller and edge appliance installations within enterprise data centers deliver deterministic policy enforcement for financial services and defense contractors. German automotive manufacturers and Japanese precision engineering firms favor this model to satisfy ISO 27001 audit requirements and sovereign cloud directives.
- Cloud-Based:Fully abstracted control planes delivered through multi-tenant SaaS architectures eliminate hardware refresh cycles and enable elastic branch onboarding. Healthcare networks in the United States and retail chains across France accelerate procurement here to support telemedicine and omnichannel fulfillment without capital-intensive CPE investments.
- Hybrid:Split-plane architectures localize critical policy decisions on-premises while bursting non-sensitive traffic through cloud gateways. Energy utilities in Texas and manufacturing clusters in Baden-Württemberg deploy this configuration to balance deterministic latency with cloud analytics integration.
- Managed Service:Third-party operational assumption of overlay orchestration, security policy maintenance, and carrier negotiation appeals to mid-market enterprises lacking certified SD-WAN engineering benches. Concentrated demand emerges from SME manufacturing in Japan's METI-subsidized digital transformation programs and distributed healthcare systems in rural United States markets.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Managed Service.
End User:
Vertical-specific compliance burdens and traffic pattern variability drive divergent technology requirements across buyer categories.
- Healthcare:Multi-site hospital systems with electronic health record synchronization demands and HIPAA-mandated encryption requirements prioritize security-integrated architectures with local breakout capabilities. United States health networks displace MPLS backbones fastest in this segment.
- Manufacturing:Industrial automation clusters require deterministic latency guarantees for programmable logic controller synchronization and predictive maintenance data flows. Germany's Ruhr region and Japan's Aichi prefecture generate concentrated procurement of managed services with private 5G backhaul integration.
- Retail:Distributed point-of-sale networks with seasonal traffic volatility favor broadband-first connectivity with cloud security stacks. Omnichannel fulfillment pressures reshape procurement toward SASE-consolidated vendors.
- Education:Campus and satellite learning center networks with constrained IT budgets gravitate toward subscription consumption models with unified support contracts. K-12 districts across California and Texas dominate regional demand patterns.
Procurement intensity clusters in Manufacturing; Education climbs fastest as federal connectivity subsidies expand.
Service Type:
Value capture migrates upstream from transactional implementation toward recurring operational relationships as enterprises unbundle hardware from managed outcomes.
- Integration:Multi-vendor stitching of edge appliances, legacy routing infrastructure, and cloud security stacks commands premium pricing during initial deployment phases. Complexity concentrates in hybrid architectures spanning on-premises controllers and multi-cloud egress points.
- Support:Tiered response commitments with dedicated technical account management differentiate managed service provider competitiveness. Financial services buyers in London and Singapore prioritize 24/7 coverage with sub-hour mean time to resolution.
- Consulting:Traffic engineering assessments and policy architecture design precede procurement decisions in large-scale transformations. Demand correlates with Fortune 500 cloud migration timelines.
- Maintenance:Firmware lifecycle management, threat signature updates, and certificate rotation constitute baseline recurring revenue pools. Commoditization pressure intensifies as automation reduces manual intervention requirements.
Revenue concentration sits with Integration; Support subscriptions expand most quickly as multi-year operational contracts displace project-based engagement.
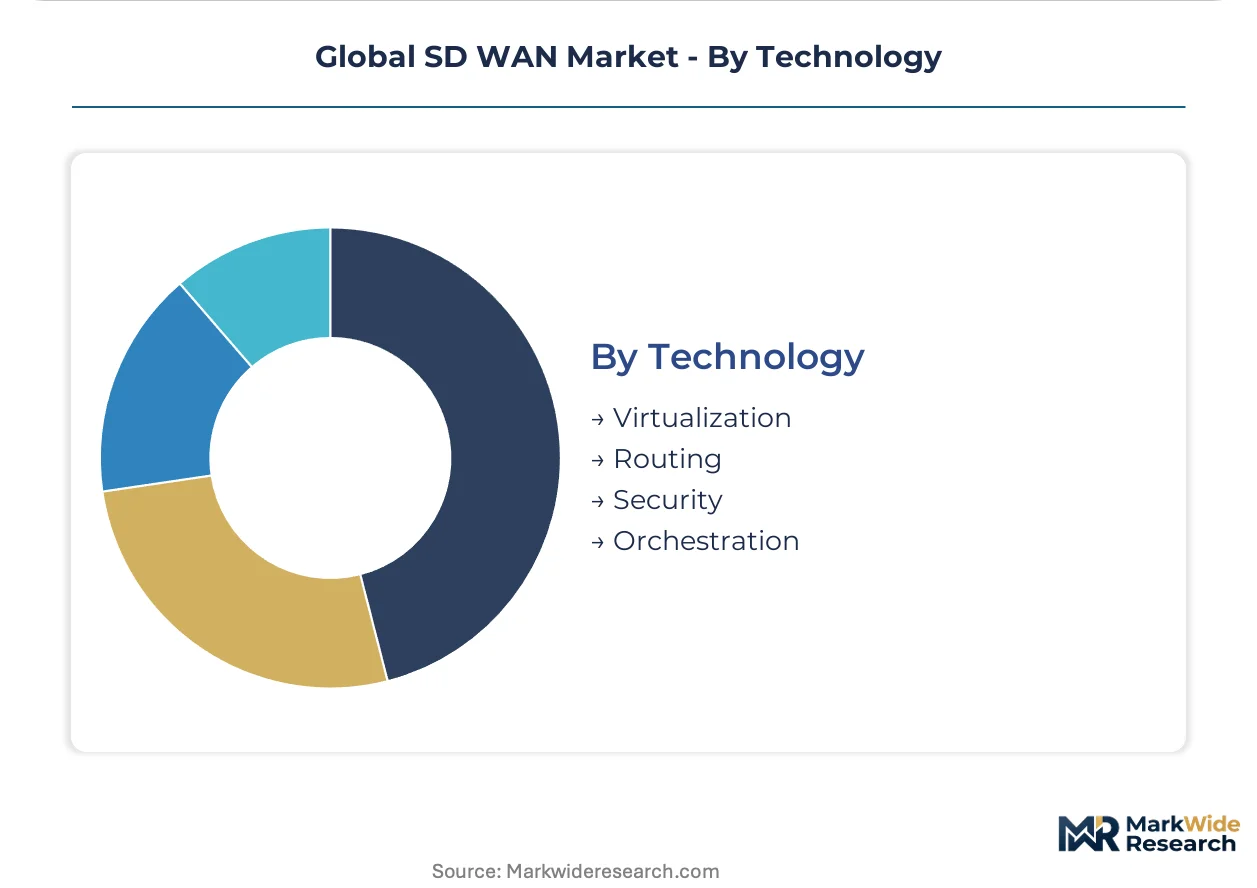
Technology:
Functional unbundling of control plane intelligence creates distinct competitive arenas with divergent margin profiles and vendor specialization patterns.
- Security:Native next-generation firewall integration, zero-trust network access enforcement, and encrypted segmentation command pricing premiums. EU NIS2 Directive compliance requirements accelerate procurement across European critical infrastructure operators.
- Orchestration:Centralized policy definition, real-time path computation, and multi-cloud traffic steering differentiate platform capabilities. Cloud-native architectures with REST API extensibility capture mid-market expansion.
- Virtualization:Network function virtualization enables software-defined edge deployment on commodity compute, reducing ASIC dependency and supply chain concentration risk. Containerized VNFs gain traction in Kubernetes-mature enterprises.
- Routing:Traditional forwarding plane optimization faces commoditization from open-source alternatives and white-box hardware programs. Incumbent vendors rebundle routing as table-stakes within security-integrated stacks.
Technology investment concentrates in Security; Orchestration capabilities gain share fastest as multi-cloud complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware production for SD-WAN edge appliances concentrates in Taiwan and China, while enterprise consumption clusters in Germany, the United States, and Japan where industrial automation and healthcare digitization drive procurement.
United States
Multi-site hospital systems displace MPLS backbones for broadband-first connectivity to support telemedicine and electronic health record synchronization. FCC net neutrality rulings shape how providers engineer traffic prioritization across enterprise networks. Healthcare networks in Texas and California accelerate cloud-delivered SD-WAN procurement to meet HIPAA-mandated encryption requirements.
Germany
Industrial automation clusters in the Ruhr and Baden-Württemberg regions generate concentrated demand for managed SD-WAN services with deterministic latency guarantees. The EU NIS2 Directive mandates encrypted segmentation for cross-border data flows in critical infrastructure sectors. Automotive manufacturers in Bavaria favor on-premises controller deployments to satisfy ISO 27001 audit requirements and sovereign cloud directives.
Japan
Government incentives under METI's digital infrastructure push create whitespace for managed service providers to displace premises-based CPE among SMEs. The country's national telecommunications regulator shapes spectrum allocation for private 5G backhaul integration. Manufacturing clusters in Aichi prefecture procure SD-WAN with deterministic latency for programmable logic controller synchronization.
France
French healthcare networks must document how AI-driven path selection affects data residency compliance under the EU AI Act's risk classification framework. CNIL enforcement of GDPR cross-border data flow rules accelerates procurement of security-integrated architectures. Retail chains across Île-de-French and Auvergne-Rhône-Alpes reshape procurement toward SASE-consolidated vendors for omnichannel fulfillment.
United Kingdom
Financial services buyers in London prioritize 24/7 support coverage with sub-hour mean time to resolution for trading floor connectivity. Post-Brexit data sovereignty requirements fragment interoperability standards with EU counterparts. Technology and retail buyers separate RFP processes for appliance supply from multi-year operational management agreements.
Global SD WAN Market Competitive Environment
Top-tier vendors anchor enterprise installations with integrated security stacks, while specialized challengers occupy the managed services tier. The vendor base stratifies across three tiers: routing heritage incumbents with rebundled subscription offerings, security-native platforms with next-generation firewall anchoring, and cloud-native specialists with service provider channel focus. Consolidation pressure intensifies as single-vendor SASE stacks overtake best-of-breed integration approaches. Dominant competitive moves include portfolio diversification into zero-trust convergence and strategic partnerships for private 5G backhaul integration.
Within the routing heritage tier, Cisco Systems and Juniper Networks exemplify incumbents rebundling hardware-centric portfolios into cloud-subscription architectures. Fortinet occupies a position bridging security-native and SD-WAN domains, anchoring competitive density through firewall-integrated positioning. Among cloud-native specialists, Versa Networks represents the service provider channel archetype with multi-tenant orchestration capabilities. These three patterns—heritage routing, security convergence, and cloud-native delivery—capture the competitive structure reshaping procurement decisions across healthcare, manufacturing, and financial services verticals.
| Leading Market Players |
|---|
| Cisco Systems |
| Fortinet |
| Hewlett Packard Enterprise |
| Nokia |
| Broadcom |
| VMware |
| Juniper Networks |
| Palo Alto Networks |
| Versa Networks |
| Others |
Value Chain & Pricing Dynamics
Captive ASIC fabrication in Taiwan anchors supply positioning for high-throughput edge appliances, while simultaneously constraining pricing power through lead-time volatility and foundry allocation scarcity. This vertical integration choice forces vendors to absorb cost compression in commoditized routing tiers while extracting premiums in security-integrated stacks.
Pricing Analysis
Premium pricing for expedited lead times from Taiwan-based foundries compresses margins on standard delivery contracts, while spot inventory discounts move through distribution channels during hardware refresh cycles. The dominant structure is subscription-tiered SaaS pricing with hardware-as-a-service bundling. Price differentiation separates ISO 27001-certified deployments from uncertified alternatives, and scales with throughput tier. Pricing pressure stems from open-source routing commoditization eroding standalone appliance margins. Mid-market healthcare buyers exhibit highest price sensitivity; defense contractors and German automotive manufacturers demonstrate lowest.
Supply Chain Analysis
ISO 27001 certification gates vendor qualification for European financial services and German industrial procurement, filtering supplier pools before commercial engagement. Geographic concentration centers on Taiwan for custom ASIC fabrication, China for commodity white-box assembly, and Malaysia for final system integration. Raw material dependencies include silicon wafers, high-bandwidth memory modules, and specialized networking ASICs. Single-source vulnerability at Taiwan foundries exposes lead time volatility. Distribution runs through authorized channel partners with technical certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-vendor SASE consolidation is compressing standalone SD-WAN vendor margins and accelerating exits among point-solution specialists. This consolidation pressure forces weaker players toward acquisition or channel obsolescence.
For Market Incumbents: Lock in enterprise relationships through zero-trust architecture convergence and private 5G backhaul integration partnerships. Fortify against cloud-native challengers by localizing policy orchestration engines within sovereign cloud regions to satisfy EU AI Act audit requirements. Prioritize certification maintenance for ISO 27001 and NIS2 Directive compliance as competitive moats. For New Entrants and Emerging Players: The EU NIS2 Directive in Europe opens a window for security-native platforms to displace legacy routing incumbents in critical infrastructure procurement. Target managed service whitespace in Japan's METI-subsidized SME digital transformation programs. Pursue channel partnerships with systems integrators possessing existing healthcare and manufacturing relationships rather than direct enterprise sales builds. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by security-platform consolidators seeking SD-WAN forwarding capabilities. The five-to-ten year viability window favors cloud-native orchestration specialists with service provider channel density over hardware-centric appliance vendors. Watch for inflection in sovereign cloud mandate enforcement across Germany, France, and Japan as signal for localization premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Convergence | Integrates identity-aware microsegmentation with SD-WAN policy engines for financial services procurement. |
| Private 5G Backhaul Integration | Addresses campus-wide cellular aggregation requirements in German and Japanese manufacturing clusters. |
| Sovereign Cloud Localization | Satisfies EU AI Act audit trail mandates for AI-driven path selection in automotive and healthcare networks. |
| Managed Service Provider Partnership | Captures METI-subsidized SME demand in Japan without capital-intensive direct sales infrastructure. |
| Open-Source Routing Commoditization Defense | Rebundles forwarding functions into security-integrated subscription stacks to preserve margin. |
Study Parameters
Multi-period observation of enterprise procurement patterns, vendor pricing disclosures, and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with network architects, managed service provider executives, carrier procurement leads, and cybersecurity policy officers at critical infrastructure operators. Secondary validation drew from FCC net neutrality filings, EU NIS2 Directive implementation guidance, METI digital infrastructure program documentation, and hyperscaler SD-WAN partnership announcements. Bottom-up triangulation of deployment volumes across healthcare, manufacturing, and financial services verticals converged with top-down market sizing.
Input-output matrices modeled relationships between control plane abstraction, edge appliance throughput tiers, and subscription pricing elasticity across deployment architectures. Segmentation dimensions included deployment model, vertical end-use, technology integration depth, and regional regulatory cluster. CAGRs were computed from fitted trend projections across the analysis window. Forecast inputs incorporated sovereign cloud mandate enforcement trajectories and private 5G spectrum allocation timelines.
The model assumes a particular technology adoption path; alternative pathways for IPv6-native orchestration or quantum-resistant encryption would alter the outlook for policy propagation latency and certification requirements. Forecasts reflect documented assumptions regarding carrier pricing stability and foundry capacity expansion. A model refresh is warranted upon material change in Taiwan semiconductor supply availability or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
IT Asset Management Solutions (ITAM) Market
Information and Communication Technology
Canada Data Center Server Market
Information and Communication Technology
Global Cloud Telecommunication AI Market
Information and Communication Technology
Latin America HMI Market
Information and Communication Technology
Global Spa and Salon Software Market
Information and Communication Technology
Quantum Information Processing Market
Information and Communication Technology
Global Linux Operating System Market
Information and Communication Technology
Tail Spend Management Solutions Market
Information and Communication Technology
Smart Tracker Market
Information and Communication Technology
Channel Management Software Market
Information and Communication Technology
AI Platform Cloud Service Market
Information and Communication Technology
Global Digital Rights Management Software Market
Information and Communication Technology
Malaysia Cybersecurity Market
Information and Communication Technology
Legal Analytics Market
Information and Communication Technology
Managed Mobility Services (MMS) Market
Information and Communication Technology
South Korea Telecom Tower Market