
 South Korea Telecom Tower Market | 2026-2036
South Korea Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Telecom Tower Market Insights
A capital-intensity divergence between tower manufacturers and network operators is rotating investment toward shared infrastructure models. KT Corporation leverages its nationwide fiber backbone to anchor co-location services at urban tower sites. SK Telecom sustains leadership through proprietary energy-efficient tower designs that reduce operational expenditure. LG Uplus competes aggressively on rural coverage expansion, deploying lighter monopole structures in mountainous Gangwon terrain.
South Korea telecom towers are steel or composite structures ranging from 15 to 100 meters in height, engineered to support multiple antenna arrays, transmission equipment, and power systems for wireless communication networks. These installations function as the physical backbone enabling radio frequency propagation across varied topography, with lattice and monopole configurations dominating based on load requirements and zoning constraints. Monopole towers command premium positioning in dense Seoul districts where footprint minimization determines permitting success, while camouflaged tower variants are gaining traction near heritage sites and residential zones where aesthetic compliance overrides pure cost efficiency. The service type dimension reveals maintenance and upgrade cycles as the steadiest margin pool, given Korea's aggressive 5G refresh timelines and typhoon-resilience mandates.
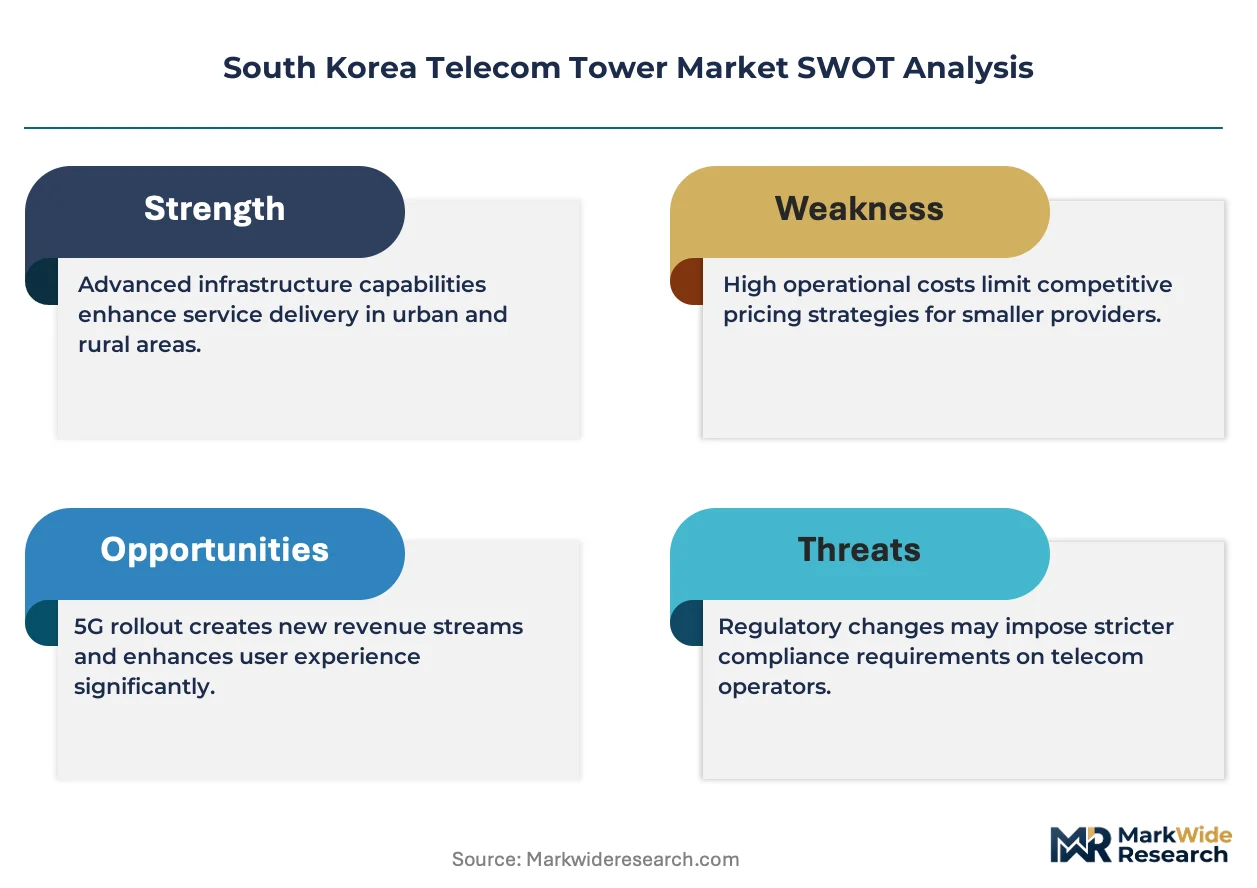
MFDS equipment certification, KOSHA workplace safety standards, and Ministry of Science and ICT radio facility licensing collectively govern tower construction, electromagnetic exposure limits, and operational permits across Korean jurisdictions. These frameworks elevate compliance costs but lock out uncertified foreign suppliers, insulating domestic fabricators and engineering firms. Stakeholders must monitor spectrum reallocation proceedings and local government smart-city integration mandates to anticipate where tower-sharing obligations and small-cell attachment rights will reshape site economics.
Market Dynamics
Spectrum densification mandates from the Ministry of Science and ICT are compressing site acquisition timelines and forcing co-location architectures across Seoul's congested urban corridors. This regulatory pressure is reconfiguring capital allocation toward shared infrastructure models that amortize deployment costs across multiple network operators.
Growth Catalysts
- 5G Mid-Band Expansion:KT Corporation, SK Telecom, and LG Uplus are racing to deploy 3.5 GHz infrastructure, multiplying antenna attachment points per tower structure.
- Smart City Integration:Seoul Metropolitan Government mandates require telecom towers to host environmental sensors and traffic management equipment, diversifying revenue streams.
- Typhoon Resilience Mandates:KOSHA workplace safety standards now require reinforced lattice designs in coastal Busan and Jeju installations, accelerating replacement cycles.
Market Restraints
- Steel Price Volatility:Domestic fabricators face input cost pressure from imported high-grade steel used in lattice tower construction.
- Zoning Concentration Risk:Permitting success in Seoul's 25 districts depends on fragmented local government aesthetic review boards with inconsistent standards.
- Small-Cell Substitution:Street-level microcells and lamp-post deployments are absorbing capacity demand that previously required macro towers.
Strategic Opportunities
- Gangwon Mountain Coverage:Underserved alpine corridors present whitespace for lightweight monopole structures with reduced foundation requirements.
- Camouflaged Tower Variants:Heritage site proximities and residential zone expansions create demand for stealth designs mimicking pine trees or church steeples.
- Energy Efficiency Incentives:Ministry of Science and ICT carbon reduction targets subsidize solar-hybrid power systems at off-grid rural sites.
Industry Challenges
- RF Engineer Scarcity:Specialized talent for electromagnetic field modeling and antenna optimization commands premium wages that compress project margins.
- MFDS Certification Timelines:Equipment approval delays for new antenna configurations extend deployment schedules by four to eight months.
- Legacy 4G Integration:Maintaining backward-compatible infrastructure while overlaying 5G active antenna systems complicates site engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Telecom Tower Market |
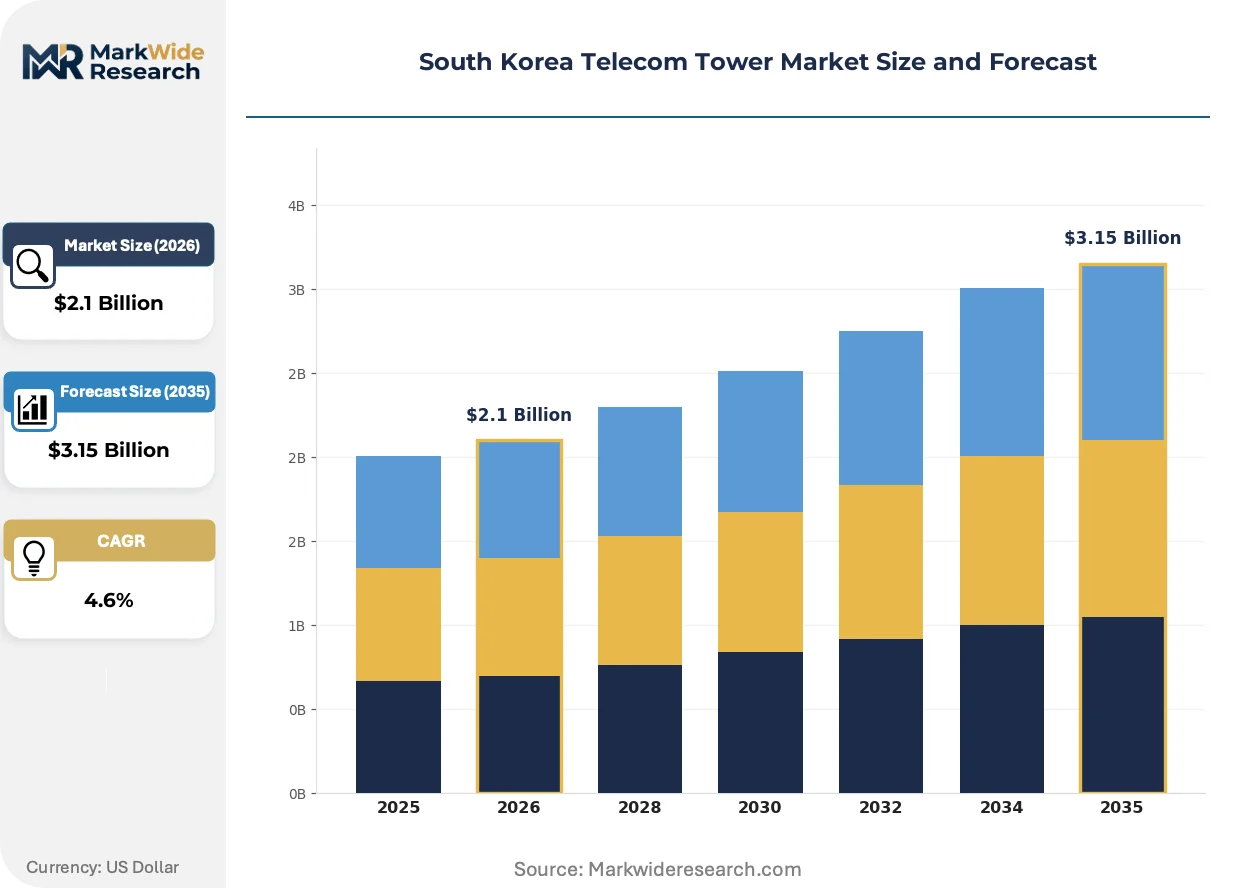
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice Tower, Camouflaged Tower, Guyed Tower End User: Mobile Network Operators, Government, Private Enterprises, ISPs Technology: 5G, 4G LTE, Microwave, Fiber Optics Service Type: Installation, Maintenance, Consulting, Design |
| Companies Covered | KT Corporation, SK Telecom, LG Uplus, SK Broadband, SK Telink, SEJONG Telecom, Dreamline, IDIS Powertel, Korea Cable Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Telecom Tower Market Trends and Innovations
Active antenna systems and edge computing integration are compressing the physical footprint of telecom infrastructure while multiplying functional density. These converging forces are redrawing equipment specifications and site economics.
Massive MIMO antenna arrays are miniaturizing from refrigerator-sized cabinets to compact panel configurations that reduce wind load and foundation requirements. Mobile network operators in Seoul's dense Gangnam and Jongno districts are adopting these systems at replacement rates exceeding legacy upgrade cycles. This compression is enabling rooftop deployments previously infeasible due to structural load constraints.
MFDS equipment certification now incorporates electromagnetic exposure testing protocols that exceed baseline international standards. Domestic fabricators must submit antenna systems for extended thermal and radiation pattern validation before commercial deployment. Tower manufacturers serving the Gyeonggi capital region are restructuring quality assurance workflows to parallel-track these regulatory submissions.
Network operators are unbundling tower maintenance from equipment supply contracts, creating standalone service procurement channels. SK Telecom and KT Corporation now separately tender preventive inspection and emergency repair services through three-year performance agreements. This disintermediation is most pronounced in Busan's industrial zones where uptime guarantees determine contract awards.
South Korea Telecom Tower Market Segmentation
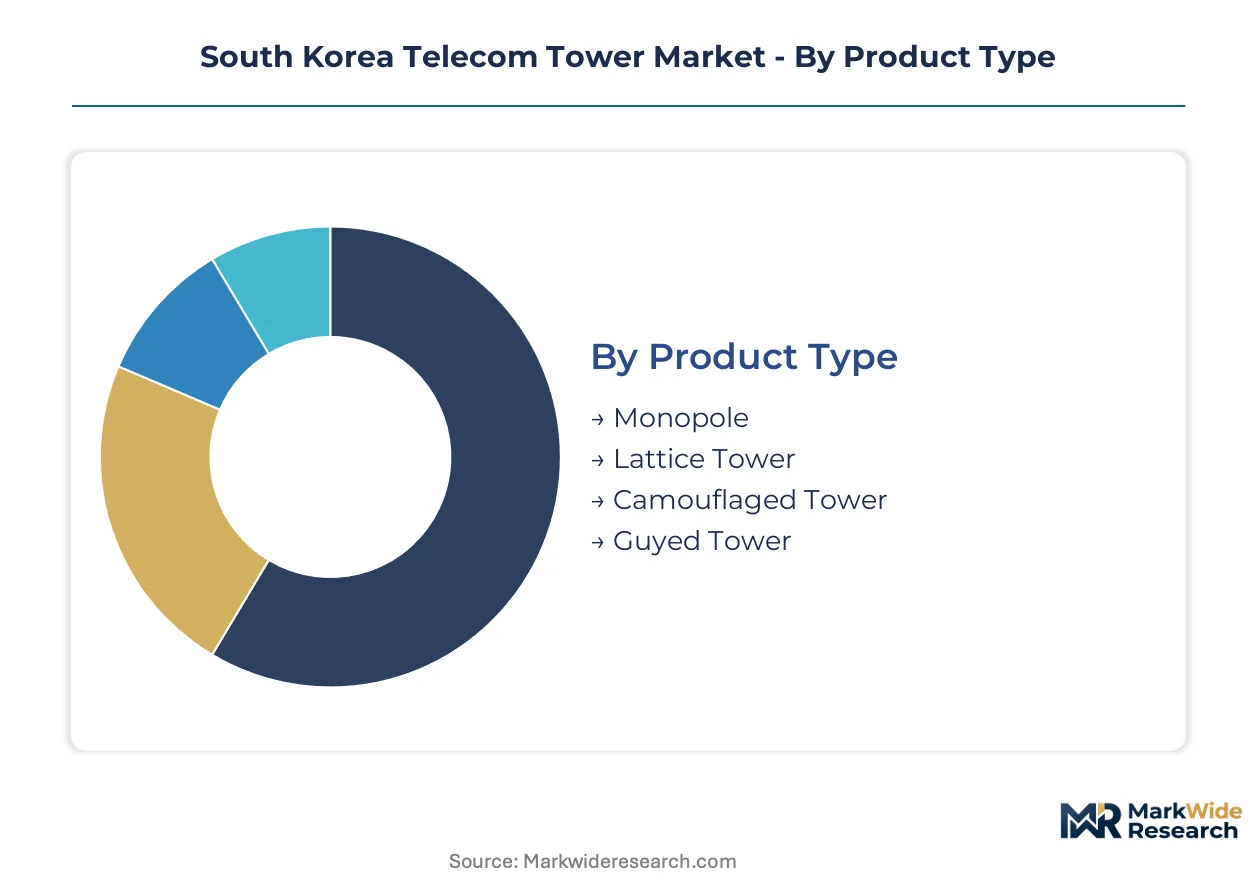
South Korea's telecom tower segmentation reflects the Ministry of Science and ICT's layered regulatory framework, where MFDS certification requirements, KOSHA safety mandates, and spectrum allocation policies create distinct compliance burdens across product categories. Understanding how these regulatory boundaries intersect with technology transitions and end-user procurement patterns determines which segments capture capital deployment priority.
Product Type:
MFDS equipment certification and KOSHA workplace safety standards impose divergent testing protocols across structural configurations, with lattice towers facing the most intensive wind-load validation while monopole variants navigate stricter electromagnetic exposure assessments.
- Monopole:Single-pole steel or composite structures ranging from 20 to 50 meters, optimized for minimal footprint in dense urban environments. Seoul's Gangnam and Jongno districts concentrate procurement where zoning boards prioritize visual intrusion minimization over absolute cost efficiency. KOSHA's revised foundation standards for seismic Zone 4 regions are extending engineering timelines by two to four months.
- Lattice Tower:Triangular or four-legged steel frameworks engineered for heavy antenna loads and heights exceeding 60 meters. Busan coastal installations and Jeju Island deployments drive replacement demand following typhoon resilience mandates that now require reinforced joint welding and corrosion-resistant galvanization. Domestic fabricators in Gyeonggi Province hold cost advantages through captive steel supply arrangements.
- Camouflaged Tower:Stealth structures mimicking pine trees, church steeples, or clock towers for heritage-adjacent and residential zone compliance.
- Guyed Tower:Cable-stabilized masts deployed primarily in temporary or remote coverage scenarios where foundation minimization outweighs land area requirements.
Lattice towers handle the majority of throughput in the current installed base; camouflaged variants are expanding most quickly as Seoul Metropolitan Government aesthetic review boards tighten visual impact standards.
End User:
Procurement authority concentrates with entities holding direct spectrum licenses or smart-city infrastructure mandates, creating tiered contract structures where payment terms and performance guarantees vary sharply by buyer type.
- Mobile Network Operators:KT Corporation, SK Telecom, and LG Uplus anchor tower demand through 5G densification programs and rural coverage obligations. These carriers are unbundling maintenance contracts from equipment supply, creating standalone service procurement channels with three-year uptime guarantee structures. Their capital allocation prioritizes co-location architectures that amortize site costs across multiple tenant arrangements.
- Government:National and municipal agencies procure towers for emergency communication networks, military installations, and public safety systems. The Ministry of Science and ICT directly funds select installations in Gangwon alpine corridors where commercial returns fail to justify private investment. Procurement cycles align with five-year national infrastructure plans rather than annual technology refresh timelines.
- Private Enterprises:Industrial conglomerates and logistics operators deploy captive towers for campus-wide private 5G networks.
- ISPs:Fixed-wireless access providers lease tower space or procure dedicated structures for last-mile broadband extension.
Mobile network operators command the dominant share of annual capital deployment; private enterprises are climbing fastest as manufacturing and port automation drives private 5G network construction.
Technology:
Antenna system specifications and power requirements vary substantially across radio frequency bands, with active antenna integration compressing physical footprints while multiplying functional density per tower structure.
- 5G:Massive MIMO arrays operating at 3.5 GHz mid-band and 28 GHz millimeter-wave frequencies demand reinforced mounting infrastructure and enhanced power distribution. Seoul's capital region concentrates deployment where site acquisition timelines have compressed to six to eight weeks under Ministry of Science and ICT densification mandates. Active antenna miniaturization is enabling rooftop installations previously infeasible due to structural load constraints.
- 4G LTE:Legacy infrastructure requiring backward-compatible overlay engineering as operators maintain voice service continuity during 5G transition. Rural Gyeongsang provinces and Jeolla regions see sustained maintenance expenditure where replacement economics remain unfavorable.
- Microwave:Point-to-point backhaul links for fiber-inaccessible sites.
- Fiber Optics:Tower-anchored fiber termination points supporting fronthaul connectivity to distributed baseband units.
5G infrastructure absorbs the preponderance of new capital allocation; fiber optic integration is gaining share fastest as KT Corporation leverages its nationwide backbone to anchor co-location service offerings.
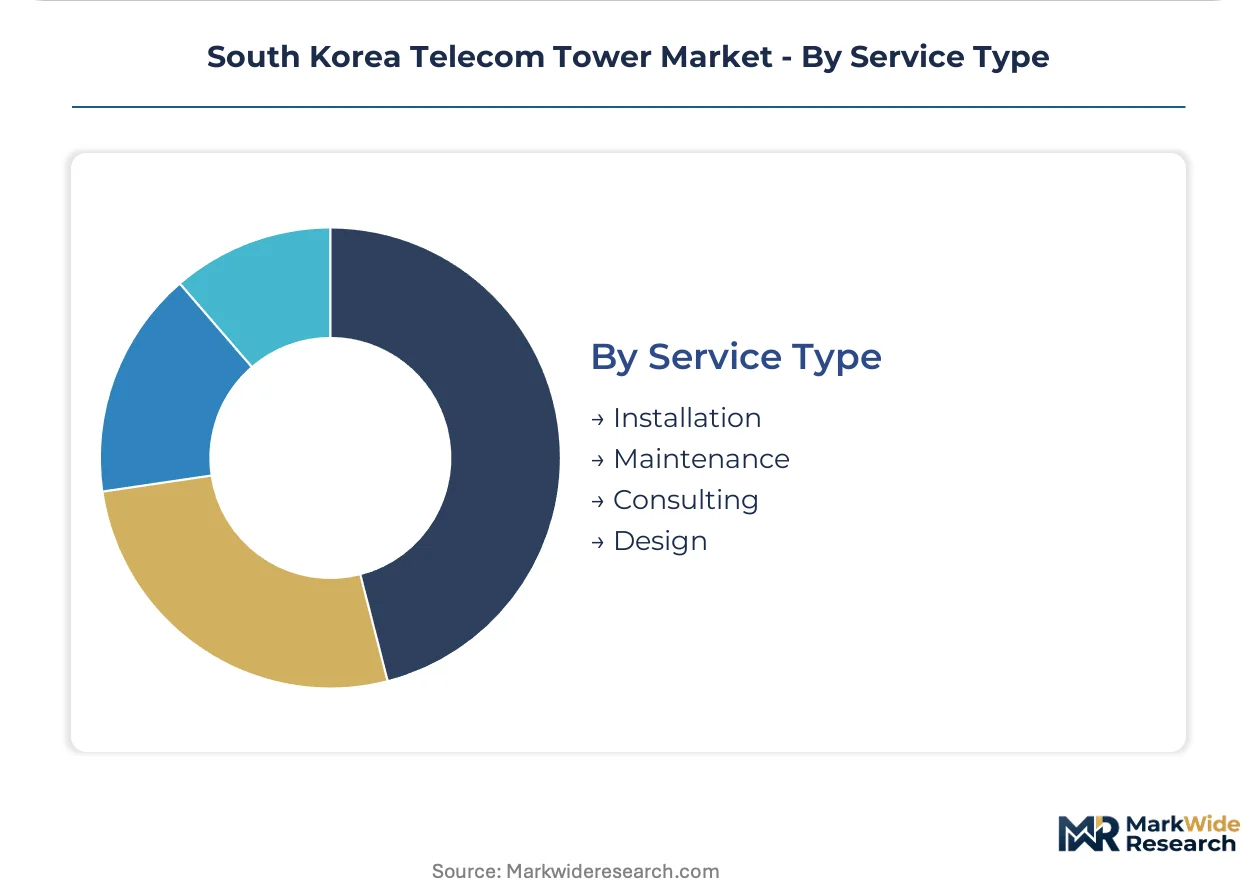
Service Type:
Margin structures diverge between one-time installation revenue and recurring maintenance streams, with typhoon resilience mandates and aggressive 5G refresh timelines stabilizing long-term service contract valuations.
- Maintenance:Preventive inspection, emergency repair, and structural reinforcement services governed by KOSHA workplace safety compliance cycles. SK Telecom and KT Corporation now tender these separately from equipment supply through performance-based agreements. Busan industrial zones and coastal installations command premium pricing for uptime guarantees.
- Installation:Site preparation, foundation construction, tower erection, and antenna mounting delivered under fixed-price or cost-plus contracts. Seoul's 25 districts impose fragmented permitting requirements that extend project timelines and elevate project management overhead.
- Consulting:RF planning, electromagnetic field modeling, and regulatory submission support.
- Design:Structural engineering, wind-load analysis, and aesthetic customization for camouflaged variants.
Maintenance commands the steadiest margin pool through recurring revenue visibility; consulting is expanding most quickly as MFDS certification timelines extend and operators seek parallel-track regulatory submission strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's telecom tower trade balance tilts toward domestic fabrication, with Gyeonggi Province steel fabricators supplying the majority of lattice structures while specialized monopole components draw selective imports from Japanese and German engineering specialists.
Seoul Capital Area
Seoul Metropolitan Government aesthetic mandates and Gangnam district zoning compressions drive camouflaged tower procurement. MFDS electromagnetic exposure protocols govern rooftop Massive MIMO installations in Jongno commercial corridors. KT Corporation anchors co-location services across 25 district jurisdictions with divergent permitting timelines.
Busan-Ulsan
Coastal typhoon resilience mandates from KOSHA accelerate replacement cycles for corroded lattice infrastructure. Heavy industrial zones in Ulsan generate private 5G network demand from shipbuilding and petrochemical operators. SK Telecom tenders separate maintenance contracts with uptime guarantees tied to port automation timelines.
Daegu-Gyeongbuk
Smart city integration policies in Daegu Metropolitan City require environmental sensor hosting on tower structures. Gyeongsang provinces sustain legacy 4G maintenance expenditure where 5G replacement economics remain unfavorable. LG Uplus competes on rural coverage expansion through lightweight monopole deployment.
Daejeon-Sejong
Government agency procurement for emergency communication networks concentrates in Sejong administrative city. Ministry of Science and ICT directly funds alpine corridor installations where commercial returns fail to justify private investment. Public procurement cycles align with five-year national infrastructure plans rather than annual technology refreshes.
Gwangju-Honam
Honam region agricultural automation drives private network tower demand from logistics and food processing operators. Jeolla provinces present whitespace for solar-hybrid power systems at off-grid rural sites under Ministry carbon reduction targets. Energy efficiency subsidies reshape site economics for distributed baseband unit deployment.
South Korea Telecom Tower Market Competitive Landscape
Concentration sits with mobile network operators who vertically integrate tower ownership with spectrum licenses. KT Corporation, SK Telecom, and LG Uplus control the preponderance of installed base through captive infrastructure arms. Three archetypes populate the competitive terrain: spectrum-anchored national carriers, government-backed rural coverage specialists, and private network system integrators serving industrial conglomerates. Competitive moves center on co-location tenancy expansion and unbundled maintenance service procurement.
Among carrier-affiliated infrastructure operators, KT Corporation, SK Telecom, and LG Uplus exemplify the spectrum-anchored archetype, each occupying positions that fuse tower ownership with radio access network deployment authority. SK Broadband and SEJONG Telecom represent secondary-tier participants with focused geographic or service-type specializations. The competitive dynamic rewards entities capable of amortizing site costs across multiple tenant arrangements while navigating fragmented municipal permitting requirements.
| Leading Market Players |
|---|
| KT Corporation |
| SK Telecom |
| LG Uplus |
| SK Broadband |
| SK Telink |
| SEJONG Telecom |
| Dreamline |
| IDIS Powertel |
| Korea Cable Telecom |
| Others |
Pricing and Supply Chain Analysis
MFDS equipment certification gates both supplier qualification and price stratification across South Korea's telecom tower market, erecting compliance barriers that domestic fabricators exploit for margin protection while foreign competitors absorb premium validation costs. This regulatory threshold simultaneously compresses the qualified vendor pool and segments pricing tiers by certification tier and structural load rating.
Pricing Analysis
Mobile network operators anchor tower procurement through multi-year co-location agreements that amortize site costs across tenant arrangements. Pricing stratifies across premium, standard, and economy tiers based on structural load capacity and KOSHA seismic certification grade, with Gangwon alpine installations commanding premiums for reduced-foundation monopole engineering. Cost compression in standard-tier lattice structures is intensifying because domestic steel fabricators face imported high-grade steel volatility. Private enterprise buyers exhibit highest price sensitivity as they evaluate captive private 5G networks against leased infrastructure alternatives.
Supply Chain Analysis
Gyeonggi Province steel rolling capacity underwrites the majority of lattice tower fabrication for Seoul capital region deployments. Domestic supply draws from captive Gyeonggi steel arrangements and selective Japanese engineering imports for specialized monopole components, with high-grade galvanization chemicals and corrosion-resistant alloys as critical input dependencies. Single-source vulnerability concentrates in seismic-rated foundation anchoring systems where MFDS certification limits qualified suppliers. Distribution runs through carrier-affiliated infrastructure arms and government procurement channels with divergent contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's telecom tower market sits at an inflection where 5G mid-band densification mandates from the Ministry of Science and ICT are compressing site acquisition timelines and forcing shared infrastructure architectures that reshape competitive economics.
For Market Incumbents: Secure co-location tenancy expansion across Seoul's 25 fragmented municipal jurisdictions to amortize fixed site costs before small-cell substitution erodes macro tower demand. Deepen backward integration into captive steel fabrication through Gyeonggi Province supply arrangements that insulate against imported input volatility. MFDS certification timeline extensions present a margin threat that demands parallel-track regulatory submission capabilities. For New Entrants and Emerging Players: Lead with lightweight monopole structures targeting Gangwon alpine corridors and Honam agricultural automation zones where commercial returns currently fail to justify incumbent capital deployment. Private 5G network system integration for Ulsan shipbuilding and Busan port automation clusters offers the most penetrable entry vector. A go-to-market angle anchored on solar-hybrid power system deployment under Ministry carbon reduction subsidies differentiates against legacy grid-tied offerings. For Investors and Strategic Acquirers: Spectrum reallocation proceedings from the Ministry of Science and ICT reshape the acquisition landscape by determining where tower-sharing obligations and small-cell attachment rights will revalue site portfolios. Long-term viability favors infrastructure operators with demonstrated multi-tenant co-location revenue streams and unbundled maintenance service capabilities. Target acquisition archetypes include regional specialists with established municipal permitting relationships in Seoul's aesthetic-review-intensive districts. The signal to watch is MFDS electromagnetic exposure protocol tightening that would accelerate replacement cycles for non-compliant installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Co-location Tenancy Expansion | Amortizes fixed site costs across KT Corporation, SK Telecom, and LG Uplus arrangements in Seoul districts. |
| Camouflaged Tower Variant Development | Meets Gangnam and Jongno aesthetic mandates where visual intrusion minimization determines permitting success. |
| Solar-Hybrid Power System Deployment | Captures Ministry of Science and ICT carbon reduction subsidies at off-grid Gangwon and Honam rural sites. |
| Unbundled Maintenance Service Procurement | Creates standalone revenue streams through KOSHA-mandated inspection cycles and typhoon resilience guarantees. |
| Lightweight Monopole Engineering | Reduces foundation requirements for alpine Gangwon terrain where commercial returns previously failed. |
Research Methodology
Desk research of Ministry of Science and ICT spectrum allocation filings, KOSHA workplace safety standard revisions, and MFDS equipment certification databases preceded structured interviews with RF engineering directors, tower fabrication plant managers, and municipal permitting officers across Seoul's 25 districts. Primary fieldwork with mobile network operator infrastructure procurement teams and government agency smart-city integration leads combined with secondary validation from Korea Iron and Steel Association trade data and Korea Communications Commission regulatory disclosures. Bottom-up site deployment tracking and top-down capital expenditure triangulation anchored market sizing.
Variance decomposition across product type, end user, technology, and service type segmentation dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from installed base replacement cycles, 5G densification mandate timelines, and typhoon resilience upgrade obligations. Massive MIMO miniaturization rates and active antenna system adoption curves served as technology-specific forecast inputs alongside fiber optic fronthaul integration intensity.
The analysis sits within stated boundaries; outcomes outside sustained Ministry of Science and ICT spectrum allocation support or KOSHA regulatory enforcement consistency would require recalibration. Forecasts reflect assumptions regarding steel input cost stabilization and municipal permitting timeline standardization. Revision becomes warranted when small-cell substitution penetration or MFDS certification protocol tightening crosses thresholds that materially alter macro tower demand economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
OTN Equipment Market