
 Global Spa and Salon Software Market | 2026-2036
Global Spa and Salon Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spa and Salon Software Market Outlook
The gap between enterprise-grade platforms and basic scheduling tools is realigning competitive dynamics across the sector. Zenoti dominates large spa chains with integrated payment and inventory modules. Vagaro, Inc. competes aggressively on price for independent salons. Fresha leverages a commission-based model to lower entry barriers for freelancers and mobile providers.
Spa and salon software encompasses cloud-native and on-premises applications that automate appointment scheduling, point-of-sale transactions, client relationship management, and inventory tracking through API-connected databases and real-time calendar synchronization. The primary commercial purpose is to reduce no-show rates, optimize staff utilization, and capture recurring revenue through membership workflows. Cloud-based deployment leads in new installations because salons prioritize remote access and zero hardware maintenance. Appointment scheduling captures the largest user base, though customer relationship management modules are expanding fastest as retention marketing becomes central to profitability. Subscription service models now dominate vendor revenue structures over perpetual licensing.
FDA oversight of wellness device integrations, GDPR data portability rules in Europe, and the EU AI Act's algorithmic transparency mandates are reshaping how vendors architect client data flows and consent mechanisms. Compliance with these frameworks determines market access for cross-border SaaS providers and influences procurement decisions by franchise networks operating in multiple jurisdictions. Stakeholders must evaluate whether their platform infrastructure can absorb emerging biometric data regulations as facial recognition and skin analysis tools penetrate high-end spa segments.
Market Dynamics
The cloud-native migration is compressing deployment cycles from months to days, forcing legacy on-premises vendors to rearchitect their data stacks or lose mid-market share to API-first competitors.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European wellness chains now require audit-ready data governance, accelerating replacement of non-compliant legacy systems with transparent, consent-tracked platforms.
- Mobile-first freelance operators:Independent beauty professionals across the United States, United Kingdom, and Australia are abandoning paper schedules for commission-based SaaS tools that require zero upfront capital.
- Biometric skin analysis integration:High-end medi-spas are deploying facial recognition and diagnostic imaging modules, creating demand for software architectures that can ingest and secure physiological data streams.
Market Restraints
- API interoperability gaps:Point-of-sale hardware from legacy manufacturers lacks standardized connectivity, forcing salons to maintain parallel data entry across disconnected systems.
- Concentrated payment processor dependence:North American vendors rely heavily on a narrow set of card network integrations, exposing revenue streams to sudden fee restructuring.
- Biometric data liability exposure:The EU AI Act's algorithmic transparency requirements impose documentation burdens that smaller SaaS providers lack legal resources to satisfy.
Strategic Opportunities
- Underpenetrated German and French provincial markets:Family-owned salon networks in secondary cities still operate on spreadsheets, presenting first-mover advantage for localized cloud platforms with EU-compliant data residency.
- Wellness device-software convergence:LED therapy beds, cryotherapy chambers, and body composition scanners require unified control dashboards, opening embedded software partnerships with equipment manufacturers.
- India's PLI scheme for digital infrastructure:Domestic software development subsidies are enabling cost-competitive regional platforms to serve Southeast Asian expansion without Western pricing premiums.
Industry Challenges
- Legacy system data migration complexity:Decades of client records trapped in proprietary formats resist automated porting, requiring expensive manual cleansing that erodes SaaS margin.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audits now take precedence in RFP evaluations, but smaller vendors lack dedicated compliance staff to accelerate documentation.
- Technical debt in acquired platforms:Consolidating vendors inherit monolithic codebases that fragment engineering resources across incompatible architecture patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spa and Salon Software Market |
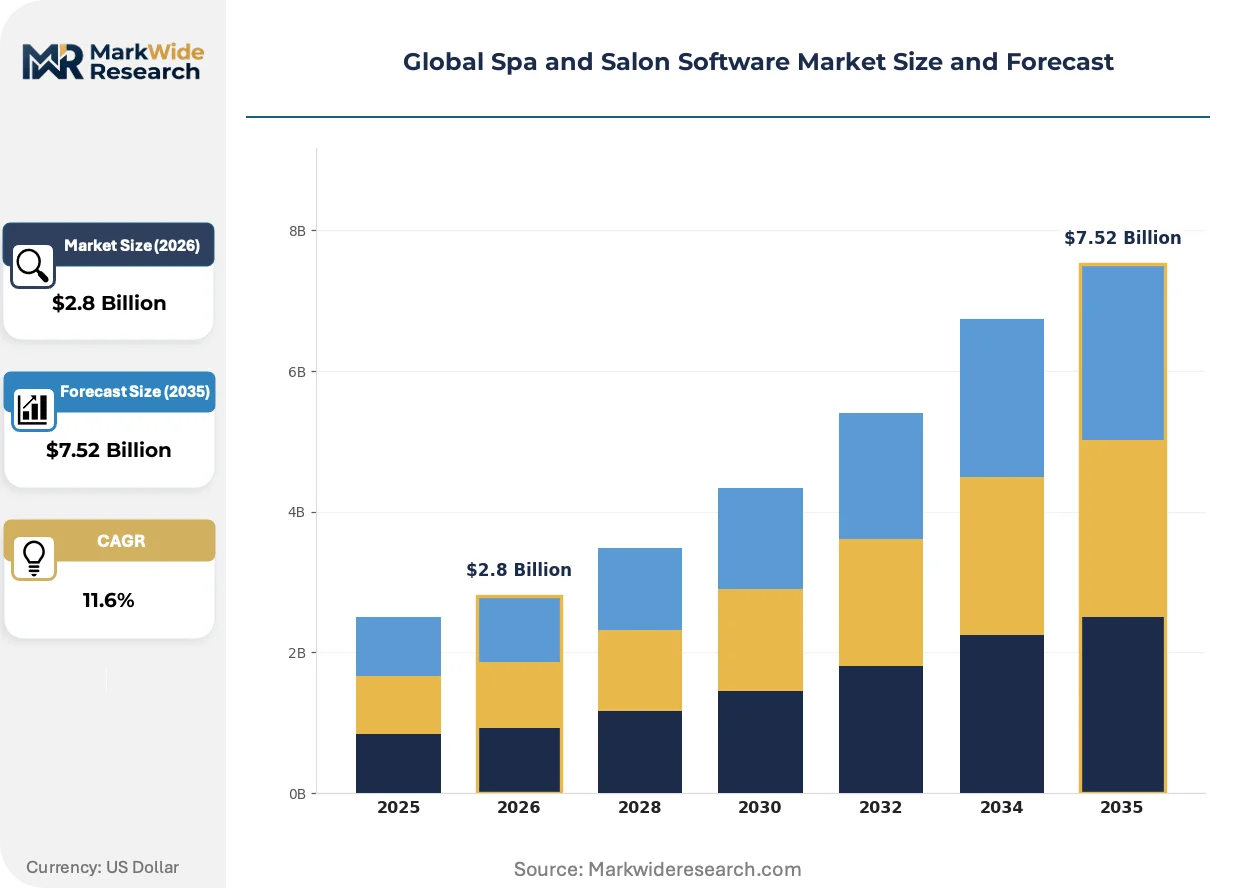
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Appointment Scheduling, Point of Sale, Customer Relationship Management, Inventory Management Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Salons, Spas, Mobile Service Providers, Freelancers Service Type: Software Licensing, Subscription, Maintenance, Training |
| Companies Covered | Mindbody, Inc., Vagaro, Inc., Zenoti, DaySmart Software, LLC, Boulevard Labs Inc., GlossGenius, Inc., Fresha, Booksy International sp. z o.o., Phorest Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spa and Salon Software Market Strategic Shifts
Artificial intelligence is embedding itself into client-facing workflows, shifting competitive advantage from feature breadth toward predictive accuracy and automated personalization.
AI-powered dynamic pricing engines are converging with real-time demand forecasting to optimize appointment yield. Premium spa chains in California and New York are piloting these systems to fill off-peak slots without discounting brand equity. The structural consequence is compressing revenue management from quarterly manual adjustments to continuous algorithmic optimization.
The EU AI Act's risk-based classification system is mandating human-in-the-loop oversight for automated appointment recommendations involving health data. Vendors serving European medi-spas must now document decision logic and maintain audit trails. High-end facial analysis modules in Swiss and Austrian wellness centers are responding by adding explicit consent checkpoints and explainable output layers.
Subscription fatigue among independent operators is driving preference for pure usage-based billing over fixed monthly fees. Freelance mobile therapists in Australian metropolitan markets are abandoning unlimited plans for per-transaction pricing that scales with irregular income patterns. This behavioral shift is most visible in Sydney and Melbourne, where platform switching cycles have compressed from annual to quarterly evaluations.
Global Spa and Salon Software Market Segmentation
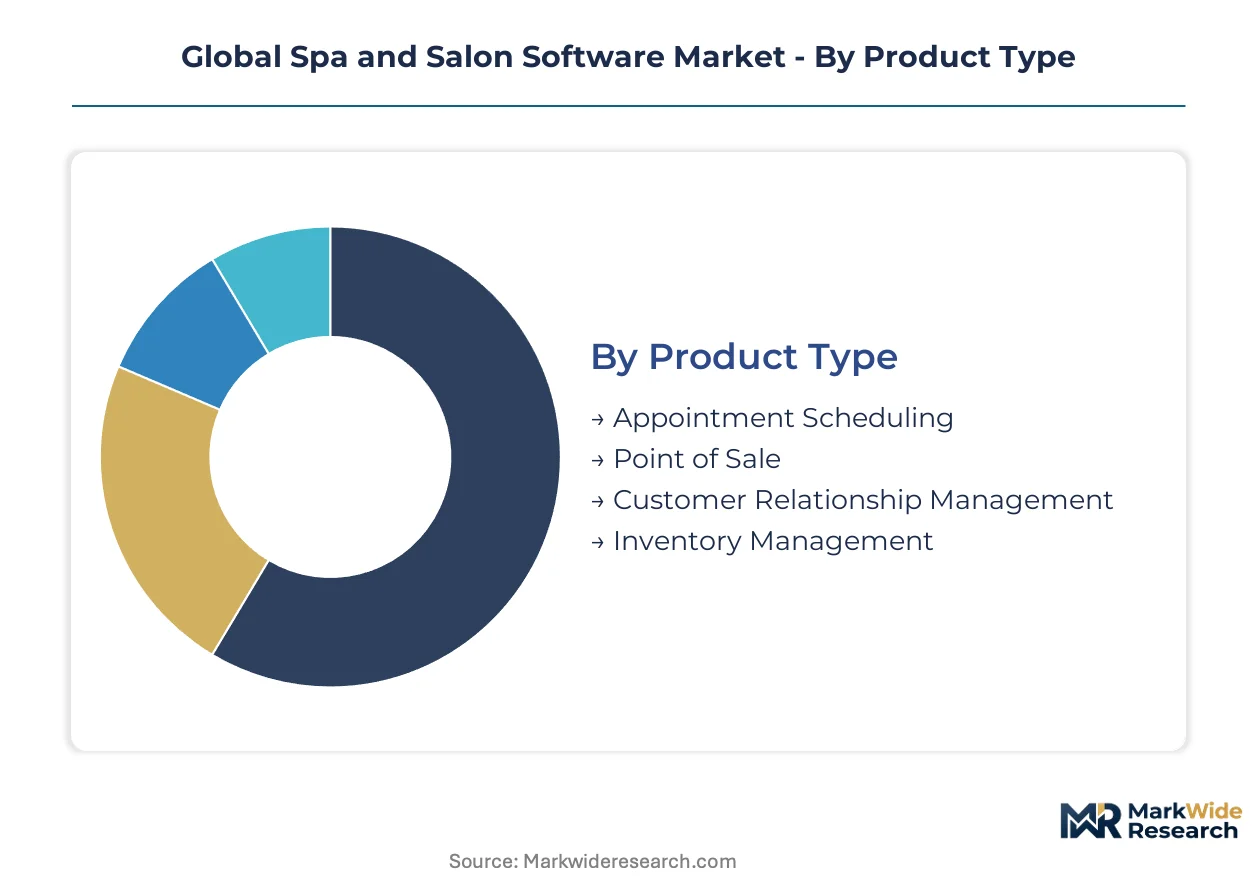
Segmentation in spa and salon software reveals how vendor specialization aligns with distinct operational workflows and compliance burdens across service categories. The market fractures along deployment preferences, product functionality, and end-user scale, each dimension carrying different margin profiles and customer lifetime value characteristics.
Product Type:
Supply concentration in appointment scheduling creates vendor lock-in effects that downstream modules struggle to displace.
- Appointment Scheduling:Core calendar synchronization engines handle multi-staff, multi-location booking with automated reminder chains. United States salon chains prioritize these systems to compress no-show rates below industry averages, though GDPR consent tracking requirements in European deployments add integration complexity.
- Customer Relationship Management:Retention marketing automation with segmented outreach and membership workflow engines. Australian mobile operators are expanding fastest here as commission-based platforms embed CRM without fixed fees, matching irregular income patterns.
- Point of Sale:Integrated payment processing with tip distribution and retail product tracking.
- Inventory Management:Real-time stock levels linked to supplier reorder points and expiration alerts.
Today's leader: Appointment Scheduling. Tomorrow's challenger: Customer Relationship Management.
Deployment:
Cost tier stratification separates zero-upfront SaaS from capital-intensive on-premises infrastructure.
- Cloud-Based:Browser-accessible platforms with API-connected databases and automatic security patching. United Kingdom independent studios dominate new installations here, driven by remote access needs and zero hardware maintenance overhead.
- Mobile:Native applications for tablet and smartphone operation with offline sync capabilities. Freelance beauty professionals across Sydney and Melbourne are abandoning desktop systems for these tools, favoring per-transaction billing that scales with appointment volume.
- On-Premises:Local server installation with full data sovereignty control.
- Hybrid:Mixed architecture with sensitive data local and scheduling functions cloud-hosted.
Cloud-Based deployment captures the dominant revenue share. Mobile deployment is climbing the fastest as workforce mobility redefines service delivery.
End User:
Customer type determines feature depth requirements and price sensitivity thresholds.
- Salons:Multi-staff operations requiring payroll integration, chair rental tracking, and retail inventory. German and French provincial family-owned networks still operate on spreadsheets, presenting first-mover opportunity for localized platforms with EU-compliant data residency.
- Spas:Wellness-focused operators with treatment room management and membership retention programs. Swiss and Austrian medi-spas are adding biometric skin analysis modules, requiring architectures that secure physiological data under EU AI Act transparency mandates.
- Mobile Service Providers:Location-independent therapists needing GPS routing and portable payment terminals.
- Freelancers:Solo operators prioritizing lowest entry barriers and flexible billing terms.
Salons generate the steadiest recurring revenue. Spas command the highest per-seat pricing as wellness device integration deepens.
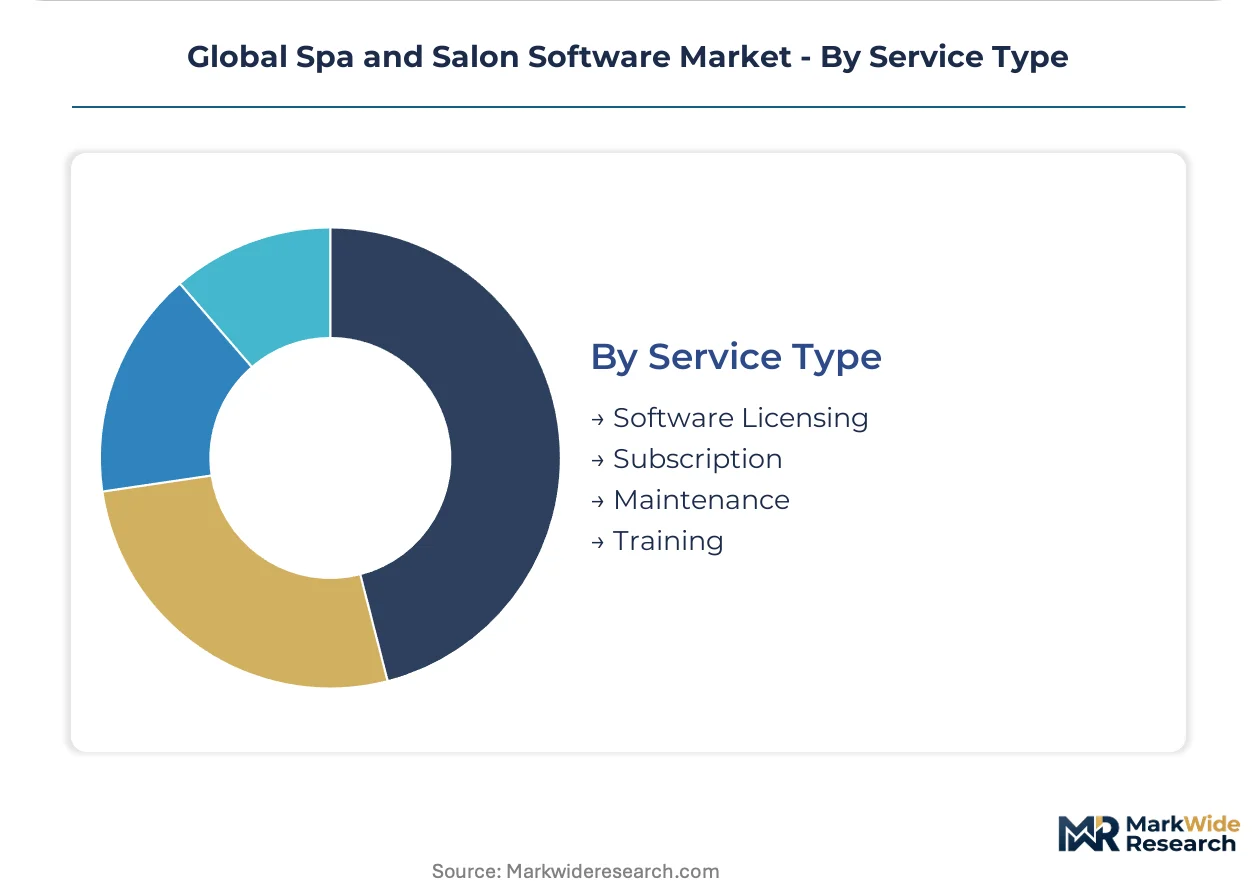
Service Type:
Margin profiles diverge sharply between one-time licensing and recurring revenue streams.
- Subscription:Monthly or annual recurring fees with tiered feature access. United States vendors have nearly completed the shift from perpetual licenses, though subscription fatigue among Australian independents is driving per-transaction alternatives.
- Software Licensing:One-time purchase with optional maintenance contracts. Legacy on-premises vendors in secondary European markets still rely on this model, though cloud-native competitors are compressing their addressable market.
- Maintenance:Technical support, security updates, and bug resolution services.
- Training:Onboarding, workflow optimization, and staff certification programs.
Subscription revenue dominates vendor financials. Software Licensing persists only in regulatory-constrained legacy environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Independent beauty professionals and salon chains cluster in metropolitan markets where digital infrastructure and regulatory frameworks create distinct adoption patterns.
United States
California and New York medi-spa chains pilot AI-powered dynamic pricing engines to optimize appointment yield. HIPAA compliance requirements shape data architecture decisions for wellness device integrations. Los Angeles and Manhattan clusters drive demand for unified payment and inventory modules.
United Kingdom
Independent studios across London and Manchester prioritize cloud-based deployment for remote access and zero hardware maintenance. GDPR consent tracking requirements add integration complexity to scheduling platforms. The Southeast England corridor concentrates commission-based platform adoption among freelance operators.
Germany
Family-owned salon networks in Bavaria and North Rhine-Westphalia still operate on spreadsheets, presenting first-mover opportunity. The EU AI Act's algorithmic transparency mandates accelerate replacement of non-compliant legacy systems. Berlin's startup ecosystem incubates localized platforms with EU-compliant data residency.
Australia
Mobile therapists in Sydney and Melbourne abandon unlimited subscription plans for per-transaction pricing that scales with irregular income patterns. Platform switching cycles have compressed from annual to quarterly evaluations. The Victoria-New South Wales corridor leads commission-based SaaS adoption among freelance beauty professionals.
India
Domestic software development subsidies under the PLI scheme enable cost-competitive regional platforms. Bengaluru and Hyderabad clusters serve Southeast Asian expansion without Western pricing premiums. Tier-1 metropolitan salons drive cloud-native migration away from paper-based scheduling.
Global Spa and Salon Software Market Competitive Environment
Top-tier vendors anchor enterprise spa chains with integrated payment and inventory modules, while mid-market specialists compete on price for independent salons. The vendor base stratifies across three tiers: enterprise-grade platforms, commission-based freelancer tools, and legacy on-premises systems. Three strategic archetypes dominate: integrated-suite providers, mobile-first commission platforms, and vertical specialists in biometric wellness devices. M&A consolidation and API-first rearchitecture represent the dominant competitive moves as legacy vendors defend mid-market share.
Within the integrated-suite tier, Zenoti and Mindbody occupy positions exemplifying enterprise-grade platform architecture. Vagaro, Inc. represents the aggressive price-competition archetype targeting independent operators. Fresha anchors the commission-based model lowering entry barriers for freelancers and mobile providers.
| Leading Market Players |
|---|
| Mindbody, Inc. |
| Vagaro, Inc. |
| Zenoti |
| DaySmart Software, LLC |
| Boulevard Labs Inc. |
| GlossGenius, Inc. |
| Fresha |
| Booksy International sp. z o.o. |
| Phorest Inc. |
| Others |
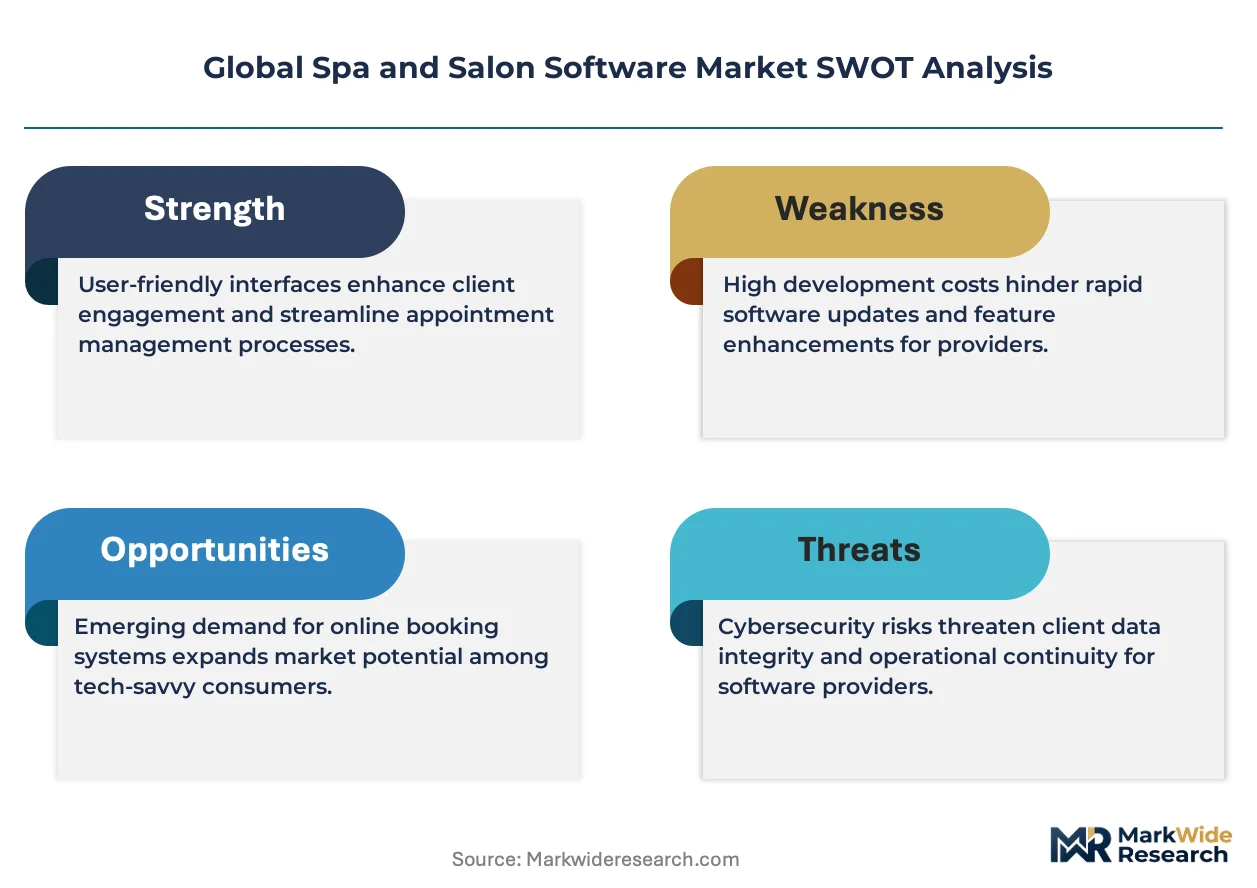
Value Chain & Pricing Dynamics
Enterprise-to-freelancer tier divergence separates bundled suite pricing from unbundled transactional models, compressing margins at the mid-market while concentrating supply chain leverage with hyperscale cloud infrastructure providers in the United States and Ireland. This bifurcation forces vendors to choose between API-first architectures that scale through payment processor networks or legacy on-premises distribution that bleeds share to zero-upstart competitors.
Pricing Analysis
Bundled-vs-unbundled service splits dominate vendor monetization strategies, with subscription tiers separating enterprise chains requiring HIPAA-compliant data residency from freelance operators preferring per-transaction commission models. Price differentiation rests on integration depth—unified payment-inventory modules command premium positioning against standalone scheduling tools. Pricing pressure stems from commission-based platforms in Australia and the United Kingdom eroding fixed-fee structures among independent operators. Freelance mobile therapists exhibit highest price sensitivity, while medi-spa chains in California and New York accept premium positioning for biometric data compliance architectures.
Supply Chain Analysis
Direct-to-salon cloud distribution channels handle hyperscale demand through browser-accessible platforms, bypassing legacy hardware intermediaries that fragment data flows. Software development concentrates in the United States, the United Kingdom, and India—Bengaluru and Hyderabad clusters leverage domestic PLI subsidies to serve Southeast Asian expansion. Raw material dependencies include AWS and Azure compute infrastructure, Stripe and Square payment APIs, and Twilio communication layers. Single-source vulnerability sits with concentrated North American card network integrations. Distribution runs through self-service onboarding portals and API documentation rather than field sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from India's PLI-enabled development cost advantages against Western pricing premiums, creating viable export platforms for Southeast Asian markets without GDPR compliance overhead.
For Market Incumbents: Hedge against API-first commission platforms by acquiring mid-market scheduling specialists in Germany and France before localized competitors establish EU AI Act-compliant data residency. Defensive consolidation should prioritize biometric data architecture investments to capture Swiss and Austrian medi-spa premium pricing, while channel control through embedded payment processing resists margin compression from pure-play scheduling entrants.
For New Entrants and Emerging Players: Capture underpenetrated family-owned salon networks in Bavaria and North Rhine-Westphalia through German-language interfaces with transparent consent-tracking workflows. White-space concentration in provincial European markets offers first-mover positioning before legacy spreadsheet operators migrate to cloud-native alternatives. Go-to-market execution should emphasize per-transaction billing that matches irregular income patterns of mobile beauty professionals.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing biometric wellness device integration capabilities and EU AI Act audit documentation. Long-term viability across the analysis window favors platforms with embedded payment processing and inventory modules that generate switching costs. Monitor platform switching cycle compression in Australian metropolitan markets as an inflection signal for subscription fatigue contagion into European independent operator segments.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rearchitecture | Compresses deployment cycles from months to days for mid-market salon chains. |
| EU AI Act Compliance Certification | Unlocks procurement decisions by German and French franchise networks requiring audit-ready data governance. |
| Biometric Data Architecture Investment | Captures premium per-seat pricing from Swiss and Austrian medi-spas deploying facial analysis modules. |
| Per-Transaction Billing Model Launch | Matches irregular income patterns of Sydney and Melbourne mobile therapists abandoning fixed subscriptions. |
| Embedded Payment Processor Integration | Reduces parallel data entry burdens from legacy POS hardware interoperability gaps. |
Study Parameters
Multiple input streams—primary interviews with spa operators and salon chain IT directors, secondary validation through SEC SaaS vendor filings and hyperscaler capex disclosures, and customs data on software service exports—were reconciled to construct market estimates. Conversations with freelance mobile therapists in Australian metropolitan markets, compliance officers at EU medi-spa chains, and platform engineers at commission-based booking providers informed adoption pattern assessments. Bottom-up triangulation across deployment model penetration rates and top-down reconciliation against aggregate cloud infrastructure spending yielded convergent market sizing.
Cross-referencing historical subscription revenue trajectories against panel input from vendor pricing disclosures anchored growth projections across the modeling period. Segmentation dimensions modeled include deployment architecture, organization scale from solo freelancer to enterprise chain, vertical specialization between beauty salons and wellness spas, integration complexity tier, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for compliance-driven replacement cycle acceleration. Forecast inputs incorporated GDPR consent tracking implementation timelines and EU AI Act documentation burden impacts on vendor operating costs.
Regulatory enforcement variance, biometric data liability litigation exposure, and payment processor fee restructuring are the dominant revision risks that could compress vendor margins or accelerate platform consolidation beyond base case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Spain Sports Management Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Construction Software As A Service Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Construction Software Market
Software & Services
Attendance Management Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Embroidery Design Software Market
Software & Services
Smartphone Applications Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Global Project Software Market
Software & Services
Fire Software Market