
 Channel Management Software Market | 2026-2036
Channel Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Channel Management Software Market Analysis
Enterprise-grade API reliability is redrawing competitive boundaries in channel management software. SiteMinder leverages its hospitality-centric integration depth to anchor positions across property management systems. RateGain competes through airline and hotel rate intelligence specialization, while ChannelAdvisor extends its control over e-commerce marketplace synchronization for retail brands.
Channel management software coordinates inventory availability, pricing, and booking workflows across disparate sales channels through centralized dashboards and real-time data feeds. Cloud-based platforms lead deployment preferences due to lower infrastructure overhead and faster onboarding cycles for distributed partner networks. SaaS offerings capture recurring revenue streams as small businesses and medium enterprises adopt subscription models over capital-intensive on-premise installations. Partner relationship management functionality within these systems concentrates margin pools where vendors bundle analytics tools for pricing optimization.
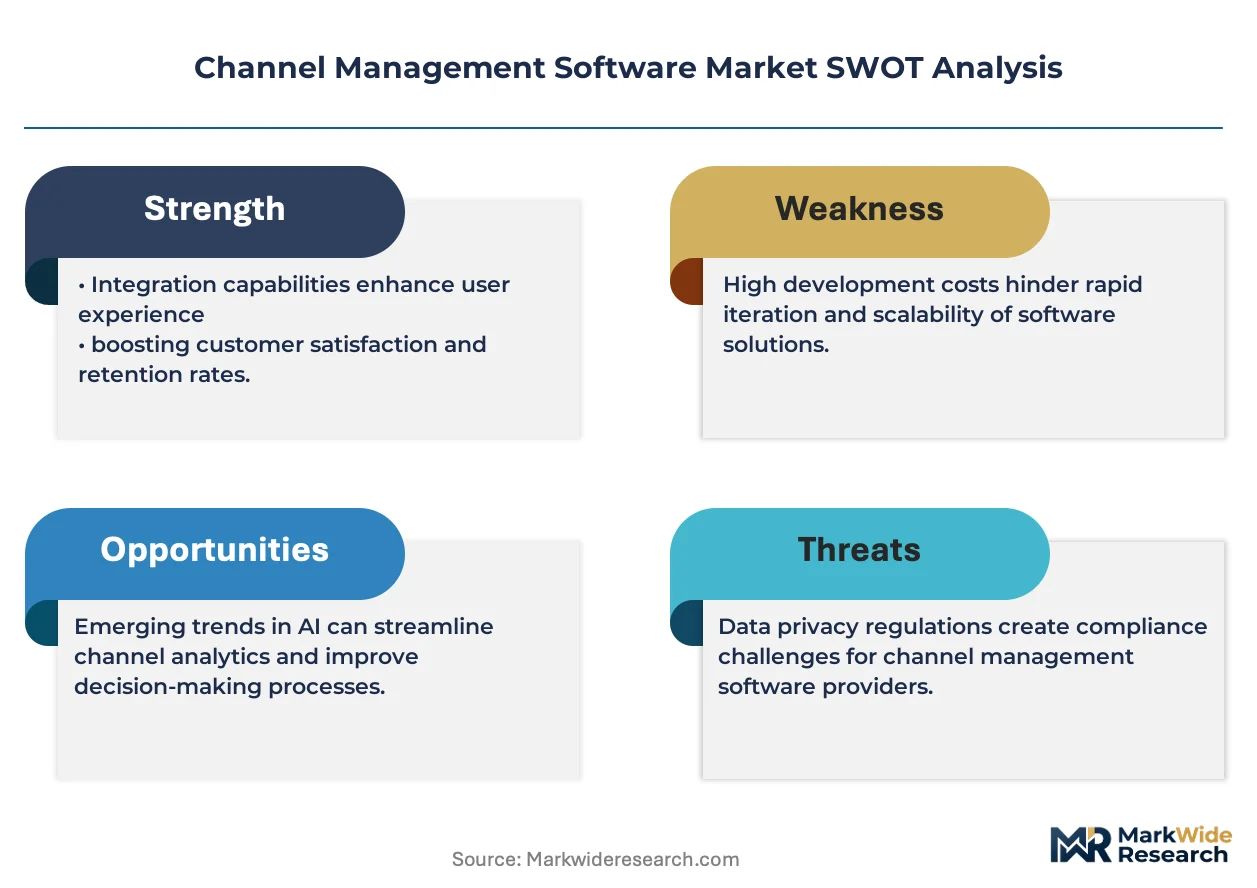
FDA oversight applies where channel software manages pharmaceutical distribution compliance, while GDPR in Europe and state-level privacy laws in the US shape data handling architectures. The EU AI Act introduces algorithmic transparency requirements for automated pricing engines embedded in optimization modules. Stakeholders must monitor evolving platform liability standards as regulators scrutinize third-party API dependencies and data breach accountability across multi-vendor channel ecosystems.
Market Dynamics
Real-time inventory synchronization requirements across fragmented distribution networks are compressing vendor consolidation timelines and forcing API architecture investments. The EU Digital Markets Act mandates data portability standards that reshape competitive moats.
Growth Catalysts
- Cloud Migration:Hospitality chains in the United States accelerate SaaS adoption to reduce infrastructure overhead and enable distributed property management without on-premise hardware investments.
- GDPR-Driven Interoperability:European hospitality operators demand API transparency to comply with data portability mandates, expanding addressable market for compliant vendors.
- Dynamic Pricing Engines:Machine learning algorithms embedded in optimization modules automate rate adjustments across airline and hotel inventory systems, capturing margin previously lost to manual processes.
Market Restraints
- API Dependency Concentration:Third-party platform outages at major online travel agencies create cascading booking failures across integrated property management systems.
- Legacy System Integration Costs:On-premise property management software in established hotel chains requires expensive middleware development for real-time synchronization.
- Subscription Fatigue:Small hospitality operators face margin pressure from accumulating SaaS fees across channel management, revenue management, and property management tools.
Strategic Opportunities
- Pharmaceutical Distribution Compliance:FDA track-and-trace requirements for drug serialization create specialized demand for channel software managing cold chain verification and lot tracking.
- AI Act Algorithmic Transparency:Automated pricing engine vendors can differentiate through explainable AI features that satisfy EU audit requirements for hospitality clients.
- Marketplace Convergence:Retail brands operating across Amazon, Walmart, and direct-to-consumer channels seek unified inventory orchestration beyond hospitality-centric incumbents.
Industry Challenges
- Technical Talent Scarcity:API architecture specialists with hospitality industry domain knowledge command premium compensation, constraining vendor development velocity.
- Multi-Vendor Liability Fragmentation:Data breach accountability disputes between channel software providers, property management systems, and booking platforms complicate cyber insurance procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Channel Management Software Market |
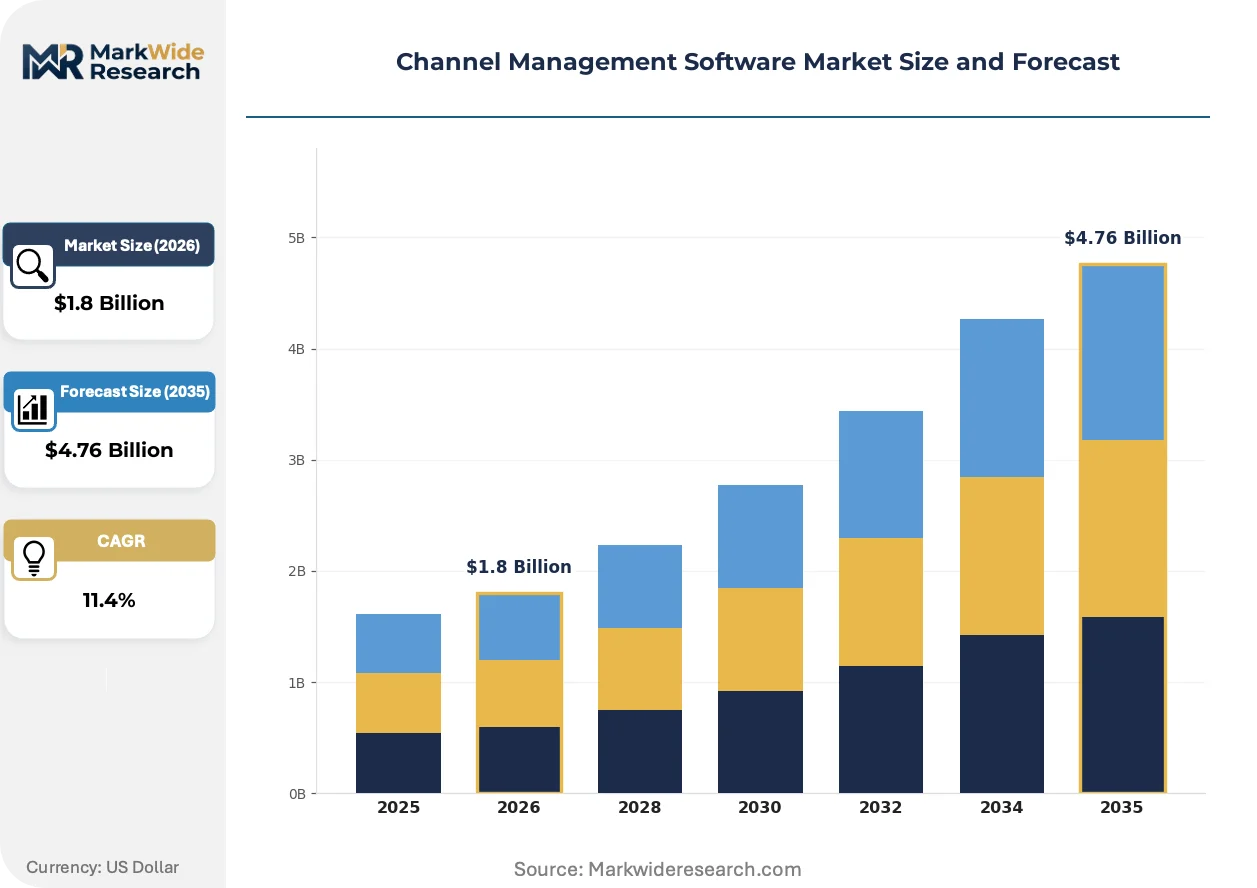
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise Solutions, Cloud-Based Platforms, Hybrid Solutions, SaaS Offerings Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Retail Chains Functionality: Inventory Management, Partner Relationship Management, Pricing Optimization, Analytics Tools Industry Vertical: Consumer Goods, Manufacturing, E-Commerce, Technology |
| Companies Covered | Yanolja Cloud, STAAH, SiteMinder, Impartner, ChannelAdvisor, roommaster, RoomRaccoon, eZee Centrix, RateGain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Channel Management Software Market Emerging Trajectories
Edge computing architectures are redistributing data processing workloads closer to property-level operations, reducing latency for availability updates while complicating vendor platform standardization efforts.
Embedded analytics modules is miniaturizing business intelligence capabilities into operational dashboards, eliminating separate BI tool procurement for mid-size hotel operators. Revenue managers at boutique hospitality chains adopt these integrated forecasting features within eighteen-month refresh cycles. The compression of vendor stacks into unified platforms is miniaturizing standalone revenue management software addressable market.
The EU AI Act mandates algorithmic transparency documentation for automated pricing systems, requiring hospitality vendors to maintain audit trails for rate adjustment logic. Industrial consequence includes expanded compliance engineering headcount and extended sales cycles for European deployments. Small independent hotels in Germany and France delay procurement until vendor certifications clarify liability boundaries.
Buyer concentration among multi-brand hospitality groups is consolidating procurement decisions into centralized technology committees, displacing property-level software selection autonomy. Franchise operators at major chains face mandated vendor approvals that limit channel management flexibility. This pattern is most visible across Marriott and Hilton property networks in the United States, where brand standards override local optimization preferences.
Channel Management Software Market Segmentation
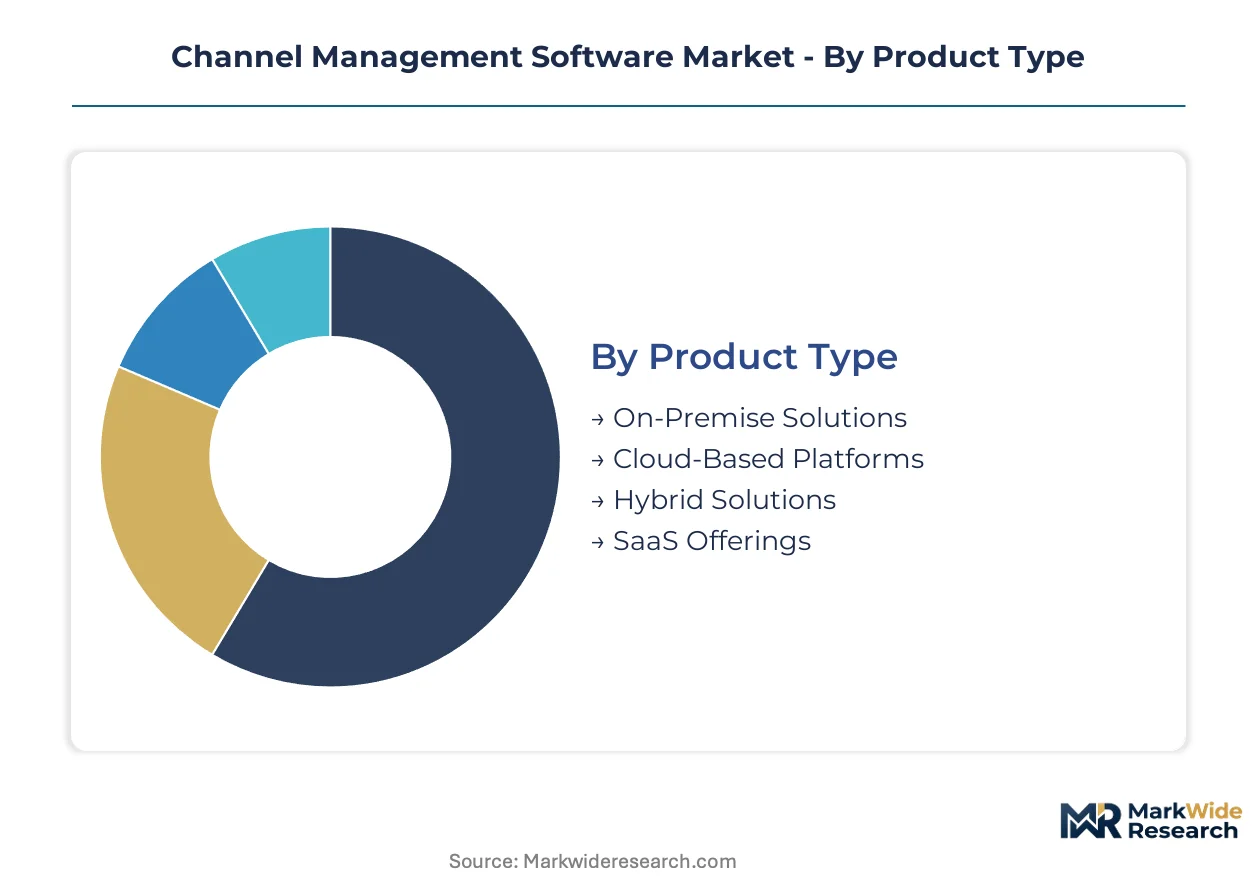
Channel management software segmentation reflects divergent compliance burdens and infrastructure investment thresholds across deployment modes and customer scales. Vendors align product architectures with specific regulatory frameworks, from FDA track-and-trace mandates in pharmaceutical distribution to GDPR data portability requirements in European hospitality operations.
Product Type:
GDPR and FDA regulations impose divergent architectural requirements on deployment models, with data residency rules and audit trail mandates shaping vendor development priorities.
- Cloud-Based Platforms:Multi-tenant architectures with automated scaling handle real-time inventory synchronization across distributed property networks. Hospitality chains in the United States favor these deployments to eliminate on-premise hardware maintenance and accelerate onboarding for franchise properties. GDPR data portability mandates in Europe drive demand for API transparency features that enable seamless data extraction.
- SaaS Offerings:Subscription pricing with tiered feature access reduces capital expenditure barriers for independent hotel operators. Small hospitality businesses in Germany and France delay procurement until EU AI Act certifications clarify algorithmic audit requirements for embedded pricing engines.
- On-Premise Solutions:Established hotel chains with legacy property management systems maintain these deployments to preserve existing middleware investments and satisfy internal security protocols.
- Hybrid Solutions:Split architectures process sensitive pricing data locally while pushing availability updates to cloud-based distribution channels, addressing FDA cold chain verification requirements in pharmaceutical distribution.
Established volume favors on-premise solutions among legacy hospitality chains; emerging adoption favors cloud-based platforms as franchise operators consolidate procurement under brand-mandated standards.
Customer Type:
Procurement autonomy varies sharply across customer tiers, with centralized technology committees at multi-brand groups displacing property-level software selection.
- Large Corporations:Multi-brand hospitality groups operate centralized technology committees that mandate approved vendor lists across franchise networks. Marriott and Hilton property systems in the United States enforce brand-standard channel management tools that override local optimization preferences. Subscription consolidation across channel, revenue, and property management functions compresses vendor stacks.
- Retail Chains:Unified inventory orchestration demands span Amazon, Walmart, and direct-to-consumer channels, extending addressable market beyond hospitality-centric incumbents. Margin pressure from accumulated SaaS fees accelerates preference for bundled analytics modules.
- Medium Enterprises:Mid-size hotel operators adopt embedded forecasting features within eighteen-month refresh cycles, eliminating separate business intelligence procurement.
- Small Businesses:Independent operators face acute subscription fatigue across overlapping hospitality software categories, constraining vendor pricing power.
Revenue concentration sits with large corporations; steepest expansion trajectory belongs to retail chains as marketplace convergence demands outstrip hospitality-specialized functionality.
Functionality:
Feature bundling reshapes competitive boundaries, with integrated modules displacing standalone point solutions.
- Pricing Optimization:Machine learning algorithms automate rate adjustments across airline and hotel inventory systems, capturing margin previously lost to manual processes. EU AI Act documentation requirements for algorithmic transparency extend sales cycles in European deployments while creating differentiation opportunities for explainable AI features.
- Analytics Tools:Miniaturized business intelligence capabilities within operational dashboards eliminate separate BI tool procurement for mid-size operators. Revenue managers at boutique hospitality chains integrate forecasting features directly into channel management workflows.
- Inventory Management:Real-time availability synchronization across fragmented distribution networks compresses vendor consolidation timelines and forces API architecture investments.
- Partner Relationship Management:Bundled functionality concentrates margin pools where vendors embed pricing optimization tools for channel partner networks.
Margin capture favors pricing optimization modules; feature integration momentum favors analytics tools as procurement committees demand unified platforms.
Industry Vertical:
End-use specialization drives vendor capability development, with pharmaceutical compliance requirements diverging sharply from retail velocity demands.
- E-Commerce:Marketplace synchronization across Amazon, Walmart, and direct-to-consumer channels requires sub-second inventory updates to prevent overselling. FDA track-and-trace serialization mandates create specialized demand for channel software managing cold chain verification and lot tracking in pharmaceutical e-commerce.
- Consumer Goods:Brand manufacturers coordinate availability across wholesale distributors, retail partners, and direct channels through centralized dashboards with real-time data feeds.
- Manufacturing:Industrial distributors leverage channel management for spare parts availability across dealer networks and direct procurement portals.
- Technology:Software and hardware vendors manage license provisioning and device availability across reseller channels and direct subscription models.
Deployment velocity favors e-commerce; compliance complexity favors consumer goods as pharmaceutical distribution requirements deepen functionality specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software export flows from the United States and United Kingdom dominate cross-border channel management licensing, while Germany and Japan import specialized compliance modules for hospitality automation. Trade balances favor North American vendors supplying cloud infrastructure to European and Asia-Pacific operators.
United States
Hospitality chains headquartered in Dallas and Phoenix drive enterprise SaaS procurement for multi-property inventory synchronization. The FTC scrutinizes third-party API data sharing practices under evolving platform liability frameworks. Marriott's technology standardization across franchise networks concentrates vendor selection authority in Bethesda, Maryland.
Germany
Independent hotel operators in Bavaria and Baden-Württemberg delay procurement until EU AI Act certifications clarify algorithmic audit requirements for automated pricing engines. The national data protection authority enforces GDPR data portability mandates that reshape API transparency specifications. Berlin's hospitality technology cluster attracts compliance-focused middleware developers serving Central European markets.
United Kingdom
London-based hospitality groups consolidate channel management decisions into centralized procurement committees, displacing property-level software autonomy. The Information Commissioner's Office applies GDPR-equivalent data handling standards post-Brexit. Manchester and Edinburgh boutique hotel operators adopt embedded analytics modules within accelerated eighteen-month refresh cycles.
Japan
Tokyo and Osaka hospitality chains integrate channel management with legacy property management systems through expensive middleware development. METI guidelines on data sovereignty influence cloud deployment preferences for domestic operators. Fukuoka's emerging technology corridor attracts vendors specializing in real-time inventory synchronization for regional ryokan networks.
India
Bangalore and Hyderabad software development centers supply API architecture talent to global channel management vendors at competitive cost structures. The RBI's digital payment integration requirements shape hospitality software procurement for properties serving international guests. Mumbai's hospitality investment surge drives demand for cloud-based property management bundles among mid-size hotel operators.
Channel Management Software Market Vendor Landscape
Listed leaders compete with private specialists across deployment model breadth, with public SaaS vendors trading scale advantages against agile private firms. The vendor base arranges into three tiers: enterprise platforms serving multi-brand hospitality groups, mid-market suites for independent operators, and niche specialists in pharmaceutical distribution compliance. Competitive moves concentrate on API architecture investments and strategic partnerships with online travel agencies.
Within the hospitality-centric tier, SiteMinder and RateGain exemplify divergent specialization strategies—SiteMinder anchoring property management system integration depth while RateGain occupies rate intelligence positioning for airline and hotel inventory. STAAH represents the mid-market cloud-native archetype serving boutique operators across Asia-Pacific markets. These three firms illustrate how geographic origin and naming conventions signal strategic positioning without requiring operational specificity.
| Leading Market Players |
|---|
| Yanolja Cloud |
| STAAH |
| SiteMinder |
| Impartner |
| ChannelAdvisor |
| roommaster |
| RoomRaccoon |
| eZee Centrix |
| RateGain |
| Others |
Supply Flow & Price Mechanics
Subscription-based SaaS contracts with annual capacity reservations lock in both API access tiers and predictable cost structures for multi-property hospitality operators navigating GDPR compliance overhead in Europe and FDA serialization mandates in pharmaceutical distribution.
Pricing Analysis
Multi-brand hospitality groups anchor subscription pricing across three-tier structures separating enterprise API bundles from mid-market dashboard access and basic channel connectivity for independent operators. Price differentiation hinges on integration depth with property management systems and real-time synchronization latency guarantees. Cost compression in the mid-tier is intensifying because bundled analytics modules eliminate separate business intelligence procurement. Small independent hoteliers exhibit acute price sensitivity while enterprise procurement committees prioritize API reliability over per-seat economics.
Supply Chain Analysis
API architecture talent scarcity in Bangalore and Hyderabad underwrites competitive positioning for vendors sourcing development capacity from India's technology corridor. Software engineering labor draws from India, Poland, and Vietnam while cloud infrastructure rests on hyperscaler data centers in the United States, Ireland, and Singapore. Single-source vulnerability concentrates around third-party online travel agency platform dependencies. Distribution runs through direct enterprise sales teams for large hospitality groups and channel partners serving boutique operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as marketplace convergence demands from retail chains outstrip hospitality-specialized functionality, creating white-space for cross-vertical platform vendors.
For Market Incumbents: Compound API integration depth into property management systems to defend against cloud-native entrants offering retail marketplace synchronization. Prioritize certification engineering headcount for EU AI Act algorithmic transparency documentation to extend sales cycle advantages in European deployments. Vertical integration into embedded analytics modules captures margin pools previously lost to standalone business intelligence vendors. For New Entrants and Emerging Players: Differentiate on pharmaceutical distribution compliance specialization where FDA track-and-trace serialization creates barriers to generalist hospitality vendors. Target mid-size retail chains operating across Amazon, Walmart, and direct-to-consumer channels with unified inventory orchestration lacking from incumbent hospitality-centric platforms. Pursue partnership-led go-to-market strategies with systems integrators serving manufacturing spare parts distribution networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform vendors with cross-vertical API architecture capabilities over point-solution specialists. Acquisition target archetypes include compliance-focused middleware developers serving Central European markets and edge computing vendors redistributing data processing closer to property-level operations. Monitor procurement committee centralization at multi-brand hospitality groups as inflection indicator for vendor stack compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API Architecture Investment | Real-time inventory synchronization across fragmented distribution networks compresses vendor consolidation timelines. |
| Strategic Partnership with Online Travel Agencies | Direct platform integrations reduce third-party outage cascading risks for property management systems. |
| Acquisition of Compliance-Focused Middleware Developer | GDPR data portability mandates and FDA serialization requirements reshape competitive moats in Europe and pharmaceutical distribution. |
| Platform Integration with Revenue Management Systems | Unified dashboards eliminate separate business intelligence procurement for mid-size hotel operators. |
| Geographic Expansion into Asia-Pacific Boutique Operator Segment | Cloud-native deployment preferences among independent hotels in Australia and Southeast Asia accelerate addressable market expansion. |
Methodological Framework
A spread of perspectives from chief technology officers at hospitality chains, IT procurement officers at retail brands, API integration specialists, channel partner managers, and regulatory compliance consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings of listed SaaS vendors, hyperscaler capex disclosures, EU regulatory documentation on the Digital Markets Act and AI Act, and hospital procurement databases tracking pharmaceutical distribution software. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern anchored the analytical framework across the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating cloud migration velocity, subscription pricing tier evolution, and compliance-driven procurement delay patterns. Industry-specific inputs included API architecture talent availability indices and online travel agency platform concentration metrics.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment and stable regulatory enforcement timelines would require recalibration. Forecasts reflect assumptions on GDPR portability mandate implementation velocity and EU AI Act certification pathway clarity. Practitioners should keep alternative scenarios live as third-party platform liability standards and data breach accountability frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Poultry Farm Management Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Load Testing Software Market
Software & Services
PLM Software Market
Software & Services
Event Management Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Non-Profit Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Online Whiteboard Software Market
Software & Services
Photobooth Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Change Control Management Software Market
Software & Services
Global Sales Engagement Platform Market