
 Global Digital Rights Management Software Market | 2026-2036
Global Digital Rights Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Rights Management Software Market Foresight
Subscription-based licensing is shifting how DRM vendors monetize enterprise relationships, moving perpetual licenses toward recurring revenue models with embedded compliance modules. Microsoft leverages its Azure ecosystem to anchor cloud-native DRM deployments across enterprise verticals. Adobe differentiates through integrated content protection workflows spanning creative cloud and document services. Irdeto specializes in broadcast and streaming media encryption, competing against broader platform players with sector-specific depth.
Digital Rights Management Software encompasses cryptographic systems, access control protocols, and persistent content protection mechanisms designed to enforce usage policies across digital assets. The technology employs encryption algorithms, watermarking techniques, and license servers to govern copying, printing, forwarding, and time-bound access to protected files, audio, video, and software. Cloud-based deployment leads solution architecture as enterprises prioritize scalable, API-integrated protection without infrastructure ownership. Content watermarking represents the fastest-expanding solution segment as forensic tracing demands intensify across media and entertainment distribution chains. License management retains mature margin pools in on-premises legacy installations within government and defense sectors where air-gapped environments persist.
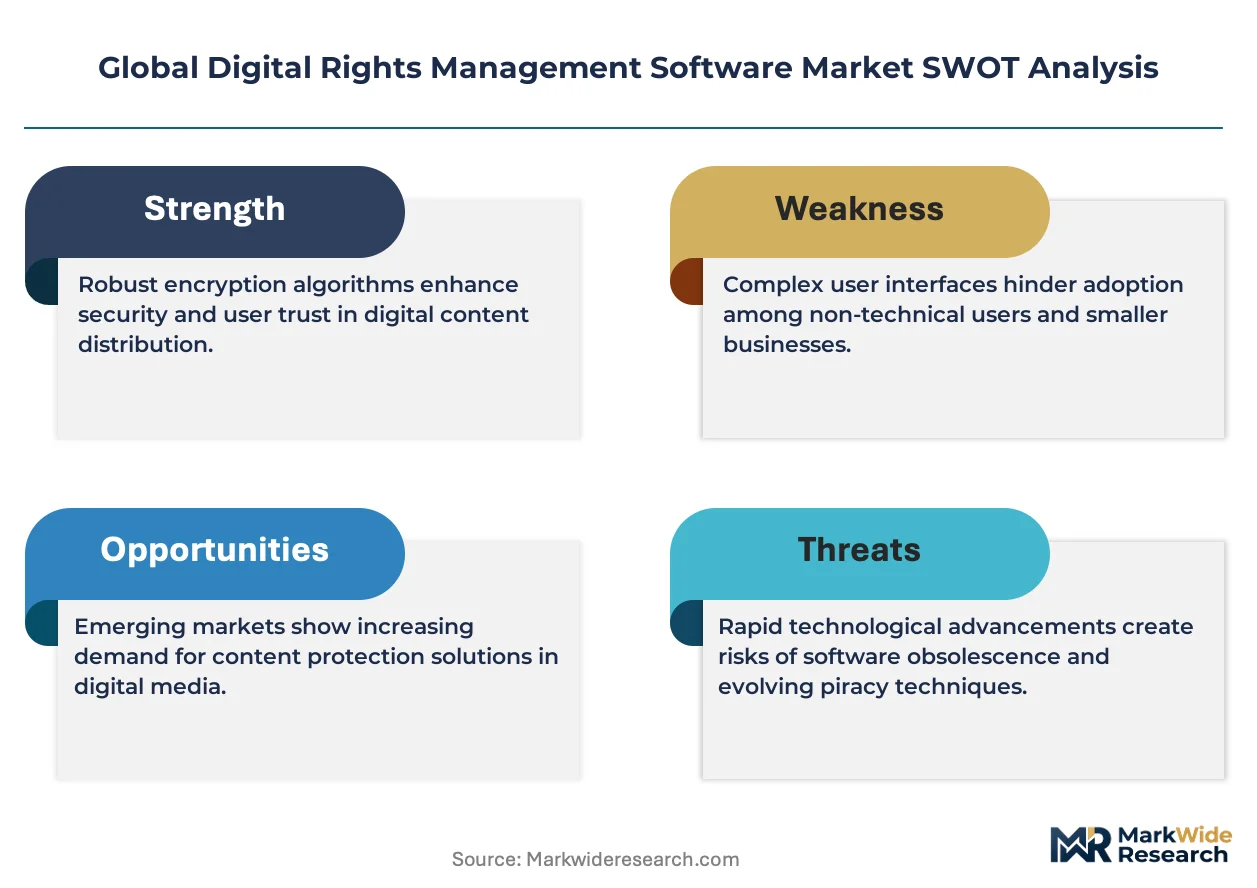
The EU AI Act and GDPR impose strict provenance and access logging requirements that DRM vendors must embed by design, while the US FCC and FTC enforce transparency in digital content licensing terms. Japan's METI guidelines on content distribution further shape product standards for Asia-Pacific market entry. Stakeholders must monitor evolving interoperability mandates between national data sovereignty frameworks and cross-border content licensing platforms.
Market Dynamics
Cloud migration across financial institutions and media enterprises is compressing deployment timelines and forcing DRM vendors to embed compliance-by-design architectures directly into subscription offerings.
Growth Catalysts
- EU AI Act provenance mandates:Automated logging requirements for AI-generated content are forcing media platforms to deploy forensic watermarking at ingestion points.
- Japan METI distribution guidelines:Content localization rules for streaming services are accelerating API-integrated DRM procurement in Tokyo and Osaka media clusters.
- Financial services cloud migration:Bank and insurance digitization of document workflows is pulling enterprise-grade license management into hybrid cloud architectures.
Market Restraints
- Legacy on-premises lock-in:Government and defense air-gapped environments in the United States and Germany resist cloud-native migration, fragmenting vendor R&D priorities.
- Cross-border data sovereignty friction:Conflicting localization requirements between GDPR, China's data security law, and US CLOUD Act create architectural complexity for multinational deployments.
- Open-source encryption alternatives:Mature cryptographic libraries reduce switching costs for price-sensitive mid-market buyers in education and nonprofit sectors.
Strategic Opportunities
- India BIS cybersecurity standards:Mandatory content protection for government digital services creates a compliance-driven procurement window for watermarking and license server vendors.
- Convergence of blockchain provenance with DRM:NFT and digital collectibles platforms require persistent ownership tracking, opening adjacent revenue streams for encryption specialists.
- Embedded insurance content protection:Underpenetrated property and casualty digitization in Brazil and Mexico presents greenfield demand for document DRM.
Industry Challenges
- Post-quantum cryptographic transition:NIST standardization timelines are compressing vendor engineering roadmaps while legacy certificate infrastructure requires parallel maintenance.
- Interoperability certification backlog:ISO 23001 and CPIX compliance testing delays are extending enterprise sales cycles beyond procurement team expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Rights Management Software Market |
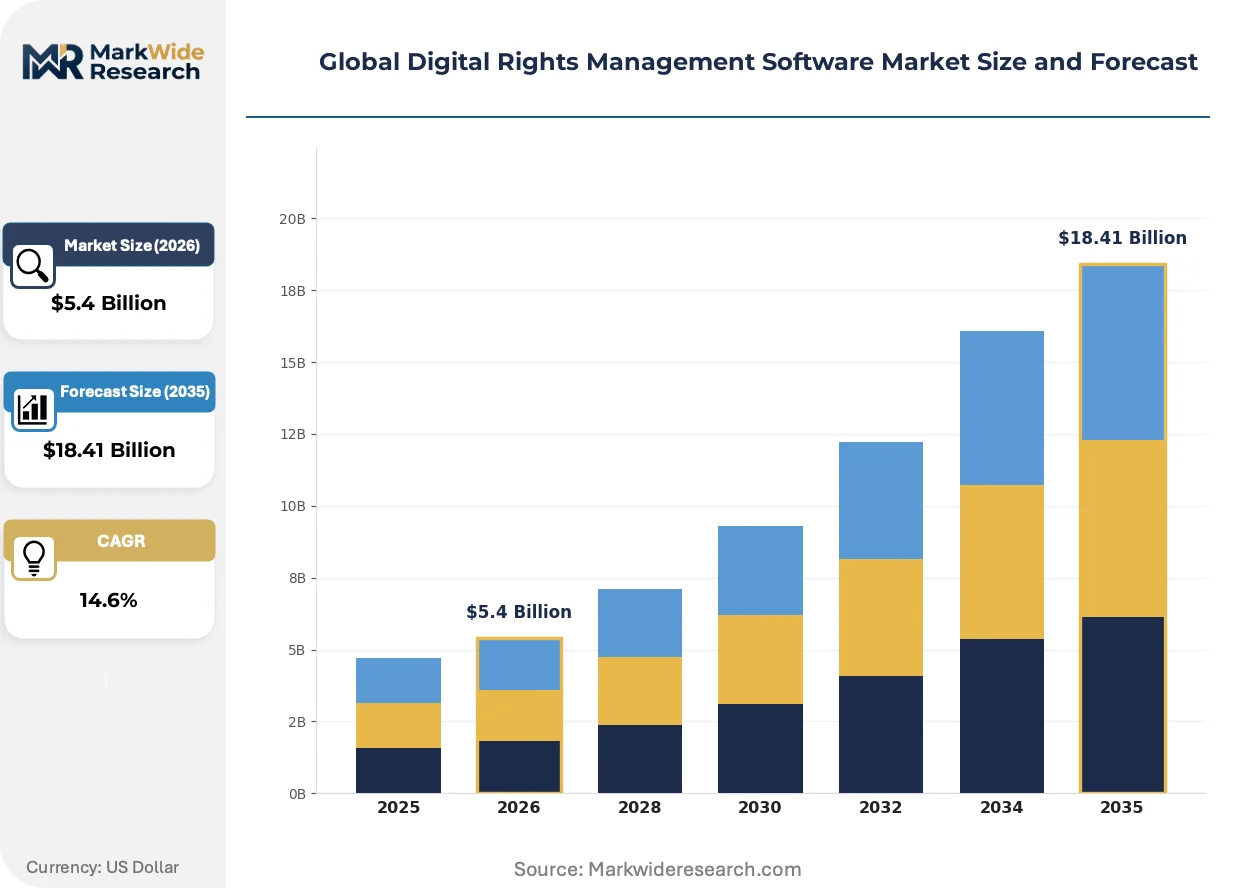
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $18.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution: Encryption, Access Control, Content Watermarking, License Management, User Authentication Application: Media & Entertainment, Education & eLearning, Government & Defense, Corporate Training, Publishing End User: IT Companies, Financial Institutions, Telecommunication Providers, Digital Publishers, Software Vendors |
| Companies Covered | Adobe, Microsoft, Google, Apple, Oracle, IBM, Irdeto, Dell, Fasoo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Rights Management Software Market Shifts & Advancements
Forensic watermarking is displacing basic encryption as the primary value layer in media distribution, while regulatory provenance requirements are hardening software architecture specifications across jurisdictions.
Client-side watermarking is expanding into browser-based streaming workflows, eliminating plugin dependencies that previously fragmented user experiences. Major broadcasters in Germany and Japan are mandating imperceptible embedding at the encoder stage, compressing vendor differentiation around detection speed rather than embedding robustness. This technology is expanding into live sports and news segments where latency constraints previously excluded forensic tracing.
The EU AI Act's transparency obligations are forcing DRM vendors to integrate automated provenance logging for synthetic media, with France's CNIL and Germany's data protection authorities already issuing implementation guidance. Industrial consequence includes mandatory audit trails for training data sourcing in generative AI platforms. Media enterprises in the Netherlands and Sweden are responding by consolidating vendor relationships around platforms with pre-certified compliance modules.
Enterprise buyers are unbundling perpetual license maintenance from active subscription tiers, compressing vendor revenue recognition toward usage-based models. Channel disruption is most visible in the United States, where direct API procurement through cloud marketplaces is displacing traditional value-added reseller networks for mid-market accounts. Defense and intelligence segments remain exceptions, maintaining bespoke procurement through cleared systems integrators.
Global Digital Rights Management Software Market Segmentation
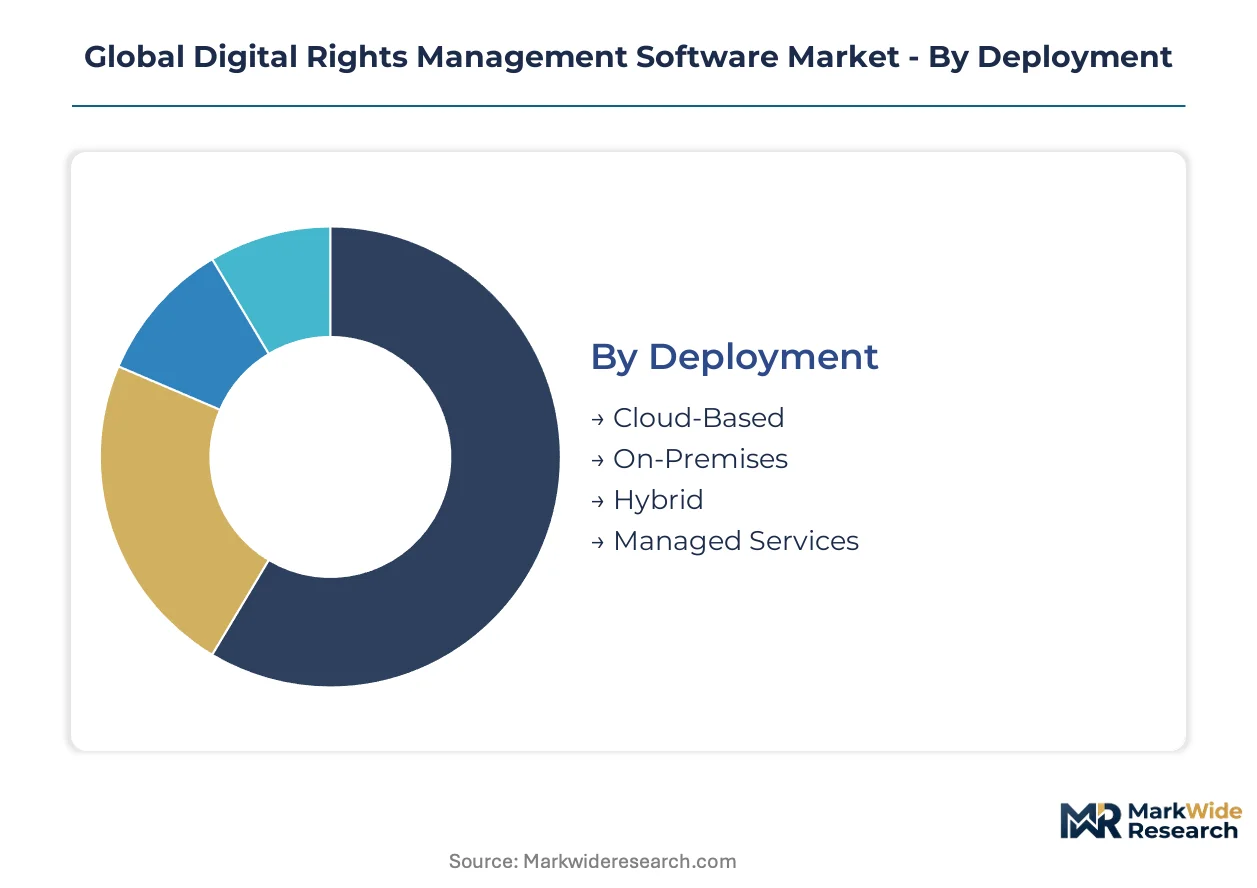
Deployment architecture determines vendor margin structure and renewal economics in DRM software. Solution type dictates integration complexity and compliance certification requirements across regulated verticals.
Deployment:
Cloud-native delivery commands premium pricing while hybrid configurations capture transitional enterprise accounts.
- Cloud-Based:API-integrated architectures enable elastic scaling for streaming platforms and financial document workflows. Demand concentrates in United States media enterprises and German automotive suppliers migrating from legacy vaults.
- On-Premises:Air-gapped license servers maintain persistent demand in defense and intelligence environments requiring physical network isolation. United States federal agencies and German Bundeswehr facilities sustain this segment despite cloud migration pressure elsewhere.
- Hybrid:Split architectures partition sensitive key management on-site while pushing distribution to cloud edge nodes.
- Managed Services:Outsourced DRM operations appeal to mid-market publishers lacking dedicated security engineering teams.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution:
Forensic capabilities now differentiate pricing tiers where encryption alone once sufficed.
- Content Watermarking:Imperceptible embedding technologies trace leak sources across distribution chains. French broadcasters and Japanese streaming platforms mandate encoder-stage insertion under METI guidelines and CSAF compliance frameworks.
- License Management:Policy enforcement engines govern device binding, time restrictions, and usage counting. German automotive documentation systems and United States insurance policy platforms drive procurement volume.
- Encryption:AES-256 and post-quantum algorithm implementations form the baseline protection layer.
- Access Control:Attribute-based and role-based mechanisms filter document availability by organizational hierarchy.
- User Authentication:Multi-factor and biometric verification gates precede protected content release.
Content Watermarking climbs the fastest as regulatory provenance mandates harden. License Management retains the deepest incumbent footprint.
Application:
Media verticals prioritize forensic tracing while government buyers emphasize audit compliance.
- Media & Entertainment:Studio distribution pipelines require frame-accurate watermarking for theatrical and streaming releases. United States major studios and German public broadcasters anchor procurement with C2PA and EU AI Act compliance requirements.
- Government & Defense:Classified document vaults demand hardware security module integration and tamper-evident audit trails. United States intelligence community specifications and German VS-NfD classifications shape vendor roadmaps.
- Education & eLearning:Courseware protection focuses on preventing unauthorized redistribution of video lectures and assessment banks.
- Corporate Training:Internal knowledge repositories require persistent protection against employee exfiltration.
- Publishing:E-book and journal distributors combat piracy through device-limited license grants.
Media & Entertainment captures current spending gravity. Government & Defense offers the steepest expansion trajectory as classified cloud migration accelerates.
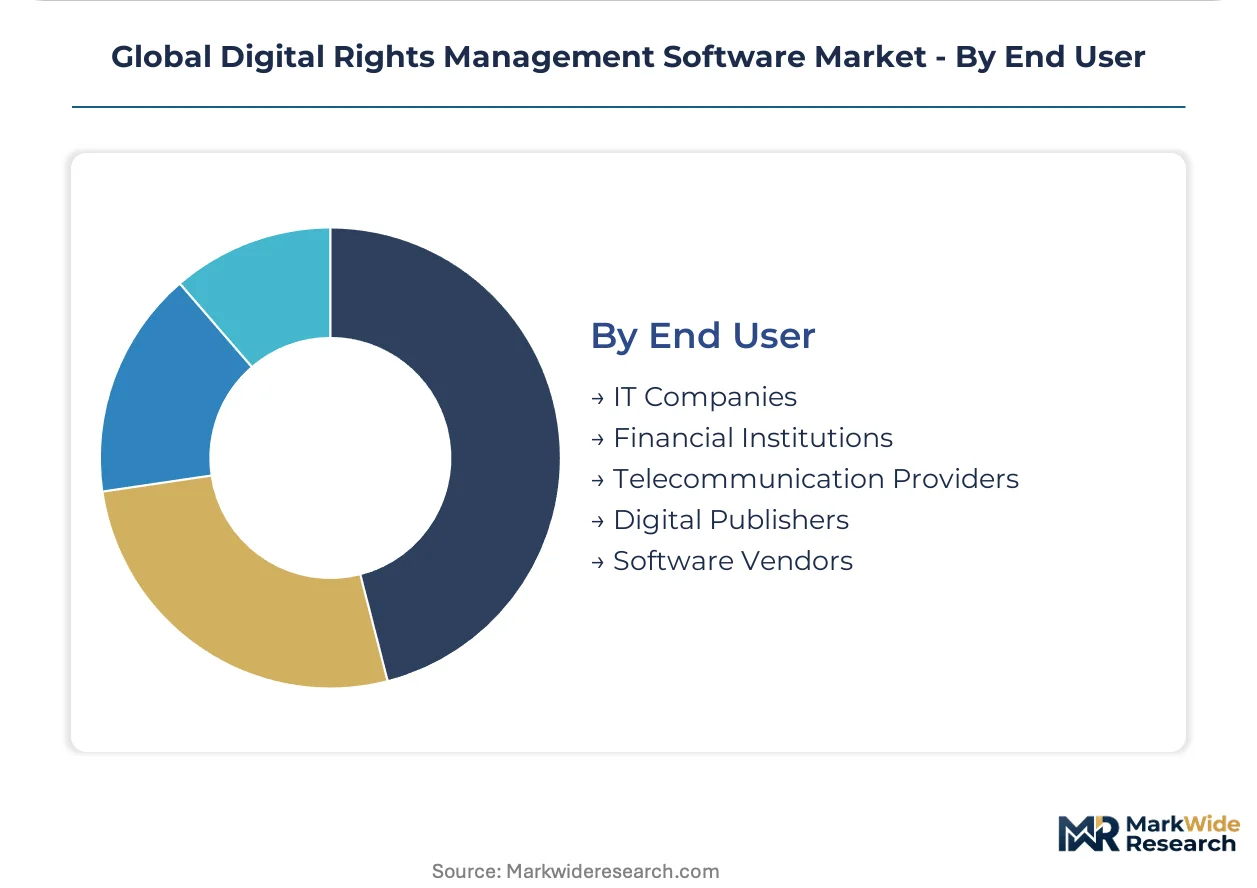
End User:
Financial services procurement is shifting from perpetual licenses toward embedded compliance subscriptions.
- Financial Institutions:Banks and insurers deploy document DRM for policy administration and regulatory reporting workflows. United States regional banks and German Sparkassen networks drive hybrid cloud adoption.
- IT Companies:Technology vendors integrate DRM APIs into SaaS platforms for customer-facing content protection.
- Telecommunication Providers:Carriers embed content protection in streaming bundles and value-added media services.
- Digital Publishers:News organizations and ebook distributors protect subscription content against credential sharing.
- Software Vendors:Application developers license code protection and trial version control mechanisms.
Financial Institutions dominate contract values today. Telecommunication Providers represent the emerging volume segment as 5G media bundles proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting procurement budgets toward jurisdictions with harmonized compliance frameworks, compressing vendor margins in fragmented enforcement environments while concentrating contract values in markets with unified data protection standards.
United States
Financial institutions in New York and Chicago are accelerating hybrid cloud DRM deployments for document workflows. The FCC and FTC enforce transparency mandates in digital content licensing that reshape vendor product specifications. Silicon Valley technology clusters and Los Angeles media enterprises anchor demand for API-integrated protection systems.
Germany
Automotive suppliers in Stuttgart and Munich are migrating from legacy vaults to cloud-native license management architectures. GDPR and the EU AI Act impose strict provenance logging requirements that vendors must embed by design. Berlin-Brandenburg hosts broadcasters mandating encoder-stage watermarking under CSAF compliance frameworks.
Japan
Streaming platforms in Tokyo and Osaka media clusters are procuring API-integrated DRM under METI distribution guidelines. The country's national content regulator shapes product standards for forensic watermarking at ingestion points. Kanto region broadcasters lead live sports deployments where latency constraints previously excluded tracing technologies.
India
Government digital services procurement is creating compliance-driven demand for watermarking and license server vendors under BIS cybersecurity standards. The central bank's data localization requirements influence hybrid deployment architectures. Bangalore and Hyderabad technology corridors concentrate SaaS platform integrations for mid-market publishers.
France
Media enterprises in Paris and Lyon are consolidating vendor relationships around platforms with pre-certified EU AI Act compliance modules. CNIL implementation guidance for synthetic media transparency obligations is compressing sales cycles. Île-de-France hosts major studios requiring frame-accurate watermarking for theatrical and streaming releases.
Global Digital Rights Management Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform ecosystems commanding premium pricing in enterprise verticals while sector-specific encryption vendors defend margin pools in broadcast and defense applications. Market structure tilts toward consolidated platform players with cloud infrastructure leverage, though specialized watermarking vendors retain defensible positions in media compliance niches. Three archetypes dominate: horizontal cloud platforms with embedded DRM modules, vertical specialists in content protection workflows, and legacy on-premises vendors serving air-gapped government environments. Competitive moves center on API marketplace distribution displacing traditional reseller networks, and compliance-by-design architectures compressing procurement timelines.
Within the horizontal platform tier, Microsoft and Adobe exemplify ecosystem-anchored strategies that bundle protection capabilities with broader cloud productivity suites. Irdeto occupies a position representing sector-specific depth in broadcast encryption, competing against broader players through forensic watermarking specialization in streaming media distribution chains. These three anchors illustrate the strategic divergence between scale-driven platform consolidation and vertical expertise defensibility.
| Leading Market Players |
|---|
| Adobe |
| Microsoft |
| Apple |
| Oracle |
| IBM |
| Irdeto |
| Dell |
| Fasoo |
| Others |
Supply & Pricing Matrix
Horizontal API marketplace integration anchors supply positioning for cloud-native DRM vendors while compressing channel margins that previously sustained value-added reseller networks. This integration choice simultaneously anchors pricing power for platform ecosystems and erodes margin pools for standalone encryption specialists competing through sector-specific depth.
Pricing Analysis
Direct-to-OEM discounts through hyperscaler marketplaces are displacing traditional distributor margins that once captured fifteen to twenty percent of contract value in mid-market accounts. Three-tier pricing structure across premium compliance-certified, standard API-integrated, and economy self-service levels separates vendor tiers by certification depth and integration complexity. Pricing pressure stems from open-source cryptographic libraries reducing switching costs for price-sensitive education and nonprofit buyers. Financial institutions demonstrate lowest price sensitivity due to embedded compliance subscription requirements, while mid-market publishers exhibit highest sensitivity as they evaluate managed service alternatives.
Supply Chain Analysis
Cryptographic engineering talent scarcity in Bangalore and Hyderabad constrains vendor capacity expansion despite surging API integration demand from SaaS platforms. Supply concentration rests on semiconductor fabrication in Taiwan and South Korea for hardware security modules, cryptographic processor IP from United Kingdom design houses, and cloud infrastructure provisioning across United States and German hyperscale regions. Single-source vulnerability in post-quantum algorithm certification creates procurement risk as NIST standardization timelines compress. Distribution runs through cloud marketplace procurement portals displacing traditional value-added reseller networks for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Rights Management Software Market operates as a stable compounder where regulatory compliance mandates across the EU AI Act, GDPR, and sector-specific frameworks generate recurring procurement cycles that sustain vendor revenue predictability.
For Market Incumbents: To counter open-source encryption alternatives eroding mid-market margins, incumbents must deepen vertical integration into hardware security module manufacturing and accelerate certification investment for EU AI Act pre-compliance modules. Channel control through exclusive cloud marketplace positioning represents the critical defensive lever against API-first challengers.
For New Entrants and Emerging Players: Begin with forensic watermarking specialization for live sports streaming where latency constraints previously excluded tracing technologies and incumbent platforms lack encoder-stage integration depth. Brazil and Mexico property and casualty insurance digitization presents the most penetrable greenfield segment for document DRM deployment.
For Investors and Strategic Acquirers: Roll-up economics work for vertical watermarking specialists because compliance certification backlogs and ISO 23001 testing delays extend enterprise sales cycles beyond independent vendor survival horizons. Target acquisition archetype includes encoder-stage forensic tracing vendors with pre-certified METI and CSAF compliance modules. Watch for NIST post-quantum standardization completion as inflection signal triggering legacy infrastructure replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-by-Design Architecture | EU AI Act provenance mandates force automated logging integration at ingestion points across media platforms. |
| API Marketplace Distribution | Direct cloud procurement through Azure and AWS marketplaces displaces traditional reseller networks in United States mid-market. |
| Forensic Watermarking Specialization | Encoder-stage imperceptible embedding at German broadcasters and Japanese streaming platforms differentiates vendor tiers. |
| Post-Quantum Cryptographic Transition | NIST algorithm standardization compresses engineering roadmaps while legacy certificate infrastructure requires parallel maintenance. |
| Hybrid Deployment Architecture | Split key management configurations capture transitional enterprise accounts migrating from on-premises vaults. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure provisioning tracking forms the analytical core of this study. Primary interviews with CISOs at financial institutions, platform engineers at streaming services, procurement officers at German automotive suppliers, and integration specialists at systems integrators combined with secondary validation against SEC filings, hyperscaler capex disclosures, and regulatory implementation guidance from France's CNIL and Germany's data protection authorities. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map deployment architecture choices to solution type procurement volumes across the projection horizon, with segmentation dimensions spanning cloud-native versus hybrid configurations, forensic watermarking versus license management solution types, and media versus government application verticals. CAGRs derive from elasticity-adjusted adoption curves incorporating EU AI Act compliance deadlines and METI guideline implementation timelines as structural forcing functions.
Several conditions sit outside the modeled scope, including geopolitical disruption to semiconductor supply chains, unilateral regulatory repudiation of cross-border data transfer mechanisms, and breakthrough advances in quantum computing rendering current encryption obsolete. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Church Management Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Global HVAC Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Global Inspection Management Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Handyman Software Market
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Global Voip Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Quality Management Software Market
Software & Services
Cricket Analysis Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market