
 Global Cloud Telecommunication AI Market | 2026-2036
Global Cloud Telecommunication AI Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Telecommunication AI Market Foresight
Graphics processing silicon is consolidating its position as the dominant compute substrate for cloud-based telecom AI workloads, displacing general-purpose CPU clusters in training and inference pipelines. Nvidia anchors this transition through its dominance in GPU-accelerated data center architectures purpose-built for telco network digital twins. Microsoft leverages its Azure for Operators platform to compete in hybrid cloud deployments spanning public and private infrastructure. IBM differentiates through its Watson AI suite integrated with Red Hat OpenShift for on-premises telecom edge environments.
Cloud Telecommunication AI encompasses machine learning models, neural network architectures, and data analytics platforms deployed via cloud infrastructure to automate, optimize, and secure telecommunications networks at scale. These systems process subscriber data, radio access network metrics, and core network telemetry through distributed cloud nodes to enable real-time decision-making with sub-50 millisecond latency requirements. Network Optimization solutions within the Solution segment lead current revenue contribution as carriers prioritize bandwidth allocation and congestion management across 5G slices. Hybrid Cloud deployments are expanding fastest among Deployment categories as operators balance data sovereignty requirements with capital expenditure constraints. Telecom Operators represent the most concentrated end-user margin pool given their direct control over network infrastructure procurement budgets.
FCC spectrum auction rules in the United States, EU AI Act risk classification requirements, and Japan's METI guidelines for AI governance in critical infrastructure collectively shape product certification pathways and cross-border data handling standards. China's MIIT cloud service licensing framework and NMPA-equivalent data security reviews further segment market access for foreign platform providers. Stakeholders must monitor evolving national AI sovereignty mandates that increasingly require in-country data residency and algorithmic auditability as prerequisites for public telecom contract eligibility.
Market Dynamics
GPU-accelerated inference pipelines are compressing latency thresholds below 10 milliseconds for real-time network orchestration, forcing carriers to rebuild cloud-native core architectures around specialized silicon rather than general-purpose compute.
Growth Catalysts
- 5G Standalone Core Rollouts:Deutsche Telekom and NTT DOCOMO are deploying AI-native network functions that automate radio resource management across massive MIMO arrays, reducing operational overhead by eliminating manual slice configuration.
- EU AI Act Compliance Mandates:Risk classification requirements for high-risk AI systems in critical infrastructure are accelerating procurement of explainable machine learning frameworks with built-in audit trails and algorithmic transparency documentation.
- Edge Computing Convergence:Distributed inference nodes at baseband hotel locations enable sub-50 millisecond decision-making for congestion control and predictive maintenance without backhauling traffic to centralized data centers.
Market Restraints
- GPU Supply Concentration:Advanced accelerator chip fabrication concentrates at TSMC facilities in Taiwan, creating single-point vulnerability for carriers scaling AI training clusters.
- Data Residency Fragmentation:China's MIIT cloud service licensing framework and data localization requirements segment market access, forcing redundant infrastructure deployment for cross-border operators.
- Interoperability Limitations:Proprietary AI model formats from hyperscale cloud providers lock carriers into specific runtime environments, complicating multi-vendor network orchestration strategies.
Strategic Opportunities
- India Telecom Modernization:TRAI's spectrum allocation reforms and Reliance Jio's aggressive 5G expansion create demand for cloud-based AI solutions that optimize TDD spectrum utilization in dense urban corridors.
- Network Digital Twin Adoption:Virtualized replica environments that simulate radio propagation and core traffic patterns enable predictive capacity planning without disrupting live subscriber services.
- Japan METI AI Governance Guidelines:Voluntary algorithmic audit standards for critical infrastructure create first-mover advantage for vendors offering certified explainable AI frameworks to KDDI and SoftBank.
Industry Challenges
- ML Operations Talent Scarcity:Carriers struggle to recruit engineers capable of deploying production-grade inference pipelines across hybrid cloud-edge environments with guaranteed latency SLAs.
- Legacy Billing Integration Complexity:AI-driven dynamic pricing for network slices requires real-time mediation with decades-old charging systems that lack API-native interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Telecommunication AI Market |
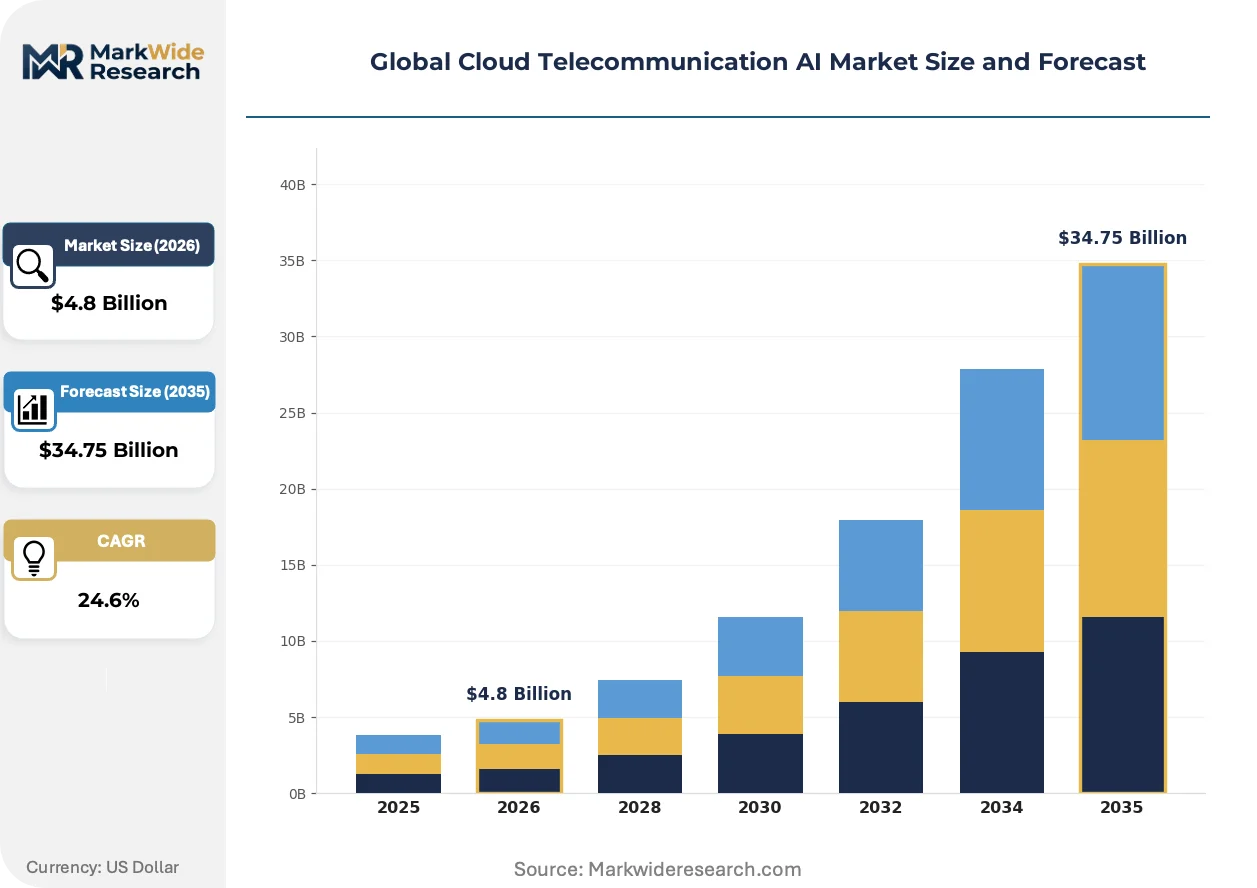
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution: Network Optimization, Predictive Maintenance, Customer Experience Management, Fraud Detection, Security Enhancement Application: Data Traffic Management, Voice Recognition, Virtual Assistants, Automated Billing, Service Quality Monitoring End User: Telecom Operators, Managed Service Providers, Internet Service Providers, System Integrators |
| Companies Covered | Amazon Web Services (AWS), Microsoft, Alphabet, IBM, Oracle, Nvidia, Salesforce, SAP SE, Tencent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Telecommunication AI Market Shifts & Advancements
Neural network architectures purpose-built for telecom workloads are displacing repurposed computer vision models, creating specialized silicon and software stacks that optimize for sparse graph structures and time-series telemetry rather than image tensors.
Containerized network functions with embedded AI accelerators are integrating directly into Kubernetes orchestration layers at distributed edge sites. Verizon and Vodafone are deploying these microservices across radio access network disaggregation layers, collapsing the traditional separation between control plane intelligence and data plane execution into unified inference pipelines.
The EU AI Act's risk classification framework is mandating human-in-the-loop oversight for automated network decisions affecting service availability. German carriers must now document algorithmic decision pathways for bandwidth allocation algorithms, creating compliance overhead that favors European vendors with pre-built audit tooling over non-EU competitors lacking GDPR-aligned data governance certifications.
Subscription-based AI model licensing is displacing perpetual software purchases as carriers seek operational expenditure alignment with revenue volatility. AT&T and BT Group now procure network optimization algorithms through usage-metered cloud contracts that scale inference capacity with traffic load, concentrating procurement leverage among hyperscale platform operators with elastic compute infrastructure.
Global Cloud Telecommunication AI Market Segmentation
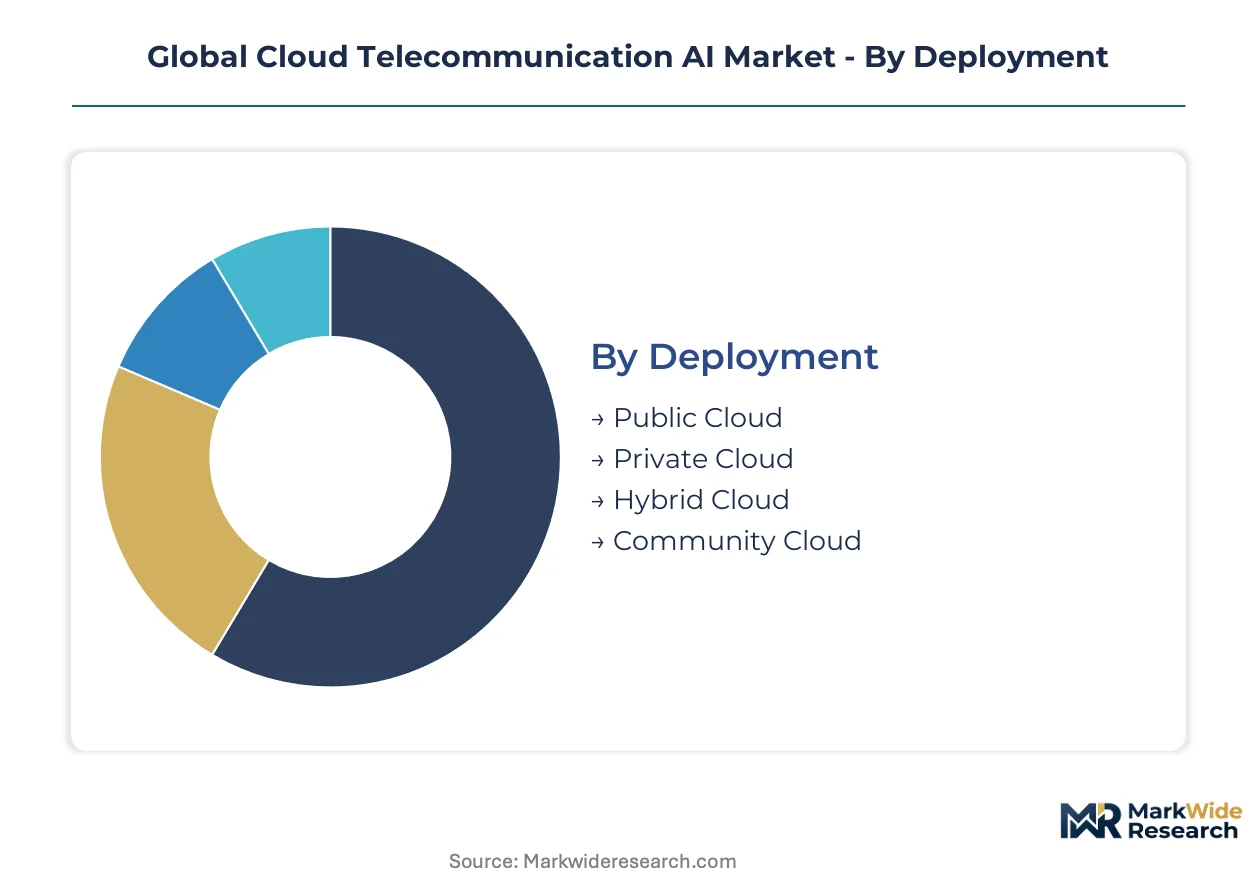
Cloud Telecommunication AI procurement decisions hinge on latency requirements, data sovereignty obligations, and existing infrastructure investments. Segmentation reveals how carriers balance operational expenditure flexibility against control over algorithmic decision-making at network edge locations.
Deployment:
Capital expenditure constraints and regulatory compliance timelines determine whether carriers lease infrastructure, build dedicated facilities, or pursue intermediate architectures.
- Public Cloud:Shared infrastructure delivers elastic compute scaling for AI training workloads without upfront silicon procurement. Deutsche Telekom and NTT DOCOMO leverage hyperscale capacity for non-sensitive network analytics where latency tolerance exceeds 100 milliseconds.
- Private Cloud:Dedicated environments host subscriber data and core network telemetry under carrier-controlled physical security. German operators prioritize this deployment to satisfy GDPR data residency mandates and EU AI Act audit trail requirements.
- Hybrid Cloud:Split architectures place training pipelines in public infrastructure while retaining inference at on-premises edge nodes. This configuration addresses the fastest-expanding use case as operators reconcile sovereignty requirements with accelerator chip scarcity.
- Community Cloud:Shared infrastructure among consortium members reduces per-carrier capital burden for regional 5G standalone core deployments. Japanese operators explore this model under METI guidance for collaborative AI governance in critical infrastructure.
Hybrid Cloud leads on scale; Hybrid Cloud leads on momentum.
Solution:
Network operational priorities dictate solution procurement sequencing, with automation of radio resource management commanding earliest deployment.
- Network Optimization:Real-time bandwidth allocation algorithms process RAN telemetry to automate congestion management across 5G network slices. This solution category anchors current revenue concentration as carriers eliminate manual configuration of massive MIMO arrays.
- Predictive Maintenance:Time-series models forecast base station component failures from power consumption signatures and thermal telemetry. Demand concentrates in Japan and Germany where MTTR reduction directly impacts regulated service availability metrics.
- Customer Experience Management:Subscriber behavior analytics identify churn risk and personalize service tier recommendations.
- Fraud Detection:Anomaly detection pipelines flag synthetic identity provisioning and subscription fraud in real-time billing systems.
- Security Enhancement:Threat intelligence models detect signaling attacks and core network intrusion patterns.
Network Optimization dominates installed base; Predictive Maintenance climbs fastest.
Application:
Functional use cases map to specific network domain expertise, with data plane automation preceding customer-facing intelligence deployment.
- Data Traffic Management:Deep learning models predict traffic spikes and preemptively reallocate spectrum resources across geographic cells. Verizon deploys these systems for video streaming optimization during stadium events and urban rush periods.
- Voice Recognition:Natural language processing enables automated call routing and network trouble ticket classification. Indian operators leverage this application to manage multilingual subscriber bases across 22 official languages.
- Virtual Assistants:Conversational AI interfaces handle subscriber plan inquiries and service provisioning requests.
- Automated Billing:Dynamic pricing engines calculate usage-based charges for network slice consumption.
- Service Quality Monitoring:Continuous probe data analysis identifies voice and video degradation before subscriber complaints.
Data Traffic Management commands largest deployment; Virtual Assistants expand most quickly.
End User:
Budget authority and infrastructure ownership determine which stakeholder categories drive procurement volume and technical specification.
- Telecom Operators:Licensed carriers with spectrum holdings directly control network infrastructure procurement and AI deployment roadmaps. This category concentrates margin capture given their ownership of subscriber relationships and regulated service obligations.
- Managed Service Providers:Outsourced network operations specialists deploy AI tooling on behalf of capital-constrained carriers. Demand is accelerating in India where Reliance Jio's aggressive expansion strains internal engineering capacity.
- Internet Service Providers:Fixed broadband providers apply cloud AI to fiber network optimization and customer premise equipment management.
- System Integrators:Professional services firms bridge legacy billing systems with AI-native orchestration layers.
Telecom Operators lead on scale; Managed Service Providers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscale cloud campuses anchor global Cloud Telecommunication AI deployment, hosting GPU training clusters for carriers spanning three continents. Regulatory fragmentation across data sovereignty regimes now dictates infrastructure placement decisions more than latency optimization alone. Capital deployment concentrates where spectrum auctions, AI governance frameworks, and edge computing mandates align.
United States
Verizon and AT&T drive demand through 5G standalone core investments requiring real-time AI orchestration. FCC spectrum auction rules mandate rapid network buildout timelines that compress procurement cycles. Dallas-Fort Worth and Northern Virginia data center clusters host the largest carrier-facing GPU deployments for network digital twin simulation.
Germany
Deutsche Telekom's massive MIMO automation projects require explainable AI frameworks with full audit documentation. EU AI Act risk classification mandates human-in-the-loop oversight for bandwidth allocation algorithms. Munich and Frankfurt edge facilities concentrate compliance-certified inference infrastructure serving Central European carrier consortiums.
Japan
NTT DOCOMO and KDDI deploy AI-native network functions across sub-6 GHz and millimeter-wave spectrum. METI guidelines for critical infrastructure AI governance establish voluntary algorithmic audit standards. Tokyo-Osaka corridor facilities host the densest concentration of containerized network functions with embedded AI accelerators.
India
Reliance Jio's aggressive 5G expansion strains internal engineering capacity and accelerates managed service provider engagement. TRAI spectrum allocation reforms enable TDD optimization in dense urban corridors. Bangalore and Hyderabad technology hubs concentrate vendor development centers for telecom-specific neural network architectures.
China
Domestic carriers build AI orchestration layers for 5G-Advanced networks under MIIT cloud service licensing requirements. Data localization mandates force redundant infrastructure deployment for cross-border operators. Shenzhen and Beijing clusters develop sovereign alternatives to foreign GPU architectures for core network telemetry processing.
Global Cloud Telecommunication AI Market Competitive Landscape
Strategic partnerships dominate the current landscape as specialized silicon vendors align with hyperscale cloud operators to capture carrier procurement budgets. The vendor base splits between GPU architecture specialists, full-stack cloud platforms, and enterprise software incumbents with telco-specific integration capabilities. Three archetypes define competitive positioning: silicon-first accelerators, platform-scale orchestrators, and vertical solution integrators. Technology licensing agreements and multi-year managed service contracts represent the primary competitive moves securing multi-vendor network environments.
Within the platform-orchestrator tier, Microsoft and Amazon Web Services occupy positions spanning public and hybrid cloud deployments for major carriers. Nvidia anchors the silicon-accelerator archetype through data center architectures purpose-built for network digital twins. IBM exemplifies the vertical-integrator position, combining Watson AI capabilities with container orchestration platforms for on-premises edge environments.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft |
| Alphabet |
| IBM |
| Oracle |
| Nvidia |
| Salesforce |
| SAP SE |
| Tencent |
| Others |
Supply & Pricing Matrix
GPU spot pricing indices from Taiwan Semiconductor Manufacturing Company wafer starts cascade through cloud infrastructure procurement, compressing margins for carriers leasing AI training capacity while amplifying pricing power for silicon-anchored platform vendors with captive foundry allocations.
Pricing Analysis
Input-cost pass-through from advanced node semiconductor fabrication concentrates pricing power among GPU architecture specialists with TSMC priority wafer commitments. Three-tier pricing structure across premium inference-optimized, standard training-grade, and economy edge-deployment levels segments carrier procurement budgets by latency requirement and data sovereignty classification. Pricing pressure stems from accelerator chip scarcity forcing longer contract terms and upfront capacity reservations. Managed service providers exhibit highest price sensitivity due to thin margin structures, while tier-one operators with sovereign cloud mandates accept premium tiers for audit-certified deployments.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry capacity for advanced AI accelerators, creating concentration risk for carriers scaling training clusters. Silicon supply draws from Taiwan, South Korea, and the United States for GPU architectures, while specialized networking optics and high-bandwidth memory components source from Japan and Germany. Tariff exposure on semiconductor fabrication equipment threatens capital expenditure timelines for European and North American edge facility buildouts. Distribution runs through hyperscale cloud platform operators who consolidate carrier demand into volume purchasing agreements with silicon vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France run substantially higher than METI-guided voluntary standards in Japan, creating margin capture opportunities for vendors with modular certification architectures.
For Market Incumbents: Deepen backward integration into specialized AI accelerator silicon through strategic foundry partnerships or captive design teams, insulating against TSMC allocation constraints. Fortify explainable AI audit tooling to defend against European challengers leveraging GDPR-aligned data governance certifications as competitive wedges. For New Entrants and Emerging Players: Managed service providers in India represent the most penetrable channel partner type, given Reliance Jio's expansion strains and TRAI spectrum reform timelines. Target hybrid cloud deployment architectures for capital-constrained carriers seeking sovereignty-compliant inference without full private cloud capital expenditure. For Investors and Strategic Acquirers: Asymmetric upside sits with containerized network function specialists possessing Kubernetes-native AI orchestration layers and existing carrier proof-of-concept deployments. Long-term viability hinges on 5G-Advanced network function virtualization adoption curves. Watch for FCC spectrum auction timing and EU AI Act enforcement precedent as inflection indicators for procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Foundry Partnership | Secures wafer allocation priority from TSMC for carrier-facing training clusters. |
| Explainable AI Certification | Accelerates EU AI Act compliance pathways for Deutsche Telekom and Vodafone procurement. |
| Edge Container Orchestration | Integrates inference microservices directly into Verizon's radio access network disaggregation layers. |
| Hybrid Cloud Platform Launch | Captures momentum from operators balancing GDPR mandates with accelerator chip scarcity. |
| Network Digital Twin Acquisition | Absorbs specialized simulation capabilities for predictive capacity planning at NTT DOCOMO. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with carrier network architects, hyperscale cloud procurement officers, AI accelerator product managers, and regulatory compliance leads. Secondary validation draws from FCC spectrum auction filings, EU AI Act implementation guidance, METI critical infrastructure advisories, and hyperscaler capital expenditure disclosures. Bottom-up carrier deployment tracking and top-down infrastructure investment flow analysis triangulate market sizing.
Rate-of-change decomposition separates 5G standalone core rollout velocity, GPU supply expansion curves, and regulatory compliance timeline shifts across the analysis window. Segmentation models capture deployment architecture, solution type, network domain application, and end-user budget authority dimensions. CAGRs derive from carrier capital expenditure commitment trajectories and silicon vendor revenue recognition patterns mapped to infrastructure deployment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation decisions, EU AI Act enforcement stringency evolution, and national AI sovereignty mandate proliferation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market