
 Global Linux Operating System Market | 2026-2036
Global Linux Operating System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linux Operating System Market Foresight
Enterprise cloud migration is collapsing traditional on-premises server procurement patterns as financial institutions and telecommunication providers reallocate capital toward elastic compute architectures. Red Hat sustains dominant positioning through its hybrid cloud platform orchestration and long-term enterprise support contracts. Canonical leverages its Ubuntu distribution to anchor cloud-native development pipelines across hyperscaler marketplaces. SUSE competes in the European regulatory environment with hardened distributions engineered for GDPR-aligned data sovereignty requirements.
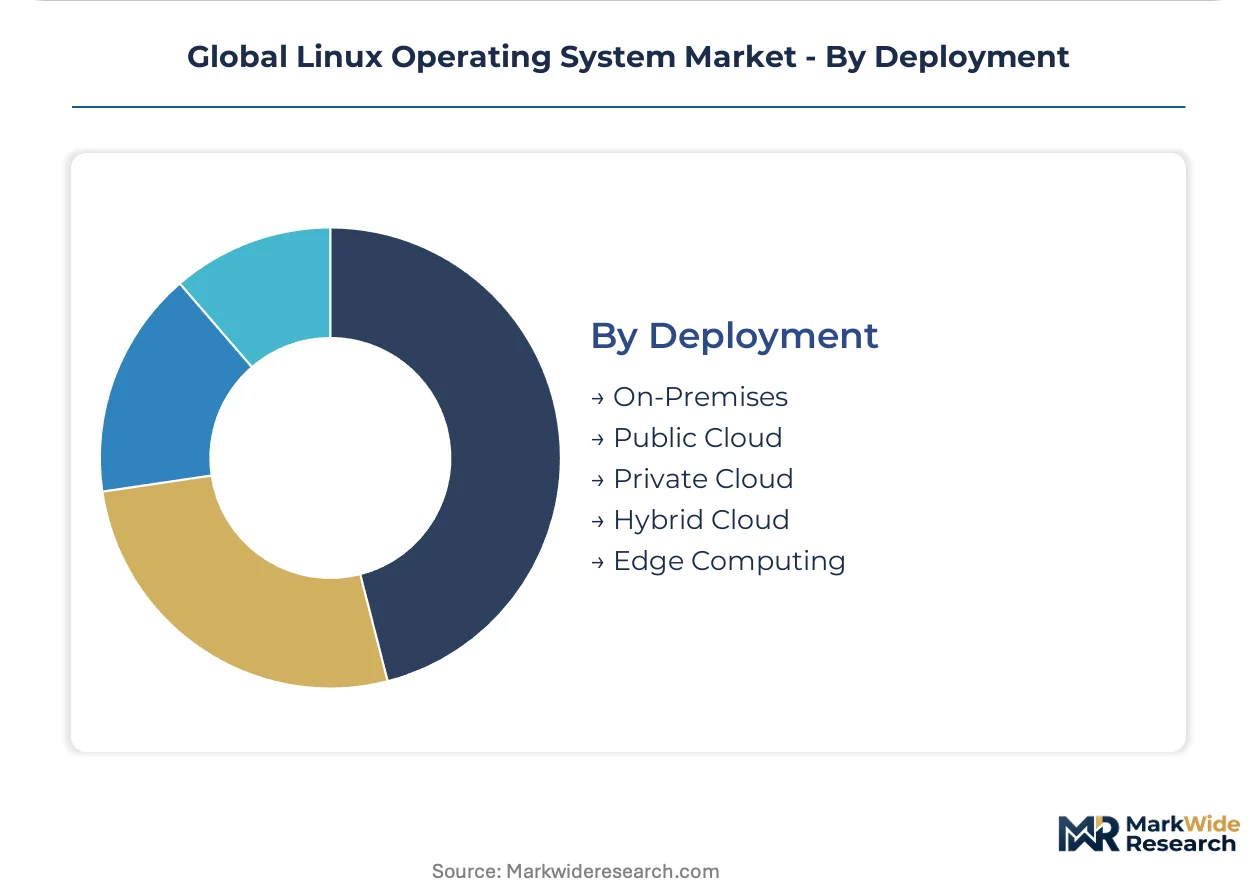
The Linux operating system comprises a monolithic or modular kernel architecture distributed under open-source licensing frameworks, supporting multiuser multitasking with POSIX-compliant system calls and extensible file systems such as ext4, XFS, or Btrfs. Its primary commercial purpose centers on providing license-free infrastructure software for servers, embedded controllers, and high-performance computing clusters where total cost of ownership and customization depth outweigh proprietary alternatives. Application segmentation shows cloud servers generating the dominant revenue pool while embedded systems represent the fastest-expanding margin corridor as automotive and industrial IoT deployments multiply. Deployment segmentation reveals hybrid cloud configurations capturing accelerating enterprise preference as organizations balance latency-sensitive workloads against regulatory data residency mandates.
FDA 21 CFR Part 820 quality system requirements shape medical device manufacturers toward validated Linux distributions with traceable patch management and long-term support commitments. The EU Cybersecurity Act and GDPR jointly force infrastructure vendors to demonstrate conformity with harmonized security standards before accessing European public procurement channels. Stakeholders must monitor evolving NIS2 implementation timelines across member states and assess whether their certification portfolios satisfy sector-specific critical infrastructure designations.
Market Dynamics
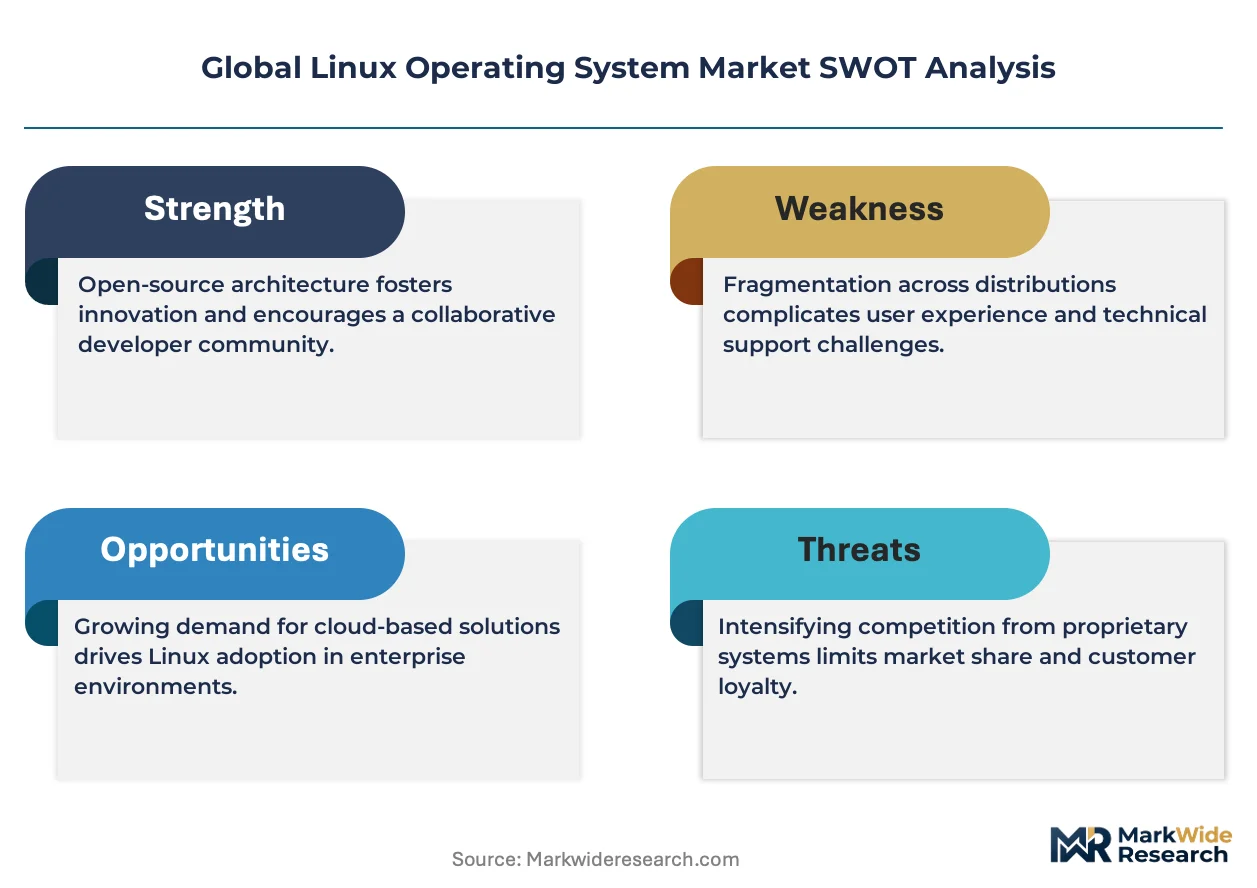
Enterprise cloud migration is collapsing traditional on-premises server procurement patterns as financial institutions and telecommunication providers reallocate capital toward elastic compute architectures. This structural shift redistributes vendor power toward hybrid cloud orchestration platforms and long-term enterprise support contracts.
Growth Catalysts
- EU Cybersecurity Act:Mandatory baseline security certifications for critical infrastructure software create compliance-driven demand for hardened distributions across European public procurement channels.
- Automotive embedded systems:Germany's automotive sector accelerates Linux adoption for in-vehicle infotainment and autonomous driving compute stacks requiring real-time kernel patches.
- Digital public infrastructure:India's stack of open-source government platforms anchors sovereign cloud deployments requiring locally maintained distributions with verifiable supply chains.
Market Restraints
- Fragmented upstream contribution:Kernel development dependencies on volunteer maintainers create unpredictable security patch timelines for long-term support commitments.
- Proprietary firmware lock-in:Hardware vendors' binary blob requirements for GPU and networking silicon limit pure open-source stack completeness in high-performance computing clusters.
- Skill scarcity:Qualified systems engineers capable of enterprise-grade kernel customization command premium compensation, elevating total cost of ownership versus managed proprietary alternatives.
Strategic Opportunities
- NIS2 Directive implementation:EU member state cybersecurity mandates open certification service markets for distributions demonstrating conformity with harmonized critical infrastructure standards.
- Edge-native convergence:Kubernetes container orchestration merged with lightweight embedded distributions enables unified management planes spanning cloud-to-device deployments.
- Brazilian digital sovereignty:Federal data localization requirements under LGPD enforcement create demand for Portuguese-localized distributions with domestic support infrastructure.
Industry Challenges
- Supply chain attestation:Reproducible build verification and SBOM generation for every kernel module strain CI/CD infrastructure and release engineering capacity.
- Legacy POSIX compatibility:Decades-old enterprise applications compiled against obsolete glibc versions resist migration to modern distribution releases without costly revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linux Operating System Market |
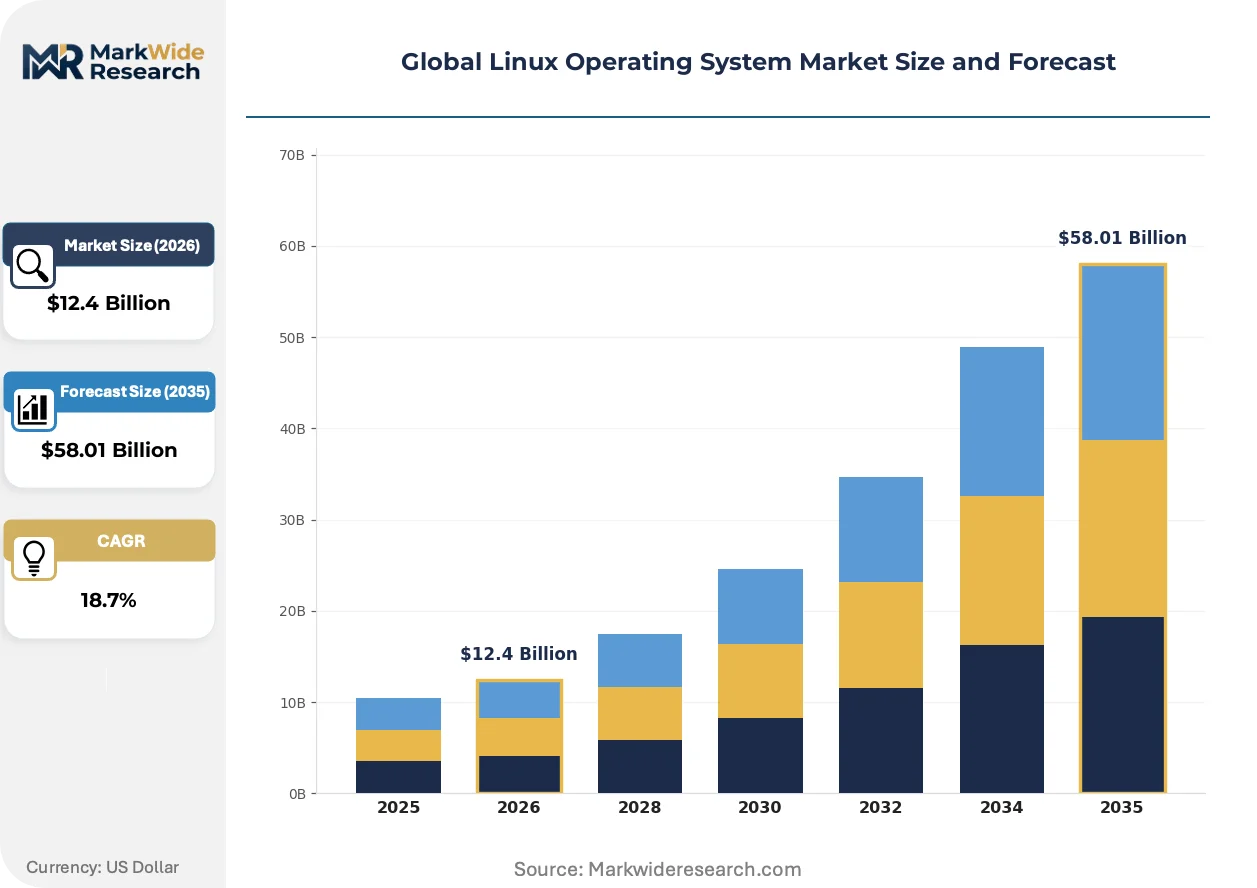
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Direct Sales, Resellers, Online Stores, System Integrators, OEM Partners Application: Cloud Servers, Embedded Systems, Desktop Computing, Networking Devices, Supercomputers End User: Telecommunication Providers, Government Agencies, Financial Institutions, Educational Establishments, E-commerce Platforms Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing |
| Companies Covered | Debian Project, Foundries.io, Canonical, BitNinja.io, Vali Cyber, Red Hat, AlmaLinux OS Foundation, Droplet Computing, SUSE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linux Operating System Market Shifts & Advancements
Immutable infrastructure patterns are reshaping how organizations consume operating system software. Deployment models now favor read-only base images with atomic updates over mutable package management, compressing patch windows and eliminating configuration drift.
eBPF kernel instrumentation is displacing traditional system call interception and userspace monitoring agents. Cloud-native observability vendors embed eBPF probes directly into hardened distribution images. Financial services firms in Singapore and London deploy these instrumented kernels for zero-overhead security telemetry without modifying application code.
The EU AI Act's risk-based classification system imposes documentation and traceability obligations on high-risk AI systems running atop Linux infrastructure. Medical device manufacturers must demonstrate that their embedded distributions preserve deterministic behavior under the Act's conformity assessment procedures. German notified bodies now require kernel configuration manifests as part of technical documentation submissions.
Subscription fatigue among mid-market enterprises is fragmenting vendor consolidation patterns. Buyers unbundle operating system licenses from hypervisor and management platform contracts, selecting best-of-breed distributions per workload tier. This behavior concentrates in India's SaaS startup ecosystem and Nordic manufacturing technology clusters where capital efficiency overrides single-vendor convenience.
Global Linux Operating System Market Segmentation
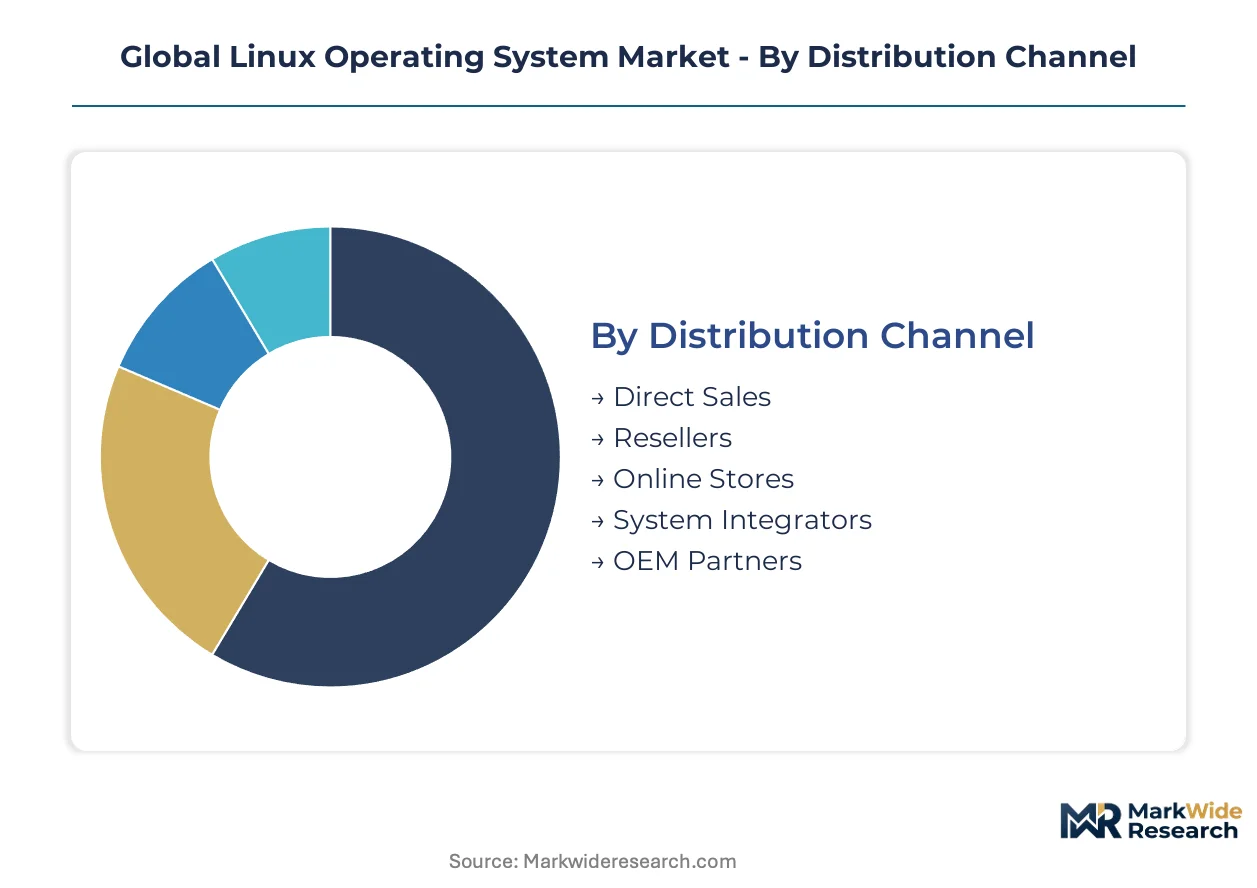
Linux adoption patterns fragment sharply across procurement channels, workload types, and infrastructure topologies. Vendors calibrate support tiers, certification depth, and pricing structures to match the operational maturity and compliance exposure of each segment cluster.
Distribution Channel:
Direct sales dominate in North American enterprise accounts with established vendor relationships, while reseller networks and system integrators carry volume across European and Asian markets where localization and compliance consulting add value.
- Direct Sales:Enterprise-grade distributions with 24/7 support SLAs and dedicated technical account managers. Financial institutions in New York and London procure through direct channels to enforce security attestation requirements under SEC and FCA oversight.
- Resellers:Value-added distributors bundling Linux subscriptions with hardware, training, and migration services. German automotive suppliers source through Munich-based resellers to satisfy KBA traceability mandates for embedded systems.
- Online Stores:Self-service procurement of developer editions and small-business subscriptions. Indian SaaS startups purchase through hyperscaler marketplaces to align with cloud-native deployment patterns.
- System Integrators:Turnkey infrastructure deployments with customized kernel configurations. Brazilian federal agencies engage domestic integrators for LGPD-compliant sovereign cloud builds.
- OEM Partners:Pre-installed distributions on server and networking hardware. Taiwanese ODMs embed hardened images for edge computing appliances shipping to North American telecommunications providers.
Direct sales holds the largest share; momentum sits with system integrators as NIS2 compliance complexity deepens.
Application:
Workload characteristics dictate kernel customization depth, from real-time patches for automotive controllers to optimized schedulers for high-frequency trading platforms.
- Cloud Servers:Container-optimized distributions with minimal footprints and rapid boot cycles. Hyperscalers in Singapore and Frankfurt deploy these images across multi-tenant infrastructure to maximize density.
- Embedded Systems:Yocto-based or custom-compiled kernels with deterministic latency guarantees. Germany's autonomous driving sector drives demand for PREEMPT_RT patches meeting ISO 26262 safety integrity levels.
- Desktop Computing:Workstation distributions with commercial graphics driver support and productivity application compatibility. Nordic design studios and Japanese animation houses standardize on these for creative pipelines.
- Networking Devices:DPDK-enabled kernels for packet processing at line rate. Telecommunication providers in South Korea and Australia deploy these in 5G core infrastructure.
- Supercomputers:HPC-optimized builds with MPI libraries and parallel file system clients. Research consortia in Switzerland and the United States run these on exascale clusters for climate and molecular modeling.
Cloud servers anchor revenue volume; embedded systems are climbing the fastest as automotive and industrial IoT deployments multiply.
End User:
Procurement sophistication varies from centralized IT governance in financial services to distributed DevOps autonomy in e-commerce platforms.
- Telecommunication Providers:Carrier-grade distributions with five-nine availability guarantees and telco-specific VNF certification. Operators in Japan and Germany negotiate multi-year enterprise agreements covering network function virtualization infrastructure.
- Government Agencies:Sovereign distributions with verifiable supply chains and domestic support infrastructure. India's digital public infrastructure stack mandates locally maintained builds for Aadhaar and UPI platforms.
- Financial Institutions:Hardened images with FIPS 140-2 validation and immutable audit logging. Singaporean banks and Swiss private wealth managers deploy these for trading infrastructure and customer data vaults.
- Educational Establishments:Campus-wide site licenses with research computing add-ons. Brazilian federal universities and German technical institutes leverage these for high-performance computing curriculum and grant-funded projects.
- E-commerce Platforms:Auto-scaling cloud-native distributions with Kubernetes integration. Indian and Southeast Asian marketplace operators prioritize these for flash sale traffic spikes and microservices architectures.
Financial institutions command premium pricing; government agencies are expanding most quickly under digital sovereignty mandates.
Deployment:
Infrastructure topology choices reflect latency sensitivity, data residency requirements, and capital allocation preferences across hybrid architectures.
- On-Premises:Traditional bare-metal and virtualized deployments with full administrative control. German manufacturers retain these for shop-floor systems where cloud connectivity introduces unacceptable operational risk.
- Public Cloud:Marketplace-optimized images with hourly billing and automatic security patching. Startups in Bangalore and São Paulo default to these for zero-capex infrastructure scaling.
- Private Cloud:OpenStack or VMware-integrated distributions with tenant isolation guarantees. Australian healthcare providers and Canadian banks deploy these for HIPAA and PIPEDA compliance.
- Hybrid Cloud:Unified management planes spanning on-premises and hyperscaler resources. British retailers and French logistics operators adopt these to balance seasonal burst capacity against legacy system integration.
- Edge Computing:Lightweight container-optimized distributions for remote and resource-constrained nodes. Oilfield operators in Norway and autonomous vehicle test fleets in California run these for millisecond-latency decisioning.
Hybrid cloud captures the largest deployment share; edge computing shows the steepest expansion trajectory as IoT sensor density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Chennai submarine cable corridor underwrites Europe-India data flow density. This infrastructure backbone channels enterprise Linux procurement toward financial services automation in Germany and digital public infrastructure scaling in India.
United States
Financial institutions in New York and cloud hyperscalers in Seattle drive enterprise distribution demand. SEC cybersecurity disclosure rules force hardened kernel configurations with immutable audit trails. Silicon Valley DevOps clusters standardize on container-optimized images for microservices deployment.
Germany
Automotive embedded systems in Stuttgart and industrial automation in Munich anchor real-time Linux adoption. KBA traceability mandates require PREEMPT_RT patches for autonomous driving compute stacks. Bavarian semiconductor fabs deploy hardened distributions for EUV lithography control systems.
India
Aadhaar identity infrastructure and UPI payment rails mandate sovereign-maintained distributions with verifiable supply chains. RBI data localization directives force domestic cloud builds with locally patched kernels. Bangalore SaaS startups consume hyperscaler marketplace images for zero-capex scaling.
United Kingdom
London financial exchanges and Edinburgh fintech clusters demand FCA-aligned security attestations. The UK National Cyber Security Centre certifies distributions for critical national infrastructure procurement. Manchester media technology firms deploy workstation distributions for creative rendering pipelines.
Singapore
Monetary Authority of Singapore operational resilience rules shape banking infrastructure software selection. Maritime logistics operators in the port cluster deploy edge-optimized distributions for container tracking automation. Regional cloud regions anchor Southeast Asian enterprise workload migration.
Global Linux Operating System Market Competitive Landscape
Concentration sits with enterprise support vendors and community-backed foundations. The vendor base splits between commercial distributors with long-term service contracts and volunteer-maintained projects with broad ecosystem adoption. Two strategic archetypes dominate: subscription-based enterprise platforms and open-source foundations monetizing through certification and support services. Competitive moves center on NIS2 compliance certification acquisition and embedded automotive distribution partnerships.
Among commercial distributors, Red Hat, Canonical, and SUSE occupy the premium-tier enterprise support vector. Red Hat exemplifies the hybrid cloud orchestration archetype through its platform integration capabilities. Canonical represents the cloud-native developer tooling position with hyperscaler marketplace penetration. SUSE anchors the European regulatory compliance specialization with hardened distribution engineering. The Debian Project and AlmaLinux OS Foundation sit within the community-governed tier, serving cost-sensitive and sovereignty-conscious deployments respectively.
| Leading Market Players |
|---|
| Debian Project |
| Foundries.io |
| Canonical |
| BitNinja.io |
| Vali Cyber |
| Red Hat |
| AlmaLinux OS Foundation |
| Droplet Computing |
| SUSE |
| Others |
Supply & Pricing Matrix
Long-term enterprise support contracts lock in multi-year revenue visibility while anchoring supply access through dedicated technical account manager allocations. Red Hat and Canonical structure these agreements with annual escalation clauses tied to certified engineer headcount, giving buyers predictable cost trajectories against volatile spot-market alternatives.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy certification levels. Premium tiers bundle FIPS 140-2 validation and NIS2 compliance documentation for financial institutions in Singapore and Frankfurt. Standard tiers target mid-market cloud-native deployments with community support fallback. Economy tiers serve Indian SaaS startups through hyperscaler marketplace hourly billing. Price differentiation hinges on certification depth and geographic proximity of support engineering. Pricing pressure stems from subscription fatigue unbundling operating system licenses from hypervisor contracts. Mid-market buyers in Nordic manufacturing clusters exhibit highest price sensitivity; German automotive OEMs demonstrate lowest due to traceability mandates.
Supply Chain Analysis
Inventory lead times for PREEMPT_RT kernel patches stretch to eighteen weeks during German automotive platform launches. Kernel development concentrates in the United States, Germany, and India with maintainers distributed across Linux Foundation working groups. Upstream dependencies draw from volunteer committer networks, hardware vendor binary blobs for GPU silicon, and Yocto Project build system toolchains. Single-source vulnerability sits with upstream LTS branch maintainers whose departure disrupts security patch timelines. Distribution runs through direct enterprise sales, Munich-based resellers for KBA compliance, and hyperscaler marketplaces for cloud-native workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Linux operating system market functions as a service-attach opportunity where long-term support subscriptions and compliance certification services expand faster than base distribution licensing. Recurring revenue from security patch management and kernel customization consulting now exceeds initial deployment fees in mature enterprise accounts.
For Market Incumbents: Fortify hybrid cloud orchestration capabilities against container-native challengers. Acquire NIS2 certification authority designations before EU member state implementation deadlines harden. Deepen upstream kernel maintainer employment to secure LTS branch influence and patch priority scheduling. For New Entrants and Emerging Players: Lead with edge-native Kubernetes distributions targeting Brazilian federal LGPD compliance and Norwegian oilfield automation. Brazilian digital sovereignty requirements under LGPD enforcement create penetrable white space lacking Portuguese-localized incumbent presence. Partner with domestic system integrators for sovereign cloud build credibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European regulatory compliance specialists with NIS2 certification pipelines. Five-to-ten year viability favors distributions with automotive embedded partnerships and real-time kernel patch capabilities. Monitor EU member state NIS2 implementation timelines as inflection signal for certification service demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| NIS2 Certification Acquisition | Unlocks European public procurement channels under harmonized critical infrastructure standards. |
| Automotive Embedded Partnership | PREEMPT_RT kernel validation for ISO 26262 autonomous driving stacks in Stuttgart. |
| Edge-Native Distribution Launch | Lightweight container-optimized builds for millisecond-latency oilfield and logistics deployments. |
| Upstream Maintainer Recruitment | Secures LTS branch influence and predictable security patch timelines for enterprise SLAs. |
| Hyperscaler Marketplace Expansion | Aligns with Indian SaaS startup zero-capex scaling patterns and cloud-native procurement. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Kernel engineering directors at Red Hat, SUSE, and Canonical provided upstream development timelines and LTS branch maintenance protocols. Enterprise procurement officers at Frankfurt financial institutions and Stuttgart automotive OEMs detailed support contract structures and compliance documentation requirements. Secondary sources included Linux Foundation contribution statistics, EU Cybersecurity Act implementation guidance, and SEC cybersecurity disclosure filings. Bottom-up segmentation modeling triangulated against top-down market sizing from hyperscaler marketplace transaction data.
Sensitivity analysis tested forecast robustness across adoption rate scenarios for NIS2 compliance deadlines and automotive embedded system deployments. Segmentation dimensions modeled include distribution channel, application workload, end-user vertical, and deployment topology across the projection horizon. CAGRs derived from fitted growth curves against historical enterprise Linux subscription expansion. Industry-specific inputs incorporated EU member state NIS2 transposition timelines and India's digital public infrastructure scaling commitments.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated automotive autonomous driving deployment would require recalibration. Forecasts reflect documented assumptions regarding kernel maintainer availability and hyperscaler marketplace penetration rates. Supply chain disruption from upstream LTS branch fragmentation or hardware vendor firmware lock-in escalation represents material revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Saas for Spa Management Market
Software & Services
Workstation Software Market
Software & Services
Winery Management Software Market
Software & Services
Credit Management Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Embroidery Design Software Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Kennel Management Software Market
Software & Services
Global Version Control Systems Market
Software & Services
Global Business Software and Service Market
Software & Services
Sports League Management Software Market
Software & Services
Packaged Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
Sales Training Software Market