
 Tail Spend Management Solutions Market | 2026-2036
Tail Spend Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Tail Spend Management Solutions Market Intelligence
Mid-market procurement teams is collapsing the traditional dominance of Fortune 500 buyers in tail spend solution adoption. Coupa Software Inc. leverages its cloud-native architecture to serve scaling enterprises with pre-configured spend taxonomies. SAP SE anchors the segment through deep ERP integration that captures transactional data across legacy procurement workflows. Jaggaer, Inc. competes by specializing in multi-ERP environments where heterogeneous technology stacks complicate spend consolidation.
Tail spend management solutions encompass software platforms and services that identify, categorize, and optimize low-value, high-frequency procurement transactions typically falling below enterprise sourcing thresholds, operating through machine learning classification engines that auto-categorize spend across thousands of supplier records into standardized taxonomies for subsequent negotiation or catalog rationalization. Cloud-based deployment leads segment adoption due to faster implementation cycles and lower total cost of ownership for mid-market buyers lacking dedicated IT infrastructure. Procurement optimization services capture expanding margin pools as organizations seek outcome-based engagement models rather than pure technology licensing. SaaS delivery models are displacing on-premise installations among large enterprises pursuing quarterly platform updates without custom upgrade projects.
The EU Green Deal and CSRD disclosure requirements in Europe, alongside the SEC climate disclosure rules in the United States, are forcing procurement organizations to trace supplier emissions through tail spend categories previously exempt from ESG scrutiny. India's PLI scheme and BIS standards for domestic manufacturing are creating compliance complexity that drives demand for localized spend analytics capabilities. Procurement leaders must evaluate whether their current tail spend platforms can ingest Scope 3 emissions data without parallel shadow systems before regulatory deadlines harden.
Market Dynamics
Machine learning classification engines are compressing implementation timelines for tail spend platforms as procurement organizations demand real-time spend visibility without multi-year ERP overhaul projects. Cloud-native architectures are dismantling the traditional IT infrastructure barrier that previously locked mid-market enterprises out of enterprise-grade sourcing analytics.
Growth Catalysts
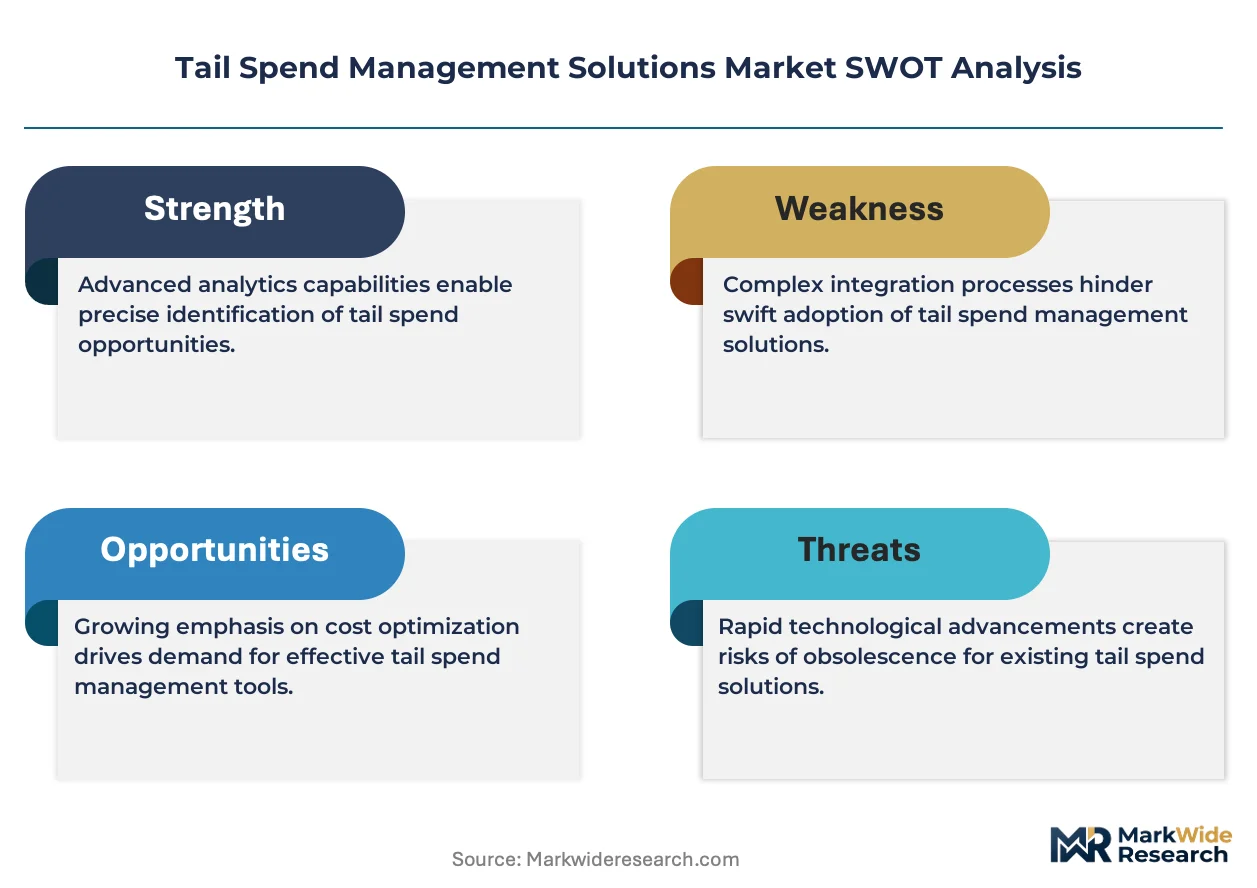
- CSRD Disclosure Mandates:The EU's Corporate Sustainability Reporting Directive forces procurement teams to capture Scope 3 emissions data across indirect supplier networks, creating mandatory demand for granular spend classification tools that can tag transactions by carbon intensity.
- Mid-market ERP Modernization:Scaling enterprises in the United States and Germany are replacing legacy procurement modules with API-first platforms that ingest transactional data from multiple source systems without custom integration projects.
- Indirect Spend Analytics:Category managers now apply sourcing discipline to previously unmanaged purchasing bands below $50,000 thresholds, using automated supplier discovery to consolidate fragmented vendor bases.
Market Restraints
- Data Fragmentation:Heterogeneous technology stacks across acquired business units prevent unified spend taxonomies, particularly in multi-ERP environments common among private equity-backed roll-ups.
- Integration Cost Structure:Custom mapping of supplier master data to standard classification schemas requires sustained professional services engagement, inflating total cost of ownership beyond initial SaaS licensing.
- Change Management Resistance:Decentralized purchasing functions in matrix organizations block platform adoption when business unit leaders retain independent vendor relationships outside corporate procurement policy.
Strategic Opportunities
- India Manufacturing Compliance:The country's PLI scheme and BIS standards for domestic production create demand for localized spend analytics that track local content requirements across fragmented supplier bases.
- Scope 3 Emissions Integration:Procurement platforms that embed carbon accounting directly into transaction workflows capture regulatory tailwinds from SEC climate disclosure rules without requiring parallel sustainability software investments.
- Supplier Marketplace Convergence:The intersection of tail spend management with B2B marketplaces is displacing traditional three-bid-and-buy processes for routine indirect purchases.
Industry Challenges
- Taxonomy Standardization Gaps:No universal classification schema exists for indirect spend categories, forcing each implementation to reconcile UNSPSC, proprietary vendor codes, and industry-specific nomenclatures.
- Legacy System Entrenchment:On-premise ERP installations with decades of customized procurement workflows resist API-based data extraction without expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tail Spend Management Solutions Market |
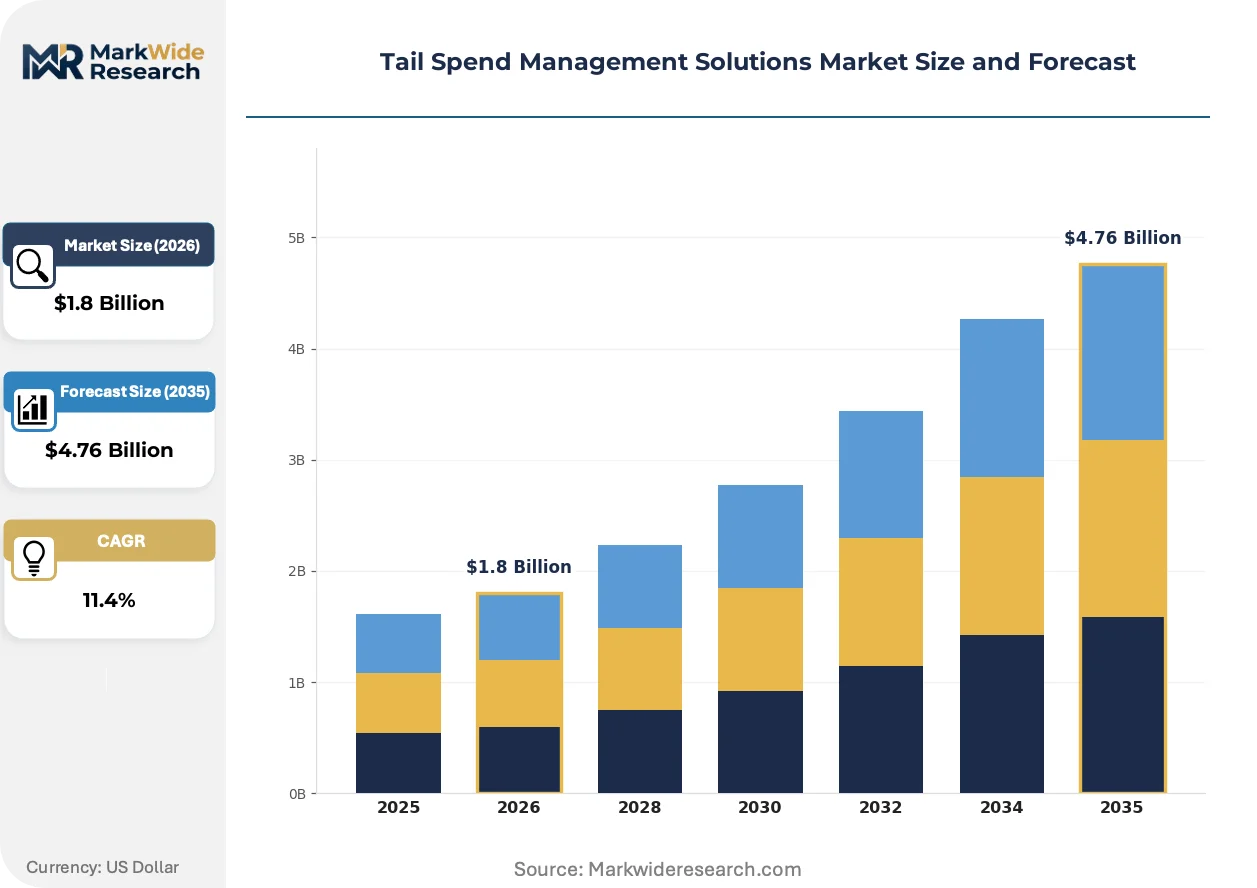
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Technology Implementation, Procurement Optimization, Spend Analysis Industry Vertical: Manufacturing, Retail, Healthcare, Education Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Customer Type: SMEs, Large Enterprises, Public Sector, Non-Profit |
| Companies Covered | Jaggaer, Inc., Ivalua, Inc., Coupa Software Inc., Order.co, Zycus Inc., SAP SE, GEP Worldwide, Inc., Proactis Group plc, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tail Spend Management Solutions Market Strategic Shifts & Innovations
Generative AI is compressing the supplier onboarding cycle from weeks to hours by auto-generating risk assessments and contract terms from unstructured source documents. Procurement technology stacks are fragmenting as point solutions challenge suite vendors for specific functional dominance.
Natural language processing engines are displacing rule-based spend classification systems that required manual maintenance of keyword libraries and supplier mapping tables. Mid-market procurement teams in the United Kingdom and Germany are adopting these tools within 90-day implementation windows. The technology is displacing legacy catalog management approaches that forced buyers into pre-negotiated supplier channels.
The EU Green Deal's supply chain due diligence requirements are mandating emissions traceability through tier-three suppliers previously invisible to corporate sustainability programs. Industrial manufacturers in Germany face compressed compliance timelines as the CSRD phases in sector-specific reporting standards. Automotive and electronics sectors are responding by embedding carbon data fields directly into procurement platform configurations.
Chief procurement officers are unbundling technology licensing from implementation services, demanding outcome-based contracts tied to realized savings rather than seat-based SaaS fees. This model disrupts traditional systems integrators who previously captured margin through time-and-materials deployment work. The shift is most visible in United States healthcare and financial services verticals where procurement leadership reports directly to CFOs with explicit cost reduction mandates.
Tail Spend Management Solutions Market Segmentation
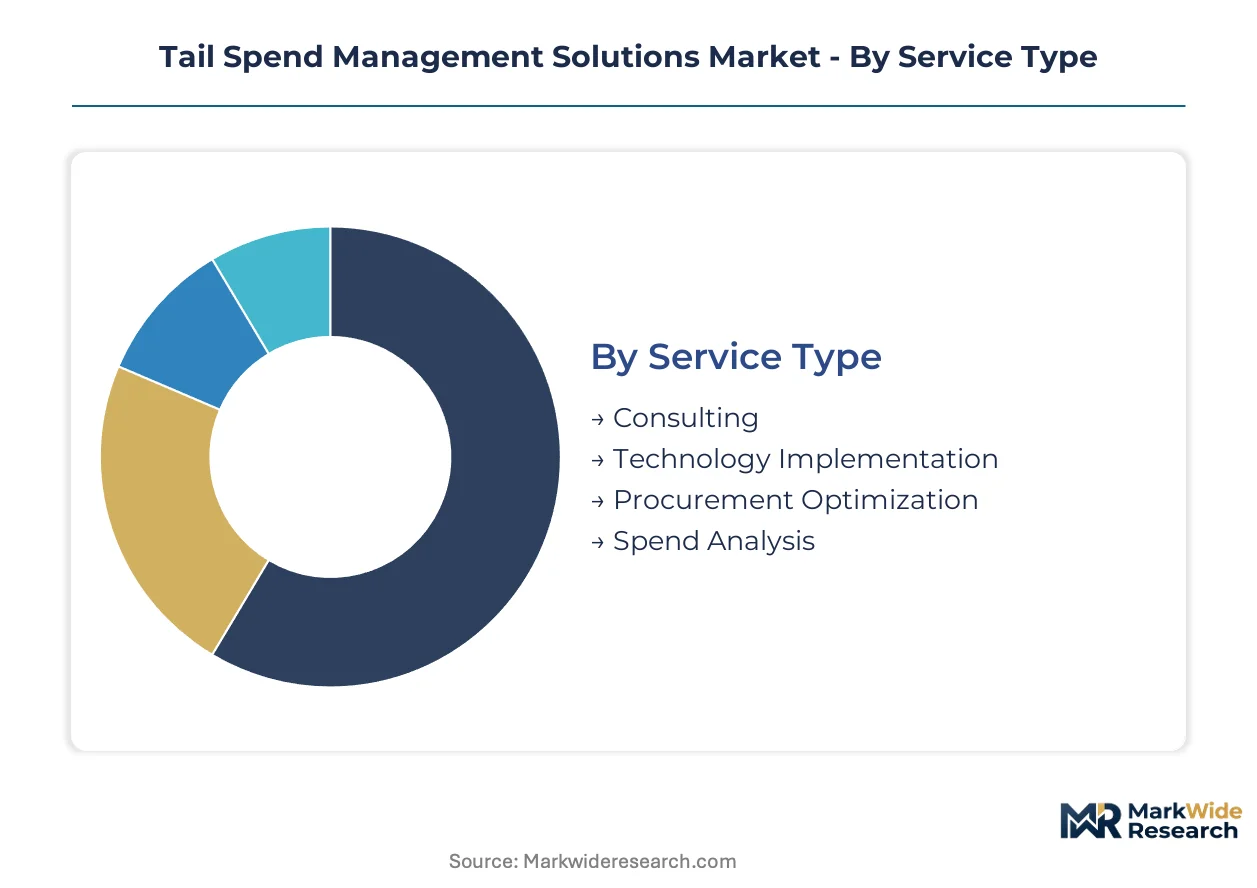
Tail spend management solutions serve heterogeneous buyer needs across service delivery models, technology architectures, and organizational scale. Procurement leaders select configurations based on existing ERP investments, compliance complexity, and internal analytics capabilities.
Service Type:
Technology Implementation faces intensifying substitution pressure from self-service SaaS platforms that compress deployment timelines and reduce professional services dependency.
- Consulting:Advisory engagements map procurement maturity gaps and design taxonomy frameworks for spend classification. Demand concentrates among mid-market enterprises in Germany and the United Kingdom where CSRD readiness requires external expertise without permanent staff expansion.
- Technology Implementation:System integration services connect tail spend platforms to ERP environments through API middleware and data mapping protocols. Manufacturing buyers in the United States drive volume as legacy SAP installations require custom extraction layers for spend visibility.
- Procurement Optimization:Outcome-based contracts tie fees to realized savings from supplier consolidation and catalog rationalization.
- Spend Analysis:One-time or recurring data classification services cleanse supplier master files and apply machine learning taxonomies.
Technology Implementation anchors the volume base while Procurement Optimization gains share at the steepest rate.
Industry Vertical:
Cost tier differentiation separates verticals with complex supplier networks from those with concentrated procurement patterns.
- Manufacturing:Industrial buyers manage thousands of indirect suppliers across MRO, logistics, and professional services categories. German automotive and electronics producers embed carbon accounting into procurement workflows to satisfy CSRD tier-three supplier disclosure mandates.
- Healthcare:Hospital systems and pharmaceutical manufacturers face HIPAA-compliant sourcing for non-medical indirect spend. United States health systems consolidate fragmented purchasing across acquired clinic networks.
- Retail:Merchandising and store operations teams source marketing services, fixtures, and logistics outside core product procurement.
- Education:Universities and K-12 districts manage decentralized purchasing across academic departments with limited central procurement oversight.
Manufacturing anchors the volume base while Healthcare climbs the fastest as compliance pressure intensifies.
Deployment:
Application context determines whether buyers prioritize implementation speed, data sovereignty, or legacy system compatibility.
- Cloud-Based:Multi-tenant architectures enable rapid deployment without infrastructure investment. Mid-market buyers in the United Kingdom adopt these platforms within 90-day windows to satisfy ESG disclosure deadlines.
- SaaS:Subscription delivery with quarterly feature updates displaces on-premise installations among enterprises seeking continuous platform evolution without upgrade projects.
- On-Premise:Self-hosted deployments persist in regulated industries requiring data residency controls and air-gapped security environments.
- Hybrid:Split configurations process sensitive spend data on-premise while leveraging cloud analytics for non-critical categories.
Cloud-Based anchors the volume base while SaaS expands most quickly as subscription economics displace perpetual licensing.
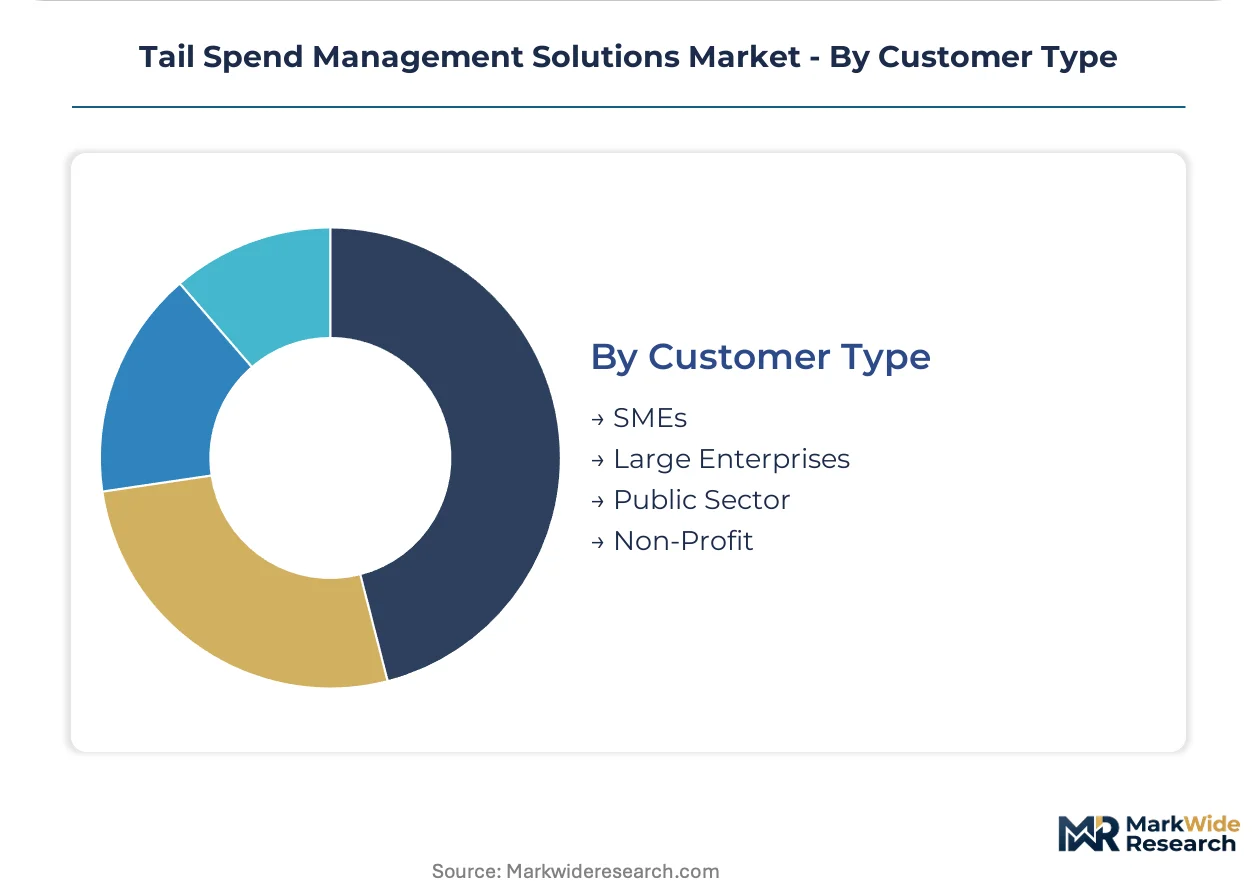
Customer Type:
Organizational scale shapes platform requirements more than any other segmentation dimension.
- Large Enterprises:Fortune 500 procurement organizations demand multi-ERP integration and advanced machine learning classification across millions of annual transactions. These buyers in the United States and Germany negotiate outcome-based contracts tied to realized savings.
- SMEs:Scaling mid-market enterprises prioritize pre-configured taxonomies and rapid implementation over customization. Cloud-native platforms capture this segment through lower total cost of ownership and reduced IT dependency.
- Public Sector:Government agencies require compliant procurement workflows with audit trails and competitive bidding documentation.
- Non-Profit:Charitable organizations seek donor-funded spend visibility to demonstrate stewardship and reduce administrative cost ratios.
Large Enterprises anchors the volume base while SMEs gain share at the steepest rate as cloud deployment dismantles previous IT barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Transatlantic fiber optic cable network and Frankfurt-London financial corridor underpin procurement digitization velocity across developed markets. Data sovereignty requirements and regulatory disclosure mandates reshape platform deployment patterns.
United States
Healthcare systems and financial services firms drive cloud-native procurement adoption. SEC climate disclosure rules force Scope 3 emissions tracking through indirect supplier networks. Procurement technology clusters concentrate in Boston and San Francisco where venture capital flows into API-first spend analytics platforms.
Germany
Automotive and industrial machinery producers anchor demand for multi-ERP integration capabilities. CSRD disclosure mandates require tier-three supplier emissions visibility by sector-specific deadlines. Manufacturing procurement teams in Baden-Württemberg embed carbon accounting fields directly into platform configurations.
United Kingdom
Mid-market enterprises in professional services and retail sectors compress implementation timelines to satisfy ESG reporting deadlines. The Financial Conduct Authority's disclosure expectations extend to supply chain transparency for listed firms. London-based procurement consultancies deliver taxonomy frameworks for CSRD readiness without permanent staff expansion.
India
Domestic manufacturing incentives and BIS standards compliance create demand for localized spend analytics. The PLI scheme requires tracking local content ratios across fragmented supplier bases. Procurement digitization accelerates in Maharashtra and Gujarat where automotive and electronics clusters face import substitution pressures.
France
Luxury goods and aerospace supply chains demand granular supplier risk assessment tools. EU Green Deal due diligence requirements extend emissions accountability to indirect procurement categories. Industrial procurement teams in Île-de-France pilot generative AI for supplier onboarding acceleration.
Tail Spend Management Solutions Market Key Industry Players
Concentration sits with ERP-integrated suite vendors and cloud-native specialists. The market structure reflects a bifurcation between legacy systems integrators and API-first challengers. Two strategic archetypes dominate: deep ERP integration players capturing Fortune 500 accounts, and modular SaaS vendors penetrating mid-market buyers with pre-configured taxonomies. Competitive moves center on outcome-based contracting models and embedded carbon accounting capabilities.
Among cloud-native specialists, Coupa Software Inc. and Zycus Inc. exemplify the API-first archetype serving scaling enterprises with rapid deployment timelines. SAP SE and Oracle Corporation occupy positions within the ERP-anchored tier where deep transactional data integration commands premium positioning. Jaggaer, Inc. represents the multi-ERP specialization vector addressing heterogeneous technology stacks common in private equity-backed roll-ups.
| Leading Market Players |
|---|
| Jaggaer, Inc. |
| Ivalua, Inc. |
| Coupa Software Inc. |
| Order.co |
| Zycus Inc. |
| SAP SE |
| GEP Worldwide, Inc. |
| Proactis Group plc |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Platform scale economies in multi-tenant cloud architectures compress marginal delivery costs below on-premise alternatives, concentrating supply-side power among vendors with established data center footprints while anchoring SaaS price floors above legacy licensing break-even thresholds. This scale dynamic shapes procurement decisions as mid-market buyers trade customization depth for implementation velocity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by ERP integration complexity and machine learning classification granularity. Premium tiers command substantial markups for multi-ERP environments and advanced carbon accounting modules. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting legacy suite vendors with API-first deployment models. SMEs exhibit highest price sensitivity, prioritizing pre-configured taxonomies over custom implementation, while Fortune 500 buyers negotiate outcome-based contracts tied to realized savings.
Supply Chain Analysis
Just-in-time deployment preferences dominate as procurement teams demand 90-day implementation windows rather than multi-year ERP overhaul projects. Software development concentrates in the United States, Germany, and India, with professional services capacity anchored in London and Frankfurt for CSRD compliance expertise. Platform engineering draws from open-source machine learning libraries and hyperscaler cloud infrastructure. Single-source vulnerability persists where buyers depend on proprietary classification algorithms without portable data schemas. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and emerging B2B marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement technology fragmentation creates white-space opportunities as point solutions challenge suite vendors for functional dominance, with mid-market ERP modernization generating niche demand for rapid-deployment platforms.
For Market Incumbents: Compound defensive positioning through deeper ERP integration moats and outcome-based contracting models that tie fees to realized savings rather than seat-based licensing. Threat substitution from API-first challengers demands accelerated cloud migration roadmaps for legacy on-premise installations. Vertical integration into carbon accounting capabilities addresses CSRD compliance pressure before regulatory deadlines harden. For New Entrants and Emerging Players: Lead with pre-configured spend taxonomies targeting SME procurement teams in the United Kingdom and Germany facing compressed ESG reporting timelines. The most penetrable segment comprises mid-market enterprises replacing legacy procurement modules without dedicated IT infrastructure. A channel-centric go-to-market through procurement consultancies delivering CSRD readiness services accelerates customer acquisition without enterprise sales overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native specialists with demonstrated API integration velocity over legacy suite vendors burdened by technical debt. Long-term viability hinges on embedded carbon accounting capabilities that capture regulatory tailwinds without parallel sustainability software investments. Acquisition targets should demonstrate multi-ERP connectivity and machine learning classification accuracy. The signal to watch is tier-three supplier emissions disclosure mandates accelerating platform consolidation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity to SAP and Oracle ERPs captures Fortune 500 procurement modernization budgets. |
| Acquisition of Specialist Firm | Carbon accounting startups with Scope 3 data ingestion capabilities address CSRD compliance deadlines. |
| Geographic Expansion | Localized spend analytics for India's PLI scheme compliance taps automotive and electronics clusters. |
| Strategic Partnership | B2B marketplace alliances displace traditional three-bid-and-buy processes for routine indirect purchases. |
| Product Launch | Generative AI supplier onboarding modules compress risk assessment cycles from weeks to hours. |
Research Approach
A standing panel of chief procurement officers, ERP integration specialists, sustainability compliance leads, and mid-market IT directors provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC climate disclosure filings, EU CSRD implementation guidance, and hyperscaler cloud infrastructure expenditure reports. Bottom-up modeling of deployment timelines and top-down triangulation against aggregate software licensing revenue established market size boundaries.
Consistency checks validated volume and value outputs against external benchmarks including procurement technology adoption surveys and ERP modernization spending patterns across the analysis window. The analytical framework modeled segmentation dimensions spanning deployment architecture, organizational scale, industry vertical, and integration complexity. CAGRs derived from fitted growth curves applied to disclosed customer expansion rates and platform utilization metrics, with carbon accounting module attach rates serving as a key demand-side input.
Forecasts assume regulatory continuity in EU CSRD phase-in schedules and SEC climate disclosure enforcement; material policy shifts would require re-modeling adoption timelines. Specific risk factors include data fragmentation preventing unified spend taxonomies and legacy system entrenchment resisting API-based extraction. Revision becomes warranted when mid-market ERP replacement velocity crosses thresholds that reallocate share between cloud-native and incumbent suite vendors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Construction Design App Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market