
 AI Platform Cloud Service Market | 2026-2036
AI Platform Cloud Service Market Size, Share, and Industry Trends Forecast 2026-2036
AI Platform Cloud Service Market Outlook
Project finance for GPU clusters is narrowing the competitive field to capital-rich operators. Microsoft Azure leverages its enterprise relationships to sustain hybrid cloud dominance. Amazon Web Services anchors global infrastructure scale through custom silicon investments. CoreWeave specializes in GPU-as-a-service models that compete on training workload density.
An AI platform cloud service delivers computational infrastructure, pre-trained models, and development toolchains accessible via networked data centers, typically provisioned through virtualized containers with sub-50ms latency guarantees for real-time inference. Its primary purpose is to eliminate capital expenditure barriers for organizations building, training, and deploying machine learning systems at scale. Public cloud deployments capture the dominant revenue share due to hyperscaler economies in accelerator procurement, while natural language processing applications attract disproportionate investment following transformer architecture proliferation. Platform as a Service offerings command premium positioning by bundling MLOps pipelines that reduce time-to-production for enterprise data science teams.
The EU AI Act and GDPR impose binding risk classifications on automated decision systems, compelling cloud providers to implement audit trails and human oversight mechanisms. The US Federal Trade Commission scrutinizes self-preferencing in AI marketplace distribution, while China's MIIT mandates algorithmic recommendation transparency for consumer-facing platforms. Stakeholders must evaluate sovereign cloud requirements against latency-sensitive workload placement as regulatory fragmentation hardens.
Market Dynamics
Accelerator chip scarcity is concentrating AI platform cloud service procurement around hyperscaler-backed providers with secured foundry allocations, compressing the competitive field to capital-intensive operators capable of multi-billion-dollar infrastructure commitments.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms across Germany, France, and Italy must deploy auditable model pipelines with human oversight mechanisms, forcing cloud infrastructure upgrades.
- Transformer architecture proliferation:Natural language processing workloads require specialized GPU clusters, pulling enterprise R&D budgets toward platform-as-a-service offerings with pre-configured training environments.
- United States hyperscaler expansion:Microsoft Azure and Amazon Web Services are extending data center footprints into secondary domestic markets, reducing latency for real-time inference applications.
Market Restraints
- NVIDIA GPU supply concentration:Taiwan Semiconductor Manufacturing Company foundry capacity constraints limit accelerator availability, creating 12-18 month procurement backlogs for secondary cloud operators.
- Electricity cost volatility:Training clusters in Northern Virginia and Phoenix face surging utility rates, eroding margins on fixed-price compute contracts.
- GDPR data residency requirements:Cross-border model training workflows face legal friction, fragmenting workload placement across sovereign cloud zones.
Strategic Opportunities
- India's PLI scheme for semiconductor manufacturing:Domestic chip packaging incentives could reduce import dependency for GPU-as-a-service providers targeting South Asian enterprise demand.
- Edge inference convergence with 5G:Telecommunications operators in South Korea and Japan are deploying micro data centers for sub-10ms latency applications.
- Algorithmic recommendation transparency mandates:China's MIIT rules are creating compliance service revenue streams for cloud providers offering audit-ready deployment pipelines.
Industry Challenges
- MLOps engineering talent scarcity:Pipeline automation and model monitoring expertise commands premium compensation, constraining platform scaling velocity.
- Legacy enterprise integration complexity:Financial services incumbents with COBOL-based core systems face 18-24 month timelines to connect modern inference APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Platform Cloud Service Market |
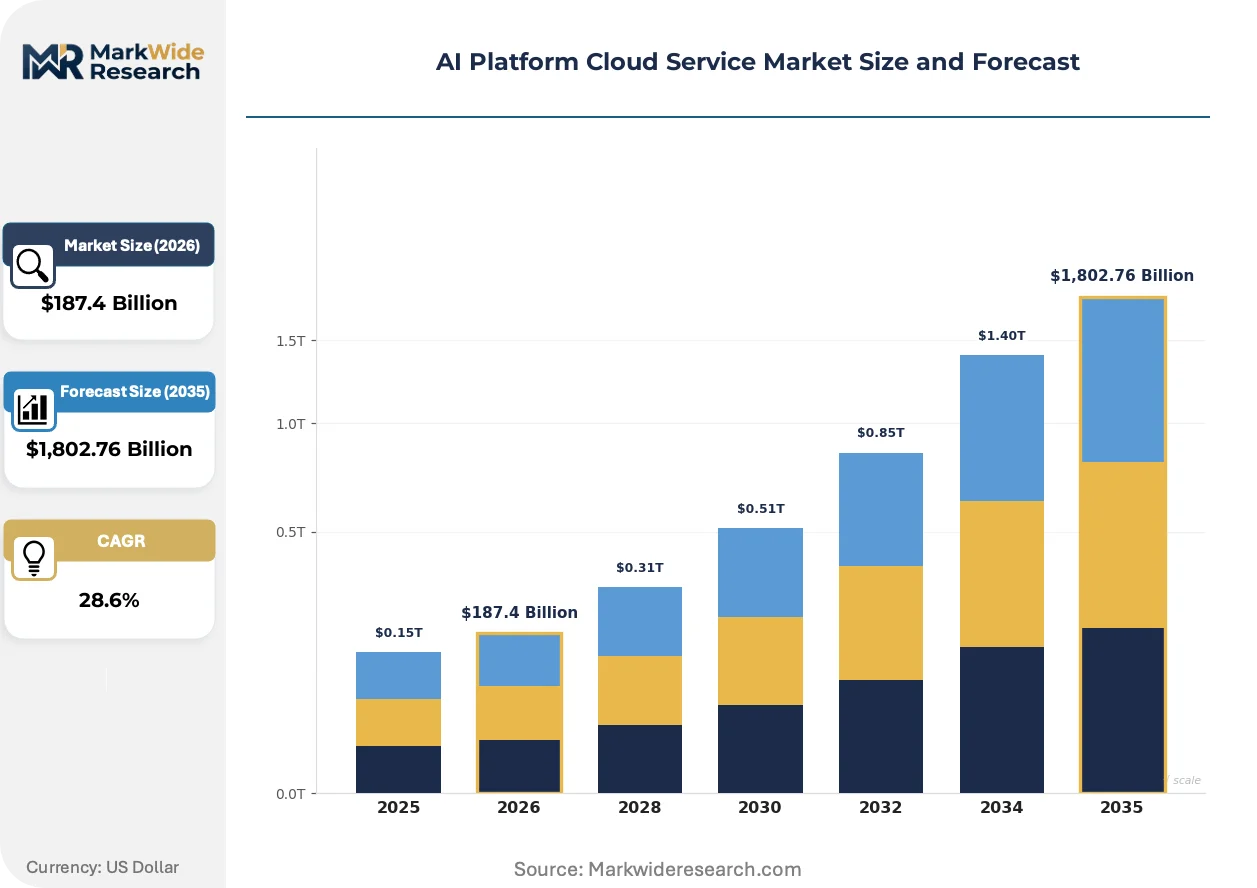
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $1,802.76 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Application: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics End User: Enterprises, Startups, Government Agencies, Academic Institutions Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, Oracle Cloud, Alibaba Cloud, DigitalOcean, CoreWeave, Tencent Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Platform Cloud Service Market Strategic Shifts
Model serving architectures are fragmenting across latency tiers, with training workloads consolidating in hyperscale facilities while inference migrates toward distributed edge nodes to meet real-time application requirements.
Containerized orchestration is migrating from Kubernetes-native frameworks toward purpose-built AI inference servers that optimize GPU memory allocation. Healthcare diagnostic imaging providers in the United States are piloting these systems for radiology workflows. The shift is compressing hardware utilization rates and forcing incumbent platform vendors to rewrite scheduling layers.
The EU AI Act's risk classification framework is binding deployers of high-risk automated decision systems to conformity assessments before production release. Cloud providers must now embed audit logging and human-in-the-loop checkpoints into standard service terms. Financial services and recruitment technology sectors in France and Germany are absorbing the highest compliance costs.
Enterprise procurement of AI infrastructure is fragmenting from centralized IT-led buying toward departmental data science teams with direct platform relationships. Self-service console adoption is displacing traditional enterprise sales cycles in the United States technology sector. This pattern is most visible among Series C-stage software companies with dedicated machine learning engineering functions.
AI Platform Cloud Service Market Segmentation
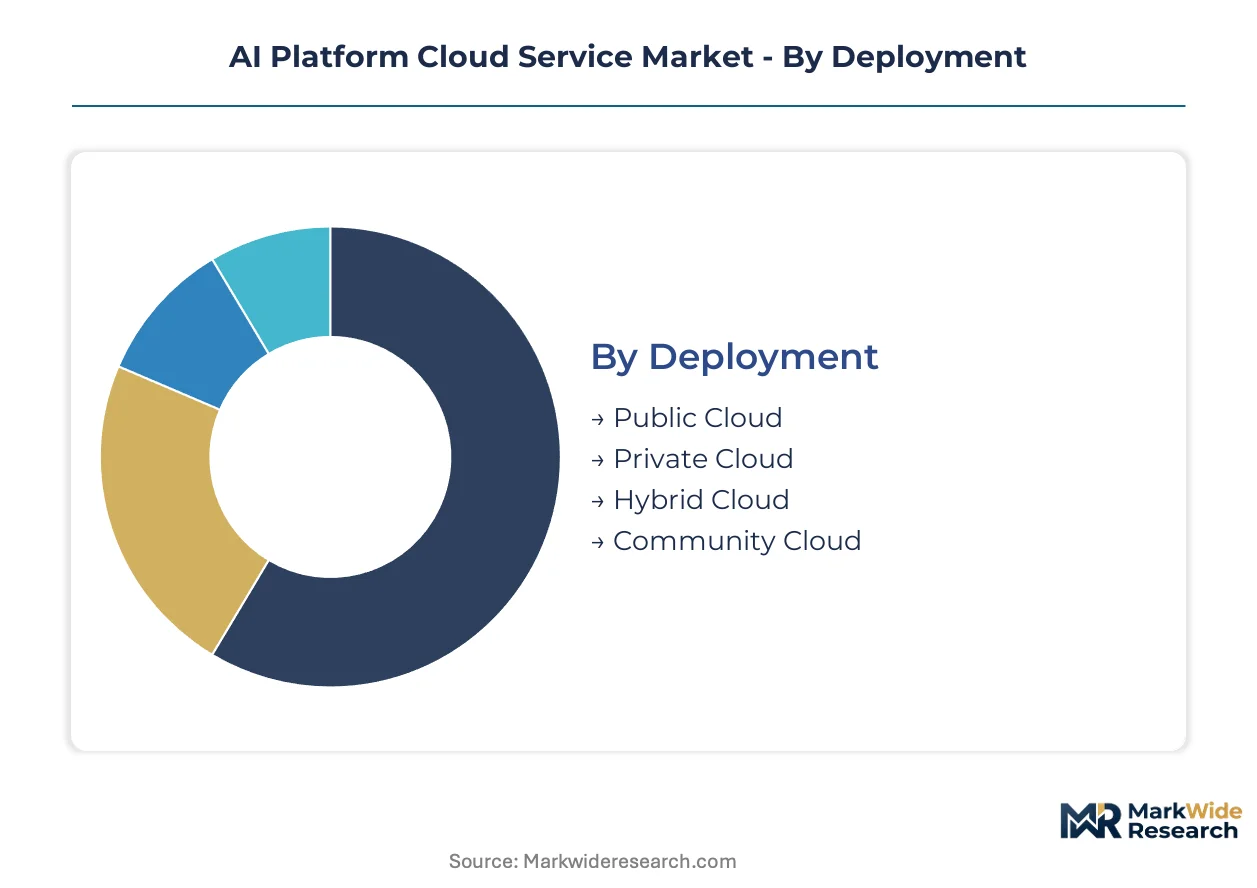
AI platform cloud service procurement patterns diverge sharply across deployment architectures, application workloads, and organizational maturity. Segment boundaries determine pricing elasticity, compliance burden, and vendor selection criteria.
Deployment:
Cost tier structures the infrastructure commitment, separating capital-intensive private deployments from variable public cloud consumption.
- Public Cloud:Multi-tenant virtualized infrastructure provisioned through hyperscaler data centers with pay-per-use GPU allocation. Financial services firms in the United States concentrate demand here for burst training workloads, constrained by EU AI Act data residency requirements for cross-border model development.
- Private Cloud:Dedicated accelerator clusters within enterprise-controlled facilities or single-tenant colocation. German automotive manufacturers and French defense contractors favor this architecture for high-risk automated decision systems subject to conformity assessments.
- Hybrid Cloud:Orchestrated workload placement spanning on-premise inference nodes and public cloud training pools. Demand concentrates among healthcare providers in the United States managing HIPAA-bound patient data alongside scalable research compute.
- Community Cloud:Shared infrastructure serving consortia with common compliance requirements or research missions. Academic supercomputing centers in Japan and national AI research initiatives in India utilize this model for cost-pooled GPU access.
Public Cloud commands the established base. The steepest expansion runs through Hybrid Cloud as sovereignty requirements harden.
Application:
Workload characteristics determine infrastructure specifications, with latency tolerance and compute intensity driving divergent procurement patterns.
- Machine Learning:General-purpose model training and inference spanning supervised, unsupervised, and reinforcement learning paradigms. Enterprise data science teams in the United States deploy MLOps pipelines here, facing talent scarcity in pipeline automation engineering.
- Natural Language Processing:Transformer-based text generation, sentiment classification, and document understanding requiring specialized memory-optimized GPU configurations. This segment absorbs disproportionate investment following large language model proliferation in commercial and research contexts.
- Computer Vision:Image classification, object detection, and video analysis workloads. Manufacturing quality control deployments in South Korea and autonomous vehicle development in Germany anchor demand.
- Predictive Analytics:Statistical forecasting and risk scoring applications with lighter compute requirements. Banking stress testing and insurance underwriting in the United States represent mature deployment contexts.
Machine Learning commands the established base. Natural Language Processing gains share fastest as foundation model investments accelerate.
End User:
Organizational scale and procurement authority shape platform engagement models, from self-service startup consumption to governed enterprise acquisition.
- Enterprises:Fortune 500 and equivalent organizations with centralized IT governance and multi-year cloud commitments. These buyers negotiate custom pricing for reserved GPU capacity, particularly in financial services and pharmaceutical sectors.
- Startups:Venture-backed technology companies with direct platform relationships and credit-based consumption. Series C-stage software firms in the United States increasingly bypass traditional enterprise sales cycles for self-service console adoption.
- Government Agencies:Public sector bodies with sovereign cloud mandates and classified workload requirements. Defense and intelligence communities in France, Germany, and the United States drive demand for air-gapped infrastructure.
- Academic Institutions:Universities and national laboratories with grant-funded research missions and educational pricing access. Federated learning initiatives and open model development concentrate in this segment.
Enterprises command the established base. Government Agencies show the steepest expansion trajectory as national AI strategies mature.
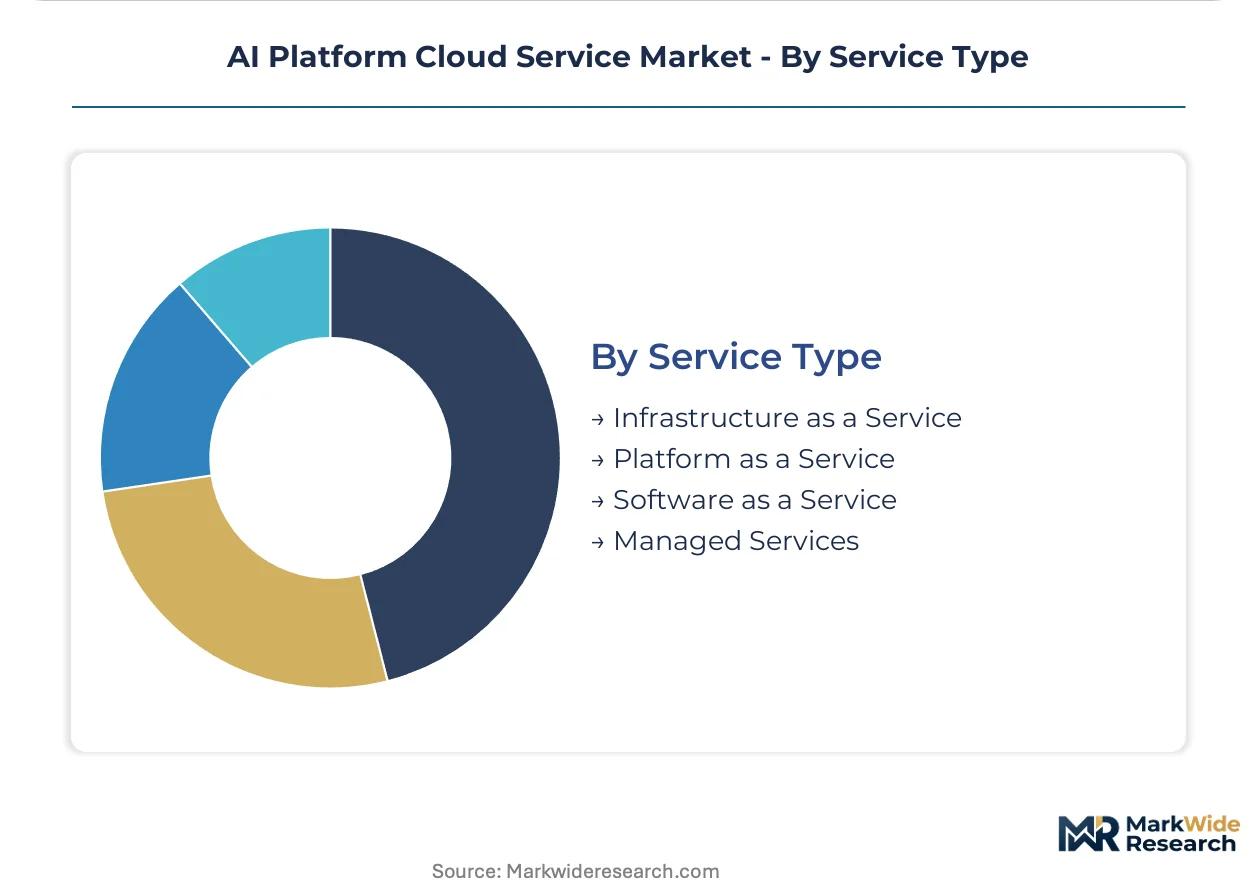
Service Type:
Abstraction layer determines customer technical burden and vendor margin capture, from raw infrastructure to fully managed outcomes.
- Infrastructure as a Service:Bare-metal GPU and CPU provisioning with minimal platform abstraction. CoreWeave and similar specialists compete here on training workload density for customers with in-house MLOps expertise.
- Platform as a Service:Bundled development environments, model registries, and deployment pipelines. Microsoft Azure and Amazon Web Services command premium positioning by reducing time-to-production for enterprise data science teams.
- Software as a Service:Pre-trained model APIs and no-code application builders. This layer abstracts infrastructure entirely, serving line-of-business users without machine learning engineering resources.
- Managed Services:Outsourced model development, fine-tuning, and operational monitoring delivered as contracted outcomes. Compliance-heavy sectors in the EU absorb these offerings to satisfy audit trail and human oversight mandates.
Platform as a Service commands the established base. Managed Services climb the fastest as regulatory complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National AI strategies and data sovereignty mandates are redrawing cloud infrastructure deployment maps. Governments in major economies now condition public sector procurement on domestic data residency, while hyperscalers race to localize accelerator clusters.
United States
Financial services firms in New York and Chicago are expanding machine learning workloads for algorithmic trading and risk modeling. The FTC scrutinizes self-preferencing in AI marketplace distribution, pressuring cloud providers to maintain open API access. Northern Virginia and Phoenix host the densest training cluster concentrations, though electricity cost volatility is compressing margins on fixed-price contracts.
Germany
Automotive manufacturers in Baden-Württemberg and Bavaria require sovereign cloud environments for autonomous vehicle development data. The EU AI Act imposes conformity assessments on high-risk automated decision systems, compelling infrastructure upgrades for audit trails and human oversight. Frankfurt anchors continental data center capacity, with Munich emerging as a secondary node for latency-sensitive industrial inference.
China
Consumer-facing platforms in Beijing and Shenzhen face MIIT-mandated algorithmic recommendation transparency requirements. The country's national AI regulator enforces dual carbon goals that constrain data center energy intensity in eastern provinces. Shanghai and Hangzhou concentrate domestic cloud provider R&D investment, with inference workloads fragmenting toward edge nodes in manufacturing corridors.
India
Enterprise data science teams in Bangalore and Hyderabad are scaling MLOps pipelines for fintech and e-commerce applications. The PLI scheme for semiconductor manufacturing offers domestic chip packaging incentives that could reduce import dependency for GPU-as-a-service providers. Mumbai and Delhi-NCR represent the fastest-growing demand pockets as Series C-stage software firms bypass traditional enterprise procurement.
Japan
Telecommunications operators in Tokyo and Osaka are deploying micro data centers for sub-10ms latency edge inference converging with 5G networks. METI coordinates national AI research initiatives that pool GPU access through academic supercomputing centers. Nagoya's manufacturing belt pilots computer vision workloads for quality control, anchoring specialized cloud service demand.
AI Platform Cloud Service Market Competitive Environment
On the supply side, the industry is consolidating around capital-intensive operators with secured foundry allocations and multi-billion-dollar infrastructure commitments. Hyperscaler-backed providers capture dominant revenue share through economies in accelerator procurement, while specialized GPU-as-a-service challengers compete on training workload density. Three strategic archetypes have emerged: full-stack platform bundlers, bare-metal infrastructure specialists, and compliance-focused managed service providers. Dominant competitive moves include custom silicon investments and sovereign cloud partnerships.
Within the full-stack platform tier, Amazon Web Services and Microsoft Azure anchor enterprise relationships through bundled MLOps pipelines. CoreWeave occupies a position exemplifying the bare-metal specialist archetype, competing on GPU density for customers with in-house machine learning engineering expertise. These three represent the primary competitive vectors shaping procurement patterns across financial services, healthcare, and technology sectors.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Cloud |
| Oracle Cloud |
| Alibaba Cloud |
| DigitalOcean |
| CoreWeave |
| Tencent Cloud |
| Others |
Value Chain & Pricing Dynamics
Taiwan Semiconductor Manufacturing Company foundry utilization rates above 90% are compressing GPU availability timelines and amplifying pricing power for hyperscalers with secured wafer allocations, while secondary operators absorb 12-18 month procurement backlogs that erode competitive positioning.
Pricing Analysis
Reserved capacity commitments create the primary spread between contract and spot compute pricing. Pricing stratifies across enterprise-negotiated reserved instances, on-demand burst workloads, and preemptible surplus capacity tiers. Cost compression in on-demand GPU clusters is intensifying because electricity rate volatility in Northern Virginia and Phoenix erodes margins on fixed-price contracts. Series C-stage software firms in the United States exhibit highest price sensitivity, while German automotive manufacturers prioritize sovereign infrastructure over unit economics.
Supply Chain Analysis
Extended payment terms from NVIDIA to hyperscaler customers with multi-billion-dollar infrastructure commitments are squeezing working capital for mid-tier GPU-as-a-service providers. Taiwan, South Korea, and the United States anchor foundry and packaging capacity for AI accelerators. Supply draws from advanced node silicon wafers, high-bandwidth memory modules, and liquid cooling infrastructure. Single-source vulnerability in TSMC's 4nm and 5nm production nodes concentrates risk. Distribution runs through direct hyperscaler procurement channels and specialized infrastructure financing vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MLOps pipeline automation expertise commands premium compensation that constrains platform scaling velocity, creating a persistent capability gap between capital-rich hyperscalers and engineering-constrained challengers.
For Market Incumbents: Entrench hybrid cloud dominance through sovereign data center partnerships in Frankfurt and Munich that satisfy EU AI Act conformity assessments. Lock in multi-year reserved GPU capacity with foundry allocation guarantees to foreclose secondary operator expansion. The threat of specialized GPU-as-a-service competitors like CoreWeave competing on training workload density demands backward integration into custom silicon development. For New Entrants and Emerging Players: Mid-market financial services firms in India seeking MLOps pipelines without hyperscaler lock-in represent the most penetrable entry point. India's PLI scheme for semiconductor packaging creates localized infrastructure incentives that reduce import dependency friction. Target compliance-heavy sectors in France and Germany with managed service offerings embedding audit logging and human-in-the-loop checkpoints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sovereign cloud infrastructure deployments as national AI strategies mandate domestic data residency. Long-term viability over the projection horizon favors acquisition targets with secured foundry relationships and established enterprise MLOps pipelines. Monitor hyperscaler capex disclosure patterns for early signals of capacity expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Investment | Amazon Web Services and Microsoft Azure reduce NVIDIA dependency through proprietary accelerator chips. |
| Sovereign Cloud Partnership | Hyperscalers establish localized data centers in Germany and France to satisfy EU AI Act data residency mandates. |
| GPU-as-a-Service Specialization | CoreWeave competes on training workload density for customers with in-house machine learning engineering expertise. |
| MLOps Platform Integration | Microsoft Azure bundles development environments and deployment pipelines to reduce enterprise time-to-production. |
| Edge Inference Convergence | Telecommunications operators in South Korea and Japan deploy micro data centers for sub-10ms latency applications. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud infrastructure procurement officers, MLOps engineering leads, enterprise data science team managers, and GPU cluster financing specialists. Secondary validation drew from hyperscaler capital expenditure disclosures, SEC 10-K infrastructure investment filings, foundry utilization reports, and EU regulatory compliance documentation. Bottom-up demand modeling across deployment architectures and application workloads triangulated against top-down market sizing from infrastructure spend aggregation.
Calibration against historical hyperscaler revenue attribution and GPU shipment data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, application workload type, organizational maturity tier, and service abstraction layer. CAGRs derived from capacity expansion trajectories and enterprise adoption curve analysis. Forecast inputs incorporated foundry allocation schedules and electricity cost volatility indices for Northern Virginia and Phoenix data center clusters.
Practitioners should monitor foundry capacity expansion announcements and EU AI Act enforcement patterns for early signals of supply constraint easing or compliance cost escalation. Forecasts reflect assumptions of sustained accelerator scarcity and regulatory fragmentation hardening. Macroeconomic contraction in enterprise technology spending, breakthrough domestic foundry capacity in India, or unified global AI governance frameworks would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Cloud ECS Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Cloud Directory Services Software Market