
 Canada Data Center Server Market | 2026-2036
Canada Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Server Market Insights
Modular server configurations is pivoting buyer preference away from monolithic rack deployments toward disaggregated compute, storage, and networking units. Microsoft sustains significant R&D intensity in liquid-cooled server architectures for Quebec facilities. eStruxture Data Centers anchors its competitive stance through dense Montreal deployments serving financial services tenants. QScale differentiates with energy-efficient designs tied to renewable power sourcing in the province.
A data center server is a high-performance computing device engineered with multi-core processors, ECC memory, and redundant power supplies, designed for continuous operation in controlled environments to process, store, and distribute digital workloads at enterprise scale. Rack servers occupy the dominant product position due to standardization and density advantages in colocation halls across Toronto and Vancouver. Hyperconverged infrastructure represents the fastest-expanding technology segment as enterprises consolidate storage, compute, and virtualization into single appliance footprints. Cloud service providers command the largest end-user margin pool through multi-year refresh cycles and custom ODM engagements.
Health Canada oversees medical data residency requirements that mandate domestic server placement for healthcare workloads. Provincial privacy commissioners in Ontario, Quebec, and British Columbia enforce sector-specific data localization standards affecting cross-border server architecture decisions. The Canadian Radio-television and Telecommunications Commission shapes telecommunications infrastructure rules that indirectly govern edge server placement near 5G networks. Stakeholders must weigh carbon intensity regulations against latency requirements when siting next-generation compute clusters.
Market Dynamics
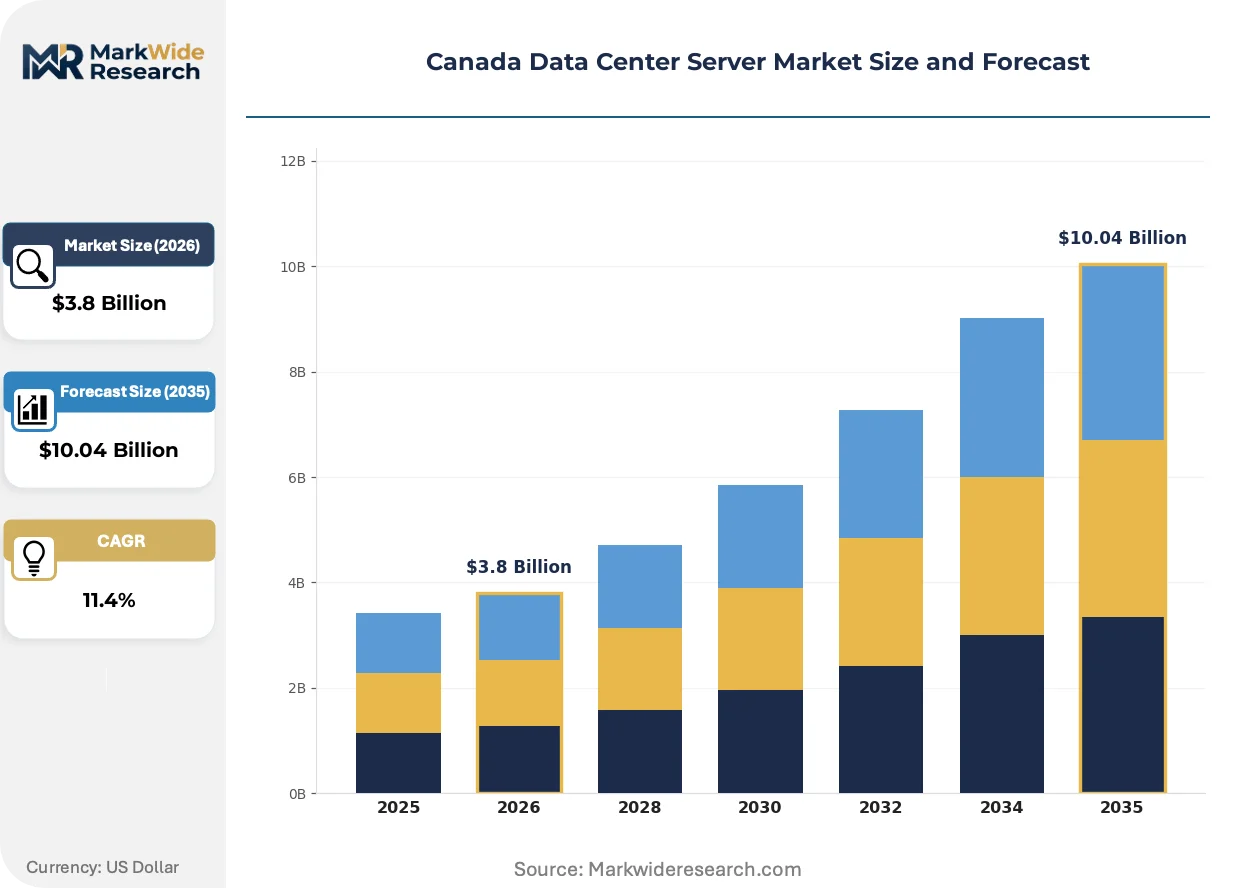
Provincial data residency mandates from Health Canada and Quebec's Commission d'accès à l'information are forcing cloud providers to expand domestic server footprints, compressing deployment timelines and reshaping procurement patterns across Ontario and Quebec facilities.
Growth Catalysts
- Health Canada Data Residency Requirements:Medical data localization rules mandate domestic server placement for healthcare workloads, pulling hyperscale investment into Toronto and Montreal colocation halls.
- Hyperconverged Infrastructure:Enterprise consolidation of compute, storage, and virtualization layers into single appliance footprints accelerates refresh cycles in financial services and public sector deployments.
- Quebec Renewable Power Access:Low-carbon hydroelectricity availability attracts energy-intensive AI training clusters to Montreal-area facilities, differentiating provincial server demand from carbon-constrained jurisdictions.
Market Restraints
- GPU Supply Concentration:AI accelerator procurement remains constrained by Taiwan-based foundry capacity and NVIDIA allocation protocols, extending lead times for Quebec machine learning deployments.
- Carbon Intensity Regulations:British Columbia's clean energy standards and federal carbon pricing mechanisms impose compliance costs on diesel backup generator configurations in Vancouver edge facilities.
- Liquid Cooling Retrofit Costs:Existing Toronto colocation infrastructure built for air-cooled densities requires substantial capital reconfiguration to support next-generation thermal envelopes above 50kW per rack.
Strategic Opportunities
- Atlantic Canada Edge Expansion:Underdeveloped Halifax and Moncton markets present first-mover positioning for latency-sensitive gaming and content delivery networks serving Maritime provinces.
- Indigenous Data Sovereignty Frameworks:Emerging First Nations-controlled data governance models create specialized server hosting demand tied to cultural resource digitization and healthcare autonomy in northern Ontario and British Columbia.
- 5G Network Function Virtualization:Radio access network disaggregation converges with edge server deployment, opening distributed compute nodes across Rogers and Telus infrastructure corridors.
Industry Challenges
- Liquid Cooling Engineering Talent Scarcity:Specialized thermal management expertise for immersion and direct-to-chip architectures remains concentrated among a limited pool of Montreal and Toronto contractors.
- Provincial Privacy Regime Fragmentation:British Columbia's Personal Information Protection Act, Quebec's Law 25, and Ontario's health-sector directives create multi-jurisdictional compliance complexity for national cloud deployments.
- Legacy Three-Tier Architecture Integration:Financial institutions in Toronto maintain substantial sunk investments in discrete storage area networks that resist rapid hyperconverged migration without operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Server Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers End User: Enterprises, Cloud Service Providers, Government, Telecommunications Technology: Virtualization, Hyperconverged Infrastructure, Edge Computing, AI Integration Deployment: On-Premises, Colocation, Managed Services, Hybrid Solutions |
| Companies Covered | Equinix, Microsoft, eStruxture Data Centers, QScale, Google, Cologix, Amazon Web Services (AWS), STACK Infrastructure, Digital Realty Trust, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Server Market Trends and Innovations
Server architecture in Canadian facilities is pivoting toward thermal and compositional flexibility as provincial energy regulations tighten and AI workloads reshape density requirements across the country's data center clusters.
Direct liquid cooling is converging with high-density GPU deployments to enable sustained AI training operations in Quebec's hydroelectric-powered facilities. Cloud providers operating Montreal campuses are retrofitting existing halls with coolant distribution units and cold plates to support thermal envelopes exceeding 100kW per rack. This convergence is compressing the viable lifecycle of air-cooled infrastructure in Ontario and Quebec markets.
Quebec's Law 25 imposes strict breach notification timelines and data localization obligations that force server architecture decisions toward in-province redundancy. Financial services tenants in Montreal colocation facilities must now demonstrate provincial data segmentation in their rack configurations. The regulation is accelerating demand for software-defined perimeter controls and zero-trust network architectures in Quebec-based deployments.
Enterprise buyers are consolidating vendor relationships through multi-year framework agreements that bundle hardware, maintenance, and disposal services. Toronto-based financial institutions and Vancouver healthcare networks are replacing transactional procurement with outcome-based contracts specifying availability and carbon intensity metrics. This consolidation is most visible in Ontario's public sector, where Infrastructure Ontario mandates standardized server configurations across provincial agencies.
Canada Data Center Server Market Segmentation
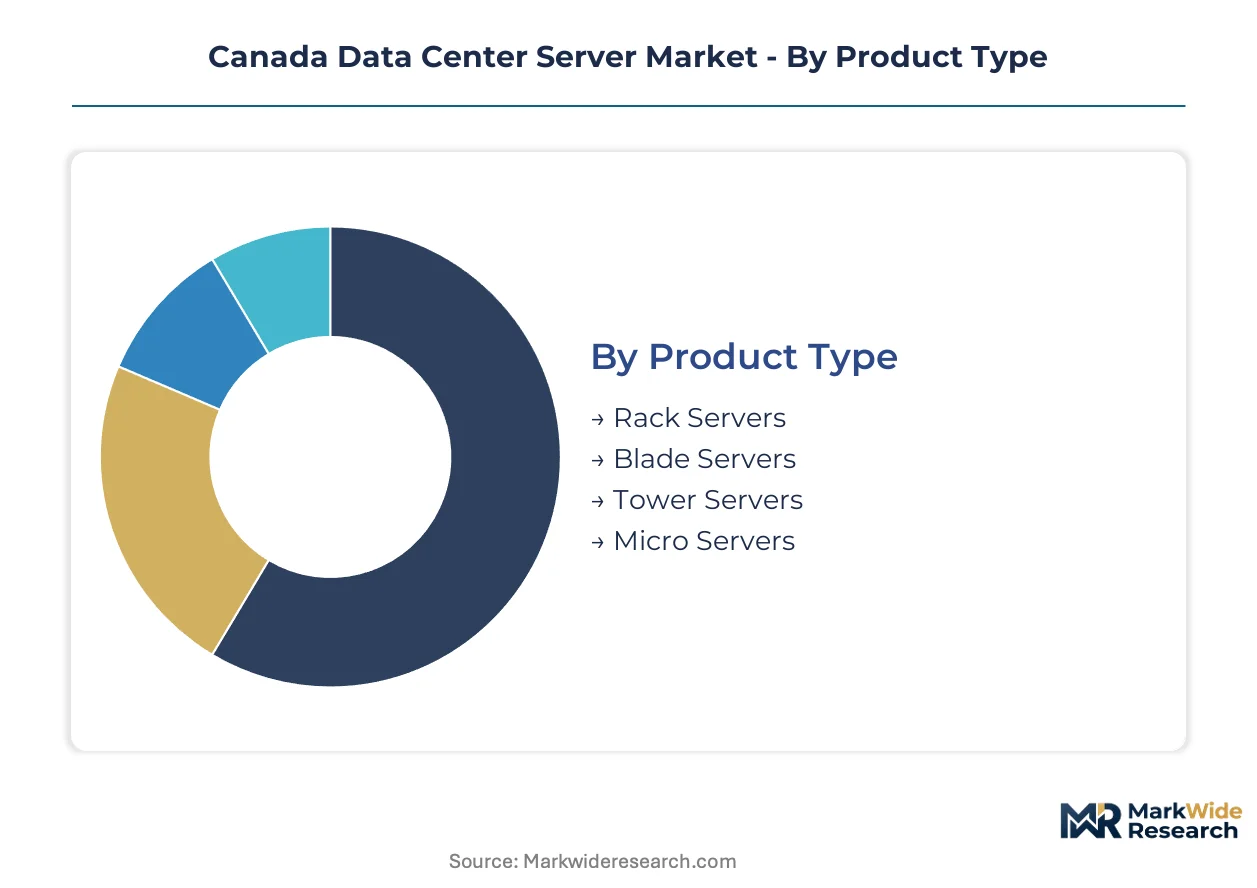
Server procurement patterns across Canadian facilities diverge sharply by workload density, regulatory jurisdiction, and thermal envelope requirements. Understanding these segment boundaries clarifies why Ontario financial institutions favor different architectures than Quebec AI clusters or Vancouver edge nodes.
Product Type:
Supply concentration among ODM manufacturers in Taiwan and China shapes availability timelines for Canadian buyers, with rack and blade formats dominating hyperscale procurement.
- Rack Servers:Standardized 19-inch form factors with hot-swappable drive bays and redundant power supplies dominate Toronto and Montreal colocation halls. Financial services tenants in Ontario facilities specify these units for their density advantages and serviceability in shared environments.
- Blade Servers:Shared chassis architectures with integrated switching and power distribution enable extreme density in Quebec AI training facilities. Microsoft and cloud providers operating Montreal campuses deploy these for machine learning workloads requiring 100kW-plus thermal envelopes.
- Tower Servers:Standalone vertical enclosures serve small-scale healthcare deployments in rural Ontario and British Columbia where rack infrastructure is unavailable.
- Micro Servers:Low-power single-socket units support edge caching and content delivery nodes across Rogers and Telus 5G infrastructure corridors in Vancouver and Calgary.
Rack servers absorb the bulk of installed capacity; hyperconverged blade configurations are expanding most quickly in Quebec AI clusters.
End User:
Procurement scale and refresh cadence separate enterprise buyers from hyperscale operators, with government mandates creating distinct compliance-driven demand patterns.
- Cloud Service Providers:Multi-year refresh cycles and direct ODM engagements characterize procurement by Microsoft, Amazon, and Google operating Toronto and Montreal facilities. These buyers specify liquid-cooled custom architectures unavailable through channel distribution.
- Enterprises:Financial institutions in Toronto and healthcare networks in Vancouver purchase through value-added resellers with three-year maintenance bundles. Their deployments emphasize hybrid cloud connectivity and disaster recovery redundancy.
- Government:Federal and provincial agencies mandate domestic data residency, driving server placement in Crown-owned or certified colocation facilities. Infrastructure Ontario standardizes configurations across ministries to simplify procurement.
- Telecommunications:Rogers, Bell, and Telus deploy edge servers for 5G network function virtualization, requiring low-latency nodes distributed across provincial infrastructure corridors.
Cloud service providers command the largest procurement volumes; government segments are climbing the fastest as Health Canada residency mandates tighten.
Technology:
Virtualization maturity varies by province, with Quebec facilities leading adoption of integrated compute-storage architectures.
- Hyperconverged Infrastructure:Single-appliance consolidation of compute, storage, and virtualization layers accelerates refresh cycles in Ontario financial services and public sector deployments. These systems reduce rack footprint and operational complexity for mid-size enterprises.
- Virtualization:Software-defined resource abstraction remains foundational in legacy Toronto data centers resisting full hardware refresh. Financial institutions maintain substantial VMware estates while evaluating Nutanix alternatives.
- Edge Computing:Distributed processing nodes support latency-sensitive applications in Vancouver gaming and Maritime content delivery networks. Telus deploys these across British Columbia and Alberta infrastructure.
- AI Integration:GPU-dense configurations for machine learning training concentrate in Quebec facilities leveraging low-carbon hydroelectricity. These deployments require specialized liquid cooling and direct-to-chip thermal management.
Virtualization retains the largest installed base; hyperconverged infrastructure is gaining share fastest among enterprise buyers consolidating three-tier architectures.
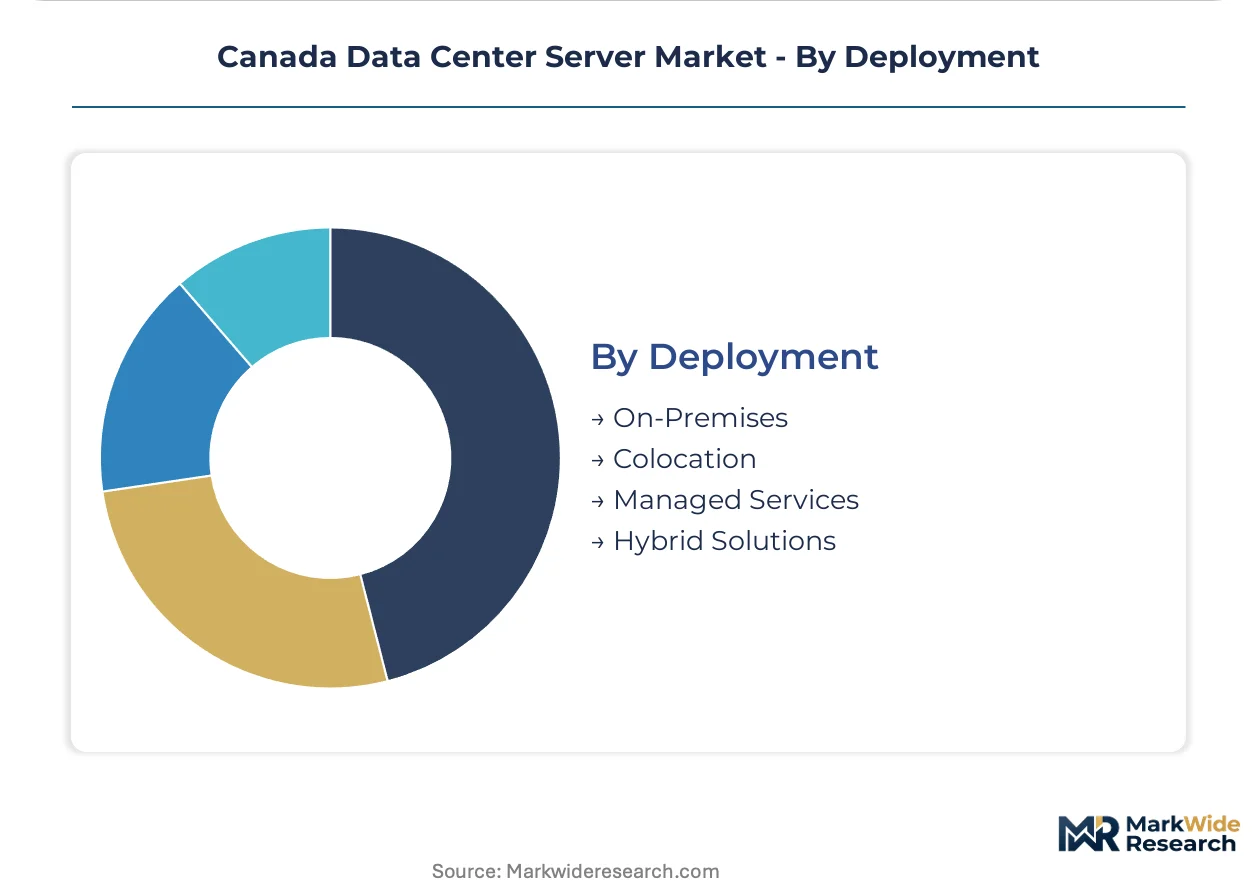
Deployment:
Capital efficiency pressures and regulatory uncertainty are shifting procurement toward hybrid and managed service models.
- Colocation:Third-party facility leasing dominates Toronto and Montreal markets, with eStruxture and QScale offering dense, compliant environments. Tenants retain hardware ownership while outsourcing power, cooling, and physical security.
- Hybrid Solutions:Workload portability across on-premises and cloud environments addresses data sovereignty requirements for Ontario healthcare and financial services. These architectures balance latency performance with regulatory compliance.
- On-Premises:Crown corporations and defense-adjacent enterprises maintain captive facilities in Ottawa and Calgary for classified or sensitive workloads. These deployments require substantial capital commitment and specialized staffing.
- Managed Services:Outcome-based contracts specifying availability and carbon intensity metrics appeal to Vancouver healthcare networks and mid-size enterprises lacking internal infrastructure expertise.
Colocation absorbs the bulk of new server deployments; hybrid solutions are expanding most quickly as enterprises navigate provincial privacy regime fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic server production remains minimal in Canada, with hardware sourced predominantly from Taiwanese and Chinese ODM manufacturers. Consumption concentrates in Ontario and Quebec facilities where cloud providers and enterprises deploy imported rack and blade systems. Provincial data residency mandates and renewable power access shape regional deployment patterns across the country's data center clusters.
Ontario
Toronto anchors the country's largest colocation market, with financial services tenants driving rack server procurement for trading and risk management workloads. Infrastructure Ontario mandates standardized server configurations across provincial agencies, compressing vendor selection timelines. The Toronto-Waterloo corridor hosts dense cloud provider campuses serving enterprise hybrid cloud demand.
Quebec
Montreal facilities attract AI training clusters leveraging low-carbon hydroelectricity from Hydro-Québec's grid. The Commission d'accès à l'information enforces Law 25 data localization requirements, forcing provincial data segmentation in rack configurations. QScale and Microsoft operate liquid-cooled campuses in the region to support 100kW-plus thermal densities.
British Columbia
Vancouver edge facilities serve gaming and content delivery networks with latency-sensitive micro server deployments. The province's clean energy standards impose compliance costs on diesel backup configurations, reshaping generator procurement. Telus distributes compute nodes across infrastructure corridors to support 5G network function virtualization.
Alberta
Calgary maintains captive on-premises facilities for Crown corporations and energy sector enterprises with classified workload requirements. The province's regulatory environment permits carbon-intensive power sourcing, differentiating deployment economics from British Columbia. Oil and gas operators in the region retain substantial legacy three-tier storage architectures resistant to rapid hyperconverged migration.
Atlantic Canada
Halifax and Moncton present underdeveloped capacity for latency-sensitive gaming and maritime logistics applications. Provincial privacy commissioners in the region enforce sector-specific data localization standards affecting cross-border architecture decisions. First Nations-controlled data governance models in northern communities create specialized hosting demand tied to healthcare autonomy and cultural resource digitization.
Canada Data Center Server Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Canada's data center server market, creating a tiered competitive structure. Hyperscale cloud operators maintain direct ODM relationships for custom liquid-cooled architectures unavailable through channel distribution. Three archetypes dominate: global cloud providers with captive infrastructure divisions, regional colocation specialists with dense facility footprints, and telecommunications carriers with distributed edge assets. Competitive moves center on facility expansion into Quebec's renewable power zones and strategic partnerships with provincial Crown corporations for government-compliant hosting.
Among global cloud operators, Microsoft, Amazon Web Services, and Google exemplify the scale-driven archetype through multi-year refresh cycles and proprietary server designs. Regional specialists eStruxture Data Centers and QScale occupy positions as facility-focused competitors, with the former anchoring dense Montreal deployments and the latter differentiating through energy-efficient designs tied to renewable sourcing. Equinix and Digital Realty Trust represent the interconnection-centric tier, leveraging global platform integration to serve multinational enterprise demand from Toronto and Vancouver hubs.
| Leading Market Players |
|---|
| Equinix |
| Microsoft |
| eStruxture Data Centers |
| QScale |
| Cologix |
| Amazon Web Services (AWS) |
| STACK Infrastructure |
| Digital Realty Trust |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud providers operating Toronto and Montreal facilities command concentrated procurement volumes that anchor contract-based long-term offtake pricing for rack and blade server architectures. Their multi-year framework agreements with Taiwanese ODMs compress margins for channel distributors serving mid-size Canadian enterprises.
Pricing Analysis
Margin tightening in the enterprise reseller tier reflects direct ODM relationships that bypass traditional distribution for Quebec AI training clusters. Pricing stratifies across liquid-cooled premium configurations, standard air-cooled rack units, and economy-tier refurbished hardware. Cost-down pressure on channel partners accelerates because Infrastructure Ontario's standardized procurement mandates favor outcome-based contracts specifying availability metrics. Government buyers exhibit lowest price sensitivity due to compliance-driven requirements, while mid-size healthcare networks in Vancouver demonstrate highest sensitivity to total cost of ownership.
Supply Chain Analysis
Reverse logistics flows for end-of-life servers create secondary value streams as Montreal facilities refurbish decommissioned units for rural Ontario healthcare deployments. Manufacturing concentration rests on Taiwan, China, and South Korea for motherboard assemblies, memory modules, and GPU accelerators. Raw material dependencies center on rare earth elements for magnetic components, high-purity silicon for semiconductors, and copper for thermal management systems. Single-source vulnerability from NVIDIA's allocation protocols for AI accelerators exposes Quebec machine learning deployments to extended lead times. Distribution runs through Vancouver port entry points for West Coast facilities and Toronto logistics hubs serving Ontario and Quebec markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
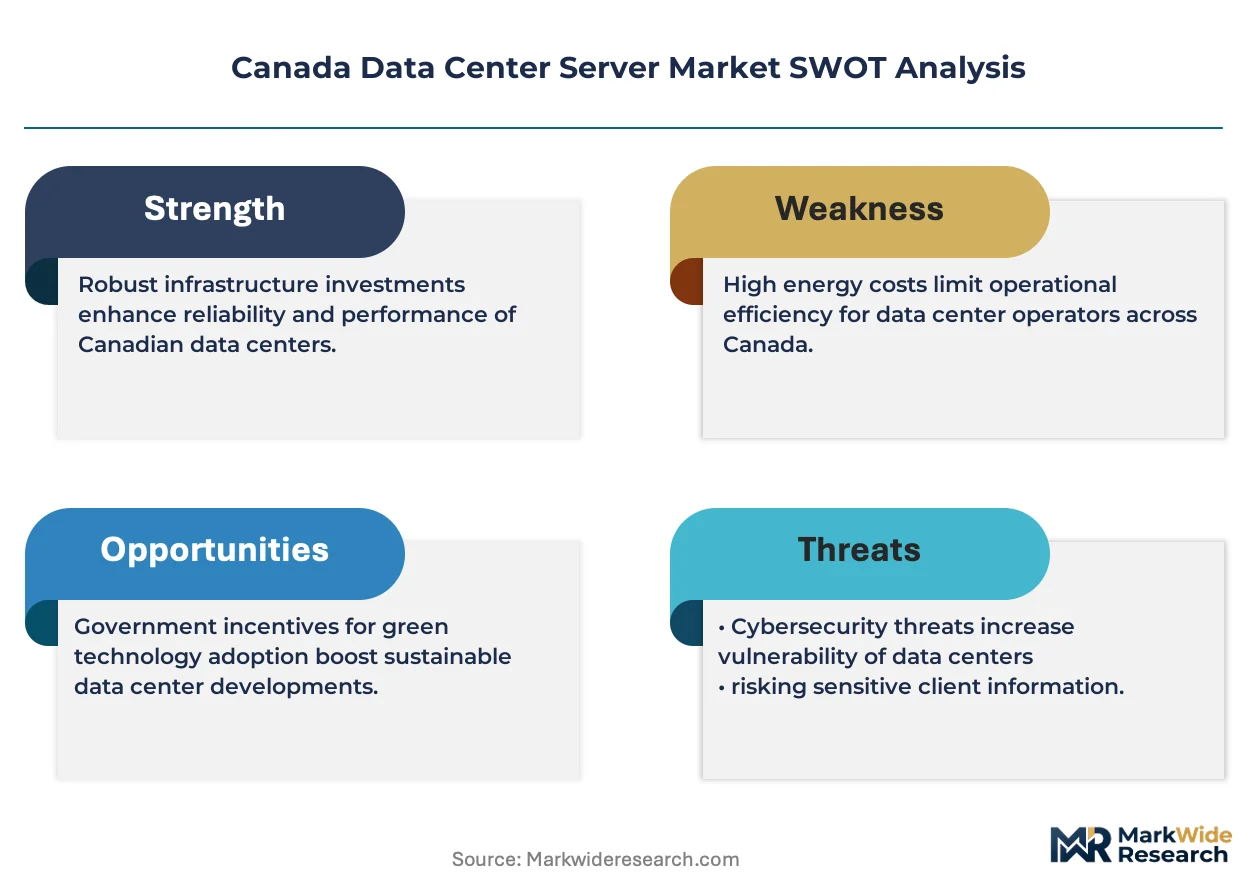
GPU supply concentration and provincial data residency mandates are forcing consolidation among regional colocation operators unable to secure long-term accelerator allocations or achieve compliance scale.
For Market Incumbents: Extend liquid-cooled infrastructure footprints in Quebec's hydroelectric zones to capture AI training demand from cloud providers seeking carbon-efficient density. Secure backward integration into direct ODM relationships that bypass distributor markups for custom blade configurations. Health Canada's tightening residency requirements threaten operators lacking domestic facility presence, making Crown corporation partnerships essential for government segment retention. For New Entrants and Emerging Players: Law 25 in Quebec opens a window for specialized compliance-focused hosting services that demonstrate provincial data segmentation capabilities. Target Atlantic Canada's underdeveloped Halifax and Moncton markets for latency-sensitive gaming and maritime logistics applications where incumbent presence remains thin. A First Nations partnership model addressing Indigenous data sovereignty frameworks in northern British Columbia and Ontario offers differentiated positioning against established Toronto and Vancouver operators. For Investors and Strategic Acquirers: The window for entry favors facility-focused specialists with dense Montreal footprints and established Hydro-Québec power contracts. Long-term viability hinges on securing renewable energy agreements and liquid-cooled infrastructure capable of sustaining 100kW-plus thermal densities. Monitor NVIDIA allocation protocol changes as the critical inflection signal for Quebec AI cluster expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables Microsoft and QScale to sustain 100kW-plus AI training densities in Quebec facilities. |
| Indigenous Data Sovereignty Partnership | Creates specialized hosting demand tied to First Nations healthcare autonomy in northern Ontario. |
| Direct ODM Relationship Establishment | Bypasses channel margins for hyperscale cloud providers operating Toronto and Montreal campuses. |
| Atlantic Canada Edge Expansion | Captures first-mover positioning for latency-sensitive gaming networks in Halifax and Moncton. |
| Crown Corporation Certification Investment | Secures Infrastructure Ontario procurement eligibility for standardized server configurations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with data center facility operators, cloud provider procurement executives, provincial IT infrastructure directors, and ODM manufacturing specialists. Health Canada guidance documents, CRTC telecommunications infrastructure rules, and provincial privacy commissioner rulings provided regulatory boundary conditions. Infrastructure Ontario procurement databases and hyperscaler capital expenditure disclosures supplied demand-side validation. Bottom-up server shipment estimates triangulated against top-down facility capacity assessments across Toronto, Montreal, and Vancouver markets.
Reconciliation of server unit volumes, average selling price trajectories, and facility deployment timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, deployment model, and provincial regulatory jurisdiction. CAGRs were derived from fitted growth curves incorporating historical procurement patterns and policy-driven demand inflections. AI workload density requirements and liquid cooling adoption curves served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for direct liquid cooling would alter the outlook if air-cooled thermal envelopes advance unexpectedly. Forecasts reflect assumptions about Health Canada residency mandate enforcement consistency and Hydro-Québec power availability for Quebec facilities. Practitioners should monitor NVIDIA supply allocation announcements and provincial privacy regime harmonization efforts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Sweden Data Center Construction Market