
 Aeration Pads Market | 2026-2036
Aeration Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Aeration Pads Market Analytics
Asset-light leasing models for pneumatic conveying infrastructure is reconfiguring how mid-sized processors access aeration pad systems without capital-heavy ownership. WAMGROUP leverages its vertical integration across silo equipment to sustain pricing power in European bulk solids markets. Solimar Pneumatics specializes in membrane-based aeration designs that anchor its position in food-grade material handling applications.
Aeration pads are porous membrane or perforated devices installed at the base of silos, hoppers, and bulk containers to introduce low-pressure air that fluidizes powdered or granular materials, typically operating at 2–6 psi to prevent ratholing and arching during discharge. The product category spans foam, rubber, plastic, and composite constructions, with composite pads capturing expanding interest due to their chemical resistance and extended service intervals in abrasive environments. Application demand splits across aquaculture, horticulture, wastewater treatment, and soil aeration, though wastewater treatment dominates volume as municipalities retrofit aging infrastructure with energy-efficient aeration systems.
EPA effluent guidelines and OSHA combustible dust standards in the United States shape product specifications and installation protocols for aeration pads in bulk handling facilities. India's BIS pneumatic equipment standards and the EU's ATEX directives for explosive atmospheres create parallel compliance pathways that manufacturers must navigate for multi-region market access. Stakeholders should monitor how tightening energy-efficiency benchmarks for aeration systems in wastewater and industrial processing reshape material selection and membrane design priorities.
Market Dynamics
India's BIS certification requirements for pneumatic equipment are compressing supplier margins while forcing rapid material upgrades across domestic manufacturing clusters, fundamentally restructuring competitive positioning in bulk solids handling.
Growth Catalysts
- Composite Material Advancement:Chemical-resistant aeration pad constructions extend service intervals in abrasive cement and mineral processing environments, reducing unplanned downtime for silo operators.
- EPA Effluent Guidelines:Municipal wastewater treatment facilities across the United States are retrofitting aging aeration infrastructure with energy-efficient membrane systems to meet tightened discharge standards.
- Maharashtra-Gujarat Cluster Density:Concentrated bulk solids processing capacity in these Indian states generates sustained replacement demand from construction and chemical sector silo operations.
Market Restraints
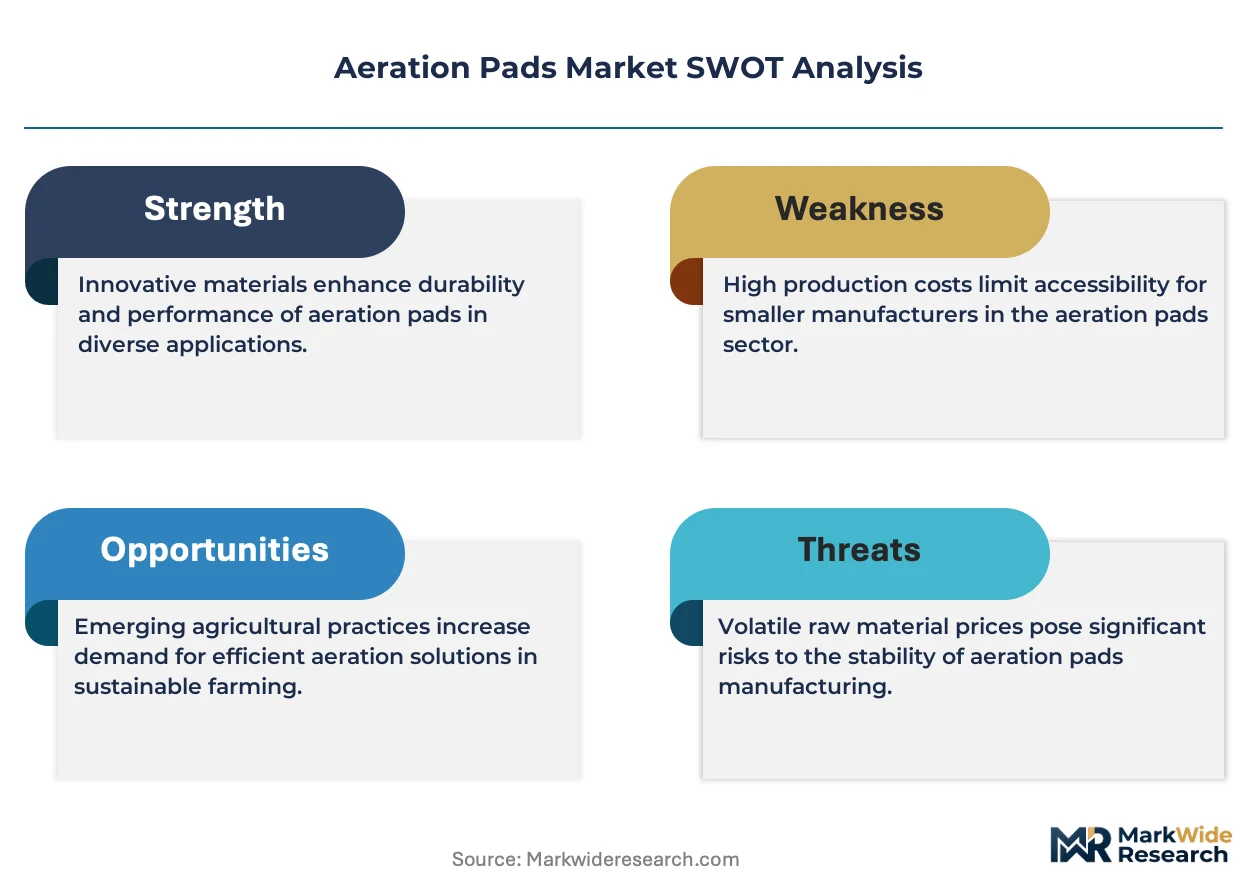
- Specialized Polymer Input Volatility:Fluoropolymer and silicone membrane feedstock prices fluctuate with petrochemical cycles, compressing pad manufacturer margins unpredictably.
- European Supply Concentration:ATEX-certified component sourcing remains concentrated among German and Italian pneumatic equipment suppliers, creating single-source vulnerability for explosion-proof specifications.
- Mechanical Agitation Substitution:Vibratory bin activators and air cannons compete for ratholing prevention applications where higher-pressure fluidization is acceptable.
Strategic Opportunities
- Leasing Model Expansion:Asset-light pneumatic conveying infrastructure access allows mid-sized Indian processors to deploy aeration systems without capital ownership burdens.
- Food-Grade Membrane Convergence:Hybrid silicone-PTFE laminates are penetrating dairy powder and infant formula silo applications where contamination sensitivity exceeds standard industrial tolerances.
- EU Green Deal Alignment:Energy-efficiency benchmarking for aeration systems creates specification advantages for low-pressure, high-uniformity pad designs in municipal procurement.
Industry Challenges
- Pneumatic System Integration Complexity:Legacy silo infrastructure often lacks compressed air capacity sizing for modern low-pressure, high-volume aeration pad configurations, requiring costly blower upgrades.
- BIS Certification Timeline Compression:Domestic Indian suppliers face 8-12 month approval cycles for new composite material formulations, delaying product launches against uncertified imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeration Pads Market |
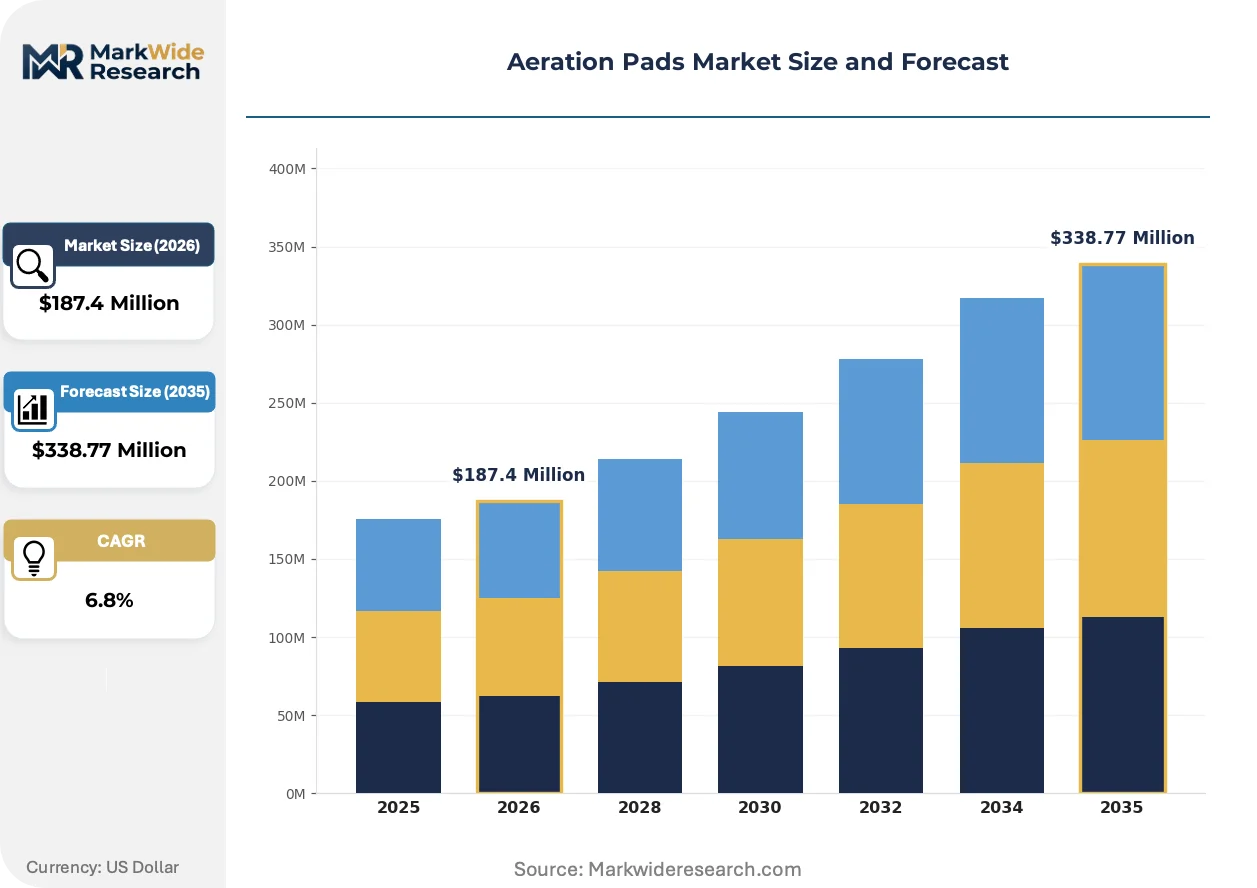
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Pads, Rubber Pads, Plastic Pads, Composite Pads Application: Aquaculture, Horticulture, Wastewater Treatment, Soil Aeration End User: Farmers, Landscapers, Municipalities, Commercial Growers Installation Method: Permanent, Removable, Integrated, Standalone |
| Companies Covered | WAMGROUP, Monitor Technologies LLC, Solimar Pneumatics, Xylem Inc, Sulzer Ltd, Evoqua Water Technologies, Aeration Industries International, Aqua Control, Aqua-Aerobic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeration Pads Market Evolving Landscape
Membrane engineering and procurement economics are actively restructuring how aeration pad specifications propagate through bulk handling value chains, with material science advances compressing traditional equipment replacement cycles.
PTFE-coated fiberglass membrane technology is migrating from high-temperature industrial filtration into standard-temperature silo aeration applications. Cement manufacturers in India and Southeast Asia are adopting these constructions for their chemical inertness and extended service life. The shift is compressing replacement part revenue streams while elevating upfront equipment margins for suppliers with captive membrane production.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of traditional PTFE membrane binders used in European-manufactured aeration pads. Industrial processors in Germany and France now face specification gaps as legacy stock depletes and certified alternatives reach commercial scale. Food-grade material handlers are experiencing the most acute transition friction due to stricter migration testing requirements under EU 10/2011.
Leasing arrangements for complete pneumatic conveying systems are displacing component-level purchasing in mid-capacity Indian processing facilities. Maharashtra-based cement distributors and Gujarat chemical formulators increasingly contract for guaranteed discharge performance rather than owning aeration hardware. The model concentrates specification authority with system integrators and compresses direct pad manufacturer channel access in these states.
Aeration Pads Market Segmentation
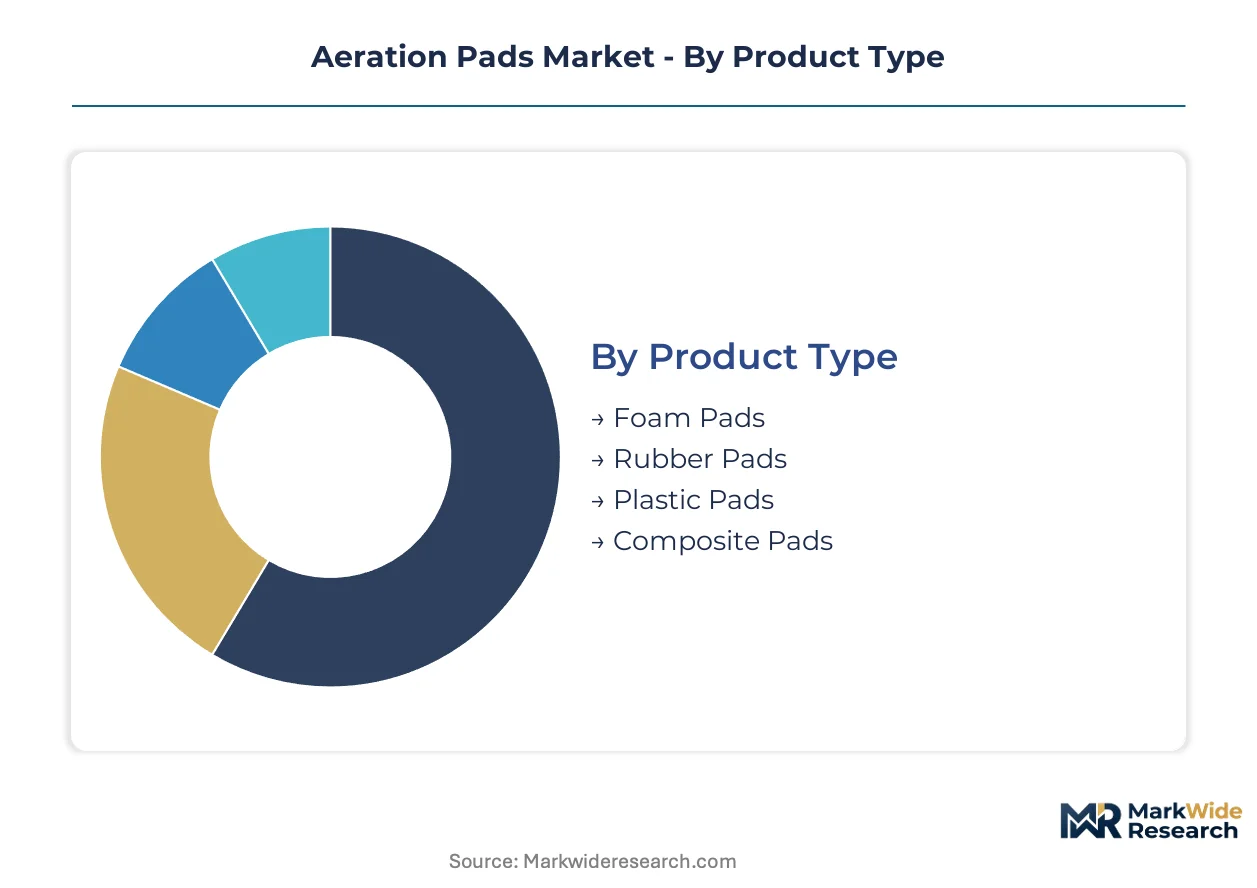
Aeration pad specifications diverge sharply across material handling intensity, regulatory exposure, and infrastructure permanence. Procurement patterns in bulk solids processing favor chemical-resistant constructions, while municipal wastewater operators prioritize energy-efficient membrane geometries.
Product Type:
Mature rubber and foam constructions anchor established silo discharge applications, while emerging composite formulations capture abrasive processing environments demanding extended service intervals.
- Composite Pads:PTFE-coated fiberglass and hybrid polymer laminates deliver chemical inertness against cement clinker and mineral acids. Demand concentrates in Maharashtra and Gujarat cement clusters where BIS-certified pneumatic equipment mandates material upgrades for continuous discharge reliability.
- Rubber Pads:Perforated elastomer constructions dominate standard-temperature silo applications through cost efficiency and established supply chains. European ATEX-certified processors favor these for explosion-proof specifications where membrane uniformity exceeds fluidization performance requirements.
- Foam Pads:Open-cell polyurethane structures serve light-duty horticultural and aquaculture aeration with low-pressure blower compatibility.
- Plastic Pads:Injection-molded polypropylene geometries target temporary installations and budget-constrained municipal retrofit programs.
Composite pads retain volume leadership in industrial bulk handling; composite constructions hold the steepest expansion curve as abrasive processing drives material upgrades.
Application:
Volume concentration tilts toward infrastructure-heavy verticals with regulatory compliance deadlines, while specialized horticultural deployments expand through precision agriculture adoption.
- Wastewater Treatment:Municipal facilities retrofit aging diffused aeration systems with low-pressure membrane pads to meet EPA effluent guidelines. Energy-efficiency benchmarking under EU Green Deal procurement specifications favors high-uniformity pad designs in German and French municipal tenders.
- Aquaculture:Dissolved oxygen management in intensive shrimp and finfish operations drives membrane aeration adoption across Southeast Asian coastal processing zones. Oxygen transfer efficiency requirements exceed standard industrial tolerances, favoring silicone-PTFE hybrid constructions.
- Horticulture:Greenhouse substrate aeration and hydroponic root zone oxygenation deploy foam and plastic pad configurations for controlled environment agriculture.
- Soil Aeration:Turf management and compacted soil remediation applications utilize removable pad installations for seasonal deployment patterns.
Wastewater treatment commands installed base dominance; aquaculture applications are climbing the fastest as protein demand intensifies coastal farming operations.
End User:
Procurement authority fragments across public tender processes and private capital allocation cycles, with municipalities facing the most compressed upgrade timelines.
- Municipalities:Public wastewater treatment operators navigate EPA consent decrees and infrastructure replacement bonds to fund aeration system retrofits. Procurement specifications increasingly mandate energy performance guarantees that favor integrated pneumatic system contracts over component-level purchasing.
- Commercial Growers:Controlled environment agriculture operators in the Netherlands and Spain specify food-grade membrane materials under EU 10/2011 migration testing protocols for hydroponic vegetable production.
- Farmers:Small-scale aquaculture and soil aeration deployments favor low-cost foam and plastic pad configurations through agricultural supply cooperatives.
- Landscapers:Seasonal turf aeration services utilize rental and leasing models for standalone pneumatic equipment with removable pad attachments.
Municipalities retain volume leadership through infrastructure replacement cycles; commercial growers gain share fastest as greenhouse acreage expands under climate-controlled production mandates.
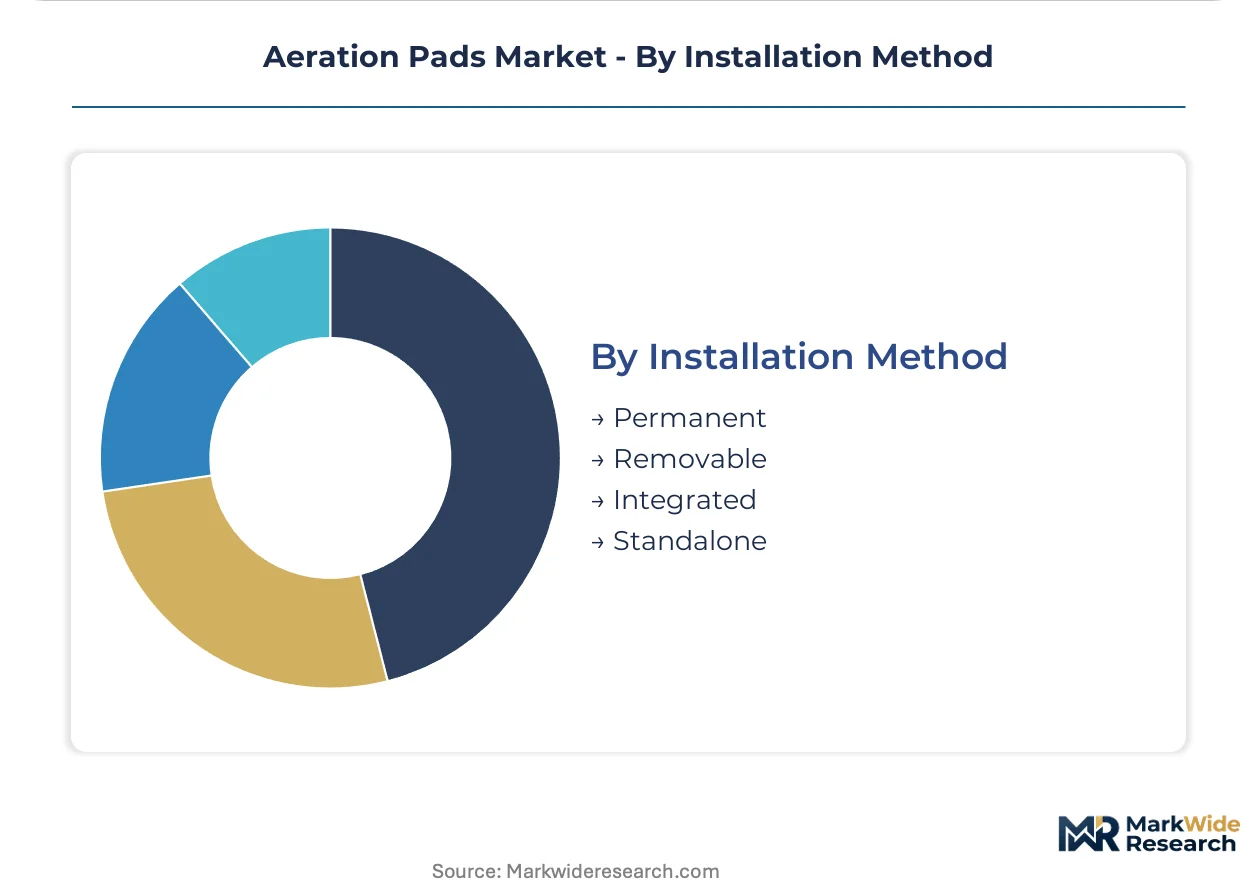
Installation Method:
Capital ownership preferences diverge between permanent infrastructure commitments and operational flexibility requirements, with leasing models reshaping mid-capacity processor access.
- Integrated:Silo-embedded aeration pads specified during original equipment manufacture ensure compressed air capacity sizing matches low-pressure, high-volume fluidization requirements. Cement manufacturers in India favor these configurations to prevent silo bridging in continuous discharge operations.
- Removable:Seasonal agricultural applications and leased pneumatic systems utilize quick-connect pad assemblies for equipment redeployment across multiple sites. Maharashtra-based chemical formulators increasingly contract for guaranteed discharge performance without hardware ownership.
- Permanent:Municipal wastewater basins and industrial silos specify welded or bolted pad installations for decades-long service intervals.
- Standalone:Mobile aeration units for emergency soil remediation and temporary aquaculture stocking deploy self-contained blower-pad combinations.
Integrated installations retain volume leadership in greenfield bulk handling; removable configurations are expanding most quickly through asset-light leasing penetration in Indian processing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cement distributors and wastewater treatment operators dominate procurement across major economies, with regulatory compliance timelines compressing upgrade cycles in industrial clusters. Regional demand concentrates where bulk solids processing and municipal infrastructure replacement intersect.
United States
EPA effluent guidelines and OSHA combustible dust standards drive municipal wastewater retrofits and silo safety upgrades. Municipal bond financing accelerates aeration system replacement in aging treatment facilities. The Gulf Coast petrochemical corridor generates sustained demand for explosion-proof pneumatic configurations.
Germany
EU Green Deal energy-efficiency benchmarks and REACH substance restrictions reshape municipal procurement specifications. ATEX directives enforce explosion-proof membrane standards in chemical processing applications. The Rhine-Ruhr industrial basin concentrates demand from cement and mineral processing operations seeking extended-service composite pads.
India
BIS certification requirements for pneumatic equipment force domestic material upgrades while cement manufacturers expand silo aeration deployment. Maharashtra and Gujarat bulk solids clusters generate replacement demand from construction and chemical sector operations. The 8-12 month BIS approval timeline disadvantages domestic suppliers against uncertified imports.
China
Dual carbon goals and GB standards for industrial energy efficiency accelerate wastewater treatment infrastructure modernization. Yangtze River Delta manufacturing clusters adopt fluidization systems for chemical and mineral powder handling. Coastal aquaculture operations in Fujian and Guangdong deploy membrane aeration for intensive shrimp farming.
Brazil
ANVISA food-grade material regulations and agricultural modernization programs expand controlled-environment agriculture aeration. São Paulo state cement and chemical processors retrofit silo discharge systems to reduce material bridging losses. The Southeast industrial corridor concentrates demand from bulk solids handling operations serving construction markets.
Aeration Pads Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure concentrates specification authority with system integrators offering guaranteed discharge performance contracts. Three archetypes dominate: vertically integrated silo equipment suppliers, membrane technology specialists, and regional pneumatic component fabricators. Competitive moves center on backward integration into captive membrane production and asset-light leasing model expansion.
Within the integrated equipment tier, WAMGROUP leverages its silo equipment portfolio to anchor European bulk solids markets. Solimar Pneumatics exemplifies the membrane-specialist archetype through its focus on food-grade material handling applications. Monitor Technologies LLC occupies a position among North American pneumatic monitoring and control specialists serving industrial processing facilities.
| Leading Market Players |
|---|
| WAMGROUP |
| Monitor Technologies LLC |
| Solimar Pneumatics |
| Xylem Inc |
| Sulzer Ltd |
| Evoqua Water Technologies |
| Aeration Industries International |
| Aqua Control |
| Aqua-Aerobic Systems |
| Others |
Value Network & Pricing Analysis
Fluoropolymer membrane feedstock volatility compresses manufacturer margins unpredictably while widening spreads between premium PTFE-laminate pads and standard rubber constructions, forcing procurement teams toward long-term offtake contracts with German and Italian component suppliers.
Pricing Analysis
Cost-plus contracts indexed to silicone and fluoropolymer resin benchmarks dominate bulk purchasing agreements between pad manufacturers and municipal wastewater operators. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified composite pads from BIS-compliant rubber constructions and unbranded foam alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with integrated system contracts commanding premiums over component sales. Margins are tightening due to REACH-driven reformulation costs in European manufacturing. Municipal procurement teams exhibit highest price sensitivity, while cement manufacturers in Maharashtra prioritize discharge reliability over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among German pneumatic equipment specialists and Italian membrane fabricators holding ATEX-certified capacity. Raw material sourcing draws from Chinese fluoropolymer resin producers, Indian silicone rubber compounders, and Belgian fiberglass substrate suppliers. Supply chain risk centers on single-source vulnerability for explosion-proof membrane specifications under EU directives. Distribution runs through system integrators offering guaranteed discharge performance contracts, displacing direct manufacturer channel access in Indian processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PTFE-coated fiberglass membrane migration from industrial filtration into silo aeration applications constitutes a material-science inflection that compresses replacement cycles and elevates upfront equipment margins for suppliers with captive membrane production.
For Market Incumbents: Pre-empt mechanical agitation substitution by embedding aeration pads into comprehensive pneumatic conveying system contracts with guaranteed discharge performance terms. Backward integration into captive PTFE membrane production defends margin position against fluoropolymer feedstock volatility. Accelerate BIS certification investment for composite material formulations to maintain competitive parity against uncertified imports in Indian bulk solids clusters.
For New Entrants and Emerging Players: Pursue leasing model expansion for mid-capacity Indian processors in Maharashtra and Gujarat seeking asset-light pneumatic infrastructure access. Food-grade dairy powder and infant formula silo applications present underpenetrated white space where hybrid silicone-PTFE laminates command contamination-sensitive premiums. Partner with regional system integrators rather than competing for direct channel access.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors membrane-specialist targets with food-grade certification depth over commodity rubber pad fabricators. Long-term viability rests on captive polymer formulation capabilities and EU regulatory compliance infrastructure. Monitor REACH substance restriction implementation timelines as inflection indicators for competitive repositioning among European-manufactured pad suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Captive PTFE-laminate supply secures margin control against fluoropolymer resin price volatility. |
| BIS Certification Investment | Domestic Indian approval accelerates product launches against uncertified import competition. |
| Leasing Model Expansion | Asset-light contracts concentrate specification authority with system integrators in Maharashtra-Gujarat clusters. |
| Food-Grade Membrane Development | EU 10/2011-compliant silicone-PTFE hybrids penetrate dairy powder contamination-sensitive applications. |
| EU Green Deal Alignment | Energy-efficiency benchmarking creates specification advantages in German and French municipal procurement. |
Research Methodology
Operator-level perspectives from silo maintenance directors, pneumatic system procurement leads at cement manufacturers, wastewater treatment plant engineers, and aftermarket service heads anchored the qualitative base. Secondary validation drew from BIS pneumatic equipment standards documentation, EPA effluent guideline filings, EU ATEX directive compliance databases, and customs trade records for fluoropolymer membrane imports. Bottom-up demand modeling across installation methods and end-user segments triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, application intensity, regulatory exposure tier, and regional compliance cluster. CAGRs derived from fitted growth curves incorporating BIS certification timeline compression effects and REACH-driven material reformulation costs. Industry-specific forecast inputs included municipal infrastructure replacement bond issuance patterns and cement sector capacity expansion announcements in Indian bulk solids clusters.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, municipal capital expenditure cycles, or cement demand trajectories would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timelines and material substitution elasticity. Quarterly review of BIS approval queue lengths and EU substance restriction enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market