
 AI Finance Market | 2026-2036
AI Finance Market Size, Share, and Industry Trends Forecast 2026-2036
AI Finance Market Insights
The performance gap between premium neural network infrastructure and commodity cloud-based tools is hardening. NVIDIA sustains dominance in GPU-accelerated training clusters for quantitative finance. Microsoft leverages Azure's financial services cloud to anchor enterprise AI deployments. JPMorgan Chase differentiates through proprietary natural language processing models for risk surveillance.
AI finance encompasses machine learning systems, predictive analytics engines, and neural network architectures purpose-built for capital allocation, credit scoring, and securities pricing. These platforms process structured market data and unstructured textual sources—regulatory filings, earnings transcripts, news sentiment—at latencies below ten milliseconds to support automated trading and real-time risk monitoring. Fraud detection and algorithmic trading applications command the largest revenue pools today, while customer insights segments show the steepest adoption curves among retail-facing institutions. Machine learning technology occupies the mature core of the market, whereas natural language processing implementations are expanding fastest across compliance and advisory workflows.
The SEC enforces disclosure standards for AI-driven investment recommendations, while the EU AI Act imposes risk-classification requirements on automated credit and insurance underwriting systems. FINRA examines algorithmic trading platforms for market manipulation vulnerabilities and model governance deficiencies. Stakeholders must weigh regulatory fragmentation against the operational cost of maintaining jurisdiction-specific compliance architectures.
Market Dynamics
Algorithmic trading infrastructure is compressing latency thresholds below ten milliseconds while regulators impose risk-classification mandates on automated decision systems, forcing institutions to rebuild compliance architectures around real-time model governance.
Growth Catalysts
- EU AI Act compliance mandates:Automated credit and insurance underwriting systems must now meet risk-tier documentation standards, driving institutional procurement of explainable AI platforms.
- GPU cluster deployment:Quantitative hedge funds and asset managers are expanding NVIDIA-accelerated training infrastructure to support neural network model refinement for securities pricing.
- Unstructured data processing:Natural language processing engines now parse regulatory filings and earnings transcripts at machine speed, creating demand for sentiment-to-signal pipelines.
Market Restraints
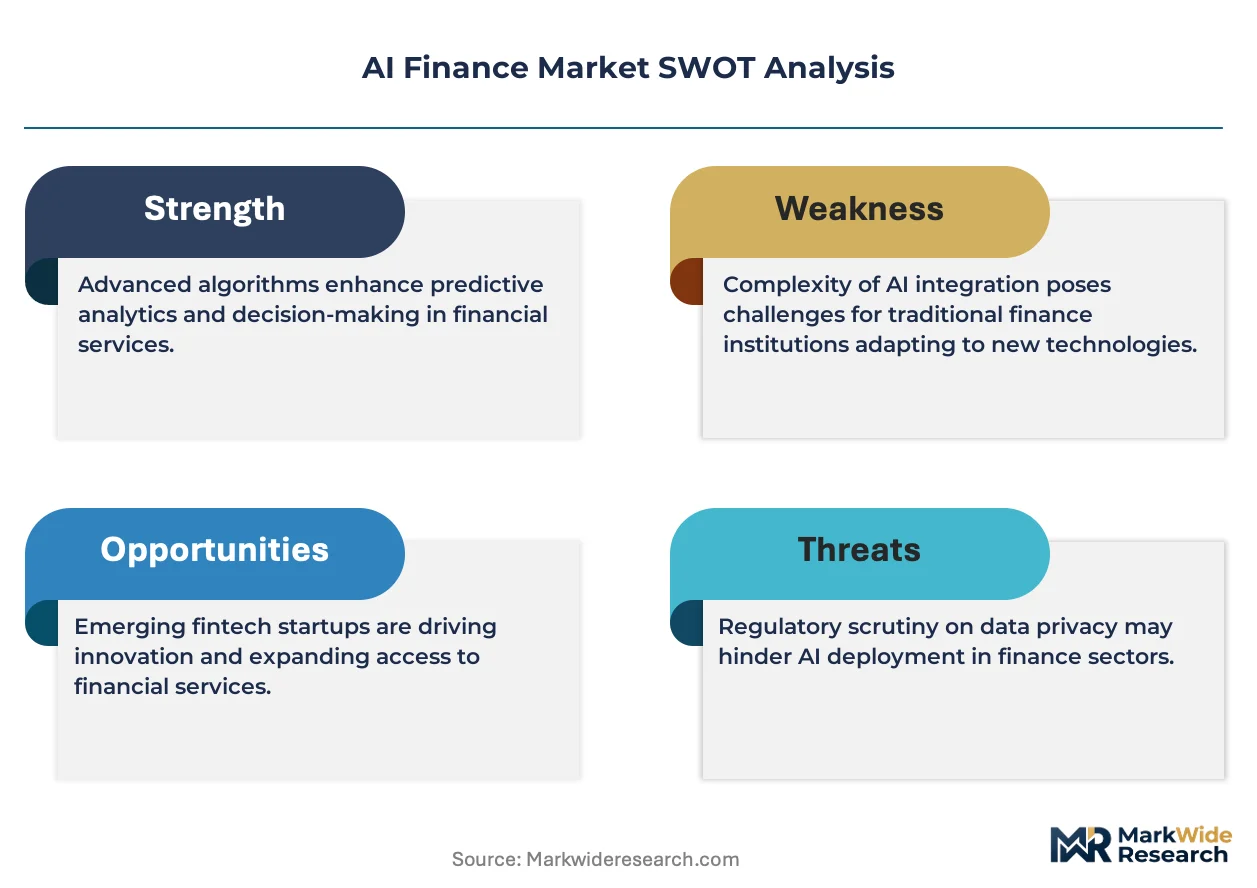
- Compute cost volatility:Cloud GPU pricing fluctuations and semiconductor supply constraints in Taiwan create unpredictable infrastructure scaling costs for mid-tier institutions.
- Regulatory fragmentation:Divergent SEC disclosure standards and EU AI Act risk classifications force parallel compliance architectures, multiplying operational overhead.
- Model interpretability limitations:Deep neural network opacity in credit decisions creates audit trail gaps that FINRA examination protocols flag as governance deficiencies.
Strategic Opportunities
- Wealth management advisory:Retail-facing institutions in Germany and France are deploying conversational AI for portfolio guidance, opening whitespace before saturation.
- Real-time risk surveillance:Proprietary natural language processing models for fraud detection represent an underexploited capability gap in commercial banking.
- Quantum-classical hybrid:Convergence of quantum annealing with classical optimization is compressing portfolio construction timelines for systematic strategies.
Industry Challenges
- Quantitative talent scarcity:Institutions face acute shortages of machine learning engineers with domain expertise in fixed income derivatives and market microstructure.
- Legacy system integration:Core banking platforms built on COBOL architectures resist API-native connectivity, delaying real-time data pipeline deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Finance Market |
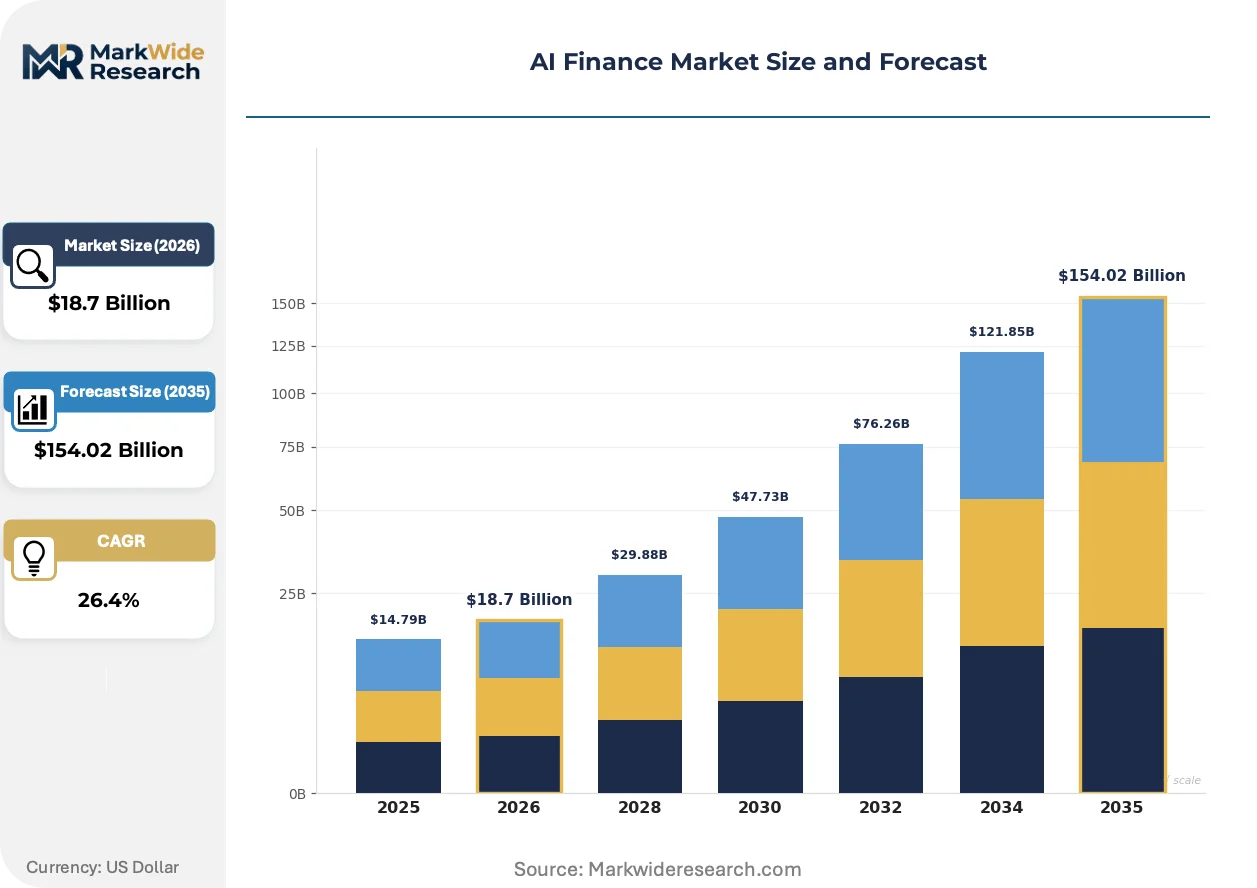
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
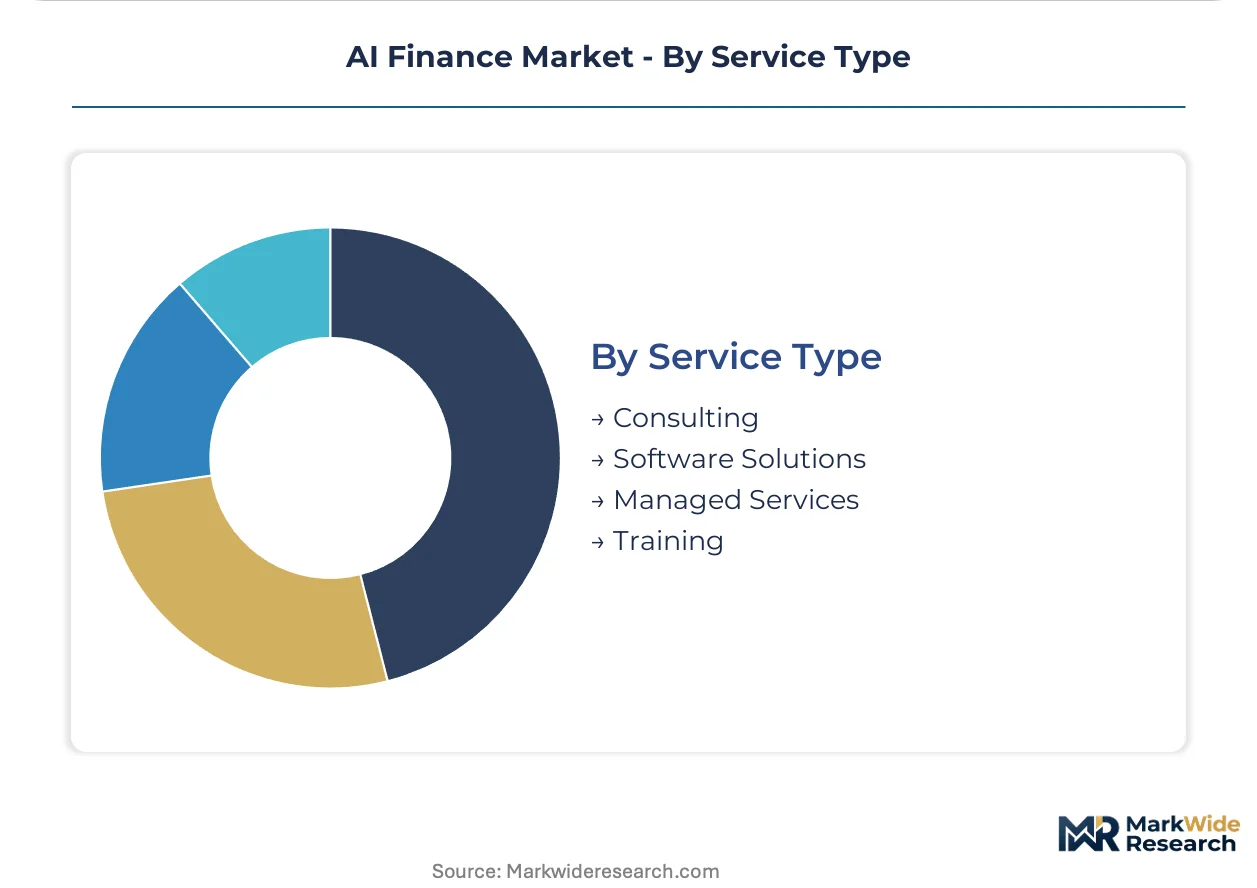
| Segmentation | Application: Fraud Detection, Risk Assessment, Algorithmic Trading, Customer Insights Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Neural Networks Customer Type: Retail Investors, Institutional Investors, Hedge Funds, Credit Unions Service Type: Consulting, Software Solutions, Managed Services, Training |
| Companies Covered | NVIDIA, Alphabet (Google), Microsoft, JPMorgan Chase, SAP, Upstart, Kavout, Brighterion, HighRadius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Finance Market Trends and Innovations
Transformer-based architectures are displacing recurrent neural networks in time-series forecasting, while regulatory pressure on model explainability is reshaping vendor selection criteria across institutional procurement functions.
Foundation models specialized for financial reasoning are integrating retrieval-augmented generation to ground outputs in real-time market data rather than static training corpora. Asset managers with systematic strategies are adopting these architectures for earnings call analysis and macro narrative tracking. The technology is integrating structured price feeds with unstructured textual sources, compressing the latency between information arrival and position adjustment.
The EU AI Act risk-classification framework is mandating human oversight protocols for automated credit decisions above defined thresholds. Banks in France and Germany must now maintain model cards documenting training data provenance and performance drift metrics. Retail lending divisions are responding by segmenting workflow automation—full automation for low-risk tiers, human-in-the-loop for elevated risk classes.
Institutional procurement of AI infrastructure is fragmenting between cloud-native deployments and on-premise GPU clusters based on data sovereignty requirements. European asset managers facing GDPR constraints are repatriating model training from hyperscale clouds to domestic colocation facilities. This pattern is most visible in Switzerland and Luxembourg, where regulatory scrutiny of cross-border data flows has intensified vendor evaluation criteria.
AI Finance Market Segmentation
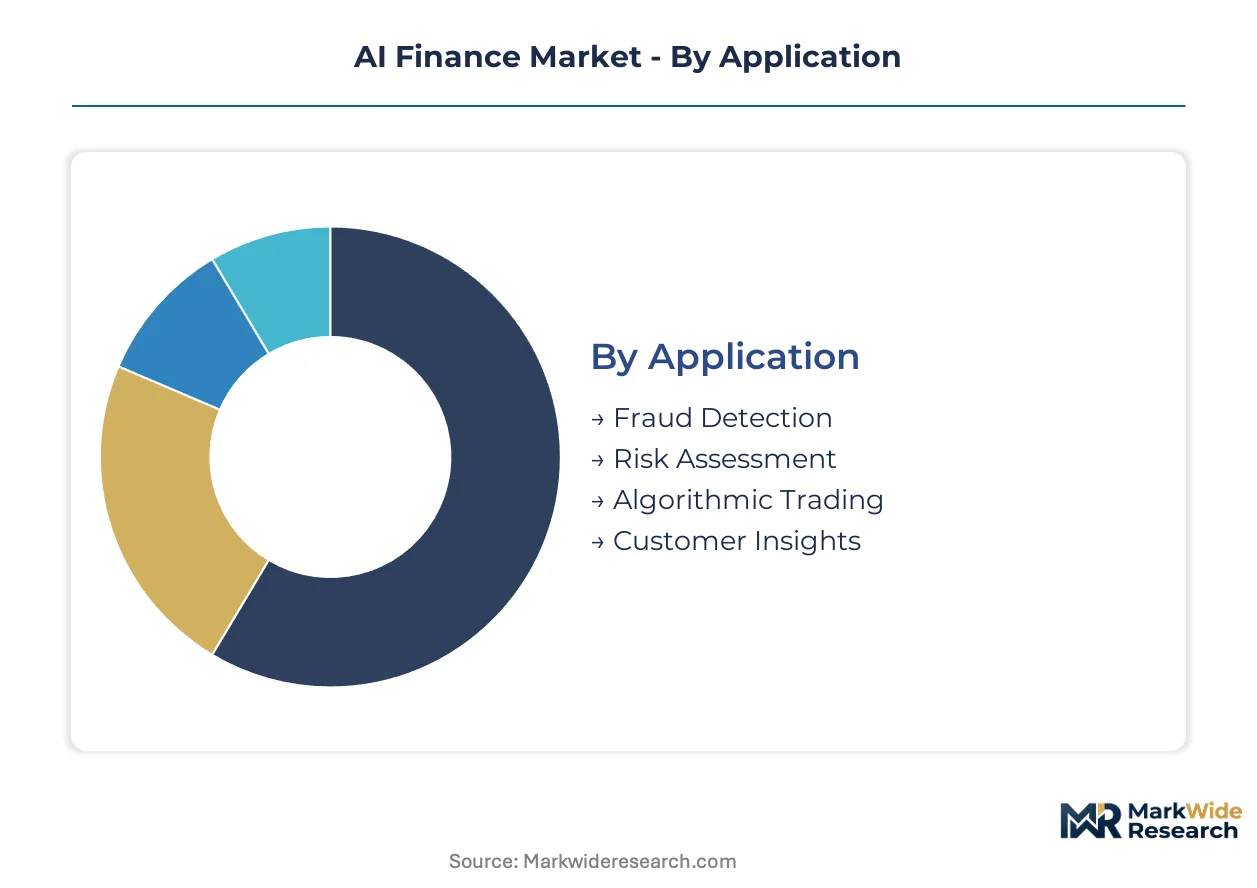
Segmentation reveals how AI finance infrastructure fragments across deployment models and buyer sophistication. Each dimension exposes distinct procurement patterns, integration complexity, and margin structures that shape vendor positioning.
Application:
Standalone platforms dominate high-frequency use cases, while embedded modules integrate into core banking workflows for compliance-heavy functions.
- Fraud Detection:Real-time transaction monitoring systems deploy pattern recognition across payment networks. Demand concentrates in commercial banking divisions facing regulatory examination pressure from FINRA and the EU AI Act.
- Algorithmic Trading:Latency-sensitive execution engines process market signals below ten milliseconds. Quantitative hedge funds in the United States drive procurement of GPU-accelerated infrastructure for model refinement.
- Risk Assessment:Credit scoring models with explainable output requirements.
- Customer Insights:Behavioral analytics for portfolio personalization and churn prediction.
Volume placements concentrate in fraud detection; the faster expansion belongs to customer insights.
Technology:
Cost tiers separate mature toolkits from emerging architectures demanding specialized talent and infrastructure investment.
- Machine Learning:Established supervised and unsupervised learning frameworks for structured data analysis. Institutional asset managers deploy these for factor modeling and portfolio optimization with predictable compute budgets.
- Natural Language Processing:Transformer-based architectures parse earnings transcripts and regulatory filings at machine speed. European banks facing EU AI Act documentation mandates are expanding sentiment-to-signal pipeline investments.
- Predictive Analytics:Statistical forecasting engines for scenario planning and stress testing.
- Neural Networks:Deep learning architectures requiring substantial training infrastructure.
Machine learning commands the largest installed base; neural networks are climbing the fastest on systematic strategy demand.
Customer Type:
Buyer sophistication determines whether procurement favors turnkey SaaS or custom infrastructure builds.
- Institutional Investors:Asset managers and pension funds with dedicated quantitative research teams. These buyers commission bespoke model development and maintain on-premise GPU clusters for data sovereignty.
- Hedge Funds:Systematic strategies with latency-sensitive execution requirements. Firms in the United States and United Kingdom lead deployment of NLP-driven macro narrative tracking systems.
- Retail Investors:Individual traders accessing AI through brokerage-embedded robo-advisory tools.
- Credit Unions:Smaller depositories with limited technical staff purchasing managed services.
Institutional investors generate the highest contract values; hedge funds are gaining share fastest on alternative data integration.
Service Type:
Margin profiles diverge sharply between labor-intensive advisory and scalable software delivery.
- Software Solutions:Licensed platforms for model development, deployment, and monitoring. Vendors price by data volume or compute consumption, capturing recurring revenue from expanding institutional AI footprints.
- Managed Services:Outsourced model operations including retraining, drift detection, and regulatory documentation. European banks under EU AI Act pressure are procuring external model governance support.
- Consulting:Advisory engagements for AI strategy and compliance architecture design.
- Training:Workforce development programs for quantitative finance skill building.
Software solutions anchor revenue stability; managed services are expanding most quickly on regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wall Street's quantitative trading corridors in Manhattan and Jersey City concentrate the densest deployments of GPU-accelerated AI infrastructure for securities pricing. Algorithmic execution engines process market signals below ten milliseconds from these facilities. Regulatory pressure from the SEC on model governance is reshaping procurement patterns across institutional investors.
United States
Hedge funds in Connecticut and asset managers in Boston drive demand for transformer-based architectures parsing earnings transcripts. The SEC enforces disclosure standards for AI-driven investment recommendations. Chicago's derivatives exchanges host co-located inference clusters for latency-sensitive futures pricing.
United Kingdom
Systematic strategies in the City of London expand natural language processing for macro narrative tracking. The Financial Conduct Authority examines algorithmic trading platforms for market manipulation vulnerabilities. Edinburgh's asset management cluster is repatriating model training to domestic colocation facilities under data sovereignty pressure.
Germany
Commercial banks in Frankfurt procure explainable AI platforms for automated credit decisions. The EU AI Act imposes risk-tier documentation standards on underwriting systems. Munich's wealth management divisions deploy conversational AI for portfolio guidance ahead of saturation.
Switzerland
Private banks in Zurich and Geneva face intensified scrutiny of cross-border data flows under GDPR constraints. FINMA guidelines on model governance are tightening audit trail requirements. The country's asset managers are expanding domestic GPU clusters rather than relying on hyperscale clouds.
Singapore
Sovereign wealth funds and family offices drive procurement of predictive analytics for alternative data integration. The Monetary Authority of Singapore mandates stress testing for AI-driven trading systems. The city's fintech corridor is attracting vendor regional headquarters for Southeast Asian market access.
AI Finance Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the AI finance stack. NVIDIA and cloud hyperscalers anchor the infrastructure tier with GPU clusters and financial services clouds, while specialized fintech vendors occupy application-layer niches. The market structures around three archetypes: semiconductor foundries supplying training hardware, platform vendors offering model development environments, and institutional incumbents building proprietary systems. Competitive moves concentrate on strategic partnerships between hardware suppliers and cloud providers, plus vertical integration by major banks into in-house model development.
Within the semiconductor archetype, NVIDIA anchors GPU-accelerated training infrastructure for quantitative strategies. Microsoft Corporation exemplifies the platform vendor position through Azure's financial services cloud deployments. JPMorgan Chase & Co. represents institutional incumbent vertical integration, maintaining proprietary natural language processing models for risk surveillance. These three occupy positions spanning the hardware-to-application value chain.
| Leading Market Players |
|---|
| NVIDIA |
| Alphabet (Google) |
| Microsoft |
| JPMorgan Chase |
| SAP |
| Upstart |
| Kavout |
| Brighterion |
| HighRadius |
| Others |
Pricing and Supply Chain Analysis
Quantitative hedge funds in the United States and United Kingdom anchor procurement volumes for AI finance infrastructure, concentrating pricing power among GPU-accelerated training cluster vendors and cloud hyperscalers. This buyer concentration rewards subscription-based SaaS pricing for model development platforms while penalizing transactional pricing for one-off consulting engagements.
Pricing Analysis
Value-based pricing tied to alpha generation or risk reduction outcomes dominates institutional AI finance procurement. Three-tier pricing structure across premium, standard, and economy levels separates bespoke model development from API-native cloud deployments and open-source toolkits. Price differentiation rests on latency thresholds and data sovereignty certifications. Pricing pressure stems from cloud GPU pricing volatility and semiconductor supply constraints. Retail-facing institutions exhibit highest price sensitivity; systematic hedge funds with dedicated quant teams show lowest sensitivity.
Supply Chain Analysis
Machine learning engineer scarcity in Taiwan and South Korea constrains GPU cluster deployment timelines for financial institutions. Taiwan, the United States, and China concentrate advanced semiconductor manufacturing for training hardware. NVIDIA accelerators, high-bandwidth memory modules, and specialized cooling systems constitute critical input dependencies. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through direct enterprise sales teams and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act imposes risk-tier documentation standards that create a cost-of-compliance moat favoring incumbent banks with established model governance infrastructure over capital-constrained entrants.
For Market Incumbents: Extend proprietary NLP model capabilities into real-time risk surveillance workflows before commercial vendors close the capability gap. Deepen backward integration into GPU cluster ownership in Switzerland and Luxembourg to satisfy data sovereignty requirements under GDPR constraints. Fortify audit trail documentation to preempt FINRA examination flags on model interpretability limitations.
For New Entrants and Emerging Players: Launch via managed services partnerships with mid-tier European banks struggling with EU AI Act compliance documentation. Target wealth management advisory whitespace in Germany and France before conversational AI saturation. Emphasize explainable AI platforms as the differentiated go-to-market angle for automated credit decisions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor managed services providers with established EU AI Act compliance expertise in Frankfurt and Paris. Long-term viability hinges on regulatory complexity expansion rather than pure technology differentiation. Monitor GPU pricing volatility as the inflection signal for infrastructure cost compression opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Model Development | JPMorgan Chase's NLP risk surveillance demonstrates competitive differentiation through in-house capability. |
| GPU Cluster Repatriation | Swiss and Luxembourg asset managers are shifting training workloads from hyperscale clouds to domestic colocation. |
| Explainable AI Platform Launch | European banks under EU AI Act pressure require documented training data provenance and performance drift metrics. |
| Managed Services Partnership | Mid-tier institutions lacking quantitative talent are outsourcing model governance and retraining operations. |
| Quantum-Classical Hybrid Investment | Systematic strategies are compressing portfolio construction timelines through quantum annealing convergence. |
Research Methodology
Document review covered SEC enforcement actions, EU AI Act implementation guidance, and FINRA examination priorities, complemented by interviews with quantitative research heads at asset managers, compliance officers at European commercial banks, GPU infrastructure procurement leads, and fintech platform engineers. Secondary validation drew from NVIDIA financial disclosures, Microsoft Azure capex reports, hyperscaler earnings calls, and regulatory filing databases. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Cross-referencing historical deployment patterns against panel input from infrastructure vendors established the analytical framework across the modeling period. Segmentation dimensions included application type, technology maturity tier, customer sophistication level, and service delivery model. CAGRs derived from slope analysis of adoption curves and capacity expansion announcements. Forecast inputs incorporated GPU supply constraints and regulatory implementation timelines.
Semiconductor supply disruption, EU AI Act enforcement variance, and quantitative talent migration patterns are the dominant revision risks to the outlook. Forecasts reflect assumptions around continued regulatory fragmentation and cloud infrastructure scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Australia Fintech Market
FinTech
Autonomous Finance Market
FinTech
Japan AI in Fintech Market
FinTech
Financial Forecasting Software Market
FinTech
France AI in Fintech Market
FinTech
Malaysia Fintech Market
FinTech
AI in Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Finance Cloud Market
FinTech
North America AI in Fintech Market
FinTech
Digital Banking Platform Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
North America Fintech Market
FinTech
Financial Services Cloud Market
FinTech
Robo Advisory Market