
 North America Fintech Market | 2026-2036
North America Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fintech Market Analytics
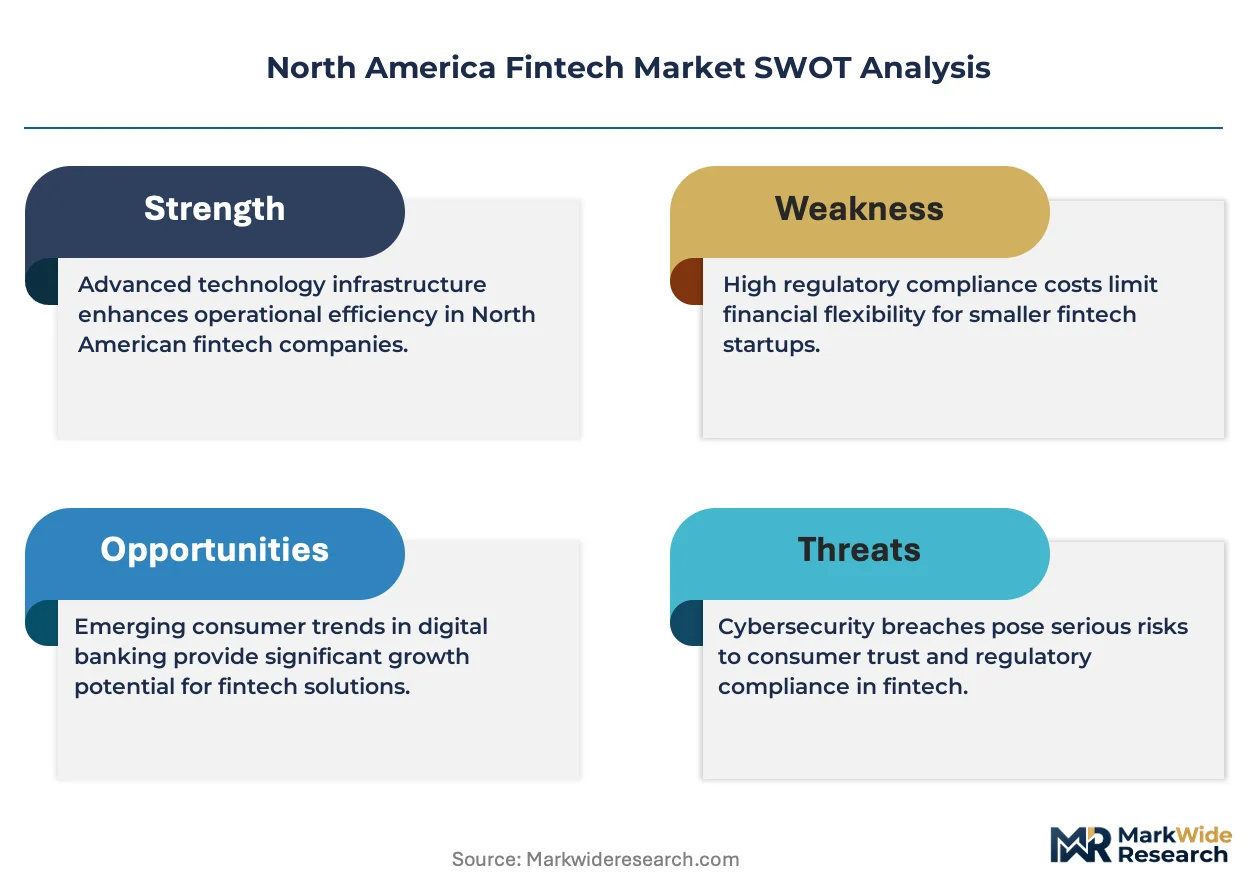
Healthcare provider payment workflows is realigning toward embedded finance platforms as hospitals and clinics seek integrated billing solutions. Stripe leverages its developer-centric infrastructure to dominate B2B payment orchestration across vertical SaaS providers. PayPal sustains consumer wallet share through its two-sided network density and merchant acquisition scale. SoFi anchors the lending segment with its diversified approach spanning student refinancing, personal loans, and chartered banking operations.
North America Fintech encompasses technology-enabled financial services delivered through software platforms, mobile applications, and API-based infrastructure that automate payments, lending, wealth management, and insurance distribution. These systems rely on real-time data pipelines, encryption protocols, and cloud-native architectures to process transactions, assess credit risk, and manage regulatory compliance across distributed computing environments. The payments service type leads in transaction volume and infrastructure maturity, while wealth management exhibits the fastest structural expansion as robo-advisory platforms democratize portfolio construction for retail investors. Cloud deployment dominates enterprise implementations due to elasticity requirements and regulatory data residency controls, though hybrid configurations gain traction among incumbent banks managing legacy core systems alongside modern API layers.
The US Consumer Financial Protection Bureau, SEC, and FINRA collectively shape market access through disclosure requirements, custody rules, and digital asset classification frameworks that determine which products reach retail versus accredited investors. State-level money transmitter licenses and the OCC's fintech charter pathway create a dual-layer compliance architecture that favors scaled platforms with dedicated regulatory operations. Stakeholders must monitor how the Federal Reserve's FedNow instant payment network alters competitive dynamics between bank-led and non-bank payment rails.
Market Dynamics
The US Consumer Financial Protection Bureau's open banking rulemaking is forcing platform operators to rebuild data infrastructure around consumer-permissioned portability, compressing competitive moats built on proprietary data silos.
Growth Catalysts
- FedNow instant payment rails:The Federal Reserve's real-time settlement network eliminates ACH latency for treasury applications, pulling corporate cash management onto modern infrastructure.
- Healthcare billing integration:Hospitals and specialty clinics are consolidating vendor relationships around platforms that embed payment, insurance verification, and patient financing into EHR workflows.
- API-first developer tooling:Vertical SaaS providers across property management and field services are white-labeling embedded finance to capture interchange revenue from their merchant bases.
Market Restraints
- Dual-layer licensing costs:Money transmitter licenses across 48 state jurisdictions impose fixed compliance overhead that scales poorly for sub-$50 million revenue platforms.
- Core banking system fragility:Tier-2 and community banks run on COBOL-era cores that resist API integration, limiting partnership velocity for fintech orchestrators.
- Talent scarcity in BSA/AML:The pool of compliance officers qualified for SAR filing and model risk management is concentrating in New York and San Francisco, inflating compensation 40% above regional medians.
Strategic Opportunities
- Canadian open finance lag:The Department of Finance's consumer-directed finance framework remains 24-36 months behind US rulemaking, creating first-mover whitespace for platforms with cross-border infrastructure.
- Credit union channel expansion:Over 4,900 US credit unions lack in-house digital lending capabilities and seek white-label partnerships for auto and personal loan origination.
- Tax-advantaged account convergence:HSA, FSA, and 529 platform operators are unifying fragmented account administration through single-API architectures that reduce employer switching costs.
Industry Challenges
- Core system migration timelines:Banks running FIS or Jack Henry legacy stacks face 18-24 month implementation cycles for real-time payment integration, delaying revenue recognition for fintech vendors.
- Model risk management documentation:The OCC's heightened expectations for AI-driven credit decisioning require explainability frameworks that most machine learning pipelines lack natively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fintech Market |
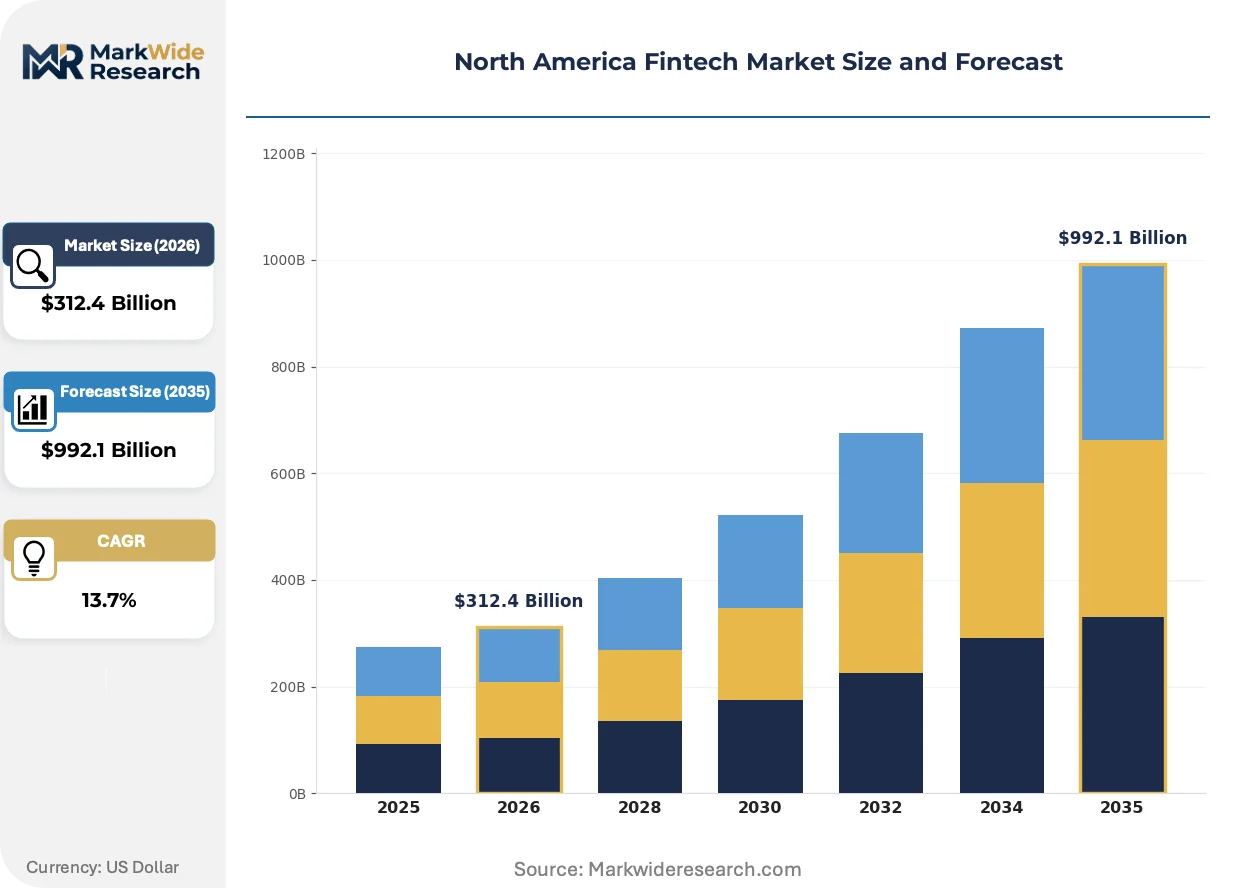
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $992.1 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payments, Lending, Wealth Management, Insurance Deployment: Cloud, On-Premises, Hybrid, Mobile Client Type: Consumers, SMEs, Corporates, Startups Technology: Blockchain, AI, Machine Learning, APIs |
| Companies Covered | Stripe, PayPal, Chime, SoFi, Square, Coinbase, Robinhood, Affirm, Intuit, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fintech Market Evolving Landscape
Embedded finance is collapsing the boundary between software and financial services, with vertical SaaS platforms capturing lending and payment margins that previously flowed to standalone banks. This structural shift is compressing the addressable market for traditional merchant acquirers while expanding total transaction volume.
Real-time account-to-account payment infrastructure is overtaking card networks for B2B disbursements, particularly in insurance claims and marketplace seller payouts. Mid-market enterprises in logistics and construction are adopting A2A rails to eliminate interchange drag on high-ticket transactions. This migration is forcing card networks to defend position through enhanced data analytics and working capital products rather than interchange economics alone.
The SEC's custody rule amendments for digital assets are reshaping infrastructure requirements for broker-dealers and investment advisers handling tokenized securities. Platforms must now demonstrate qualified custodian relationships or restrict certain asset classes to accredited investors only. Registered investment advisers in Texas and Florida are responding by consolidating vendor relationships around custody-integrated trading platforms that satisfy both state and federal registration requirements.
Healthcare providers are consolidating vendor relationships around platforms that unify patient estimation, payment plan enrollment, and revenue cycle analytics into single-workflow experiences. Specialty practices in dermatology and dental are abandoning standalone payment terminals for EHR-embedded checkout that reduces front-desk staffing requirements. This preference shift is most visible in the US Southeast, where private equity-backed practice aggregators are standardizing technology stacks across acquired locations.
North America Fintech Market Segmentation
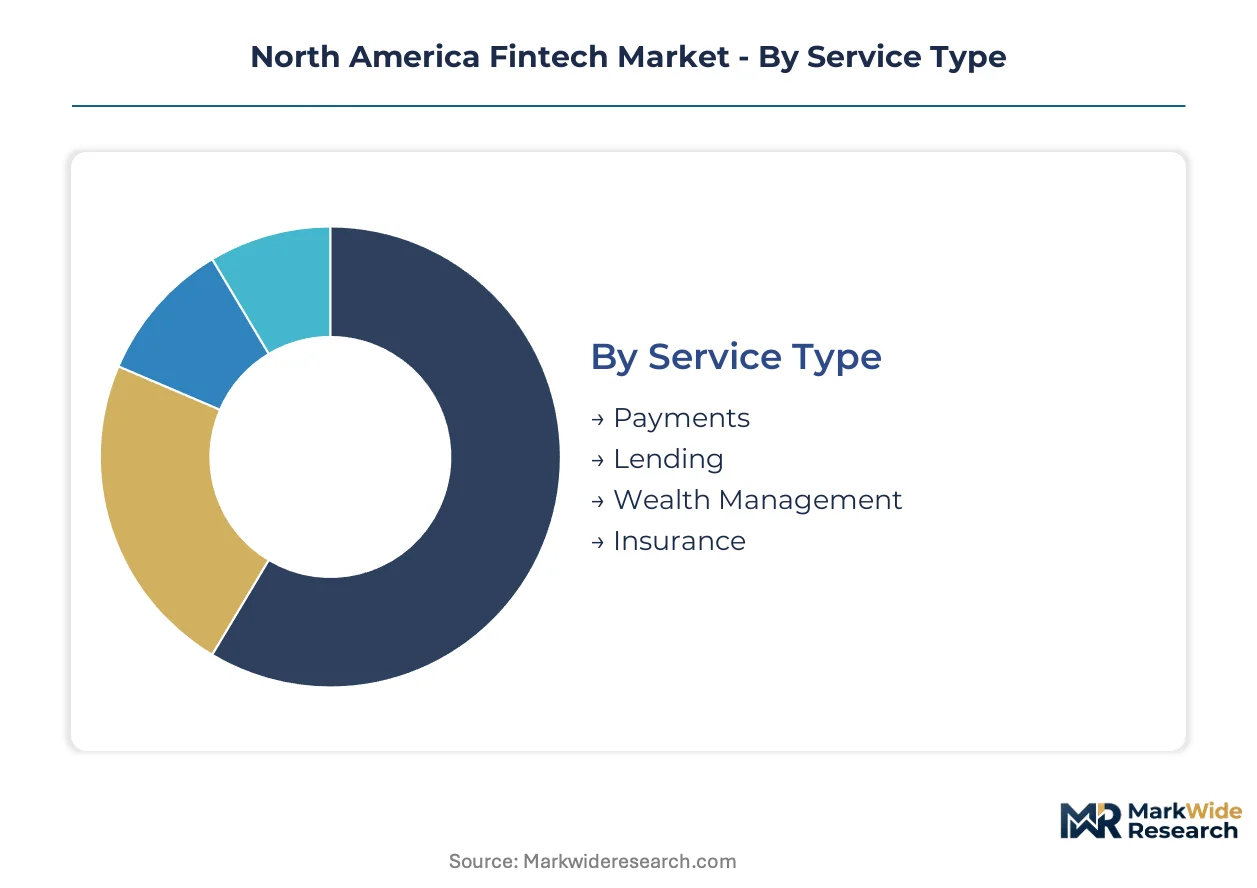
Segmentation in North American fintech reveals how infrastructure choices and buyer profiles reshape vendor selection criteria. Payment orchestrators, cloud-native lenders, and embedded finance platforms each serve distinct operational requirements across regulated financial services.
Service Type:
Platform selection hinges on transaction volume economics and regulatory exposure tolerance.
- Payments:Real-time settlement infrastructure dominates enterprise procurement, with FedNow integration becoming a non-negotiable requirement for treasury departments managing high-velocity disbursements. Demand concentrates among mid-market logistics firms in Texas and Georgia seeking to eliminate interchange drag on freight payments.
- Lending:Automated credit decisioning pipelines leverage alternative data sources for instant underwriting, though the OCC's model risk management expectations force explainability investments. Credit unions across the US Southeast are white-labeling these capabilities for auto and personal loan origination.
- Wealth Management:Robo-advisory platforms democratize portfolio construction through tax-loss harvesting and fractional share access.
- Insurance:API-based distribution embeds policy quoting into vertical SaaS workflows for property management and field services.
Payments leads on scale; Wealth Management leads on momentum.
Deployment:
Infrastructure architecture reflects data residency mandates and legacy system entanglement.
- Cloud:Elastic compute resources enable real-time fraud detection and instant scaling during peak transaction windows. US West Coast technology corridors favor multi-tenant configurations with FedRAMP authorization for federal contract eligibility.
- Hybrid:Tier-2 banks maintain sensitive customer data on-premises while exposing APIs through cloud gateways, bridging COBOL-era cores to modern orchestration layers. This configuration dominates among regional banks in the US Midwest managing 18-24 month core migration timelines.
- On-Premises:Complete data sovereignty satisfies state-level money transmitter audit requirements.
- Mobile:Native SDK deployment captures consumer wallet share through biometric authentication and push-to-pay functionality.
Cloud dominates current procurement; Hybrid shows steepest expansion trajectory among incumbent banks.
Client Type:
Revenue concentration and support intensity vary dramatically across buyer sophistication tiers.
- SMEs:Embedded finance adoption accelerates as vertical SaaS providers bundle payment acceptance, lending, and payroll into single-vendor relationships. Specialty clinics in Florida and dermatology practices in California consolidate vendor stacks to reduce front-desk staffing requirements.
- Corporates:Treasury departments demand API-first platforms with multi-bank connectivity and real-time cash visibility. Demand clusters among private equity-backed practice aggregators standardizing technology across acquired locations.
- Consumers:Two-sided network density drives wallet retention through merchant acceptance ubiquity.
- Startups:Developer-centric tooling and transparent pricing accelerate platform selection decisions.
SMEs represent the fastest-growing client segment; Corporates anchor average contract value.
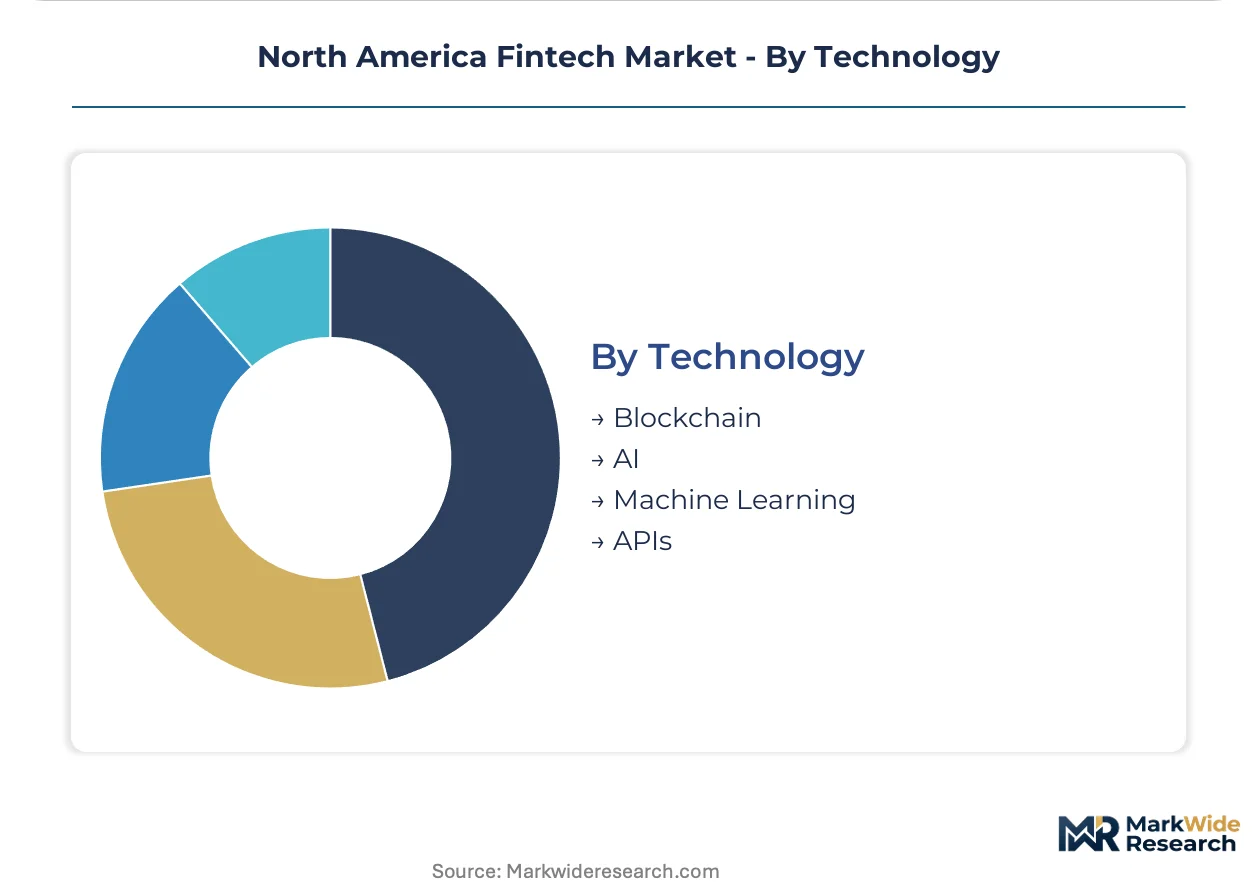
Technology:
Technical architecture choices determine compliance automation capabilities and partnership velocity.
- APIs:REST and GraphQL interfaces enable modular service composition, allowing vertical SaaS providers to embed financial products without building regulated infrastructure. Property management platforms in Arizona and field services software in Colorado leverage these for interchange revenue capture.
- AI:Natural language processing automates customer service and document extraction for mortgage underwriting. The SEC's custody rule amendments for digital assets force explainability frameworks that most machine learning pipelines lack natively.
- Blockchain:Distributed ledger infrastructure supports tokenized securities settlement and cross-border remittance corridors.
- Machine Learning:Predictive models optimize fraud detection thresholds and dynamic pricing for insurance products.
APIs command the broadest implementation base; AI attracts the steepest capital allocation for compliance automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US West Coast technology corridor spanning San Francisco and Seattle anchors North American fintech infrastructure development, with embedded finance platforms and real-time payment orchestrators clustering around venture capital concentration and cloud hyperscaler proximity.
United States
FedNow instant payment rails and healthcare billing integration drive enterprise procurement decisions among mid-market logistics firms and specialty clinic networks. The Consumer Financial Protection Bureau's evolving open banking rules compress competitive moats built on proprietary data silos. Demand concentrates in Texas and Georgia treasury departments seeking to eliminate interchange drag on freight payments.
Canada
The Department of Finance's consumer-directed finance framework remains 24-36 months behind US rulemaking, creating first-mover whitespace for cross-border infrastructure platforms. Credit unions across Ontario and British Columbia seek white-label digital lending partnerships for auto and personal loan origination. Toronto's financial district hosts the headquarters of several API-first payment orchestrators serving North American SME segments.
Mexico
Remittance corridor digitization and SME financial inclusion programs accelerate mobile wallet adoption among unbanked populations. The central bank's SPEI real-time payment system enables account-to-account transfers that reduce cash dependency. Mexico City fintech clusters focus on payroll-embedded lending products for informal sector workers.
US Southeast
Private equity-backed healthcare practice aggregators in Florida and Georgia standardize EHR-embedded payment and patient financing stacks across acquired dermatology and dental locations. State-level money transmitter licensing creates compliance overhead that favors scaled platforms with dedicated regulatory operations. Atlanta anchors regional demand for treasury automation among logistics and construction mid-market enterprises.
US Northeast
Chartered digital banks and robo-advisory platforms cluster in New York and Boston, drawn by concentrated compliance talent pools and proximity to institutional investor bases. The SEC's custody rule amendments for digital assets reshape infrastructure requirements for broker-dealers handling tokenized securities. Boston's wealth technology corridor specializes in tax-advantaged account convergence through single-API architectures.
North America Fintech Market Competitive Landscape
API-first platform expansion dominates the current competitive landscape as orchestrators embed financial services into vertical SaaS workflows. The vendor base stratifies across three tiers: developer-centric infrastructure providers, two-sided consumer networks, and chartered balance-sheet lenders. Strategic archetypes include payment rail specialists capturing interchange revenue, lending platforms leveraging alternative data for instant underwriting, and custody-integrated trading venues satisfying digital asset compliance requirements. M&A activity and strategic bank-fintech partnerships represent the dominant competitive moves reshaping market structure.
Within the infrastructure tier, Stripe exemplifies developer-centric payment orchestration through modular API architectures, while PayPal occupies a position as a two-sided network anchor sustaining consumer wallet density. SoFi represents the diversified lending archetype spanning student refinancing, personal loans, and chartered banking operations.
| Leading Market Players |
|---|
| Stripe |
| PayPal |
| Chime |
| SoFi |
| Square |
| Coinbase |
| Robinhood |
| Affirm |
| Intuit |
| Others |
Value Network & Pricing Analysis
FedRAMP authorization requirements gate cloud infrastructure access for federal fintech contracts, concentrating premium-tier pricing power among multi-tenant platforms with compliance certification while squeezing uncertified providers into commodity service tiers.
Pricing Analysis
Interchange revenue sharing between vertical SaaS platforms and embedded finance providers determines effective pricing tiers across the ecosystem. Three-tier pricing structure across premium API orchestration, standard payment facilitation, and economy merchant acquiring segments reflects FedNow integration depth and model risk management documentation quality. Cost compression in the economy tier intensifies because regional banks delay core system migrations, forcing vendors to absorb extended implementation timelines. SME clinics and field services platforms exhibit highest price sensitivity, while private equity-backed healthcare aggregators prioritize workflow integration over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from tier-1 banks require fintech orchestrators to maintain qualified relationships with at least two cloud hyperscalers for resilience certification. Infrastructure supply concentrates in the United States, Ireland, and Singapore data center corridors, with compute resources drawing from specialized chip architectures and encryption hardware modules. Talent pipelines for BSA/AML compliance officers present single-source vulnerability given geographic concentration in New York and San Francisco. Distribution runs through API marketplaces and direct enterprise sales teams serving vertical SaaS providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American fintech rests on automation of compliance documentation and consolidation of fragmented tax-advantaged account administration onto single-API architectures.
For Market Incumbents: Extend developer tooling depth to capture interchange revenue from property management and field services verticals before specialized orchestrators achieve API lock-in. Consolidate custody-integrated trading infrastructure to satisfy SEC digital asset amendments and restrict competitor access to accredited investor channels. Vertical integration into alternative data sourcing for credit decisioning protects against model risk management scrutiny from the OCC. For New Entrants and Emerging Players: The pricing gap between premium FedNow-integrated treasury platforms and economy ACH-dependent alternatives creates entry whitespace for hybrid solutions targeting mid-market logistics firms in Texas and Georgia. Canadian credit union white-label partnerships offer the most penetrable geography given regulatory lag against US open banking rules. Developer-centric documentation and transparent sandbox pricing accelerates platform selection against incumbent sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for API-first payment orchestrators because dual-layer state licensing costs create fixed overhead that scales poorly below $50 million revenue, favoring consolidation plays. Platforms with chartered bank partnerships and real-time settlement infrastructure anchor long-term viability through FedNow network effects. Watch for inflection where core banking system migration timelines compress from 18-24 months to sub-12 months, signaling vendor readiness acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Integration Partnership | Real-time settlement capability anchors treasury automation contracts with mid-market logistics enterprises in Texas and Georgia. |
| Healthcare EHR Embedding | Specialty clinic consolidation around unified billing workflows reduces front-desk staffing requirements across Florida dermatology practices. |
| Credit Union White-Label Expansion | Digital lending partnerships with 4,900 US credit unions capture auto and personal loan origination volume in underserved Southeast markets. |
| Cross-Border Infrastructure Buildout | Canadian consumer-directed finance lag creates 24-36 month first-mover advantage for platforms with Ontario and British Columbia presence. |
| Alternative Data Credit Pipelines | Instant underwriting capabilities satisfy credit union demand while building defensible moats against OCC model risk management requirements. |
Research Methodology
Bottom-up embedded finance adoption modeling reconciled against top-down payment infrastructure deployment tracking forms the analytical core of this study. Primary interviews with fintech platform CTOs, vertical SaaS product leads, credit union lending officers, healthcare revenue cycle directors, and regulatory compliance specialists combined with secondary validation from SEC filings, FedNow participation disclosures, CFPB rulemaking dockets, and cloud hyperscaler federal contract announcements. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Historical trendline analysis of payment volume migration from ACH to real-time rails informed projection frameworks across the modeling period. Segmentation dimensions include service type, deployment architecture, client sophistication tier, and technology stack composition. CAGRs derive from elasticity modeling of SME embedded finance penetration and corporate treasury automation cycles. Industry-specific forecast inputs incorporate FedNow network expansion timelines and state money transmitter licensing velocity.
Caveats apply where CFPB open banking rulemaking acceleration or FedNow fee structure revisions could materially shift the outlook. Deviation in core banking system migration timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
US AI in Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
China Fintech Market
FinTech
North America AI in Fintech Market
FinTech
India AI in Fintech Market
FinTech
Smart Finance Connectivity Market
FinTech
Wealthtech Solutions Market
FinTech
Fintech Cloud Market
FinTech
United States Fintech Market
FinTech
Smart Lending Platform Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Africa AI in Fintech Market
FinTech
Robo Advisory Market
FinTech
Micro-Investing Platform Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Lendtech Market