
 Lendtech Market | 2026-2036
Lendtech Market Size, Share, and Industry Trends Forecast 2026-2036
Lendtech Market Foresight
India's digital public infrastructure build-out is reshaping how unsecured credit reaches first-time borrowers. SoFi leverages its vertically integrated stack spanning origination, servicing, and deposit-taking to sustain margin compression in personal loans. Upstart competes through AI-native underwriting that incorporates employment history beyond FICO scores, while Klarna dominates buy-now-pay-later point-of-sale financing across European retail channels.
Lendtech encompasses digital platforms, algorithmic decision engines, and API-connected infrastructure that automate borrower acquisition, credit assessment, fund disbursement, and loan servicing with sub-second response times and machine-learning-driven risk pricing. Cloud-based deployment now leads platform architecture due to elastic scaling during origination surges and lower capital expenditure barriers for entrants. Peer-to-peer funding methods have matured into institutional capital channels, shifting margin pools toward balance-sheet lenders and away from retail-sourced platforms.
The Consumer Financial Protection Bureau shapes US disclosure requirements and fair-lending algorithms, while the EU AI Act imposes explainability mandates on automated credit decisions in Europe. India's RBI fintech regulatory sandbox permits controlled testing of alternative data models without full licensing. Stakeholders must monitor how divergent data localization rules and algorithmic accountability standards fragment platform architecture decisions across operating jurisdictions.
Market Dynamics
Open banking APIs and real-time credit scoring algorithms are compressing loan origination timelines from days to seconds, forcing traditional lenders to rebuild their technology stacks or cede market position to cloud-native competitors.
Growth Catalysts
- India's RBI fintech regulatory sandbox:Controlled testing environments permit alternative data models without full licensing, accelerating first-time borrower onboarding.
- Small enterprise digital onboarding:Branch-based origination is collapsing as automated KYC and document verification slash acquisition costs for micro-business lending.
- Embedded finance APIs:Point-of-sale lending integration with retail e-commerce platforms is capturing transaction-level data for instant credit decisions.
Market Restraints
- Algorithmic explainability mandates:The EU AI Act imposes documentation burdens on automated underwriting, increasing compliance overhead for European operations.
- Data localization requirements:Divergent cross-border data rules fragment platform architecture, forcing redundant infrastructure deployment in each operating jurisdiction.
- Institutional capital channel concentration:Peer-to-peer funding maturity has shifted margin pools toward balance-sheet lenders, squeezing marketplace revenue models.
Strategic Opportunities
- US regulatory sandboxes and fintech charters:Accelerated licensing pathways are lowering barriers for digital-first lending entrants in the world's largest consumer credit market.
- Employment history beyond FICO scores:AI-native underwriting incorporating alternative data sources is expanding addressable borrower pools previously excluded by traditional scoring.
- Cloud-native servicing infrastructure:Elastic scaling capabilities enable sub-second response times during origination surges without fixed capital expenditure commitments.
Industry Challenges
- Machine learning model governance:Fair-lending algorithm audits demanded by the Consumer Financial Protection Bureau require specialized compliance talent scarce in financial services.
- Legacy core banking integration:Real-time API connectivity with incumbent deposit-taking systems demands expensive middleware development and extended implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lendtech Market |
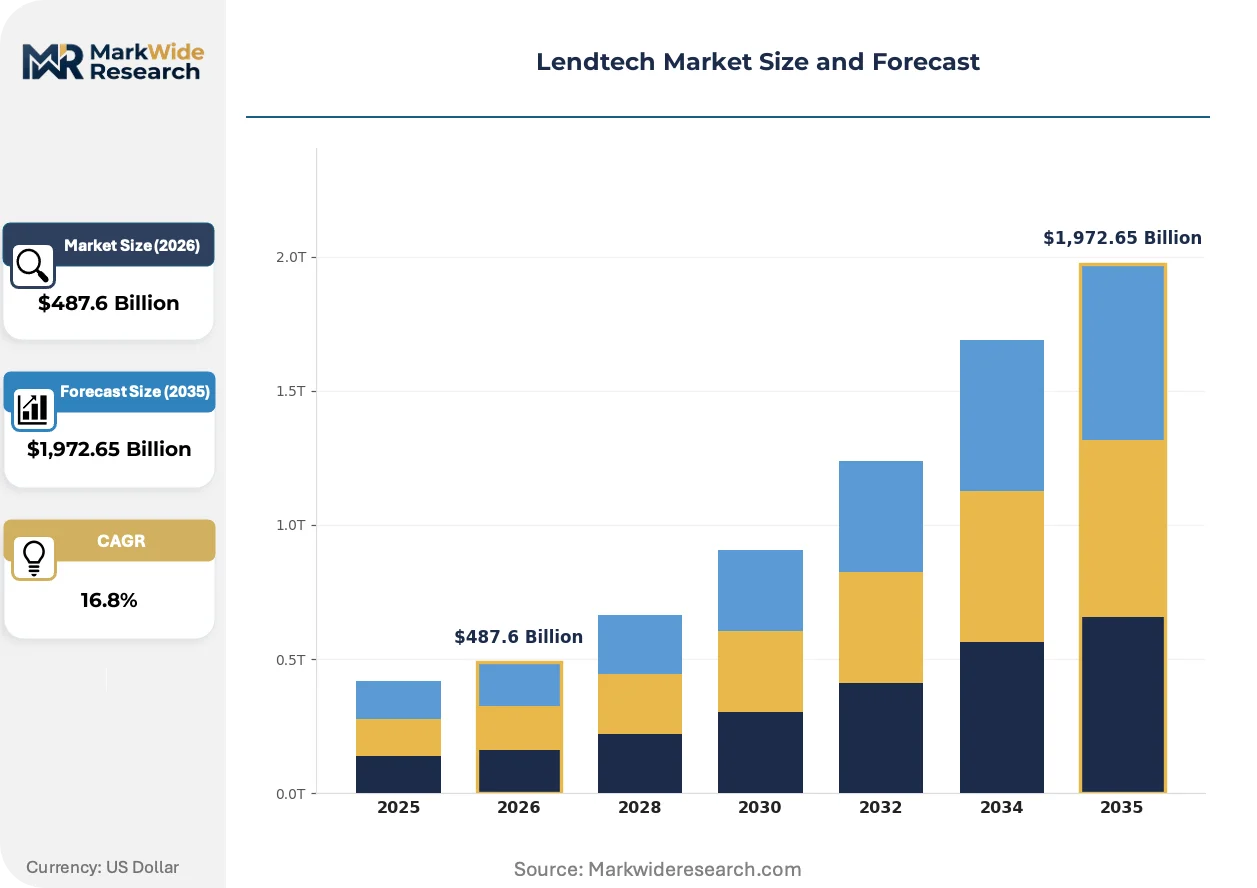
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,972.65 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Loans, Business Loans, Mortgage Loans, Auto Loans Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Platforms Customer Type: Individuals, Small Enterprises, Corporations, Nonprofits Funding Method: Equity Financing, Debt Financing, Peer-to-Peer, Crowdfunding |
| Companies Covered | Nelito Systems Ltd., Affirm, SoFi, LendingClub, Upstart, Funding Circle, Prosper Marketplace, Klarna, Finastra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lendtech Market Shifts & Advancements
Credit decisioning infrastructure is fragmenting across specialized technology layers, with distinct competitive advantages emerging in data aggregation, algorithmic scoring, and embedded distribution rather than monolithic platform dominance.
Alternative data fusion is hybridizing traditional credit bureau files with cash-flow analytics from bank account connections and employment verification APIs. Mid-market lenders are adopting these capabilities fastest, seeking differentiation against both incumbent banks and venture-backed challengers. This convergence is compressing the information advantage previously held by established scoring agencies.
The EU AI Act's explainability mandates are forcing automated underwriting systems to generate human-interpretable decision rationales. Lenders serving European markets must retrofit black-box models with interpretable feature attribution, increasing development costs but reducing regulatory enforcement exposure. Consumer credit segments with higher denial rates face the steepest compliance retrofit requirements.
Buyers of lending technology are unbundling procurement across best-of-breed origination, servicing, and collections modules rather than accepting integrated suites. Regional banks and credit unions are driving this fragmentation, selecting specialized vendors for each function. This pattern is most pronounced in the United States, where core banking vendor lock-in has historically constrained technology refresh cycles.
Lendtech Market Segmentation
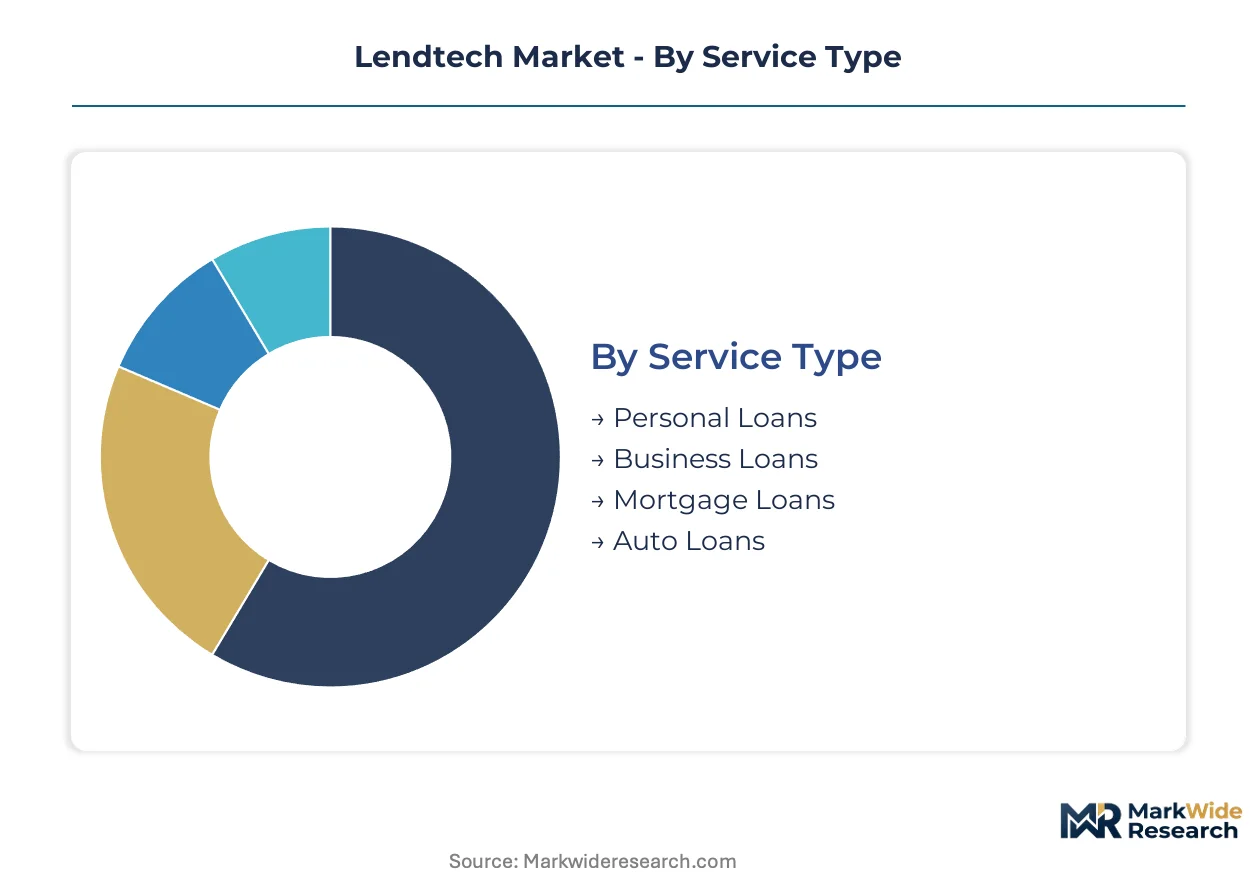
Segmentation in lendtech reveals how risk pricing, infrastructure costs, and regulatory exposure vary across borrower profiles and technology architectures. Platform operators configure their stacks differently depending on which combination of service type, deployment mode, customer base, and capital structure they target.
Service Type:
After-sales service intensity varies sharply across loan products, with mortgage platforms requiring sustained servicing relationships over decades while personal loan operators optimize for minimal post-disbursement contact.
- Personal Loans:Unsecured credit products with algorithmic underwriting powered by alternative data feeds from payroll APIs and bank account aggregators. Demand concentrates among US fintech challengers competing on sub-minute approval speeds.
- Business Loans:Working capital and term financing products incorporating real-time cash-flow analytics from accounting software integrations. Small enterprises in India drive fastest expansion as digital onboarding replaces branch-based origination for micro-business credit.
- Mortgage Loans:Long-tenure secured products requiring extensive documentation verification and regulatory compliance layers.
- Auto Loans:Asset-backed financing with vehicle telematics enabling usage-based risk adjustments and collateral monitoring.
By volume, personal loans lead. By growth pace, business loans are expanding most quickly.
Deployment:
Capital expenditure requirements and scalability constraints divide deployment architectures, with cloud-native platforms capturing venture funding while incumbent banks defend on-premises installations.
- Cloud-Based:Elastic infrastructure enabling sub-second response times during origination surges without fixed hardware commitments. US regulatory sandboxes accelerate licensed activity for cloud-native entrants.
- On-Premises:Dedicated hardware installations serving institutions with stringent data residency mandates or legacy core banking dependencies.
- Hybrid:Split architectures processing sensitive data locally while leveraging cloud compute for non-critical workloads.
- Mobile Platforms:Smartphone-native distribution reaching first-time borrowers through app-based onboarding and document capture.
Cloud-based deployment dominates new platform launches. Mobile platforms are gaining share fastest among unbanked population segments.
Customer Type:
Acquisition economics and lifetime value calculations shift dramatically across borrower sophistication levels, from thin-file individuals to treasury-managed corporations.
- Individuals:Consumer borrowers assessed through AI-native underwriting incorporating employment history beyond traditional credit scores.
- Small Enterprises:Micro-businesses previously excluded from formal credit due to lack of collateral or audited financials. Automated KYC and document verification slash acquisition costs for this segment.
- Corporations:Large borrowers with complex capital structure needs requiring relationship-managed credit facilities and covenant monitoring.
- Nonprofits:Mission-driven organizations with irregular cash flows demanding specialized repayment structuring.
Individuals represent the largest addressable base. Small enterprises show the steepest expansion trajectory as digital infrastructure penetrates informal economies.
Funding Method:
Margin pool distribution and balance sheet risk exposure hinge on how platforms source capital, with institutional channels displacing retail-sourced funding.
- Equity Financing:Venture and growth equity backing platform development before revenue scale, common among US and European challengers.
- Debt Financing:Warehouse lines and securitization facilities from institutional lenders enabling balance-sheet lending at scale.
- Peer-to-Peer:Retail investor matching platforms that have matured into institutional capital channels, squeezing marketplace revenue models.
- Crowdfunding:Community-based capital pools for niche or impact-focused lending propositions with limited scale.
Debt financing underpins the largest origination volumes. Equity financing is climbing the fastest among pre-profitability platforms in emerging markets.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment concentrates in jurisdictions offering regulatory clarity for algorithmic underwriting and open banking infrastructure. The United States, India, Germany, United Kingdom, and Brazil each present distinct licensing pathways and data governance frameworks that shape platform architecture decisions.
United States
Demand from fintech challengers and regional banks drives cloud-native platform adoption. The Consumer Financial Protection Bureau enforces fair-lending algorithm audits under fair credit reporting statutes. Silicon Valley and New York City host the densest clusters of venture-backed lending infrastructure providers competing on sub-minute approval speeds.
India
First-time borrower onboarding through smartphone-native distribution is expanding addressable credit pools. The Reserve Bank of India's fintech regulatory sandbox permits controlled testing of alternative data models without full licensing. Mumbai and Bangalore anchor the largest concentrations of digital lending platforms integrating with the country's digital public infrastructure stack.
Germany
Mid-market lenders are unbundling procurement across specialized origination and servicing modules. The EU AI Act imposes explainability mandates on automated credit decisions, increasing compliance overhead. Frankfurt's financial technology corridor hosts incumbent banks retrofitting black-box models with interpretable feature attribution for European market access.
United Kingdom
Open banking API adoption is compressing origination timelines for personal and business loan products. The Financial Conduct Authority oversees disclosure requirements and conduct standards for algorithmic underwriting. London's fintech cluster dominates balance-sheet lending models that have displaced peer-to-peer funding channels.
Brazil
Embedded finance APIs are capturing transaction-level data for instant credit decisions at point-of-sale. The central bank's regulatory framework governs data localization and consumer protection in digital lending. São Paulo anchors the primary concentration of platforms serving thin-file borrowers previously excluded from formal credit systems.
Lendtech Market Competitive Landscape
Vertically integrated full-stack lenders and specialized infrastructure providers split the market based on balance-sheet risk appetite and technology depth. Consolidation pressures favor scaled platforms with captive deposit bases or institutional funding relationships. Three archetypes dominate: balance-sheet lenders originating and holding loans, marketplace platforms matching borrowers to institutional capital, and pure-technology vendors licensing decisioning engines. Competitive dynamics center on M&A activity targeting servicing capabilities and strategic partnerships embedding lending APIs into retail commerce channels.
Within the balance-sheet lender tier, SoFi and Upstart exemplify divergent approaches to underwriting differentiation, while Klarna occupies a position anchoring point-of-sale financing across European retail networks. Affirm represents the embedded finance archetype integrating directly with e-commerce checkout flows. LendingClub and Funding Circle sit within the institutional capital channel segment that has matured beyond peer-to-peer origins. These named entities illustrate how geographic origin and capital structure archetype determine competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Nelito Systems Ltd. |
| Affirm |
| SoFi |
| LendingClub |
| Upstart |
| Funding Circle |
| Prosper Marketplace |
| Klarna |
| Finastra |
| Others |
Supply & Pricing Matrix
Undercapacity in cloud-native infrastructure across Southeast Asian data centers is compressing margins for platform operators while forcing balance-sheet lenders to absorb higher compute costs into origination pricing. This utilization squeeze simultaneously elevates supplier bargaining power for elastic scaling services and intensifies pricing competition among lenders competing on sub-second approval speeds.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for automated underwriting platforms serving European markets, forcing compliance cost layering that separates premium interpretable-model offerings from standard black-box deployments. Three-tier pricing structure across premium, standard, and economy levels reflects algorithmic audit depth, API response time guarantees, and geographic data residency coverage. Cost compression in the standard tier is intensifying because mid-market lenders are unbundling procurement across specialized vendors rather than accepting integrated suites. Small enterprises show the steepest price sensitivity as automated KYC slashes acquisition costs and enables competitive rate shopping.
Supply Chain Analysis
Extended payment terms from institutional capital providers now stretch to 90-120 days for warehouse line securitization facilities, squeezing working capital for balance-sheet lenders. Cloud infrastructure supply concentrates in the United States, India, and Ireland, drawing from specialized data center operators, API connectivity providers, and machine-learning compute platforms. Single-source vulnerability in real-time credit scoring algorithms creates concentration risk for platforms dependent on narrow alternative data feeds. Distribution runs through embedded finance APIs integrated at point-of-sale, direct-to-consumer mobile applications, and white-label partnerships with regional banking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across origination, servicing, and collections modules is creating specialist niches as regional banks abandon monolithic platform suites. This unbundling pattern rewards vendors with deep capability in single layers rather than breadth across the stack.
For Market Incumbents: Build captive deposit bases as the defensive moat against margin compression in personal loan origination. Acquire specialized servicing capabilities to deepen retention economics over loan lifecycles. Balance-sheet lenders face direct threat from AI-native challengers competing on employment-history underwriting beyond FICO scores. Prioritize backward integration into cloud-native infrastructure to control sub-second response time guarantees during origination surges. For New Entrants and Emerging Players: Build out thin-file borrower segments in Brazil and India where digital public infrastructure enables first-time credit access without traditional collateral. White-space concentration sits in small enterprise working capital products with real-time cash-flow analytics from accounting software integrations. Go-to-market execution should anchor on embedded finance API partnerships with retail e-commerce platforms capturing transaction-level data for instant decisions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across balance-sheet lending models as institutional funding channels mature and peer-to-peer margin pools evaporate. Long-term viability favors platforms with vertically integrated stacks spanning origination through servicing and deposit-taking. Target acquisition profile centers on specialized decisioning engine vendors with EU AI Act-compliant interpretable models. Watch regulatory sandbox expansion velocity as the inflection signal for jurisdictional entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Integration | Captures transaction-level data at point-of-sale for instant credit decisions in retail e-commerce. |
| Alternative Data Model Certification | Secures RBI sandbox approval for employment-history underwriting beyond traditional credit scores in India. |
| Cloud-Native Servicing Infrastructure | Enables elastic scaling during origination surges without fixed hardware commitments across US regulatory sandboxes. |
| Interpretable Model Retrofit | Generates human-readable decision rationales satisfying EU AI Act explainability mandates for European market access. |
| Balance-Sheet Lending Scale-Up | Shifts margin pools from marketplace platforms toward institutional capital channels with warehouse line securitization. |
Research Methodology
Desk research of regulatory filings, open banking API documentation, and cloud infrastructure capex disclosures preceded structured interviews with chief technology officers at lending platforms, risk officers at institutional capital providers, and compliance leads navigating EU AI Act implementation. Primary fieldwork with platform engineers and embedded finance partnership directors validated secondary findings on API connectivity economics. SEC filings, RBI sandbox participant lists, and European Banking Authority guidance documents anchored bottom-up segmentation sizing against top-down market aggregation.
Forecast assumptions held regulatory sandbox expansion rates and open banking API adoption curves within observed historical patterns across the analysis window. Segmentation modeling incorporated service type, deployment architecture, customer sophistication tier, and funding method as core dimensions. CAGRs derived from elasticity-adjusted origination volume projections and pricing trend analysis. Alternative data penetration rates and real-time credit scoring algorithm deployment timelines served as industry-specific demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated full-stack lenders or hyperscaler-backed challengers would shift outcomes. Macroeconomic contraction in consumer credit, algorithmic accountability enforcement beyond current EU AI Act scope, or fragmentation of data localization rules would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Canada AI in Fintech Market
FinTech
Fintech Lending Market
FinTech
Finance Cloud Market
FinTech
Wealthtech Solutions Market
FinTech
Generative AI in Fintech Market
FinTech
Fintech Cloud Market
FinTech
China Fintech Market
FinTech
Europe Fintech Market
FinTech
North America AI in Fintech Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Global Saas Spend Management Software Market
FinTech
Financial Services Cloud Market
FinTech
France BNPL Market
FinTech
Russia AI in Fintech Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Supply Chain Finance Market