
 Account Checking Software Market | 2026-2036
Account Checking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Account Checking Software Market Insights
EU Digital Operational Resilience Act (DORA) compliance deadlines is shifting procurement priorities toward audit-ready reconciliation infrastructure. Broadridge leverages its custody banking network to dominate enterprise-grade deployments. SS&C anchors its position through fund administration specialization. BlackLine differentiates via continuous accounting workflows that reduce period-end bottlenecks.
Account checking software automates financial transaction matching, exception identification, and balance certification across enterprise ledgers, typically processing millions of records daily through rule engines and machine learning algorithms. Cloud-based deployment leads segment growth as banks retire legacy mainframe reconciliation jobs. Financial institutions represent the deepest margin pool due to regulatory pressure for same-day certification. Web platforms compete with integrated systems for mid-market share where ERP connectivity determines switching costs.
SEC disclosure rules, EU DORA, and FCA operational resilience requirements collectively mandate demonstrable control over financial data integrity. These frameworks shape product roadmaps by requiring immutable audit trails and real-time exception alerting. Stakeholders must monitor how open banking API standards reshape data ingestion architectures and vendor lock-in dynamics.
Market Dynamics
Cloud-native reconciliation architectures are displacing on-premise mainframe installations as financial institutions confront transaction volume spikes and real-time certification mandates from regulators.
Growth Catalysts
- EU DORA compliance deadlines:Operational resilience mandates are forcing banks to replace batch-processed reconciliation with continuous monitoring systems that provide immutable audit trails.
- Real-time payment rails:FedNow and SEPA Instant adoption is generating sub-second settlement data that legacy matching engines cannot process, accelerating demand for modern platforms.
- Open banking API proliferation:Standardized data ingestion protocols are reducing integration friction and enabling multi-bank aggregation for corporate treasury departments.
Market Restraints
- Legacy system entrenchment:Cobol-based reconciliation jobs running on IBM mainframes represent sunk costs exceeding replacement budgets at regional banks.
- Data residency requirements:GDPR localization rules and divergent national cloud sovereignty laws are fragmenting vendor deployment architectures across European jurisdictions.
- Talent scarcity in specialized domains:Shortages of engineers fluent in both financial accounting rules and distributed systems engineering are elongating implementation timelines.
Strategic Opportunities
- Embedded finance reconciliation:Non-bank fintechs offering banking-as-a-service lack internal reconciliation expertise, creating white space for outsourced platform provision.
- Carbon accounting convergence:Scope 3 emissions tracking requirements are extending reconciliation workflows to environmental data streams, opening adjacent module sales.
- India's digital public infrastructure:Account Aggregator framework and UPI transaction volumes are generating reconciliation demand among domestic non-banking financial companies.
Industry Challenges
- Multi-ERP integration complexity:Enterprises running SAP, Oracle, and Workday simultaneously face data model incompatibilities that prolong implementation cycles.
- Certification timeline compression:SOX and PCI-DSS audit windows are shrinking from quarterly to monthly, straining exception resolution workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Account Checking Software Market |
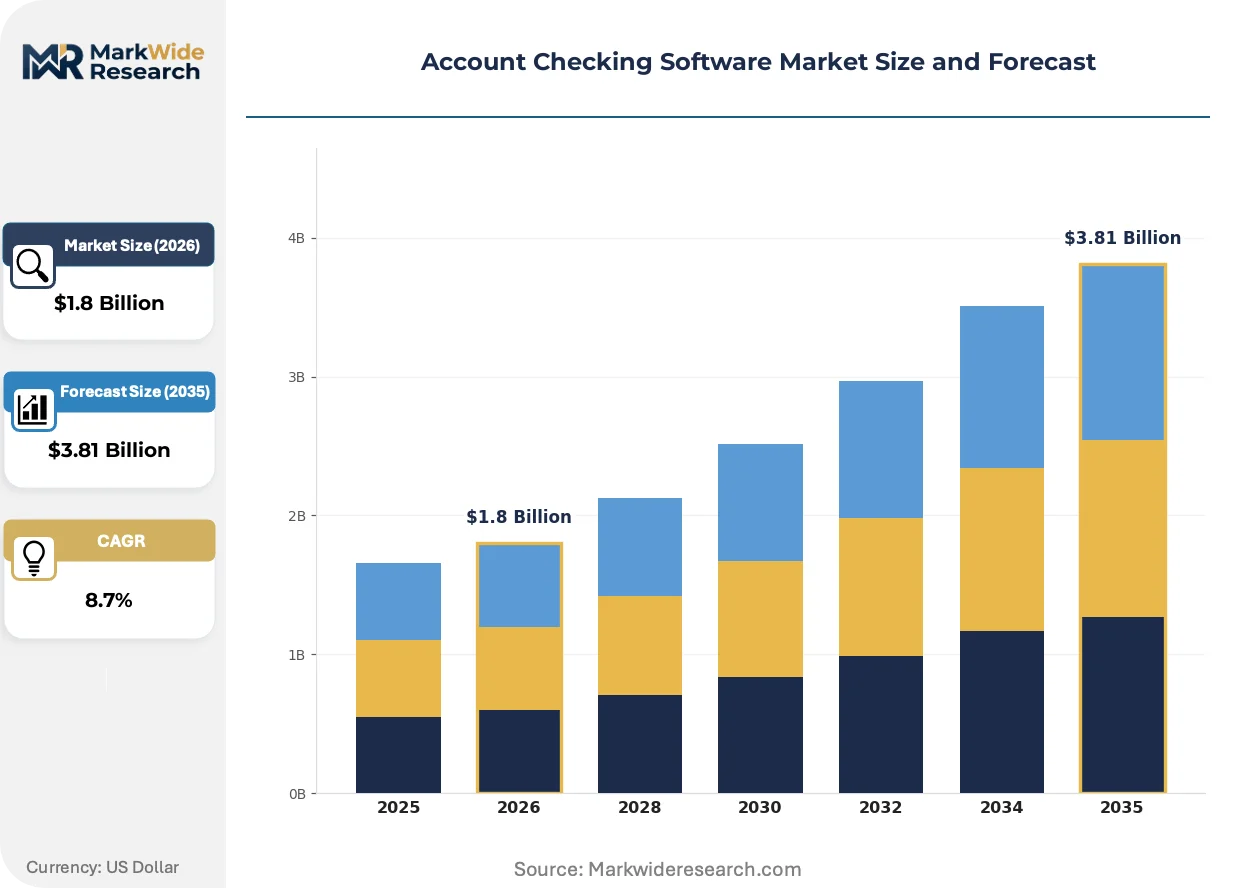
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Consumers, Small Businesses, Enterprises, Financial Institutions Solution: Mobile Apps, Desktop Software, Web Platforms, Integrated Systems Customer Type: Retail Customers, Corporate Clients, Non-profits, Government Entities |
| Companies Covered | Broadridge, AutoRek, ReconArt, SmartStream, Oracle, SS&C, Adra, BlackLine, Fiserv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Account Checking Software Market Trends and Innovations
Machine learning matching algorithms are compressing exception resolution from hours to minutes, while regulatory pressure for immutable audit trails is reshaping vendor roadmaps toward blockchain-verified certification.
Natural language processing is overtaking rule-based exception classification in high-volume transaction environments. Tier-one custody banks are deploying NLP engines to parse unstructured payment references and SWIFT message fields that rigid regex patterns fail to match. This capability is overtaking traditional deterministic approaches in markets where reference data quality varies across correspondent networks.
SEC climate disclosure rules are mandating granular traceability for sustainability-linked financial instruments. Asset managers must now reconcile ESG data vendor feeds against portfolio holdings with the same rigor applied to cash positions. Fund administrators in the United States are responding by embedding sustainability data validation modules directly into reconciliation workflows.
Treasury departments are consolidating vendor relationships from point solutions to integrated financial operations platforms. Mid-market enterprises previously running separate reconciliation, cash forecasting, and payment tools are demanding unified suites with native ERP connectivity. This consolidation pattern is most pronounced in the United Kingdom, where open banking APIs have reduced switching costs between platform providers.
Account Checking Software Market Segmentation
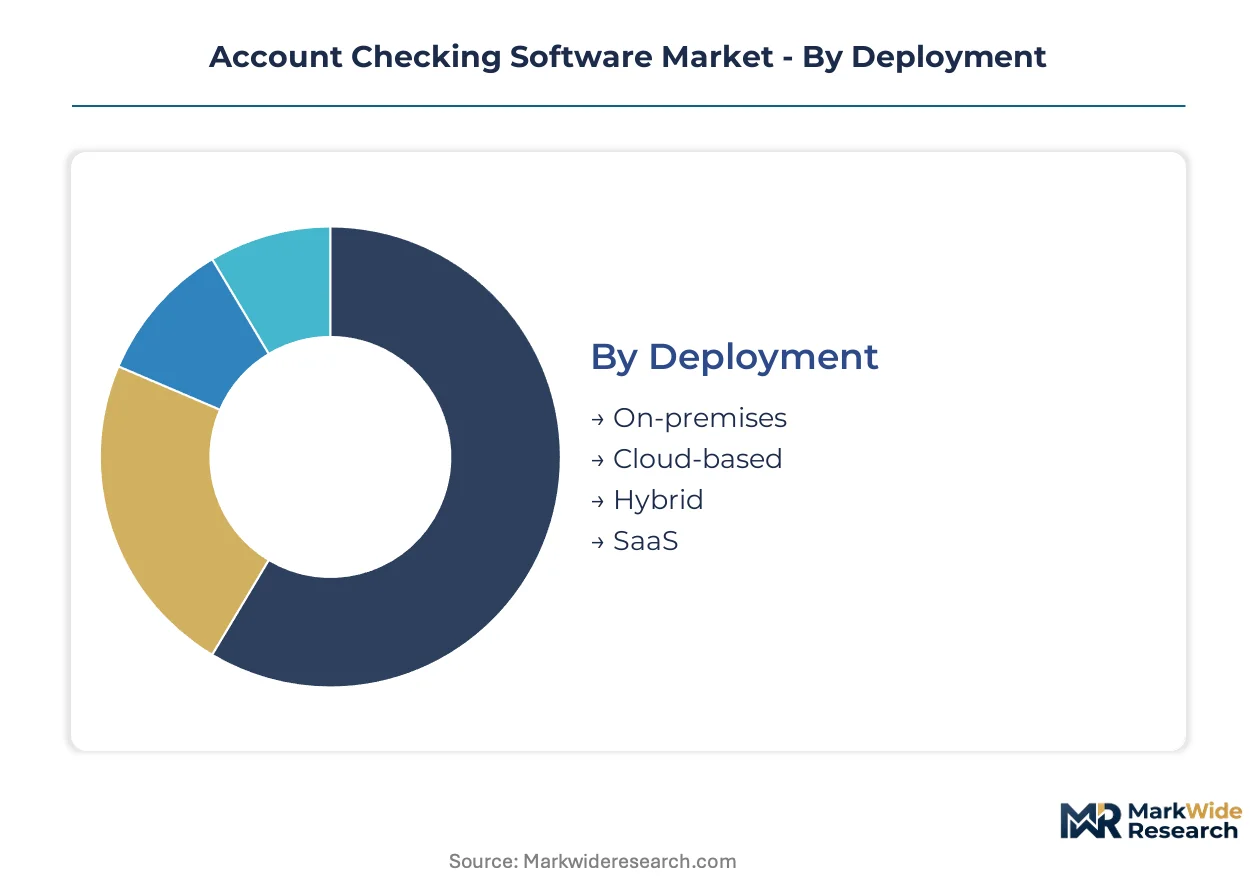
Deployment architecture determines total cost of ownership and implementation timelines for account checking software. Financial institutions weigh data sovereignty requirements against elasticity needs when selecting infrastructure models. End-user scale and solution delivery mechanism further refine vendor positioning across price-performance tiers.
Deployment:
Cloud-based configurations demand the lowest upfront capital outlay, while on-premises installations require substantial data center investment and dedicated operations staff.
- Cloud-based:Multi-tenant architectures with automatic scaling handle transaction volume spikes without provisioning delays. Banks in Germany and the United Kingdom favor this model to satisfy GDPR localization through EU-region hosting while avoiding mainframe maintenance overhead.
- On-premises:Dedicated infrastructure within institutional firewalls supports air-gapped environments for classified financial data. United States defense credit unions and certain Swiss private banks mandate this deployment to satisfy national security and banking secrecy frameworks.
- Hybrid:Sensitive matching operations remain local while exception analytics shift to cloud resources. Regional banks with uneven transaction patterns adopt this middle path.
- SaaS:Fully managed reconciliation workflows with subscription pricing lower barriers for mid-market treasury departments lacking internal DevOps capacity.
On-premises systems retain the bulk of installed capacity at incumbent financial institutions; cloud-based deployment is expanding most quickly among fintech challengers and neobanks.
End User:
Enterprise complexity drives the deepest feature requirements, while consumer-facing solutions prioritize mobile accessibility and simplified exception alerts.
- Financial Institutions:Custody banks and fund administrators process millions of daily transactions across correspondent networks. Regulatory mandates from the SEC and EU DORA compel same-day certification and immutable audit trails.
- Enterprises:Multinational corporations operating SAP, Oracle, and Workday simultaneously require multi-ERP connectors and consolidated treasury dashboards. Manufacturing conglomerates in the United States and Germany represent concentrated demand.
- Small Businesses:Automated bank feed matching and simplified reconciliation reports reduce bookkeeping overhead. Limited customization tolerance shapes product design.
- Consumers:Personal finance applications aggregate checking, savings, and credit accounts through open banking APIs. United Kingdom adoption leads due to mandated API standards.
Financial institutions command the highest average contract values; small businesses are climbing the fastest as embedded finance proliferation extends reconciliation tools to non-bank platforms.
Solution:
Integration depth separates premium offerings from commodity tools, with ERP-native connectivity determining switching costs and implementation duration.
- Integrated Systems:Native modules within SAP, Oracle, or Workday eliminate data export friction and maintain single-source-of-truth architectures. Large enterprises with heterogeneous ERP landscapes pay substantial premiums for pre-built connectors.
- Web Platforms:Browser-based reconciliation with API-first ingestion reduces IT dependency for mid-market treasury teams. United Kingdom corporates leverage open banking standards for multi-bank aggregation.
- Desktop Software:Local installation with file-based import remains viable for smaller entities with limited transaction volumes and no real-time certification requirements.
- Mobile Apps:Exception alerting and approval workflows extend reconciliation oversight to distributed finance teams. Field-based treasury managers at logistics and construction firms drive niche adoption.
Integrated systems capture the majority of enterprise spending; web platforms are gaining share fastest as API standardization erodes switching cost advantages.
Customer Type:
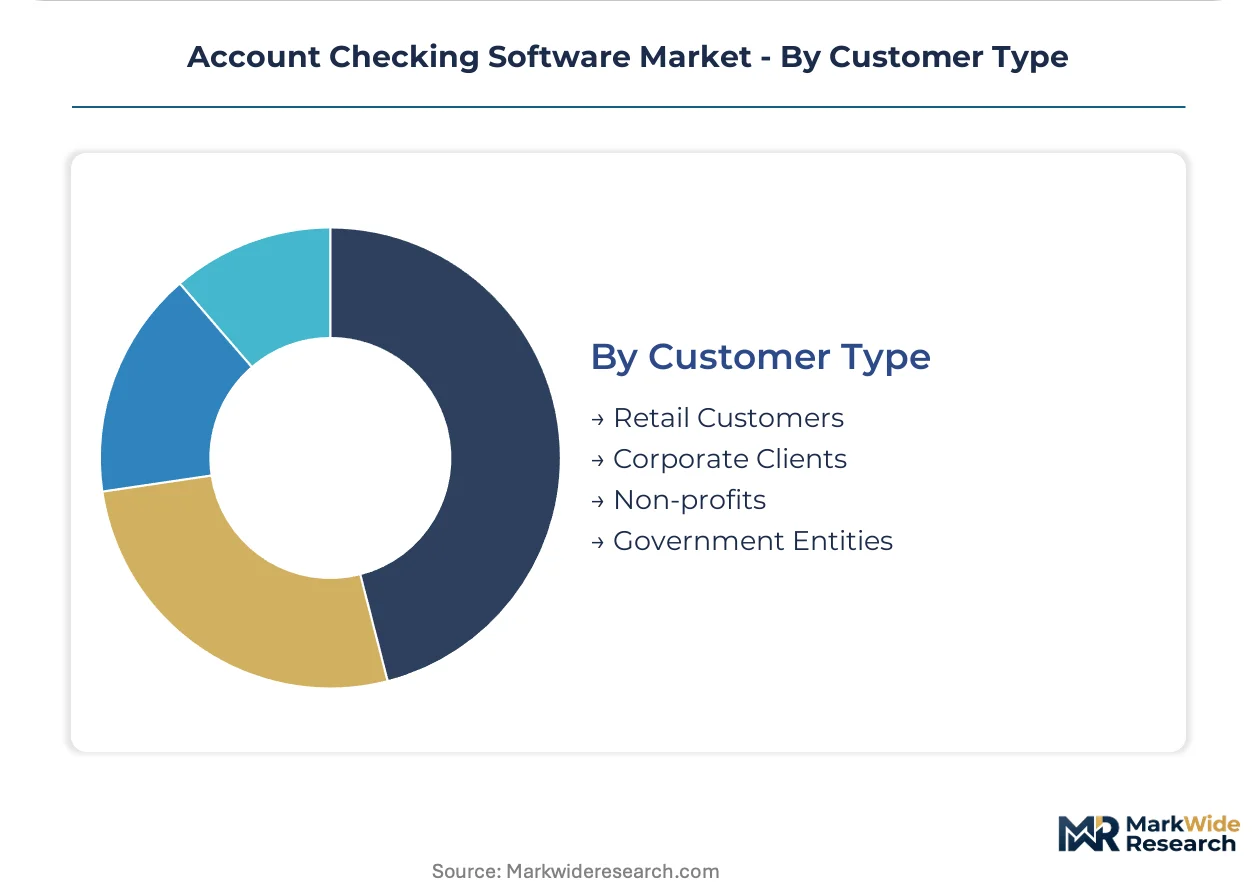
Procurement sophistication varies sharply, with corporate clients demanding SLA-backed performance guarantees and government entities imposing rigid compliance documentation.
- Corporate Clients:Treasury departments at multinational manufacturers and energy conglomerates negotiate volume-based pricing and dedicated implementation support. United States and German headquarters locations concentrate demand.
- Government Entities:Municipal finance departments and federal agencies require FedRAMP authorization and detailed audit logging. Procurement cycles extend substantially due to appropriations timelines and security review requirements.
- Retail Customers:Individual users and sole proprietors select based on mobile experience and subscription affordability. Limited differentiation tolerance compresses margins.
- Non-profits:Grant compliance and donor restriction tracking extend reconciliation requirements beyond standard cash position verification. Smaller operational budgets favor SaaS delivery models.
Corporate clients represent the deepest margin pool; government entities show the steepest expansion trajectory as operational resilience mandates extend to public sector financial operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the largest consumption footprint for account checking software, while development and vendor headquarters concentrate domestically. European financial centers drive secondary demand through regulatory mandates. Asia-Pacific adoption accelerates as digital payment infrastructure matures.
United States
FedNow real-time payment adoption and SEC climate disclosure rules are driving replacement of legacy reconciliation systems. The SEC mandates immutable audit trails for same-day certification. New York and Chicago custody banks dominate enterprise deployment volumes.
Germany
EU DORA compliance deadlines and GDPR data residency requirements are reshaping procurement toward EU-hosted cloud architectures. BaFin operational resilience guidelines enforce continuous monitoring standards. Frankfurt's custody banking cluster leads continental deployment scale.
United Kingdom
Open banking API standards and FCA operational resilience requirements are compressing implementation timelines for treasury platforms. The FCA mandates demonstrable control frameworks with real-time exception alerting. London's fintech corridor drives SaaS adoption among mid-market corporates.
India
UPI transaction volume surges and Account Aggregator framework expansion are generating reconciliation demand among non-banking financial companies. RBI guidelines on digital payment security mandate audit-ready infrastructure. Mumbai and Bangalore technology clusters anchor domestic platform development.
Japan
Real-time gross settlement system upgrades and METI digital transformation incentives are modernizing banking back-office operations. The central bank's operational resilience guidance emphasizes automated exception resolution. Tokyo's megabank headquarters concentrate premium-tier procurement.
Account Checking Software Market Competitive Landscape
The competitive structure tilts toward specialized reconciliation vendors over generalist ERP providers. Tier-one custody banks and fund administrators command premium pricing through domain expertise. Three archetypes dominate: enterprise reconciliation specialists, fund administration platforms, and ERP-native modules. M&A activity concentrates on API-first challengers, while incumbents defend position through workflow integration depth.
Within the enterprise specialist tier, Broadridge leverages its custody banking network footprint, SS&C anchors through fund administration specialization, and BlackLine exemplifies continuous accounting workflow differentiation. Oracle represents the ERP-native archetype with pre-built connector advantages. These three occupy positions across price-performance tiers, with specialists commanding margins in regulated financial services while integrated modules capture heterogeneous ERP environments.
| Leading Market Players |
|---|
| Broadridge |
| AutoRek |
| ReconArt |
| SmartStream |
| Oracle |
| SS&C |
| Adra |
| BlackLine |
| Fiserv |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure costs cascade through SaaS subscription tiers as vendors pass hyperscaler compute pricing downstream to financial institutions and mid-market treasury departments.
Pricing Analysis
Transaction throughput anchors value-based pricing across enterprise reconciliation platforms. Subscription tiers stratify by monthly record volume, with financial institutions paying premiums for real-time certification and immutable audit trails. Price differentiation hinges on ERP connector depth and regulatory compliance module inclusion. Pricing pressure stems from open-source matching engine alternatives gaining traction among fintech challengers. Small businesses exhibit highest price sensitivity, while custody banks accept substantial premiums for same-day certification guarantees.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor software delivery networks for account checking platforms. Core dependencies draw from cloud hyperscalers (AWS, Azure, GCP), specialized data center operators, and API gateway providers. Single-source vulnerability concentrates in hyperscaler compute capacity for real-time processing workloads. Distribution runs through direct enterprise sales teams, systems integrators, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Talent scarcity in distributed systems engineering and financial accounting domains props pricing power for implementation services.
For Market Incumbents: Cement workflow integration depth as the primary defensive moat against API-first challengers. Acquire specialized NLP matching engine startups to neutralize natural language processing disruption. Expand EU-region hosting capacity to capture DORA-driven procurement shifts before compliance deadlines crystallize vendor selection. For New Entrants and Emerging Players: Launch via embedded finance partnerships targeting non-bank fintechs lacking internal reconciliation expertise. Target India's non-banking financial companies as the most penetrable geography given UPI volume surges and Account Aggregator framework expansion. Prioritize carbon accounting module development to capture sustainability data convergence demand. For Investors and Strategic Acquirers: FedNow transaction volume acceleration is the leading indicator that real-time payment infrastructure modernization will sustain reconciliation platform demand. Position acquisitions around API-first challengers with proven multi-ERP connectors. Monitor EU DORA implementation timelines as the signal for enterprise replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectors reduce switching costs for SAP, Oracle, and Workday environments simultaneously. |
| Acquisition of Specialist Firm | NLP matching engine capabilities accelerate exception resolution from hours to minutes. |
| Geographic Expansion | EU-region data centers satisfy GDPR localization and DORA audit trail mandates. |
| Strategic Partnership | Open banking API alliances enable multi-bank aggregation for corporate treasury departments. |
| Product Launch | Carbon accounting modules capture Scope 3 emissions tracking convergence demand. |
Research Methodology
SEC filings, EU regulatory databases, and cloud hyperscaler capex disclosures formed the secondary backbone. Primary interviews with CTOs at custody banks, treasury platform engineers, fund administration operations leads, and open banking integration specialists validated demand assumptions. Bottom-up deployment modeling and top-down financial services IT spending analysis triangulated market sizing across the analysis window.
Historical trendline analysis tracked transaction volume growth, cloud migration patterns, and regulatory implementation timelines. Segmentation dimensions modeled include deployment architecture, end-user scale, solution integration depth, and regional adoption pattern. CAGRs derive from elasticity-adjusted growth curves incorporating FedNow and SEPA Instant adoption trajectories alongside DORA compliance deadline effects.
Regulatory timeline delays, hyperscaler pricing volatility, and talent acquisition bottlenecks are the dominant revision risks. Forecasts reflect documented assumptions around real-time payment rail adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Cyber Security in Fintech Market
FinTech
Financial Forecasting Software Market
FinTech
Latin America Fintech Market
FinTech
Stock Trading App Market
FinTech
Latin America AI in Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Japan AI in Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
Canada AI in Fintech Market
FinTech
Finance Cloud Market
FinTech
Automotive Fintech Market
FinTech
China Fintech Market
FinTech
AI in Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Asia-Pacific Fintech Market