
 Europe AI in Fintech Market | 2026-2036
Europe AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AI in Fintech Market Analytics
Cloud-native infrastructure is pivoting away from legacy on-premises data centers across European financial services. Microsoft Corp leverages its Azure cloud ecosystem to anchor AI workloads for major banking clients. Alphabet Inc competes through specialized natural language processing tools tailored for regulatory document analysis. International Business Machines Corp sustains its position via deep vertical expertise in risk management algorithms.
Europe AI in Fintech encompasses artificial intelligence systems deployed within financial technology infrastructure, utilizing machine learning models, neural networks, and predictive algorithms to automate credit scoring, detect anomalous transactions, and generate personalized customer recommendations. These systems process structured and unstructured financial data in real time to reduce operational risk and enhance decision velocity. Machine learning applications currently dominate functional deployment, while natural language processing shows accelerated growth in customer service automation and regulatory compliance documentation. Banking institutions represent the most mature end-user category with established procurement frameworks, though payment processors are expanding fastest as real-time settlement networks proliferate.
EMA frameworks for algorithmic transparency intersect with GDPR data governance requirements and the EU AI Act risk-based classification system to mandate explainable decision-making in automated lending and insurance underwriting. The European Banking Authority supplements these standards with technical guidance on model risk management for AI-driven credit assessments. Stakeholders must monitor evolving supervisory expectations around algorithmic accountability while building compliance architectures that preempt enforcement action.
Market Dynamics
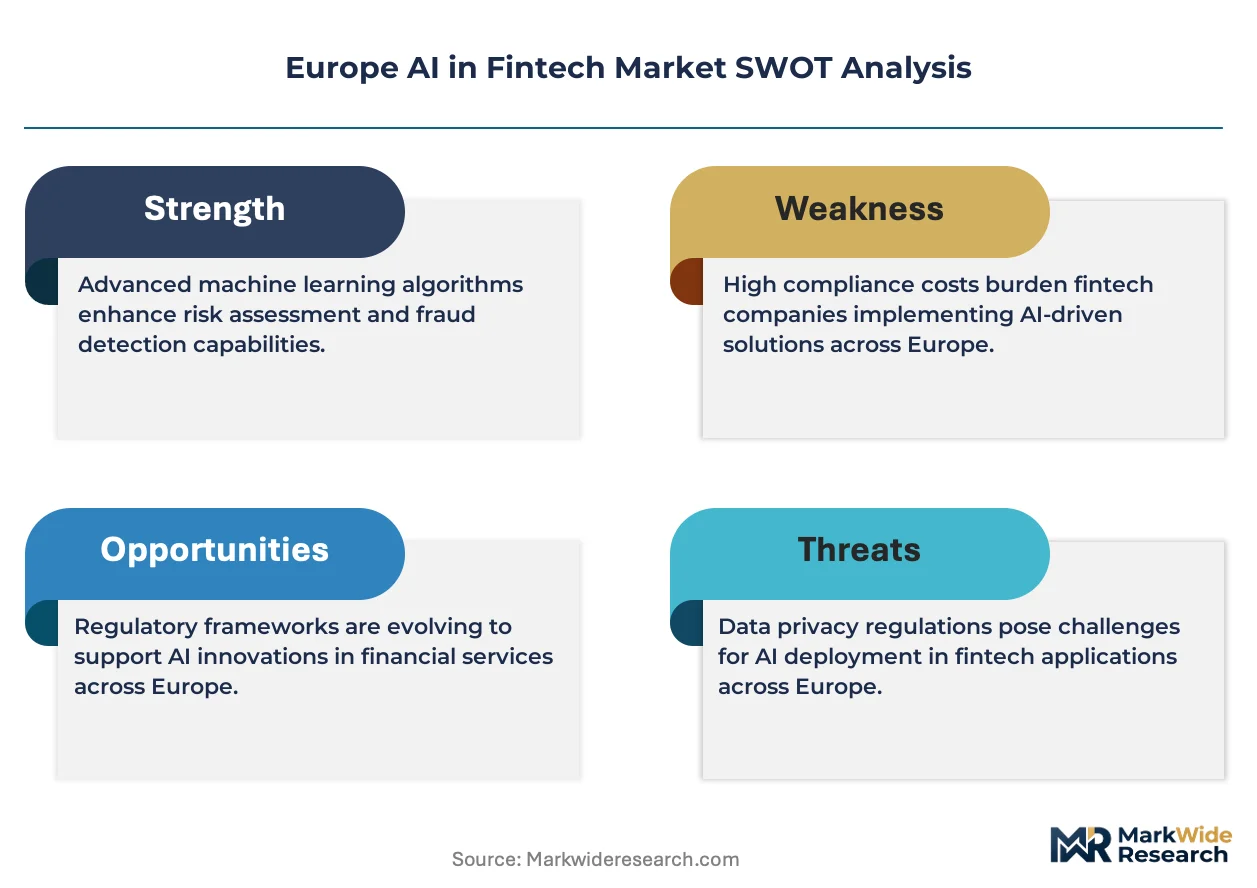
The EU AI Act's risk-based classification system is forcing European banks to re-architect their machine learning pipelines, creating immediate procurement pressure for explainable AI infrastructure and compliance tooling.
Growth Catalysts
- Regulatory Mandate:The EU AI Act's high-risk system requirements push financial institutions toward documented algorithmic governance frameworks, accelerating vendor replacement cycles.
- Real-Time Payment Rails:SEPA Instant Credit Transfer adoption across Germany, France, and Italy generates demand for sub-second fraud detection capabilities that legacy rule engines cannot deliver.
- Cloud Migration:Banking IT departments are retiring on-premises data centers in favor of elastic compute infrastructure capable of training large language models on proprietary transaction datasets.
Market Restraints
- Compute Cost Volatility:GPU cluster pricing fluctuations strain operational budgets for mid-tier banks running transformer-based credit scoring models.
- Talent Concentration:Machine learning engineering expertise clusters in London, Paris, and Berlin, leaving secondary financial centers dependent on outsourced model development.
- Data Localization:GDPR cross-border transfer restrictions fragment training datasets, preventing pan-European model optimization and inflating compliance overhead.
Strategic Opportunities
- Embedded Finance:Non-bank platforms in Spain and the Netherlands seek white-label AI underwriting modules, opening distribution beyond traditional banking procurement channels.
- Regulatory Sandboxes:The European Banking Authority's innovation hubs in Frankfurt and Copenhagen permit live testing of generative AI customer service agents under supervisory observation.
- Sustainability Integration:CSRD disclosure requirements create demand for AI systems that automate carbon footprint calculation across lending portfolios and investment mandates.
Industry Challenges
- Model Documentation:Technical teams struggle to produce audit-ready evidence trails for neural network decisions under EBA supervisory expectations.
- Legacy Integration:Core banking systems from the 1990s resist API connectivity, forcing expensive middleware development for AI overlay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AI in Fintech Market |
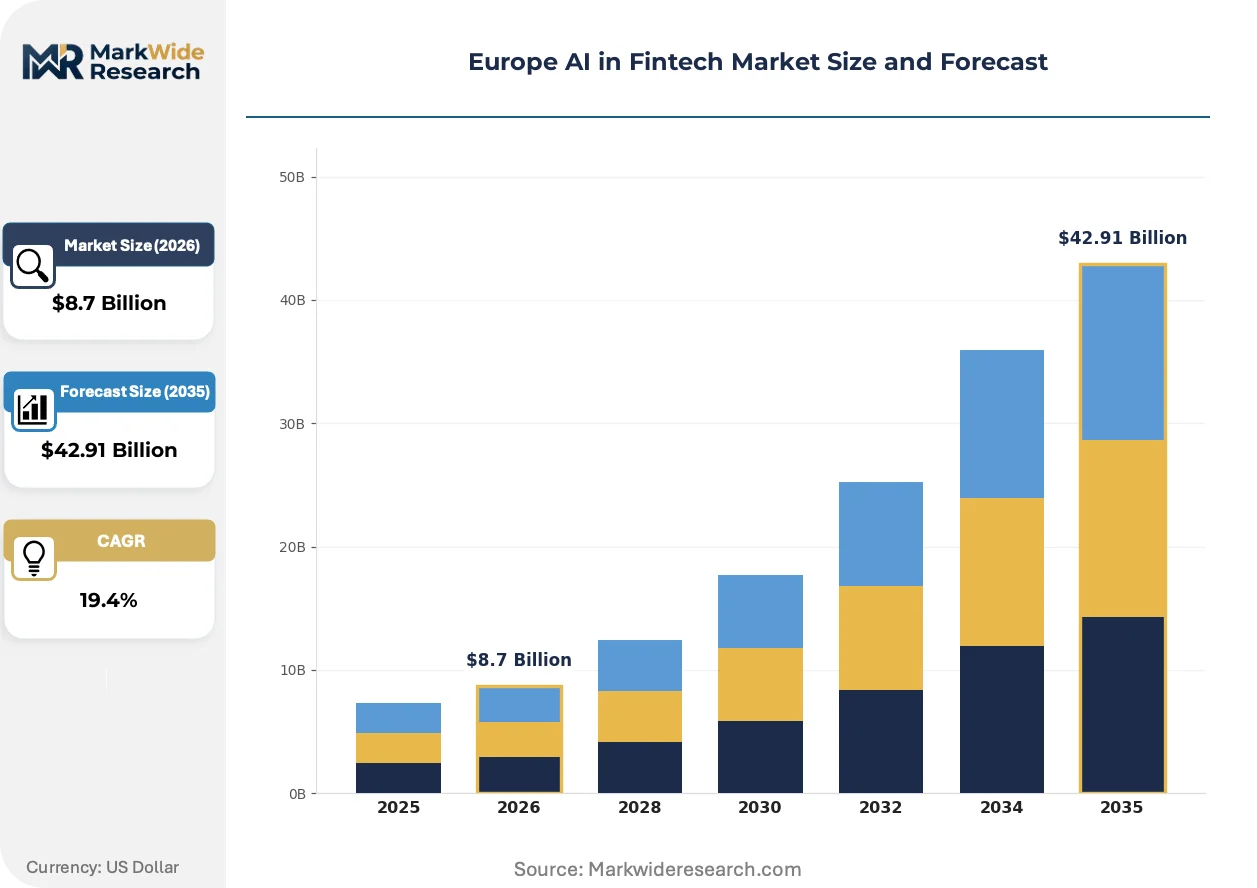
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Insights, Personalization Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics End User: Banking Institutions, Investment Firms, Payment Processors, Insurance Companies Deployment: Cloud-based Solutions, On-premises Solutions, Hybrid Solutions, Managed Services |
| Companies Covered | Microsoft Corp, Alphabet Inc, International Business Machines Corp, Amazon.com Inc, Oracle Corp, Intel Corp, ComplyAdvantage, Salesforce Inc, Feedzai, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AI in Fintech Market Evolving Landscape
Foundation models trained on financial regulatory text are compressing compliance workflow timelines, while edge computing architectures bring inference closer to transaction origination points.
Federated learning architectures are consolidating across European banking consortia. These distributed training protocols enable institutions to build collective fraud detection models without centralizing sensitive customer data. Dutch and Belgian banks have formed operational data alliances, reducing per-institution training costs while preserving GDPR separation. The structural result is consolidating vendor influence toward platform providers capable of orchestrating multi-party computation.
The EU AI Act's conformity assessment procedures are reshaping procurement documentation. Financial institutions must now maintain technical files proving risk management, data governance, and human oversight for automated lending decisions. German universal banks and French mutual insurers face the steepest compliance ramps, engaging notified bodies earlier in development cycles to preempt authorization delays.
Subscription-based AI tooling is displacing perpetual license structures in procurement negotiations. Tier-one banks in the United Kingdom negotiate consumption-based pricing for natural language processing APIs, while Nordic institutions favor outcome-linked contracts tied to fraud reduction metrics. This shift is most pronounced in cloud-native challenger banks lacking capital reserves for upfront enterprise software commitments.
Europe AI in Fintech Market Segmentation
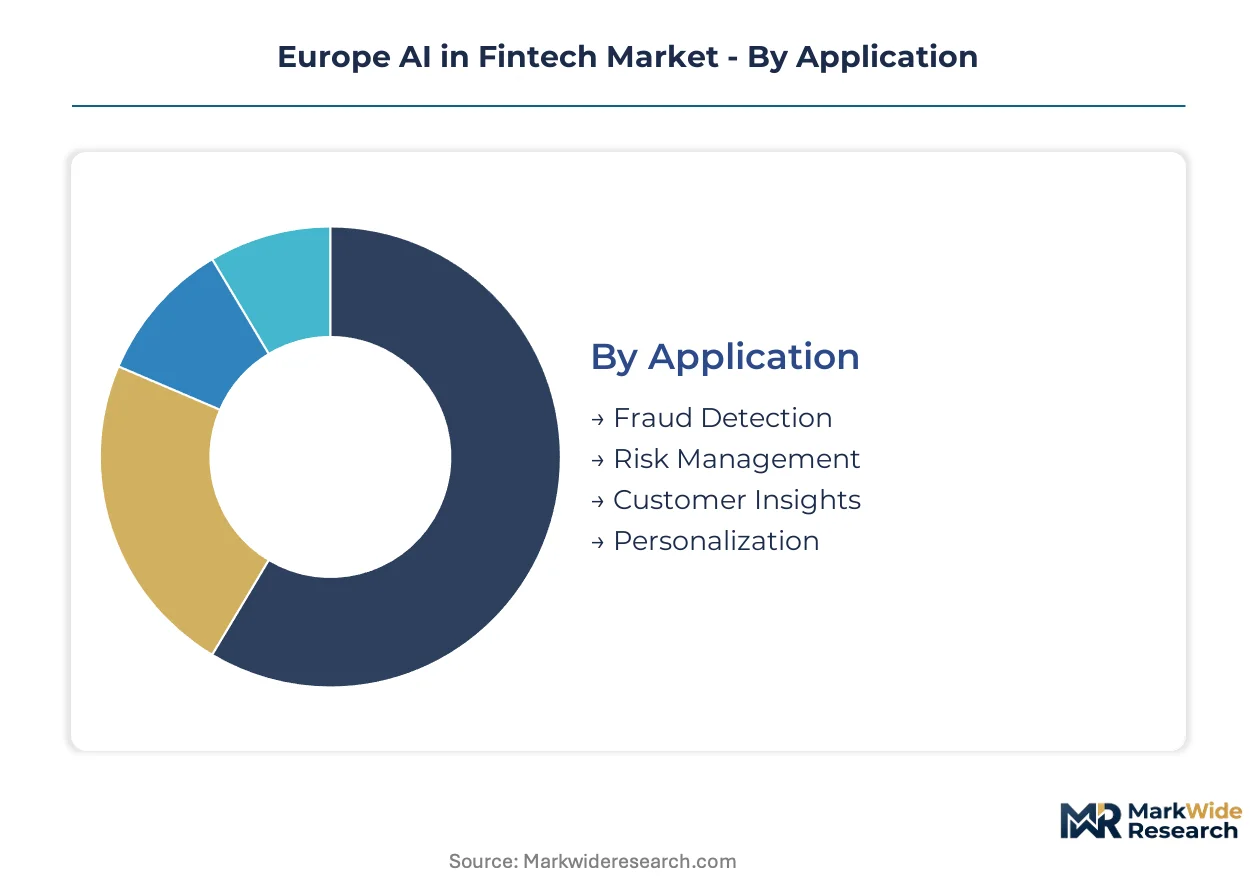
Segmentation reveals how procurement priorities diverge across European financial institutions. Technology choices, deployment architectures, and application focus areas determine vendor selection criteria and contract structures in this regulatory-intensive market.
Application:
Functional deployment priorities separate institutions by their core operational risk exposure and customer engagement intensity.
- Fraud Detection:Real-time transaction monitoring systems deploy neural networks trained on SEPA Instant payment flows. German and French retail banks prioritize sub-second inference latency as instant settlement networks expand across the eurozone.
- Risk Management:Credit scoring algorithms integrate alternative data sources including open banking feeds and supply chain payment histories. Dutch commercial banks lead adoption of dynamic limit-setting tools for SME lending portfolios.
- Customer Insights:Behavioral analytics platforms aggregate transaction patterns to predict churn and cross-sell propensity.
- Personalization:Recommendation engines tailor product offerings based on life-event detection from spending pattern shifts.
Fraud Detection leads volumes today; Personalization is gaining share fastest.
Technology:
Technical architecture choices reflect the balance between model sophistication and regulatory explainability requirements.
- Machine Learning:Supervised learning models dominate production environments for credit decisions and anomaly detection. Gradient-boosted frameworks from the UK and Scandinavian banks emphasize interpretable feature importance scores for EBA audit trails.
- Natural Language Processing:Transformer-based systems parse regulatory filings and customer service interactions. Italian and Spanish institutions deploy multilingual sentiment analysis across Mediterranean market operations.
- Computer Vision:Document verification pipelines extract data from identity papers and financial statements.
- Predictive Analytics:Time-series forecasting supports liquidity planning and macroeconomic stress testing.
Machine Learning anchors current procurement; Natural Language Processing shows the steepest expansion trajectory.
End User:
Institutional category determines budget scale, compliance burden, and integration complexity for AI vendors.
- Banking Institutions:Universal banks and mutual lenders operate the most mature procurement functions with dedicated model risk management offices. German Sparkassen networks and French cooperative banking groups consolidate vendor negotiations through shared service entities.
- Payment Processors:Real-time clearing infrastructure operators require elastic compute for transaction spikes. Nordic payment schemes and Dutch iDEAL operators drive demand for edge-deployed inference nodes.
- Investment Firms:Asset managers apply NLP to earnings call transcripts and ESG disclosure documents.
- Insurance Companies:Underwriting automation focuses on property damage assessment and claims fraud.
Banking Institutions command the largest contract values; Payment Processors are expanding most quickly.
Deployment:
Infrastructure location decisions trade data sovereignty assurance against computational scalability and operational flexibility.
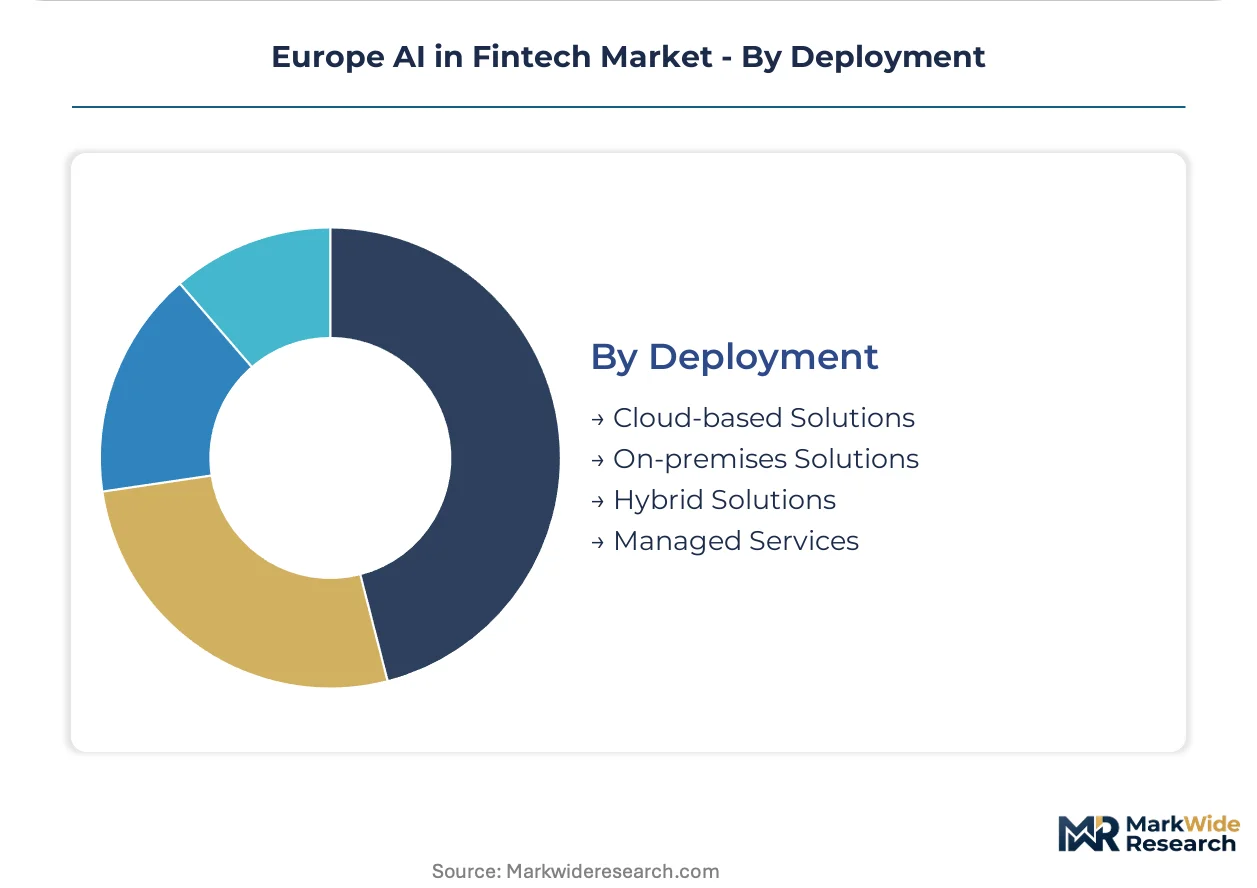
- Cloud-based Solutions:Elastic compute resources support training workloads for large language models on anonymized transaction corpora. UK challenger banks and Benelux fintechs favor consumption-based pricing without capital-intensive data center commitments.
- Hybrid Solutions:Sensitive data remains on-premises while model training leverages cloud burst capacity. Austrian and Swiss private banks architect split deployments to satisfy national financial secrecy frameworks.
- On-premises Solutions:Legacy core banking environments in Southern Europe retain localized inference for regulatory comfort.
- Managed Services:Outsourced model operations appeal to mid-tier institutions lacking internal ML engineering benches.
Cloud-based Solutions dominate new procurement; Hybrid Solutions are climbing the fastest as compliance architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's banking cluster anchors Europe's AI fintech demand, with German universal banks driving procurement for explainable credit scoring infrastructure. The EU AI Act's high-risk system requirements are reshaping vendor selection criteria across continental financial centers.
Germany
Sparkassen networks and cooperative banking groups are consolidating AI procurement through shared service entities. The Federal Financial Supervisory Authority (BaFin) mandates model risk documentation for automated lending decisions. Frankfurt's financial district hosts the densest concentration of explainable AI deployments for SME credit assessment.
United Kingdom
London-based challenger banks favor consumption-based cloud pricing for natural language processing APIs. The Bank of England's machine learning guidance shapes supervisory expectations for algorithmic credit decisions. The Square Mile and Canary Wharf clusters concentrate vendor engineering talent for real-time fraud detection systems.
France
French mutual insurers face steep compliance ramps for EU AI Act conformity assessments. The Autorité de Contrôle Prudentiel et de Résolution (ACPR) supplements EBA guidance with national technical standards. Paris La Défense hosts major deployments of regulatory document analysis systems for insurance underwriting automation.
Netherlands
Dutch commercial banks lead adoption of dynamic limit-setting tools for SME lending portfolios. The Dutch Central Bank (DNB) emphasizes algorithmic accountability in its fintech supervision framework. Amsterdam's payment processing cluster drives demand for edge-deployed inference nodes serving iDEAL real-time settlement networks.
Italy
Italian institutions deploy multilingual transformer systems for Mediterranean market customer service automation. The Bank of Italy's fintech oversight unit monitors AI-driven credit scoring for consumer protection compliance. Milan's financial district anchors southern European procurement for document verification and identity authentication pipelines.
Europe AI in Fintech Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and specialized compliance tooling. The vendor base stratifies between hyperscale platform providers and vertical-focused risk management specialists. Three archetypes dominate: cloud-native challengers with elastic compute offerings, legacy technology vendors with deep banking relationships, and emerging specialists in regulatory compliance automation. Consolidation pressure is accelerating through strategic partnerships between infrastructure providers and domain-specific AI developers.
Among US-based technology conglomerates, Microsoft Corp and Alphabet Inc exemplify the hyperscale platform archetype, anchoring cloud infrastructure procurement for major European banking clients. International Business Machines Corp occupies a position representing legacy vertical expertise in risk management algorithms. These three entities sit within distinct competitive vectors—cloud ecosystem breadth, specialized natural language processing capabilities, and established financial services consulting relationships—shaping how procurement teams evaluate vendor proposals against EU AI Act compliance requirements.
| Leading Market Players |
|---|
| Microsoft Corp |
| Alphabet Inc |
| International Business Machines Corp |
| Amazon.com Inc |
| Oracle Corp |
| Intel Corp |
| ComplyAdvantage |
| Salesforce Inc |
| Feedzai |
| Others |
Value Network & Pricing Analysis
Captive cloud infrastructure investments by hyperscale providers anchor supply positioning and pricing power across European AI fintech procurement. Microsoft Azure and Google Cloud Platform operate dedicated EU data center regions, enabling tier-one banks to negotiate consumption-based contracts while satisfying GDPR data localization mandates.
Pricing Analysis
GPU cluster cost pass-through dominates vendor pricing structures for transformer-based fraud detection deployments. Subscription-based SaaS tiers separate premium explainability modules from standard inference APIs, with price differentiation driven by EU AI Act audit documentation depth and real-time latency guarantees. Pricing pressure stems from mid-tier banks consolidating vendor relationships to reduce compliance overhead. Payment processors show highest price sensitivity due to transaction-volume volatility; universal banks absorb premium pricing for regulatory pre-certification.
Supply Chain Analysis
Direct-to-bank channels handle hyperscale buyer demand for cloud-native AI infrastructure, bypassing traditional systems integrators. Supply concentrates in Ireland, Netherlands, and Germany for EU-regulated data center capacity. NVIDIA GPU silicon and specialized AI accelerators from Intel and AMD constitute critical hardware dependencies. Single-source vulnerability in advanced semiconductor fabrication threatens training pipeline continuity. Distribution runs through cloud marketplace platforms and dedicated financial services vertical teams at major hyperscalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European AI fintech has entered a late-cycle quality phase where procurement committees prioritize EU AI Act pre-certification over raw inference performance. Banks now demand documented algorithmic governance as a baseline specification, elevating compliance-automation vendors above pure-play accuracy leaders.
For Market Incumbents: Deploy explainable AI documentation frameworks to preempt regulatory displacement. Consolidate procurement relationships with Sparkassen and cooperative banking networks before challenger banks scale. Threat: Cloud-native entrants offering consumption-based pricing without legacy integration baggage. Lever: Deep vertical expertise in BaFin and ACPR model risk management protocols.
For New Entrants and Emerging Players: Specialist compliance-tooling vendors represent the most penetrable channel partner category for white-label distribution. Target embedded finance platforms in Spain and the Netherlands seeking pre-built underwriting modules. Go-to-market: Outcome-linked contracts tied to fraud reduction metrics rather than per-API consumption fees.
For Investors and Strategic Acquirers: Roll-up economics work for regulatory compliance automation specialists because EU AI Act conformity assessment requirements fragment vendor landscapes across national supervisory interpretations. Five-to-ten-year viability hinges on consolidation of EBA technical guidance expertise. Acquisition archetype: Notified body relationships plus model documentation tooling. Signal: European Banking Authority innovation hub graduation rates for generative AI customer service pilots.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | BaFin and ACPR documentation requirements accelerate procurement cycles for pre-certified vendors. |
| Federated Learning Consortium Formation | Dutch-Belgian data alliances reduce per-institution training costs while preserving GDPR separation. |
| Edge Computing Infrastructure Deployment | Nordic iDEAL operators demand sub-50ms inference latency for real-time settlement networks. |
| Regulatory Sandbox Graduation | Frankfurt and Copenhagen innovation hubs validate generative AI customer service under supervisory observation. |
| Sustainability-Linked AI Tooling | CSRD disclosure mandates automate carbon footprint calculation across lending portfolios. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement targeted chief data officers at German universal banks, model risk management leads at French mutual insurers, procurement directors at Dutch payment processors, and AI engineering heads at UK challenger banks. Secondary validation drew from European Banking Authority technical guidance documents, EBA stress test disclosures, EU AI Act implementing acts, and hyperscaler cloud region expansion announcements. Bottom-up deployment estimates triangulated against top-down banking IT spending projections.
Segment-weighting approaches distributed value across application categories, technology types, and deployment architectures. Machine learning and natural language processing trajectories modeled separately given divergent regulatory treatment. Cloud-based, hybrid, and on-premises deployment splits reflected national financial secrecy framework variations. CAGRs derived from S-curve adoption modeling anchored to SEPA Instant payment rail expansion timelines and EU AI Act enforcement phase transitions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GPU supply constraints, EBA supervisory guidance evolution, and pan-European banking consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Latin America AI in Fintech Market
FinTech
Japan AI in Fintech Market
FinTech
Financial Consolidation Software Market
FinTech
Global Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Netherlands AI in Fintech Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Financial Fraud Detection Software Market
FinTech
Singapore AI in Fintech Market
FinTech
Decentralized Finance Technology Market
FinTech
Smart Financial Solutions Market
FinTech
Micro-Investing Platform Market
FinTech
Africa AI in Fintech Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Fintech-As-A-Service Market
FinTech
Germany Fintech Market