
 Spend Management Platform Market | 2026-2036
Spend Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Spend Management Platform Market Intelligence
Healthcare provider networks is broadening its share of platform deployments as hospital systems replace fragmented purchasing tools with unified spend orchestration. SAP SE anchors its position through deep ERP integration that locks in procurement data flows across multinational manufacturing clients. Coupa Software differentiates via AI-powered supplier risk scoring that flags contract anomalies before invoice approval. Brex competes in the corporate card-linked expense segment, leveraging real-time transaction categorization to capture mid-market SaaS buyers.
A spend management platform is a software system that automates procurement, expense reporting, invoice processing, and budget enforcement through configurable approval workflows and general ledger integration. It operates by ingesting structured supplier data, applying policy rules engines, and generating audit trails for financial compliance. Cloud-Based deployment leads current uptake because it eliminates infrastructure maintenance and accelerates multi-entity rollouts for distributed workforces. Large Enterprises represent the deepest margin pool due to complex approval hierarchies and custom integration requirements, though SMEs show faster adoption velocity as pre-configured templates reduce implementation cycles.
The EU AI Act shapes algorithmic transparency mandates for automated spend classification tools, while GDPR imposes data residency constraints on cross-border supplier records. The SEC's climate disclosure rules in the US extend liability to Scope 3 emissions tracking, forcing platforms to embed carbon accounting into procurement workflows. Stakeholders must decide whether to build native ESG data layers or partner with specialized carbon intelligence vendors before regulatory deadlines harden.
Market Dynamics
EU AI Act algorithmic transparency mandates and GDPR data residency constraints are compressing vendor compliance timelines while hospital networks accelerate procurement digitization to replace fragmented purchasing tools.
Growth Catalysts
- Healthcare Digitization:Hospital systems are consolidating fragmented purchasing tools into unified spend orchestration platforms to eliminate maverick spending and enforce contract compliance across distributed care networks.
- GDPR Data Residency:Cross-border supplier record storage restrictions are compelling enterprises to deploy region-locked cloud instances with auditable data lineage for procurement workflows.
- Industrial Mittelstand Expansion:Germany's mid-sized manufacturing firms are digitizing supplier payment workflows to reduce invoice processing delays and capture early-payment discounts.
Market Restraints
- Legacy ERP Integration Costs:Custom API development for SAP and Oracle systems consumes 40-60% of implementation budgets, extending payback periods for mid-market buyers.
- Supplier Data Fragmentation:Inconsistent master data formats across tier-2 and tier-3 vendors limit automated spend classification accuracy and require manual reconciliation.
- EU AI Act Compliance Burden:Algorithmic transparency documentation for automated approval workflows demands specialized legal-technical resources that smaller vendors cannot staff.
Strategic Opportunities
- Scope 3 Carbon Accounting:SEC climate disclosure rules are forcing platforms to embed emissions tracking into procurement workflows, creating partnership openings with carbon intelligence vendors.
- SME Pre-Configured Templates:Reduced implementation cycles for small and medium enterprises are accelerating adoption velocity in underserved segments previously locked out by enterprise complexity.
- Real-Time Corporate Card Linkage:Transaction categorization at point-of-sale is capturing mid-market SaaS buyers seeking immediate budget visibility without expense report lag.
Industry Challenges
- Specialized Implementation Talent:Scarce consultants with both procurement domain expertise and cloud architecture skills are extending deployment timelines and inflating professional services costs.
- Multi-Entity Rollout Complexity:Distributed workforces across tax jurisdictions require localized approval hierarchies and currency handling that strain platform configurability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spend Management Platform Market |
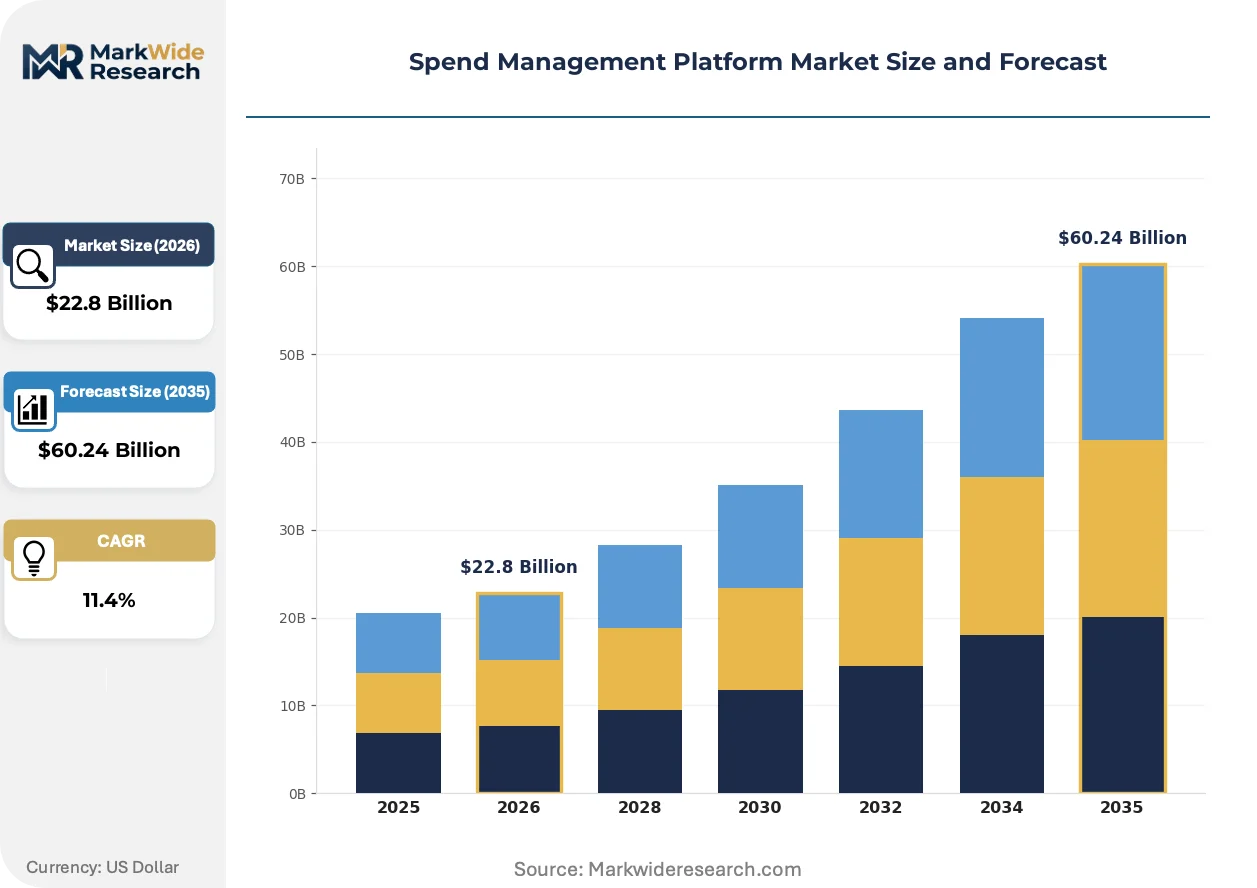
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $60.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: SMEs, Large Enterprises, Government Agencies, Non-Profits Service Type: Consulting, Implementation, Support, Training Solution: Procurement Management, Invoice Management, Expense Tracking, Budget Planning |
| Companies Covered | Coupa Software, SAP SE, Expensify, The Sage Group, Spendesk, Brex, Rippling, Tipalti, Workday, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spend Management Platform Market Strategic Shifts & Innovations
Spend management platforms are converging with embedded finance and carbon accounting as regulatory pressure intensifies for auditable procurement data. Vendors are racing to differentiate through vertical-specific workflow templates.
Machine learning-powered supplier risk scoring is automating contract anomaly detection before invoice approval. Mid-market manufacturing buyers are adopting these tools fastest, compressing due diligence cycles from weeks to hours. The technology is automating procurement oversight functions previously staffed by category managers.
The EU AI Act mandates explainable logic for automated spend classification algorithms used in approval workflows. Industrial enterprises deploying these tools must now document decision pathways for audit scrutiny. German automotive suppliers are responding by demanding vendor-provided compliance certifications before platform procurement.
Hospital networks are unbundling purchasing from materials management to gain direct supplier negotiation leverage. Group purchasing organizations are losing volume lock-in as health systems deploy direct e-procurement channels. This pattern is most visible in US metropolitan hospital clusters consolidating through merger activity.
Spend Management Platform Market Segmentation
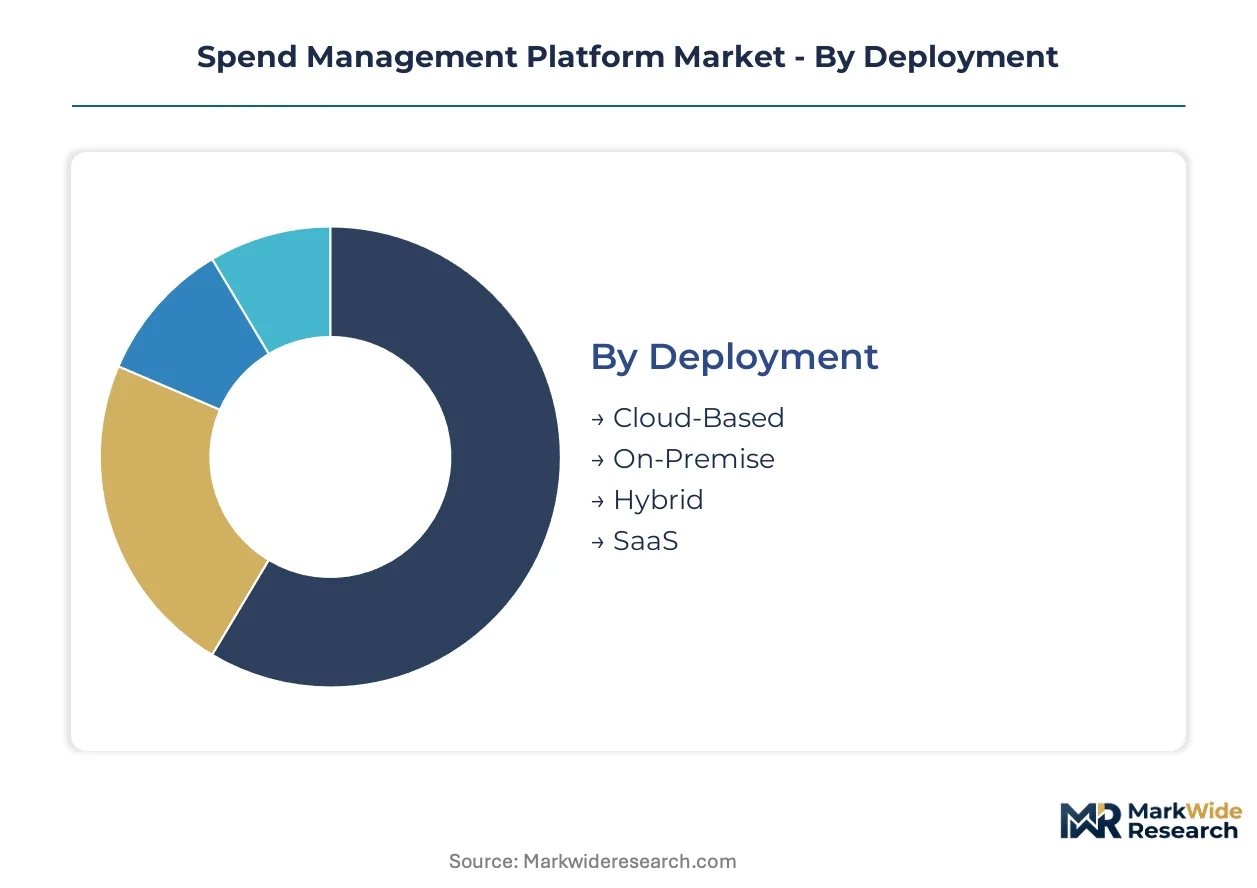
Spend management platforms fragment across deployment architectures and user scale, with each configuration imposing distinct integration costs and compliance obligations. Procurement leaders select segments based on existing ERP footprints, cross-border data residency requirements, and workforce distribution patterns.
Deployment:
Supply concentration among hyperscale cloud providers shapes infrastructure choices and data sovereignty compliance.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance and enable rapid rollouts across distributed facilities. Hospital networks in Germany and manufacturing clusters in the US Midwest are migrating here to satisfy GDPR and state-level privacy mandates without captive infrastructure.
- SaaS:Subscription models with pre-configured workflows compress implementation timelines for mid-market buyers lacking dedicated IT procurement staff. German Mittelstand firms favor this segment for supplier payment digitization without capital expenditure.
- Hybrid:Split architectures retain sensitive supplier data on-premise while routing non-critical workflows through cloud instances. Financial services regulators in Switzerland and Luxembourg are mandating this pattern for cross-border payment records.
- On-Premise:Self-hosted deployments persist in defense contracting and classified government procurement where air-gapped networks are mandatory.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
End User:
Customer scale determines margin structure and professional services intensity, with complexity premiums concentrated at the top.
- Large Enterprises:Multi-entity hierarchies with localized approval chains and currency handling generate the deepest service revenue pools. These deployments require custom API development for SAP and Oracle integration, extending implementation cycles.
- SMEs:Pre-configured templates and reduced implementation friction are unlocking adoption velocity in segments previously excluded by enterprise complexity. Mid-market SaaS buyers in particular are driving real-time corporate card linkage demand.
- Government Agencies:Public procurement regulations mandate auditable spend trails and competitive bidding workflows that platform vendors must certify against federal acquisition standards.
- Non-Profits:Grant compliance and donor restriction tracking create specialized workflow requirements distinct from commercial procurement logic.
Large Enterprises command the highest per-seat revenue; SMEs are climbing the fastest as template standardization reduces entry barriers.
Service Type:
Professional services revenue scales with implementation complexity and ongoing compliance maintenance burdens.
- Implementation:System configuration, data migration, and ERP connector development consumes the largest share of services budgets, particularly for hybrid deployments requiring legacy integration.
- Consulting:Procurement process redesign and policy optimization engagements help enterprises capture early-payment discounts and eliminate maverick spending.
- Support:Tiered response agreements cover break-fix incidents and platform updates, with premium tiers guaranteeing dedicated technical account management.
- Training:Change management and user adoption programs reduce resistance to automated approval workflows and self-service supplier onboarding.
Implementation captures the greatest services revenue; Consulting is gaining share fastest as procurement teams seek external expertise for EU AI Act documentation.
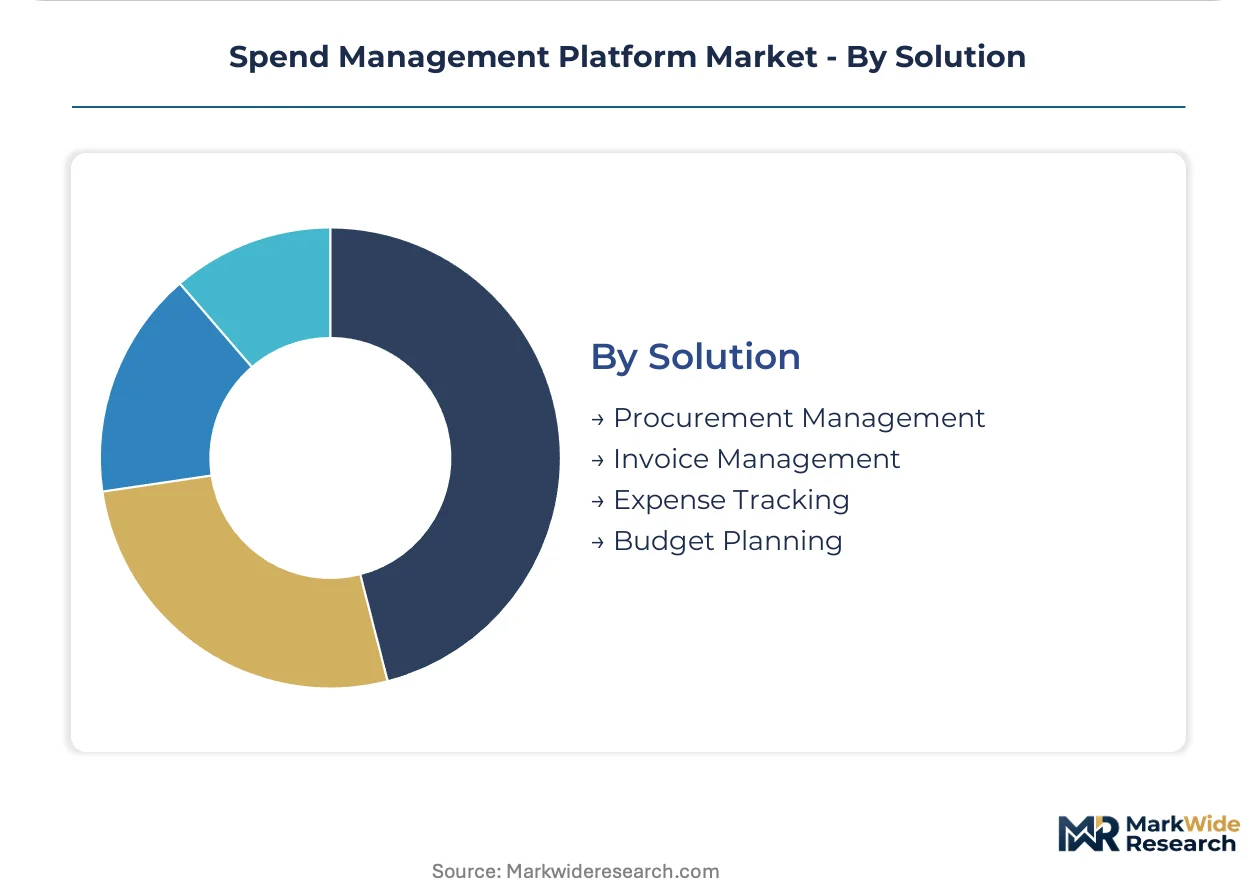
Solution:
Functional modules align with specific procurement pain points, with integration depth determining platform stickiness.
- Procurement Management:Supplier onboarding, contract lifecycle management, and purchase order orchestration form the core platform anchor. Healthcare provider networks are unbundling this from materials management to gain direct negotiation leverage.
- Invoice Management:Automated matching of purchase orders to receipts and invoices, with exception routing for discrepancy resolution. German automotive suppliers are demanding this capability to compress payment cycles.
- Expense Tracking:Corporate card-linked transaction categorization and mobile receipt capture for employee-initiated spending. Real-time budget visibility here is displacing traditional expense report lag.
- Budget Planning:Forecasting tools that enforce encumbrance accounting and prevent overspend before commitment. Public sector buyers require this for fiscal year appropriation compliance.
Procurement Management holds the largest functional footprint; Expense Tracking is expanding most quickly as corporate card issuers embed spend controls at point-of-sale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates in the United States and Germany, while consumption spreads across healthcare networks and industrial clusters seeking compliance-ready procurement infrastructure.
United States
Hospital systems in metropolitan clusters are consolidating fragmented purchasing tools into unified orchestration platforms. The SEC's climate disclosure rules extend liability to Scope 3 emissions tracking, forcing procurement workflows to embed carbon accounting. Greater Boston and the Pacific Northwest host dense concentrations of SaaS buyers adopting real-time corporate card linkage.
Germany
Industrial Mittelstand firms are digitizing supplier payment workflows to capture early-payment discounts and reduce invoice processing delays. The EU AI Act mandates algorithmic transparency documentation for automated approval workflows. Bavaria and Baden-Württemberg anchor automotive supplier demand for vendor-provided compliance certifications.
United Kingdom
Mid-market SaaS buyers are driving adoption of pre-configured templates that compress implementation cycles. GDPR data residency constraints push enterprises toward region-locked cloud instances with auditable data lineage. London and the Southeast concentrate financial services procurement digitization.
France
Healthcare provider networks are accelerating replacement of legacy materials management systems with direct e-procurement channels. The EU Green Deal shapes supplier qualification criteria for public procurement contracts. The Île-de-France region hosts hospital clusters unbundling from group purchasing organizations.
India
SME manufacturing clusters are adopting cloud-based deployment to eliminate infrastructure maintenance costs. RBI guidelines on cross-border payment data localization influence platform architecture decisions. Karnataka and Maharashtra concentrate mid-market buyers seeking rapid multi-entity rollouts.
Spend Management Platform Market Key Industry Players
Top-tier vendors anchor enterprise ERP integration, while mid-market specialists compete on implementation velocity and pre-configured workflow templates. The competitive structure stratifies across three archetypes: legacy ERP extenders, cloud-native disruptors, and embedded finance operators. Consolidation pressure intensifies as compliance burdens from the EU AI Act and SEC climate rules favor vendors with specialized legal-technical resources. Dominant competitive moves include strategic partnerships with carbon intelligence vendors and geographic expansion through localized cloud instances.
Within the cloud-native disruptor tier, Coupa Software and Brex exemplify divergent positioning strategies. Coupa Software occupies a position anchored in AI-powered supplier risk scoring for enterprise manufacturing clients. Brex sits within the corporate card-linked expense segment, capturing mid-market SaaS buyers through point-of-sale transaction categorization. SAP SE represents the legacy ERP extender archetype, leveraging deep integration to lock in procurement data flows across multinational manufacturing clients.
| Leading Market Players |
|---|
| Coupa Software |
| SAP SE |
| Expensify |
| The Sage Group |
| Spendesk |
| Brex |
| Rippling |
| Tipalti |
| Workday |
| Others |
Cost & Logistics Intelligence
Healthcare provider network consolidation into unified spend orchestration platforms is compressing implementation timelines and forcing vendors to absorb upfront integration costs, which squeezes margin structures and shifts pricing power toward buyers with multi-year contract commitments.
Pricing Analysis
Short lead-time deployments command premium pricing as hospital systems and Mittelstand manufacturers demand rapid go-live windows to capture regulatory compliance deadlines. SaaS-tiered subscription models dominate, with price differentiation anchored in ERP integration depth and AI-powered risk scoring capabilities. Cost compression in the mid-market tier is intensifying because pre-configured templates from cloud-native vendors reduce switching costs. SMEs exhibit highest price sensitivity due to constrained procurement budgets, while large enterprises with complex SAP footprints tolerate premium pricing for custom configurability.
Supply Chain Analysis
Returns and data migration rework flows are expanding as failed ERP integration attempts force platform vendors to absorb remediation costs and extend professional services commitments. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscale providers in Ireland, Singapore, and Virginia. Supply chain risk centers on single-source vulnerability for specialized implementation talent possessing both procurement domain expertise and cloud architecture skills. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform delivery capacity is bottlenecked by scarce consultants with dual procurement-cloud expertise, propping pricing for professional services and extending vendor backlogs.
For Market Incumbents: Deploy native ESG data layers or carbon intelligence partnerships before SEC climate disclosure deadlines harden. Consolidate position through vertical-specific workflow templates for healthcare and automotive supplier networks. Channel control via certified implementation partner programs defends against cloud-native disruptors capturing mid-market share with rapid deployment velocity. For New Entrants and Emerging Players: Capture SME manufacturing clusters in India and Germany's Mittelstand segment through pre-configured SaaS templates with rapid multi-entity rollout capability. White-space exists in real-time corporate card-linked expense tracking for mid-market SaaS buyers seeking immediate budget visibility without legacy ERP integration burdens. For Investors and Strategic Acquirers: The window for entry favors vendors with EU AI Act compliance documentation and established carbon accounting partnerships. Long-term viability hinges on regulatory certification moats rather than feature velocity alone. Monitor German automotive supplier procurement decisions as an inflection indicator for platform standardization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic transparency documentation satisfies German automotive supplier procurement mandates. |
| Carbon Intelligence Partnership | Embedded Scope 3 tracking addresses SEC climate disclosure liability extension. |
| Healthcare Workflow Template | Vertical-specific modules capture hospital network unbundling from group purchasing organizations. |
| Real-Time Card Linkage | Point-of-sale categorization displaces expense report lag for mid-market SaaS buyers. |
| Localized Cloud Instance Deployment | Region-locked infrastructure satisfies GDPR data residency constraints across EU member states. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with procurement technology officers, ERP integration specialists, hospital purchasing committee members, and cloud platform engineers. SEC climate disclosure filings, EU AI Act implementation guidance, and healthcare GPO contract databases provided segmentation benchmarks. Bottom-up deployment counts and top-down enterprise software spending estimates were triangulated to validate market sizing.
Granularity-level modeling distinguished cloud-based, SaaS, hybrid, and on-premise deployment architectures across large enterprise, SME, government agency, and non-profit end-user segments. Solution modules including procurement management, invoice management, expense tracking, and budget planning were projected across the analysis window. CAGR derivation incorporated healthcare digitization velocity, Mittelstand payment workflow automation rates, and regulatory compliance deadline clustering.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency and SEC climate rule litigation outcomes. Forecasts reflect assumptions regarding implementation talent availability and hyperscale cloud capacity expansion. Practitioners should monitor German automotive supplier RFP language and US hospital merger announcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Asia-Pacific Fintech Market
FinTech
US AI in Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
Saudi Arabia Fintech Market
FinTech
Decentralized Finance Technology Market
FinTech
Canada AI in Fintech Market
FinTech
Financial Audit Software Market
FinTech
Netherlands AI in Fintech Market
FinTech
Smart Financial Solutions Market
FinTech
Hand Account Software Market
FinTech
United Kingdom Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Europe Fintech Cloud Market
FinTech
Automotive Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
India AI in Fintech Market