
 AI-Powered Wealth Management Solution Market | 2026-2036
AI-Powered Wealth Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Powered Wealth Management Solution Market Insights
Subscription-based model delivery is expanding as the dominant commercial layer in AI-powered wealth management, shifting perpetual-license buyers toward recurring-revenue relationships. Betterment leverages its direct-to-consumer channel to sustain organic user acquisition without advisor intermediation. BlackRock anchors institutional scale through its Aladdin technology ecosystem, which extends risk analytics into wealth workflows. Fidelity Investments competes across the full service spectrum, from robo-advisory to human-hybrid wealth management.
AI-powered wealth management solutions encompass algorithmic platforms that ingest client financial data, risk tolerance profiles, and market signals to automate portfolio construction, rebalancing, and tax-loss harvesting with sub-second execution latency. These systems serve commercial purposes by reducing marginal cost per client while maintaining fiduciary-grade compliance documentation. Cloud-based deployment leads solution type adoption because scalability constraints diminish for firms serving volatile AUM inflows. Robo-advisory functionality captures the fastest expansion within solution types, as algorithmic account opening and goal-based investing reduce minimum balance thresholds. High Net Worth Individuals remain the most mature end-user category, though family offices now represent the steepest demand curve for consolidated multi-generational reporting.
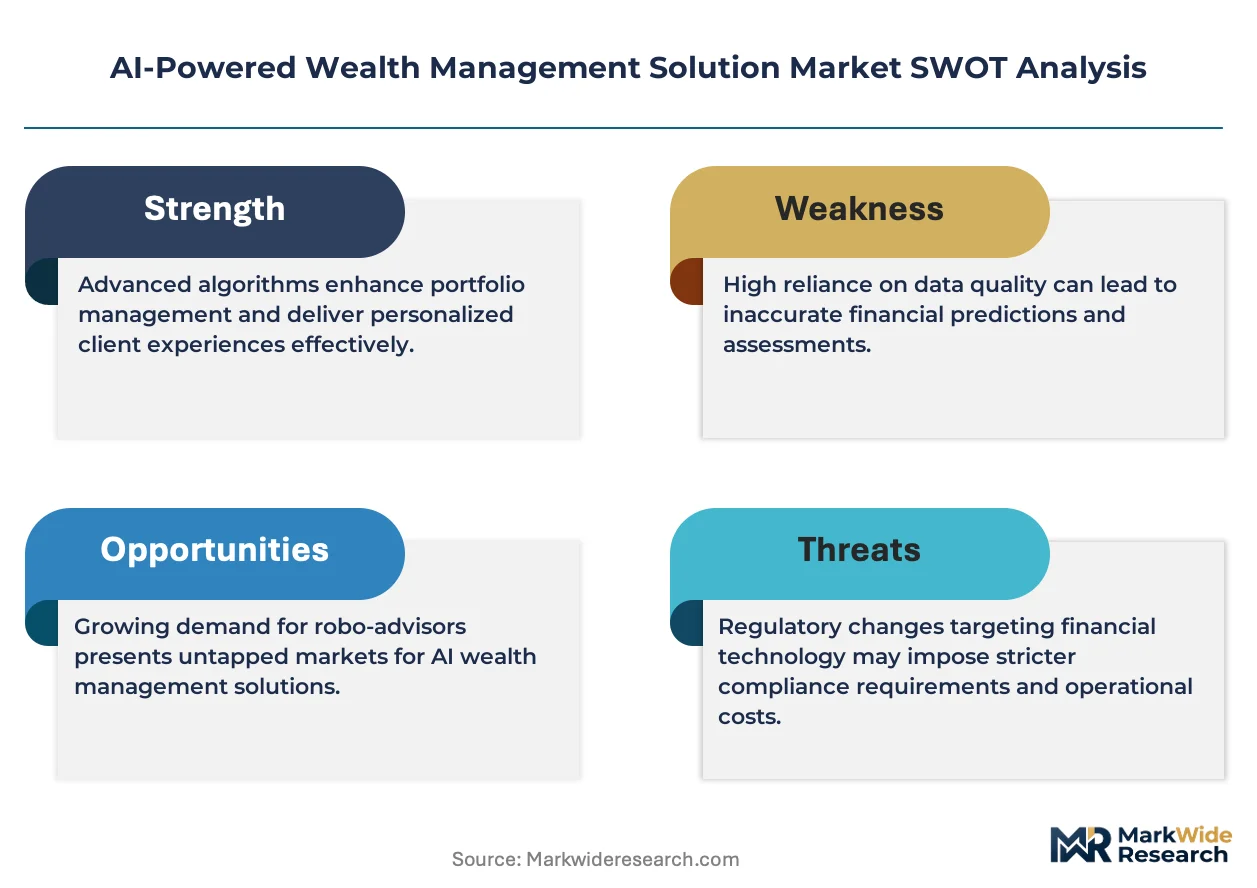
The SEC scrutinizes AI-generated investment recommendations under evolving fiduciary standards, while the EU AI Act imposes risk-classification requirements on automated financial decision systems. FINRA examination priorities now explicitly target model governance and algorithmic bias testing, compelling vendors to embed audit trails directly into platform architecture. Stakeholders must monitor whether jurisdictional regulatory fragmentation forces dual-compliance architectures or creates first-mover advantages for regionally specialized platform providers.
Market Dynamics
The SEC's evolving fiduciary guidance on algorithmic investment advice is compressing vendor compliance timelines while simultaneously opening distribution channels for firms that embed audit-ready model governance from platform inception.
Growth Catalysts
- EU AI Act risk-classification mandates:Automated financial decision systems face tiered compliance obligations that favor established platform providers with embedded governance architecture, accelerating consolidation toward vendors with pre-built audit trails.
- Tax-loss harvesting automation:Machine learning algorithms now execute sub-second harvesting across fragmented cost-basis histories, reducing marginal tax drag for retail accounts previously below advisor service thresholds.
- Family office data consolidation:Multi-generational reporting requirements for illiquid alternative holdings are driving demand for unified dashboards that aggregate private market positions alongside public securities.
Market Restraints
- Cloud infrastructure concentration:Dominant hyperscaler dependencies create single-point-of-failure risk for real-time portfolio rebalancing engines during volatility spikes.
- FINRA model governance examination intensity:Compelled algorithmic bias testing and documentation requirements extend implementation timelines for new platform deployments.
- Human advisor substitution ceiling:Complex estate planning and behavioral coaching for ultra-high-net-worth segments resist full automation, capping addressable market expansion.
Strategic Opportunities
- Embedded finance distribution:Banking-as-a-Service platforms integrate robo-advisory modules into neobank and fintech apps, bypassing traditional wealth management channels entirely.
- Natural language interface convergence:Large language models paired with portfolio analytics enable conversational goal-setting and explanation generation for digitally-native investors.
- Retirement decumulation automation:Dynamic withdrawal algorithms that optimize Social Security timing, Medicare bridge strategies, and sequence-of-returns risk represent underpenetrated white space in lifecycle planning.
Industry Challenges
- Quantitative risk modeler scarcity:Firms compete for talent capable of translating stochastic calculus into production-grade Python while maintaining interpretability for regulatory examination.
- Legacy core banking integration friction:Mainframe-based custody and accounting systems require expensive middleware layers to interface with modern API-first wealth platforms.
- Cross-border data residency fragmentation:Divergent privacy frameworks complicate centralized algorithm training across jurisdictional client bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Powered Wealth Management Solution Market |
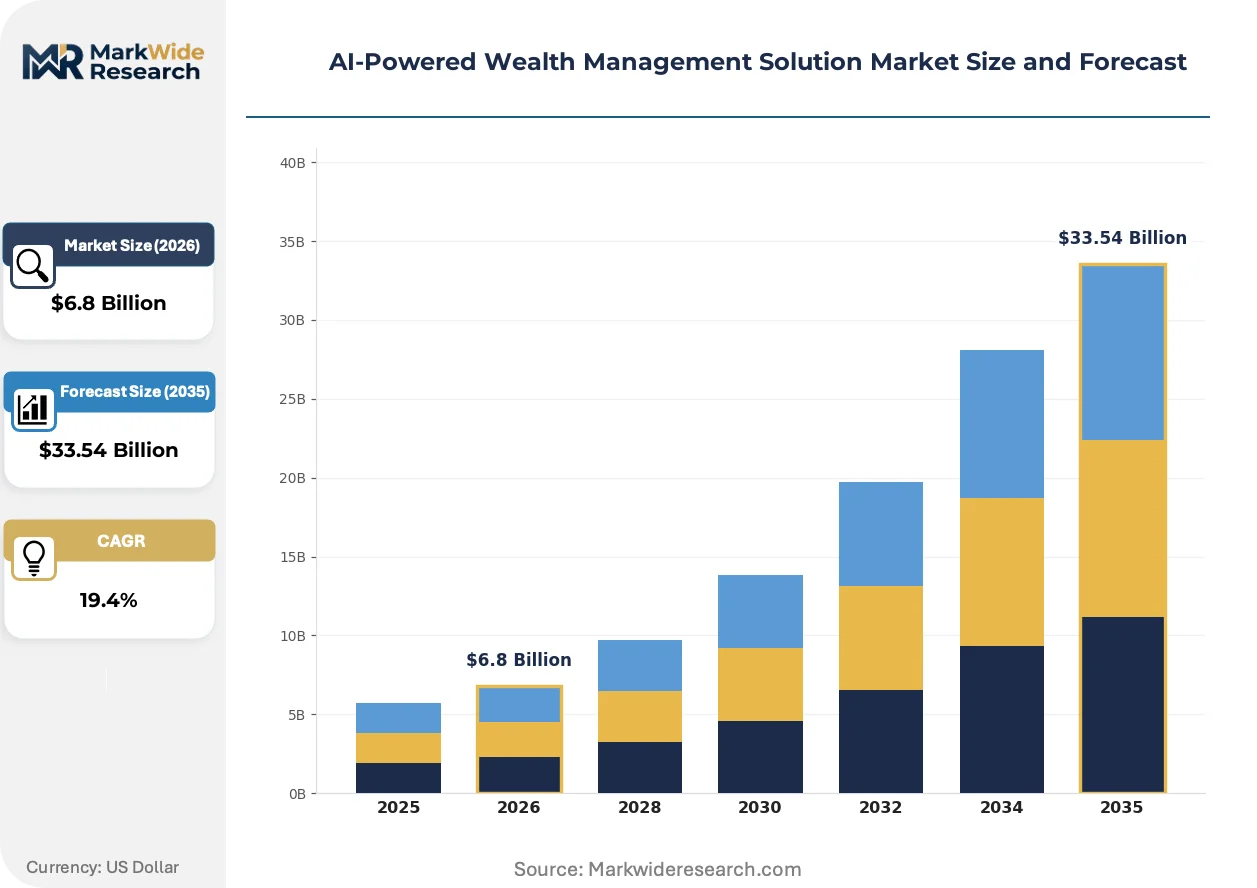
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $33.54 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Type: Portfolio Management, Robo-Advisory, Risk Assessment, Customer Insights, Compliance Automation Use Case: Asset Allocation, Retirement Planning, Tax Optimization, Estate Planning, Financial Forecasting End User: High Net Worth Individuals, Family Offices, Investment Advisors, Small Cap Firms, Private Equity |
| Companies Covered | Wealthfront, Betterment, Charles Schwab, Vanguard, BlackRock, Fidelity Investments, Addepar, Masttro, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Powered Wealth Management Solution Market Trends and Innovations
Algorithmic explainability requirements and generative interface adoption are restructuring how wealth platforms balance automation depth with client trust maintenance.
Reinforcement learning from human feedback is converging with portfolio construction engines to generate personalized glide paths that adapt to stated preferences and inferred behavioral patterns. Mass-affluent investors at digital-first brokerages are encountering these capabilities through conversational onboarding flows. This convergence is compressing the historical trade-off between customization depth and operational scalability that defined earlier robo-advisory generations.
The EU AI Act's risk-based classification framework imposes documentation and human oversight mandates on automated financial decision systems above defined impact thresholds. Vendors serving European wealth managers must embed technical file maintenance and conformity assessment procedures into platform architecture. High-net-worth advisory segments in Germany and France are experiencing the steepest compliance-driven vendor switching as incumbent platforms retrofit governance capabilities.
Subscription pricing for standalone financial planning tools is displacing asset-based fee structures among younger accumulator segments. Direct-to-consumer apps offering unlimited advisor access for flat monthly rates are capturing share from percentage-of-AUM models. This shift is most visible in United States metropolitan markets where digital-native investors prioritize predictable costs over traditional wealth management relationships.
AI-Powered Wealth Management Solution Market Segmentation
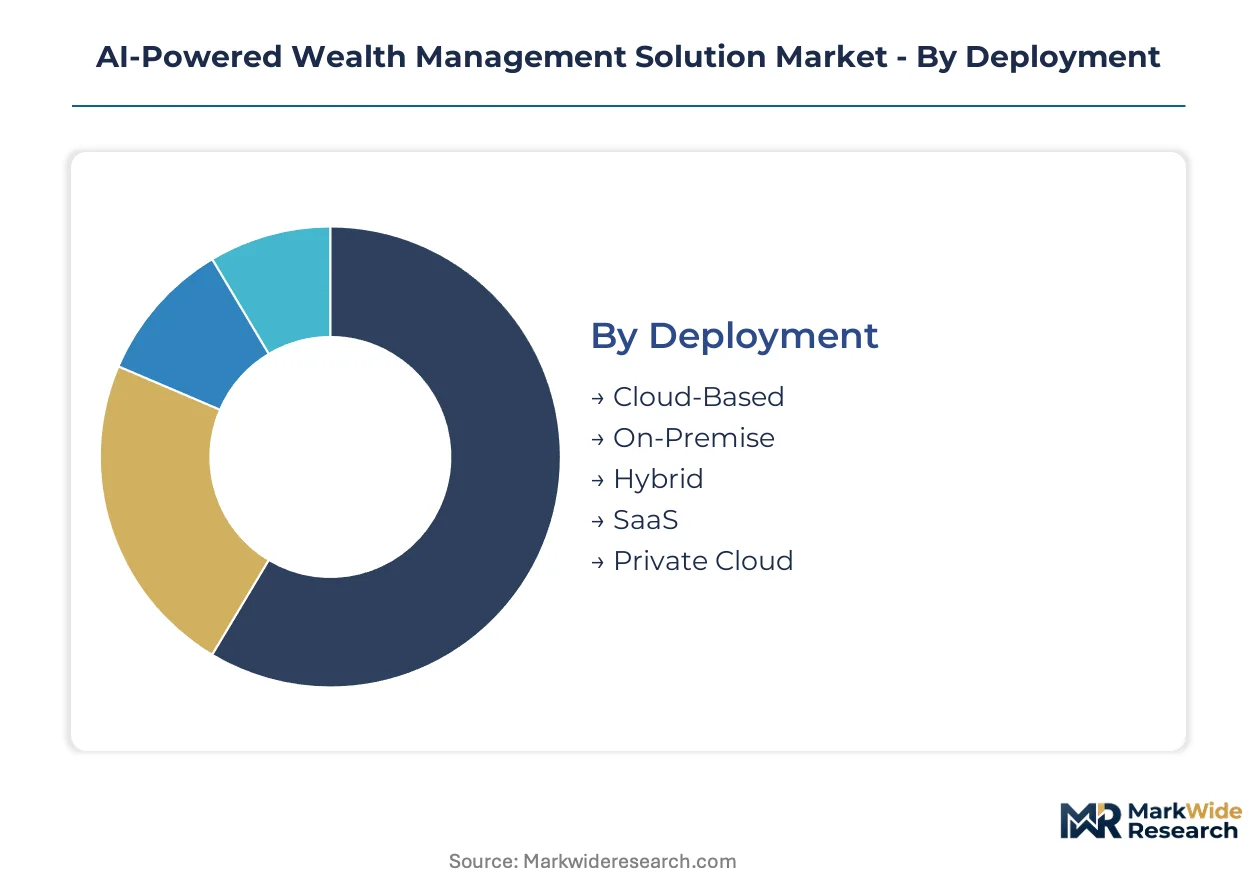
Segmentation in AI-powered wealth management reveals how deployment economics, solution complexity, and client sophistication create distinct competitive arenas. Vendors must align architecture choices with regulatory exposure and service tier expectations.
Deployment:
Buyers prioritize scalability against data sovereignty requirements when selecting infrastructure models.
- Cloud-Based:Multi-tenant architectures enable elastic compute scaling during market volatility spikes without capital expenditure commitments. Demand concentrates among mid-market broker-dealers in the United States seeking to bypass legacy data center overhead while maintaining SEC examination readiness.
- On-Premise:Air-gapped installations satisfy institutional custody banks with mandatory physical control over client asset records and algorithmic model weights. Family offices in Germany favor this deployment for GDPR Article 32 compliance documentation.
- Hybrid:Sensitive portfolio construction runs locally while client-facing interfaces leverage public cloud edge nodes.
- SaaS:Subscription pricing aligns vendor incentives with ongoing platform utilization rather than perpetual license extraction.
- Private Cloud:Dedicated single-tenant environments serve sovereign wealth funds with nationality-based data residency mandates.
Cloud-Based leads on scale; Hybrid leads on momentum.
Solution Type:
Functional depth determines whether platforms displace human advisors or merely augment their productivity.
- Robo-Advisory:Algorithmic onboarding and goal-based glide paths reduce marginal client service costs to near-zero for accounts below traditional advisor minimums. Retail accumulators at digital-first brokerages drive demand in United States metropolitan markets.
- Portfolio Management:Real-time rebalancing engines ingest market microstructure data to execute tax-loss harvesting with sub-second latency. Investment advisors at independent RIAs adopt these tools to scale book-of-business without proportional staff expansion.
- Risk Assessment:Monte Carlo simulations and stress testing modules quantify tail-risk exposure across correlated asset classes.
- Customer Insights:Behavioral analytics identify at-risk clients through engagement pattern degradation.
- Compliance Automation:Audit trail generation and model governance documentation reduce FINRA examination preparation burden.
Portfolio Management leads on scale; Robo-Advisory leads on momentum.
Use Case:
Client life-cycle positioning shapes whether algorithms optimize for accumulation or decumulation outcomes.
- Asset Allocation:Mean-variance optimization and Black-Litterman implementations construct efficient frontiers across traditional and alternative asset classes. Investment advisors serving mass-affluent households in the United States deploy these capabilities to standardize portfolio construction across advisor teams.
- Tax Optimization:Machine learning algorithms harvest losses across fragmented cost-basis histories and coordinate gain realization with charitable giving vehicles. High Net Worth Individuals in California demand this functionality to manage state and federal tax stacking.
- Retirement Planning:Dynamic withdrawal strategies balance sequence-of-returns risk against longevity uncertainty.
- Estate Planning:Multi-generational trust administration and beneficiary distribution modeling resist full automation due to jurisdictional complexity.
- Financial Forecasting:Stochastic projections integrate Monte Carlo simulation with deterministic liability matching.
Asset Allocation leads on scale; Tax Optimization leads on momentum.
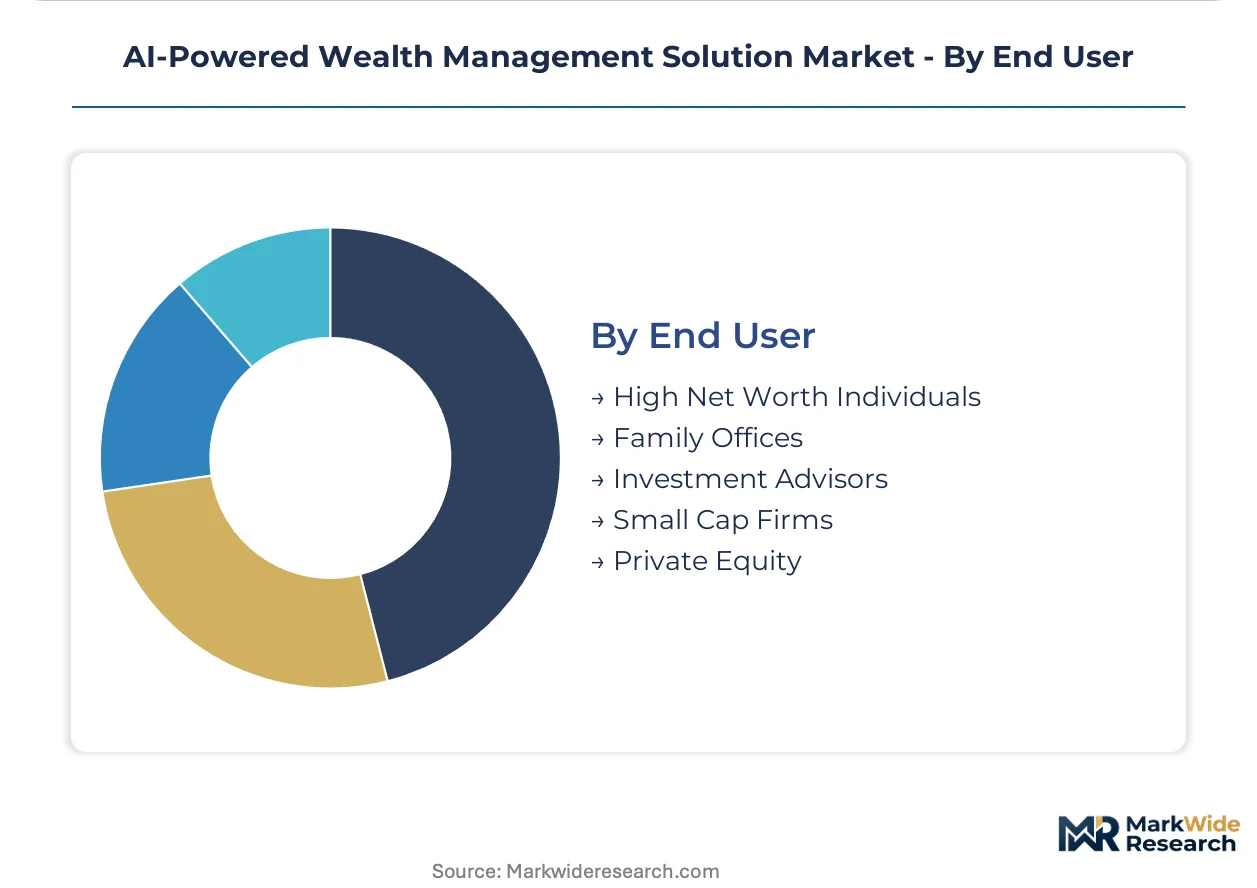
End User:
Wealth concentration and advisory relationship structure determine platform customization requirements.
- High Net Worth Individuals:Clients with liquid assets exceeding traditional advisor minimums demand hybrid service models combining algorithmic efficiency with human relationship management. This segment concentrates in United States coastal metropolitan markets.
- Family Offices:Multi-generational reporting requirements for illiquid alternative holdings drive demand for consolidated dashboards aggregating private market positions. Single-family offices in Texas and Florida represent the steepest adoption curve.
- Investment Advisors:Independent RIAs and wirehouse breakaways seek scalable technology stacks to compete with institutional platforms.
- Small Cap Firms:Regional broker-dealers with limited technology budgets prioritize out-of-box functionality over customization depth.
- Private Equity:Fund administrators apply wealth management algorithms to limited partner reporting and distribution waterfall calculations.
High Net Worth Individuals leads on scale; Family Offices leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys robo-advisory platforms at scale, while Germany's wealth managers navigate stricter algorithmic governance under the EU AI Act. Regulatory fragmentation across these markets is forcing dual-compliance architectures for cross-border platform providers.
United States
SEC examination priorities now explicitly target model governance and algorithmic bias testing, compelling vendors to embed audit trails directly into platform architecture. Broker-dealers in New York and California are integrating machine learning into legacy wealth platforms to serve retail investors at lower cost bases. The FINRA oversight framework is reshaping compliance obligations for algorithmic tools across Manhattan-based fintech clusters.
Germany
Family offices in Frankfurt and Munich demand consolidated dashboards aggregating private market positions alongside public securities for multi-generational reporting. The EU AI Act imposes risk-classification requirements on automated financial decision systems, accelerating vendor switching as incumbent platforms retrofit governance capabilities. Bavaria's private banking centers are experiencing the steepest compliance-driven technology upgrades.
United Kingdom
The Financial Conduct Authority scrutinizes AI-generated investment recommendations under evolving fiduciary standards, compressing vendor compliance timelines. London's wealth management district is deploying cloud-based portfolio rebalancing engines to maintain sub-second execution latency during volatility spikes. Fintech clusters in the Square Mile are pioneering natural language interface convergence for digitally-native investors.
Switzerland
Swiss private banks in Geneva and Zurich favor on-premise deployments to satisfy mandatory physical control over client asset records and algorithmic model weights. Swissmedic-aligned data residency mandates are driving demand for air-gapped installations among institutional custody banks. The country's wealth concentration supports premium-tier hybrid service models combining algorithmic efficiency with human relationship management.
Singapore
The Monetary Authority of Singapore is advancing sandbox frameworks for AI-driven investment advice, opening distribution channels for firms that embed audit-ready model governance from platform inception. Family offices in the Marina Bay financial district are adopting retirement decumulation automation to optimize dynamic withdrawal strategies. Southeast Asian wealth hubs are leveraging Singapore's regulatory clarity to pilot conversational goal-setting interfaces.
AI-Powered Wealth Management Solution Market Competitive Landscape
Top-tier vendors anchor institutional scale, while mid-market specialists compete on embedded finance distribution and natural language capabilities. The vendor base stratifies across three tiers: asset managers with captive technology ecosystems, standalone robo-advisory platforms, and banking-as-a-service integrators. Dominant competitive moves include strategic partnerships with neobank distribution channels and portfolio diversification into retirement decumulation automation.
Within the institutional technology tier, BlackRock and Fidelity Investments occupy positions that exemplify platform consolidation at scale. Betterment represents the direct-to-consumer archetype, sustaining organic user acquisition without advisor intermediation. Among specialized analytics providers, Addepar and Salesforce sit within the data consolidation and customer insights segments respectively.
| Leading Market Players |
|---|
| Wealthfront |
| Betterment |
| Charles Schwab |
| Vanguard |
| BlackRock |
| Fidelity Investments |
| Addepar |
| Masttro |
| Salesforce |
| Others |
Pricing and Supply Chain Analysis
EU AI Act risk-classification mandates gate qualified supply access for algorithmic audit-trail capabilities and embed premium-tier pricing for platforms with pre-built governance architecture. Cloud infrastructure concentration in hyperscaler environments shapes buyer procurement flexibility, while subscription-based SaaS delivery compresses perpetual-license revenue recognition timelines.
Pricing Analysis
Capacity additions in United States cloud regions are reshaping price floors for multi-tenant wealth platforms as hyperscaler competition intensifies. Subscription-SaaS tiering dominates, with price differentiation anchored in audit-trail depth and FINRA examination readiness. Pricing pressure stems from mid-market broker-dealers demanding out-of-box compliance functionality without customization premiums. Small-cap firms exhibit highest price sensitivity, while family offices prioritize governance depth over cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for cloud compute and data residency compliance mandate multi-supplier qualification across United States, Germany, and Singapore infrastructure zones. Algorithmic model development draws from stochastic calculus talent pools, Python-based execution frameworks, and regulatory documentation engines. Single-source vulnerability concentrates in hyperscaler dependencies for real-time rebalancing engines. Distribution runs through direct-to-consumer channels, advisor-intermediated platforms, and embedded finance integrations within neobank ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI-powered wealth management solution market represents a late-cycle quality story as demand shifts toward fiduciary-grade audit documentation and algorithmic explainability. Premium specifications now center on embedded model governance rather than raw automation depth.
For Market Incumbents: Lock in advisor channel control through API-first architecture that embeds seamlessly into independent RIA workflows. Deepen backward integration into proprietary risk analytics engines to defend against standalone robo-advisory substitution. Prioritize FINRA examination-ready documentation as the primary retention lever against compliance-driven vendor switching.
For New Entrants and Emerging Players: Capture retirement decumulation automation white space where dynamic withdrawal algorithms remain underpenetrated against accumulation-focused incumbents. Target family offices in Texas and Florida with multi-generational reporting consolidation as the most penetrable segment. Pursue banking-as-a-service distribution partnerships to bypass traditional wealth management channel barriers entirely.
For Investors and Strategic Acquirers: Roll-up economics work for mid-market compliance automation specialists because FINRA examination intensity extends implementation timelines and favors acquired scale over greenfield development. Five-to-ten year viability hinges on regulatory fragmentation deepening rather than harmonizing across jurisdictions. Monitor EU AI Act enforcement intensity in Germany as the signal for compliance-driven vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded finance distribution through neobank APIs bypasses traditional wealth channels entirely. |
| Acquisition of Specialist Firm | Compliance automation vendors with FINRA-ready audit trails command scarcity premiums in consolidation. |
| Strategic Partnership | Hyperscaler alliances secure elastic compute for volatility-spike rebalancing without capital commitment. |
| Product Launch | Natural language interfaces paired with portfolio analytics capture digitally-native investor segments. |
| Geographic Expansion | Singapore sandbox frameworks open distribution for audit-ready model governance from platform inception. |
Research Methodology
Multiple input streams — primary interviews with wealth management CTOs, compliance officers at broker-dealers, and independent RIA technology leads; secondary validation through SEC examination guidance documents, FINRA regulatory notices, and EU AI Act technical standards; and hyperscaler infrastructure disclosure filings — were reconciled through bottom-up and top-down triangulation. Stakeholder perspectives from platform engineers, algorithmic risk modelers, and family office technology directors informed deployment architecture assumptions.
Historical revenue trajectories were cross-referenced against panel input from vendor pricing disclosures and client procurement patterns across the projection horizon. Segmentation dimensions modeled include deployment model, solution functional depth, end-user wealth tier, and jurisdictional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating cloud infrastructure scaling costs and compliance documentation burden estimates.
Regulatory enforcement intensity, hyperscaler service continuity events, and quantitative risk modeler availability are the dominant revision risks to forecast assumptions. Deviation in SEC examination priority weighting toward algorithmic bias testing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Lendtech Market
FinTech
Europe Financial Analytics Market
FinTech
Embedded Finance Market
FinTech
Decentralized Finance Technology Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Smart Advisors Market
FinTech
Blockchain in Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Singapore AI in Fintech Market
FinTech
Global Fundraising Software Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Germany Fintech Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Latin America AI in Fintech Market
FinTech
Cloud AI in Fintech Market
FinTech
Smart Lending Platform Market