
 Multichannel Digital Banking Integration Software Market | 2026-2036
Multichannel Digital Banking Integration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multichannel Digital Banking Integration Software Market Insights
Mid-sized financial institutions are bifurcating from large universal banks as the fastest-growing buyer archetype for integration platforms. SAP Fioneer leverages its embedded finance architecture to serve this expanding segment. Oracle anchors enterprise-grade deployments through database-layer integration that unifies core banking with digital channels. Temenos competes aggressively on cloud-native modular designs that reduce implementation timelines for regional players.
Multichannel digital banking integration software orchestrates real-time data exchange across mobile, web, branch, and call center touchpoints using API gateways with sub-second latency thresholds and ISO 20022 message compatibility. Its primary commercial purpose is to eliminate siloed customer records and transaction processing systems that fragment service delivery. Cloud-based deployment captures the dominant share of new installations as banks prioritize elastic infrastructure over fixed-capacity data centers. API management solutions within the solution-type category generate disproportionate margin pools because each open banking mandate expands interconnectivity requirements. Workflow automation is accelerating fastest among application segments as institutions seek to compress loan origination and compliance reporting cycles.
The EU's PSD2 framework and the Digital Operational Resilience Act impose strict API security and incident reporting standards that elevate procurement scrutiny across European institutions. In the United States, the OCC and CFPB scrutinize vendor concentration risk in critical banking infrastructure, prompting multi-vendor strategies. India's RBI mandates interoperability protocols for payment systems that directly shape integration software specifications. Stakeholders must monitor how divergent national data localization rules fragment what vendors can offer as standardized global platforms.
Market Dynamics
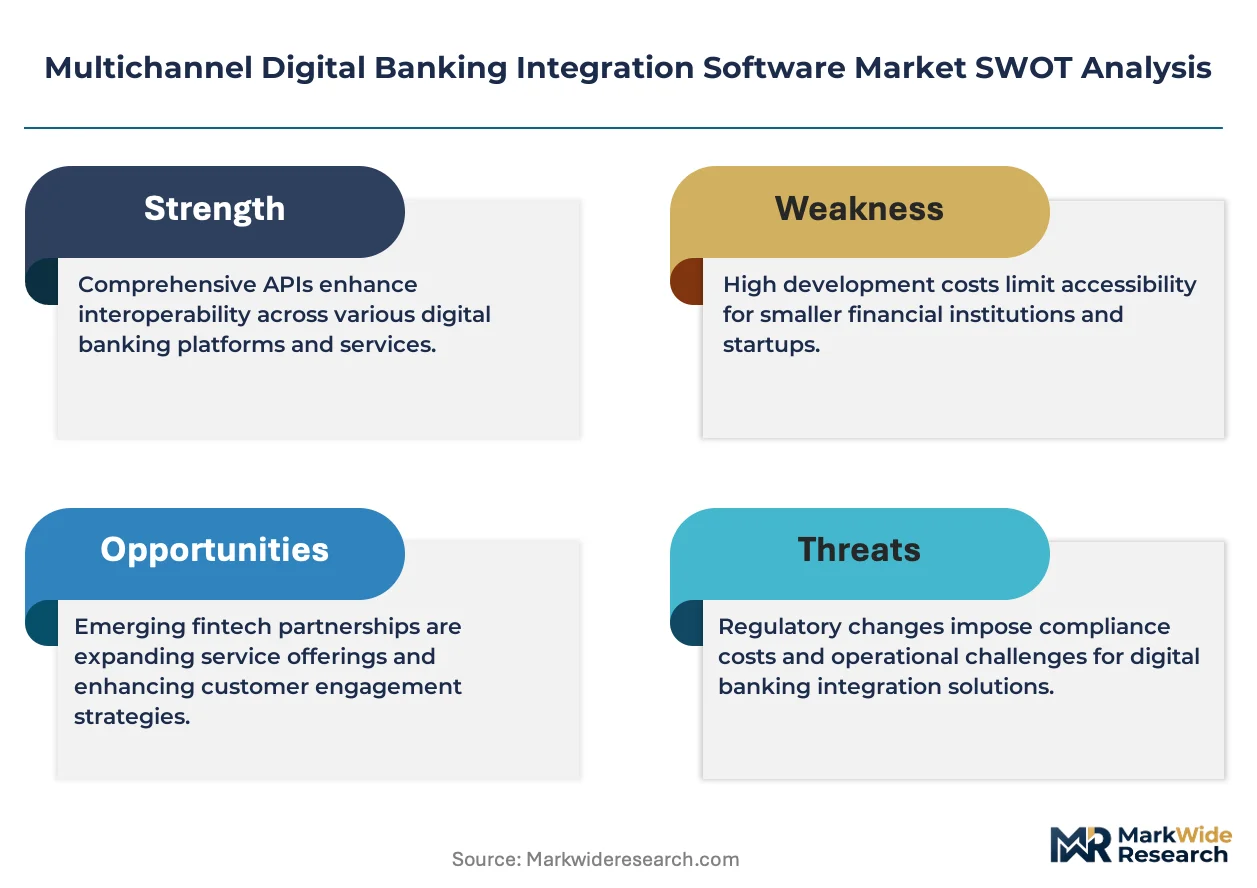
Real-time payment infrastructure mandates across multiple jurisdictions are forcing banks to replace batch-oriented core systems with API-native architectures that synchronize transaction data across channels instantaneously.
Growth Catalysts
- India's RBI interoperability protocols:The central bank's Unified Payments Interface mandates require banks to deploy standardized API gateways, creating immediate procurement pull for integration platforms that handle high-volume instant transfers.
- ISO 20022 message migration:SWIFT's cross-border payment modernization and domestic real-time schemes in Brazil and Australia compel institutions to upgrade message formats, driving replacement cycles for middleware infrastructure.
- Credit union consolidation wave:North American cooperative banks are merging operations and require unified digital platforms to harmonize disparate member databases and loan origination workflows.
Market Restraints
- Cloud concentration risk:Three hyperscale providers dominate bank-grade infrastructure, creating single points of failure that regulators in Germany and Singapore now scrutinize explicitly.
- Specialized engineering talent scarcity:Shortages of developers proficient in both legacy COBOL core systems and modern API gateway architectures extend implementation timelines by 40-60%.
- Data localization fragmentation:Divergent national rules on cross-border data flows prevent vendors from offering standardized global platforms, forcing costly regional customization.
Strategic Opportunities
- Embedded finance convergence:Non-bank retailers and logistics platforms in Southeast Asia seek white-label banking modules, opening distribution channels beyond traditional financial institutions.
- Workflow automation acceleration:Loan origination and compliance reporting cycles present immediate compression targets for robotic process automation layered atop integration layers.
- EU Digital Operational Resilience Act:Incident reporting and third-party risk management mandates create recurring revenue streams for vendors offering continuous monitoring and audit-ready documentation tools.
Industry Challenges
- Core banking system entrenchment:Decades-old transaction processing architectures resist API abstraction, requiring expensive parallel-running migration periods that strain IT budgets.
- Multi-vendor integration complexity:Institutions pursuing regulator-diversified supplier strategies face orchestration overhead across incompatible middleware stacks from competing vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multichannel Digital Banking Integration Software Market |
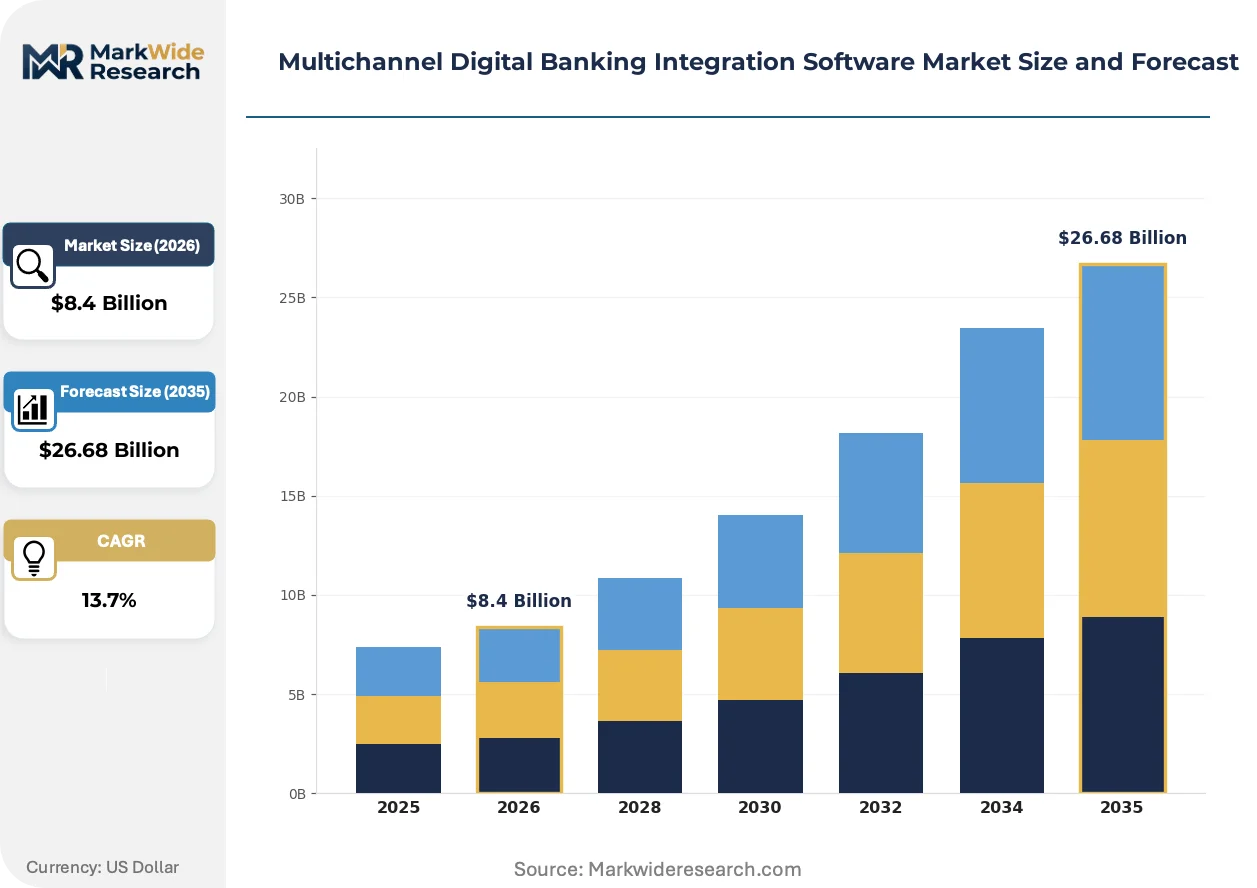
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Virtualized Solution Type: API Management, Payment Gateway, Account Aggregation, Fraud Detection, Data Analytics, Workflow Automation Application: Personal Banking, Corporate Finance, Wealth Management, Loan Processing, Customer Support, Regulatory Compliance End User: Traditional Banks, Credit Unions, FinTech Firms, Payment Processors, Mortgage Lenders, Investment Firms |
| Companies Covered | SAP Fioneer, Salesforce, Oracle, Infosys Finacle, Temenos, Tata Consultancy Services, Finastra, ebankIT, Dais Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multichannel Digital Banking Integration Software Market Trends and Innovations
API-first architectural patterns are restructuring how financial institutions compose customer-facing services, with modular microservices replacing monolithic core banking extensions.
Event-driven architecture is decomposing traditional batch processing into stream-based transaction flows. Regional banks in Australia and the Nordics are deploying Apache Kafka and cloud-native event buses to synchronize account balances across mobile, web, and branch channels within milliseconds. This decomposition collapses the distinction between front-end experience layers and back-end ledger systems, enabling product teams to launch features without core system releases.
PSD2's Strong Customer Authentication requirements have hardened API security standards across European institutions. The European Banking Authority's technical standards mandate multi-factor authentication and dynamic linking for payment initiation, forcing vendors to embed behavioral biometrics and tokenization into gateway layers. French and German retail banks now treat security certification as a primary procurement filter, disqualifying platforms lacking eIDAS-qualified trust service integration.
Buyers are consolidating vendor relationships to reduce operational resilience audit burden. Large universal banks in the United Kingdom and Canada are terminating point solutions in favor of integrated platform contracts that bundle API management, identity verification, and analytics. This concentration shifts negotiation leverage toward vendors with broad functional coverage and documented operational continuity procedures.
Multichannel Digital Banking Integration Software Market Segmentation
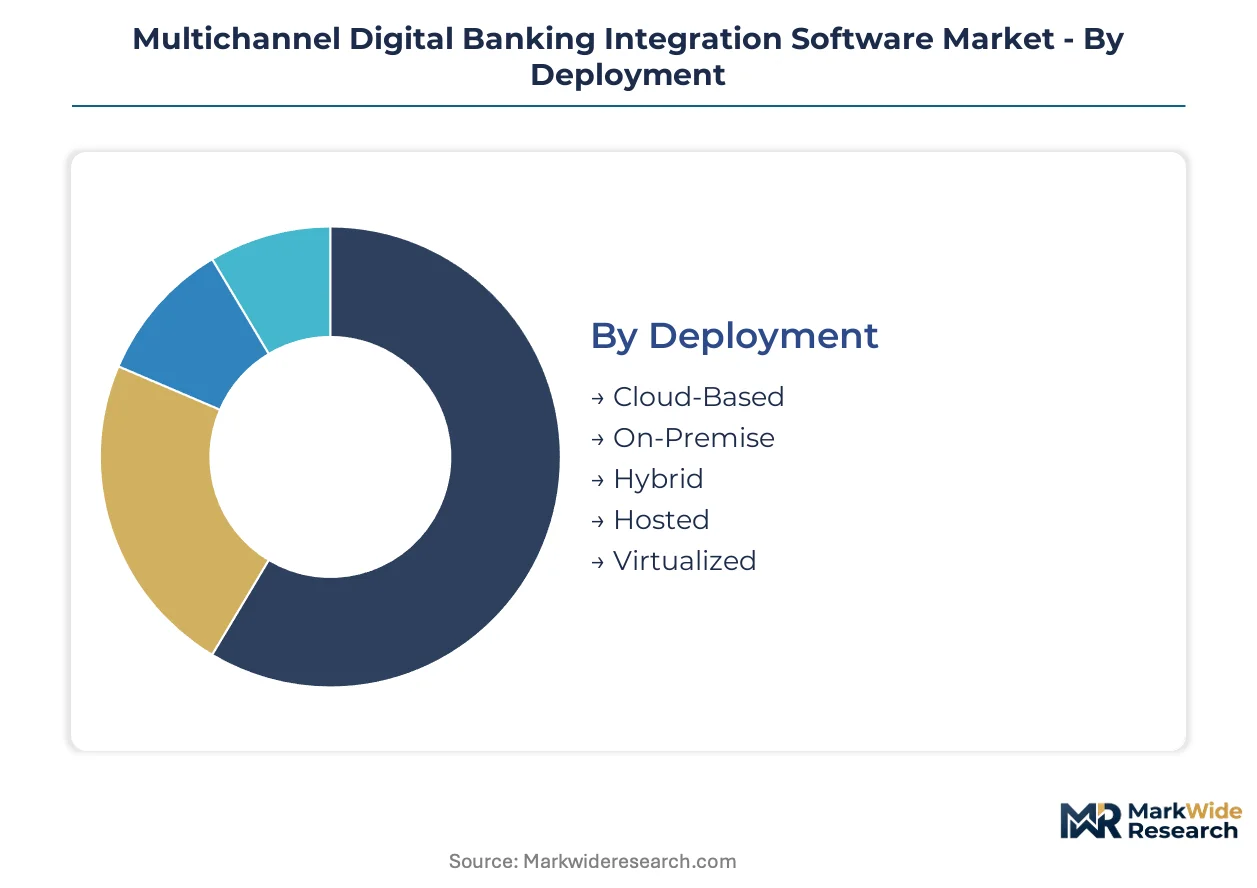
Segmentation in multichannel digital banking integration software reveals how procurement priorities diverge between legacy institutions seeking incremental modernization and digital-native entrants demanding API-first architectures from inception.
Deployment:
Geographic spread varies sharply by deployment model, with cloud-based adoption concentrated in jurisdictions with permissive data sovereignty frameworks while on-premise persists where localization mandates dominate.
- Cloud-Based:Elastic infrastructure enables banks to scale transaction processing capacity dynamically during peak payment windows. Demand concentrates among mid-sized institutions in Singapore and the Netherlands, where regulators have issued explicit cloud guidance that reduces compliance uncertainty.
- On-Premise:Fixed-capacity data centers maintain direct hardware control for institutions subject to strict data localization. German and Swiss banks favor this model given national banking supervisory requirements for physical infrastructure auditability.
- Hybrid:Combines sensitive core ledger operations on-premise with customer-facing channels in cloud environments. Indian regional banks deploy this architecture to satisfy RBI data localization rules while enabling UPI interoperability.
- Hosted:Third-party managed infrastructure offloads operational burden without full cloud abstraction. Credit unions in Canada select hosted deployments to access enterprise-grade security without dedicated IT staffing.
- Virtualized:Containerized workloads abstract hardware dependencies while retaining single-tenant isolation. Australian banks leverage virtualization to compress disaster recovery timelines across geographically distributed processing nodes.
Cloud-based deployment holds the largest share; momentum sits with hybrid configurations that balance regulatory compliance with channel agility.
Solution Type:
Cost tier stratification separates commodity payment processing from high-margin analytics layers, with API management commanding premium pricing due to open banking mandate complexity.
- API Management:Gateway platforms enforce security policies, rate limiting, and protocol translation between internal systems and external developers. European institutions under PSD2 and DORA obligations drive disproportionate procurement volume for certified API infrastructure.
- Payment Gateway:Transaction routing engines handle authorization, settlement, and reconciliation across card networks and real-time schemes. Brazilian banks upgrading to PIX instant payments represent concentrated demand for gateway replacement.
- Account Aggregation:Data consolidation layers unify balances and transaction histories across multiple financial relationships. UK open banking implementation has normalized aggregation as a baseline customer expectation.
- Fraud Detection:Real-time scoring engines analyze behavioral patterns and device fingerprints to flag anomalous transactions. Southeast Asian digital banks prioritize fraud layers given mobile-first customer acquisition without physical verification.
- Data Analytics:Customer insight platforms transform raw transaction streams into segmentation and propensity models. Wealth managers in the United States deploy analytics to personalize portfolio recommendations across digital touchpoints.
- Workflow Automation:Robotic process automation compresses loan origination, KYC verification, and compliance reporting cycles. Nordic banks target automation to offset high labor costs in back-office operations.
API management commands the dominant revenue share; workflow automation is expanding most quickly as institutions target operational cost reduction.
Application:
Customer type maturity separates established use cases from emerging digital workflows, with corporate finance applications trailing consumer banking in API-native redesign.
- Personal Banking:Retail account management, payment initiation, and self-service servicing across mobile and web channels. Indian banks under UPI mandate drive volume for real-time personal payment integration.
- Corporate Finance:Treasury management, multi-entity cash pooling, and automated payable-receivable matching. German Mittelstand banks seek corporate modules that interface with ERP systems from SAP and Oracle.
- Wealth Management:Portfolio aggregation, robo-advisory interfaces, and tax-optimized rebalancing across custodial relationships. Swiss private banks prioritize wealth applications for cross-border client segments.
- Loan Processing:Digital origination, document verification, and automated underwriting decisioning. US credit unions automate mortgage workflows to compete with non-bank lenders.
- Customer Support:Unified agent desktops integrating transaction history, CRM context, and communication channels. Australian banks consolidate support layers to reduce call center attrition costs.
- Regulatory Compliance:Automated reporting, audit trail generation, and risk data aggregation for supervisory submission. EU institutions facing DORA incident reporting deadlines accelerate compliance procurement.
Personal banking retains the largest installed base; loan processing is gaining share fastest as digital origination becomes a competitive differentiator.
End User:
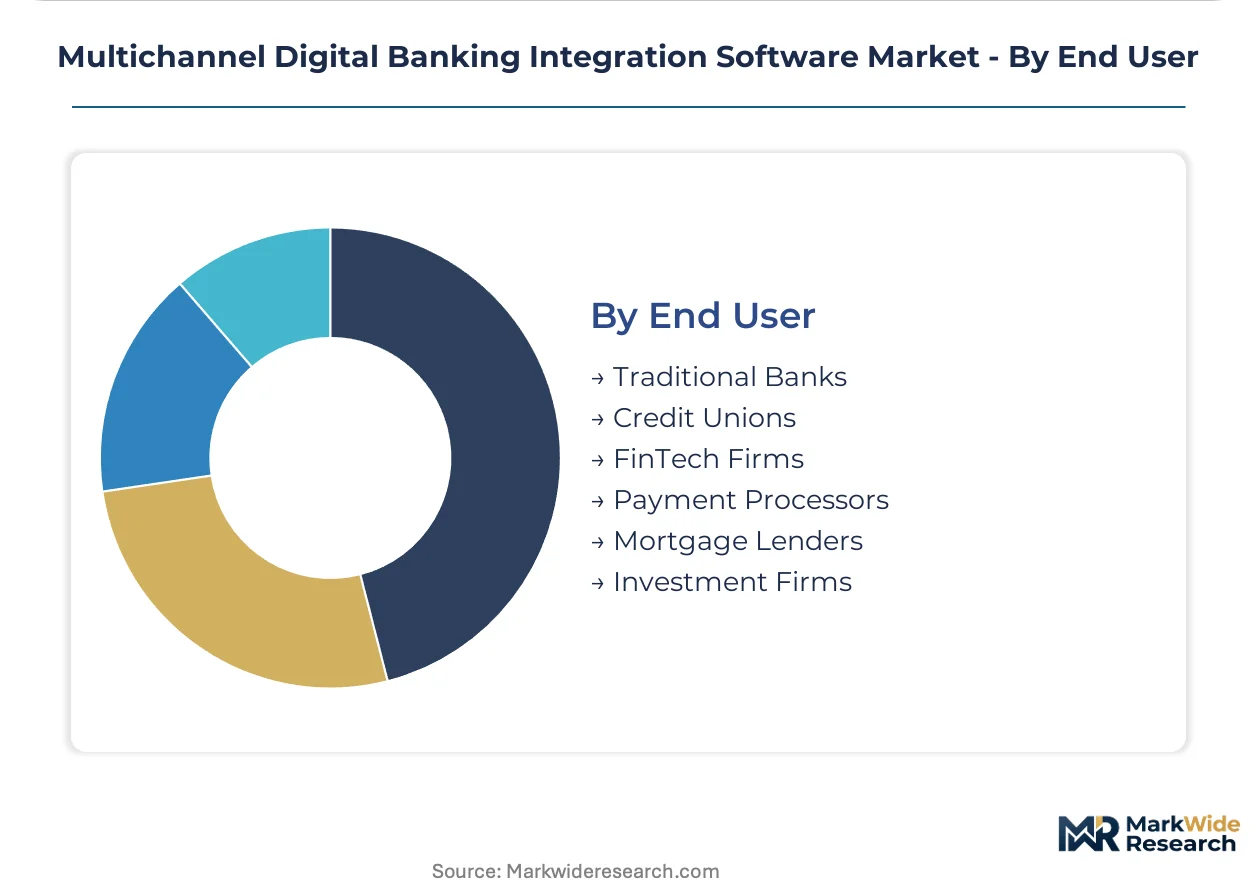
Institutional archetype determines functional requirements, with traditional banks prioritizing core system compatibility and FinTech firms demanding cloud-native modularity.
- Traditional Banks:Incumbent institutions with legacy core systems requiring abstraction layers for digital channel modernization. Regional banks in Spain and Italy dominate procurement for gradual migration pathways.
- Credit Unions:Cooperative institutions seeking member-centric platforms with limited IT staffing requirements. North American credit unions consolidating through merger waves drive unified platform demand.
- FinTech Firms:Digital-native entrants building banking services without legacy infrastructure encumbrance. Brazilian neobanks and Southeast Asian super-apps procure modular components for rapid feature deployment.
- Payment Processors:Specialized intermediaries requiring high-throughput, low-latency transaction routing. Indian payment system operators under NPCI oversight scale infrastructure for UPI volume growth.
- Mortgage Lenders:Specialized originators seeking automated valuation, document collection, and investor delivery workflows. UK building societies prioritize digital mortgage pipelines to compete with direct lenders.
- Investment Firms:Broker-dealers and asset managers requiring trade execution, portfolio accounting, and client reporting integration. US registered investment advisors demand unified platforms to reduce operational overhead.
Traditional banks account for the largest revenue pool; FinTech firms are climbing the fastest as embedded finance expands addressable market boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports multichannel digital banking integration software expertise to Southeast Asian markets, where real-time payment infrastructure builds replicate its UPI success model. European banks import API management capabilities from vendors with proven PSD2 compliance records.
United States
Mid-sized regional banks drive procurement volume as they consolidate disparate core systems into unified digital platforms. The OCC scrutinizes vendor concentration risk in critical banking infrastructure, prompting multi-vendor procurement strategies. Charlotte and Dallas banking clusters concentrate integration deployment for institutions serving 500,000 to 2 million customers.
India
The RBI's UPI interoperability protocols mandate standardized API gateways for instant payment processing at massive scale. NPCI oversight shapes technical specifications for payment system operators handling billion-transaction monthly volumes. Mumbai and Bengaluru fintech corridors host integration specialists serving domestic banks and export markets.
Germany
Mittelstand banks seek corporate finance modules interfacing with SAP and Oracle ERP ecosystems. BaFin enforces strict data localization requirements that favor on-premise or hybrid deployment architectures. Frankfurt's financial center anchors enterprise-grade integration projects for universal banks with complex cross-border operations.
Brazil
PIX instant payment adoption forces replacement of batch-oriented middleware with real-time API-native architectures. Banco Central do Brasil regulates payment system interoperability standards that shape vendor selection criteria. São Paulo's neobank cluster drives demand for modular cloud-native platforms enabling rapid feature deployment.
Australia
Apache Kafka and cloud-native event buses synchronize account balances across mobile, web, and branch channels within milliseconds. APRA prudential standards govern operational resilience requirements for critical banking infrastructure. Sydney and Melbourne financial centers deploy event-driven architectures to collapse front-end and back-end system distinctions.
Multichannel Digital Banking Integration Software Market Competitive Landscape
Player mix skews toward enterprise software conglomerates with banking-specialized divisions rather than pure-play fintech vendors. Market structure concentrates around three strategic tiers: cloud-native modular specialists, database-layer integration incumbents, and embedded finance platform providers. Dominant competitive moves include strategic partnerships between core banking vendors and hyperscale cloud providers, plus portfolio diversification into workflow automation layers.
Within the enterprise software tier, SAP Fioneer and Oracle occupy positions representing contrasting architectural philosophies—embedded finance depth versus database-layer unification. Temenos exemplifies the cloud-native specialist archetype with modular designs targeting regional bank implementation speed. These three anchors illustrate how vendor selection bifurcates between institutions prioritizing legacy system compatibility and those demanding API-first agility.
| Leading Market Players |
|---|
| SAP Fioneer |
| Salesforce |
| Oracle |
| Infosys Finacle |
| Temenos |
| Tata Consultancy Services |
| Finastra |
| ebankIT |
| Dais Software |
| Others |
Pricing and Supply Chain Analysis
API gateway substitution for legacy middleware stacks redraws supply geography toward India and Ireland while compressing pricing economics for on-premise perpetual licenses. Cloud-native container orchestration displaces fixed-capacity data center deployments, forcing vendors to absorb hyperscale infrastructure costs into subscription tiers.
Pricing Analysis
Next-generation event-driven architectures command 40-60% subscription premiums over prior-generation batch-oriented middleware, while current-generation API management platforms occupy the pricing middle. Pricing stratifies across premium, standard, and economy tiers with differentiation anchored in ISO 20022 certification status and sub-second latency guarantees. Cost compression in standard tiers is intensifying because Indian payment system operators negotiate volume-scaled enterprise agreements. Mid-sized regional banks exhibit highest price sensitivity, while universal banks with complex cross-border operations demonstrate lowest sensitivity due to operational resilience audit requirements.
Supply Chain Analysis
Container shipping congestion on Asia-Europe trade lanes elevates inbound logistics costs for German and Dutch banks procuring hardware appliances for hybrid deployments. Engineering talent concentrates in India, Ireland, and Singapore, with these jurisdictions anchoring vendor delivery centers and professional services capacity. The supply chain draws from legacy COBOL expertise pools, open-source Kafka committer networks, and hyperscale cloud compute reserves. Single-source vulnerability in cloud infrastructure creates concentration risk that BaFin and MAS now scrutinize explicitly. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as real-time payment infrastructure mandates across Brazil, India, and Australia create immediate procurement pull for API-native architectures.
For Market Incumbents: Consolidate workflow automation capabilities through targeted capability acquisitions to defend against pure-play RPA vendors encroaching on loan origination use cases. Deepen vertical integration into core banking abstraction layers to capture migration spend from batch-oriented legacy systems. Prioritize DORA-compliant audit documentation tools as recurring revenue anchors within European accounts. For New Entrants and Emerging Players: PSD2 certification fast-tracks through eIDAS-qualified trust service partnerships open immediate access to French and German retail bank procurement cycles. White-label embedded finance modules for Southeast Asian logistics platforms represent the most penetrable white-space target. Pursue channel partnerships with hyperscale cloud providers rather than direct enterprise sales buildout. For Investors and Strategic Acquirers: The market sits at an infrastructure replacement phase that favors cloud-native modular specialists with proven regional bank implementation velocity. Acquisition targets should demonstrate sub-90-day deployment timelines and ISO 20022 pre-certification. Monitor Brazilian PIX transaction volume growth as the signal to watch for middleware replacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Hyperscale Cloud Provider | Combines SAP Fioneer's embedded finance architecture with elastic infrastructure for mid-sized bank scalability. |
| Acquisition of Workflow Automation Specialist | Compresses loan origination cycles for credit unions competing against non-bank digital lenders. |
| ISO 20022 Pre-Certification Investment | Accelerates procurement decisions for Brazilian banks modernizing PIX instant payment infrastructure. |
| Geographic Expansion into Southeast Asia | Captures embedded finance demand from super-apps seeking white-label banking modules. |
| Platform Integration with ERP Ecosystems | Enables German Mittelstand banks to unify treasury management with SAP and Oracle corporate systems. |
Research Methodology
A standing panel of chief technology officers, integration platform engineers, regulatory compliance officers, and procurement leads at regional banks provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against RBI circulars, BaFin guidance notices, SEC 10-K infrastructure spend disclosures, and SWIFT ISO 20022 migration timelines. Bottom-up deployment counts across cloud, on-premise, and hybrid configurations were triangulated against top-down vendor revenue segmentation.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler financial services vertical revenue disclosures and payment system operator procurement announcements. The analytical framework modeled deployment mode, institution size tier, solution type, and regional regulatory cluster across the projection horizon. CAGRs were derived from slope analysis of adoption curves adjusted for mandate-driven acceleration effects. Forecast inputs incorporated real-time payment infrastructure buildout schedules and open banking regulatory compliance deadlines.
Underlying assumptions cover sustained regulatory pressure for API interoperability, with deviation risk concentrated in data localization rule fragmentation and cloud concentration enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Digital Banking Platform Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
IT Financial Management Tools Market
FinTech
China Fintech Market
FinTech
Vietnam Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
Cloud AI in Fintech Market
FinTech
Supply Chain Finance Market
FinTech
France BNPL Market
FinTech
Financial Consolidation Software Market
FinTech
Financial Forecasting Software Market
FinTech
Financial App Market
FinTech
Financial Management Software Market
FinTech
Blockchain in Fintech Market
FinTech
Wealthtech Solutions Market
FinTech
AI Finance Market