
 Gardasil (HPV Vaccine) Market | 2026-2036
Gardasil (HPV Vaccine) Market Size, Share, and Industry Trends Forecast 2026-2036
Gardasil (HPV Vaccine) Market Insights
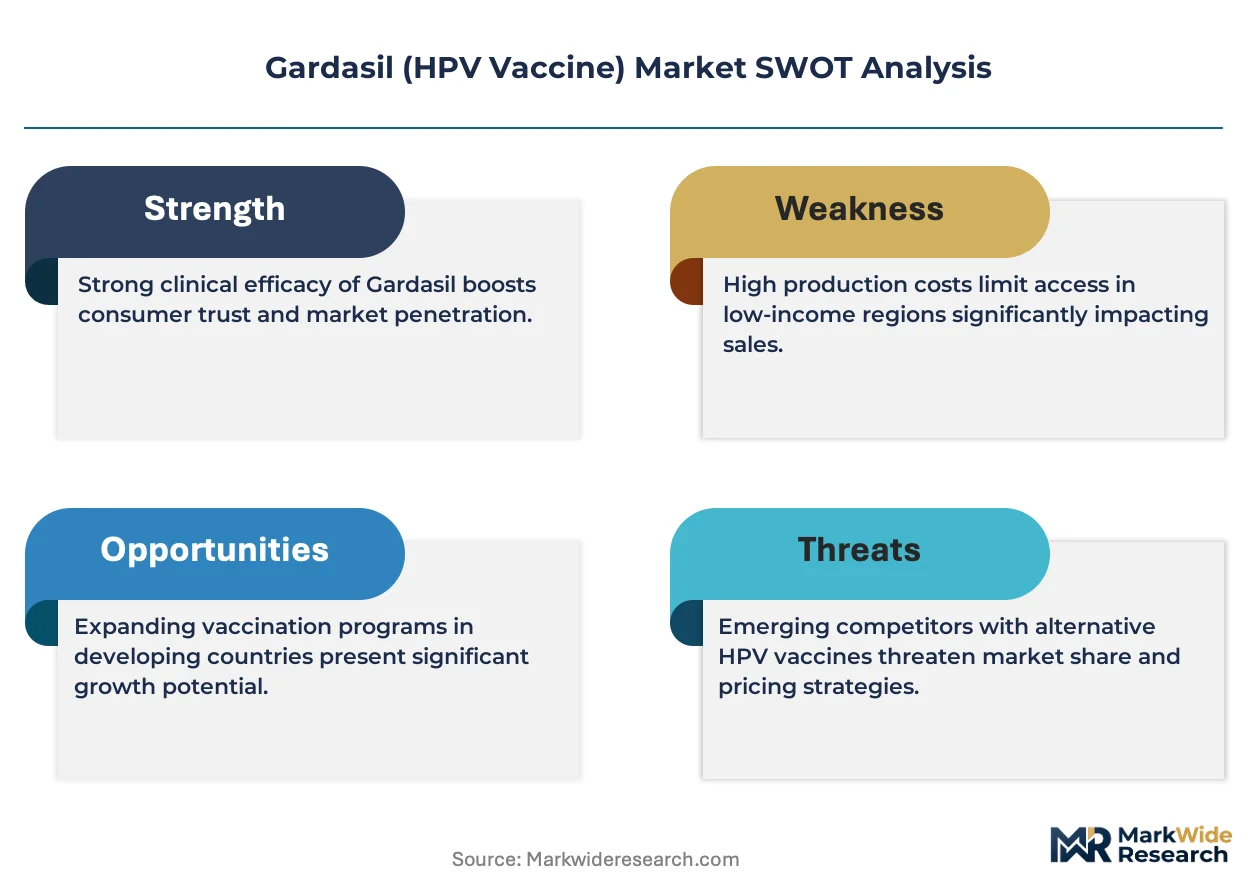
Nonavalent specification-grade coverage is unwinding the competitive baseline as healthcare systems prioritize broader serotype protection. Merck & Co., Inc. anchors the premium segment through decades of clinical data accumulation and WHO prequalification status. GlaxoSmithKline plc competes via its established bivalent platform in cost-sensitive procurement channels. Serum Institute of India Pvt. Ltd. leverages massive fill-finish capacity to supply emerging-market national programs at scale.
Gardasil (HPV Vaccine) comprises recombinant virus-like particles self-assembled from L1 major capsid proteins expressed in yeast or insect cell systems, formulated with proprietary adjuvants to induce neutralizing antibodies against oncogenic HPV serotypes. Its primary purpose is preventing cervical, oropharyngeal, and anogenital cancers through prophylactic immunization prior to viral exposure. The nonavalent product type commands the dominant value share due to expanded serotype coverage, while the intramuscular administration route remains structurally entrenched because cold-chain and injection infrastructure already exists at hospital and clinic end-user points. Research institutions represent a narrower but strategically significant segment where longitudinal efficacy data generates prescribing influence across the broader end-user base.
The FDA oversees manufacturing consistency and label expansion through BLA supplements, while WHO prequalification shapes access to Gavi-funded national programs in low-income settings. China's NMPA implements localized lot-release testing that adds regulatory steps for imported vaccines but creates protected runway for domestic manufacturers like Wantai BioPharm. Stakeholders must track how national immunization program inclusion decisions in high-population countries reshape volume allocation between multilateral procurement and direct commercial tenders.
Market Dynamics
Nonavalent vaccine platforms are compressing competitive timelines as healthcare systems prioritize broader serotype coverage over legacy bivalent formulations, forcing manufacturers to accelerate recombinant protein scale-up or exit procurement channels entirely.
Growth Catalysts
- Brazil's national immunization program expansion:Adolescent vaccination coverage mandates are creating sustained volume commitments through public procurement channels, locking in multi-year supply agreements.
- FDA accelerated approval pathways:Compressed development timelines for prophylactic vaccines are reducing capital-at-risk periods for novel candidates entering Phase III trials.
- Recombinant protein production scaling:Yeast and insect cell expression systems are achieving commercial yields that enable cost-competitive supply to emerging-market national programs.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile distribution failures in tropical climates degrade vaccine potency before administration, limiting effective reach despite manufacturing capacity.
- WHO prequalification bottlenecks:Lot-release testing delays for imported vaccines compress available supply windows during peak immunization seasons.
- Fill-finish capacity concentration:Sterile injectable manufacturing clusters in specific geographies create single-point vulnerabilities for global supply continuity.
Strategic Opportunities
- China's provincial CDC procurement networks:Domestic manufacturers capturing protected market access through NMPA localized testing requirements are building regional supply dominance.
- Oropharyngeal cancer prevention indication:Expanded label claims beyond cervical protection are opening adult male vaccination segments previously excluded from target populations.
- Single-dose regimen development:Immunological research into simplified dosing schedules is displacing multi-visit compliance barriers in resource-limited settings.
Industry Challenges
- Adjuvant formulation expertise scarcity:Proprietary immunostimulant development requires specialized talent pools concentrated at limited research institutions.
- Longitudinal efficacy data collection:Decades-long cancer endpoint studies demand sustained funding commitments that strain smaller development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gardasil (HPV Vaccine) Market |
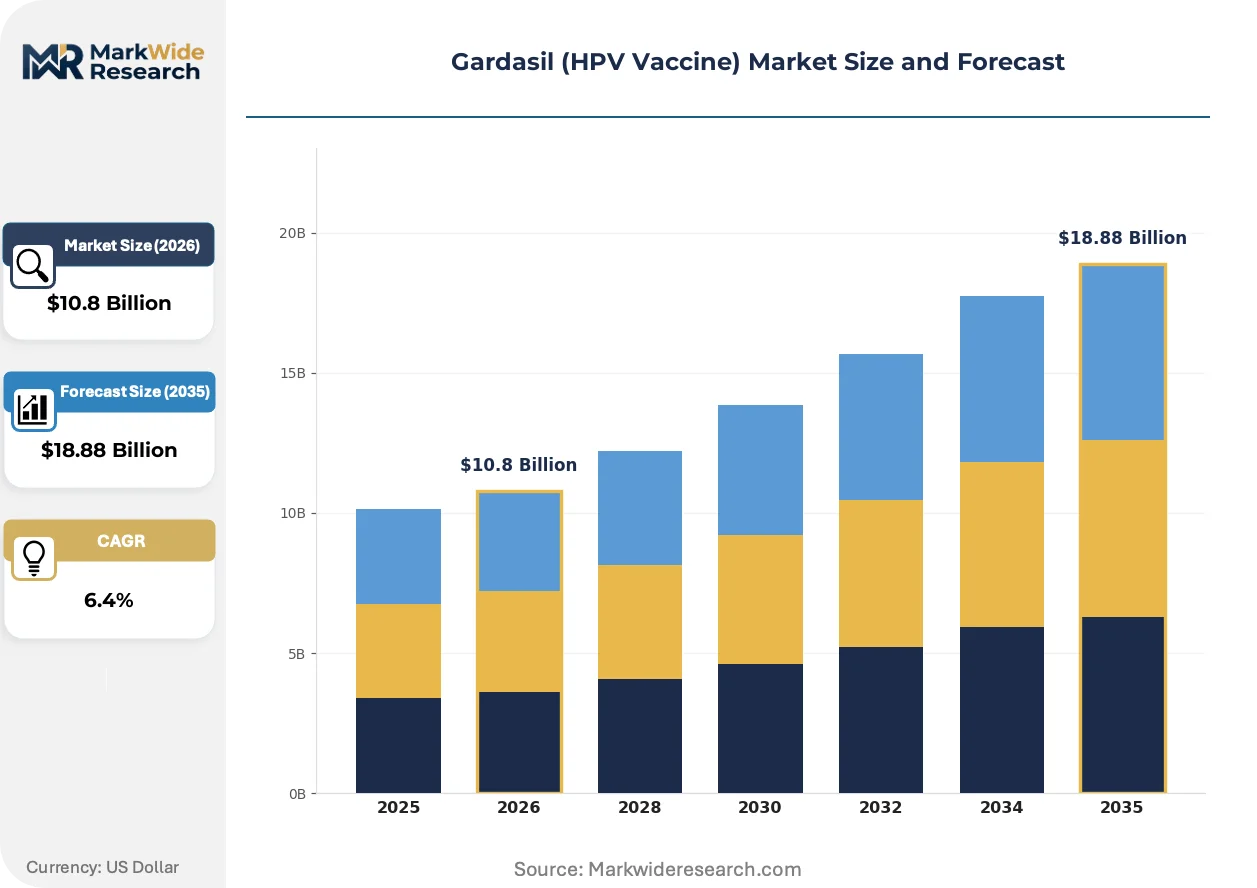
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrivalent, Nonavalent, Bivalent, Other Administration Route: Intramuscular, Subcutaneous, Oral, Others End User: Hospitals, Clinics, Pharmacies, Research Institutions Age Group: Teens, Young Adults, Middle-Aged, Seniors |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Sanofi Pasteur, Serum Institute of India Pvt. Ltd., Wantai BioPharm, Shanghai Zerun Biotech Co., Ltd., Pfizer Inc., CSL Limited, Panacea Biotec Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gardasil (HPV Vaccine) Market Trends and Innovations
Vaccine platform evolution is bifurcating between premium nonavalent coverage and cost-optimized regional alternatives, with regulatory science and procurement mechanics now determining competitive outcomes more than clinical efficacy alone.
Self-assembling virus-like particle technology is displacing traditional subunit approaches as the dominant manufacturing paradigm for HPV immunization. Hospital and clinic procurement committees are prioritizing candidates with demonstrated cross-neutralization breadth. This shift is compressing development investment timelines for bivalent platforms that cannot demonstrate comparable serotype coverage.
China's NMPA localized lot-release testing requirements are adding regulatory steps for imported vaccines while creating protected runway for domestic recombinant protein manufacturers. Multinational suppliers must duplicate quality control infrastructure or cede provincial CDC procurement networks to local competitors. The policy most affects premium-priced nonavalent products competing against emerging domestic alternatives.
Buyer concentration within national immunization programs is consolidating procurement leverage into single-tender mechanisms that prioritize volume scale over brand premium. Direct commercial channels are losing share to centralized CDC purchasing in high-population countries. Brazil and India's national program structures exemplify this mechanism most visibly.
Gardasil (HPV Vaccine) Market Segmentation
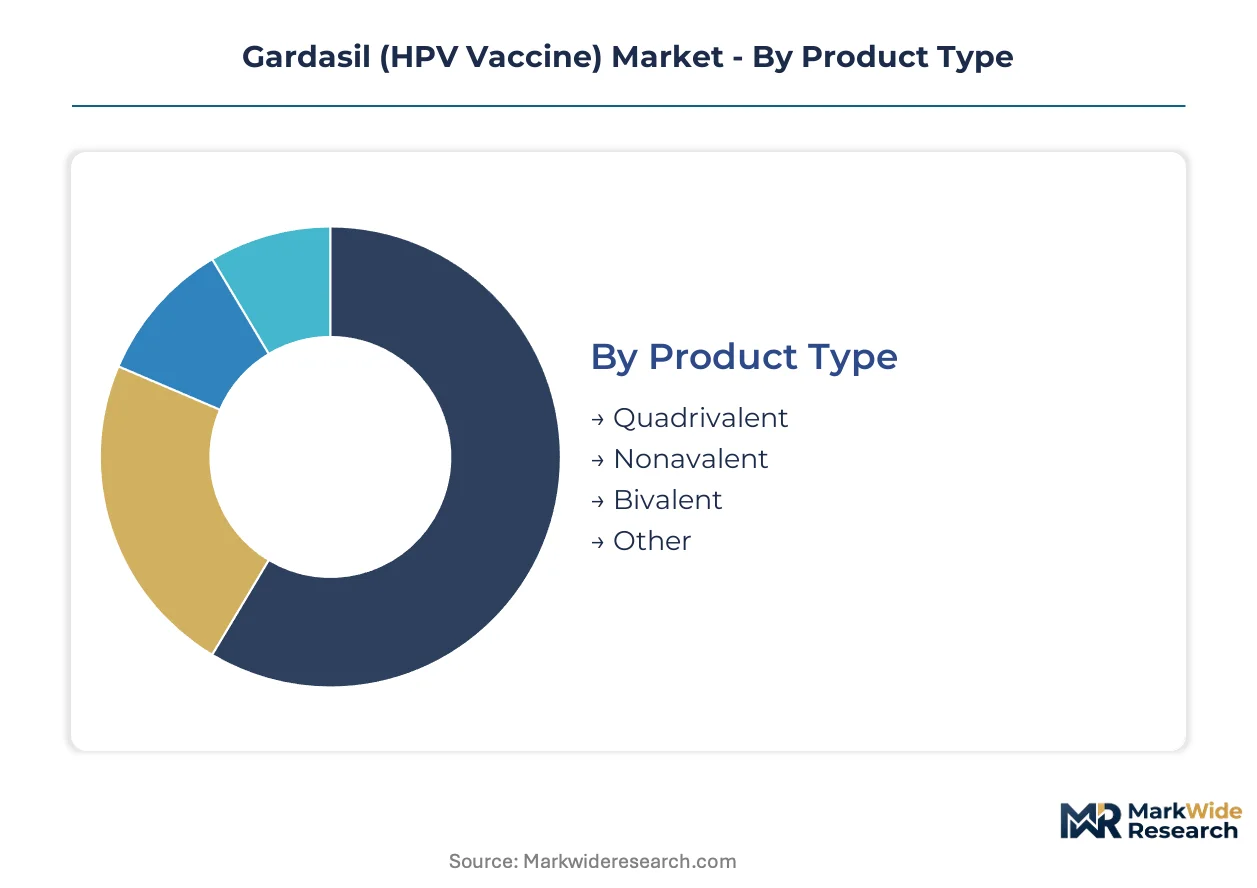
HPV vaccine procurement channels stratify sharply across product specifications and delivery settings. Margin capture concentrates where serotype breadth commands premium positioning and where cold-chain infrastructure determines effective market access.
Product Type:
Premium pricing power clusters around expanded serotype coverage, with recombinant protein manufacturing scale determining competitive viability across cost tiers.
- Nonavalent:Self-assembling virus-like particles target nine oncogenic HPV serotypes through yeast-derived L1 capsid protein expression. Brazil's national immunization program and China's provincial CDC networks concentrate demand as healthcare systems prioritize broader cancer prevention coverage over legacy alternatives.
- Quadrivalent:Four-serotype protection against HPV types 6, 11, 16, and 18 established the foundational clinical evidence base for prophylactic cervical cancer prevention. Procurement committees in cost-sensitive emerging markets continue specifying this platform where national budgets constrain access to nonavalent alternatives.
- Bivalent:Focused protection against HPV 16 and 18 leverages established fill-finish infrastructure.
- Other:Investigational multivalent candidates and therapeutic vaccine platforms occupy pre-commercial development stages.
Nonavalent holds installed capacity. Bivalent is rotating up the share rankings in procurement channels prioritizing cost containment.
Administration Route:
Delivery mechanism selection reflects cold-chain infrastructure maturity and healthcare worker training depth at the point of care.
- Intramuscular:Deltoid or anterolateral thigh injection remains structurally entrenched across hospital and clinic networks. Existing cold-chain preservation protocols and injection safety infrastructure at CDC distribution hubs in Brazil and provincial procurement centers in China reinforce this route's procurement dominance.
- Subcutaneous:Alternative delivery into adipose tissue layers offers potential compliance advantages in resource-limited settings where trained vaccinator availability constrains intramuscular administration.
- Oral:Mucosal immunization approaches remain experimental with no commercial formulation approved by FDA or WHO prequalification pathways.
- Others:Intradermal and nasal spray delivery mechanisms occupy early-phase clinical investigation.
Intramuscular commands procurement specification. Subcutaneous is climbing the fastest as simplified delivery research advances.
End User:
Channel concentration shapes volume allocation between public procurement tenders and direct commercial sales.
- Hospitals:Integrated health systems with captive pharmacy and outpatient clinic networks capture adolescent vaccination through scheduled well-child visits. Brazil's Sistema Único de Saúde hospital networks and China's tier-1 hospital systems concentrate procurement volume through centralized CDC allocation mechanisms.
- Clinics:Community-based primary care settings deliver the majority of routine immunization visits. These facilities depend on provincial and municipal cold-chain distribution infrastructure with limited on-site storage capacity.
- Pharmacies:Retail vaccination settings expand access for young adult catch-up doses outside pediatric care continuity.
- Research Institutions:Academic medical centers generate longitudinal efficacy data that shapes prescribing influence across broader end-user bases.
Hospitals hold installed capacity. Pharmacies are gaining share fastest as retail vaccination authorization expands.
Age Group:
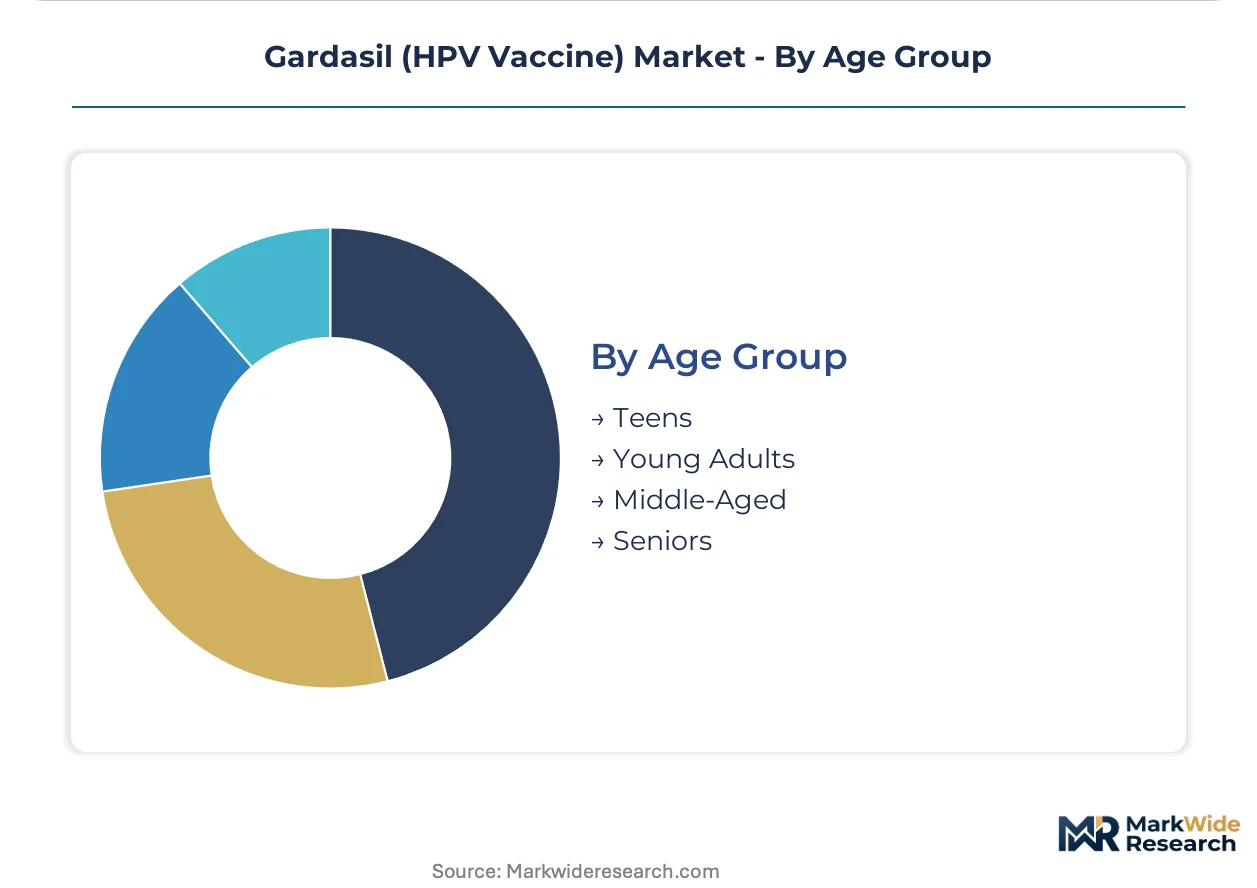
Target population segmentation determines dosing schedule optimization and indication expansion strategy.
- Teens:Adolescents aged 9-14 years represent the core prophylactic target prior to sexual debut and viral exposure. Brazil's national program mandates and school-based delivery mechanisms concentrate procurement volume in this cohort.
- Young Adults:Catch-up vaccination through age 26 captures individuals missed during adolescent programming. China's urban provincial CDC networks prioritize this segment as domestic manufacturers scale recombinant production.
- Middle-Aged:Adult vaccination through age 45 occupies expanding label claims as oropharyngeal cancer prevention evidence accumulates.
- Seniors:Older adult populations show limited vaccine-eligible indication scope given prior exposure prevalence.
Teens hold installed capacity. Young Adults are expanding most quickly as catch-up program coverage deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in HPV vaccines tilt toward import dependence in emerging markets while established manufacturing clusters in North America and Europe supply premium nonavalent formulations to procurement networks worldwide.
United States
FDA's accelerated approval pathways compress development timelines for prophylactic candidates entering Phase III trials. The agency oversees manufacturing consistency through BLA supplements while expanding label claims for oropharyngeal cancer prevention. Research institutions in Boston and the Research Triangle generate longitudinal efficacy data that shapes prescribing patterns across hospital networks.
China
Provincial CDC procurement networks concentrate demand as domestic manufacturers scale recombinant protein production. NMPA localized lot-release testing adds regulatory steps for imported vaccines while creating protected runway for Wantai BioPharm and Shanghai Zerun Biotech. Yangtze River Delta bioclusters in Shanghai and Suzhou anchor fill-finish capacity expansion for regional supply.
Brazil
National immunization program mandates drive sustained volume commitments through Sistema Único de Saúde public procurement channels. ANVISA regulates import lot-release testing that compresses available supply windows during peak adolescent vaccination seasons. São Paulo and Rio de Janeiro hospital networks concentrate cold-chain distribution infrastructure for last-mile delivery.
India
Serum Institute of India leverages massive fill-finish capacity to supply emerging-market national programs at scale. CDSCO regulates domestic manufacturing while WHO prequalification shapes access to Gavi-funded procurement in neighboring low-income settings. Hyderabad and Pune biotech corridors concentrate sterile injectable manufacturing for regional export.
Germany
EMA centralized marketing authorization procedures coordinate label expansion across member states while German hospital networks prioritize nonavalent coverage in adolescent vaccination protocols. Bavaria and Baden-Württemberg pharmaceutical clusters anchor clinical trial infrastructure for longitudinal cancer endpoint studies that support premium positioning.
Gardasil (HPV Vaccine) Market Competitive Landscape
Listed leaders compete with private specialists across regulatory science and procurement mechanics, with competitive outcomes now determined more by WHO prequalification status and national immunization program inclusion than clinical efficacy alone. The vendor base concentrates around three strategic archetypes: premium nonavalent innovators with decades of clinical data, cost-optimized regional suppliers leveraging fill-finish scale, and domestic protected-market players capturing provincial procurement through localized regulatory compliance. Dominant competitive moves include strategic partnerships for recombinant protein manufacturing scale-up and geographic expansion through Gavi-funded tender participation.
Within the premium-tier vector, Merck & Co., Inc. and GlaxoSmithKline plc exemplify archetypes differentiated by serotype breadth and cost positioning. Serum Institute of India Pvt. Ltd. occupies a scale-driven position supplying emerging-market national programs through volume-optimized procurement channels. These three anchors represent distinct competitive strategies: clinical data accumulation, established platform cost containment, and manufacturing scale leverage.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Sanofi Pasteur |
| Serum Institute of India Pvt. Ltd. |
| Wantai BioPharm |
| Shanghai Zerun Biotech Co., Ltd. |
| Pfizer Inc. |
| CSL Limited |
| Panacea Biotec Ltd. |
| Others |
Pricing and Supply Chain Analysis
WHO prequalification status gates both supply qualification to Gavi-funded national programs and price differentiation between premium nonavalent and cost-optimized bivalent tiers. This certification mechanism simultaneously determines which manufacturers access low-income procurement channels and which command brand premiums in direct commercial tenders.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium nonavalent formulations command price premiums based on FDA label breadth and WHO prequalification status, while cost compression in the bivalent tier intensifies as Serum Institute of India scales fill-finish capacity for emerging-market tenders. National immunization program procurement committees exhibit highest price sensitivity, whereas private hospital networks in China and Brazil demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Shanghai and Ningbo ports elevate inbound logistics costs for imported adjuvant raw materials. Yeast-derived L1 capsid protein production concentrates in the United States, China, and India, while proprietary aluminum-based adjuvant sourcing draws from limited specialty chemical suppliers in Germany and Japan. Single-source vulnerability in sterile injectable fill-finish capacity creates supply continuity risk. Distribution runs through national CDC cold-chain networks in Brazil and provincial procurement hubs in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for prophylactic vaccines compress development timelines and disrupt incumbent data accumulation advantages, creating entry windows for novel platform technologies.
For Market Incumbents: Consolidate longitudinal efficacy data advantages through expanded oropharyngeal cancer prevention label claims that emerging entrants cannot replicate without decade-long studies. Deepen backward integration into recombinant protein manufacturing by acquiring yeast expression system specialists in the Yangtze River Delta. Lock in multi-year supply agreements with Brazil's Sistema Único de Saúde before domestic manufacturers achieve WHO prequalification. For New Entrants and Emerging Players: Lead with single-dose regimen development targeting resource-limited settings where multi-visit compliance barriers exclude incumbent products. Capture white-space in China's provincial CDC procurement networks by navigating NMPA localized lot-release testing requirements that disadvantage imported vaccines. Pursue Gavi-funded tender participation as the primary go-to-market channel, leveraging cost-optimized bivalent platforms against premium nonavalent incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recombinant protein manufacturing as yeast and insect cell expression systems achieve commercial yield parity. Long-term viability over the next decade hinges on national immunization program inclusion decisions in high-population countries rather than clinical differentiation alone. Target acquisition candidates with existing WHO prequalification status or protected domestic market access through localized regulatory compliance. Monitor FDA label expansion timelines for oropharyngeal cancer prevention as the critical inflection signal for adult male vaccination segment opening.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks Gavi-funded procurement in low-income settings where national programs concentrate volume. |
| Recombinant Protein Scale-Up | Enables cost-competitive supply to emerging-market CDC networks competing against domestic manufacturers. |
| Label Expansion for Oropharyngeal Indication | Opens adult male vaccination segments previously excluded from core adolescent target populations. |
| Single-Dose Regimen Development | Displaces multi-visit compliance barriers in resource-limited settings with limited cold-chain infrastructure. |
| Provincial CDC Network Partnership | Secures protected market access in China through NMPA localized testing compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA BLA supplements, WHO prequalification databases, and national immunization program procurement records. Primary interviews engaged regulatory affairs leads at vaccine manufacturers, formulary directors at hospital systems, and procurement managers at Brazil's Ministry of Health and China's provincial CDC networks. Secondary validation drew from ClinicalTrials.gov entries, ANVISA import lot-release documentation, and Gavi tender award disclosures. Bottom-up volume estimates triangulated against top-down market sizing across recombinant protein production capacity and fill-finish throughput.
Segmentation dimensions modeled span product type, administration route, end-user channel, and age group across the projection horizon. CAGRs derived from regression analysis of historical procurement volumes against national program expansion timelines and domestic manufacturing capacity buildouts. Forecast inputs incorporated NMPA regulatory pathway timelines for Wantai BioPharm and Shanghai Zerun Biotech, plus cold-chain infrastructure deployment rates in tropical climates.
The analysis sits within stated boundaries; outcomes outside sustained national immunization program funding commitments or WHO prequalification timeline assumptions would require recalibration. Forecasts reflect documented assumptions regarding regulatory approval trajectories and procurement mechanism stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Blood Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market