
 Second Generation Cephalosporins Market | 2026-2036
Second Generation Cephalosporins Market Size, Share, and Industry Trends Forecast 2026-2036
Second Generation Cephalosporins Market Insights
Multi-source API procurement is hardening as a standard practice among finished-dose manufacturers seeking supply security. Pfizer Inc. leverages captive fermentation capacity across multiple geographies to buffer against raw material volatility. Lupin Limited anchors its position through backward integration into cephalosporin intermediate production in India. Sandoz Group AG competes aggressively on cost through high-volume generic manufacturing of cefuroxime and cefaclor.
Second generation cephalosporins comprise a class of beta-lactam antibiotics characterized by enhanced gram-negative coverage relative to first-generation agents, with cefuroxime demonstrating particular stability against many beta-lactamase enzymes; these agents serve primarily as empiric therapy for community-acquired respiratory and urinary tract infections where resistance surveillance guides formulary decisions. Injectable delivery modes command the dominant margin pool due to hospital preference for intravenous administration in acute bacterial infections, while oral formulations sustain volume leadership in step-down therapy and outpatient settings. Respiratory infection applications retain the largest therapy area footprint, though urinary tract infection indications are gaining protocol share as ambulatory treatment models expand.
FDA antimicrobial stewardship mandates and EMA good manufacturing practice inspections shape product standards and market access pathways for second generation cephalosporin manufacturers. The WHO Essential Medicines List inclusion criteria and national resistance monitoring programs in India and China further constrain which agents gain formulary placement. Stakeholders must monitor evolving carbapenem resistance patterns and corresponding hospital formulary restrictions to anticipate shifts in cephalosporin prescribing tiers.
Market Dynamics
Hospital formulary restrictions and antimicrobial stewardship mandates are compressing prescribing freedom for second generation cephalosporins, forcing manufacturers to demonstrate resistance surveillance value and therapeutic equivalency to retain tiered placement.
Growth Catalysts
- Community-acquired pneumonia protocols:Hospital infection control committees in the United States are expanding empiric cefuroxime use in step-down therapy pathways. This creates pull-through demand for matched oral formulations.
- EMA good manufacturing practice harmonization:Streamlined batch certification across European member states is reducing regulatory lag for multi-site manufacturers. API producers in India benefit from mutual recognition agreements.
- Carbapenem-sparing initiatives:Stewardship programs in tertiary care centers are elevating second generation cephalosporins as preferred alternatives for susceptible gram-negative infections. This preserves agent utility for resistant pathogen coverage.
Market Restraints
- Fermentation feedstock volatility:Corn steep liquor and soybean meal prices fluctuate with agricultural commodity cycles. This squeezes margin predictability for bulk API manufacturers dependent on biological starting materials.
- Single-source intermediate concentration:Production of 7-ACA and 7-ADCA intermediates clusters among three dominant suppliers in China and India. Any disruption propagates rapidly through finished-dose supply chains.
- Extended-spectrum beta-lactamase prevalence:Rising ESBL-producing Enterobacteriaceae in community settings erodes clinical confidence in cefuroxime empiric therapy. Physicians in high-prevalence regions pivot to carbapenems or combination agents.
Strategic Opportunities
- Fixed-dose combination development:Pairing cefuroxime with beta-lactamase inhibitors addresses emerging resistance mechanisms. Regulatory pathways for such combinations remain underutilized relative to standalone agents.
- Outpatient parenteral antimicrobial therapy expansion:Home infusion services in Germany and France are creating demand for stable, long-acting injectable formulations. This shifts site of care from inpatient to ambulatory settings.
- CDSCO fast-track designation:India's streamlined approval for anti-infectives addressing unmet resistance needs accelerates market entry for domestic innovators. Local manufacturers leverage this to compete with legacy multinational products.
Industry Challenges
- Stability testing for multi-source API switches:Finished-dose manufacturers must revalidate dissolution profiles and impurity specifications when qualifying alternate suppliers. This extends qualification timelines by months.
- Cross-contamination control in beta-lactam facilities:Dedicated production lines and HVAC segregation for cephalosporin manufacturing impose capital intensity. Smaller manufacturers struggle to justify facility investments against volume forecasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second Generation Cephalosporins Market |
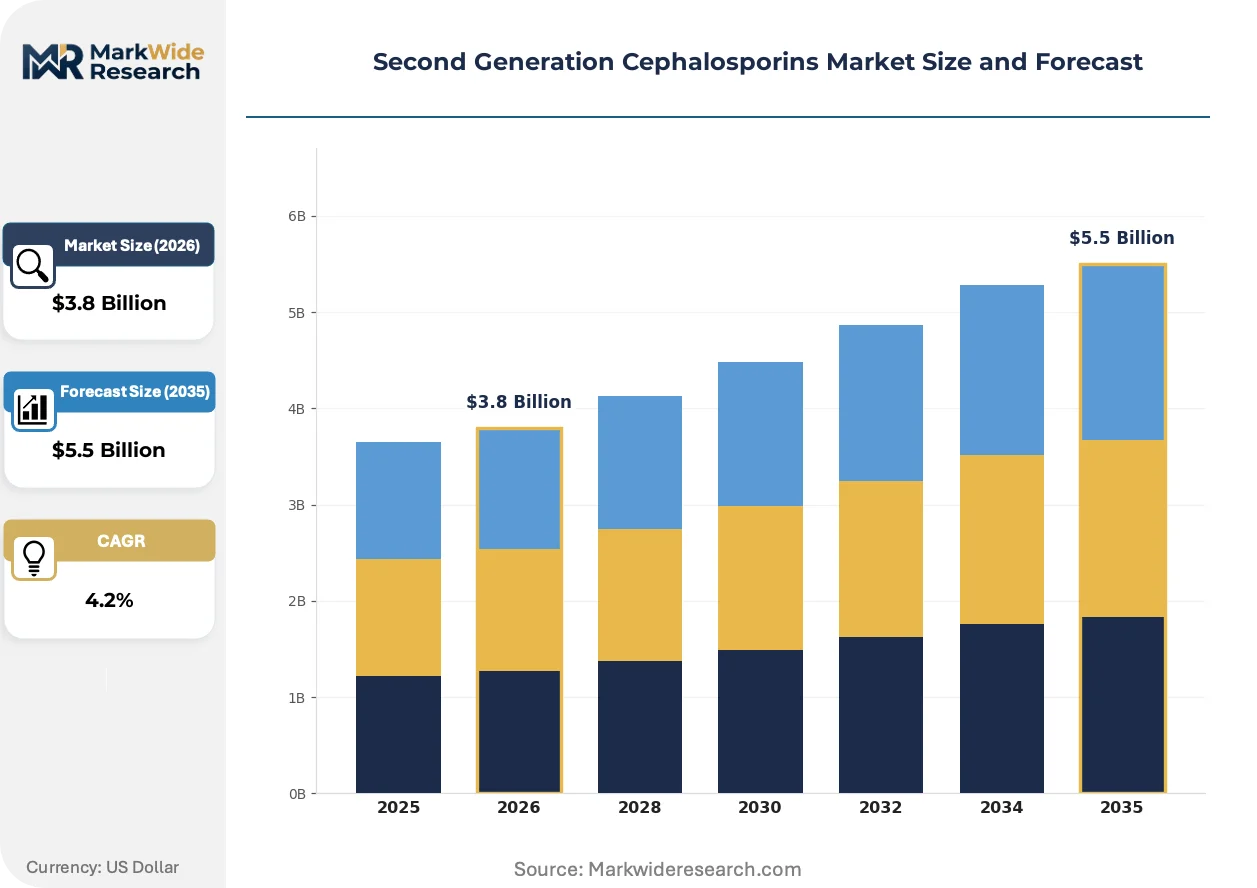
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cefuroxime, Cefaclor, Cefprozil, Cefamandole Therapy Area: Respiratory Infections, Skin Infections, Urinary Tract Infections, Bacterial Infections Delivery Mode: Injectable, Oral, Intravenous, Subcutaneous End User: Hospitals, Clinics, Long-term Care Facilities, Home Healthcare |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Merck & Co. Inc., Lupin Limited, Teva Pharmaceutical Industries Ltd, Sandoz Group AG, Abbott Laboratories, F. Hoffmann-La Roche AG, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second Generation Cephalosporins Market Trends and Innovations
Continuous manufacturing technologies and real-time release testing are displacing batch-oriented production paradigms in cephalosporin synthesis. These shifts compress cycle times and reduce in-process inventory holding costs.
Process analytical technology is automating in-line monitoring of fermentation parameters and crystallization endpoints. Contract manufacturers serving European markets are adopting PAT-enabled systems to reduce offline laboratory testing burdens. This automation is compressing batch release timelines from weeks to days while improving critical quality attribute consistency.
FDA's Quality Management Maturity program is elevating supplier qualification standards for sterile injectable facilities. Manufacturers must now demonstrate proactive quality system maturity rather than reactive compliance. Indian API-to-finished-dose integrators are investing in QMM-aligned documentation systems to maintain US market access.
Hospital purchasing consortia are consolidating antibiotic procurement under single-source or dual-source agreements with price-volume guarantees. This displaces fragmented spot purchasing and fragments the customer base into large contract holders and excluded smaller manufacturers. The United Kingdom's NHS Supply Chain and France's RESAH are most advanced in this consolidation.
Second Generation Cephalosporins Market Segmentation
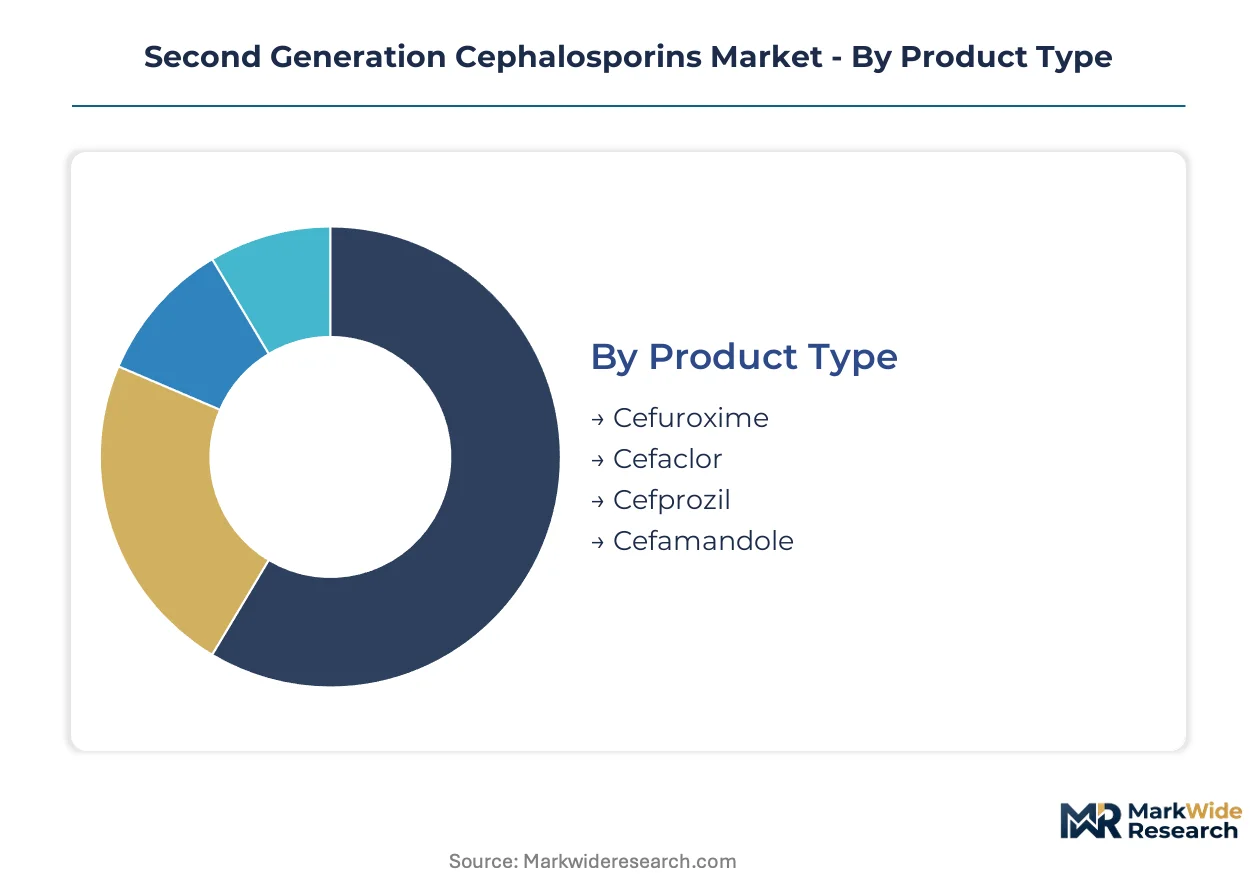
Second generation cephalosporin manufacturers align R&D investment and manufacturing capacity against distinct product, therapy, and delivery specifications. Segmentation clarity determines which formulations capture hospital formulary placement versus outpatient market share.
Product Type:
Chemical structure variations differentiate beta-lactamase stability spectra and gram-negative coverage profiles.
- Cefuroxime:The oxime-substituted side chain confers resistance to hydrolysis by common plasmid-mediated beta-lactamases. Hospital procurement in the United States concentrates on matched IV-to-oral step-down kits for community-acquired pneumonia protocols.
- Cefaclor:This oral agent demonstrates enhanced activity against Haemophilus influenzae relative to first-generation comparators. Indian domestic manufacturers scale cefaclor API production to serve price-sensitive outpatient markets across Southeast Asia.
- Cefprozil:Extended half-life supports twice-daily oral dosing compliance in pediatric otitis media regimens.
- Cefamandole:The N-methylthiotetrazole side chain mandates coagulation monitoring in prolonged therapy.
Cefuroxime leads on scale; cefprozil leads on momentum.
Therapy Area:
Infectious disease indication drives dosing regimen design and regulatory submission strategy.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis represent the largest prescription volume for second generation agents. German ambulatory care networks favor cefuroxime axetil for step-down from IV ceftriaxone in uncomplicated cases.
- Urinary Tract Infections:Uncomplicated cystitis in women drives high-volume oral cefaclor prescribing in France and Spain. Rising ESBL prevalence in community E. coli strains is compressing empiric confidence in these agents.
- Skin Infections:Cellulitis protocols in UK emergency departments retain cefuroxime for streptococcal coverage when MRSA risk is low.
- Bacterial Infections:Broad-spectrum empiric therapy captures mixed infection presentations where pathogen identification awaits culture results.
Respiratory Infections leads on scale; Urinary Tract Infections leads on momentum.
Delivery Mode:
Route of administration determines manufacturing complexity, stability requirements, and margin structure.
- Injectable:Sterile powder-for-injection formulations command premium pricing in hospital procurement. Lupin Limited and Sandoz Group AG compete on vial supply security for cefuroxime sodium in European tender processes.
- Intravenous:Ready-to-use IV bags reduce pharmacy compounding burden in US and German tertiary centers. Stability data requirements for frozen premix solutions extend development timelines.
- Oral:Tablet and suspension formulations serve step-down therapy and primary care initiation. Bioequivalence studies for generic cefaclor suspensions face tightening FDA dissolution profile standards.
- Subcutaneous:Outpatient parenteral antimicrobial therapy programs in France pilot subcutaneous cefuroxime for stable patients meeting home infusion criteria.
Injectable leads on scale; Subcutaneous leads on momentum.
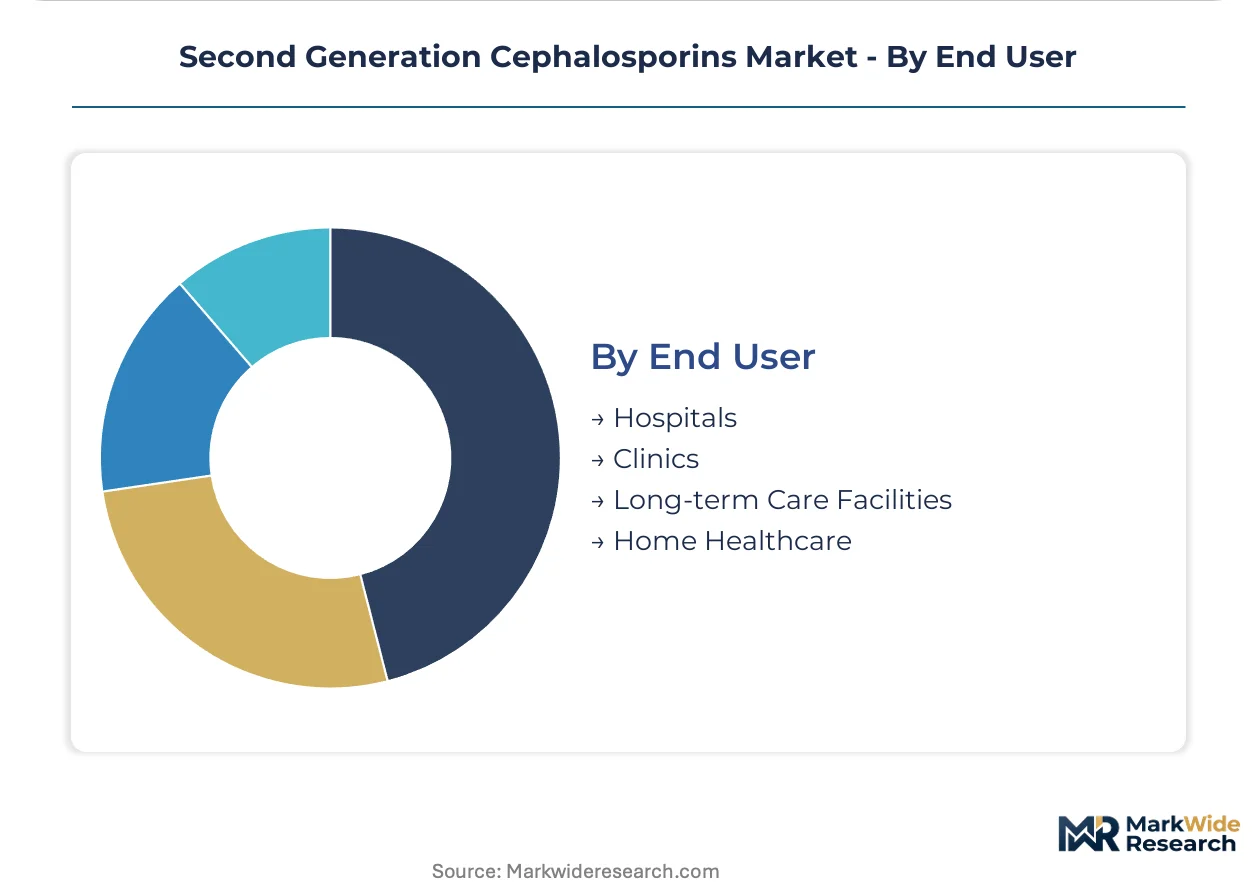
End User:
Care setting dictates formulary control mechanisms and purchasing consolidation patterns.
- Hospitals:Antimicrobial stewardship committees in US academic medical centers restrict second generation cephalosporins to protocol-defined indications. NHS Supply Chain in England consolidates antibiotic procurement under single-source agreements with 24-month price locks.
- Clinics:Primary care networks in India prescribe oral cefaclor and cefuroxime axetil for uncomplicated respiratory infections. CDSCO post-market surveillance programs monitor resistance trends in these high-volume settings.
- Long-term Care Facilities:Nursing home residents with recurrent UTIs receive extended oral courses where IV access is problematic.
- Home Healthcare:German home infusion providers expand OPAT services for stable patients completing IV cefuroxime courses post-discharge.
Hospitals leads on scale; Home Healthcare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's API-to-finished-dose corridor in Hyderabad and Ahmedabad anchors global supply for second generation cephalosporins, with domestic manufacturers scaling captive intermediate production to meet hospital procurement contracts across Europe and North America.
United States
Hospital stewardship committees at Cleveland Clinic and Mayo Clinic restrict cefuroxime to step-down protocols from carbapenems. FDA antimicrobial stewardship mandates tighten prescription criteria through 2025. New Jersey and Massachusetts house sterile injectable facilities serving NHS Supply Chain tenders.
Germany
Home infusion networks in Bavaria and North Rhine-Westphalia expand outpatient parenteral antimicrobial therapy for stable cefuroxime patients. EMA good manufacturing practice harmonization accelerates batch certification for Indian API suppliers. Frankfurt clusters pharmaceutical logistics for Central European distribution.
India
CDSCO fast-track designations for anti-infectives accelerate market entry for domestic innovators addressing unmet resistance needs. Maharashtra and Gujarat concentrate API fermentation capacity and finished-dose formulation plants. Lupin Limited anchors backward integration into cephalosporin intermediate production in Pune.
France
RESAH consolidates antibiotic procurement under dual-source agreements with 24-month price locks for hospital networks. Subcutaneous cefuroxime pilots in Paris and Lyon shift site of care from inpatient wards to home healthcare. ANSM monitors post-market resistance trends in high-volume primary care settings.
China
NMPA strengthens environmental inspections of fermentation facilities producing 7-ACA and 7-ADCA intermediates. Shandong and Jiangsu provinces concentrate three dominant intermediate suppliers whose disruptions propagate through global finished-dose chains. SAMR price controls compress margins for domestic generic manufacturers.
Second Generation Cephalosporins Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fixed-dose combination development and continuous manufacturing adoption. The vendor base stratifies across three tiers: multinational innovators with captive fermentation networks, Indian API-to-finished-dose integrators, and European generic specialists competing on tender pricing. Two strategic archetypes dominate: backward-integrated manufacturers controlling intermediate supply, and high-volume generic producers optimizing cost positions. Capacity expansion and regulatory harmonization partnerships constitute the primary competitive moves.
Among multinational pharmaceutical conglomerates, Pfizer Inc. and GlaxoSmithKline plc exemplify the captive-capacity archetype through multi-site fermentation networks. Lupin Limited represents the Indian integration model, anchoring its position through in-house intermediate production. Sandoz Group AG occupies the European generic specialist tier, competing aggressively on cost through high-volume manufacturing.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Merck & Co. Inc. |
| Lupin Limited |
| Teva Pharmaceutical Industries Ltd |
| Sandoz Group AG |
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Baxter International |
| Others |
Pricing and Supply Chain Analysis
Hospital purchasing consortia in the United Kingdom and France anchor procurement volume for second generation cephalosporins, compressing pricing power into long-term tender agreements with 24-month price locks. This buyer concentration forces manufacturers to absorb agricultural feedstock volatility rather than pass through costs.
Pricing Analysis
Corn steep liquor and soybean meal price swings pass through unevenly across manufacturer tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA QMM-certified sterile injectable facilities from standard GMP-compliant plants and commodity API traders. Price differentiation hinges on batch certification speed and dedicated beta-lactam line availability. Cost compression in the economy tier is intensifying because Chinese intermediate suppliers face NMPA environmental enforcement. Indian domestic manufacturers exhibit highest price sensitivity; multinational captive-fermentation networks least.
Supply Chain Analysis
Specialized fermentation technicians in Maharashtra and Gujarat, India, and Shandong and Jiangsu, China, constrain capacity expansion for 7-ACA and 7-ADCA intermediate production. Bulk API manufacturing draws from corn steep liquor, soybean meal, and purified water inputs. Single-source vulnerability concentrates among three dominant intermediate suppliers whose disruptions propagate through finished-dose chains. Distribution runs through pharmaceutical logistics clusters in Frankfurt and Mumbai serving hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Second generation cephalosporins constitute a late-cycle quality story where hospital formulary placement increasingly depends on resistance surveillance data packages and QMM-aligned documentation. Demand is shifting toward premium sterile injectable formulations with matched oral step-down kits.
For Market Incumbents: Acquire real-time release testing capabilities and PAT-enabled continuous manufacturing lines. Defensive consolidation requires securing captive 7-ACA intermediate supply through backward integration into Indian fermentation capacity. Carbapenem-sparing stewardship protocols threaten to displace empiric cefuroxime use; manufacturers must embed resistance surveillance services into hospital contracts to defend tiered placement. For New Entrants and Emerging Players: Fixed-dose combination development pairing cefuroxime with novel beta-lactamase inhibitors offers technology-first entry. White-space targets include subcutaneous outpatient parenteral antimicrobial therapy formulations for German and French home infusion networks, plus CDSCO fast-track anti-infective pathways for Indian domestic innovators. Go-to-market through hospital stewardship committee education on carbapenem preservation protocols. For Investors and Strategic Acquirers: Indian API-to-finished-dose integrators are the most active acquirer in this space, seeking sterile injectable facility assets with FDA QMM maturity ratings. Long-term viability rests on stewardship-driven formulary consolidation favoring manufacturers with captive intermediate supply and real-time release capabilities. Acquisition target archetype: mid-scale Indian manufacturers with incomplete backward integration. Signal to watch: NHS Supply Chain and RESAH tender consolidation accelerating toward single-source agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cephalosporin Intermediates | Lupin Limited's Pune facility demonstrates margin protection against 7-ACA supply disruptions. |
| FDA Quality Management Maturity Alignment | Indian API-to-finished-dose integrators invest in documentation systems to maintain US market access. |
| Fixed-Dose Combination Development | Pairing cefuroxime with beta-lactamase inhibitors addresses ESBL resistance mechanisms. |
| Continuous Manufacturing Adoption | PAT-enabled systems compress batch release timelines from weeks to days for European contract manufacturers. |
| Outpatient Parenteral Antimicrobial Therapy Expansion | German home infusion providers create demand for stable subcutaneous cefuroxime formulations. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and API trade flow tracking — were reconciled to construct market estimates. Primary interviews with drug development executives, formulary directors at US academic medical centers, hospital procurement managers in NHS Supply Chain, and CDSCO regulatory affairs leads informed demand-side assumptions. Secondary validation drew from FDA 483 inspection observations, EMA good manufacturing practice certification records, and Indian customs export data. Bottom-up volume modeling and top-down value reconciliation triangulated segment-level outputs.
Historical volume trends were cross-referenced against panel input from antimicrobial stewardship committees to calibrate projection trajectories across the analysis window. Segmentation dimensions modeled include chemical structure variation, therapy area indication, delivery mode, and end-user care setting. CAGRs were derived from fitted growth curves incorporating resistance surveillance trend data and formulary restriction intensity indices. Forecast inputs included carbapenem resistance prevalence rates and hospital purchasing consortium consolidation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ESBL prevalence acceleration, intermediate supply disruptions, and stewardship protocol stringency shifts. Forecasts reflect documented assumptions regarding regulatory harmonization progress and agricultural commodity price stability. Material deviation in carbapenem resistance trajectories or 7-ACA supplier concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Iron Deficiency Injectables Market