
 Anti-Aircraft Defense Systems Market | 2026-2036
Anti-Aircraft Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aircraft Defense Systems Market Analysis
Israel is reshaping competitive dynamics in the anti-aircraft defense sector through sustained investment in multi-layered interception architectures. Rafael Advanced Defense Systems leverages its Iron Dome pedigree to anchor missile system exports across Europe and Asia-Pacific. Lockheed Martin Corporation dominates integrated air-and-missile defense programs with its THAAD and PAC-3 product lines. Raytheon Technologies Corporation specializes in radar-enabled kill chains that extend from acquisition through intercept.
Anti-aircraft defense systems encompass kinetic and directed-energy platforms engineered to detect, track, and neutralize aerial threats including aircraft, missiles, and unmanned systems at ranges from point-defense to theater-wide coverage. These systems integrate phased-array radars, command-and-control networks, and interceptors with hit-to-kill or proximity-fuse warheads to protect military installations, population centers, and critical infrastructure. Missile Systems command the largest revenue share due to proven reliability against evolving threat vectors, while Laser Systems represent the fastest-expanding technology segment as solid-state and fiber-laser sources mature for counter-drone applications. AI-Enabled Systems are capturing disproportionate R&D allocation as autonomous target classification reduces operator burden in saturated airspace.
The US Department of Defense's National Defense Authorization Act shapes procurement priorities through hypersonic defense mandates and Indo-Pacific theater requirements. NATO's Air and Missile Defence Committee harmonizes interoperability standards across member arsenals, while the EU Green Deal's defense carve-outs under the European Defence Fund accelerate cross-border development of next-generation systems. Stakeholders must monitor directed-energy weapon maturation timelines and sovereign production requirements in priority export markets to align capability roadmaps with buyer industrial policy.
Market Dynamics
Directed-energy weapon maturation is collapsing traditional interceptor economics, forcing defense primes to reallocate R&D from kinetic kill vehicles toward solid-state laser and high-power microwave architectures. This technology shift compresses per-intercept costs from six-figure missile expenditures to single-digit dollar-per-shot operations, fundamentally restructuring procurement calculus across NATO and Indo-Pacific arsenals.
Growth Catalysts
- Hypersonic Defense Mandates:The US National Defense Authorization Act redirects acquisition budgets toward next-generation interceptors capable of countering maneuvering hypersonic glide vehicles. Defense primes are accelerating hit-to-kill technology maturation to meet operational requirements by 2030.
- Drone Proliferation:Loitering munitions and swarm tactics employed in Ukraine and Middle Eastern theaters drive urgent demand for point-defense layers. Militaries are procuring counter-UAS systems at unprecedented rates to protect forward operating bases.
- Indo-Pacific Theater Posture:Japan, Australia, and South Korea are expanding indigenous production capacity through technology transfer agreements with US and Israeli partners. Sovereign manufacturing requirements in these markets create localized supply chain incentives.
Market Restraints
- Rare Earth Element Concentration:Neodymium and dysprosium supply chains concentrate in Chinese processing facilities, creating vulnerability for permanent magnet components in radar gimbals and directed-energy beam steering systems.
- Interoperability Certification Costs:NATO's Air and Missile Defence Committee mandates STANAG compliance for cross-border system integration, imposing multi-year validation timelines and seven-figure testing expenditures on non-European suppliers.
- Gallium Nitride Substrate Shortage:Domestic production capacity for GaN-on-SiC wafers remains insufficient for simultaneous radar and electronic warfare demand, constraining active electronically scanned array output.
Strategic Opportunities
- Modular Open Systems Architecture:The US Department of Defense's modular open systems approach mandate creates entry points for software-defined radar and effector vendors previously excluded from prime contractor supply chains.
- European Sovereign Capacity:The European Defence Fund's permanent structured cooperation mechanism finances cross-border development of next-generation systems, offering non-EU primes joint venture pathways into continental procurement.
- Maritime Layered Defense:Navalized directed-energy and kinetic systems for carrier strike group protection represent underpenetrated demand, with the US Navy and Royal Navy accelerating shipboard laser integration programs.
Industry Challenges
- Systems Engineering Talent Scarcity:Integration of radar, command-and-control, and interceptor subsystems requires specialized expertise in model-based systems engineering that defense labor markets cannot supply at required scale.
- Legacy Radar Obsolescence:Mechanical scanning arrays in existing Patriot and Hawk batteries create sustainment burdens as component manufacturers discontinue vacuum tube and analog signal processor production.
- Test Range Capacity Bottlenecks:Live-fire validation of hypersonic interceptors requires exclusive access to White Sands Missile Range and Pacific Test Ranges, creating queue delays that compress development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aircraft Defense Systems Market |
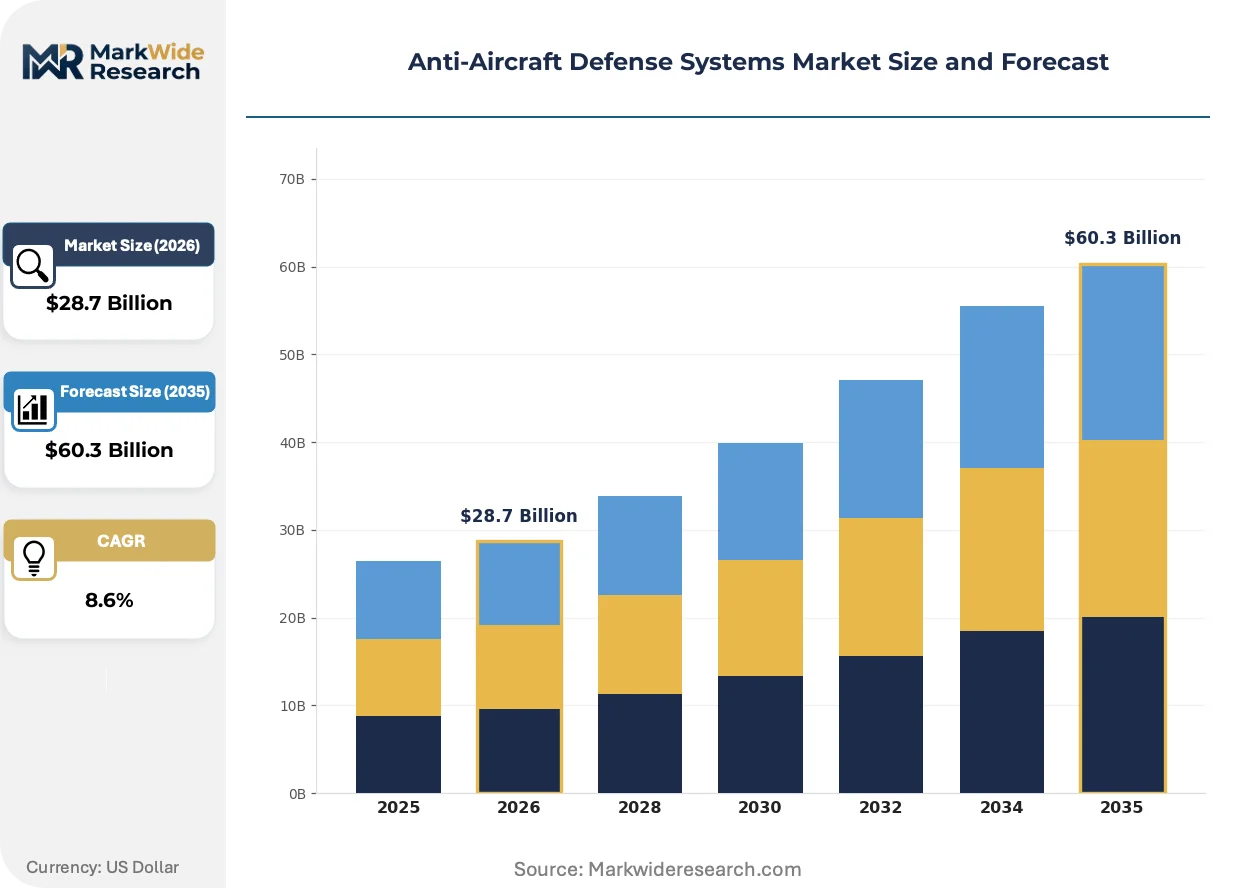
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $60.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missile Systems, Gun Systems, Laser Systems, Directed Energy Weapons Application: Military Use, Civilian Protection, Security Operations, Research & Development Technology: Guided Missiles, Radar Systems, Electronic Warfare, AI-Enabled Systems End User: Defense Forces, Government Agencies, Private Security Firms, International Organizations |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems, Thales Group, Rafael Advanced Defense Systems, MBDA, Saab AB, Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aircraft Defense Systems Market Emerging Trajectories
Artificial intelligence inference at the sensor edge is collapsing kill-chain latency, enabling autonomous target classification without human-in-the-loop authorization for saturated threat environments. This capability shift demands new hardware-software integration competencies across the defense industrial base.
Solid-state laser weapons are collapsing the cost-per-engagement economics that have dominated air defense procurement since the Cold War. The US Army's Indirect Fire Protection Capability program is fielding 300-kilowatt systems for counter-rocket and counter-drone missions. Defense primes are integrating fiber laser combiners and adaptive optics to achieve atmospheric compensation at tactically relevant ranges.
The EU AI Act establishes risk classification frameworks for autonomous targeting systems that weaponize machine learning algorithms. European defense procurement authorities are requiring algorithmic transparency documentation and human override protocols for AI-enabled fire control. Israeli and US suppliers are adapting export system architectures to satisfy Brussels conformity assessment procedures.
Allied militaries are consolidating maintenance and sustainment contracts under multi-year performance-based agreements that transfer operational risk to prime contractors. The Royal Australian Air Force's AIR 6500 program bundles system availability guarantees with spares provisioning and software update cycles. This structure displaces transactional spare-part purchasing and creates captive aftermarket revenue streams for integrated system providers.
Anti-Aircraft Defense Systems Market Segmentation
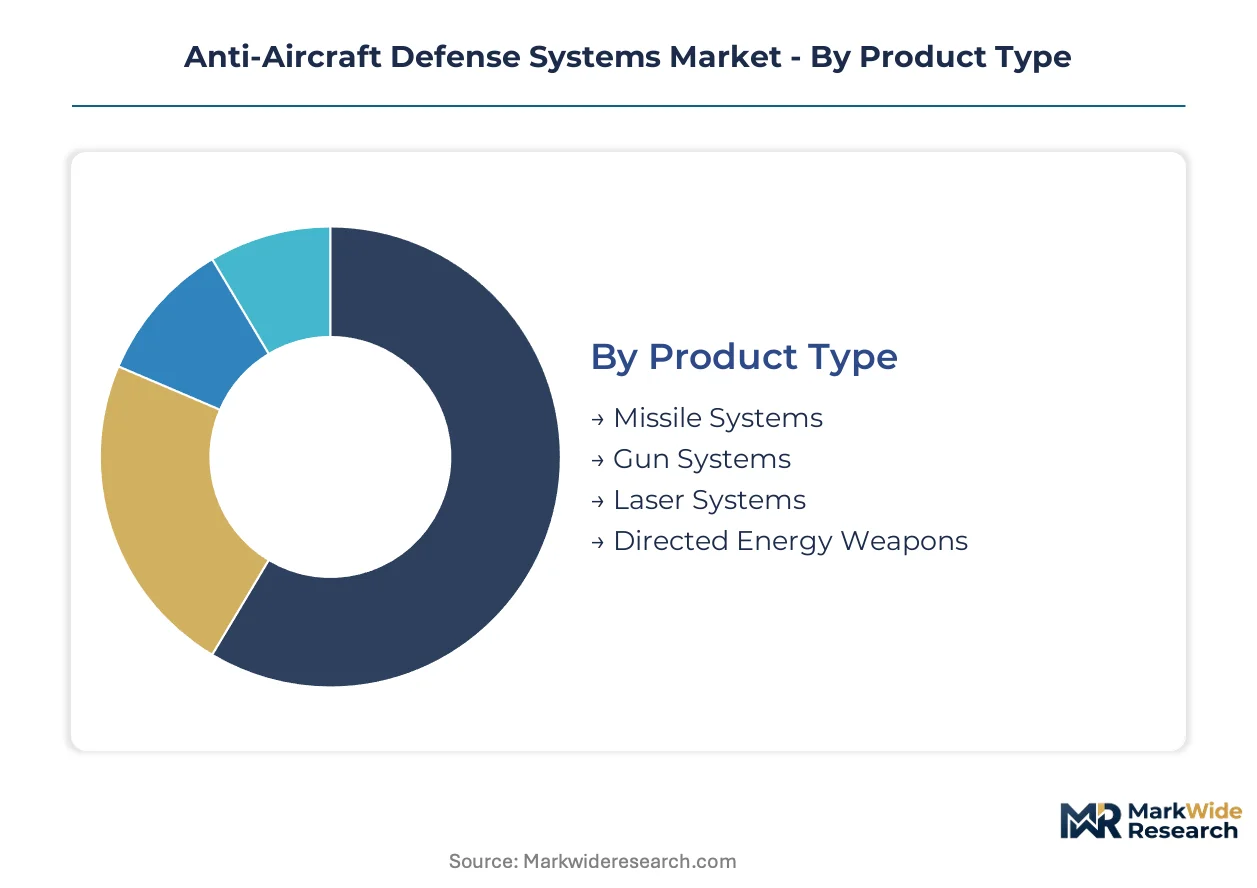
Defense procurement cycles vary dramatically across anti-aircraft system categories. Missile inventories refresh over 15-20 year horizons while directed-energy platforms iterate in 3-5 year sprints. Understanding these differential replacement rhythms shapes supplier capacity planning and R&D allocation decisions.
Product Type:
Cycle-time divergence separates kinetic interceptors with decades-long service lives from directed-energy weapons undergoing annual capability upgrades. Missile Systems anchor the revenue base through sustained fleet replenishment, while Laser Systems compress development-to-deployment timelines through software-defined performance improvements.
- Missile Systems:Solid-propellant and dual-thrust interceptors with hit-to-kill or blast-fragmentation warheads dominate layered defense architectures. The US Army's Patriot modernization and Japan's indigenous Type-03 programs sustain demand for advanced seekers and divert thrusters. Procurement concentrates in NATO and Indo-Pacific theaters responding to ballistic missile threats.
- Laser Systems:Solid-state and fiber-laser platforms deliver precision counter-UAS engagement at marginal per-shot cost. The US Army's Indirect Fire Protection Capability and Israeli Iron Beam deployments validate tactical utility. Solid-state laser maturation is collapsing engagement economics from six-figure missiles to single-digit dollar operations.
- Gun Systems:Revolver cannons and rotary autocannons provide terminal defense against saturation attacks.
- Directed Energy Weapons:High-power microwave and particle beam systems disrupt electronics through electromagnetic pulse effects.
Missile Systems anchors the volume base while Laser Systems gains share at the steepest rate.
Application:
Cost-tier stratification separates sovereign military procurement from commercial security spending. Military programs absorb integrated system premiums while civilian protection operates on constrained municipal budgets requiring modular, scalable configurations.
- Military Use:Integrated air-and-missile defense networks protect maneuver forces and fixed installations through layered radar and interceptor coordination. The US Indo-Pacific Command and NATO's Integrated Air and Missile Defence System drive standardization requirements. Multi-domain operations demand seamless interoperability between ground-based and naval platforms.
- Civilian Protection:Airport perimeter defense and critical infrastructure protection employ scaled-down radar and kinetic interceptors against drone incursions. German and French civil aviation authorities mandate counter-UAS coverage for major hubs. Regulatory frameworks under EASA and FAA jurisdiction shape procurement specifications.
- Security Operations:Private and government security services deploy portable detection and defeat systems for event protection.
- Research & Development:National laboratories and defense primes validate next-generation seeker algorithms and directed-energy beam control.
Military Use commands the premium tier while Civilian Protection expands most quickly through regulatory mandates.
Technology:
Supply concentration in semiconductor substrates and rare earth processing creates asymmetric vulnerability across technology categories. Radar and electronic warfare systems compete for identical gallium nitride wafer capacity, forcing prioritization trade-offs in prime contractor manufacturing.
- Guided Missiles:Infrared, radar, and multimodal seekers with divert thruster propulsion achieve precision endgame interception. Israeli and US seeker technologies dominate export markets through integrated kill-chain architectures. Hit-to-kill accuracy requirements drive investment in focal plane array and active radar homing subsystems.
- AI-Enabled Systems:Edge-deployed neural networks classify aerial targets and prioritize engagement sequences without human latency. The EU AI Act mandates algorithmic transparency and human override protocols for autonomous fire control. European procurement authorities require conformity assessment documentation from Israeli and US suppliers.
- Radar Systems:Active electronically scanned arrays with gallium nitride transmit-receive modules enable multi-target tracking.
- Electronic Warfare:Jamming and spoofing systems disrupt drone command links and missile guidance radars.
Guided Missiles retains the installed base while AI-Enabled Systems climbs the fastest through software upgrade cycles.
End User:
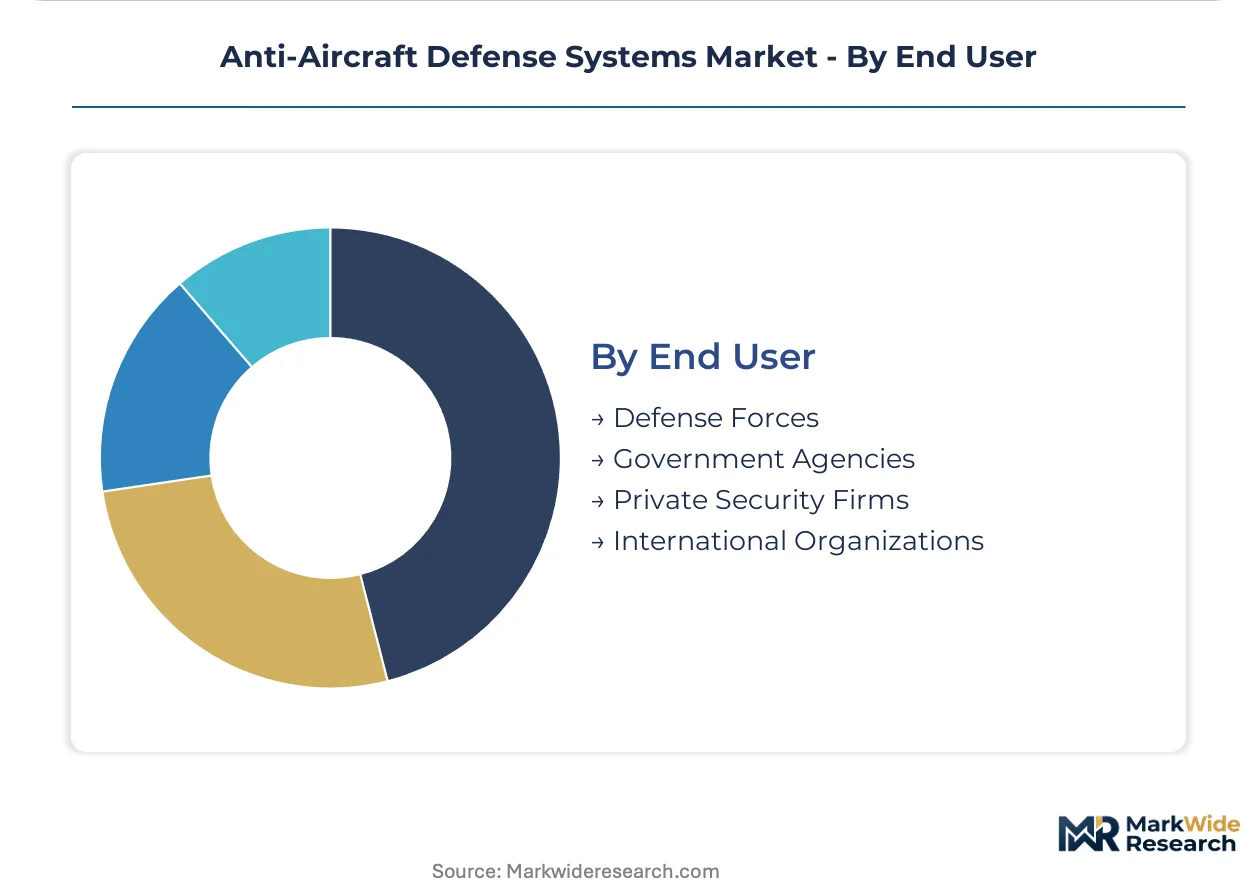
Customer-type differentiation separates classified program access from commercial off-the-shelf availability. Defense forces demand sovereign control over source code and supply chains while private security accepts black-box system integration.
- Defense Forces:National militaries operate theater-wide integrated defense networks with sovereign maintenance capabilities. Australia's AIR 6500 and South Korea's L-SAM programs mandate technology transfer for domestic production. Multi-year performance-based contracts transfer operational risk to prime contractors.
- Government Agencies:Border patrol and coast guard services deploy mobile radar and interceptor systems for territorial airspace monitoring. US Customs and Border Protection and EU Frontex coordinate counter-UAS procurement specifications. Interagency interoperability requirements complicate vendor selection processes.
- Private Security Firms:Commercial operators purchase portable detection and kinetic defeat systems for client site protection.
- International Organizations:UN and NATO peacekeeping missions lease integrated defense capabilities for force protection in contested environments.
Defense Forces dominates procurement value while Government Agencies shows the steepest expansion trajectory through border security investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permanent magnet processing for radar gimbals and directed-energy beam steering concentrates in Chinese facilities, creating supply vulnerability for defense primes assembling systems in NATO and Indo-Pacific theaters. This concentration shapes procurement security protocols and alternative sourcing investments across manufacturing bases.
United States
The National Defense Authorization Act mandates counter-hypersonic interceptor development by 2030, redirecting acquisition budgets toward next-generation hit-to-kill architectures. The FAA coordinates civil-military airspace integration standards for counter-UAS deployments around critical infrastructure. White Sands Missile Range and Pacific Test Ranges in New Mexico and California host live-fire validation queues that compress development schedules for primes.
Germany
The European Defence Fund finances cross-border development of layered air defense through permanent structured cooperation mechanisms. The KBA certifies military transport systems while Brussels conformity assessment procedures govern algorithmic transparency for AI-enabled fire control. Industrial clusters in Bavaria and Baden-Württemberg host subsystem integration facilities for radar and electronic warfare components.
Japan
The Ministry of Defense accelerates indigenous Type-03 interceptor production and joint-development programs with US partners under revised security guidelines. METI oversees technology transfer frameworks that mandate sovereign manufacturing capacity for critical subsystems. Manufacturing concentration in the Nagoya-Chubu corridor supports divert thruster and seeker assembly for layered defense architectures.
Australia
The Royal Australian Air Force's AIR 6500 program bundles system availability guarantees with multi-year performance-based sustainment contracts. The TGA framework influences dual-use export classifications for radar components with medical imaging applications. The Woomera Test Range in South Australia provides exclusive access for hypersonic interceptor validation outside congested US ranges.
Israel
Rafael Advanced Defense Systems anchors multi-layered interception exports across Europe and Asia-Pacific through technology transfer agreements. The national regulator for defense exports coordinates sovereign control requirements with buyer industrial policies. Industrial concentration in Haifa and the Negev Desert supports fiber-laser combiner development for Iron Beam deployments.
Anti-Aircraft Defense Systems Market Vendor Landscape
Integrated system primes and subsystem specialists split the market through differentiated risk-reward structures. The vendor base organizes around three archetypes: layered defense integrators commanding multi-billion dollar programs, directed-energy technology developers collapsing per-intercept economics, and radar component suppliers capturing gallium nitride substrate premiums. Competitive dynamics center on strategic partnerships for technology licensing and sovereign production mandates in priority export markets.
Within the integrated system tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify primes with established kill-chain architectures. Rafael Advanced Defense Systems occupies a distinct position representing Israeli multi-layered interception expertise. These three anchors illustrate how geographic origin and program heritage shape competitive positioning across NATO and Indo-Pacific procurement cycles.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| Rafael Advanced Defense Systems |
| MBDA |
| Saab AB |
| Israel Aerospace Industries |
| Others |
Supply Flow & Price Mechanics
The Nagoya-Chubu manufacturing corridor in Japan anchors global production capacity for divert thruster assemblies and active radar seeker subsystems, concentrating pricing power among Tier 1 primes that control technology transfer terms in Indo-Pacific procurement negotiations. This geographic concentration enables integrated system providers to command premium positioning for sovereign production mandates, while buyers face cost compression pressures from rare earth magnet dependencies and gallium nitride substrate shortages.
Pricing Analysis
The US National Defense Authorization Act dictates the pricing tier structure for counter-hypersonic interceptors, establishing three-tier pricing structure across premium, standard, and economy levels based on integration complexity and sovereign manufacturing requirements. Price differentiation rests on STANAG certification status and technology transfer depth, with NATO-compliant systems commanding substantial premiums over export-restricted configurations. Pricing pressure stems from directed-energy weapon maturation collapsing per-intercept economics, forcing kinetic system providers to absorb margin compression. Defense forces exhibit lowest price sensitivity due to operational risk transfer in performance-based contracts, while civilian protection operators face acute budget constraints requiring modular, scalable procurement.
Supply Chain Analysis
Contract manufacturing for gallium nitride-on-silicon carbide wafers concentrates at Cree Wolfspeed's New York facilities and II-VI Incorporated's operations, with additional substrate capacity at Sumitomo Electric in Japan. Raw material dependencies center on Chinese-processed neodymium and dysprosium for permanent magnet radar gimbals, Japanese-sourced high-purity gallium for semiconductor epitaxy, and Israeli fiber-laser combiner components for directed-energy systems. Supply chain risk manifests as single-source vulnerability for GaN substrates where radar and electronic warfare demands compete for identical wafer output. Distribution runs through prime contractor-led integrated system deliveries with multi-year sustainment bundling, displacing transactional component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among defense ministries consolidating procurement under multi-year performance-based agreements, fragmenting supplier leverage and transferring operational risk to primes. This consolidation dynamic rewards integrated system providers while pressuring subsystem specialists to accept captive supply relationships.
For Market Incumbents: Pre-empt directed-energy weapon displacement by accelerating solid-state laser and high-power microwave R&D through captive supply of gallium nitride substrates and adaptive optics subsystems. Lock in rare earth magnet sourcing via backward integration into alternative processing partnerships outside Chinese supply chains. Priority lever centers on securing exclusive test range access at Woomera and White Sands to compress development queues for hypersonic interceptors. For New Entrants and Emerging Players: Maritime layered defense for carrier strike group protection represents the most penetrable white-space target, with the US Navy and Royal Navy accelerating shipboard laser integration programs underserved by established primes. European sovereign capacity under the European Defence Fund's permanent structured cooperation mechanism offers joint venture pathways for non-EU technology developers. Go-to-market angle should emphasize modular open systems architecture compliance to exploit software-defined radar entry points previously excluded from prime contractor supply chains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors directed-energy technology developers collapsing per-intercept economics from six-figure missiles to single-digit dollar operations. Long-term viability across the analysis window hinges on algorithmic transparency capabilities satisfying EU AI Act conformity assessment procedures for autonomous fire control systems. Acquisition target archetype: Israeli or US subsystem specialists with proven fiber-laser combiner or edge-AI inference hardware. Signal to watch: White Sands Missile Range queue compression rates as indicator of hypersonic interceptor development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Directed-Energy Weapon Maturation | Solid-state laser deployment by the US Army's Indirect Fire Protection Capability program validates tactical utility and collapses engagement economics. |
| Sovereign Manufacturing Partnership | Japan's METI-mandated technology transfer frameworks for Type-03 interceptor production create localized supply chain incentives for foreign primes. |
| Algorithmic Transparency Investment | EU AI Act compliance documentation enables Israeli and US suppliers to maintain European defense procurement access for autonomous fire control systems. |
| Multi-Year Performance-Based Contracting | Australia's AIR 6500 program bundles availability guarantees with sustainment, creating captive aftermarket revenue streams for integrated providers. |
| Rare Earth Alternative Sourcing | Non-Chinese neodymium and dysprosium processing investments reduce vulnerability for permanent magnet components in radar and directed-energy systems. |
Methodological Framework
A spread of perspectives from program executives at integrated defense primes, procurement officers at NATO and Indo-Pacific defense ministries, radar subsystem engineering directors, and directed-energy weapon specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through US Department of Defense budget justification materials, NATO Air and Missile Defence Committee STANAG documentation, European Defence Fund project announcements, and SEC 10-K filings from publicly traded defense contractors. Bottom-up build-ups of segment-level demand were triangulated against top-down macro defense spending allocations across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling procurement cycles across missile systems with 15-20 year refresh horizons versus directed-energy platforms iterating in 3-5 year sprints. Segmentation dimensions included product type, application tier, technology maturity, and end-user sovereignty requirements, with additional modeling of gallium nitride substrate allocation trade-offs between radar and electronic warfare demand. CAGRs were derived from regression analysis of historical procurement patterns against threat environment intensification indicators, incorporating live-fire test range capacity constraints and technology transfer agreement velocity as industry-specific forecast inputs.
Practitioners should monitor directed-energy weapon fielding rates, rare earth processing facility commissioning outside China, and EU AI Act enforcement patterns for early signals of forecast revision. Assumptions underlying projections reflect current defense budget authorization trajectories, threat environment stability, and semiconductor substrate capacity expansion plans. Quarterly review of White Sands and Woomera test range queue lengths, gallium nitride wafer allocation announcements, and permanent structured cooperation project awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Airborne Fire Control Radar Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Global Missile Interceptor Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market