
 North America Ammunition Market | 2026-2036
North America Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ammunition Market Analytics
Modular packaging configurations for military small-caliber rounds is shifting procurement patterns across North America. Winchester Ammunition leverages backward integration into brass manufacturing to secure raw material supply for Department of Defense contracts. General Dynamics Ordnance and Tactical Systems anchors its position through large-scale Lake City Army Ammunition Plant operations. Hornady Manufacturing differentiates via precision match-grade product lines that command premium positioning in law enforcement channels.
North America ammunition encompasses projectiles, propellants, primers, and cartridge cases engineered to precise chamber-pressure and ballistic-coefficient specifications for reliable firearm discharge. Centerfire rounds dominate military and law enforcement procurement due to reloadability and higher pressure tolerance, while rimfire sustains volume in recreational and training segments where cost per round drives selection. The hunting end-user category occupies mature demand patterns tied to seasonal licensing cycles, whereas self-defense application channels through retail and e-commerce distribution show structural expansion in concealed-carry jurisdictions.
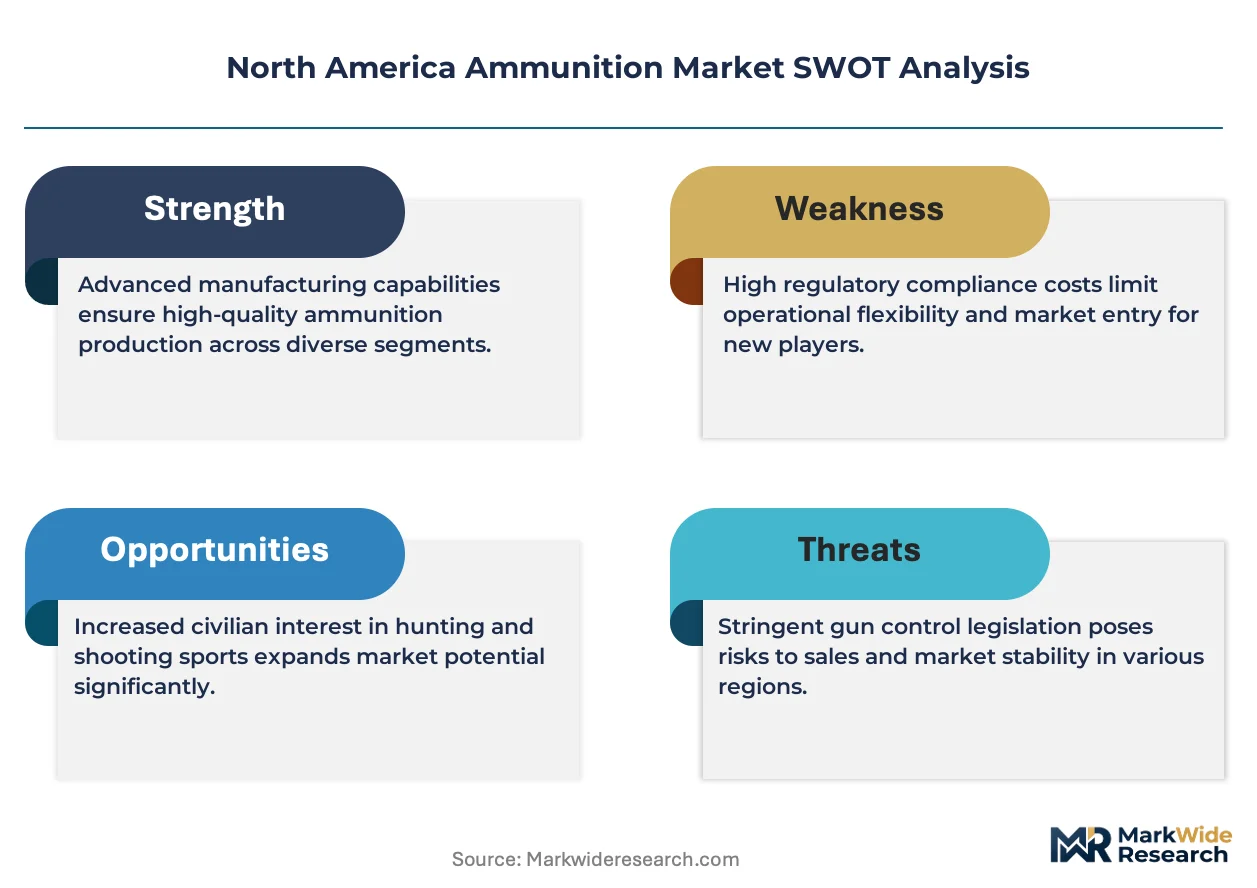
The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces manufacturing licensing and interstate commerce rules that constrain market entry, while Department of Defense Mil-Spec standards mandate lot consistency and traceability for all military-destined production. The Environmental Protection Agency regulates lead-content thresholds in manufacturing effluent, pressuring facilities toward non-toxic primer and bullet-core formulations. Stakeholders must monitor evolving state-level ammunition serialization proposals and NATO qualification testing protocols to anticipate compliance-driven capital requirements.
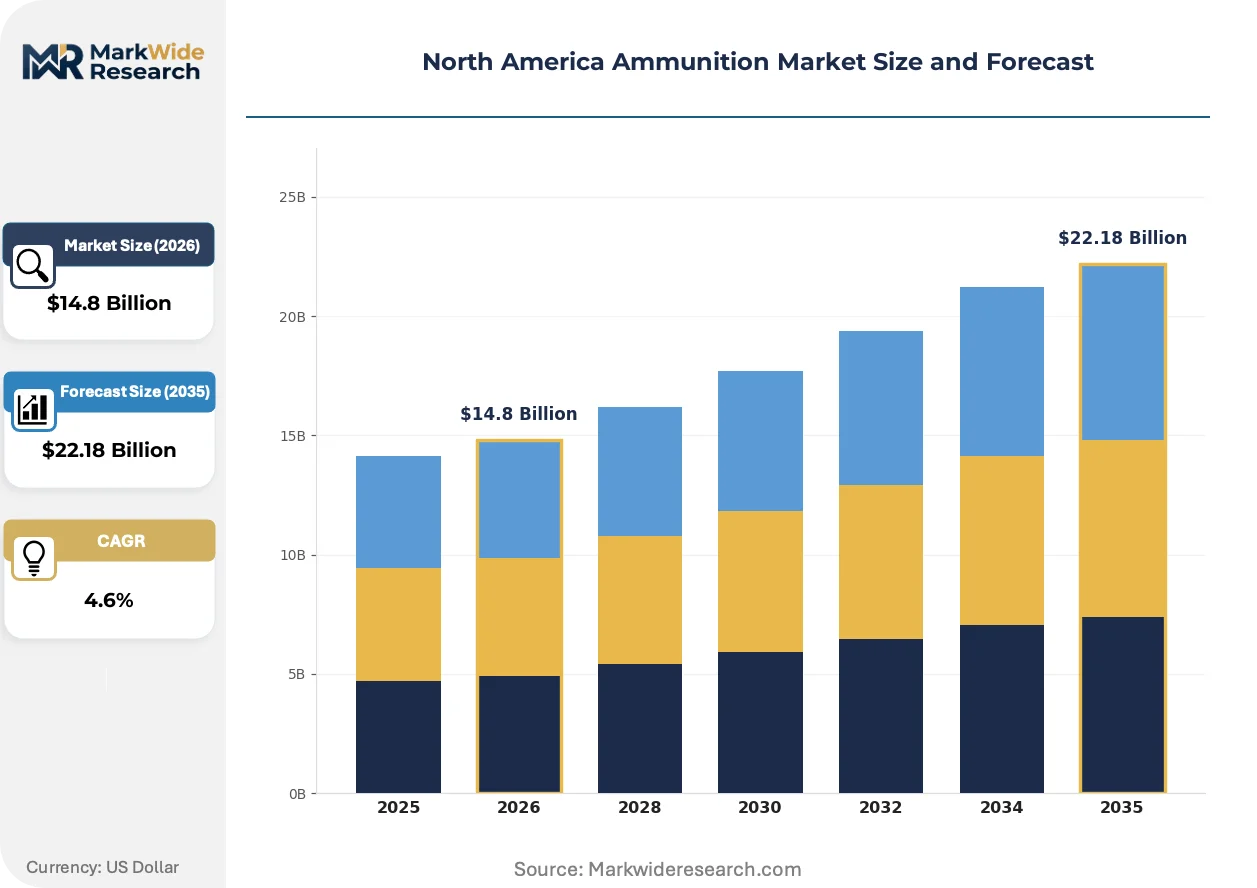
Market Dynamics
The Biden administration's ammunition procurement reforms and NATO standardization requirements are compressing contractor qualification timelines while expanding minimum lot-size thresholds, forcing mid-tier suppliers toward consolidation or joint-venture structures to meet volume and traceability mandates.
Growth Catalysts
- Department of Defense Mil-Spec standardization:Unified NATO qualification testing protocols are opening cross-border procurement pools for certified manufacturers, expanding addressable contract volume beyond domestic defense budgets.
- Lead-free primer chemistry:Non-toxic primer formulations are gaining regulatory preference under EPA manufacturing effluent rules, creating first-mover advantage for facilities with compliant production lines.
- Southwestern training installation concentration:Army and Marine Corps bulk purchases at Fort Bliss, Fort Hood, and Camp Pendleton generate recurring demand blocks that stabilize production scheduling for qualified suppliers.
Market Restraints
- Brass supply concentration:Captive brass manufacturing capacity limits raw material access for non-integrated competitors, elevating input cost volatility during commodity price swings.
- ATF licensing friction:Interstate commerce enforcement and manufacturing license renewal timelines create entry barriers that extend market penetration cycles for new facilities.
- Polymer-cased substitution threat:Lightweight composite cartridge cases for medium-caliber applications are displacing brass in select training scenarios, compressing traditional metalworking demand.
Strategic Opportunities
- Canadian defense procurement alignment:NORAD modernization funding streams are opening cross-border contract opportunities for US-based suppliers meeting Canadian military specifications.
- Precision match-grade law enforcement channels:Specialized sniper and tactical units are segmenting procurement toward premium ballistic-coefficient rounds with documented lot consistency.
- E-commerce self-defense distribution:Concealed-carry licensing expansion across southwestern and southeastern states is shifting ammunition purchases toward direct-to-consumer platforms with age-verification infrastructure.
Industry Challenges
- Ballistician talent scarcity:Specialized expertise in internal ballistics and propellant chemistry is concentrating at legacy facilities, constraining R&D velocity at newer market entrants.
- Lake City contract qualification timelines:Department of Defense source-approval processes for new production lines extend 18-36 months, freezing capital deployment until certification completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ammunition Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rimfire, Centerfire, Shotshell, Blank End User: Military, Law Enforcement, Sports Shooting, Hunting Application: Defense, Training, Self-Defense, Recreational Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | Winchester Ammunition, Ammo, Inc., General Dynamics Ordnance and Tactical Systems, Black Hills Ammunition, SIG Sauer, Northrop Grumman, Hornady Manufacturing, FN America, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ammunition Market Evolving Landscape
Modular packaging configurations and precision-manufacturing automation are compressing cost structures while elevating lot-traceability standards across military and law enforcement supply chains.
Polymer-cased ammunition technology is absorbing engineering investment from major prime contractors seeking weight reduction for dismounted infantry loadouts. Marine Corps expeditionary units are field-testing composite 5.56mm and 7.62mm rounds in arid climate conditions. The technology is absorbing procurement share from brass-cased equivalents in training applications where reloadability is not mission-critical.
EPA lead-content thresholds in manufacturing effluent are forcing propellant and primer facilities toward green chemistry reformulation. Winchester Ammunition and General Dynamics Ordnance have invested in non-toxic primer production lines at their primary US facilities. Military-destined production faces the most stringent compliance timelines, with lot-documentation requirements extending from point of manufacture through final firing.
Law enforcement agencies are consolidating ammunition purchases through state-level cooperative procurement vehicles, displacing fragmented municipal bidding processes. Texas and Arizona have established multi-jurisdictional contracts that aggregate demand from sheriff departments, highway patrol, and municipal tactical units. Southwestern states exhibit the most advanced cooperative structures, with standardized performance specifications reducing supplier qualification overhead.
North America Ammunition Market Segmentation
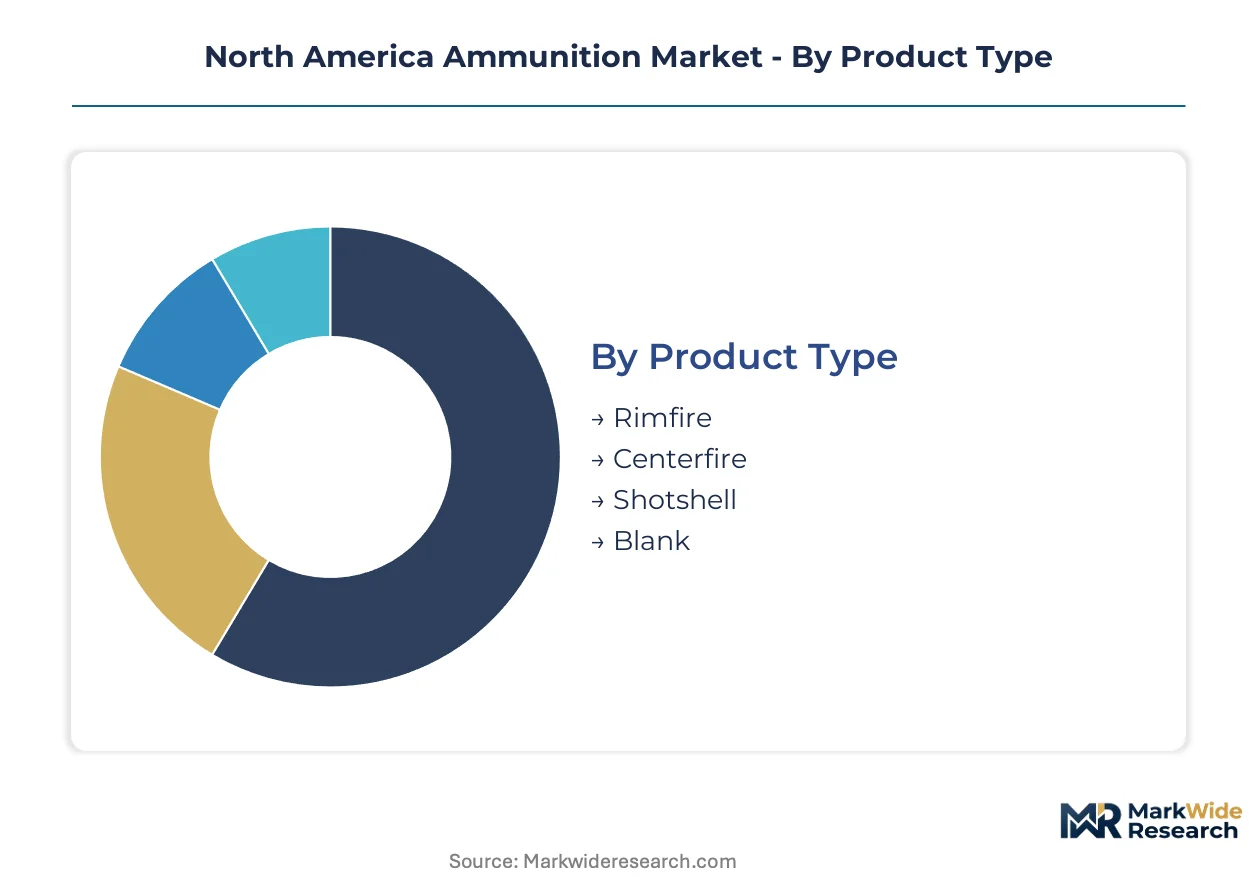
Ammunition procurement in North America operates through distinct technical and commercial channels that reshape contractor positioning. Understanding where volume concentrates versus where premium pricing commands margin reveals how suppliers allocate capital across production lines.
Product Type:
Centerfire rounds absorb the bulk of military and law enforcement contract value, while rimfire sustains recreational volume through cost-driven repeat purchases.
- Centerfire:Reloadable brass-cased construction tolerates higher chamber pressures required for NATO-standard rifle and pistol platforms. Department of Defense procurement at Lake City and commercial law enforcement channels concentrate demand here, with lot-traceability mandates favoring integrated manufacturers.
- Rimfire:Thin-walled brass construction with integral priming compound enables low-cost manufacturing for high-volume training and plinking applications. Cost per round drives selection at commercial ranges across Texas and Arizona, though margins compress against centerfire equivalents.
- Shotshell:Polymer or paper-hulled configurations loaded with lead or steel shot serve hunting and tactical breaching applications where pattern density matters.
- Blank:Cartridge cases crimped without projectiles generate muzzle report for ceremonial, training simulation, and cinematic use cases.
Today's leader: Centerfire. Tomorrow's challenger: Polymer-cased centerfire variants gaining share in expeditionary training.
End User:
Military procurement anchors contract stability, while law enforcement segments toward premium performance tiers and sports shooting fragments across price-sensitive retail.
- Military:Unified NATO qualification protocols and Mil-Spec lot consistency requirements compress supplier pools to certified prime contractors. Bulk orders from Army and Marine Corps training installations in the southwestern United States generate recurring demand blocks that stabilize production scheduling.
- Law Enforcement:State-level cooperative procurement vehicles in Texas and Arizona aggregate demand from sheriff departments and tactical units toward premium match-grade specifications with documented ballistic coefficient consistency.
- Sports Shooting:Recreational competitors and range members purchase across rimfire and centerfire categories with price elasticity varying by discipline.
- Hunting:Seasonal licensing cycles in rural states drive predictable demand spikes for shotshell and centerfire rifle configurations.
Military contracts provide volume foundation. Law enforcement channels deliver margin expansion fastest.
Application:
Defense applications concentrate procurement through federal channels, while training absorbs the highest round counts and self-defense channels shift toward direct-to-consumer distribution.
- Defense:Combat-destined ammunition faces stringent NATO interoperability testing and supply chain security protocols that extend qualification timelines.
- Training:Bulk purchases at Fort Bliss, Fort Hood, and Camp Pendleton generate recurring demand for standard ball and reduced-range training rounds where reloadability is non-critical.
- Self-Defense:Concealed-carry licensing expansion across southwestern and southeastern states shifts purchases toward hollow-point and specialty defensive loads distributed through e-commerce with age-verification infrastructure.
- Recreational:Weekend range visits and competitive shooting events sustain rimfire volume through cost-per-round sensitivity.
Training commands round volume. Self-defense is climbing the fastest as concealed-carry jurisdictions multiply.
Distribution Channel:
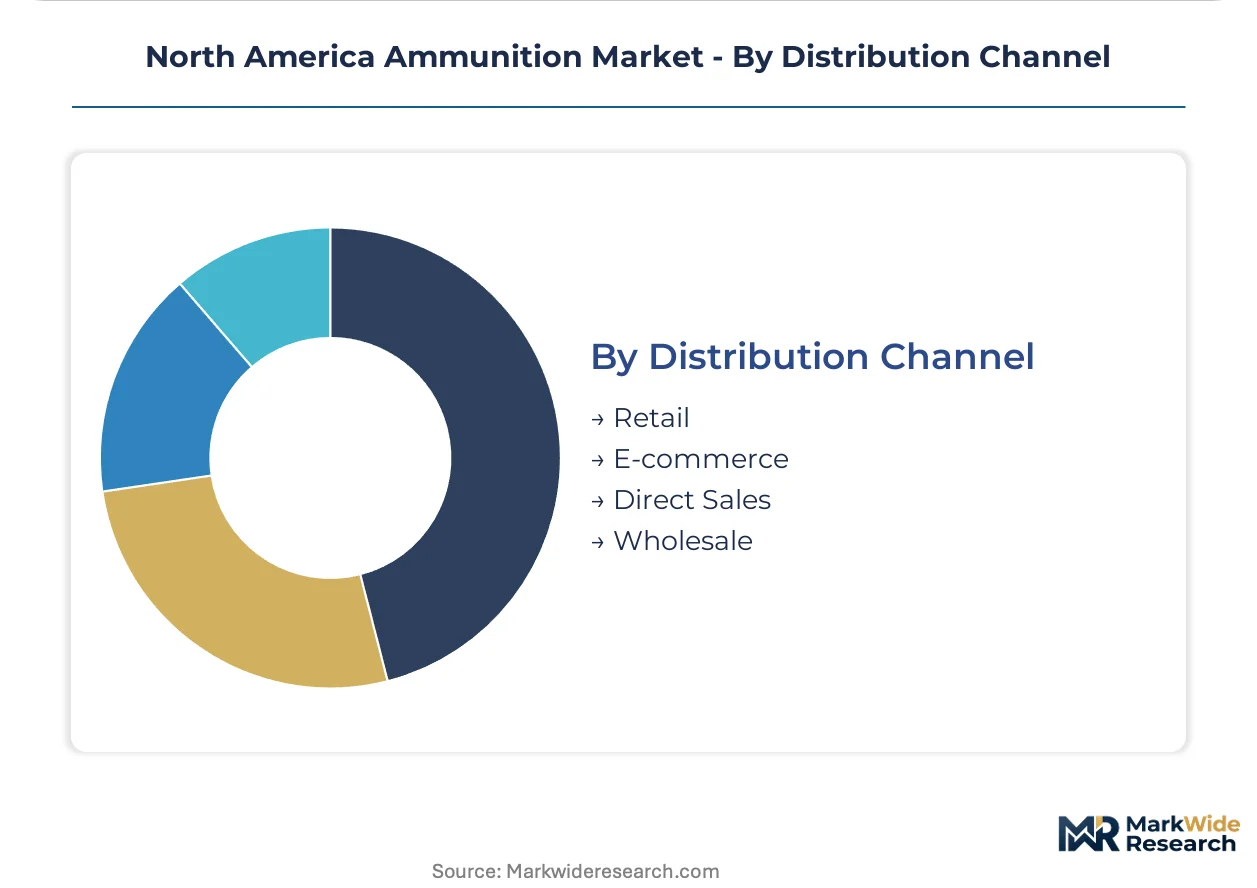
Retail storefronts sustain hunting and recreational walk-in purchases, while e-commerce platforms capture self-defense demand requiring discrete fulfillment.
- Retail:Brick-and-mortar sporting goods and dedicated firearm retailers serve walk-in hunters and range customers with immediate fulfillment.
- E-commerce:Age-verification infrastructure and direct-to-consumer shipping compliance enable discrete fulfillment for self-defense purchasers in concealed-carry states.
- Direct Sales:Prime contractors deliver Mil-Spec production directly to Department of Defense arsenals and law enforcement agency armories under long-term indefinite-delivery contracts.
- Wholesale:Distributors aggregate fragmented municipal and commercial demand into volume tiers that qualify for manufacturer volume pricing.
Direct sales lock in military volume. E-commerce is gaining share fastest among civilian channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American ammunition industry traces its modern scale to World War II-era government-owned contractor-operated facilities, particularly the Lake City Army Ammunition Plant established in Missouri during 1941. This federal production model created durable supply relationships between prime contractors and military procurement channels that persist across the United States and Canada today.
United States
Southwestern training installations at Fort Bliss, Fort Hood, and Camp Pendleton generate the continent's highest recurring ammunition demand from Army and Marine Corps units. EPA lead-content thresholds in manufacturing effluent are pressuring propellant facilities toward non-toxic primer reformulation. The Lake City Army Ammunition Plant in Independence, Missouri anchors domestic military production capacity under contractor operation.
Canada
NORAD modernization funding streams are expanding cross-border procurement opportunities for certified US-based suppliers meeting Canadian military specifications. Health Canada and PMRA regulate lead exposure thresholds at manufacturing facilities, aligning with EPA standards south of the border. Quebec and Ontario host the majority of Canadian defense industrial base capacity for small-arms ammunition assembly.
Mexico
Law enforcement modernization programs under the Secretariat of National Defense are expanding import demand for NATO-standard calibers from US manufacturers. The country's national defense regulator oversees ammunition import licensing and end-use verification for military and federal police contracts. Northern border states concentrate ammunition transit and customs processing infrastructure for cross-border supply chains.
North America Ammunition Market Competitive Landscape
The competitive structure tilts toward prime contractors with federal facility operating experience. Department of Defense source-approval processes compress the qualified supplier pool to a handful of integrated manufacturers capable of meeting Mil-Spec lot consistency and traceability mandates. Three archetypes dominate: government-owned contractor-operated facility operators, backward-integrated brass manufacturers, and precision match-grade specialists. Consolidation through joint ventures and strategic partnerships represents the primary competitive response to rising minimum lot-size thresholds.
Within the integrated manufacturing tier, Winchester Ammunition and General Dynamics Ordnance and Tactical Systems exemplify archetypes of captive raw material control and large-scale federal facility operation respectively. Hornady Manufacturing occupies a position among precision-oriented specialists serving law enforcement premium segments. These three anchors demonstrate how qualification timelines and capital requirements stratify competitive positioning across military, law enforcement, and commercial channels.
| Leading Market Players |
|---|
| Winchester Ammunition |
| Ammo, Inc. |
| General Dynamics Ordnance and Tactical Systems |
| Black Hills Ammunition |
| SIG Sauer |
| Northrop Grumman |
| Hornady Manufacturing |
| FN America |
| BAE Systems |
| Others |
Value Network & Pricing Analysis
Ballistician expertise concentration in Missouri and Arizona creates labor-cost differentials that widen spreads between Lake City Mil-Spec contracts and commercial rimfire production. EPA lead-content compliance investments at primer facilities amplify tier separation as integrated manufacturers absorb reformulation costs while smaller competitors face capital constraints.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs North American ammunition procurement. Price differentiation centers on NATO qualification certification and lot-traceability documentation, with Mil-Spec certified rounds commanding substantial premiums over commercial equivalents. Cost compression in rimfire training ammunition is intensifying because polymer-cased substitution erodes brass demand. Sports shooting segments exhibit highest price sensitivity per round, while law enforcement tactical units show lowest sensitivity for match-grade specifications.
Supply Chain Analysis
Brass cartridge case remanufacturing and reloadable component recovery flows sustain cost efficiency at integrated facilities like Lake City Army Ammunition Plant. Raw material sourcing draws from domestic copper mining in Arizona and Utah, Canadian zinc production, and imported antimony for primer compounds. Single-source vulnerability concentrates in captive brass manufacturing capacity controlled by backward-integrated primes. Distribution runs through Department of Defense direct delivery for military contracts, wholesale distributors for law enforcement cooperative purchasing, and e-commerce platforms for civilian self-defense channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American ammunition functions as a regulatory compounder where EPA non-toxic primer mandates and NATO standardization protocols continuously reshape procurement requirements and manufacturing capital allocation.
For Market Incumbents: Anchor market position through Lake City contract renewal qualification and captive brass supply consolidation. Polymer-cased substitution technology threatens traditional metalworking demand; counter through precision match-grade R&D investment for law enforcement premium channels. Vertical integration into primer chemistry facilities defends margin structure against EPA compliance cost spikes. For New Entrants and Emerging Players: E-commerce direct-to-consumer platforms offer the most penetrable route for self-defense ammunition in concealed-carry expansion states. Target state-level cooperative procurement vehicles in Texas and Arizona where fragmented municipal demand aggregates into volume tiers. Pursue Canadian NORAD modernization subcontracting as qualification pathway toward full NATO certification. For Investors and Strategic Acquirers: Defense prime contractors are the most active acquirer in this space, seeking ballistician talent and Mil-Spec production line assets. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume exposure. Monitor EPA enforcement intensity at manufacturing effluent discharge points as inflection indicator for accelerated green chemistry transition.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Toxic Primer Production Line Investment | EPA compliance timelines at Lake City and Independence facilities accelerate capital deployment toward green chemistry. |
| NATO Qualification Certification | Cross-border Canadian defense procurement opens addressable contract pools beyond domestic military budgets. |
| Precision Match-Grade Product Development | Law enforcement sniper unit specifications in Texas and Arizona command premium positioning with documented lot consistency. |
| E-Commerce Age-Verification Infrastructure | Direct-to-consumer fulfillment captures self-defense demand in concealed-carry licensing expansion states. |
| Brass Manufacturing Backward Integration | Captive raw material supply secures Department of Defense contract stability against commodity price volatility. |
Research Methodology
Multiple input streams — procurement officer interviews, manufacturing facility assessments, and regulatory filing analysis — were reconciled to construct market estimates. Primary fieldwork engaged Department of Defense acquisition specialists, Lake City operations managers, law enforcement procurement coordinators, and EPA compliance officers at propellant facilities. Secondary validation drew from ATF manufacturing license databases, Department of Defense contract award announcements, EPA effluent discharge records, and NATO standardization directive documentation. Bottom-up production capacity modeling and top-down contract value aggregation were cross-checked for consistency.
Data-stream reconciliation across product type, end-user category, application purpose, and distribution channel dimensions shaped the analytical framework. Segmentation modeling captured centerfire versus rimfire technical splits, military-law enforcement-commercial user archetypes, defense-training-self-defense-recreational application mixes, and direct-wholesale-retail-e-commerce channel flows. CAGRs were derived from contract award trajectory analysis and production line capacity expansion announcements. Forecast inputs included NATO modernization funding appropriations and state-level concealed-carry licensing velocity indices.
Brass commodity price shocks, EPA enforcement acceleration, and polymer-cased technology adoption curves are the dominant revision risks to production cost and demand substitution assumptions. Forecasts embed these contingencies as scenario-weighted outputs rather than point estimates. Practitioners should monitor lead-content threshold litigation outcomes and Marine Corps composite ammunition field-test results for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Middle East and Africa Ammunition Market