
 Global Liposuction Surgery Devices Market | 2026-2036
Global Liposuction Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liposuction Surgery Devices Market Foresight
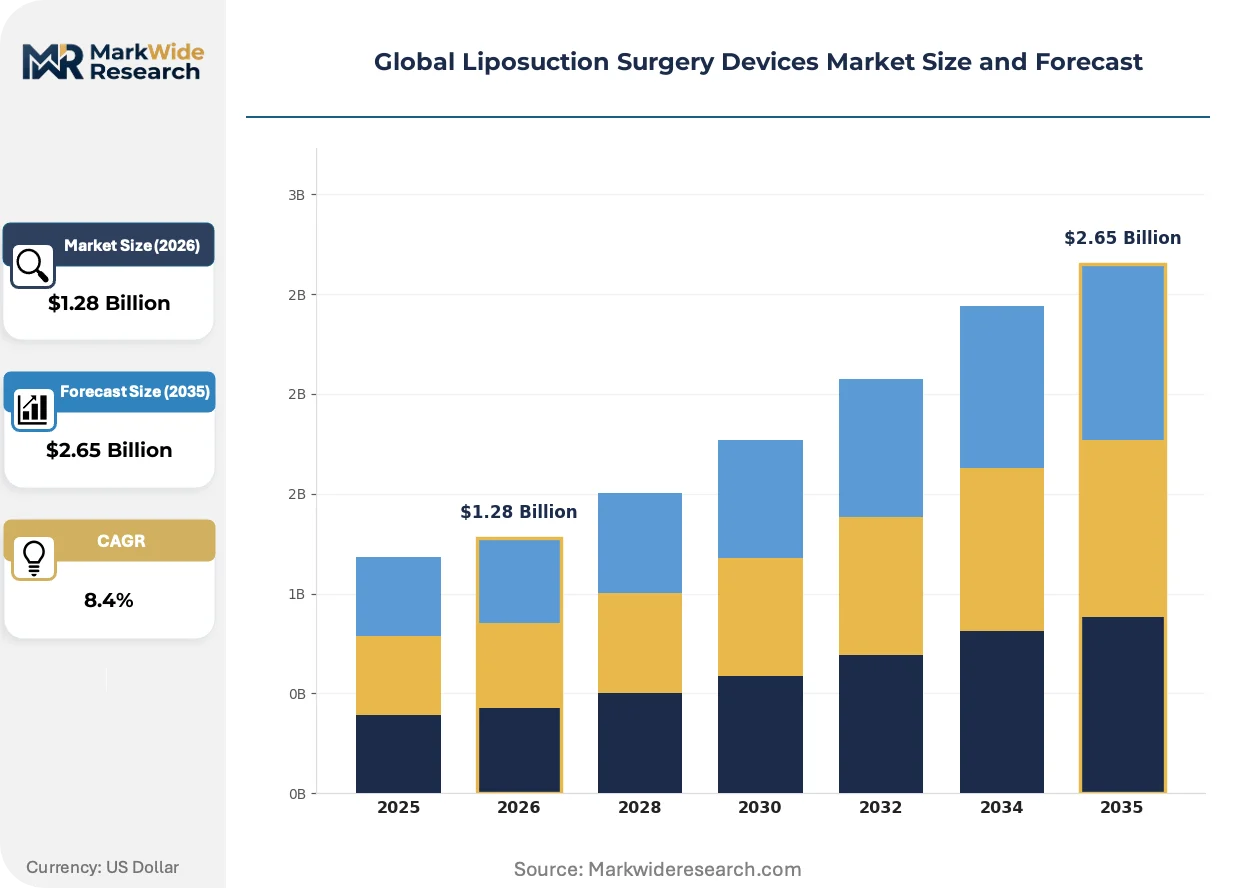
Subscription-based maintenance and software-defined energy calibration is expanding the commercial footprint of liposuction platforms beyond capital equipment sales. Cynosure Inc. leverages its installed base of laser systems to sustain recurring service revenue across dermatology centers. InMode Ltd. anchors its growth on radiofrequency-enhanced lipolysis platforms that compete with traditional suction methods. Alma Lasers differentiates through multi-modality workstations that integrate ultrasound and laser delivery for varied tissue densities.
Liposuction surgery devices are electromechanical or energy-based instruments designed to aspirate adipose tissue through cannulae ranging from 2 to 6 millimeters in diameter, employing negative pressure, ultrasonic cavitation, laser thermal disruption, or mechanical reciprocation to liquefy and extract fat. These systems serve the primary commercial purpose of body contouring in aesthetic and reconstructive medicine, enabling precise volume reduction with minimized collateral tissue trauma. Laser-assisted devices command premium positioning due to their dual action of fat emulsification and dermal tightening, while power-assisted systems occupy the high-volume procedural tier through faster aspiration cycles that improve surgeon ergonomics. Ultrasound-assisted platforms lead in fibrous tissue indications such as gynecomastia or secondary revision cases where traditional suction encounters resistance.
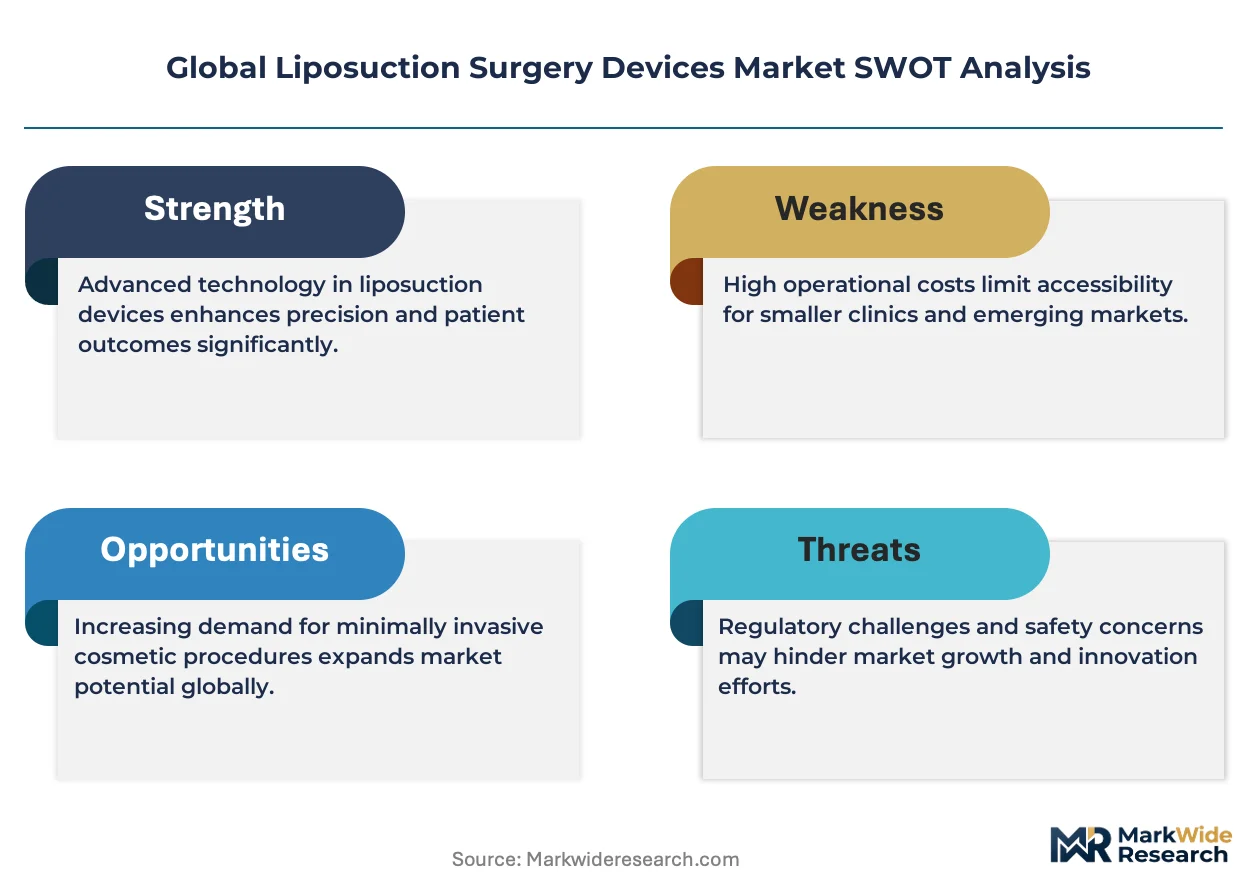
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation (MDR) imposes enhanced clinical evidence requirements for energy-based surgical equipment across European markets. Health Canada and Brazil's ANVISA maintain parallel vigilance systems that shape product labeling and post-market surveillance obligations for manufacturers seeking multi-jurisdiction access. Stakeholders must monitor evolving energy-output safety thresholds and reimbursement positioning for outpatient aesthetic procedures as regulatory bodies tighten scrutiny on adverse event reporting.
Market Dynamics
Energy-based fat disruption modalities are compressing procedural timeframes and expanding treatable patient profiles beyond traditional suction limitations. The convergence of laser thermal systems with radiofrequency platforms is redrawing competitive boundaries between device manufacturers.
Growth Catalysts
- EU MDR clinical evidence pathways:Enhanced post-market surveillance requirements for energy-based surgical equipment are accelerating consolidation among manufacturers with robust quality management systems.
- Plastic surgery clinic expansion:Outpatient aesthetic centers in Brazil and South Korea are scaling procedural capacity through dedicated liposuction suites and surgeon training programs.
- Radiofrequency-enhanced lipolysis:Dual-action platforms combining fat emulsification with dermal tightening are capturing premium positioning in body contouring protocols.
Market Restraints
- Capital intensity of multi-modality workstations:Integrated laser-ultrasound platforms require substantial upfront investment, limiting penetration in mid-tier dermatology practices.
- FDA 510(k) clearance timelines:Energy-output safety threshold revisions are extending pre-market notification review periods for novel device submissions.
- Non-invasive cryolipolysis alternatives:External cooling technologies are capturing patient segments seeking fat reduction without cannula-based intervention.
Strategic Opportunities
- Subscription-based maintenance models:Software-defined energy calibration services are generating recurring revenue streams beyond initial capital equipment sales.
- Secondary revision case specialization:Ultrasound-assisted platforms optimized for fibrous tissue indications address underserved gynecomastia and post-operative correction segments.
- Health Canada parallel vigilance alignment:Harmonized post-market surveillance obligations with FDA frameworks reduce regulatory duplication for North American market access.
Industry Challenges
- Surgeon ergonomics certification:Power-assisted system training requirements create bottlenecks in scaling procedural throughput across high-volume centers.
- Legacy suction platform integration:Hybrid workflows combining traditional negative-pressure systems with energy-based modalities complicate operating room configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liposuction Surgery Devices Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound-Assisted, Laser-Assisted, Power-Assisted, Suction-Assisted, Injection-Assisted Procedure Technique: Tumescent, Dry, Super-Wet, Water-Assisted, Micro-Air, VASER End User: Plastic Surgery Clinics, Dermatology Centers, Ambulatory Surgical Centers, Cosmetic Hospitals, Aesthetic Specialists Distribution Channel: Direct Sales, Online Platforms, Medical Equipment Distributors, Specialty Retailers |
| Companies Covered | Cynosure Inc., InMode Ltd., Solta Medical, Alma Lasers, Sciton Inc., Wells Johnson Co., Bausch Health Companies Inc., Genesis Biosystems, Inc., MicroAire Surgical Instruments, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liposuction Surgery Devices Market Shifts & Advancements
Device architecture is pivoting from standalone capital sales toward integrated hardware-software ecosystems with predictive maintenance capabilities. This shift is compressing replacement cycles and elevating service contract attach rates.
Microcannula laser delivery systems are electrifying precision fat targeting through sub-millimeter thermal control. Dermatology centers in South Korea are adopting these platforms for facial contouring applications. The technology is electrifying demand for outpatient procedures previously requiring surgical suite infrastructure.
FDA 510(k) substantial equivalence determinations are tightening for laser-assisted devices with novel wavelength configurations. Manufacturers must now demonstrate thermal injury profiles beyond predicate device benchmarks. High-power diode platforms face extended review timelines as the agency recalibrates energy-output safety thresholds.
After-sales service unbundling is fragmenting procurement decisions across capital committees and operational budget owners. Hospital systems are separating device acquisition from maintenance contracting, pressuring OEM margin structures. This pattern is most pronounced in United States integrated delivery networks managing multi-site aesthetic service lines.
Global Liposuction Surgery Devices Market Segmentation
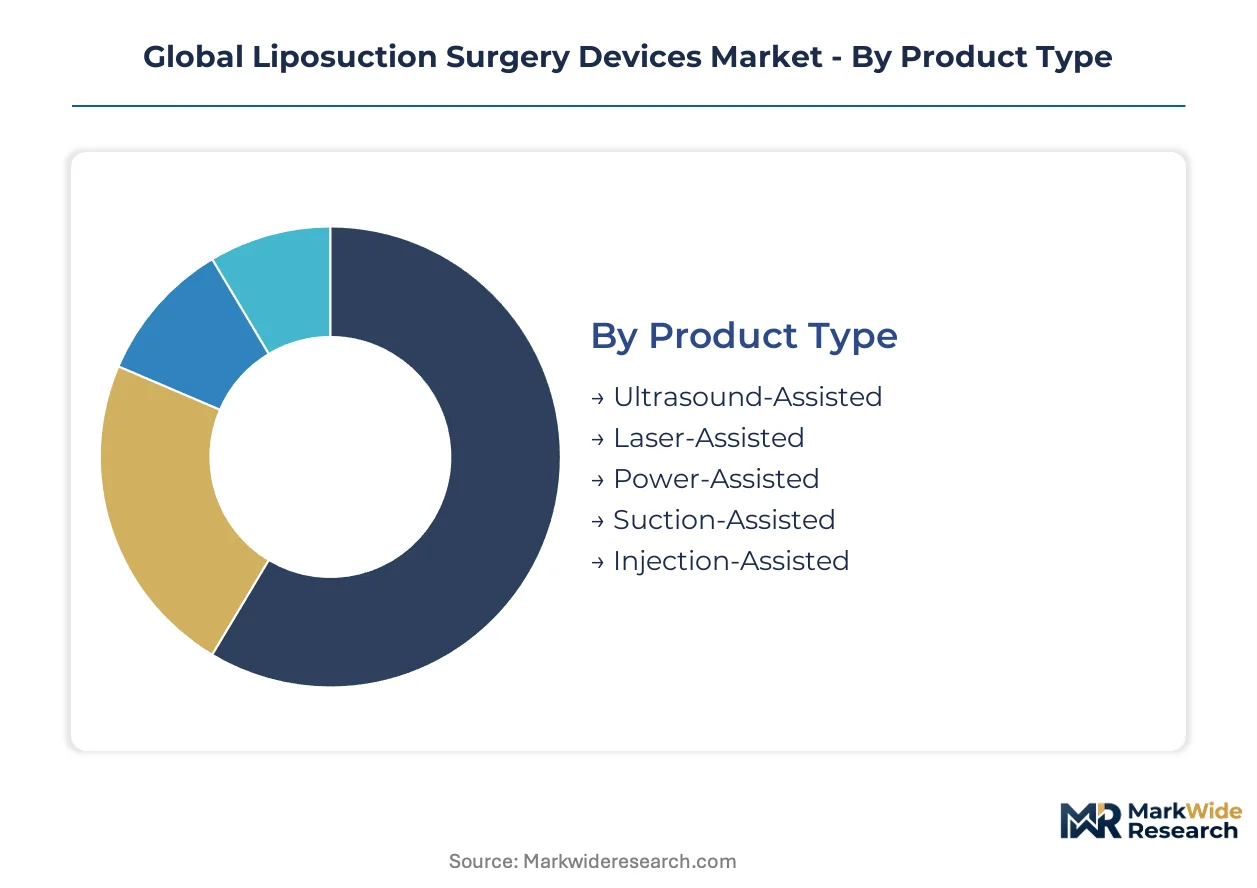
Device categorization in liposuction surgery tracks how energy delivery mechanisms reshape procedural economics and clinical outcomes across patient profiles. Segmentation reveals where capital investment concentrates versus where disposable instrument flows dominate recurring revenue.
Product Type:
Volume concentration clusters around suction-based platforms while premium positioning accrues to energy-assisted modalities with thermal or ultrasonic fat disruption.
- Ultrasound-Assisted:These systems deploy high-frequency acoustic waves to emulsify adipose tissue before aspiration, excelling in fibrous anatomical regions. Demand concentrates in Brazil's specialized gynecomastia correction centers where dense male breast tissue resists mechanical suction alone. The technology commands higher per-procedure revenue but requires extended capital recovery timelines.
- Laser-Assisted:Thermal disruption platforms liquefy fat while simultaneously inducing collagen contraction for dermal tightening. South Korean dermatology chains prioritize these systems for facial contouring applications where skin retraction determines aesthetic outcomes. Dual-action capability justifies premium pricing against single-modality alternatives.
- Power-Assisted:Reciprocating cannula tips accelerate aspiration velocity through mechanical vibration, reducing surgeon fatigue in high-volume settings. United States outpatient surgery centers deploy these platforms for trunk and extremity contouring where procedural throughput drives profitability.
- Suction-Assisted:Traditional negative-pressure systems remain the foundational technology across cost-sensitive markets and training institutions. Standard cannula configurations limit tissue selectivity but minimize per-procedure supply costs.
- Injection-Assisted:Pre-aspiration infiltration systems deliver tumescent or wetting solutions through integrated handpieces. These platforms streamline workflow in ambulatory settings where anesthesia coordination adds operational complexity.
Mature deployment sits with Suction-Assisted platforms across established training programs. Newer deployment is concentrated in Laser-Assisted systems gaining share fastest in premium aesthetic markets.
Procedure Technique:
Technique selection follows tissue density characteristics and anesthesia protocols rather than pure device capability matrices.
- Tumescent:Large-volume dilute anesthetic infiltration enables bloodless fat extraction under local sedation. This technique dominates United States office-based surgery suites where avoiding general anesthesia reduces regulatory overhead and recovery facility requirements.
- Dry:Absence of pre-infiltration limits application to small-volume extraction under general anesthesia. The technique persists in legacy hospital environments with established anesthesiology support but loses share to wetting variants.
- Super-Wet:Moderate infiltration volumes balance hemostasis with aspiration efficiency. Brazilian cosmetic hospitals favor this approach for combined procedures where lipoaspirate volumes approach physiological limits.
- Water-Assisted:Pulsed saline jets simultaneously dislodge and aspirate adipocytes, preserving cell viability for potential reinjection. European centers exploring fat grafting applications drive adoption of this technique.
- Micro-Air:Compressed air-powered systems enable precise fat harvesting for facial sculpting through reduced-diameter cannulae. South Korean specialists deploy these platforms for periorbital and jawline contouring where millimeter precision determines outcomes.
- VASER:Proprietary ultrasound platform with specialized probe designs for high-definition body sculpting. United States and Brazilian markets concentrate demand for this technique in athletic patient segments seeking muscular definition enhancement.
Established technique penetration peaks with Tumescent methods across North American outpatient infrastructure. Technique innovation is accelerating most quickly in Water-Assisted variants addressing fat grafting compatibility.
End User:
Site-of-service economics determine device configuration preferences, with facility fee structures and staffing models driving capital allocation decisions.
- Plastic Surgery Clinics:Dedicated aesthetic facilities maintain multi-modality device portfolios to address diverse patient anatomies. These centers in Brazil and South Korea generate highest per-facility procedural volumes through specialized surgeon concentration.
- Dermatology Centers:Skin-focused practices increasingly incorporate lipolysis for body contouring service line expansion. United States dermatology groups leverage existing laser infrastructure to add fat disruption capabilities with incremental capital outlay.
- Ambulatory Surgical Centers:Medicare-certified facilities in the United States optimize equipment utilization across mixed surgical specialties. Liposuction device selection prioritizes interoperability with existing anesthesia and monitoring systems.
- Cosmetic Hospitals:Full-service institutions in Brazil combine liposuction with overnight recovery capabilities for complex or combined procedures. Capital budgets accommodate integrated laser-ultrasound workstations with dedicated procedure suites.
- Aesthetic Specialists:Solo practitioners and small group practices concentrate in high-income urban corridors. These operators favor lease-financed or subscription-accessed devices to preserve working capital.
Institutional concentration centers on Plastic Surgery Clinics for comprehensive modality deployment. Emerging site-of-service growth is climbing the fastest in Dermatology Centers expanding beyond traditional skin services.
Distribution Channel:
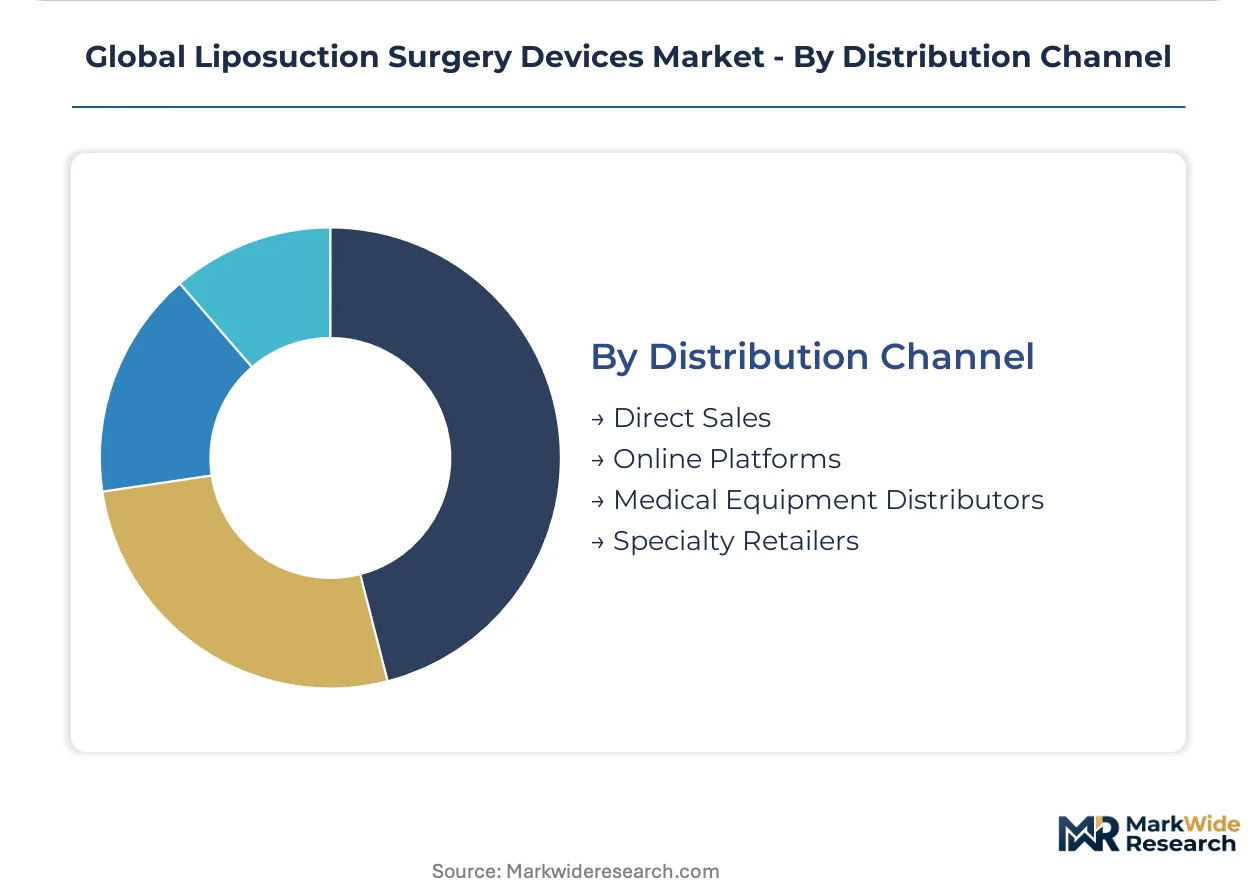
Channel selection reflects capital intensity tolerance and technical service requirements across customer segments.
- Direct Sales:Manufacturer field organizations handle high-value workstation transactions requiring installation, training, and service integration. Cynosure and InMode maintain direct presence in United States metropolitan markets.
- Medical Equipment Distributors:Regional specialists aggregate capital equipment portfolios across complementary surgical specialties. These intermediaries dominate Brazilian and South Korean procurement channels for mid-tier practices.
- Online Platforms:E-commerce penetration concentrates in disposable cannulae, infiltration tubing, and maintenance consumables. United States group purchasing organizations increasingly route these transactions through digital procurement portals.
- Specialty Retailers:Aesthetic device leasing brokers and refurbished equipment dealers serve price-sensitive entrants. These channels expand access for aesthetic specialists in secondary United States markets.
Primary procurement flows through Direct Sales for integrated system transactions. Channel expansion is gaining share fastest in Online Platforms for consumable replenishment and aftermarket accessories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates in Israel and the United States, while procedural consumption clusters in Brazil, South Korea, and the United States where aesthetic medicine infrastructure matures fastest.
United States
Outpatient surgery centers in Florida and California drive power-assisted system procurement for high-volume trunk contouring. FDA 510(k) clearance pathways govern laser-assisted device commercialization with extended review timelines for novel wavelength configurations. The Miami-Dade surgical corridor anchors demand for VASER high-definition platforms targeting athletic patient segments.
Brazil
Cosmetic hospitals in São Paulo and Rio de Janeiro scale multi-modality workstation deployment for combined aesthetic procedures. ANVISA vigilance systems shape post-market surveillance obligations and product labeling requirements for energy-based surgical equipment. The Jardins district aesthetic cluster generates highest per-facility procedural volumes through specialized surgeon concentration.
South Korea
Dermatology chains in Seoul's Gangnam district prioritize laser-assisted platforms for facial contouring applications demanding millimeter precision. MFDS medical device regulations enforce clinical evidence standards for energy-output safety thresholds in aesthetic equipment. The Apgujeong medical tourism corridor electrifies demand for microcannula laser delivery systems in outpatient settings.
Germany
EU MDR compliance costs accelerate consolidation among manufacturers with robust quality management systems serving European markets. ECHA and notified body oversight reshape clinical evidence requirements for energy-based surgical platforms. The Munich-Stuttgart medical technology belt concentrates precision engineering capabilities for ultrasound-assisted device components.
Israel
Energy-based aesthetic device R&D clusters in Tel Aviv and Haifa supply global OEMs with laser and radiofrequency platform technologies. Ministry of Health medical device regulations align with FDA frameworks to facilitate dual-market access for innovative surgical equipment. The Caesarea medical technology corridor anchors development of next-generation thermal disruption systems.
Global Liposuction Surgery Devices Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through integrated hardware-software ecosystems, while mid-tier specialists compete on procedure-specific modality optimization. The vendor base stratifies across laser platform originators, radiofrequency-enhanced lipolysis developers, and power-assisted mechanical system fabricators. Three archetypes dominate: energy-technology innovators, surgical instrument specialists, and multi-modality workstation integrators. Competitive moves concentrate on M&A for technology portfolio expansion and strategic partnerships for regulatory pathway acceleration.
Within the energy-technology innovator tier, Cynosure Inc. and InMode Ltd. exemplify platform developers leveraging recurring service revenue models beyond capital equipment sales. Alma Lasers occupies a position among multi-modality workstation integrators combining ultrasound and laser delivery architectures. These three entities represent the dominant competitive anchors shaping procurement dynamics across plastic surgery clinics and dermatology centers in Brazil, the United States, and South Korea.
| Leading Market Players |
|---|
| Cynosure Inc. |
| InMode Ltd. |
| Solta Medical |
| Alma Lasers |
| Sciton Inc. |
| Wells Johnson Co. |
| Bausch Health Companies Inc. |
| Genesis Biosystems, Inc. |
| MicroAire Surgical Instruments, LLC |
| Others |
Supply & Pricing Matrix
Energy-based modality transitions toward software-defined calibration systems simultaneously compress per-procedure cost structures and concentrate component sourcing among Israeli and United States precision engineering clusters. This technological pivot elevates recurring service revenue share while tethering capital equipment margins to semiconductor availability for embedded control systems.
Pricing Analysis
Margin tightening in mid-tier dermatology practices reflects extended FDA 510(k) review timelines for novel wavelength configurations that delay premium product launches. Pricing stratifies across premium laser-assisted platforms with dermal tightening, standard power-assisted systems for high-volume centers, and economy suction-based devices for training institutions. Price differentiation hinges on CE marking tier and after-sales service bundling. Cost-down pressure on standard-tier equipment accelerates because Brazilian and South Korean distributors consolidate procurement volumes. Hospital purchasing committees exhibit highest price sensitivity; cosmetic hospital chains in São Paulo demonstrate lowest sensitivity due to bundled procedure economics.
Supply Chain Analysis
Precision optics and embedded systems engineering workforce availability in Israel, Germany, and the United States anchors component fabrication for energy-based platforms. Final assembly draws from electromechanical manufacturing clusters in the United States and South Korea. Raw material dependencies center on rare-earth elements for laser cavities, medical-grade aluminum for cannula fabrication, and specialized polymers for handpiece insulation. Single-source vulnerability concentrates in high-power diode laser emitters sourced from Israeli R&D corridors. Distribution runs through manufacturer direct sales for integrated workstations and regional medical equipment distributors for mid-tier practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary software calibration ecosystems represents the decisive competitive lever as hardware margins compress toward service-attachment economics.
For Market Incumbents: Lock in installed base retention through predictive maintenance contracts that embed energy-output optimization algorithms. Defend against radiofrequency-enhanced lipolysis substitutes by accelerating MFDS and ANVISA parallel regulatory submissions. Prioritize backward integration into laser diode captive supply to insulate margin structures from rare-earth price volatility.
For New Entrants and Emerging Players: Capture white-space opportunity in secondary revision case specialization for gynecomastia correction where ultrasound-assisted platforms face limited competition. Target ambulatory surgical centers in United States Medicare-certified corridors with lease-financed power-assisted systems that preserve capital budgets. Deploy clinical outcome guarantee programs to differentiate against established laser platform vendors.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multi-modality workstation integrators seeking energy-technology portfolio expansion. Long-term viability favors manufacturers with software-defined service revenue exceeding forty percent of total mix. Watch FDA substantial equivalence determination timelines for novel thermal disruption platforms as inflection signal for competitive repositioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Energy Calibration Development | Transforms capital equipment vendors into recurring revenue platforms serving dermatology centers. |
| CE Marking Pathway Acceleration | EU MDR clinical evidence requirements favor manufacturers with robust quality management systems. |
| Hospital System Partnership | United States integrated delivery networks consolidate aesthetic service line procurement decisions. |
| Reimbursement Strategy | Outpatient procedure coding alignment determines site-of-service economics for ambulatory centers. |
| Multi-Modality Workstation Integration | Brazilian cosmetic hospitals demand combined laser-ultrasound platforms for complex procedures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plastic surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with FDA 510(k) databases, ANVISA vigilance reports, and MFDS medical device registrations. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data.
Reconciliation of installed base tracking, procedural frequency surveys, and capital equipment order flow informed the analytical framework across the projection horizon. Segmentation dimensions modeled include energy delivery mechanism, procedure technique, end-user facility type, and regional regulatory cluster. CAGRs derived from slope-intercept modeling of historical procedural growth and penetration rate assumptions. Industry-specific inputs incorporated energy-output safety threshold revisions and outpatient aesthetic service line expansion patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement intensity and non-invasive cryolipolysis technology advancement. Forecasts reflect documented assumptions regarding procedural volume trajectories and regulatory pathway timelines. Material deviation in FDA review period extensions or ANVISA vigilance system modifications warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Patches Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Photopheresis Products Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Medical Electrodes Market