
 Ocular Adhesive Market | 2026-2036
Ocular Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Adhesive Market Intelligence
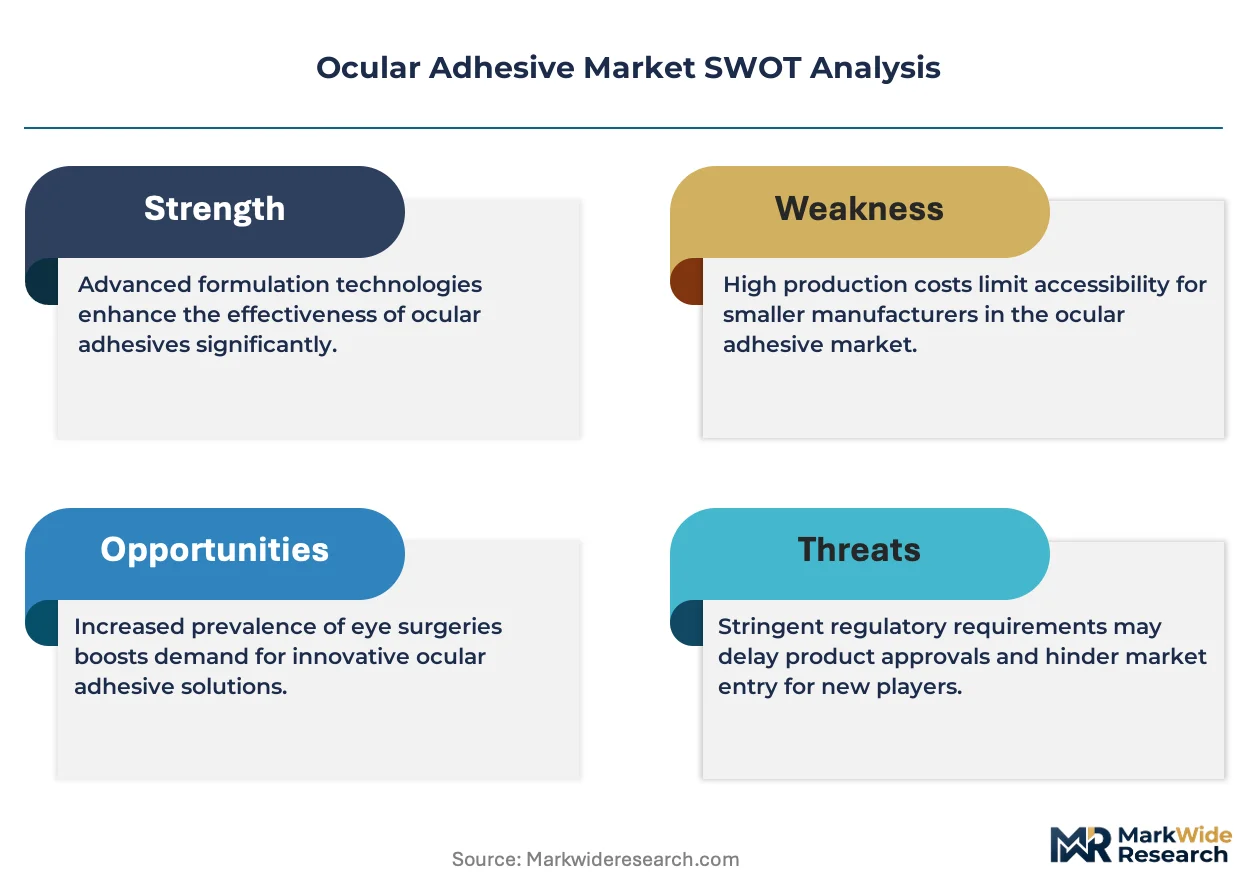
Biocompatible polymer engineering is tilting ocular adhesive development toward synthetic platforms with tunable degradation profiles. Johnson & Johnson Services, Inc. leverages its ophthalmic surgery infrastructure to sustain channel dominance in hospital settings. Baxter International, Inc. anchors its position through captive plasma fractionation that secures fibrin raw material supply. Ocular Therapeutix, Inc. differentiates via hydrogel depot technology that extends drug-elution timelines beyond conventional sealants.
Ocular adhesives comprise sterile formulations designed to bond ocular tissues or secure implants through polymerization, cross-linking, or fibrin clot formation, with viscosity parameters typically ranging from 5 to 500 centipoise depending on surgical site requirements. Cyanoacrylate formulations lead procedural volume in corneal laceration repair due to rapid polymerization kinetics, while bioadhesives represent the fastest-expanding category as surgeons seek alternatives to suture-induced astigmatism. Hospitals capture the dominant share of end-user demand through integrated purchasing contracts, though ambulatory surgical centers are gaining traction for same-day retina procedures where gel-based delivery reduces operating room time.
FDA 510(k) pathways govern cyanoacrylate and synthetic sealant approvals in the United States, while EMA's Medical Device Regulation imposes stricter biocompatibility testing for European market access, and ISO 10993 standards define cytotoxicity and sensitization benchmarks that all manufacturers must satisfy. These frameworks elevate R&D costs for new entrants but simultaneously validate premium pricing for compliant platforms. Stakeholders must monitor how evolving bioadhesive reimbursement codes in Medicare and commercial payers reshape site-of-care economics between hospitals and outpatient settings.
Market Dynamics
Biocompatible polymer engineering is compressing development cycles for synthetic ocular adhesives while FDA 510(k) pathways accelerate hospital procurement decisions for cyanoacrylate platforms.
Growth Catalysts
- EMA Medical Device Regulation:Stricter biocompatibility testing requirements in Europe validate premium pricing for compliant sealant platforms and accelerate hospital purchasing of certified products.
- Suture-induced astigmatism reduction:Retina surgeons in Germany and the United States are switching to fibrin-based sealants to minimize post-operative refractive complications in corneal procedures.
- Cyanoacrylate polymerization kinetics:Rapid-setting formulations reduce operating room time for corneal laceration repair, driving volume in emergency departments and trauma centers.
Market Restraints
- Plasma fractionation supply concentration:Captive fibrin raw material supply chains limit independent manufacturer entry and create dependency on established blood plasma processors.
- ISO 10993 cytotoxicity testing costs:Extended biocompatibility validation timelines elevate R&D expenditure for new adhesive platforms before commercial launch.
- Suture substitution resistance:Established ophthalmic surgeons in mature markets retain preference for traditional suturing techniques in complex reconstructive cases.
Strategic Opportunities
- Ambulatory surgical center expansion:Same-day retina procedures using gel-based delivery systems reduce facility costs and capture outpatient volume shifting from hospital settings.
- Hydrogel depot convergence:Drug-eluting adhesive platforms combine tissue sealing with sustained therapeutic release, opening reimbursement codes for combination device-drug products.
- Heidelberg-Berlin clinical cluster:University eye clinics in Germany generate real-world evidence that accelerates adoption across European teaching hospital networks.
Industry Challenges
- Biopolymer formulation expertise scarcity:Synthetic ocular adhesive development requires specialized polymer chemists with ophthalmic biocompatibility experience, constraining R&D team scaling.
- Reimbursement code fragmentation:Medicare and commercial payer classification variability between sealant and suture categories creates pricing uncertainty across site-of-care settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Adhesive Market |
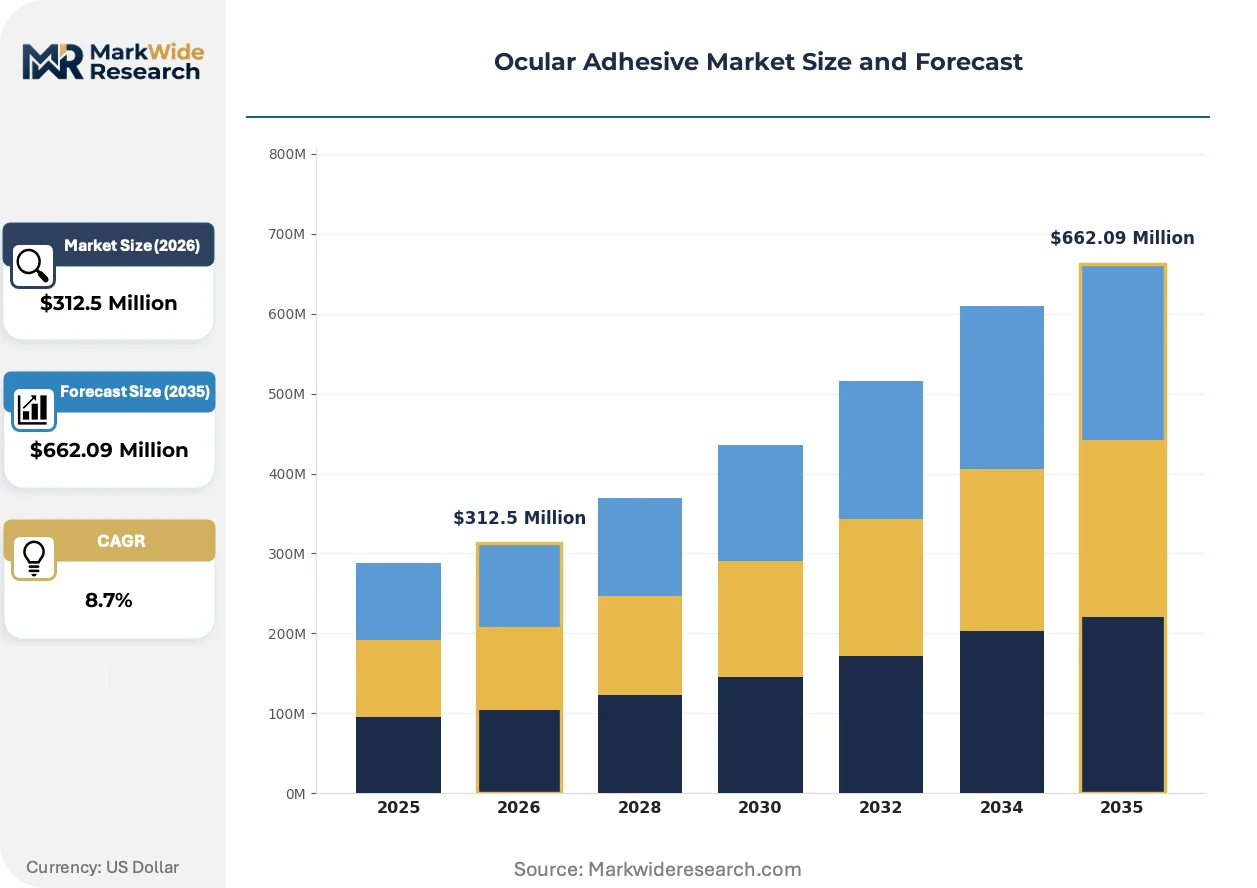
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanoacrylate, Fibrin, Tissue Sealants, Bioadhesives Application: Corneal Surgeries, Retina Surgeries, Eyelid Repair, Glaucoma Treatment End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Institutes Form: Liquid, Gel, Patch, Spray |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Johnson & Johnson Services, Inc., Baxter International, Inc., Medtronic plc, Ocular Therapeutix, Inc., B. Braun Melsungen AG, Reliance Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Adhesive Market Strategic Shifts & Innovations
Synthetic platform development is virtualizing traditional manufacturing assumptions while regulatory compression and procurement evolution reshape competitive positioning in ocular tissue bonding.
Photocrosslinkable hydrogel systems are virtualizing conventional cyanoacrylate dominance in corneal sealing applications. Academic medical centers in the United States and Germany are piloting these platforms for Descemet membrane endothelial keratoplasty procedures. The technology is virtualizing the trade-off between adhesion strength and bioresorbability that has constrained formulation design for two decades.
FDA 510(k) clearance pathway streamlining is compressing development timelines for Class II ocular sealant devices. Pre-submission meeting protocols now provide definitive biocompatibility testing guidance before pivotal studies commence. Synthetic adhesive manufacturers are responding by front-loading regulatory strategy into polymer design phases rather than treating compliance as a terminal gate.
Integrated purchasing contracts are consolidating hospital procurement decisions into centralized supply chain committees. Ambulatory surgical centers are bypassing traditional distributor markups through direct manufacturer agreements for high-volume sealant SKUs. This channel compression is most visible in United States metropolitan markets where health system consolidation has concentrated buying power into three to five dominant networks per region.
Ocular Adhesive Market Segmentation
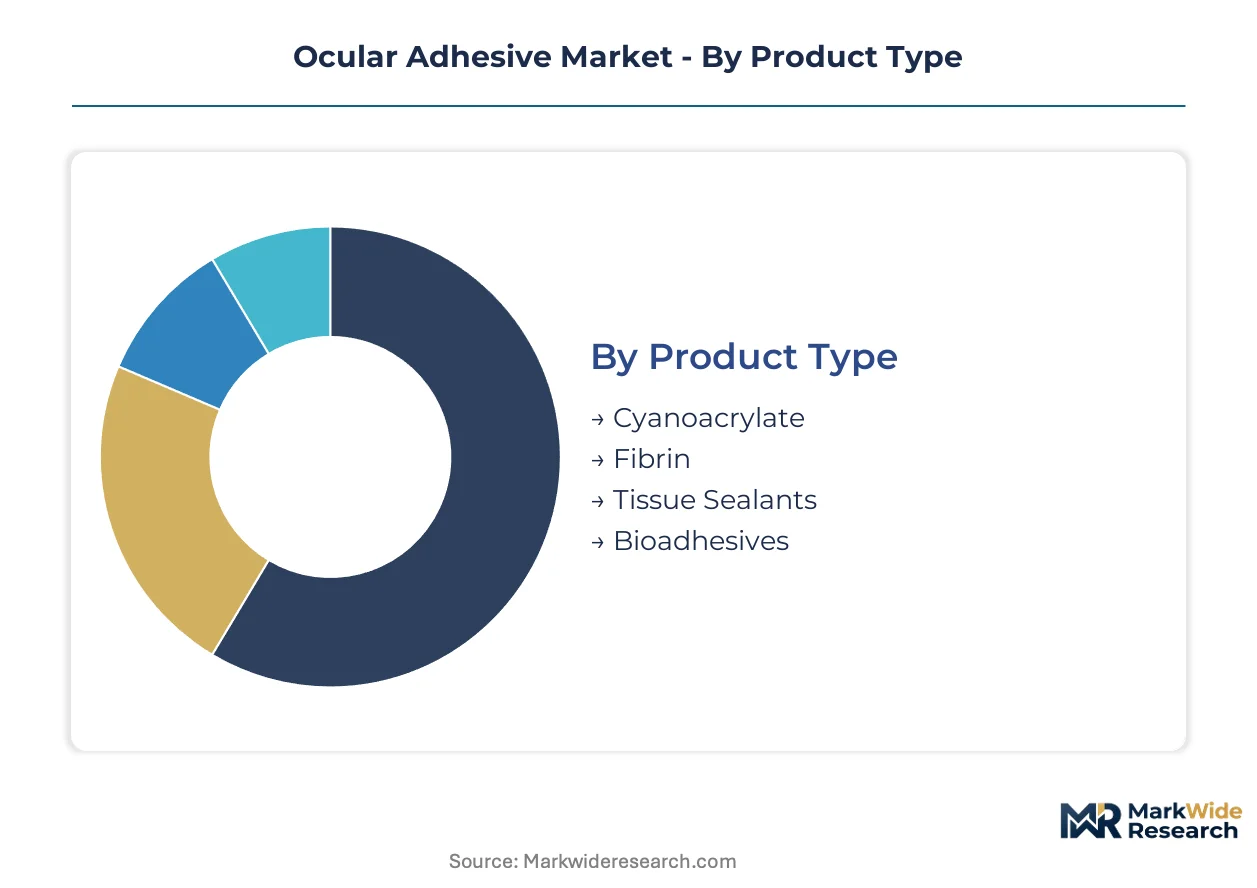
Segmentation in ocular adhesives reveals how polymer chemistry, surgical site requirements, and care delivery economics split procurement decisions across hospital systems. Manufacturers configure formulation portfolios around viscosity specifications and setting kinetics that match procedural workflows.
Product Type:
Cost tier stratification separates premium fibrin platforms from commodity cyanoacrylate formulations in hospital purchasing negotiations.
- Cyanoacrylate:Rapid polymerization kinetics (2-60 seconds) suit emergency corneal laceration repair where operating room throughput drives value. Demand concentrates in United States trauma centers and German university hospitals seeking suture alternatives for globe rupture cases.
- Fibrin:Dual-component sealants derived from human plasma provide hemostasis and tissue adhesion through thrombin-catalyzed clot formation. Heidelberg and Berlin eye clinics in Germany anchor European adoption for Descemet membrane endothelial keratoplasty procedures where biocompatibility outweighs cost sensitivity.
- Tissue Sealants:Synthetic polyethylene glycol-based platforms offer tunable degradation profiles for retina surgeries requiring temporary adhesion.
- Bioadhesives:Hydrogel depot technologies combining tissue sealing with drug elution are climbing the fastest in reimbursement value per procedure.
Cyanoacrylate holds installed capacity. Bioadhesives are rotating up the share rankings.
Application:
Surgical site anatomy dictates viscosity requirements ranging from 5 centipoise for intracameral delivery to 500 centipoise for external tissue approximation.
- Corneal Surgeries:Penetrating keratoplasty and lamellar procedures demand optical clarity and minimal refractive distortion. Gel formulations with photopolymerization triggers are expanding most quickly in academic medical centers across the United States.
- Retina Surgeries:Vitrectomy wound closure and macular hole repair require low-viscosity liquids that spread across curved posterior segment anatomy. German university clinics generate real-world evidence driving adoption across European teaching hospital networks.
- Eyelid Repair:Oculoplastic procedures favor flexible patch formats that accommodate dynamic tissue movement.
- Glaucoma Treatment:Filtering bleb repair and tube shunt fixation utilize spray formulations for rapid hemostasis in vascularized conjunctival tissue.
Corneal applications command procedure volume. Retina applications are rotating up the share rankings.
End User:
Customer type determines packaging scale, sterility assurance levels, and procurement channel access for adhesive platforms.
- Hospitals:Integrated purchasing contracts consolidate buying power into centralized supply chain committees. United States health system consolidation has concentrated procurement decisions into three to five dominant networks per metropolitan region.
- Eye Clinics:Standalone ophthalmology practices in Germany and the United States favor single-use prefilled syringes that eliminate mixing steps and reduce staff training burden.
- Ambulatory Surgical Centers:Same-day retina procedures using gel-based delivery systems reduce facility costs and capture outpatient volume shifting from hospital settings.
- Research Institutes:Academic medical centers pilot photocrosslinkable hydrogel systems for next-generation keratoplasty techniques.
Hospitals hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
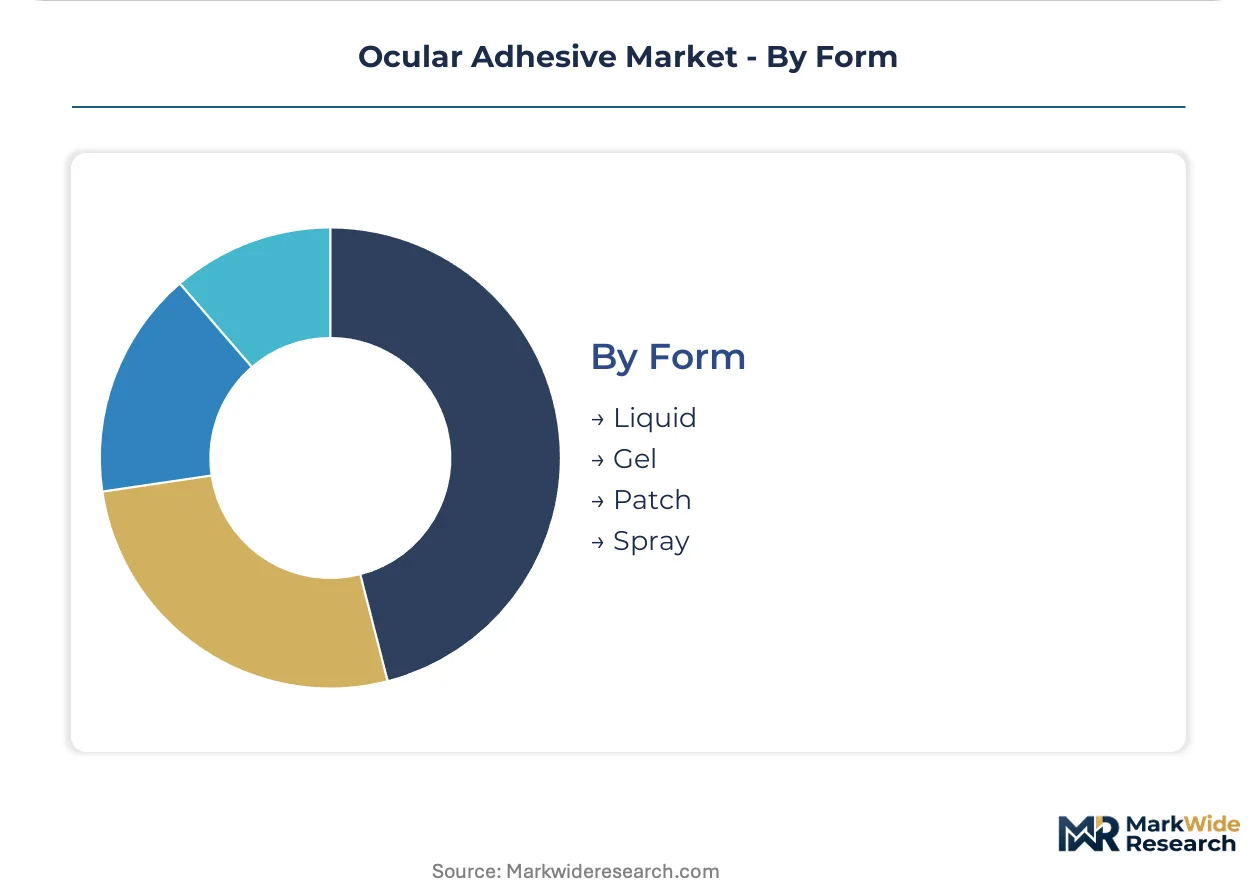
Form:
Physical state determines applicator design, shelf stability, and site-of-care preparation requirements for clinical staff.
- Liquid:Low-viscosity formulations (5-50 centipoise) penetrate tissue interstices for deep wound closure. Demand concentrates in United States emergency departments managing chemical and mechanical ocular trauma.
- Gel:Shear-thinning rheology enables injection through narrow-gauge cannulas while maintaining shape retention at rest. German retina specialists in Heidelberg favor gel platforms for sutureless sclerotomy closure.
- Patch:Solid matrix formats provide mechanical reinforcement for eyelid and adnexal reconstruction.
- Spray:Aerosolized delivery covers large surface areas for conjunctival and scleral applications.
Liquid formulations hold installed capacity. Gel formats are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports fibrin-based ocular sealants to university hospital networks across France and the Netherlands, while the United States supplies cyanoacrylate formulations to trauma centers in Canada and Mexico through integrated distributor agreements.
United States
FDA 510(k) clearance pathways compress development timelines for Class II ocular sealant devices, accelerating hospital procurement decisions. Medicare reimbursement codes for bioadhesive procedures reshape site-of-care economics between hospitals and ambulatory surgical centers. The Greater Boston and Pacific Northwest clusters anchor photocrosslinkable hydrogel pilot programs for next-generation keratoplasty techniques.
Germany
EMA Medical Device Regulation imposes stricter biocompatibility testing requirements that validate premium pricing for compliant sealant platforms. University eye clinics in Heidelberg and Berlin generate real-world evidence driving fibrin-based sealant adoption across European teaching hospital networks. The Baden-Württemberg medical technology corridor concentrates polymer engineering expertise for synthetic adhesive development.
Japan
PMDA marketing authorization pathways for combination device-drug products create regulatory clarity for hydrogel depot platforms with extended drug-elution timelines. METI funding programs support domestic biopolymer formulation capabilities for ophthalmic applications. The Kansai region around Osaka anchors manufacturing partnerships between Japanese chemical conglomerates and regional surgical device distributors.
India
CDSCO medical device registration requirements for imported ocular sealants elevate compliance costs for multinational manufacturers while creating openings for domestic plasma fractionation ventures. Reliance Life Sciences and other domestic players expand fibrin sealant production through captive blood plasma processing. The Maharashtra pharmaceutical cluster around Mumbai concentrates contract manufacturing for synthetic adhesive intermediates.
Switzerland
Swissmedic certification for high-risk medical devices positions the country as a regulatory launchpad for premium ocular adhesive platforms seeking European market access. ISO 10993 testing laboratories in the Basel region serve manufacturers from Germany and France. The Zurich-Bern corridor concentrates ophthalmic surgery device headquarters leveraging Swiss precision manufacturing reputation.
Ocular Adhesive Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement decisions in consolidated hospital systems. The vendor base splits between diversified medical device conglomerates with integrated purchasing contracts and focused adhesive developers with formulation-specific intellectual property. Three archetypes dominate: plasma fractionation-integrated manufacturers securing raw material supply, polymer engineering specialists with tunable degradation platforms, and hydrogel depot innovators combining tissue sealing with drug delivery. Competitive moves concentrate on strategic partnerships with university medical centers for real-world evidence generation and direct agreements with ambulatory surgical centers bypassing traditional distributor markups.
Within the diversified medical technology tier, Johnson & Johnson Services, Inc. and Baxter International, Inc. occupy positions anchored by hospital system relationships and captive supply chain infrastructure. Ocular Therapeutix, Inc. exemplifies the specialized platform developer archetype, representing hydrogel depot convergence strategies that extend therapeutic utility beyond conventional sealant applications. These three companies illustrate how competitive positioning in ocular adhesives depends on controlling either procurement channel access, raw material supply security, or formulation differentiation vectors.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Johnson & Johnson Services, Inc. |
| Baxter International, Inc. |
| Medtronic plc |
| Ocular Therapeutix, Inc. |
| B. Braun Melsungen AG |
| Reliance Life Sciences |
| Others |
Cost & Logistics Intelligence
Plasma fractionation capacity in the United States and Germany concentrates fibrin raw material supply among three dominant processors, anchoring margin pools downstream with hospital-system incumbents who negotiate multi-year adhesive supply contracts. This upstream concentration compresses pricing flexibility for independent sealant manufacturers while amplifying procurement leverage for integrated device conglomerates with captive plasma sourcing.
Pricing Analysis
Next-generation photocrosslinkable hydrogel platforms command premium positioning against established cyanoacrylate formulations and commodity fibrin sealants. Pricing stratifies across premium bioresorbable tiers, standard synthetic platforms, and economy cyanoacrylate SKUs based on ISO 10993 certification depth and drug-elution capability. Cost compression in the economy tier intensifies as Indian and Chinese manufacturers expand synthetic adhesive production. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure reimbursement caps, while German university hospitals prioritize biocompatibility validation over unit cost.
Supply Chain Analysis
Human plasma feedstock draws from United States, German, and Austrian collection networks, with synthetic polymer precursors sourcing from Japanese and South Korean chemical manufacturers. Key dependencies include thrombin enzymes, polyethylene glycol resins, and photoinitiator compounds. Single-source vulnerability concentrates in plasma fractionation where Baxter International and CSL Behring control majority capacity. Distribution runs through integrated purchasing contracts with United States health systems and direct manufacturer agreements with German university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ocular adhesives constitute a regulatory entrenchment market where FDA 510(k) clearance histories and ISO 10993 testing investments create switching costs that protect incumbent positions. Network effects concentrate in hospital system purchasing committees that standardize sealant protocols across multi-facility networks.
For Market Incumbents: Insulate market position by deepening captive plasma fractionation relationships and accelerating photocrosslinkable hydrogel R&D to preempt next-generation displacement. Secure GPO contract renewals before Medicare reimbursement codes shift toward outpatient settings. Prioritize certification investment in ISO 10993-5 cytotoxicity testing to maintain premium tier access.
For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgical center channels where direct manufacturer agreements bypass incumbent distributor relationships. Target gel-based delivery formats for same-day retina procedures in United States metropolitan markets. Pursue white-space positioning in synthetic bioadhesives with tunable degradation profiles that fibrin platforms cannot match.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polymer engineering specialists possessing ophthalmic biocompatibility expertise but lacking hospital channel infrastructure. Five-to-ten year viability hinges on convergence between tissue sealing and sustained drug delivery. Watch for inflection signals in Medicare reimbursement code expansion for combination device-drug products.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates hospital procurement decisions for cyanoacrylate and synthetic sealant platforms in United States trauma centers. |
| CE Marking Pathway | Validates premium pricing for EMA MDR-compliant fibrin sealants across German and French teaching hospital networks. |
| Hospital System Partnership | Secures integrated purchasing contract access through centralized supply chain committee relationships. |
| Plasma Fractionation Integration | Ensures captive thrombin and fibrinogen supply security against raw material concentration risk. |
| Reimbursement Strategy | Captures outpatient volume shift through Medicare code alignment for gel-based same-day retina procedures. |
Research Approach
A standing panel of retina surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary fieldwork phases. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, ISO 10993 testing laboratory records, and hospital procurement contract registries. Bottom-up procedure volume estimates triangulated against top-down adhesive consumption data from plasma fractionation reports and synthetic polymer trade flows.
Scenario-bracketing framed demand projections across the analysis window using three regulatory and reimbursement trajectories. Segmentation dimensions modeled included product chemistry class, surgical site anatomy, end-user facility type, and regional regulatory cluster. CAGRs derived from spline-interpolated adoption curves calibrated to historical cyanoacrylate penetration patterns and pilot program expansion rates for photocrosslinkable hydrogel platforms.
Sensitivities concentrate around Medicare reimbursement code revisions, EMA MDR enforcement intensity shifts, and plasma supply disruptions from donor collection variability. Cross-checking against hospital purchasing database benchmarks and surgical procedure registry trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Pleural Catheters Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Vaginal Specula Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market